
 Insulation Products Market | 2026-2036
Insulation Products Market Size, Share, and Industry Trends Forecast 2026-2036
Insulation Products Market Outlook
Performance-based insulation service contracts is realigning how building envelope solutions get monetized, shifting capital expenditure into operational agreements. Owens Corning leverages its integrated fiberglass-to-finished-system pipeline to capture recurring maintenance revenue. Saint-Gobain anchors European specification channels through technical advisory services tied to mineral wool installations. Knauf Insulation competes on acoustic-fire combined ratings that extend contract value beyond thermal metrics alone.
Insulation products are engineered thermal barriers manufactured from fibrous, cellular, or reflective materials with specified R-values, lambda coefficients, and fire reaction classes, designed to reduce conductive and convective heat transfer in built environments. Production involves melt spinning, foaming, or fiberizing processes that control density, pore structure, and binder chemistry to meet EN 13162 or ASTM C518 performance thresholds. Fiberglass and mineral wool dominate mature replacement cycles with stable margin pools, while spray foam commands premium positioning in commercial retrofit where air sealing integration drives specification. Rigid foam board leads new construction for continuous insulation layers, particularly in climate zones with stringent thermal bridge requirements.
EPA ENERGY STAR certification, ASHRAE 90.1 standards, and the EU Green Deal building renovation targets collectively mandate step-change improvements in envelope U-values, directly expanding addressable product volume. OSHA workplace exposure limits for isocyanates and formaldehyde emissions reshape spray foam contractor training and product formulation pathways. Stakeholders must track how embodied carbon disclosure rules in France, Germany, and California alter material preference hierarchies before specification databases harden around environmental product declarations.
Market Dynamics
Building decarbonization mandates are compressing retrofit cycles and forcing specification upgrades across commercial envelopes, pulling demand toward higher-performance materials with verified environmental product declarations.
Growth Catalysts
- EU Green Deal renovation targets:The directive mandates envelope U-value improvements across member states, expanding mineral wool and rigid foam volumes in German and French retrofit pipelines.
- Commercial building energy efficiency mandates:ASHRAE 90.1 standards in the United States tighten thermal bridge requirements, accelerating continuous insulation adoption in new construction.
- Spray foam air sealing integration:The technology captures premium positioning in commercial retrofit where blower door testing requirements now specify combined thermal-air barrier performance.
Market Restraints
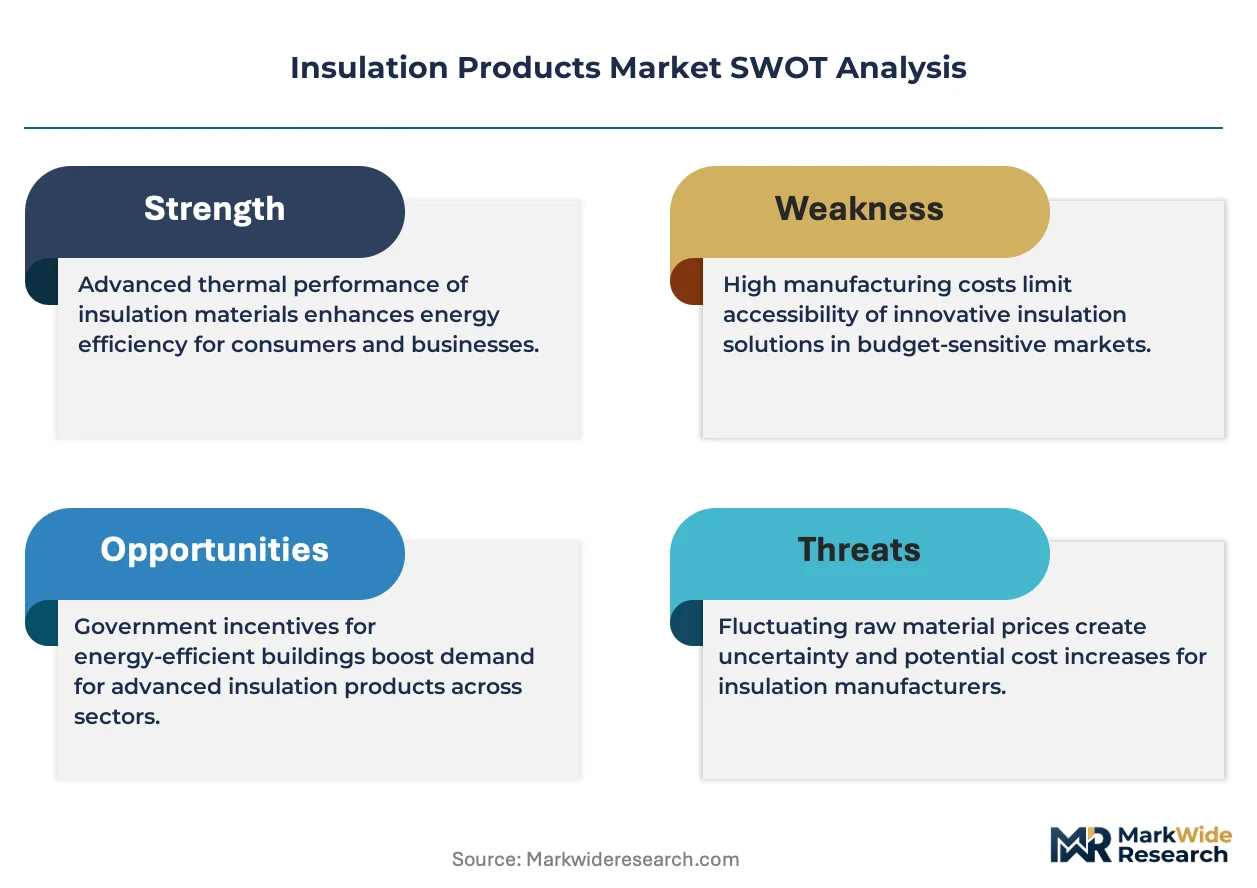
- Petrochemical feedstock volatility:Polyol and MDI price swings compress spray foam margins and destabilize rigid foam board costing models.
- Isocyanate exposure limits:OSHA workplace regulations extend contractor training timelines and restrict spray foam application crew availability.
- Mineral wool supply concentration:European production clusters in Germany and Belgium create geographic vulnerability to energy cost shocks.
Strategic Opportunities
- Deep energy retrofit incentives:The US Inflation Reduction Act tax credits for envelope improvements expand addressable residential retrofit volume.
- Embodied carbon disclosure requirements:France's RE2020 regulation and California's Buy Clean policies create first-mover advantage for manufacturers with verified EPDs.
- Acoustic-fire combined specification:Healthcare and education construction in China increasingly specify integrated performance ratings that extend contract value.
Industry Challenges
- Certified installer scarcity:Spray foam contractor licensing requirements and isocyanate safety training bottleneck deployment capacity.
- Legacy building stock assessment:Pre-1990s commercial structures require invasive moisture and structural evaluation before envelope upgrades, extending sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulation Products Market |
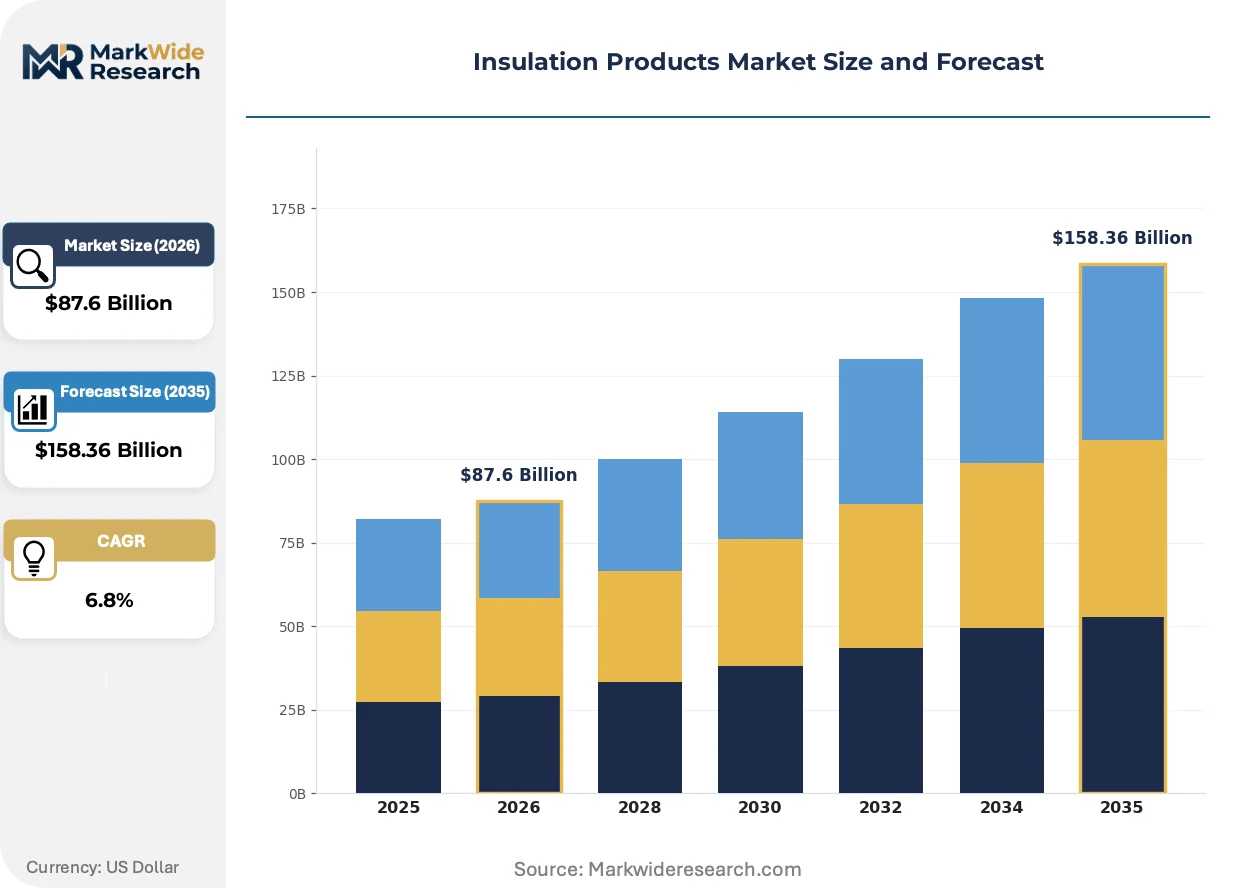
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiberglass, Foam Board, Spray Foam, Mineral Wool End Use: Residential, Commercial, Industrial, HVAC Material: Polyurethane, Cellulose, Polystyrene, Cotton Form: Batts, Rolls, Rigid Panels, Loose Fill |
| Companies Covered | Owens Corning, Saint-Gobain, Rockwool International, Knauf Insulation, BASF SE, Kingspan Group, Johns Manville, Covestro AG, Dow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulation Products Market Strategic Shifts
Material science advances and regulatory disclosure requirements are fusing thermal performance with carbon accounting, reshaping how products compete on specification databases.
Aerogel blanket insulation is converging with thin-profile retrofit applications where space constraints prohibit conventional thickness. Historic building preservation authorities in Italy and the United Kingdom specify the material for facade upgrades where heritage restrictions limit envelope depth. The convergence is compressing the addressable market for traditional internal insulation systems in dense urban cores.
The EU F-Gas Regulation phase-down is forcing reformulation of blowing agents in extruded polystyrene and polyurethane foams. Manufacturers are shifting to hydrofluoroolefin and hydrocarbon alternatives to maintain lambda coefficients under tightening GWP limits. German and Nordic markets are experiencing the fastest specification migration as national building codes anticipate 2027 F-Gas quota reductions.
Building owners now require lifecycle carbon data alongside R-value metrics in specification requests. Facility managers in Dutch and Danish commercial portfolios prioritize products with third-party EPDs that disclose embodied carbon per square meter. This behavioral shift is elevating cellulose and wood fiber insulation in segments previously dominated by petrochemical foams.
Insulation Products Market Segmentation
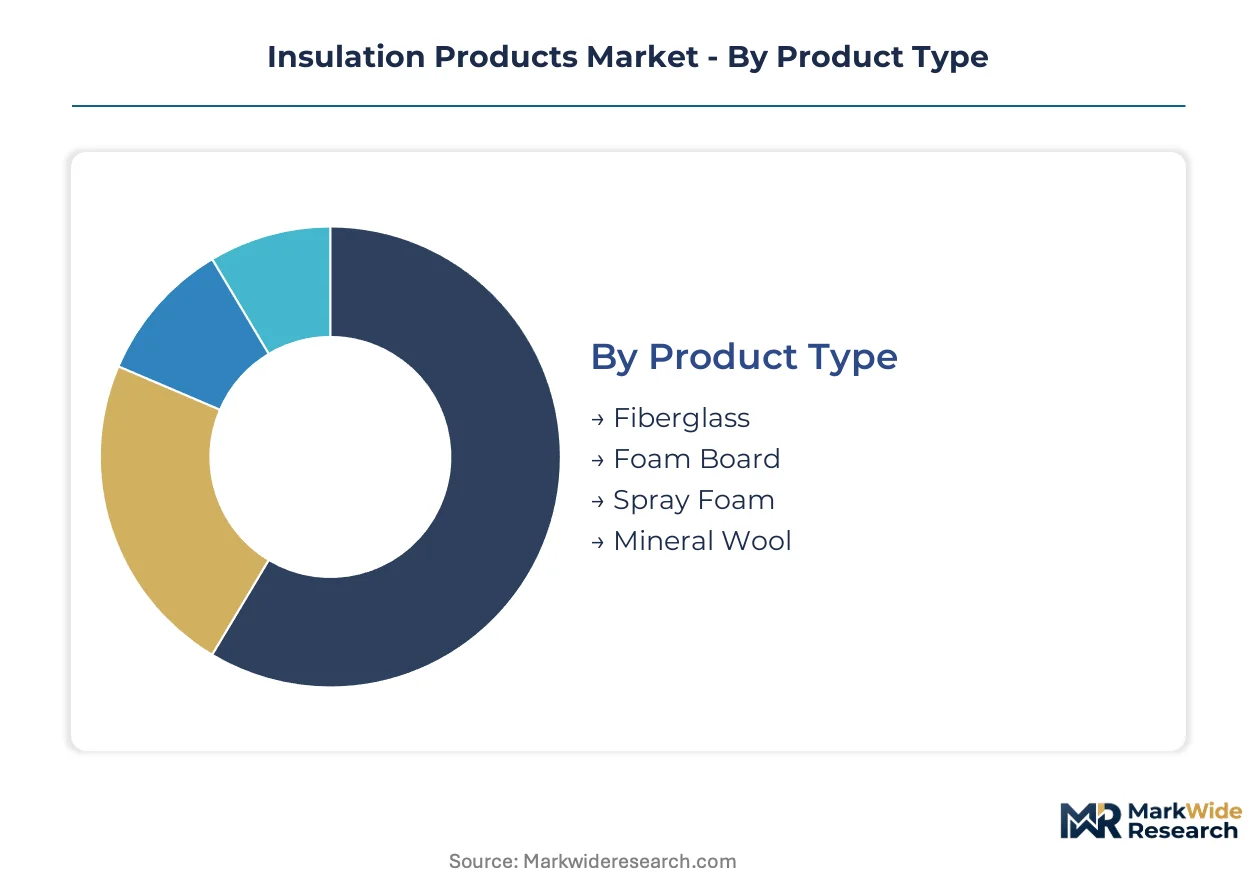
Insulation product specifications diverge sharply across building ages and regulatory climates. Upgrade cycles in commercial envelopes favor different material combinations than residential retrofit programs, creating distinct margin pools within each segment cluster.
Product Type:
Replacement-cycle timing and thermal bridge regulations determine which products capture volume in each construction phase.
- Fiberglass:Melt-spun borosilicate glass fibers bound with phenolic resin deliver consistent R-values across batt and loose-fill configurations. German and United States residential contractors specify fiberglass for cost-sensitive retrofit volumes where blower door testing requirements remain moderate.
- Spray Foam:Two-component polyurethane systems combining polymeric MDI with polyol blends create monolithic air barriers with lambda coefficients below 0.025 W/mK. Commercial retrofit demand in California and New York concentrates here where combined thermal-air barrier performance is mandatory.
- Foam Board:Extruded polystyrene and polyisocyanurate rigid panels provide continuous insulation layers for new construction thermal bridge compliance.
- Mineral Wool:Stone or slag fiber matrices deliver fire reaction class A1 ratings alongside acoustic dampening for multi-occupancy buildings.
Fiberglass sits at the top of the volume ranking, with spray foam climbing the fastest.
End Use:
Customer procurement patterns split between asset owners seeking operational savings and developers optimizing first-cost compliance.
- Commercial:Facility managers in United States office portfolios and German retail chains specify high-performance systems with verified EPDs to meet corporate decarbonization targets and lease certification requirements.
- Residential:Single-family and multi-family builders in China and India drive batt and loose-fill volumes where code adoption is accelerating.
- Industrial:Process facility operators in petrochemical and food processing sectors demand fire-rated systems for pipe and vessel insulation.
- HVAC:Mechanical contractors source duct wrap and pipe insulation for energy loss reduction in commercial and institutional buildings.
Commercial commands the largest contract value per project, while residential delivers the highest unit volume.
Material:
Feedstock chemistry and embodied carbon disclosure rules are reordering specification hierarchies in regulated markets.
- Polyurethane:Isocyanate-based rigid foams and spray systems dominate premium commercial applications where space constraints limit insulation thickness.
- Cellulose:Recycled paper fiber treated with borate fire retardants gains share in Dutch and Danish markets where lifecycle carbon data drives procurement decisions.
- Polystyrene:Expanded and extruded variants face reformulation pressure under EU F-Gas Regulation phase-down timelines.
- Cotton:Denim and textile waste fibers serve niche residential applications with low chemical emission profiles.
Polyurethane retains the highest value concentration, with cellulose expanding most quickly in carbon-regulated jurisdictions.
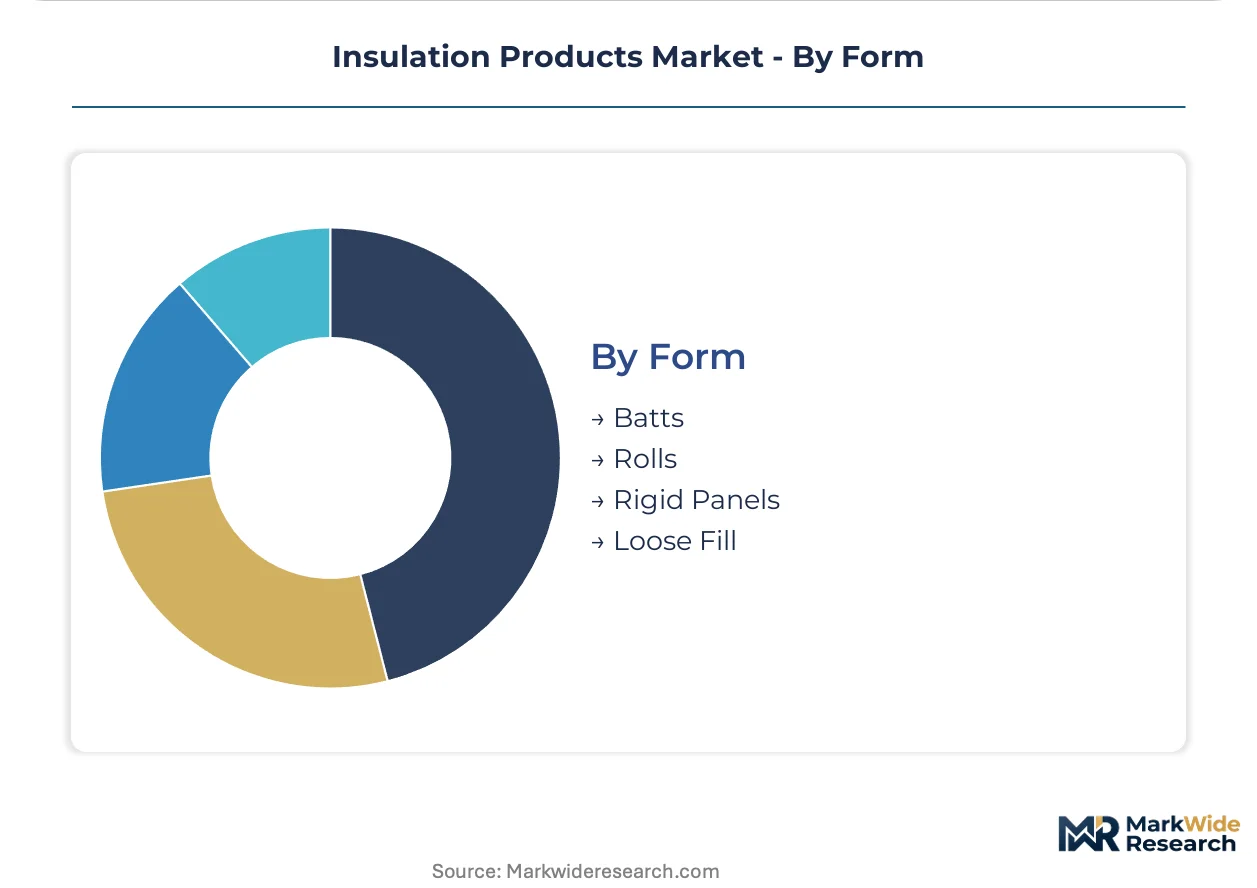
Form:
Installation labor availability and building geometry dictate form factor selection across new construction and retrofit pipelines.
- Batts:Pre-cut fiberglass or mineral wool segments friction-fit between studs and joists for residential wall and ceiling applications.
- Rolls:Continuous batts reduce cutting waste in long-span attics and commercial roof assemblies.
- Rigid Panels:Factory-cut foam boards enable precise thermal bridge detailing in curtain wall and foundation systems.
- Loose Fill:Blown cellulose or fiberglass conforms to irregular cavities in historic building envelopes where invasive demolition is restricted.
Batts lead in installation simplicity, with rigid panels gaining specification intensity in high-performance commercial envelopes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating production to jurisdictions with lower energy costs and streamlined environmental compliance timelines. This regulatory arbitrage is redrawing supply maps as EU F-Gas phase-downs accelerate faster than North American equivalents.
Germany
Deep energy retrofit mandates and RE2020 embodied carbon disclosure rules drive specification toward mineral wool and wood fiber systems. The EU Green Deal renovation targets compress project timelines across the Rhine-Ruhr and Stuttgart manufacturing belts. BASF SE and Covestro AG anchor polyurethane supply chains in Ludwigshafen and Leverkusen chemical clusters.
United States
IRA tax credits for envelope improvements expand residential retrofit volumes while ASHRAE 90.1 standards tighten commercial thermal bridge requirements. OSHA isocyanate exposure limits reshape spray foam contractor certification pathways. Production concentrates in Ohio, Texas, and Georgia where fiberglass and rigid foam board capacity serves national distribution networks.
China
Dual carbon goals and GB standards for building energy efficiency accelerate mineral wool and fiberglass adoption in commercial construction. MIIT industrial policy favors domestic insulation material production for data center and cold chain infrastructure. Manufacturing clusters in Shandong and Jiangsu provinces supply both domestic retrofit pipelines and Southeast Asian export markets.
France
RE2020 regulation mandates lifecycle carbon accounting in public procurement, elevating cellulose and hemp fiber specifications. ANSM oversees workplace chemical exposure limits affecting spray foam application protocols. Lyon and Lille metropolitan areas concentrate retrofit activity where heritage building restrictions favor thin-profile aerogel solutions.
India
BIS standards adoption in commercial building codes creates specification pull for rigid foam and fiberglass systems in IT campus and pharmaceutical manufacturing construction. CEA energy efficiency directives for industrial facilities expand process insulation demand. Gujarat and Maharashtra industrial corridors concentrate manufacturing investment serving domestic and Middle Eastern export demand.
Insulation Products Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated material producers commanding premium positioning in specification-driven commercial envelopes while regional fabricators compete on installation speed and cost. The vendor base organizes around three strategic archetypes: chemical conglomerates with captive polymer supply, building materials specialists with envelope system integration capabilities, and regional insulation contractors with certified installer networks. Dominant competitive moves include backward integration into blowing agent and resin production to secure margin pools, plus geographic expansion through distributor acquisition in high-retrofit-velocity markets.
Among integrated building materials specialists, Owens Corning, Saint-Gobain, and Knauf Insulation occupy positions that exemplify the envelope-systems archetype. Owens Corning represents North American fiberglass-to-finished-system integration. Saint-Gobain anchors European specification channels through technical advisory positioning. Knauf Insulation sits within the acoustic-fire combined ratings tier that extends contract value beyond thermal performance alone.
| Leading Market Players |
|---|
| Owens Corning |
| Saint-Gobain |
| Rockwool International |
| Knauf Insulation |
| BASF SE |
| Kingspan Group |
| Johns Manville |
| Covestro AG |
| Dow Inc. |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap insulation specialists across Germany and the United States anchor supply discipline through generational capital structures that resist cyclical margin erosion. Their ownership patterns enforce pricing rigidity even when petrochemical feedstock volatility compresses downstream margins, creating asymmetric power against distributor networks.
Pricing Analysis
Capacity additions in China are reshaping price floors for fiberglass batt and rigid foam board categories. Three-tier pricing structure across premium, standard, and economy levels separates certified EPD-bearing systems from commodity-grade alternatives. Price differentiation hinges on thermal performance certification and embodied carbon disclosure tiers. Pricing pressure stems from MDI and polyol cost compression in spray foam segments. Residential retrofit contractors exhibit highest price sensitivity, while commercial facility managers prioritize lifecycle performance over unit cost.
Supply Chain Analysis
Regional distribution centers in Ohio, Texas, and Georgia operate hub-and-spoke patterns serving North American contractor networks. Manufacturing concentrates in Germany, the United States, and China, with Ludwigshafen and Leverkusen chemical clusters feeding polyurethane systems. Raw material dependencies include borosilicate glass, slag wool feedstock, and isocyanate precursors. Supply chain risk centers on single-source vulnerability for blowing agent formulations under EU F-Gas Regulation phase-downs. Distribution runs through specification-grade distributors and direct contractor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in premium-tier systems where embodied carbon disclosure commands specification premiums. Cost-down trajectories in cellulose and wood fiber processing unlock volume scalability without petrochemical exposure.
For Market Incumbents: Acquire certified installer networks to capture recurring maintenance revenue streams threatened by spray foam contractor scarcity. Defensive consolidation should target regional distributors in high-retrofit-velocity German and French markets. Backward integration into blowing agent production secures margin pools as EU F-Gas quotas tighten. For New Entrants and Emerging Players: Historic building preservation authorities represent an underserved buyer archetype with thin-profile aerogel demand unmet by conventional thickness limitations. White-space targets include Italian and United Kingdom facade upgrade pipelines restricted by heritage envelope depth constraints. Go-to-market positioning should emphasize acoustic-fire combined ratings that extend contract value beyond thermal metrics alone. For Investors and Strategic Acquirers: Valuations sit cheapest among regional insulation contractors with certified installer networks lacking national scale. Long-term viability favors asset-light specification platforms over capital-intensive manufacturing. Acquisition target archetype: envelope-system integrators with technical advisory capabilities tied to mineral wool installations. Signal to watch: EPD database hardening around environmental product declarations as procurement gate.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Blowing Agent Production | Captures margin pools as EU F-Gas Regulation phase-downs restrict hydrofluorocarbon supply. |
| Certified Installer Network Acquisition | Locks in deployment capacity constrained by OSHA isocyanate exposure training timelines. |
| Embodied Carbon Disclosure Investment | Positions systems for France RE2020 and California Buy Clean procurement mandates. |
| Technical Advisory Service Expansion | Mirrors Saint-Gobain's European specification channel anchoring through envelope engineering support. |
| Thin-Profile Retrofit Product Development | Addresses aerogel demand from Italian and United Kingdom heritage building preservation authorities. |
Study Parameters
Multiple input streams — primary fieldwork with spray foam contractors and facility managers, trade data reconciliation, and regulatory filing analysis — were reconciled to construct segment-level demand estimates. Industry stakeholders interviewed included commercial envelope specifiers, mineral wool plant managers, HVAC mechanical contractors, and building code officials across Germany, the United States, and China. Secondary validation drew from EU Green Deal implementation reports, ASHRAE 90.1 standard documentation, EPA ENERGY STAR certification databases, and customs records for borosilicate glass and isocyanate precursor trade flows. Bottom-up project pipeline enumeration was cross-checked against top-down construction spending allocation models.
Data-stream reconciliation applied product type, end-use sector, material chemistry, and installation form factor as segmentation dimensions across the analysis window. CAGRs were derived from retrofit cycle compression rates aligned with decarbonization timelines and new construction thermal bridge regulation adoption curves. Industry-specific forecast inputs included blower door testing mandate expansion rates and EPD database penetration by national building code.
Underlying measurement precision varies by segment; spray foam and aerogel categories carry tighter precision than commodity fiberglass batt volumes due to concentrated contractor reporting. Forecasts reflect documented assumptions regarding EU F-Gas quota enforcement timelines and IRA tax credit renewal probabilities. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Insulation Boards Market
Insulation Materials
Active Insulation Market
Insulation Materials
Wire Insulation and Jacketing Compounds Market
Insulation Materials
Microporous Insulation Material Market
Insulation Materials
Impact Sound Insulation Acoustic Mat Market
Insulation Materials
Global Insulation Market
Insulation Materials
Low Temperature Insulation Materials Market
Insulation Materials
Europe Phase Change Material Market
Insulation Materials
Global Industrial Foam Market
Insulation Materials
Global Extruded Polypropylene Foam Market
Insulation Materials
Global Advanced Insulation Material Market
Insulation Materials
Reflective Thermal Insulation Coatings Market
Insulation Materials
Global Low Smoke Halogen-Free Cable Materials Market
Insulation Materials
Fire Protective Materials Market
Insulation Materials
North America Expanded Polypropylene Foam Market
Insulation Materials
Global Molded Foams Market