
 Aircraft Weight Scale Market | 2026-2036
Aircraft Weight Scale Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Weight Scale Market Insights
Market Context
Multi-source procurement for load cell assemblies is expanding as maintenance facilities diversify supplier relationships beyond single-source dependencies. Intercomp Company leverages its Minnesota manufacturing base to sustain domestic production of portable aircraft scales for regional operators. Vishay Precision Group anchors the high-accuracy segment with strain gauge technologies that serve aerospace calibration laboratories. General Electrodynamics Corporation competes through specialized military and commercial platforms engineered for rapid deployment in field conditions.
Technical Definition and Segments
An aircraft weight scale is a precision ground support instrument that measures total aircraft mass and center-of-gravity positioning using distributed load points, typically achieving accuracy within 0.1 percent of reading through calibrated strain gauge or load cell architectures. These systems enable regulatory compliance with FAA and EASA weight-and-balance mandates while preventing unsafe flight configurations that arise from fuel loading errors or cargo distribution failures. Electronic scales dominate installed base value due to digital output integration with maintenance management software, while load cell technology leads new procurement as facilities replace legacy hydraulic platforms. Cargo weighing applications show the fastest structural expansion, driven by e-commerce freight volume and dedicated freighter conversions that require precise payload documentation for fuel optimization.
Regulatory Framework
FAA Advisory Circular 120-27E governs aircraft weight control programs and mandates periodic weighing intervals that sustain recurring equipment demand across certified repair stations. EASA CS-25 certification standards and the EU Green Deal emissions accounting protocols shape European procurement specifications, while China's CAAC aligns with GB standards for ground support equipment through NMPA-equivalent aviation safety channels. Stakeholders must monitor evolving battery-powered scale electrification standards and wireless data transmission security protocols that regulators will embed into next-generation certification requirements.
Market Dynamics
Fleet modernization cycles and regulatory recertification mandates are compressing replacement intervals for legacy hydraulic weighing platforms, forcing maintenance facilities to accelerate capital deployment toward electronic load cell architectures that interface directly with digital maintenance management ecosystems.
Growth Catalysts
- FAA Advisory Circular 120-27E:Mandated periodic weighing intervals sustain recurring equipment demand across certified repair stations and Part 145 maintenance organizations.
- E-commerce freight volume:Dedicated freighter conversions and cargo payload optimization requirements drive precision weighing infrastructure investment at express cargo hubs.
- Strain gauge miniaturization:Advances in microelectromechanical load sensing enable portable scale form factors that reduce aircraft downtime during field weighing operations.
Market Restraints
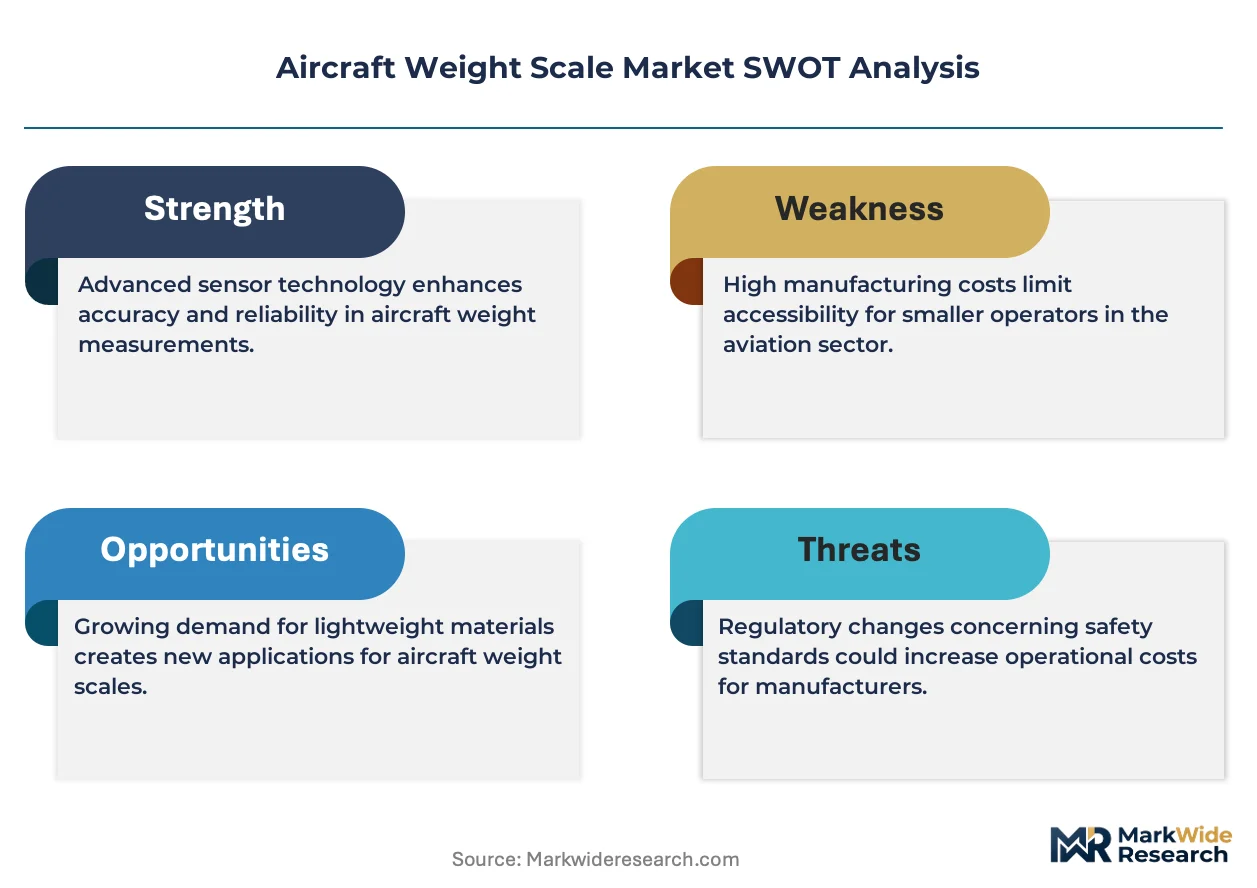
- Aluminum and semiconductor input costs:Load cell manufacturing depends on precision-machined aluminum alloys and analog-to-digital converter chips subject to supply volatility.
- Single-source calibration laboratory concentration:North American aerospace metrology services cluster around FAA-designated engineering representatives, creating bottleneck risk for scale recertification.
- Wireless electromagnetic interference:Bluetooth and Wi-Fi data transmission protocols face restricted use on active ramp areas due to avionics interference protocols.
Strategic Opportunities
- Battery-powered electrification standards:Emerging FAA guidelines for cordless ground support equipment open procurement pathways for lithium-ion powered portable scales.
- India MRO infrastructure expansion:Greenfield maintenance facilities at Delhi and Mumbai airports represent unserved demand for calibrated weighing systems under DGCA oversight.
- Machine vision convergence:Integration of optical center-of-gravity verification with load cell data creates automated weight-and-balance documentation workflows.
Industry Challenges
- Metrology technician scarcity:FAA-certified scale calibration requires specialized training that outpaces vocational program output in aviation maintenance hubs.
- Legacy system integration:Electronic scales must interface with proprietary maintenance management software from incumbent platform vendors, complicating procurement decisions.
Report Scope
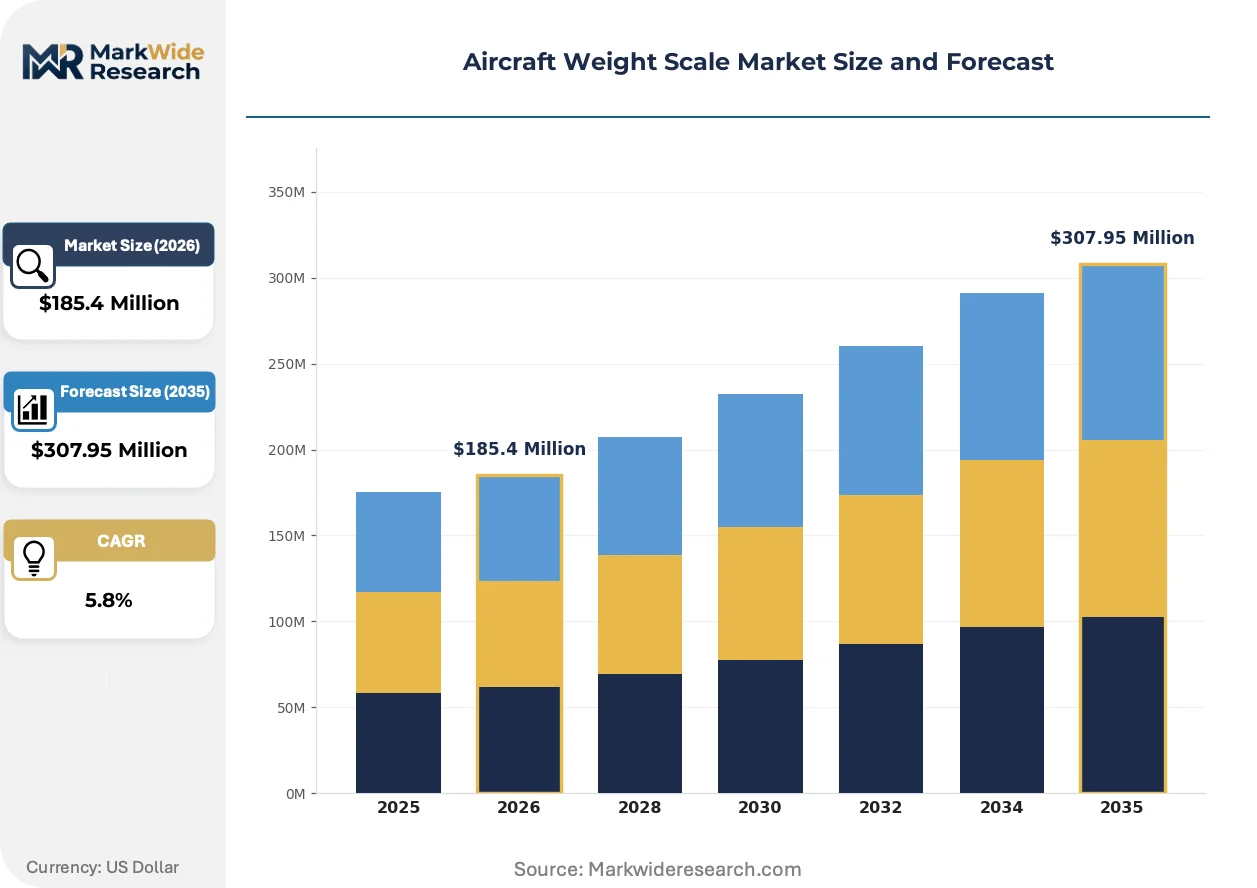
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Weight Scale Market |
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $307.95 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Scales, Electronic Scales, Hydraulic Scales, Digital Scales Technology: Load Cell, Strain Gauge, Pneumatic, Piezoelectric, Capacitive Application: Pre-flight Weight Measurement, Cargo Weighing, Maintenance Checks, Fuel Management End User: Aircraft Maintenance Facilities, Cargo Handlers, Airlines, Aerospace Engineering Firms |
| Companies Covered | Intercomp Company, Vishay Precision Group, General Electrodynamics Corporation, Teknoscale Oy, Jackson Aircraft Weighing Systems, Langa Industrial, Henk Maas Weegschalen BV, FEMA Airport, Alliance Scale, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Weight Scale Market Trends and Innovations
Digital thread connectivity and predictive maintenance algorithms are transforming aircraft weight scales from isolated measurement instruments into networked nodes within integrated fleet health monitoring architectures.
Wireless load cell networks with mesh topology protocols are rewriting how distributed weighing data aggregates across multi-point aircraft platforms. Regional carriers operating turboprop fleets adopt these systems fastest due to limited IT infrastructure. The technology is compressing weighing cycle times from hours to minutes while eliminating cable failure points in harsh ramp environments.
EU Green Deal emissions accounting protocols now mandate verified payload documentation for carbon offset eligibility, affecting European cargo operators most directly. Airlines retrofit existing scales with blockchain-anchored data logging to satisfy audit trail requirements. This regulatory pressure accelerates replacement of analog systems that lack tamper-evident digital outputs.
Leasing and managed service arrangements displace capital purchase models among mid-size cargo handlers seeking to convert fixed weighing infrastructure costs to variable per-use expenses. Third-party ground support equipment providers in the United States expand rental fleets with calibrated scale pools that rotate through seasonal demand peaks. This shift concentrates maintenance expertise with specialized lessors while reducing operator technical staffing requirements.
Aircraft Weight Scale Market Segmentation
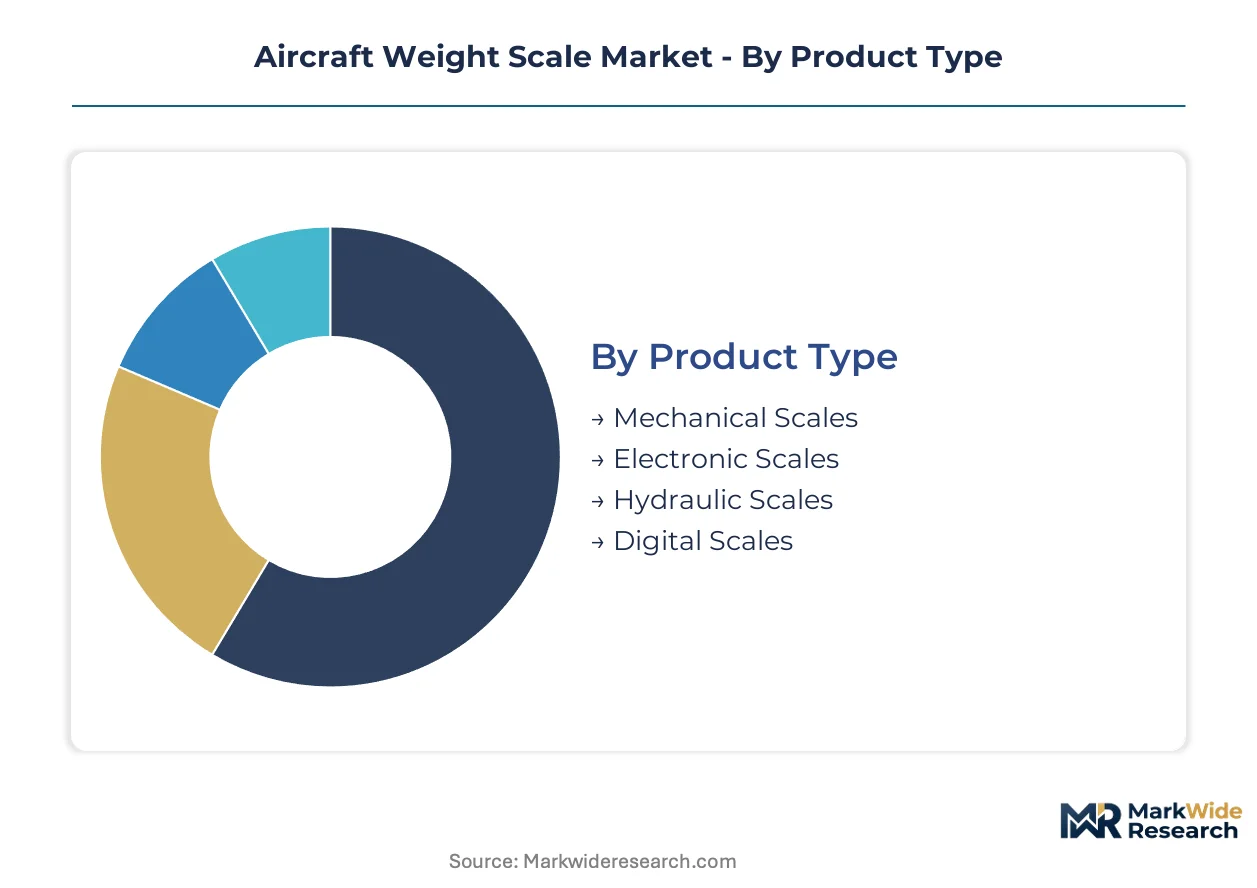
Aircraft weight scales serve distinct operational profiles across commercial aviation, military logistics, and MRO infrastructure. Product architecture and sensing technology choices directly determine certification pathways, calibration intervals, and total cost of ownership for fleet operators.
Product Type:
Electronic platforms command premium pricing through digital integration capabilities, while mechanical and hydraulic systems retain residual demand in cost-sensitive regional markets. The installed base splits between legacy analog infrastructure and networked electronic replacements.
- Electronic Scales:Strain gauge load cells with analog-to-digital conversion enable direct data export to maintenance management software. Airlines in the United States prioritize these systems for Part 145 repair station compliance with FAA Advisory Circular 120-27E documentation requirements.
- Digital Scales:Microprocessor-controlled platforms with touchscreen interfaces and wireless connectivity support rapid deployment scenarios. Cargo handlers at express freight hubs adopt these for throughput optimization during peak e-commerce seasons.
- Mechanical Scales:Spring-based or lever-arm architectures without electrical dependencies serve remote airfields with limited technical support infrastructure.
- Hydraulic Scales:Fluid-pressure measurement systems dominate legacy military installations and some emerging market maintenance facilities with established hydraulic tool ecosystems.
Today's leader: Electronic Scales. Tomorrow's challenger: Digital Scales.
Technology:
Load cell architectures generate the majority of new procurement value through standardized calibration protocols and supplier competition. Alternative sensing modalities address specialized environmental constraints or accuracy requirements.
- Load Cell:Resistive strain gauge elements in wheatstone bridge configurations deliver the 0.1 percent accuracy standard for commercial aviation certification. Maintenance facilities across North America and Europe specify these for interchangeability and traceable metrology chains.
- Strain Gauge:Thin-film or foil strain sensors bonded to precision-machined aluminum flexures enable miniaturized portable scale designs. Regional turboprop operators adopt these for field weighing without fixed pit infrastructure.
- Piezoelectric:Quartz crystal force sensors excel in dynamic load measurement applications where transient weight capture matters more than static precision.
- Pneumatic:Air-pressure based systems operate in explosive atmosphere environments where electrical ignition risks preclude electronic alternatives.
- Capacitive:Variable capacitance displacement sensors offer immunity to electromagnetic interference in high-RF ramp environments near active radar installations.
Load Cell holds the dominant share. Strain Gauge is climbing the fastest as portability requirements intensify.
Application:
Cargo weighing applications are expanding most quickly as e-commerce freight volumes drive dedicated freighter conversions and payload optimization imperatives. Pre-flight measurement remains the regulatory baseline sustaining recurring equipment demand.
- Cargo Weighing:Precision measurement of containerized and bulk freight enables fuel load optimization and center-of-gravity verification for express logistics operators. EU Green Deal emissions accounting protocols now mandate verified payload documentation for carbon offset eligibility.
- Pre-flight Weight Measurement:Regulatory-mandated total aircraft weighing and center-of-gravity calculation prevents unsafe flight configurations. FAA Part 121 operators conduct these checks at prescribed intervals per Advisory Circular 120-27E.
- Maintenance Checks:Periodic weighing during heavy maintenance intervals tracks aircraft weight growth from modifications, repairs, and accumulated contamination.
- Fuel Management:Fuel load verification scales support tankering optimization and regulatory compliance with maximum zero-fuel weight limits.
Cargo Weighing is gaining share fastest. Pre-flight Weight Measurement defends the volume base.
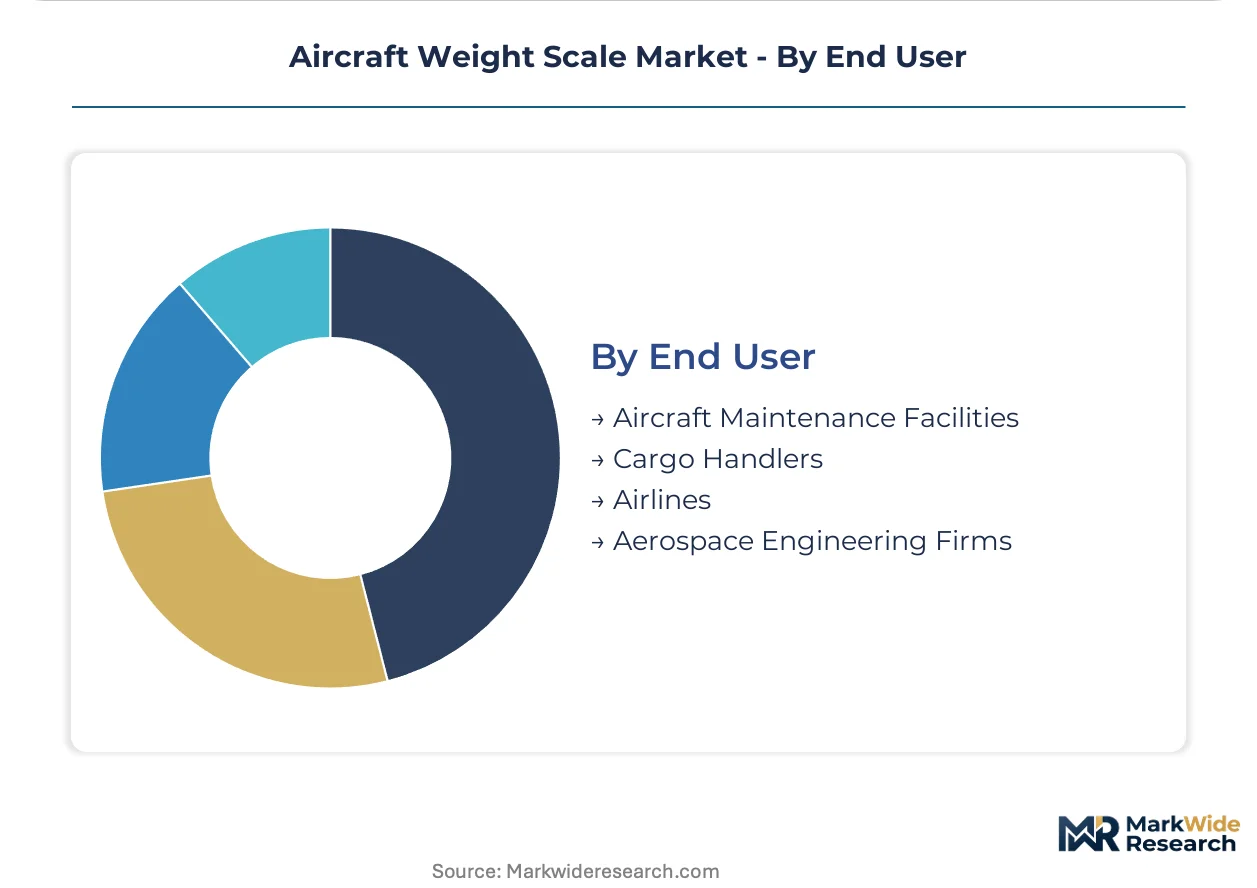
End User:
Aircraft maintenance facilities concentrate capital deployment for regulatory compliance, while cargo handlers drive technology refresh cycles through operational efficiency imperatives. Airlines balance in-house capability against third-party MRO outsourcing.
- Cargo Handlers:Express logistics providers and dedicated freight operators invest in high-throughput weighing infrastructure at hub airports. These users prioritize speed and integration with warehouse management systems over absolute accuracy.
- Aircraft Maintenance Facilities:Part 145 certified repair stations and airline technical operations centers maintain calibration-certified scales for regulatory weighing mandates. These facilities anchor demand for traceable metrology and FAA-recognized engineering representative oversight.
- Airlines:Network carriers and low-cost operators deploy scales across line maintenance stations and heavy check facilities, with procurement decisions influenced by fleet standardization strategies.
- Aerospace Engineering Firms:Design organizations and modification specialists require precision weighing for prototype certification, flight test programs, and supplemental type certificate validation.
Aircraft Maintenance Facilities anchor current demand. Cargo Handlers represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as manufacturers migrate toward jurisdictions with streamlined aerospace equipment certification pathways and concentrated MRO infrastructure investment.
United States
Major network carriers operate the world's largest commercial fleets, sustaining dense maintenance infrastructure across the Sun Belt and Midwest. FAA Advisory Circular 120-27E mandates periodic weighing intervals that drive recurring equipment demand through Part 145 repair stations. Dallas-Fort Worth and Atlanta anchor the heaviest concentration of heavy-check facilities where calibrated scale procurement concentrates.
Germany
Lufthansa Technik and premium cargo handlers sustain demand for high-accuracy weighing systems integrated with digital maintenance workflows. EASA CS-25 certification standards and EU Green Deal emissions accounting protocols shape procurement specifications toward tamper-evident digital outputs. The Hamburg aviation cluster drives specialized scale deployment for freighter conversion programs and cargo payload optimization.
China
CAAC-aligned GB standards for ground support equipment channel procurement through NMPA-equivalent aviation safety channels as domestic MRO capacity expands. COMAC fleet introduction and airport infrastructure buildout in Chengdu and Xi'an create calibrated equipment demand. The Yangtze River Delta concentrates manufacturing investment for load cell assemblies serving both domestic and export markets.
India
DGCA oversight of greenfield maintenance facilities at Delhi and Mumbai airports represents unserved demand for traceable metrology systems. The country's civil aviation regulator tightens weight-and-balance compliance requirements as international traffic recovers. Bengaluru's emerging aerospace manufacturing corridor attracts calibration laboratory investment to reduce single-source dependencies.
United Kingdom
Heathrow and East Midlands cargo hubs drive precision weighing infrastructure for express logistics operators under CAA regulatory frameworks. Post-Brexit divergence from EASA standards creates dual-certification complexity for equipment suppliers. The Midlands aerospace cluster sustains demand for portable scale systems supporting defense and commercial maintenance operations.
Aircraft Weight Scale Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue wireless connectivity and battery-powered electrification to differentiate field-deployment capabilities. The vendor base organizes around three archetypes: precision sensor specialists with aerospace calibration heritage, diversified ground support equipment manufacturers leveraging distribution scale, and regional fabricators serving cost-sensitive maintenance facilities. Consolidation pressure intensifies as load cell commoditization compresses margins at the mid-market tier. Strategic moves center on technology licensing partnerships for digital thread integration and geographic expansion through MRO service network acquisitions.
Within the precision sensor tier, Vishay Precision Group anchors high-accuracy positioning through strain gauge heritage, while Intercomp Company exemplifies domestic manufacturing concentration for portable platform supply. General Electrodynamics Corporation occupies a position bridging military specification and commercial rapid-deployment requirements. These three represent distinct competitive vectors: laboratory-grade calibration, regional operator accessibility, and field-hardened mobility.
| Leading Market Players |
|---|
| Intercomp Company |
| Vishay Precision Group |
| General Electrodynamics Corporation |
| Teknoscale Oy |
| Jackson Aircraft Weighing Systems |
| Langa Industrial |
| Henk Maas Weegschalen BV |
| FEMA Airport |
| Alliance Scale |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists in Minnesota and Ohio anchor domestic production of portable aircraft scales, their conservative balance sheets enabling pricing discipline even as aluminum and semiconductor input costs fluctuate. Their ownership structure insulates pricing from quarterly earnings pressure while sustaining long-term supplier relationships with FAA-designated calibration laboratories.
Pricing Analysis
Distributor margins of 15-25 percent separate factory pricing from end-user acquisition costs, with direct-to-OEM volume discounts compressing this spread for fleet-standardization contracts. Three-tier pricing structure across laboratory-grade, field-certified, and economy portable levels reflects certification grade and traceable metrology chain length. Pricing pressure stems from load cell commoditization at the mid-market tier as Asian suppliers enter with GB-standard equipment. Regional turboprop operators exhibit highest price sensitivity, while Part 145 repair stations prioritize calibration traceability over unit cost.
Supply Chain Analysis
Domestic-content mandates in FAA procurement specifications reshape sourcing toward US-machined aluminum flexures and strain gauge assemblies. Manufacturing concentrates in Minnesota, Ohio, and California for precision-machined components, with analog-to-digital converter chips drawing from Taiwan and South Korea supply chains. Single-source vulnerability concentrates in aerospace-grade aluminum alloys subject to tariff exposure. Distribution runs through specialized ground support equipment dealers and direct OEM relationships, with leasing companies emerging as volume aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as airlines consolidate procurement around traceable metrology and digital maintenance integration, displacing lowest-bidder selection criteria.
For Market Incumbents: Lock in calibration laboratory partnerships to defend against emerging entrants offering wireless connectivity without FAA-recognized engineering representative oversight. Deepen backward integration into strain gauge assembly to capture margin compression from commoditized load cells. Prioritize certification investment for battery-powered electrification standards before regulatory mandates harden. For New Entrants and Emerging Players: Begin with India's greenfield MRO infrastructure at Delhi and Mumbai airports, where DGCA oversight creates demand without entrenched incumbent relationships. Target cargo handlers seeking per-use leasing models rather than capital purchase, using managed service arrangements to bypass upfront scale certification barriers. Lead with lithium-ion portable platforms to differentiate from legacy hydraulic installed base. For Investors and Strategic Acquirers: Valuations sit cheapest among regional fabricators serving cost-sensitive maintenance facilities, their undifferentiated product lines exposed to Asian import competition. Long-term viability hinges on digital thread integration capabilities and MRO service network density. Watch for FAA guidance finalization on cordless ground support equipment as inflection signal for electrification capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Laboratory Acquisition | Captures recurring recertification revenue streams under FAA Advisory Circular 120-27E mandates. |
| Wireless Load Cell Certification | Opens procurement pathways as FAA relaxes electromagnetic interference restrictions on active ramp areas. |
| India MRO Service Network Entry | Positions for DGCA-oversight demand at greenfield Delhi and Mumbai maintenance facilities. |
| Leasing Fleet Expansion | Converts fixed infrastructure costs to variable per-use expenses for mid-size cargo handlers. |
| Machine Vision Integration Partnership | Combines optical center-of-gravity verification with load cell data for automated documentation workflows. |
Research Methodology
Bottom-up MRO facility modeling reconciled against top-down load cell supplier tracking forms the analytical core of this study. Primary interviews with Part 145 repair station managers, FAA-designated engineering representatives, airline technical procurement officers, and ground support equipment lessors combined with secondary validation from FAA Advisory Circulars, EASA CS-25 certification databases, SEC 10-K filings of precision sensor manufacturers, and customs trade records for aluminum alloy and semiconductor imports.
Input-output matrices across product type, sensing technology, application, and end-user dimensions drive volume and value projections throughout the forecast period. CAGRs derive from segment-level demand elasticity modeling against fleet modernization cycles and regulatory recertification intervals. Industry-specific forecast inputs include commercial aircraft delivery schedules, dedicated freighter conversion pipelines, and MRO infrastructure investment announcements.
Caveats apply where FAA electrification standard timelines or aluminum tariff regimes could materially shift the outlook for battery-powered scale adoption and input cost structures. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
MRO Protective Coatings Market
Aircraft Maintenance and MRO Solutions
Aviation MRO Software Market
Aircraft Maintenance and MRO Solutions
Aircraft Tire Balancer Market
Aircraft Maintenance and MRO Solutions
Aircraft Recycling Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Landing Gear MRO Market
Aircraft Maintenance and MRO Solutions
Helicopter MRO Market
Aircraft Maintenance and MRO Solutions
On-Premises MRO Software Market
Aircraft Maintenance and MRO Solutions
US Aviation MRO Software Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Training Market
Aircraft Maintenance and MRO Solutions
Air Transport MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Autoclave Market
Aircraft Maintenance and MRO Solutions
Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Airline Maintenance Software Market
Aircraft Maintenance and MRO Solutions
Aviation Engine MRO Market
Aircraft Maintenance and MRO Solutions
US Aerospace Components MRO Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Maintenance Repair and Overhaul (MRO) Market