
 Nanopore Technologies Market | 2026-2036
Nanopore Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Nanopore Technologies Market Intelligence
The unbundling of sequencing chemistries from proprietary hardware platforms is broadening access for smaller research groups and diagnostic laboratories. This modular approach allows for greater flexibility in experimental design. Oxford Nanopore Technologies leverages its portable device strategy to penetrate field-based research and point-of-care applications. In contrast, Pacific Biosciences differentiates with a focus on high-fidelity, long-read sequencing systems targeted at large-scale genomic research centers requiring maximum data accuracy.
Nanopore technologies identify molecules by threading them through a protein or solid-state pore, often just a few nanometers in diameter, and measuring resulting disruptions in an ionic current. This method enables real-time, direct analysis of single molecules like DNA or RNA without requiring prior amplification. DNA sequencing constitutes the primary application, driving development across the sector. While on-premise, high-throughput setups serve large genomic research centers, portable devices represent the fastest-growing deployment mode, enabling new applications in environmental and infectious disease monitoring.
Regulatory frameworks for clinical diagnostics govern market entry for many nanopore applications. In the United States, the FDA’s clearance pathways for medical devices are critical for platforms intended for patient diagnosis. Similarly, CE marking under the Medical Device Regulation (MDR) is mandatory for market access in Europe. The successful navigation of these regulatory hurdles for diagnostic use cases will determine the technology's ultimate clinical and commercial impact.
Market Dynamics
The unbundling of sequencing chemistries from proprietary hardware platforms is the central force shaping the market. This modularity democratizes access to genomic sequencing, shifting power away from integrated system providers and enabling greater experimental flexibility for a broader range of research and clinical users.
Growth Catalysts
- Portable Sequencing Devices:The continued development of portable, real-time sequencing devices enables new applications in field-based environmental monitoring, agriculture, and infectious disease surveillance, expanding the user base beyond traditional laboratories.
- Public Health Investment:Increased government funding for pathogen genomics, exemplified by initiatives from the WHO and national public health agencies, accelerates the adoption of nanopore technology for real-time outbreak tracking and surveillance.
- US Research Funding:Substantial federal research investment from agencies like the National Institutes of Health (NIH) in the United States supports academic and genomic centers, creating concentrated demand for advanced sequencing technologies.
Market Restraints
- Data Accuracy Limitations:Higher intrinsic error rates compared to established short-read sequencing methods remain a technical barrier for clinical applications that demand maximum data fidelity, such as certain cancer genomics and rare disease diagnostics.
- Consumable Costs:The recurring cost of proprietary flow cells and reagents can present a significant financial barrier for smaller labs or projects with limited budgets, offsetting the low initial capital expenditure for some hardware.
- Regulatory Validation Hurdles:The complex and lengthy process for obtaining FDA premarket approval or European CE marking for in vitro diagnostic (IVD) use slows the translation of nanopore technologies into routine clinical practice.
Strategic Opportunities
- Direct RNA and Protein Sequencing:Expanding beyond DNA to direct RNA and protein sequencing opens new frontiers in transcriptomics and proteomics, providing novel insights into biological processes without the need for reverse transcription or complex sample preparation.
- Point-of-Care Diagnostics:Developing simplified, ruggedized systems for point-of-care diagnostics in low-resource settings, particularly in Southeast Asia and Africa, addresses unmet needs in infectious disease management where laboratory infrastructure is limited.
- AI-Powered Data Analysis:The convergence of nanopore sequencing with advanced machine learning algorithms offers a significant opportunity to improve real-time base calling accuracy, streamline data analysis, and accelerate the interpretation of complex genomic data.
Industry Challenges
- Bioinformatics Skill Gaps:A shortage of bioinformaticians trained to manage and interpret the unique characteristics of long-read, real-time sequencing data creates a bottleneck for many research groups and clinical labs adopting the technology.
- Lack of Standardization:The absence of universally accepted standards for data formats, quality control metrics, and analytical pipelines across different nanopore platforms complicates data sharing, reproducibility, and cross-study comparisons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanopore Technologies Market |
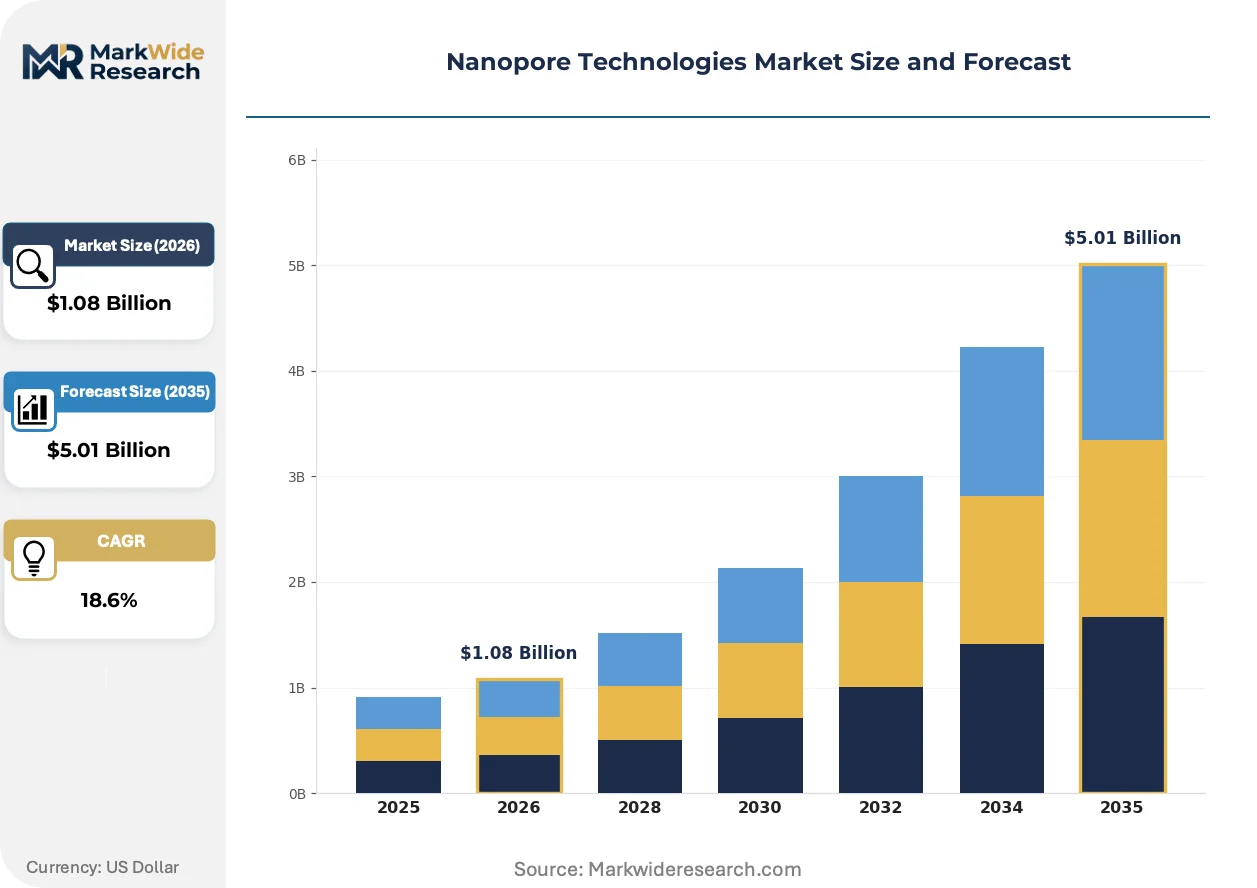
| Market Size in 2026 | $1.08 Billion |
| Market Size in 2035 | $5.01 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Biological Nanopores, Solid-State Nanopores, Hybrid Nanopores, Synthetic Nanopores Application: DNA Sequencing, Protein Analysis, Biomarker Detection, Drug Discovery, Pathogen Identification End User: Genomic Research Centers, Pharmaceutical Firms, Diagnostic Laboratories, Academic Institutions Deployment Mode: On-Premise Systems, Cloud-Integrated Platforms, Portable Devices, High-Throughput Setups |
| Companies Covered | Thermo Fisher Scientific, F. Hoffmann-La Roche, Oxford Nanopore Technologies, NorthShore Bio, Nabsys, Pacific Biosciences, QIAGEN, Electronic BioSciences, Agilent Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanopore Technologies Market Strategic Shifts & Innovations
A fundamental shift from centralized, high-throughput sequencing to distributed, application-specific analysis is underway. This transformation is driven by technological miniaturization and a demand for immediate, actionable genomic information at the point of need, rather than in a remote core facility.
Portable, real-time nanopore sequencers enable the direct analysis of nucleic acids without prior amplification. Field researchers and public health officials are adopting these devices for on-site environmental DNA (eDNA) monitoring and rapid pathogen identification. This technology is decentralizing genomic analysis away from large, capital-intensive centers, empowering immediate decision-making in diverse settings from remote ecosystems to clinical wards.
The European Union’s Medical Device Regulation (MDR) is setting a higher bar for clinical validation. This regulation imposes more stringent requirements for clinical evidence and post-market surveillance on any sequencing platform intended for diagnostic purposes. Manufacturers targeting the European clinical market must now invest in more rigorous validation studies to achieve the necessary CE marking for their systems and assays.
Flexible purchasing models are gaining traction over traditional, closed-system sales. The unbundling of sequencing chemistries from specific hardware allows laboratories to source reagents and software from third-party vendors, disrupting the razor-and-blade business model. This trend is most prominent within academic research groups in North America and Europe that prioritize experimental flexibility and cost control.
Nanopore Technologies Market Segmentation
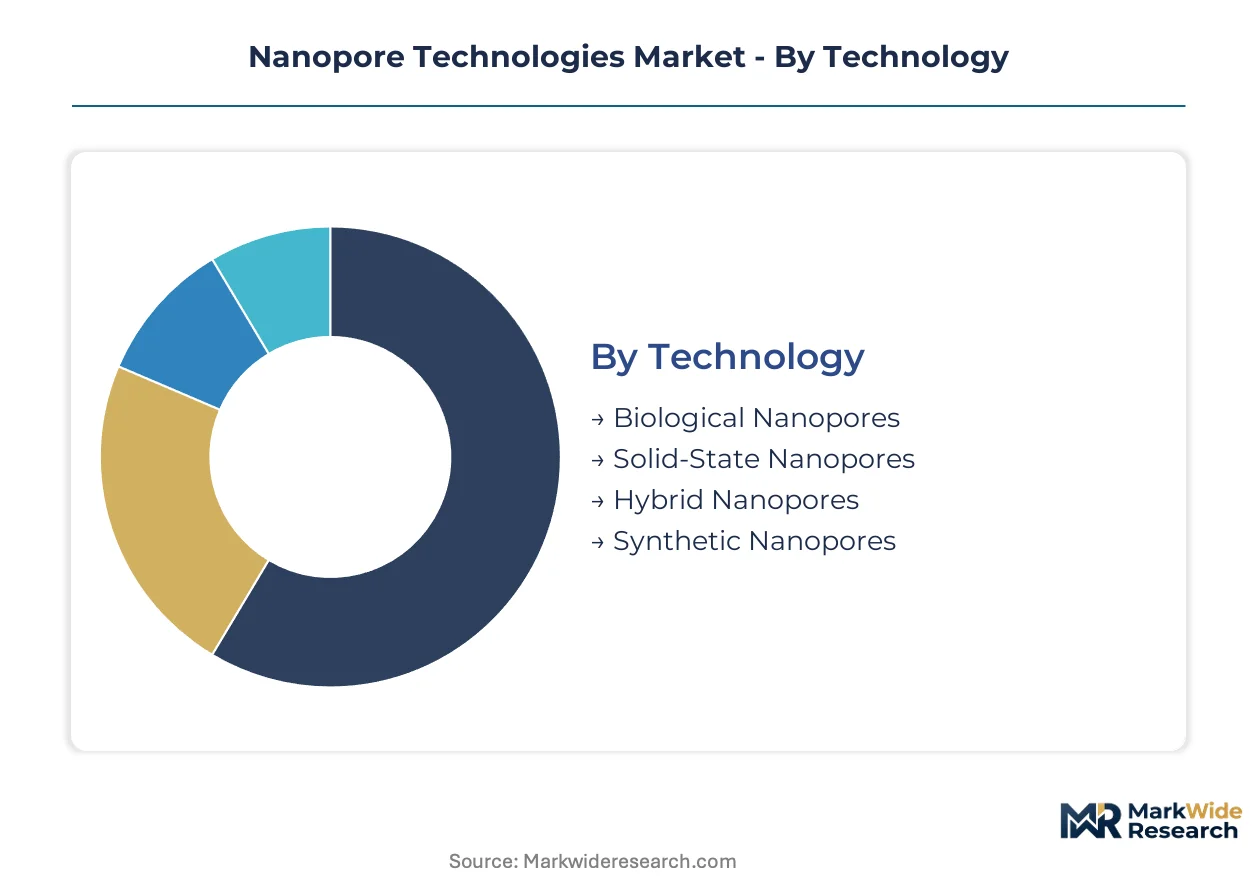
The Nanopore Technologies Market is segmented across several critical dimensions, reflecting the diverse technological approaches, varied applications, and distinct end-user requirements driving its expansion. Understanding these segments is crucial for identifying areas of concentrated demand and emerging opportunities.
Technology:
The choice of nanopore technology often hinges on the desired analytical resolution, throughput requirements, and the specific molecular targets for sequencing or detection.
- Biological Nanopores:These use naturally occurring or engineered protein pores embedded in a membrane, forming the basis for commercially available real-time sequencing platforms. Demand concentrates in academic research and public health surveillance due to their established performance and portability.
- Solid-State Nanopores:Fabricated from synthetic materials like silicon nitride or graphene, these pores offer high stability and tunable dimensions for advanced single-molecule analysis. Research in the United States is exploring their potential for ultra-high throughput and direct protein sequencing.
- Hybrid Nanopores:These combine aspects of both biological and solid-state approaches, aiming to leverage the strengths of each for improved performance or novel applications. These are primarily in early-stage research and development within specialized university labs.
- Synthetic Nanopores:Entirely synthetic structures, often polymer-based, are designed for specific molecular interactions and offer high customizability for niche diagnostic or sensing applications.
Biological Nanopores lead on current market scale; Solid-State Nanopores lead on technological momentum.
Application:
Nanopore technologies find diverse utility across various scientific and clinical applications, each demanding specific performance characteristics from the underlying platform.
- DNA Sequencing:This application involves reading the base sequence of DNA in real-time, enabling rapid genomic analysis for research, clinical diagnostics, and infectious disease tracking. Demand is driven by the need for long-read sequencing in complex genome assembly and structural variation detection.
- Pathogen Identification:This application utilizes nanopore devices for rapid, on-site detection and characterization of bacteria, viruses, and other pathogens, critical for public health and outbreak response. The WHO and national public health agencies are investing in this capability for global surveillance.
- Protein Analysis:This emerging application aims to directly sequence or characterize individual protein molecules, offering new insights into proteomics without traditional labeling methods. Early research is concentrated in specialized academic centers exploring novel biomarker discovery.
- Biomarker Detection:This involves identifying specific molecular indicators of disease or biological states, leveraging nanopore's single-molecule sensitivity for early diagnosis. This is an area of active development within diagnostic laboratories in Europe.
- Drug Discovery:Nanopore platforms are employed in various stages of drug discovery, including target validation, screening for drug-target interactions, and nucleic acid-based therapeutic development. Pharmaceutical firms are exploring their utility for high-throughput screening.
DNA Sequencing remains the foundational application, while Pathogen Identification offers significant public health impact.
End User:
Different end-user segments leverage nanopore technology based on their operational scale, regulatory environment, and primary research or clinical objectives.
- Genomic Research Centers:These large-scale facilities conduct extensive genomic studies, requiring high-throughput sequencing capabilities and robust bioinformatics support. Federal funding from agencies like the NIH in the United States sustains significant demand from these centers.
- Diagnostic Laboratories:Clinical laboratories utilize nanopore technology for patient testing, requiring regulatory validation and integration into existing diagnostic workflows. FDA clearance pathways and CE marking are critical for market entry in this segment.
- Pharmaceutical Firms:Companies in the pharmaceutical industry use nanopore sequencing for drug development, quality control, and understanding disease mechanisms. These firms prioritize data accuracy and scalability for their research pipelines.
- Academic Institutions:Universities and other academic research groups employ nanopore devices for basic scientific discovery, technology development, and educational purposes. Flexible purchasing models and lower capital expenditure appeal to these groups.
Genomic Research Centers consume the largest volume, with Diagnostic Laboratories representing a critical area for future expansion.
Deployment Mode:
The choice of deployment mode reflects an organization's need for real-time analysis, data processing capacity, and infrastructure availability.
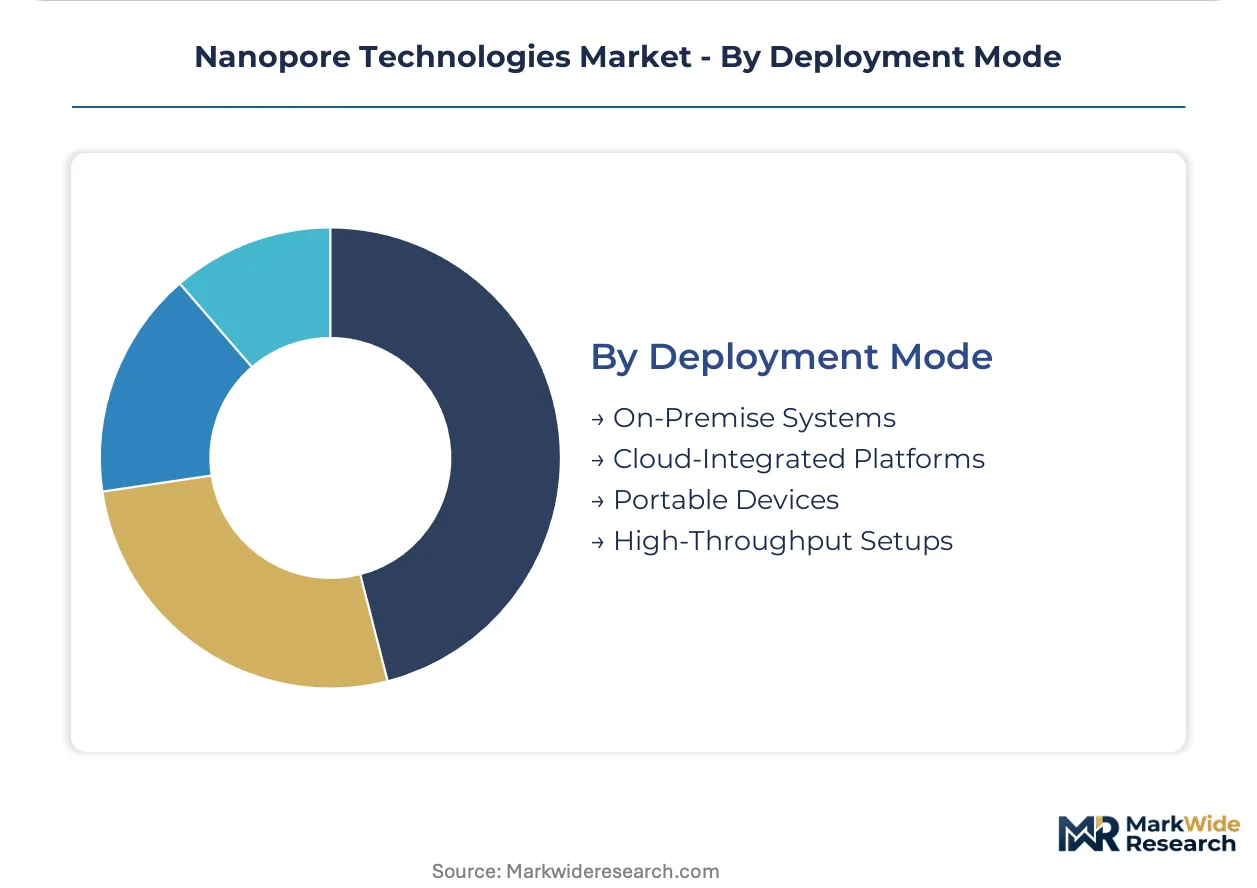
- On-Premise Systems:These involve hardware and software installed and managed directly by the end-user organization, offering maximum control over data and security. Large research centers with dedicated IT infrastructure favor this mode.
- Cloud-Integrated Platforms:These leverage cloud computing resources for data storage, processing, and analysis, providing scalability and reducing the need for extensive local IT infrastructure. Smaller labs and remote research teams benefit from this flexibility.
- Portable Devices:Compact, handheld sequencers enable real-time analysis in field settings, at the point of care, or in remote locations without extensive laboratory facilities. Public health initiatives in Southeast Asia are adopting these for infectious disease monitoring.
- High-Throughput Setups:These systems are designed for processing a large volume of samples efficiently, typically found in core genomic facilities and large research institutions. These setups are essential for population-scale genomic projects.
Portable Devices are expanding most quickly, while High-Throughput Setups remain essential for large-scale genomic projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Nanopore Technologies Market, having its foundational scaling in advanced research institutions, has expanded from its origins in academic laboratories to a global commercial presence. Early development in sequencing methods, particularly in the United States and the United Kingdom, laid the groundwork for current market expansion. This technological lineage underpins the diverse regional adoption patterns observed today.
United States
Demand for nanopore technologies in the United States is driven by extensive federal research funding and a dense network of genomic centers. The National Institutes of Health (NIH) provides substantial grants supporting academic and clinical research in advanced sequencing. Major genomic research hubs like those in Boston, Massachusetts, and San Francisco, California, demonstrate concentrated demand for high-throughput and portable systems.
Germany
Germany exhibits strong demand for nanopore solutions within its robust pharmaceutical and biotech sectors, alongside a growing focus on public health applications. The European Medical Device Regulation (MDR) influences market entry for diagnostic platforms, necessitating rigorous validation. Research clusters in cities like Heidelberg and Berlin are actively exploring novel applications in biomarker detection and advanced genomic analysis.
United Kingdom
The United Kingdom's nanopore market benefits from pioneering research and the presence of key technology developers. Regulatory bodies like the Medicines and Healthcare products Regulatory Agency (MHRA) oversee clinical applications, ensuring device safety and efficacy. Oxford, England, serves as a significant hub for nanopore technology innovation, with companies commercializing portable sequencing devices for global use.
Japan
Japan's market for nanopore technologies is characterized by strong investment in advanced research and development, particularly in precision medicine and infectious disease monitoring. The Pharmaceuticals and Medical Devices Agency (PMDA) regulates clinical applications, guiding market access for diagnostic tools. Research institutions in Tokyo and Kyoto are actively integrating nanopore sequencing into large-scale genomic projects and drug discovery initiatives.
Nanopore Technologies Market Key Industry Players
The competitive structure tilts toward a blend of diversified life science giants and specialized sequencing innovators. The market exhibits moderate concentration, with a few dominant players offering comprehensive solutions alongside several agile firms focusing on niche applications and emerging technologies. Companies actively engage in strategic partnerships to expand their technological capabilities and pursue portfolio diversification into new application areas, such as direct RNA sequencing and advanced biomarker detection.
Within the specialized sequencing innovator tier, Oxford Nanopore Technologies, a UK-based company, exemplifies the focus on portable, real-time sequencing devices for field-based research and point-of-care applications. Pacific Biosciences, a US-based corporation, represents the high-fidelity, long-read segment, catering to large-scale genomic research centers requiring maximum data accuracy. Thermo Fisher Scientific, a major US-headquartered life sciences firm, occupies a broader position, leveraging its extensive R&D and distribution networks to offer a wide array of laboratory solutions, including components that integrate with nanopore workflows.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| F. Hoffmann-La Roche |
| Oxford Nanopore Technologies |
| NorthShore Bio |
| Nabsys |
| Pacific Biosciences |
| QIAGEN |
| Electronic BioSciences |
| Agilent Technologies |
| Others |
Cost & Logistics Intelligence
Regulatory validation hurdles for clinical diagnostics in the United States and Europe mandate significant supplier investment, impacting pricing strategies. This demand for validated solutions influences proprietary reagent and hardware costs, shaping the market's supply chain responsiveness.
Pricing Analysis
A hybrid transactional and modular purchasing model characterizes nanopore technology pricing. Brand premium from established players and specific regulatory certifications like FDA approval or CE marking drive price differentiation. Cost compression in consumables is intensifying due to increasing competition and the availability of third-party reagents. Academic institutions and smaller research groups exhibit high price sensitivity for recurring consumable costs, while large genomic research centers prioritize data accuracy and throughput, showing less sensitivity.
Supply Chain Analysis
Proprietary flow cell and reagent supply for nanopore technologies primarily centers on manufacturers in the United Kingdom and the United States. This supply chain draws from specialized biochemical reagents, biological protein pores, and synthetic solid-state materials like silicon nitride. Single-source vulnerability for proprietary consumable components remains a structural risk, particularly for specialized flow cells. Distribution occurs through direct sales to large genomic research centers and diagnostic laboratories, complemented by specialized distributors for academic institutions and field deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Nanopore Technologies Market is transforming into a late-cycle quality story, driven by a demand shift toward premium specifications for clinical diagnostics. This transition necessitates greater data accuracy and regulatory validation for widespread adoption in patient care settings.
For Market Incumbents:
Extend regulatory validation efforts across diverse clinical applications, particularly for FDA premarket approval and European CE marking. This move counters the threat of data accuracy limitations compared to established short-read methods. Deepen strategic partnerships with diagnostic laboratories to integrate nanopore platforms into existing workflows. Investment in AI-powered data analysis serves as a critical lever to improve real-time base calling and data interpretation.
For New Entrants and Emerging Players:
Enter via direct RNA and protein sequencing, exploring novel insights beyond DNA. Focus on developing simplified, ruggedized systems for point-of-care diagnostics, particularly in low-resource settings across Southeast Asia and Africa. This addresses unmet needs in infectious disease management where laboratory infrastructure is limited. A strong go-to-market angle involves offering modular, cost-effective solutions for field-based environmental monitoring.
For Investors and Strategic Acquirers:
Asymmetric upside sits with agile firms developing novel nanopore chemistries or advanced bioinformatics solutions. The market offers substantial long-term growth potential over the next decade, driven by expanding applications in clinical diagnostics and pathogen surveillance. Target acquisition profiles include specialized firms focused on solid-state nanopores or AI-powered data analysis. A successful FDA or CE marking for a new diagnostic platform represents a critical signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Regulatory Validation Portfolio | Securing FDA premarket approval strengthens market access for diagnostic laboratories in the United States. |
| Invest in AI-Powered Bioinformatics | Enhancing base calling accuracy and streamlining data analysis accelerates genomic interpretation for research centers. |
| Develop Direct RNA/Protein Sequencing | Unlocking novel insights into transcriptomics and proteomics creates new biomarker discovery opportunities in Europe. |
| Forge Point-of-Care Partnerships | Deploying ruggedized systems addresses unmet infectious disease management needs in Southeast Asia. |
| Diversify Consumable Supply Chains | Reducing single-source vulnerability for proprietary flow cells enhances operational resilience for pharmaceutical firms. |
Research Approach
Multiple input streams — primary interviews, industry reports, and regulatory filings — were reconciled to build a comprehensive market view. This involved extensive conversations with genomic research center directors, diagnostic laboratory managers, pharmaceutical R&D leads, and public health officials. Secondary validation drew from FDA filings, CE marking documentation, NIH grant databases, and WHO reports. Both bottom-up and top-down triangulation methods were applied to ensure data consistency.
Data stream reconciliation informed a robust analytical framework applied across the analysis window. Segmentation dimensions modeled included technology type, application area, end-user segment, deployment mode, and regional adoption patterns. Compound annual growth rates were derived by assessing historical trends and projecting future market drivers. Key industry-specific inputs included R&D spending in genomics and regulatory approval timelines for new diagnostic platforms.
Inputs from publicly available financial reports and scientific publications were available through the study window; gaps in proprietary R&D budgets and specific clinical trial outcomes introduce uncertainty bands. Forecasts reflect assumptions regarding evolving regulatory landscapes and rapid technological advancements. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanobiotechnology
Boron Nitride Nanotubes in Nanomedicine Market
Nanobiotechnology
Nanobiotechnology Market
Nanobiotechnology
Nano Biosensors Market
Nanobiotechnology
Nanopore Sequencing Market
Nanobiotechnology
Europe Nanozymes Market
Nanobiotechnology
Nanozymes Market
Nanobiotechnology
Designer DNA Nanocages Market
Nanobiotechnology
Nanotechnology Drug Delivery Market
Nanobiotechnology
Nanopharmaceuticals Market
Nanobiotechnology
Europe Molecular Biosensors Market
Nanobiotechnology
Nanobody Market
Nanobiotechnology
Bio-Inspired and Nano-Engineered Surfaces Market