
 US Direct-To-Consumer Genetic Testing Market | 2026-2036
US Direct-To-Consumer Genetic Testing Market Size, Share, and Industry Trends Forecast 2026-2036
US Direct-To-Consumer Genetic Testing Market Analysis
Clinical-grade sequencing accuracy is collapsing toward consumer price points, forcing incumbents to recalibrate quality tiers. 23andMe leverages its FDA-cleared health risk reports to sustain premium positioning. Ancestry.com anchors the heritage segment through database scale. Color Health specializes in employer-sponsored preventive screening, differentiating beyond recreational genealogy.
Direct-to-consumer genetic testing delivers SNP-based or whole-genome analysis of saliva-derived DNA, generating ancestry, health risk, and pharmacogenomic reports without clinician intermediation. The primary commercial purpose spans personal health management, genealogical discovery, and increasingly, preventive care integration with primary physicians. Health risk testing captures the fastest margin expansion as FDA 510(k) clearances validate clinical utility, while ancestry testing matures into a subscription-renewal model. SNP analysis dominates volume due to cost efficiency, though whole genome sequencing is gaining traction among early adopters seeking comprehensive pharmacogenomic data.
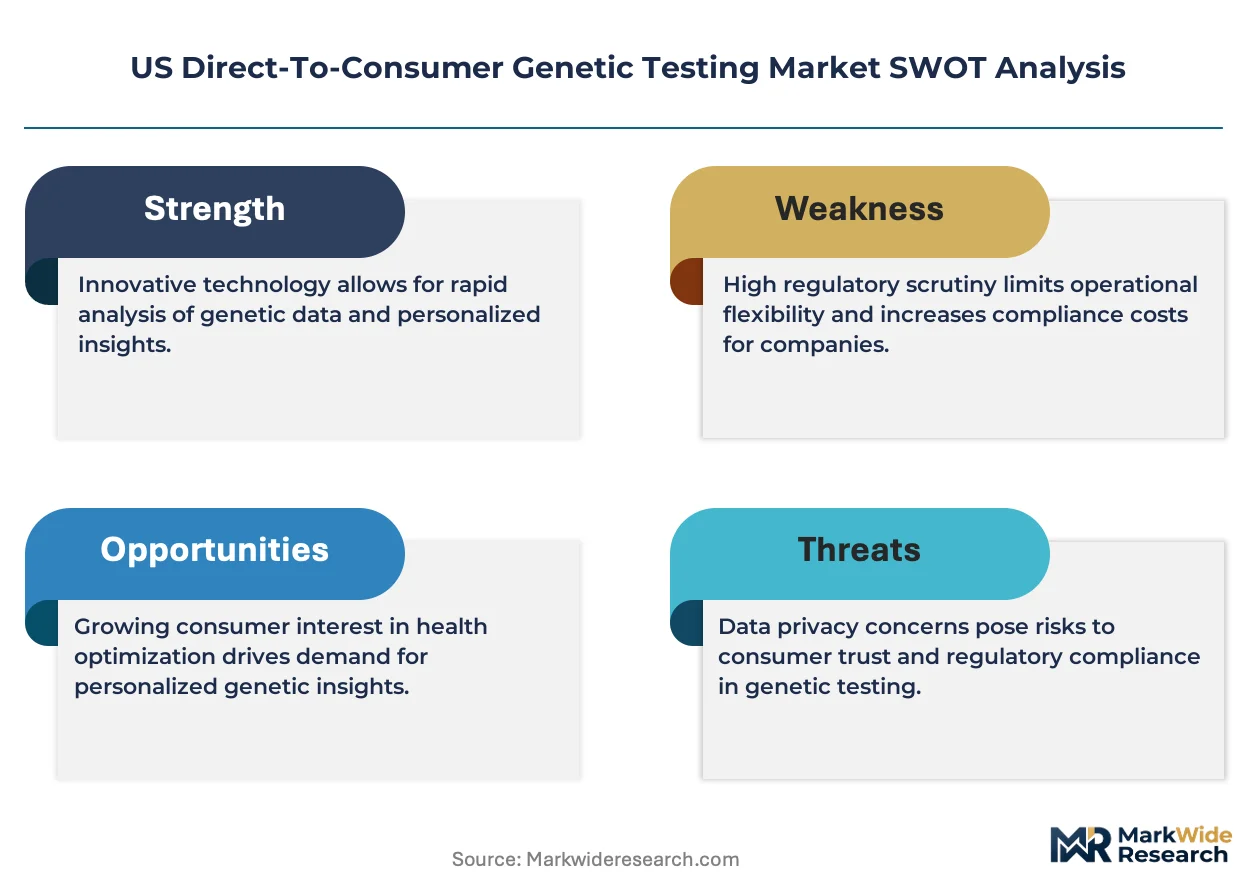
FDA premarket review, CLIA laboratory certification, and state-level physician oversight laws collectively determine which tests reach consumers and how results are interpreted. HIPAA compliance obligations intensify as insurers and employers seek access to genetic data for underwriting and wellness program design. Stakeholders must monitor evolving FDA guidance on artificial intelligence-driven variant interpretation and state legislative battles over genetic privacy protections.
Market Dynamics
Clinical-grade sequencing accuracy is collapsing toward consumer price points, forcing incumbents to recalibrate quality tiers and service models. This compression is reshaping competitive positioning across health risk, ancestry, and pharmacogenomic segments.
Growth Catalysts
- FDA 510(k) Clearances:Premarket review validates clinical utility of health risk reports, expanding reimbursable use cases and physician acceptance.
- Health-conscious millennials:This demographic segment drives demand for preventive genetic screening integrated with wellness applications.
- SNP analysis cost efficiency:Saliva-based single nucleotide polymorphism testing reduces laboratory overhead while maintaining diagnostic relevance.
Market Restraints
- HIPAA compliance obligations:Data privacy requirements intensify as insurers and employers seek genetic information access, creating legal friction.
- CLIA laboratory certification:Federal quality standards limit test variety and interpretation scope, constraining product pipeline velocity.
- Whole genome sequencing cost:Comprehensive pharmacogenomic analysis remains prohibitively expensive for mass-market adoption.
Strategic Opportunities
- Employer-sponsored preventive screening:Corporate wellness programs represent underpenetrated B2B distribution channel expansion.
- Artificial intelligence-driven variant interpretation:FDA guidance evolution on automated analysis creates regulatory tailwind for algorithmic report generation.
- Subscription-renewal models:Ancestry testing maturation enables recurring revenue through database updates and new relative matching features.
Industry Challenges
- Bioinformatics talent scarcity:Variant interpretation and pipeline development require specialized computational biology expertise that outpaces supply.
- State-level physician oversight laws:Fragmented regulatory landscape creates compliance complexity across California, New York, and Maryland.
- Primary care integration friction:Test result translation into actionable clinical workflows demands EHR compatibility investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Direct-To-Consumer Genetic Testing Market |
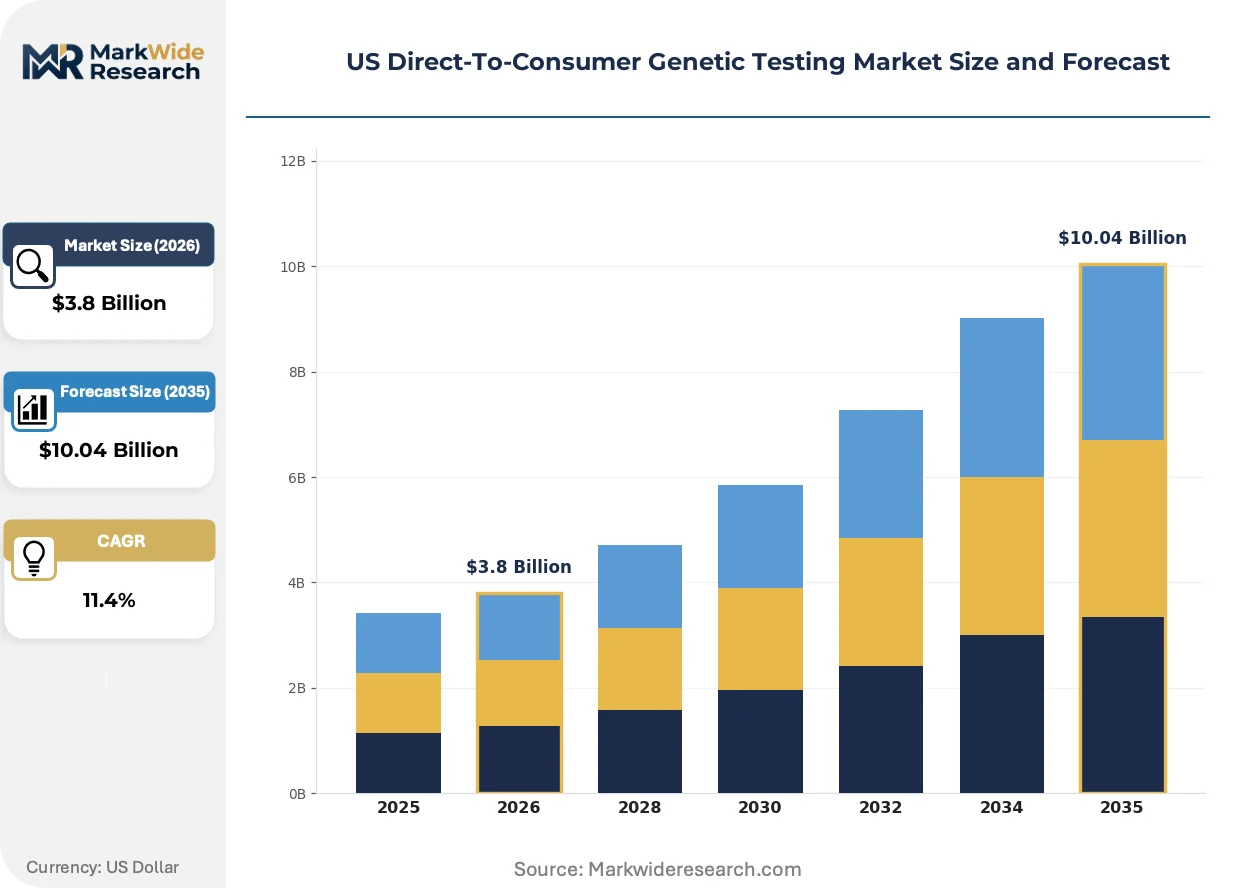
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ancestry Testing, Health Risk Testing, Trait Testing, Paternity Testing Technology: SNP Analysis, Whole Genome Sequencing, Mitochondrial DNA Testing, Y-DNA Testing End User: Individuals, Families, Researchers, Healthcare Providers Service Model: Subscription-Based, One-Time Purchase, Sample Collection Kit, Online Consultation |
| Companies Covered | 23andMe, Inc, Ancestry.com LLC, Color Health, Inc., Family Tree DNA, MyHeritage Ltd., Gene by Gene, Ltd., Myriad Genetics, Inc., Nebula Genomics, Inc., Pathway Genomics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Direct-To-Consumer Genetic Testing Market Emerging Trajectories
Three converging forces are compressing the value chain: sequencing hardware is miniaturizing, FDA oversight is tightening validation standards, and millennial buyers are demanding seamless digital health integration.
Microfluidic sample processing technology is miniaturizing laboratory workflows into cartridge-based systems. Early adopters in employer wellness programs are deploying these platforms for on-site collection. The technology is miniaturizing capital requirements and enabling point-of-care genetic screening outside traditional CLIA facilities.
FDA premarket review of laboratory-developed tests continues tightening validation standards for health risk claims. This regulatory pressure is elevating barriers to entry and consolidating competitive advantage among cleared incumbents. Health risk testing segments are responding by investing in prospective clinical studies to support 510(k) submissions.
Millennial consumers are demanding direct integration of genetic reports with primary care workflows and wellness applications. This behavioral shift is disrupting recreational genealogy models and rewarding platforms that offer physician-facing dashboards. California's biotech corridor and major metropolitan hubs exhibit the strongest demand concentration for clinically actionable results.
US Direct-To-Consumer Genetic Testing Market Segmentation
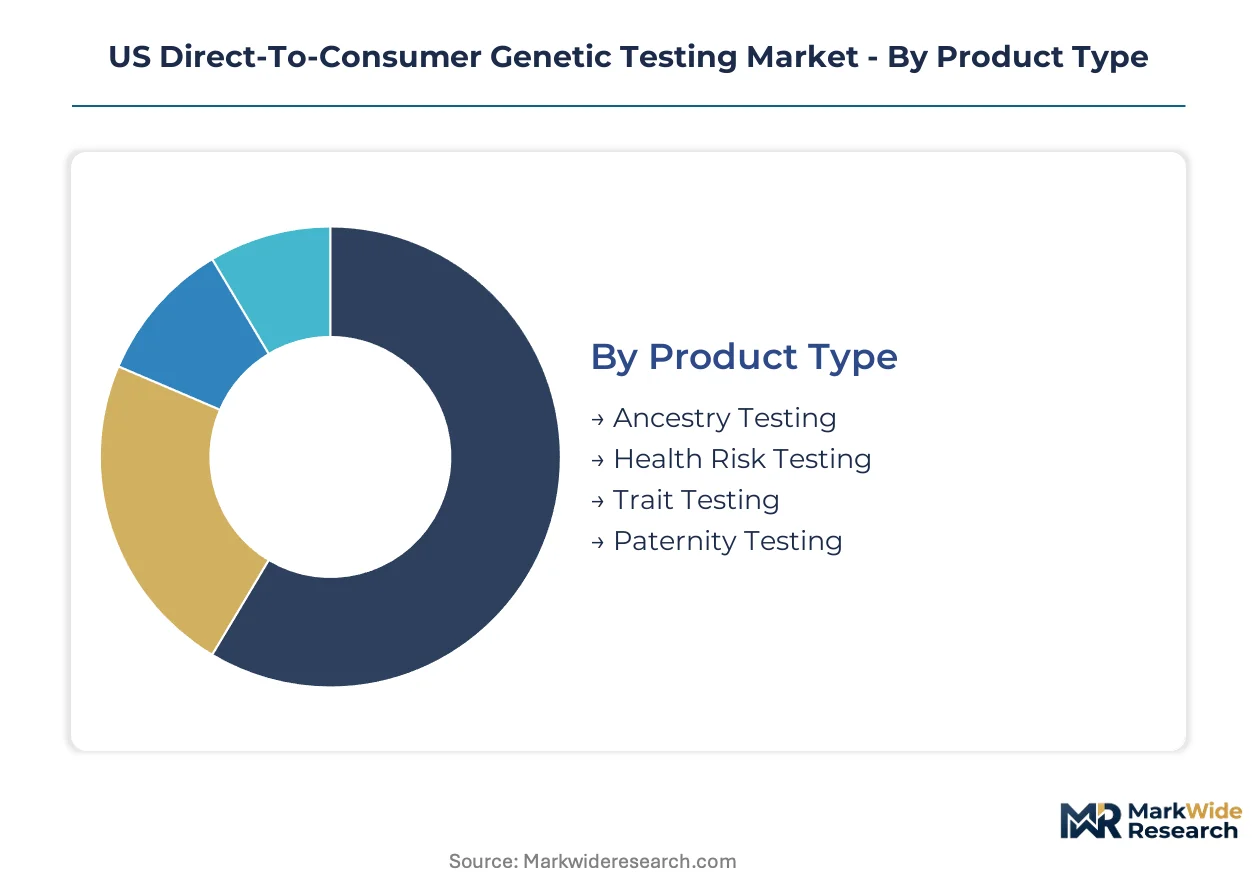
Genetic testing segments flow through distinct channel architectures that shape margin capture and customer acquisition costs. Product type determines whether consumers purchase through direct e-commerce, employer benefits portals, or clinical partnerships.
Product Type:
Channel mix varies sharply across these four segments, with health risk testing commanding premium placement through physician-integrated platforms while ancestry testing dominates direct-to-consumer advertising spend.
- Health Risk Testing:FDA 510(k)-cleared assays for carrier status, pharmacogenomics, and disease predisposition. Demand concentrates among California's biotech corridor employers integrating preventive screening into wellness programs, driven by millennial health consciousness and reimbursable clinical utility validation.
- Ancestry Testing:SNP-based ethnic composition and genealogical matching services. Database scale in major metropolitan hubs sustains subscription renewal models, with relative-matching network effects creating customer lock-in that outpaces other segments.
- Trait Testing:Cosmetic, behavioral, and wellness-oriented genetic insights including skin aging and caffeine metabolism. Direct-to-consumer marketing through social media channels targets individual curiosity rather than clinical decision-making.
- Paternity Testing:Relationship confirmation assays with legal and personal use variants. Discrete online ordering and rapid turnaround requirements distinguish this segment's fulfillment infrastructure from recreational genealogy.
Ancestry testing dominates installed base. Health risk testing is where expansion concentrates.
Technology:
Cost tier stratification separates mass-market accessible methods from comprehensive analysis requiring significant laboratory capital investment.
- SNP Analysis:Targeted genotyping of known variant positions using microarray platforms. Saliva-based collection and automated processing enable sub-hundred-dollar price points that penetrate individual consumer budgets at scale.
- Whole Genome Sequencing:Comprehensive nucleotide resolution across the entire genome. Early adopters in Texas and Massachusetts research corridors seek pharmacogenomic depth despite premium pricing that limits mass-market penetration.
- Mitochondrial DNA Testing:Maternal lineage tracing through mtDNA haplogroup analysis. Deep ancestry enthusiasts and population geneticists drive niche demand for deep-time migration reconstruction.
- Y-DNA Testing:Paternal lineage analysis through Y-chromosome STR and SNP markers. Genealogical surname projects and male-line family history research sustain this specialized segment.
SNP analysis commands volume leadership. Whole genome sequencing is climbing the fastest as sequencing costs compress toward consumer accessibility.
End User:
Customer type determines regulatory exposure and data privacy obligations, with institutional purchasers imposing stricter compliance requirements than individual consumers.
- Individuals:Personal health management and genealogical discovery purchasers. HIPAA obligations intensify as direct-to-consumer platforms expand into clinically actionable reporting that bridges into healthcare system integration.
- Families:Multi-generational testing for inherited risk assessment and relationship confirmation. Employer-sponsored preventive screening programs in California and New York metropolitan areas increasingly subsidize family-tier purchases.
- Researchers:Academic and commercial genomics studies requiring de-identified aggregate data. Consent architecture and data governance requirements exceed standard consumer terms of service.
- Healthcare Providers:Primary care and specialist physicians ordering pharmacogenomic or carrier screening panels. EHR compatibility and clinical decision support integration determine platform selection.
Individuals represent the deepest installed base. Healthcare providers are gaining share fastest as FDA clearances validate clinical workflow integration.
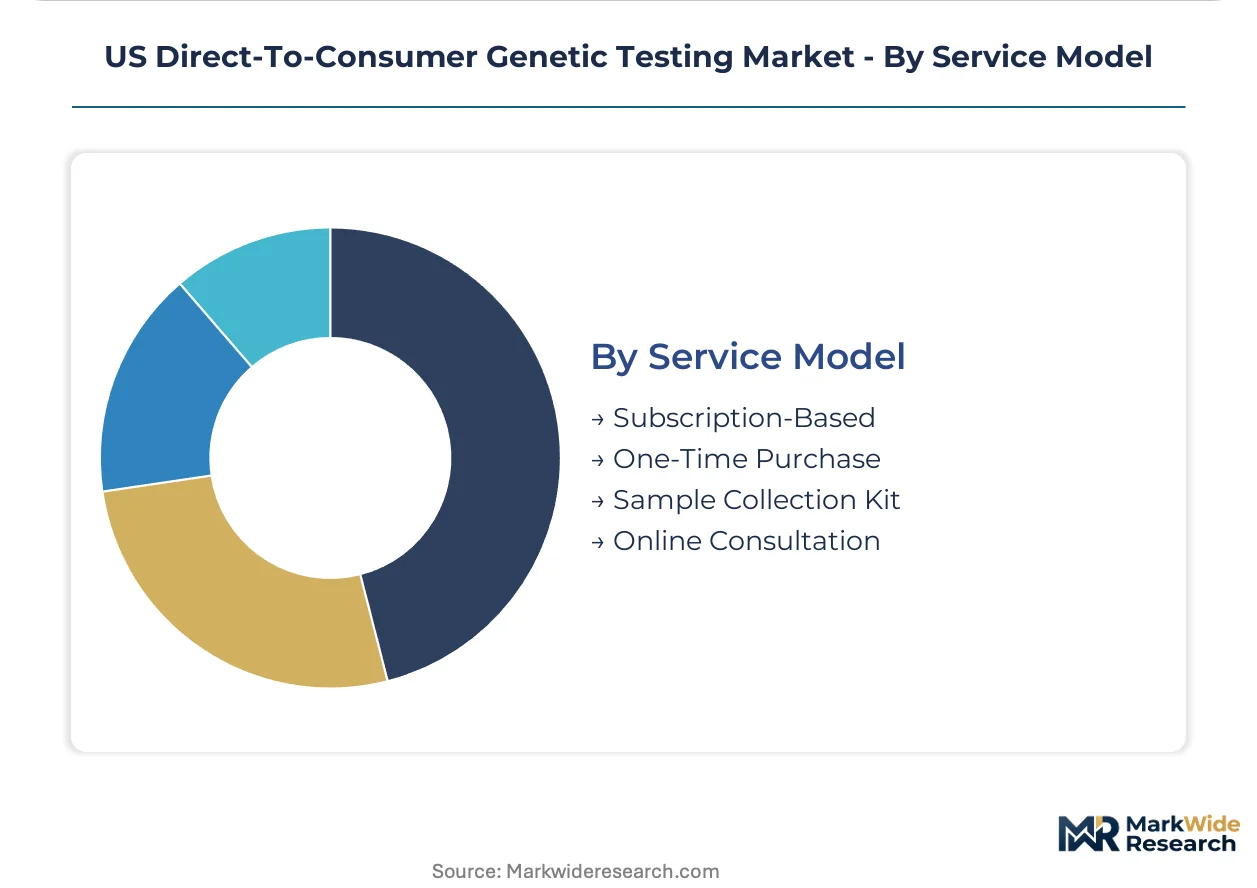
Service Model:
Revenue recognition timing and customer lifetime value calculations diverge sharply between recurring subscription architectures and transactional purchase models.
- Subscription-Based:Recurring access to updated ancestry matches, health risk algorithm refinements, and new trait reports. Database expansion in major metropolitan hubs sustains renewal rates that outperform one-time purchase economics.
- One-Time Purchase:Single report generation with permanent account access to static results. Price compression in SNP analysis has eroded margins, pushing platforms toward upsell conversion into subscription tiers.
- Sample Collection Kit:Physical saliva collection materials with prepaid laboratory processing. Logistics infrastructure and CLIA facility proximity determine fulfillment speed and customer satisfaction scores.
- Online Consultation:Genetic counselor access for result interpretation and clinical translation. Regulatory fragmentation across California, New York, and Maryland state licensing requirements constrains scalable delivery.
One-time purchase retains volume leadership. Subscription-based models are expanding most quickly as ancestry database network effects deepen customer retention.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US direct-to-consumer genetic testing market exhibits minimal export activity given saliva sample logistics constraints and FDA jurisdiction limitations, while domestic consumption concentrates in coastal metropolitan corridors where health technology adoption outpaces national averages.
California
San Francisco Bay Area and San Diego biotech corridors generate disproportionate demand for pharmacogenomic and preventive health screening services among technology sector employees. FDA 510(k) clearance holders cluster in South San Francisco and La Jolla research parks to maintain proximity to premarket review staff. Silicon Valley employers subsidize Color Health and 23andMe enterprise contracts as wellness program differentiators.
New York Metro
Manhattan and Brooklyn health-conscious consumer bases drive premium pricing for clinically integrated genetic reports with genetic counselor interpretation. New York State's physician oversight laws require licensed practitioner involvement for certain health risk disclosures, creating regulatory friction that favors established platforms with compliance infrastructure. Columbia University and Mount Sinai medical center partnerships anchor academic-industry collaboration.
Greater Boston
Cambridge and Boston's concentration of academic medical centers and venture capital sustains early-stage whole genome sequencing adoption despite premium price points. Massachusetts General Hospital and Brigham and Women's Hospital integration partnerships validate clinical workflow compatibility for emerging platforms. Harvard-affiliated research hospitals drive demand for research-grade data quality.
Texas
Houston and Dallas metropolitan areas exhibit growing employer-sponsored screening penetration among energy and technology sector workforces. Texas Medical Center proximity enables CLIA laboratory certification advantages for processing facilities. Austin's technology sector migration patterns mirror California demand profiles for preventive health integration.
Pacific Northwest
Seattle and Portland consumer bases prioritize data privacy protections, with Washington State's genetic information nondiscrimination laws exceeding federal HIPAA baseline requirements. Amazon and Microsoft employee wellness programs represent concentrated B2B contract opportunities. University of Washington medical school partnerships support pharmacogenomic research validation.
US Direct-To-Consumer Genetic Testing Market Vendor Landscape
Listed leaders compete with private specialists across regulatory clearance status and channel access dimensions. The market structure consolidates around three FDA-cleared incumbents with multi-million sample databases, while private specialists occupy employer wellness and whole genome sequencing niches. Two strategic archetypes dominate: database-scale ancestry platforms leveraging network effects, and clinical-integration specialists pursuing physician workflow adoption. Competitive moves center on FDA 510(k) clearance accumulation and employer benefits portal distribution partnerships.
Within the database-scale tier, 23andMe, Inc and Ancestry.com LLC exemplify platform consolidation through consumer sample accumulation and relative-matching network effects. Color Health, Inc. occupies the clinical-integration archetype, representing employer-sponsored preventive screening specialization. These three companies anchor distinct competitive vectors: recreational genealogy with health risk upsell, heritage discovery through subscription renewal, and B2B wellness program integration.
| Leading Market Players |
|---|
| 23andMe, Inc |
| Ancestry.com LLC |
| Color Health, Inc. |
| Family Tree DNA |
| MyHeritage Ltd. |
| Gene by Gene, Ltd. |
| Myriad Genetics, Inc. |
| Nebula Genomics, Inc. |
| Pathway Genomics |
| Others |
Supply Flow & Price Mechanics
Capacity reservation agreements with CLIA-certified laboratories lock in processing slots and stabilize per-sample costs for platforms scaling employer wellness contracts. These arrangements tether price visibility to wet-lab throughput commitments, creating procurement rigidity that favors incumbents with multi-year facility leases in California and Texas.
Pricing Analysis
Health-conscious millennials anchor a three-tier pricing structure across premium, standard, and economy levels, with FDA 510(k) clearance status and genetic counselor access as primary differentiation drivers. Cost compression in SNP-based screening is intensifying because automated microarray processing erodes laboratory overhead. Individual consumers exhibit highest price sensitivity, while employer-sponsored programs absorb premium tiers for clinical integration.
Supply Chain Analysis
Illumina microarray manufacturing concentration in California and Singapore underwrites SNP analysis cost efficiency for mass-market penetration. Supply chains draw from Taiwanese semiconductor foundries for sequencing chip fabrication, California biotech corridors for reagent formulation, and Texas CLIA facilities for sample processing. Single-source vulnerability in sequencing hardware creates procurement risk. Distribution runs through direct-to-consumer e-commerce platforms and employer benefits portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized bioinformatics expertise for variant interpretation and pipeline development represents the critical capability gap constraining platform expansion, with computational biology PhD hiring timelines extending eighteen months beyond product roadmap requirements.
For Market Incumbents: Fortify CLIA laboratory certification moats through capacity expansion in Texas Medical Center corridors where processing density accelerates turnaround times. Deepen genetic counselor networks across California, New York, and Maryland to preempt state-level physician oversight compliance friction. Defend against emerging whole genome sequencing specialists by accelerating FDA 510(k) accumulation for pharmacogenomic report categories. For New Entrants and Emerging Players: Lead with employer-sponsored preventive screening in underpenetrated Houston and Dallas metropolitan corridors where energy sector wellness budgets exceed California saturation. Target Pacific Northwest technology employers prioritizing data privacy protections exceeding federal baselines. Deploy microfluidic cartridge platforms for on-site collection as differentiated B2B channel access mechanism. For Investors and Strategic Acquirers: Clinical-integration specialists with FDA-cleared health risk portfolios and established EHR compatibility represent the highest-conviction acquisition archetype for sustained margin capture. Long-term viability hinges on prospective clinical study infrastructure supporting iterative 510(k) submissions. Monitor FDA guidance evolution on artificial intelligence-driven variant interpretation as regulatory inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Accumulation | Premarket review validates clinical utility for health risk reports, expanding reimbursable use cases and physician acceptance. |
| Employer Benefits Portal Integration | Corporate wellness program distribution reduces customer acquisition costs while embedding preventive screening into subsidized benefits architecture. |
| Microfluidic Sample Processing Deployment | Cartridge-based miniaturization enables point-of-care collection outside traditional CLIA facilities, compressing logistics overhead. |
| Genetic Counselor Network Expansion | Licensed practitioner coverage satisfies New York and Maryland physician oversight laws while improving clinical translation of actionable results. |
| EHR Compatibility Investment | Primary care workflow integration determines platform selection for healthcare provider purchasers seeking seamless clinical decision support. |
Methodological Framework
A standing panel of CLIA laboratory directors, genetic counseling program directors, employer benefits administrators, and FDA regulatory affairs specialists provided ongoing calibration across primary interview cycles. This study combines practitioner insights with secondary validation from FDA 510(k) clearance databases, CLIA certification registries, and CMS reimbursement code analyses. Bottom-up sample volume modeling and top-down market sizing triangulate through employer wellness contract disclosures and direct-to-consumer platform traffic estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segments by product type, technology tier, end user category, and service model, with regional regulatory clusters as an additional dimension. CAGRs derive from segmented growth rate reconciliation against macroeconomic health expenditure trends and millennial preventive care adoption patterns. Forecast inputs include FDA premarket review pipeline velocity and employer wellness program penetration rates by metropolitan corridor.
Forecasts assume regulatory continuity in FDA oversight of laboratory-developed tests and HIPAA enforcement regimes; material policy shifts would require re-modeling. Specific risks include state-level genetic privacy legislation fragmentation and artificial intelligence variant interpretation guidance revisions. Practitioners should keep alternative scenarios live as CLIA certification standards and employer data-sharing consent architectures evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
DNA Methylation Market
Genomics
Microbiome Sequencing Outsourcing Services Market
Genomics
Human Genetics Market
Genomics
Nutrigenomics Testing Market
Genomics
Genomics Personalized Health Market
Genomics
Global Pharmacogenetics Testing in Psychiatry/Depression Market
Genomics
Global Genomics Market
Genomics
Whole Plasmid Sequencing Market
Genomics
Spatial OMICS Market
Genomics
Global NGS Sample Preparation Market
Genomics
Reproductive Genetics Market
Genomics
United States Cancer Biomarkers Market
Genomics
Japan Next Generation Sequencing Market
Genomics
Asia-Pacific Whole Exome Sequencing Market
Genomics
Microbiome Sequencing Market
Genomics
Genomic Biomarkers Market