
 Pharmacogenomics Technology Market | 2026-2036
Pharmacogenomics Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmacogenomics Technology Market Analytics
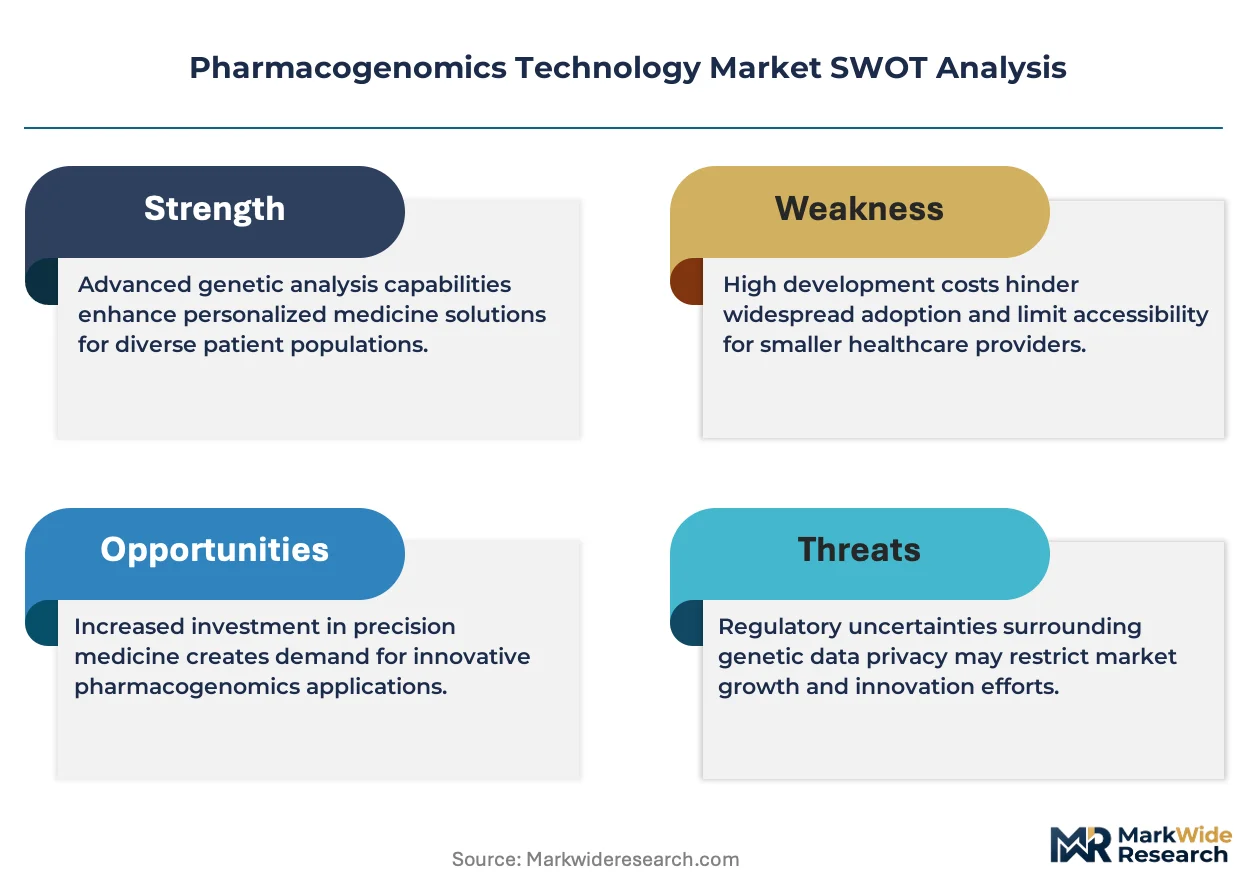
The FDA's Table of Pharmacogenetic Associations is decoupling reimbursement from traditional diagnostic codes, forcing laboratories to recalibrate their billing infrastructure. Illumina, Inc. leverages its installed base of sequencing platforms to dominate clinical pharmacogenomic testing workflows. Thermo Fisher Scientific Inc. anchors its position through integrated reagent-to-analyzer systems that lock in consumable pull-through. QIAGEN N.V. competes via sample-to-insight automation that reduces hands-on time for high-complexity laboratories.
Pharmacogenomics technology encompasses the analytical methods used to identify genetic variations affecting individual drug response, including single nucleotide polymorphism detection, copy number variation analysis, and haplotype phasing through massively parallel sequencing with read depths exceeding 30x for clinical-grade variant calling. Its primary purpose is to guide therapeutic selection and dosing to minimize adverse drug reactions while maximizing efficacy. DNA Sequencing leads product type revenue due to the irreplaceable resolution it provides for complex pharmacogenes like CYP2D6 with its hybrid structural variants. Oncology application demand outpaces neurology and cardiovascular segments because oncologists face narrower therapeutic windows with higher toxicity stakes. Next-Generation Sequencing technology captures the fastest expansion trajectory as panel sizes grow from single-gene to comprehensive pharmacogenomic profiles without proportional cost increases.
FDA oversight through its In Vitro Diagnostics program and the Clinical Laboratory Improvement Amendments framework shapes test validation requirements and laboratory accreditation standards. EMA's pharmacogenomic biomarker qualification process and ISO 15189 medical laboratory accreditation create parallel compliance pathways for multinational diagnostic companies. CLIA high-complexity testing regulations determine which laboratories can perform pharmacogenomic analysis, directly constraining service availability. Stakeholders must monitor how payer coverage policies evolve for preemptive pharmacogenomic testing versus indication-based ordering models.
Market Dynamics
Next-generation sequencing platforms are compressing per-sample costs below traditional single-gene assays, forcing laboratories to consolidate testing menus around comprehensive pharmacogenomic panels or exit the market entirely. This technological displacement is accelerating vendor concentration while expanding reimbursable test catalogs.
Growth Catalysts
- Preemptive Testing Reimbursement:Private payers in the United States now cover pharmacogenomic panels for antidepressant and anticoagulant selection, expanding test volumes beyond oncology into primary care workflows.
- FDA Table Expansion:The FDA's Table of Pharmacogenetic Associations now lists actionable gene-drug pairs for cardiovascular and psychiatric medications, creating billing pathways for expanded clinical indications.
- Oncology Clinical Integration:Major cancer centers now mandate pharmacogenomic screening before high-toxicity chemotherapy regimens, embedding testing into standard-of-care protocols.
Market Restraints
- Reagent Supply Concentration:Sequencing consumables for pharmacogenomic workflows concentrate among three global suppliers, creating vulnerability to supply disruptions and price volatility.
- CLIA Laboratory Bottlenecks:High-complexity testing certification requirements limit service availability to approximately 250 US laboratories capable of clinical-grade variant interpretation.
- Electronic Health Record Fragmentation:Incompatible data standards between diagnostic platforms and prescribing systems impede real-time clinical decision support integration.
Strategic Opportunities
- Pediatric Pharmacogenomics:Underpenetrated neonatal and pediatric populations in Germany and France present expansion targets as EMA biomarker qualification pathways mature for developmental pharmacology applications.
- Pharmacy-Based Testing:Community pharmacy chains in the United Kingdom are piloting point-of-care pharmacogenomic screening for warfarin and clopidogrel dosing, creating direct-to-consumer channels.
- AI-Augmented Interpretation:Machine learning tools for structural variant calling in complex pharmacogenes like CYP2D6 are reducing manual review time and enabling scaled panel deployment.
Industry Challenges
- Bioinformatics Talent Scarcity:Clinical laboratories face acute shortages of variant scientists capable of interpreting pharmacogenomic data under CLIA interpretive guidelines.
- Multi-Gene Assay Validation:Comprehensive panel validation requirements under FDA In Vitro Diagnostics regulations extend development timelines and inflate regulatory submission costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmacogenomics Technology Market |
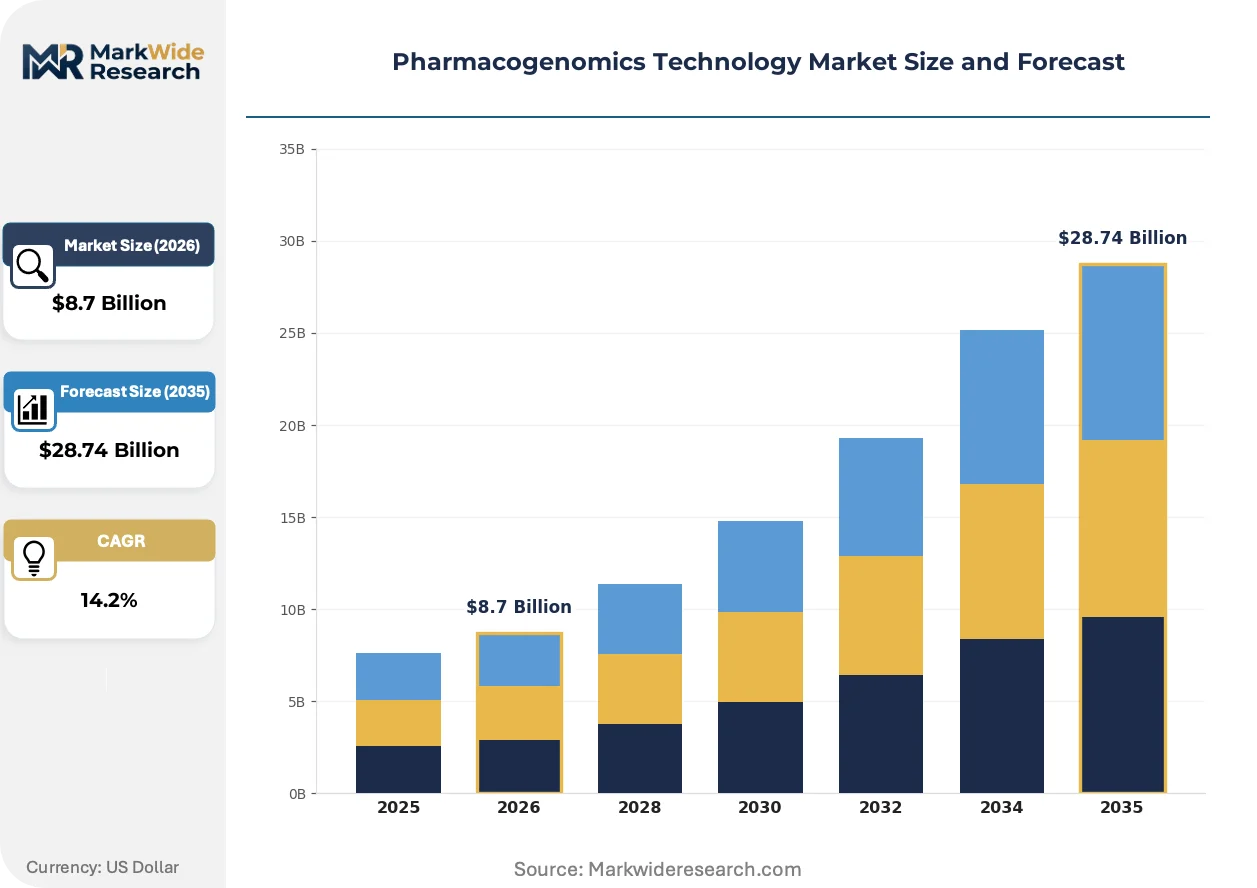
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DNA Sequencing, Genotyping, Microarrays, Gene Panels Application: Oncology, Neurology, Cardiovascular, Pain Management End User: Hospitals, Diagnostic Laboratories, Research Institutes, Pharmacies Technology: Next-Generation Sequencing, Polymerase Chain Reaction, Sanger Sequencing, CRISPR |
| Companies Covered | Illumina, Inc., Thermo Fisher Scientific Inc., F. Hoffmann-La Roche Ltd, QIAGEN N.V., Agilent Technologies, Inc., Abbott Laboratories, Myriad Genetics, Inc., Oxford Nanopore Technologies plc, Foundation Medicine, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmacogenomics Technology Market Evolving Landscape
Automation and artificial intelligence are compressing interpretation workflows while regulatory frameworks evolve to accommodate preemptive testing models. These shifts are reshaping how laboratories structure service offerings and how clinicians integrate genetic data into prescribing decisions.
Automated liquid handling systems integrated with next-generation sequencing platforms are automating sample preparation for high-throughput pharmacogenomic panels. Regional reference laboratories in Texas and California are deploying these systems to process thousands of samples daily. This automation is automating the bottleneck that previously constrained panel economics, enabling price points competitive with single-gene assays.
EMA's pharmacogenomic biomarker qualification process is streamlining parallel approval pathways for multinational diagnostic companies seeking European market access. The process reduces redundant clinical validation requirements across member states. Oncology companion diagnostics are the primary beneficiaries, with manufacturers consolidating previously fragmented national submissions.
Health system procurement departments are consolidating pharmacogenomic testing contracts under centralized laboratory partnerships rather than maintaining hospital-specific send-out agreements. This concentration favors high-volume reference laboratories with integrated interpretation services. The Veterans Health Administration in the United States exemplifies this shift, implementing system-wide preemptive pharmacogenomic screening through designated genomic medicine centers.
Pharmacogenomics Technology Market Segmentation
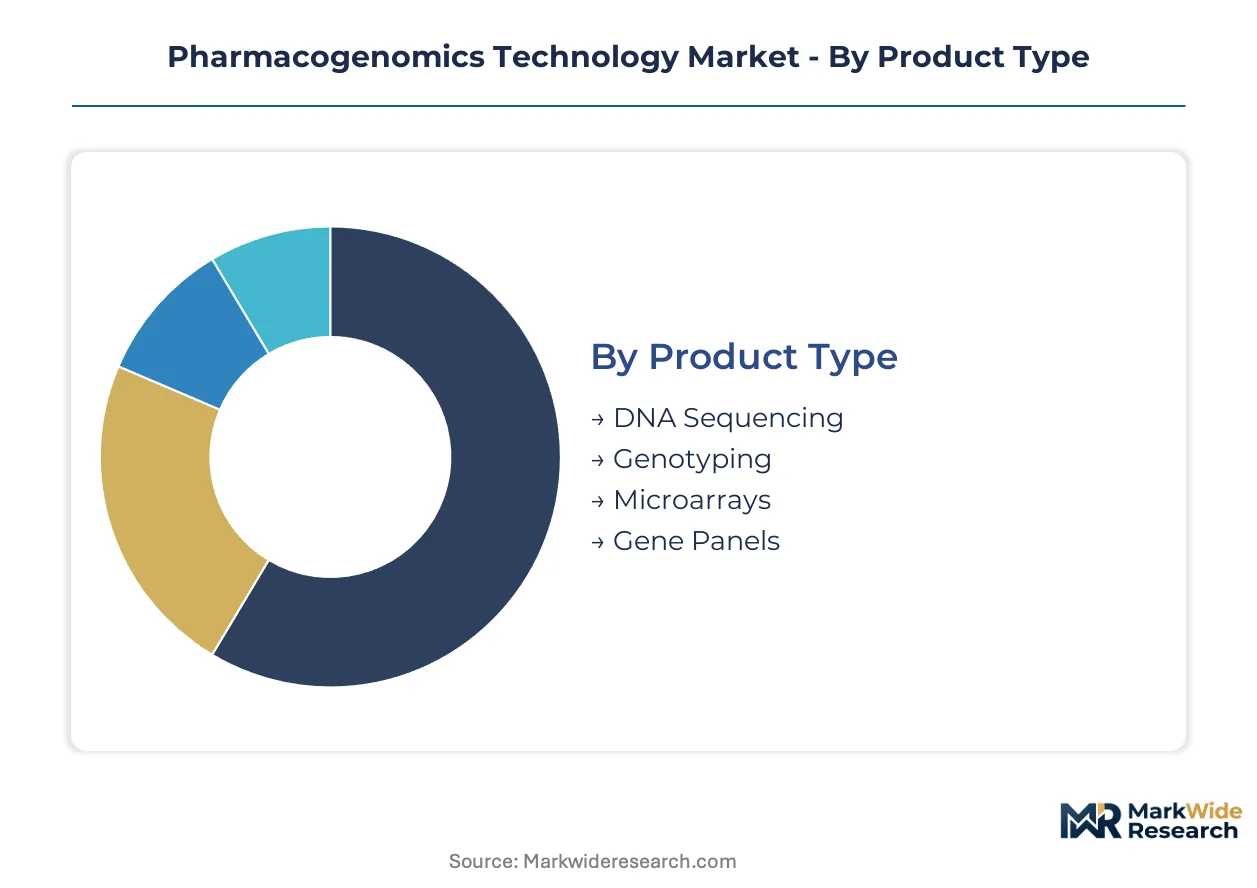
Pharmacogenomics technology segments diverge sharply in their upgrade cycles and replacement economics. Laboratories weigh platform longevity against panel expansion capabilities when committing capital to analytical infrastructure.
Product Type:
Replacement cycles in pharmacogenomics platforms accelerate as comprehensive panels displace single-gene assays, compressing the functional lifespan of earlier-generation equipment.
- DNA Sequencing:Massively parallel sequencing with read depths exceeding 30x delivers irreplaceable resolution for complex pharmacogenes like CYP2D6. Major cancer centers in the United States now mandate this capability before high-toxicity chemotherapy regimens.
- Genotyping:Single nucleotide polymorphism detection platforms offer rapid turnaround for established gene-drug pairs. Demand concentrates in cardiovascular clinics across Germany and France where warfarin and clopidogrel dosing protocols require swift genetic assessment.
- Microarrays:Fixed-content arrays face displacement as customizable panels expand, though they retain niche utility in large-scale retrospective pharmacogenomic studies.
- Gene Panels:Targeted multiplex assays balance cost and content breadth, finding adoption in diagnostic laboratories seeking CLIA-compliant workflows without full sequencing infrastructure.
DNA Sequencing sits at the top of the volume ranking, with Gene Panels climbing the fastest as laboratories seek intermediate solutions between single-gene tests and comprehensive profiling.
Application:
Clinical adoption velocity varies dramatically across therapeutic areas, with regulatory precedent and therapeutic window width determining integration speed.
- Oncology:Narrow therapeutic indices and severe toxicity profiles drive mandatory pharmacogenomic screening before chemotherapy initiation. The FDA's expanding Table of Pharmacogenetic Associations creates billing pathways for expanded indications.
- Neurology:Psychiatric medication selection benefits from preemptive testing reimbursement by private payers, embedding pharmacogenomic panels into antidepressant prescribing workflows.
- Cardiovascular:Anticoagulant and antiplatelet dosing represents mature pharmacogenomic applications with established clinical guidelines.
- Pain Management:Opioid metabolism variability drives emerging interest, though regulatory frameworks for analgesic pharmacogenomics remain less codified than oncology or cardiovascular applications.
Oncology commands the largest share of clinical testing volume, while Neurology gains share fastest as preemptive screening expands beyond cancer centers into primary care.
End User:
Customer concentration patterns reflect regulatory certification requirements and interpretation capability distribution across the healthcare system.
- Hospitals:Integrated health systems consolidate testing contracts under centralized laboratory partnerships, favoring high-volume reference laboratories with embedded interpretation services.
- Diagnostic Laboratories:Approximately 250 CLIA high-complexity certified facilities in the United States perform clinical-grade variant interpretation, creating supply-constrained service availability.
- Research Institutes:Academic medical centers drive biomarker discovery and validation studies supporting FDA In Vitro Diagnostics submissions.
- Pharmacies:Community pharmacy chains in the United Kingdom pilot point-of-care pharmacogenomic screening, creating direct-to-consumer channels for warfarin and clopidogrel dosing.
Diagnostic Laboratories process the highest test volumes, with Pharmacies expanding most quickly as point-of-care models mature.
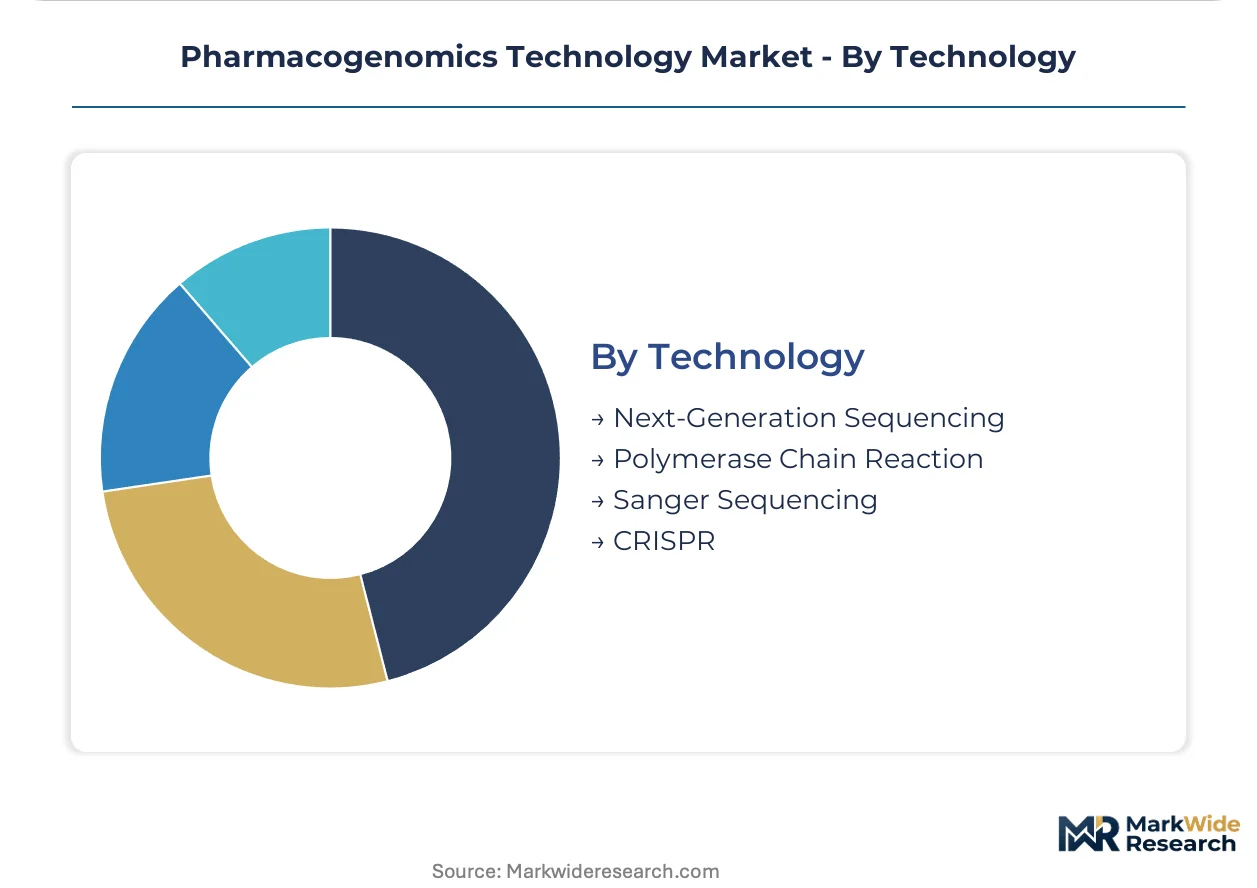
Technology:
Platform selection determines panel scalability, cost trajectory, and regulatory validation burden for pharmacogenomic assay development.
- Next-Generation Sequencing:Panel sizes grow from single-gene to comprehensive pharmacogenomic profiles without proportional cost increases, compressing per-sample economics below traditional assays.
- Polymerase Chain Reaction:Established qPCR methods retain utility for high-priority single-gene tests with rapid turnaround requirements.
- Sanger Sequencing:First-generation sequencing persists for confirmatory testing and targeted variant verification in regulatory submissions.
- CRISPR:Emerging diagnostic applications leverage CRISPR-based detection for point-of-care pharmacogenomic screening with minimal equipment requirements.
Next-Generation Sequencing leads technology deployment, with CRISPR gaining traction fastest in decentralized testing models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clinical bioinformaticians and variant interpretation specialists concentrate in metropolitan research corridors, anchoring pharmacogenomics service availability to specific urban clusters with CLIA-certified infrastructure and academic medical center density.
United States
Private payer coverage expansion for preemptive pharmacogenomic screening drives test volume growth beyond oncology into primary care antidepressant prescribing. FDA Table of Pharmacogenetic Associations updates create direct billing pathways for cardiovascular and psychiatric gene-drug pairs. The Veterans Health Administration operates designated genomic medicine centers in San Diego and Palo Alto, implementing system-wide preemptive screening protocols.
Germany
Cardiovascular clinics in Bavaria and North Rhine-Westphalia generate sustained demand for warfarin and clopidogrel pharmacogenomic assessment. EMA pharmacogenomic biomarker qualification processes streamline parallel approval pathways for diagnostic manufacturers. Heidelberg and Berlin academic medical centers anchor biomarker discovery pipelines supporting European IVD submissions.
United Kingdom
Community pharmacy chains pilot point-of-care pharmacogenomic screening for anticoagulant dosing, creating novel direct-to-consumer distribution channels. MHRA recognition of FDA pharmacogenetic associations accelerates regulatory convergence for multinational test manufacturers. London and Cambridge genomic medicine clusters concentrate interpretation expertise for NHS reference laboratory networks.
Japan
PMDA pharmacogenomic guideline development for oncology companion diagnostics shapes test validation requirements across Asia-Pacific markets. Tokyo and Osaka metropolitan areas host concentrated sequencing infrastructure serving domestic biopharmaceutical clinical trials. Japanese health technology assessment processes increasingly incorporate pharmacogenomic cost-effectiveness data for reimbursement determinations.
Switzerland
Swissmedic streamlined qualification pathways attract diagnostic developers seeking European market entry with reduced redundant clinical validation. Basel and Zurich pharmaceutical research corridors generate demand for pharmacogenomic biomarker discovery services. Swiss academic medical centers participate in EMA qualification studies for developmental pharmacology applications in pediatric populations.
Pharmacogenomics Technology Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across instrument, reagent, and service segments, creating a tiered competitive structure. Sequencing platform vendors anchor the infrastructure layer while specialized interpretation service providers occupy downstream clinical workflows. Three archetypes dominate: integrated reagent-to-analyzer system suppliers, sample-to-insight automation vendors, and clinical laboratory service consolidators. M&A activity concentrates in bioinformatics interpretation capabilities while strategic partnerships link instrument manufacturers with health system procurement networks.
Among diversified life science conglomerates, Thermo Fisher Scientific Inc. and F. Hoffmann-La Roche Ltd exemplify integrated system suppliers with consumable pull-through business models. Illumina, Inc. occupies a distinct position as sequencing platform infrastructure anchor, leveraging installed base density to shape clinical workflow standardization. QIAGEN N.V. represents the sample-to-insight automation archetype, targeting high-complexity laboratory efficiency requirements.
| Leading Market Players |
|---|
| Illumina, Inc. |
| Thermo Fisher Scientific Inc. |
| F. Hoffmann-La Roche Ltd |
| QIAGEN N.V. |
| Agilent Technologies, Inc. |
| Abbott Laboratories |
| Myriad Genetics, Inc. |
| Oxford Nanopore Technologies plc |
| Foundation Medicine, Inc. |
| Others |
Value Network & Pricing Analysis
Integrated health system procurement departments in the United States anchor pricing power for pharmacogenomic testing services, consolidating contracts under centralized laboratory partnerships that favor volume-based pricing models over fragmented hospital-specific agreements.
Pricing Analysis
Bundled comprehensive panel pricing dominates hospital system contracts, while unbundled per-gene reimbursement persists in smaller diagnostic laboratories lacking high-throughput infrastructure. Price differentiation centers on CLIA certification tier and interpretation service depth, with high-complexity variant analysis commanding premium positioning. Cost compression in single-gene assays is intensifying because next-generation sequencing platforms displace legacy methods without proportional price increases. Community pharmacy chains exhibit highest price sensitivity, while major cancer centers prioritize turnaround reliability over per-test economics.
Supply Chain Analysis
Reverse-logistics flows for sequencing instrument refurbishment and reagent cold-chain returns concentrate service capabilities in metropolitan research corridors with dense CLIA-certified laboratory networks. Sequencing consumables for pharmacogenomic workflows draw from concentrated supplier bases in the United States, Germany, and Japan. Critical dependencies include fluorophore-labeled nucleotides, polymerase enzymes, and flow cell substrates. Single-source vulnerability for proprietary sequencing chemistries creates structural risk exposure. Distribution runs through regional reference laboratory hubs that aggregate samples from hospital networks before forwarding to centralized interpretation facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in pharmacogenomics technology rests on automation-driven cost compression in sample preparation workflows, enabling comprehensive panel economics competitive with single-gene assays while preserving premium pricing for complex variant interpretation.
For Market Incumbents: Anticipate consolidation pressure from next-generation sequencing platform vendors expanding into downstream interpretation services by deepening bioinformatics capabilities and securing exclusive health system procurement contracts. Lock in consumable pull-through through integrated reagent-to-analyzer system deployments. Prioritize CLIA high-complexity laboratory certification investments to defend service availability constraints against emerging point-of-care competitors. For New Entrants and Emerging Players: Enter via pharmacy-based point-of-care screening models in the United Kingdom and pediatric pharmacogenomics applications in Germany, where regulatory pathways remain underpenetrated by established reference laboratories. Community pharmacy chains represent the most penetrable channel. Pursue warfarin and clopogrel dosing as initial go-to-market applications with established clinical guidelines and direct-to-consumer accessibility. For Investors and Strategic Acquirers: Platform biotechnology companies with companion diagnostic development pipelines are the most active acquirer in this space, seeking pharmacogenomic biomarker discovery capabilities to anchor oncology therapeutic positioning. Long-term viability hinges on preemptive testing reimbursement expansion beyond oncology into primary care workflows. Target acquisition archetypes include bioinformatics interpretation specialists with CLIA-certified variant scientists. Monitor FDA Table of Pharmacogenetic Associations expansion velocity as inflection indicator for billing pathway creation and test volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA High-Complexity Laboratory Certification | FDA and state laboratory regulations determine service availability for clinical-grade pharmacogenomic variant interpretation. |
| Preemptive Testing Reimbursement Strategy | Private payer coverage expansion in the United States creates billing pathways for cardiovascular and psychiatric gene-drug pairs. |
| Sample-to-Insight Automation Deployment | Integrated liquid handling and interpretation systems reduce hands-on time for high-complexity laboratories processing thousands of daily samples. |
| EMA Biomarker Qualification Pathway | Parallel approval processes streamline European market access for multinational diagnostic manufacturers seeking reduced redundant clinical validation. |
| Pharmacy-Based Point-of-Care Pilot | Community pharmacy chains in the United Kingdom create direct-to-consumer distribution channels for anticoagulant dosing applications. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with laboratory directors, bioinformatics scientists, health system procurement officers, and regulatory affairs specialists at diagnostic manufacturers with secondary validation from FDA In Vitro Diagnostics submissions, EMA pharmacogenomic biomarker qualification documents, Clinical Laboratory Improvement Amendments certification records, and private payer coverage policy databases. Bottom-up test volume estimates and top-down market sizing approaches were triangulated to anchor projections.
Historical reference periods spanning platform replacement cycles and reimbursement policy shifts anchored the forecast window across the analysis window. Segmentation dimensions modeled include product type, application area, end-user category, and technology platform, with additional stratification by CLIA certification tier and health system integration depth. CAGRs were derived from instrument installation base trajectories and panel adoption curves. Key forecast inputs encompassed sequencing platform cost compression rates and preemptive testing reimbursement expansion velocity.
Inputs from regulatory filing databases and payer policy documents were available through the study window; gaps in real-time health system procurement contract terms introduce uncertainty bands around price point assumptions. Forecasts reflect documented assumptions regarding FDA Table expansion timing and CLIA laboratory capacity growth. Practitioners should monitor EMA biomarker qualification completion rates and community pharmacy pilot program scale-up for early signals of channel structure evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Genetic Testing Market
Genomics
Point-Of-Care Genetic Testing Market
Genomics
DNA Mass Ladder Market
Genomics
Cancer Biomarkers Market
Genomics
DNA Microarray Market
Genomics
Global Whole Genome Sequencing (WGS) Market
Genomics
Direct-To-Consumer (DTC) Genetic Testing Market
Genomics
Microarray Scanners Market
Genomics
North America Genetic Testing Market
Genomics
Transcriptomics Technologies Market
Genomics
Global Mirna Sequencing and Assay Market
Genomics
DNA Methylation Market
Genomics
Alagille Syndrome Market
Genomics
Europe Gene Synthesis (Research Use) Market
Genomics
SNP Genotyping Market
Genomics
Short-Read Sequencing Market