
 China Genetic Testing Market | 2026-2036
China Genetic Testing Market Size, Share, and Industry Trends Forecast 2026-2036
China Genetic Testing Market Intelligence
China's dual carbon goals is pivoting hospital procurement toward energy-efficient sequencing platforms and greener laboratory infrastructure. BGI Genomics leverages its domestic manufacturing scale to control costs across reagent production. MGI Tech anchors the high-throughput instrument segment with proprietary sequencing chemistry. WuXi NextCODE competes through bioinformatics specialization in rare disease interpretation.
Genetic testing comprises molecular diagnostic methods that analyze DNA, RNA, chromosomes, or proteins to detect heritable disease mutations, pharmacogenomic variants, and somatic alterations using specimen preparation protocols, nucleic acid extraction, amplification, and detection systems with sensitivity thresholds reaching single-nucleotide resolution. Next-Generation Sequencing leads the technology landscape as the default platform for oncology panel and whole-exome applications, while PCR retains dominance in infectious disease and rapid turnaround settings. Disease Diagnosis generates the largest revenue pool among applications, though Pharmacogenomics exhibits the steepest growth trajectory as precision prescribing protocols expand through tier-three hospital networks.
NMPA's medical device classification rules and GB standards for in vitro diagnostics shape product registration timelines and clinical evidence requirements for domestic and imported assay kits. SAMR enforces pricing transparency rules that constrain hospital markup structures on genetic tests. MEE hazardous waste regulations govern laboratory consumable disposal protocols. Stakeholders must monitor how NMPA's evolving breakthrough device pathway interacts with provincial reimbursement decisions to determine viable commercialization sequences.
Market Dynamics
NMPA's breakthrough device pathway is compressing approval timelines for oncology companion diagnostics, while provincial reimbursement fragmentation forces manufacturers to sequence commercialization across tier-one hospital clusters before broader rollout.
Growth Catalysts
- Dual carbon policy mandates:Hospital procurement guidelines now prioritize energy-efficient sequencing platforms, accelerating replacement cycles in Beijing and Shanghai laboratory networks.
- Hereditary cancer screening protocols:Oncology clinics in the Yangtze River Delta are expanding BRCA and Lynch syndrome panels as standard-of-care for high-risk patient stratification.
- NMPA streamlined review pathway:Innovative diagnostic submissions receive prioritized technical review, reducing registration timelines for novel biomarker assays.
Market Restraints
- Reagent import dependency:High-fidelity polymerases and fluorescent probes concentrate among overseas suppliers, exposing domestic laboratories to currency volatility and logistics disruption.
- SAMR pricing transparency enforcement:Markup caps on genetic tests constrain hospital laboratory revenue models, compressing margins on high-complexity molecular assays.
- Specialist interpretation bottleneck:Certified clinical geneticists remain concentrated in tier-one cities, limiting test report turnaround in provincial medical centers.
Strategic Opportunities
- Pharmacogenomics expansion:Tier-three hospital networks in Sichuan and Shaanxi provinces present untapped demand for warfarin and clopidogrel genotyping protocols.
- Non-invasive prenatal testing corridors:Municipal health commissions in Guangdong and Jiangsu are integrating NIPT into routine maternal screening programs.
- AI-assisted variant classification:Machine learning tools for rare disease interpretation are converging with cloud-based bioinformatics pipelines to reduce manual curation burden.
Industry Challenges
- Bioinformatics talent scarcity:Computational biology and variant curation expertise concentrates among academic medical centers, forcing commercial laboratories to compete for limited personnel.
- Laboratory information system integration:Legacy hospital IT infrastructure requires custom middleware development to connect sequencing instruments with electronic medical records.
- Hazardous waste compliance:MEE regulations governing nucleic acid extraction consumable disposal impose specialized logistics requirements on high-throughput facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Genetic Testing Market |
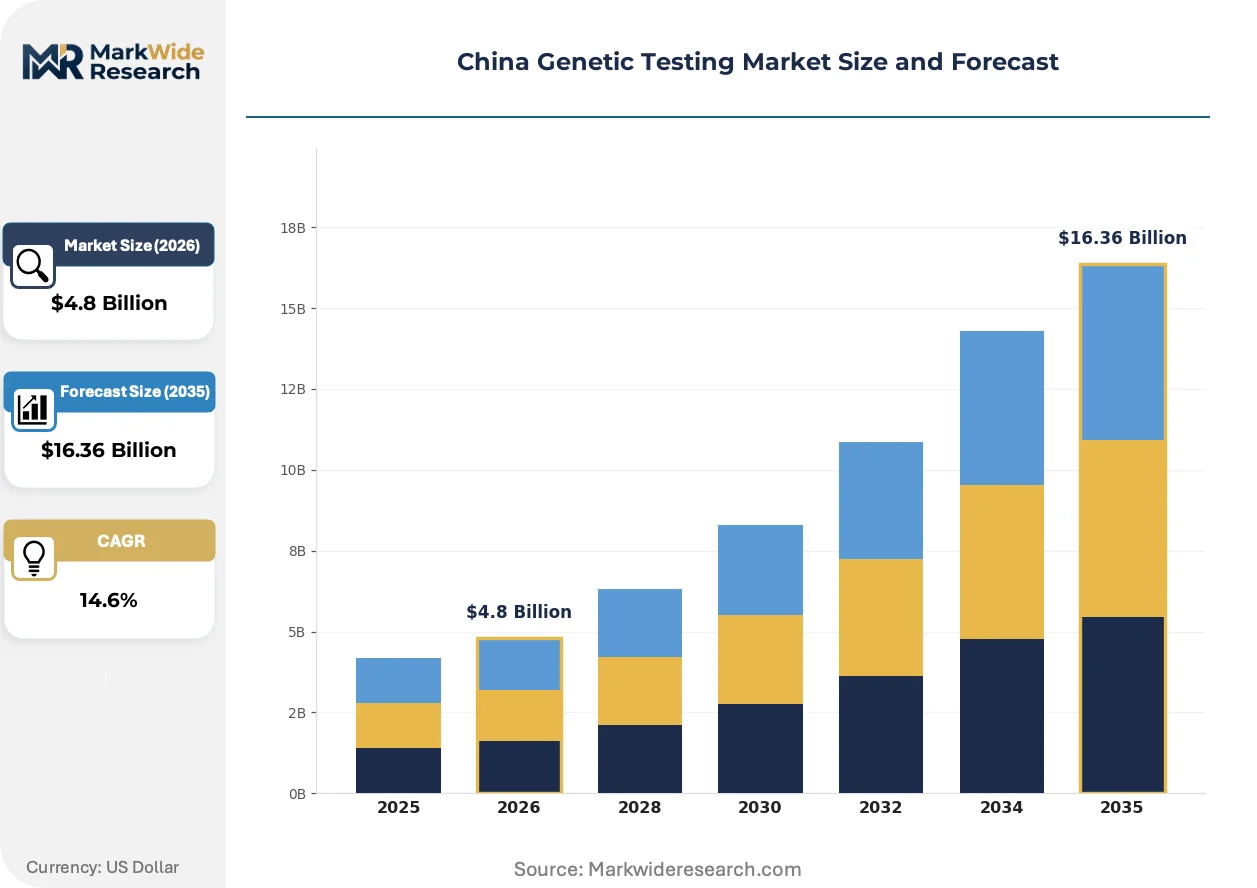
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Next-Generation Sequencing, PCR, Microarray, Sanger Sequencing Product Type: Reagents, Instruments, Software, Consumables End User: Hospitals, Diagnostic Labs, Research Institutes, Pharmaceutical Companies Application: Disease Diagnosis, Prenatal Testing, Carrier Testing, Pharmacogenomics |
| Companies Covered | WuXi NextCODE, WuXi PharmaTech, BGI Genomics, CapitalBio Technology, MGI Tech, Berry Genomics, Annoroad Gene Technology, GeneID Technology, Daan Gene, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Genetic Testing Market Strategic Shifts & Innovations
Long-read sequencing platforms are penetrating clinical workflows previously dominated by short-read chemistry, while artificial intelligence tools compress variant interpretation timelines. Regulatory frameworks are adapting to accommodate software-as-medical-device classifications for diagnostic algorithms.
Third-generation sequencing technology is expanding into structural variant detection and methylation analysis applications previously inaccessible to short-read platforms. Oncology reference laboratories in Beijing and Shanghai are adopting these instruments for complex cancer genome characterization. The technology is expanding into pharmacogenomic panel design by enabling haplotype-resolved CYP gene analysis without statistical phasing.
NMPA's medical device classification rules now explicitly address software-based diagnostic algorithms, creating registration pathways for AI-assisted variant interpretation tools. This regulatory evolution enables domestic bioinformatics vendors to commercialize decision-support products previously operating in regulatory gray zones. Oncology and rare disease applications face the steepest compliance burden given the clinical consequence of algorithmic errors.
Centralized procurement platforms operated by provincial health commissions are consolidating genetic test purchasing decisions previously fragmented across individual hospital laboratories. Tier-two and tier-three facilities in Henan and Shandong provinces increasingly delegate molecular diagnostic service selection to regional procurement consortia. This concentration shifts negotiating leverage toward volume buyers and compresses pricing differentiation among assay manufacturers.
China Genetic Testing Market Segmentation
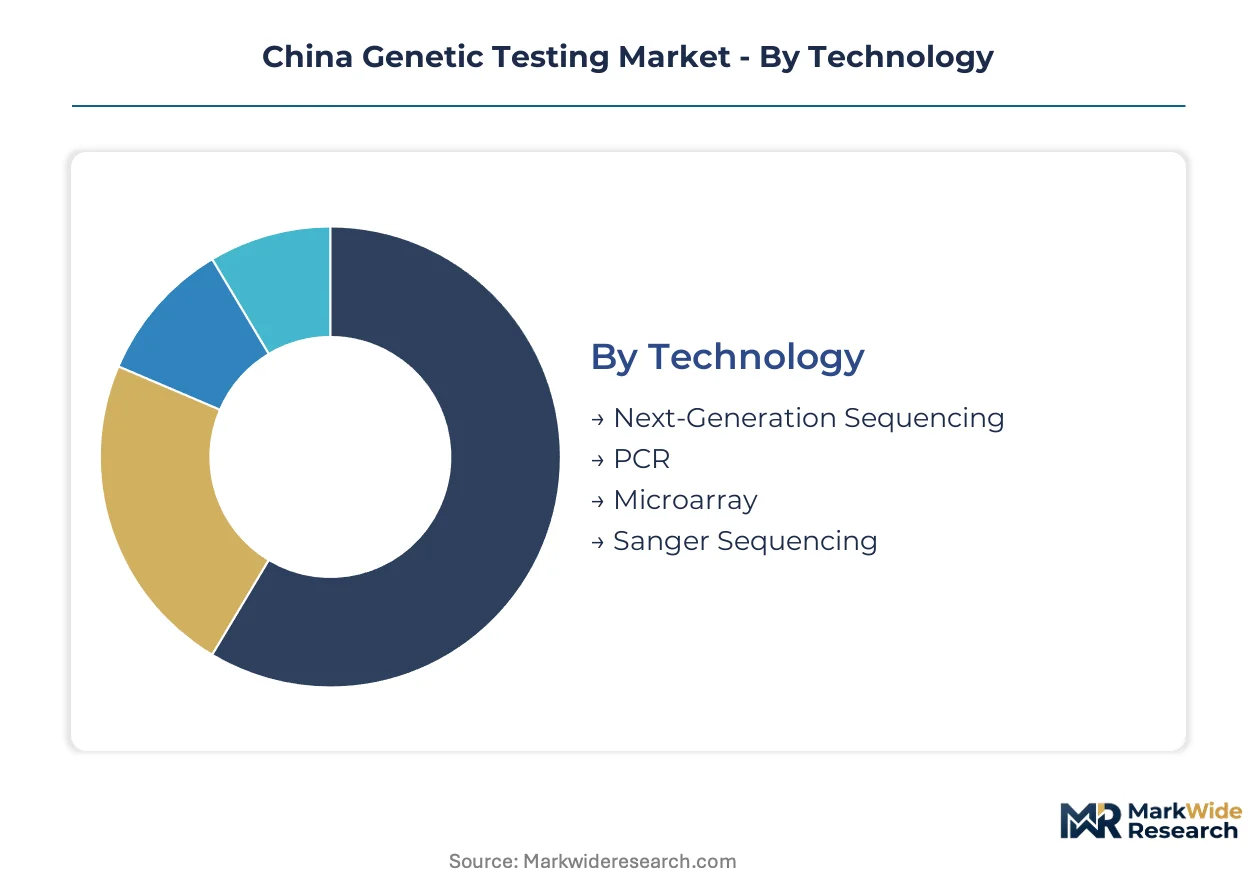
Segmentation in China's genetic testing market reveals how NMPA regulatory pathways and provincial procurement patterns concentrate value capture across technology tiers and end-user channels. Understanding these divisions exposes where domestic manufacturers compete on cost versus where imported platforms retain technical dominance.
Technology:
Supply concentration among domestic instrument manufacturers is compressing per-run costs for high-throughput applications while leaving specialized chemistry dependent on overseas sources.
- Next-Generation Sequencing:Short-read platforms dominate oncology panel and whole-exome workflows with read lengths of 150-300 base pairs. Beijing and Shanghai oncology clinics are consolidating procurement around instruments with proprietary flow-cell chemistry, though fluorescent reagent kits remain import-dependent.
- PCR:Thermal cycling amplification retains primacy in infectious disease panels and pharmacogenomic rapid-turnaround settings. Sichuan and Shaanxi tier-three hospitals are expanding CYP2C19 and VKORC1 genotyping capacity using domestically manufactured thermal cyclers.
- Microarray:SNP genotyping arrays serve carrier screening and ancestry applications with standardized probe sets.
- Sanger Sequencing:Capillary electrophoresis confirms variants detected by NGS and resolves short tandem repeat expansions.
Today's leader: Next-Generation Sequencing. Tomorrow's challenger: Long-read platforms penetrating structural variant detection.
Product Type:
Cost tier differentiation separates premium imported reagents from domestically manufactured consumables, with software emerging as a margin expansion vector.
- Reagents:Polymerases, fluorescent probes, and library preparation kits constitute the highest recurring cost category. High-fidelity enzymes concentrate among US and European suppliers, exposing Yangtze River Delta laboratories to currency volatility.
- Instruments:Sequencing platforms, thermal cyclers, and hybridization ovens represent capital-intensive procurement decisions. MGI Tech and BGI Genomics anchor domestic manufacturing with proprietary sequencing chemistry and flow-cell architectures.
- Software:Variant interpretation pipelines and laboratory information management systems are gaining NMPA software-as-medical-device registrations.
- Consumables:Extraction columns, tips, and plates face centralized procurement pressure from provincial health commission platforms.
Reagents command the largest revenue pool. Software exhibits the steepest margin expansion trajectory.
End User:
Volume concentration in tier-one hospital networks is shifting toward regional procurement consortia that aggregate demand across tier-two and tier-three facilities.
- Hospitals:Tertiary medical centers in Beijing, Shanghai, and Guangzhou operate integrated molecular diagnostic laboratories with NMPA-licensed assays. Oncology departments are expanding hereditary cancer screening programs for BRCA and Lynch syndrome stratification.
- Diagnostic Labs:Independent reference laboratories process overflow from hospital networks and specialize in rare disease interpretation. WuXi NextCODE competes through bioinformatics specialization in variant curation.
- Research Institutes:Academic medical centers drive technology adoption for translational studies.
- Pharmaceutical Companies:Companion diagnostic development partnerships require clinical-grade sequencing infrastructure.
Hospitals retain the dominant volume position. Diagnostic labs are gaining share fastest through NIPT and rare disease specialization.
Application:
Geographic clustering in the Yangtze River Delta and Pearl River Delta is concentrating prenatal testing demand while pharmacogenomics expands inland.
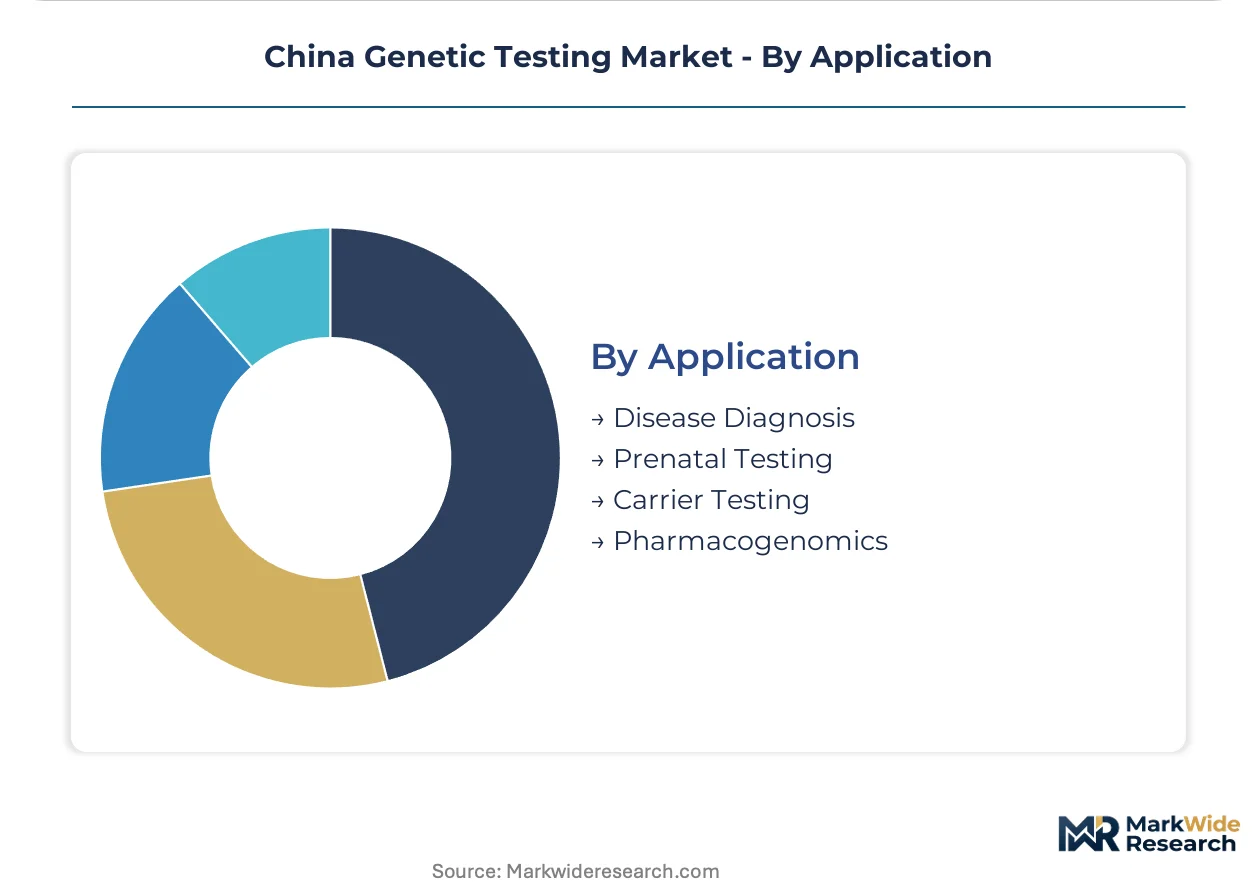
- Disease Diagnosis:Oncology panels and hereditary cancer screening generate the largest revenue pool among applications. Shanghai and Beijing clinics are standardizing BRCA testing for high-risk patient stratification.
- Prenatal Testing:Non-invasive fetal testing corridors in Guangdong and Jiangsu provinces are integrating cell-free DNA screening into routine maternal care protocols.
- Carrier Testing:Expanded carrier panels for recessive disorders serve preconception and prenatal counseling workflows.
- Pharmacogenomics:Warfarin and clopidogrel genotyping protocols are penetrating tier-three hospital networks in Henan and Shandong provinces.
Disease Diagnosis anchors current revenue. Pharmacogenomics represents the steepest expansion trajectory as precision prescribing protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Genetic testing infrastructure in China originated from state-funded genome projects in Beijing during the early 2000s. This institutional foundation seeded commercial laboratories that now dominate domestic sequencing capacity. Provincial health commissions now shape regional deployment patterns through centralized procurement mandates.
Beijing-Tianjin-Hebei
Oncology companion diagnostics and hereditary cancer screening drive demand in this northern cluster. NMPA's breakthrough device pathway accelerates approvals for Beijing-based reference laboratories. CapitalBio Technology anchors the regional instrument supply chain through proprietary microarray platforms serving military and civilian hospitals.
Yangtze River Delta
Non-invasive prenatal testing corridors concentrate demand across Shanghai, Jiangsu, and Zhejiang maternal health networks. SAMR pricing transparency rules compress hospital markup structures on cell-free DNA screening panels. Suzhou and Hangzhou biotech parks host domestic reagent manufacturers scaling polymerase production for NGS workflows.
Pearl River Delta
Guangdong province integrates pharmacogenomic testing into tier-three hospital formularies for cardiovascular and oncology therapeutics. MEE hazardous waste regulations govern disposal protocols for Shenzhen high-throughput sequencing facilities. Guangzhou medical centers expand BRCA and Lynch syndrome screening for high-risk patient stratification.
Sichuan-Chongqing
Western China presents untapped demand for warfarin and clopidogrel genotyping in Chengdu and Chongqing cardiology departments. Dual carbon policy mandates steer hospital procurement toward energy-efficient thermal cyclers and sequencing platforms. Local health commissions pilot AI-assisted variant interpretation for rare disease cases.
China Genetic Testing Market Key Industry Players
Capital-heavy instrument manufacturers compete with asset-light bioinformatics specialists across China's genetic testing value chain. Market structure consolidates around three domestic conglomerates controlling sequencing hardware while fragmenting across dozens of reagent suppliers and software vendors. Strategic archetypes separate platform owners, consumables producers, and interpretation service providers. Dominant competitive moves include backward integration into reagent manufacturing and cloud-based bioinformatics partnerships with tier-one hospitals.
Among Beijing-based sequencing specialists, BGI Genomics and MGI Tech occupy positions as platform anchors with proprietary flow-cell chemistry and domestic manufacturing scale. WuXi NextCODE exemplifies the bioinformatics archetype through rare disease interpretation specialization. Berry Genomics represents the prenatal testing vertical with established NIPT service networks across municipal health commissions.
| Leading Market Players |
|---|
| WuXi NextCODE |
| WuXi PharmaTech |
| BGI Genomics |
| CapitalBio Technology |
| MGI Tech |
| Berry Genomics |
| Annoroad Gene Technology |
| GeneID Technology |
| Daan Gene |
| Others |
Cost & Logistics Intelligence
High-fidelity polymerase procurement from US and European specialty chemical producers cascades through three distinct pricing tiers for NGS reagent kits, with hospital laboratories absorbing currency volatility through centralized provincial procurement contracts that compress margins on imported consumables.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs genetic testing reagents and instruments in China, with premium tiers commanded by FDA-cleared imported assays and economy tiers captured by domestic GB-certified alternatives. Price differentiation hinges on NMPA registration tier and hospital procurement volume scale. Cost compression in standard-tier NGS panels is intensifying because provincial health commission consortia aggregate demand across tier-two and tier-three facilities. Municipal maternal health networks exhibit highest price sensitivity for NIPT reagent kits, while Beijing oncology reference laboratories show lowest sensitivity for companion diagnostic assays.
Supply Chain Analysis
Fluorescent probe and high-fidelity enzyme supply rests on US, German, and Japanese specialty chemical manufacturers, with domestic polymerase production scaling in Suzhou and Hangzhou biotech parks. Raw material dependencies span modified nucleotides, fluorophore conjugates, and sequencing flow-cell substrates. Single-source vulnerability concentrates in thermostable polymerase enzymes held by three overseas suppliers. Distribution runs through provincial health commission procurement platforms that consolidate previously fragmented hospital laboratory purchasing decisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's genetic testing market reads as a late-cycle quality story as precision prescribing protocols shift demand toward NMPA-cleared companion diagnostics with demonstrated clinical utility over unvalidated laboratory-developed tests.
For Market Incumbents: Extend proprietary sequencing chemistry advantages into cloud-based bioinformatics partnerships with tier-one hospital networks. Incumbent platform owners should deepen backward integration into reagent manufacturing to offset currency exposure on imported polymerases. MGI Tech and BGI Genomics face emerging pressure from long-read platform entrants in structural variant detection applications. For New Entrants and Emerging Players: Enter via AI-assisted variant interpretation software positioned for NMPA software-as-medical-device registration, targeting the rare disease curation bottleneck concentrated in tier-one academic medical centers. The most penetrable white-space sits in pharmacogenomic panel deployment across Sichuan and Shaanxi tier-three cardiology departments. A direct-to-hospital laboratory sales model bypassing centralized procurement platforms offers viable go-to-market positioning. For Investors and Strategic Acquirers: Consolidation pressure builds where bioinformatics talent scarcity fragments variant interpretation service providers across dozens of sub-scale competitors. Long-term viability favors asset-light interpretation specialists with established NMPA regulatory pathways over capital-intensive instrument manufacturers facing replacement cycle compression. The signal to watch is NMPA breakthrough device pathway expansion into AI diagnostic algorithms as inflection indicator for software-as-medical-device valuations.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Software-as-Medical-Device Registration | Enables AI variant interpretation tools to exit regulatory gray zones and capture hospital procurement contracts. |
| Backward Integration into Polymerase Manufacturing | Reduces currency volatility exposure for domestic reagent producers serving Yangtze River Delta laboratories. |
| Provincial Health Commission Partnership | Secures volume placement through centralized procurement platforms consolidating tier-two and tier-three demand. |
| Long-Read Platform Clinical Adoption | Penetrates structural variant and methylation analysis applications previously inaccessible to short-read chemistry. |
| Pharmacogenomic Panel Tier-Three Expansion | Captures warfarin and clopidogrel genotyping demand in Sichuan and Shaanxi cardiovascular departments. |
Research Approach
Bottom-up hospital laboratory modeling reconciled against top-down instrument shipment tracking forms the analytical core of this study. Primary interviews with NMPA regulatory affairs specialists, hospital procurement committee members, clinical geneticists, and reference laboratory operations directors were combined with secondary validation from NMPA medical device registration databases, SAMR pricing transparency filings, and provincial health commission procurement records. This approach triangulates demand-side test volume assumptions against supply-side reagent and instrument production data.
Historical trendline analysis of NGS and PCR platform installations across Beijing, Shanghai, and Guangzhou tertiary medical centers established baseline penetration rates. The projection framework segments by technology chemistry, NMPA registration tier, hospital classification, and application area across the analysis window. CAGRs were derived from modeled test volume expansion in oncology companion diagnostics, pharmacogenomic protocols, and NIPT corridors, calibrated against MGI Tech and BGI Genomics disclosed instrument placement trends.
Inputs from NMPA registration databases and provincial procurement platforms were available through the study window; gaps in private laboratory pricing data and reagent import volumes introduce uncertainty bands around margin estimates. Forecasts reflect assumptions regarding NMPA breakthrough device pathway expansion and provincial reimbursement decisions. Regulatory delays in AI diagnostic algorithm classification and SAMR markup enforcement intensity warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Direct-To-Consumer (DTC) Genetic Testing Market
Genomics
Point-Of-Care Genetic Testing Market
Genomics
Cancer-Focused Genetic Testing Services Market
Genomics
Omics Lab Services Market
Genomics
Global Immune Repertoire Sequencing Market
Genomics
Forensic Genomics Market
Genomics
Europe Genetic Testing Market
Genomics
Next-Generation Sequencing for Non-Invasive Prenatal Testing Market
Genomics
Global Gene Expression Market
Genomics
Genomics and Transcriptomics Market
Genomics
Genome Sequencing Market
Genomics
Whole Exome Sequencing (WES) Market
Genomics
Genetic Leukemia Detection Testing Market
Genomics
Short-Read Sequencing Market
Genomics
Europe Hereditary Cancer Testing Market
Genomics
North America DNA Sequencing Products Market