
 Omics Lab Services Market | 2026-2036
Omics Lab Services Market Size, Share, and Industry Trends Forecast 2026-2036
Omics Lab Services Market Intelligence
Software-defined bioinformatics pipelines are realigning what laboratories sell, shifting value from raw instrument runs to interpretive data packages. Thermo Fisher Scientific leverages its cloud-based analysis platforms to extend recurring revenue beyond physical sequencing. BGI Group anchors its competitive position through massive sample throughput infrastructure spanning multiple continents. Illumina, Inc. dominates the installed base of sequencing hardware, though it now competes with service providers bundling instruments into per-sample contracts.
Omics lab services encompass the outsourced generation, processing, and analysis of genomic, proteomic, transcriptomic, and metabolomic data using specialized instrumentation and computational workflows. These services typically employ next-generation sequencing producing reads from 50 to 300 base pairs, mass spectrometry resolving proteins at parts-per-million mass accuracy, and quantitative PCR achieving cycle threshold precision for expression profiling, all directed toward biomarker identification, therapeutic target validation, and diagnostic assay development. Genomics services currently occupy the largest revenue share given clinical adoption of tumor profiling and rare disease testing. Proteomics and metabolomics represent faster-growing service lines as pharmaceutical clients seek multi-omic integration for biomarker discovery. Drug discovery applications command premium pricing compared to agricultural research, though personalized medicine diagnostics show the steepest volume trajectory.
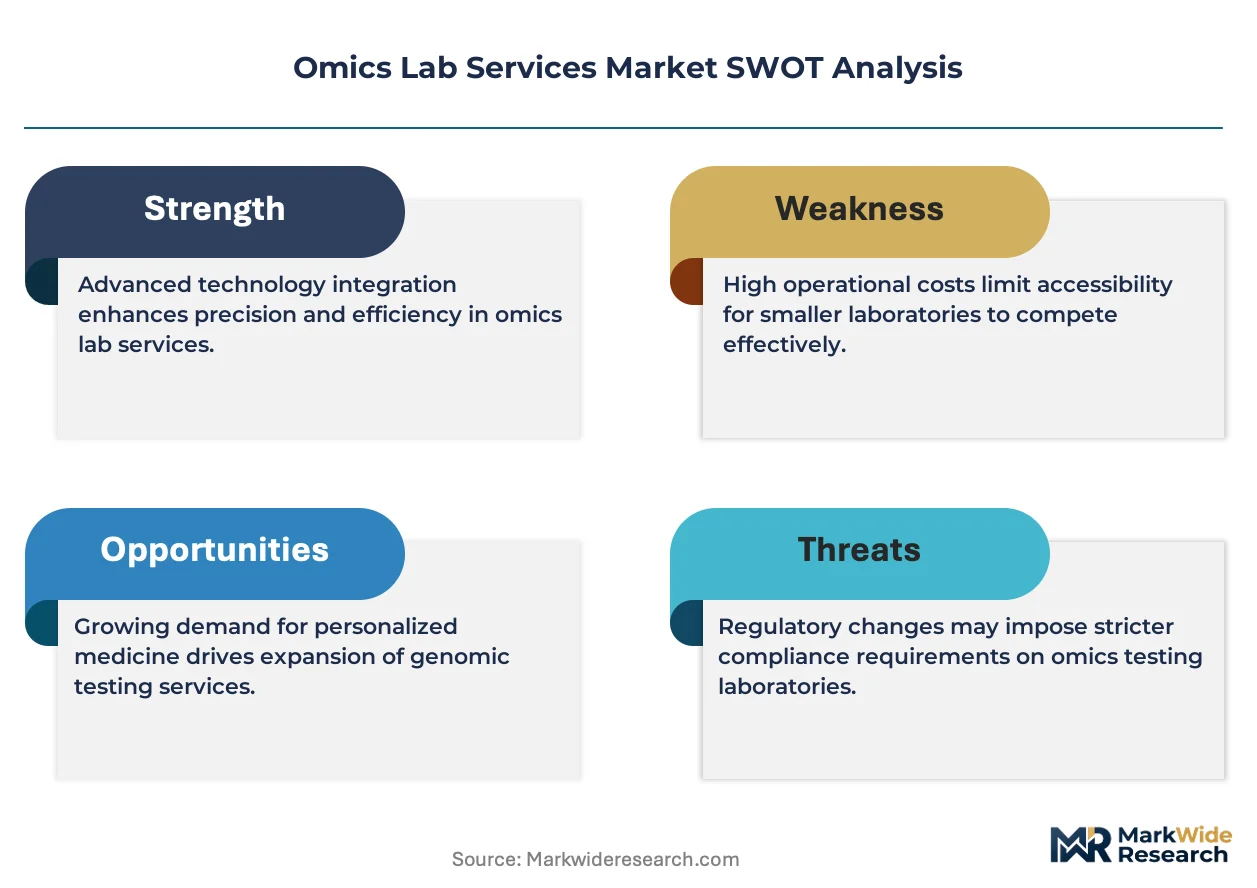
FDA oversight of laboratory-developed tests and clinical trial assay validation shapes service provider investment in quality management systems. The EMA's In Vitro Diagnostic Regulation and GDPR constraints on genomic data transfer create compliance complexity for European operations. China's NMPA accelerated review pathways for innovative diagnostics are redirecting capacity expansion toward domestic biotech clusters. Stakeholders must monitor how fragmented reimbursement policies across national health systems determine which omics applications transition from research to routine clinical use.
Market Dynamics
Software-defined bioinformatics pipelines are compressing turnaround times from weeks to days, forcing service providers to reconfigure pricing models around data interpretation rather than instrument access alone.
Growth Catalysts
- Precision medicine mandates:FDA's accelerated approval pathways for companion diagnostics are expanding clinical sequencing volumes. Biopharma sponsors now require biomarker stratification for oncology trials.
- Multi-omic integration:Pharmaceutical clients are contracting combined genomics-proteomics workflows to reduce target validation cycles. Service providers bundling these capabilities capture premium positioning.
- China's NMPA fast-track:Domestic biotech clusters in Shanghai and Suzhou are attracting regional sequencing capacity. Local innovators receive priority review for novel diagnostic platforms.
Market Restraints
- Reagent supply concentration:Specialized polymerases and modified nucleotides originate from a limited supplier base in Germany and the United States. Disruptions propagate directly to service delivery timelines.
- GDPR genomic data friction:Cross-border transfer restrictions complicate multi-site clinical studies spanning European and non-European jurisdictions. Compliance overhead consumes operational bandwidth.
- Illumina instrument lock-in:Proprietary flow cell chemistry creates switching costs that limit price competition. Alternative platform adoption requires full workflow revalidation.
Strategic Opportunities
- Liquid biopsy standardization:Circulating tumor DNA protocols remain methodologically fragmented. Laboratories establishing CLIA-validated, reproducible workflows will capture clinical trial outsourcing.
- Single-cell multi-omics:Convergence of droplet microfluidics with mass spectrometry is opening spatial transcriptomics services. Academic medical centers represent early adopters.
- India's CDSCO diagnostic expansion:Regulatory clarity for next-generation sequencing-based oncology panels is emerging. First-mover laboratories can establish reference laboratory relationships with domestic hospitals.
Industry Challenges
- Bioinformatics talent scarcity:Computational biologists capable of pipeline development and clinical interpretation command compensation premiums. Training pipelines lag market requirements by three to five years.
- CAP/CLIA dual accreditation complexity:Laboratories serving both research and clinical markets must maintain parallel quality systems. Audit preparation diverts technical staff from revenue-generating activities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Omics Lab Services Market |
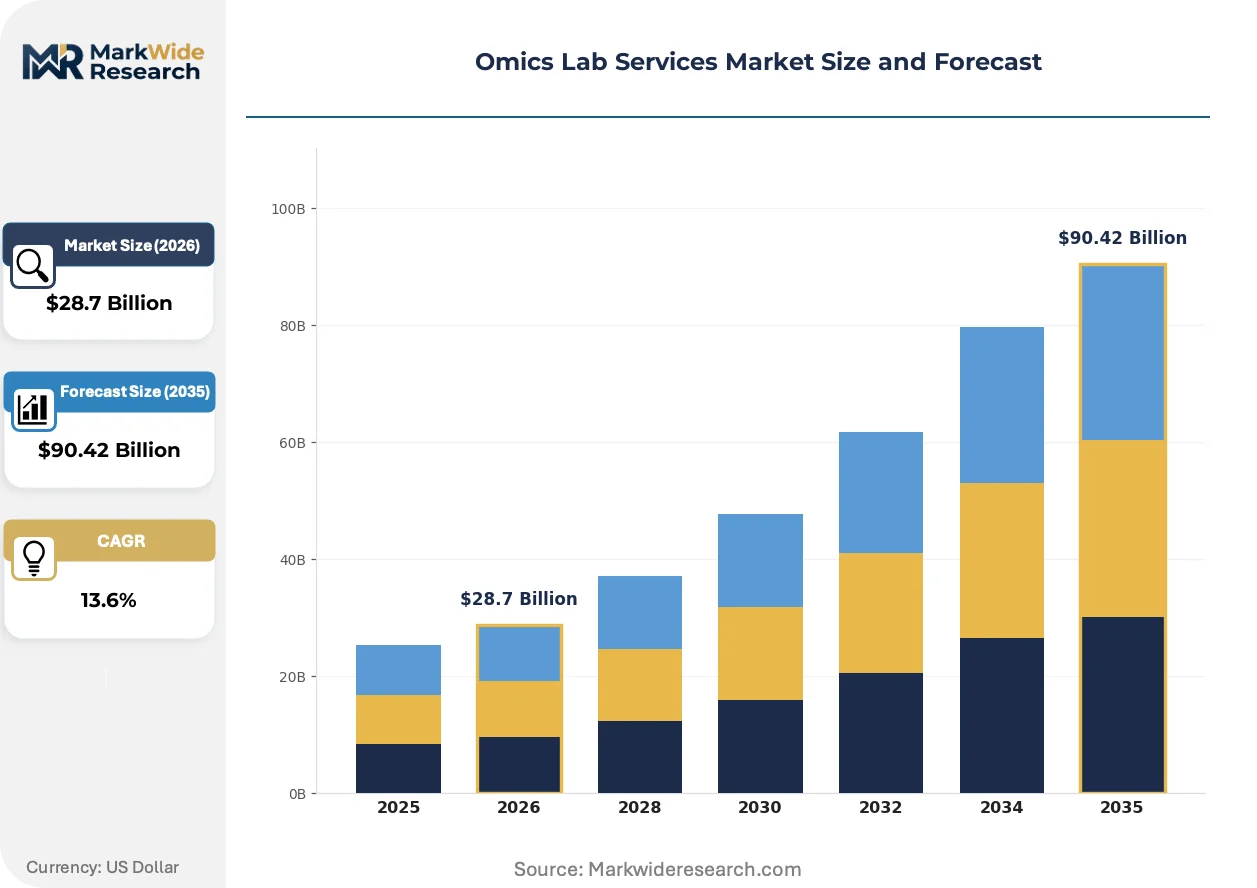
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $90.42 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Genomics, Proteomics, Transcriptomics, Metabolomics End User: Biotechnology Firms, Pharmaceutical Companies, Academic Institutions, Research Organizations Technique: Next-Generation Sequencing, Mass Spectrometry, Microarray, PCR Application: Drug Discovery, Personalized Medicine, Diagnostics, Agricultural Research |
| Companies Covered | Quest Diagnostics Incorporated, BGI Group, Thermo Fisher Scientific, Inc., Flomics Biotech, Q2 Solutions, Agilent Technologies, Inc., Illumina, Inc., PhenoSwitch Bioscience, Qiagen N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Omics Lab Services Market Strategic Shifts & Innovations
Artificial intelligence is embedding directly into sequencing workflows, compressing variant interpretation from days to hours while raising new questions about algorithmic validation standards.
Cloud-native bioinformatics platforms are unifying sample tracking, computational processing, and clinical reporting into single environments. Mid-sized biopharma sponsors lacking internal informatics infrastructure are adopting these systems fastest. This architecture is unifying what were previously fragmented vendor relationships, reducing switching flexibility.
EMA's In Vitro Diagnostic Regulation is mandating clinical evidence standards for laboratory-developed tests that previously operated under lighter oversight. Service providers must now generate prospective performance data for oncology panels. European reference laboratories are responding by consolidating clinical trial assay development with routine diagnostic production.
Pharmaceutical procurement teams are unbundling sequencing services from data analysis, creating separate vendor relationships for wet-lab production and dry-lab interpretation. Contract research organizations with captive sequencing capacity face margin pressure from specialized bioinformatics boutiques. This pattern is most visible in United States-based Phase II oncology trials where sponsor data science teams prefer direct platform access.
Omics Lab Services Market Segmentation
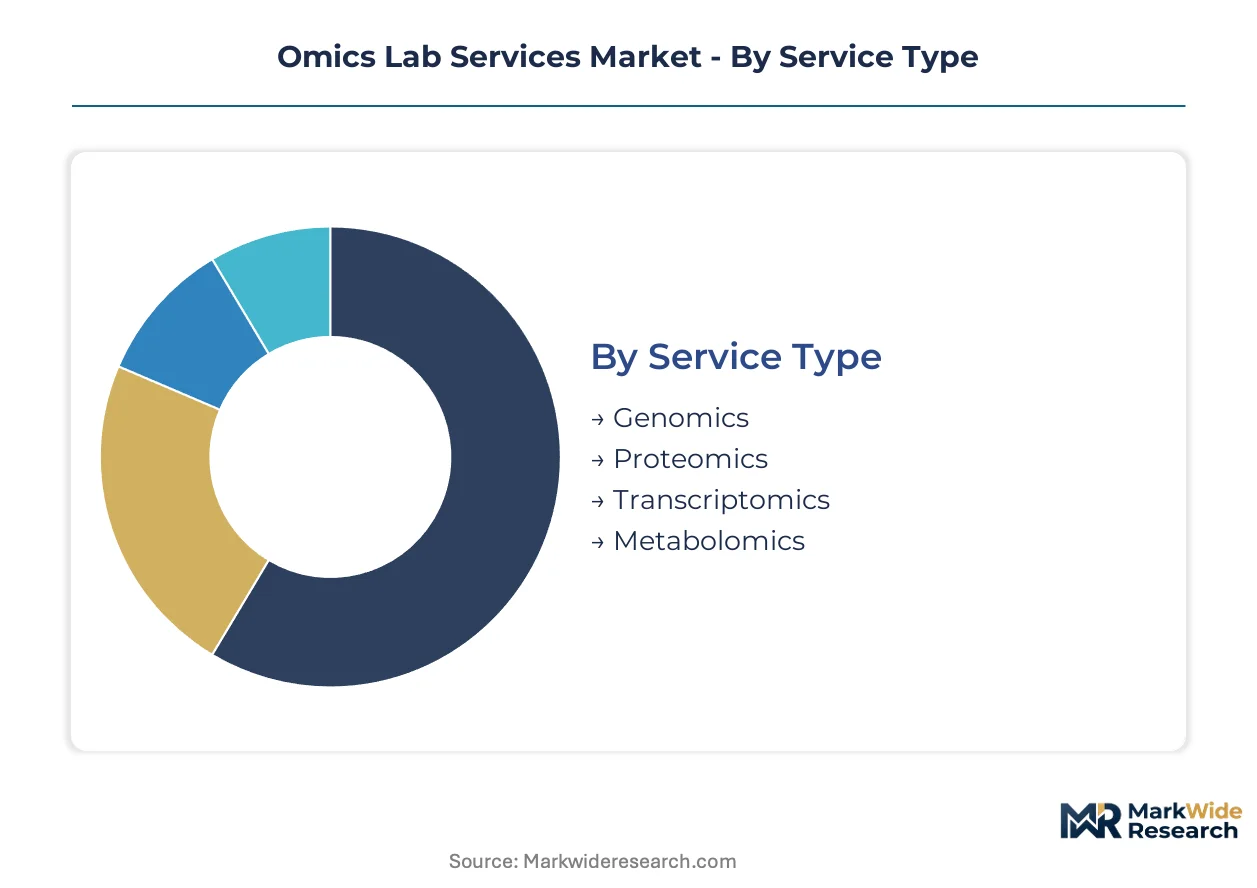
Omics lab services fragment across multiple technical and commercial dimensions, each carrying distinct margin profiles and customer loyalty patterns. Pharmaceutical procurement teams evaluate segments through the lens of regulatory burden and data interpretability rather than per-sample cost alone. Understanding these structural divisions reveals where service providers can defend pricing power versus where commoditization pressures dominate.
Service Type:
Upgrade cycles from microarray to sequencing platforms are compressing replacement timelines from seven years to four, reshaping how laboratories amortize capital equipment across service lines.
- Genomics:DNA and RNA analysis services employing next-generation sequencing platforms producing 50-300 base pair reads with variant calling pipelines. Tumor profiling contracts in the United States and rare disease testing mandates from Germany's national health system concentrate demand here. FDA companion diagnostic approvals are expanding clinical sequencing volumes faster than research applications.
- Proteomics:Mass spectrometry-based protein identification and quantification resolving analytes at parts-per-million mass accuracy. Pharmaceutical sponsors in China and the United States are contracting multi-omic integration workflows that combine proteomics with genomics to compress target validation cycles. Service providers bundling these capabilities capture premium positioning.
- Transcriptomics:RNA sequencing and expression profiling services using quantitative PCR and sequencing-based methods. Academic medical centers represent the primary demand concentration for spatial transcriptomics applications.
- Metabolomics:Small-molecule profiling through mass spectrometry and nuclear magnetic resonance. Agricultural biotechnology firms in Germany and the United States utilize metabolomic services for crop trait validation.
Volume placements concentrate in Genomics; the faster expansion belongs to Proteomics.
End User:
Cost tier differentiation separates enterprise pharmaceutical sponsors with captive data science teams from mid-sized biotechnology firms outsourcing entire analytical workflows.
- Pharmaceutical Companies:Large sponsors with internal bioinformatics infrastructure unbundling wet-lab production from dry-lab interpretation. Phase II oncology trials in the United States increasingly separate sequencing vendors from analytical boutiques. Procurement teams negotiate per-sample contracts with direct platform access clauses.
- Biotechnology Firms:Venture-backed innovators lacking computational infrastructure adopting cloud-native bioinformatics platforms bundled with sequencing services. Shanghai and Suzhou clusters are redirecting regional capacity expansion toward these domestic sponsors under NMPA fast-track pathways.
- Academic Institutions:University medical centers and research hospitals with grant-funded sequencing requirements. Spatial transcriptomics and single-cell multi-omics adoption concentrates here.
- Research Organizations:Government laboratories and independent research institutes conducting agricultural and environmental omics. Metabolomics and transcriptomics services see steady demand from this segment.
Revenue concentration sits with Pharmaceutical Companies; Biotechnology Firms are gaining share fastest.
Technique:
Application maturity separates established clinical workflows from emerging methods still navigating validation requirements.
- Next-Generation Sequencing:Dominant platform for genomic and transcriptomic analysis with established CLIA-validated pipelines. Illumina's installed base creates switching costs, though alternative platforms from BGI Group and Thermo Fisher Scientific are gaining traction in non-United States markets.
- Mass Spectrometry:Core technology for proteomic and metabolomic services requiring specialized operator expertise. Proteomics services combining mass spectrometry with liquid chromatography command premium pricing for biomarker discovery contracts.
- Microarray:Legacy platform for expression profiling and genotyping now displaced by sequencing in most major markets. Agricultural research applications retain some microarray demand for cost-sensitive screening.
- PCR:Quantitative and digital PCR methods for targeted expression analysis and rare variant detection. Diagnostic assay development services utilize PCR for clinical trial companion diagnostic validation.
Installed base dominance belongs to Next-Generation Sequencing; Mass Spectrometry is climbing the fastest.
Application:
Margin structure differentiates premium-priced drug discovery services from volume-driven diagnostic production.
- Drug Discovery:Target validation and biomarker identification services for pharmaceutical sponsors. Multi-omic integration workflows command the highest per-sample pricing. EMA's In Vitro Diagnostic Regulation is mandating clinical evidence standards that increase assay development costs.
- Personalized Medicine:Companion diagnostic and tumor profiling services with steepest volume trajectory. FDA accelerated approval pathways are expanding clinical sequencing volumes. Reimbursement fragmentation across national health systems determines which applications transition from research to routine use.
- Diagnostics:Laboratory-developed tests and clinical trial assay validation services. CAP/CLIA dual accreditation requirements create operational complexity for providers serving both research and clinical markets.
- Agricultural Research:Crop genomics and livestock breeding applications with cost-sensitive pricing. Metabolomics and transcriptomics services see demand from seed companies and agricultural biotechnology firms.
Pricing power concentrates in Drug Discovery; Personalized Medicine shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors the most concentrated sequencing infrastructure outside North America, with Suzhou and Beijing forming a domestic biotech corridor that processes clinical trial volumes rivaling European hubs.
United States
FDA accelerated approval pathways for companion diagnostics are expanding clinical sequencing volumes faster than research applications. The agency's oversight of laboratory-developed tests shapes provider investment in quality management systems. Greater Boston and San Diego biotech clusters concentrate precision medicine contract research, with sponsors unbundling wet-lab production from analytical interpretation.
China
NMPA fast-track review pathways for innovative diagnostics are redirecting capacity expansion toward domestic biotech clusters. The regulator's priority review for novel diagnostic platforms benefits Shanghai and Suzhou innovators. BGI Group anchors massive sample throughput infrastructure spanning multiple continents from its Shenzhen headquarters.
Germany
Germany's national health system mandates for rare disease testing concentrate genomics demand in centralized reference laboratories. EMA's In Vitro Diagnostic Regulation and GDPR constraints on genomic data transfer create compliance complexity for European operations. Munich and Heidelberg academic medical centers drive spatial transcriptomics adoption for research applications.
India
CDSCO regulatory clarity for next-generation sequencing-based oncology panels is emerging from Delhi and Mumbai regulatory offices. The country's national pharmaceutical regulator is establishing frameworks for clinical trial assay validation. Bangalore and Hyderabad biotech parks attract first-mover laboratories seeking reference laboratory relationships with domestic hospital networks.
United Kingdom
Genomics England's population-scale sequencing initiatives sustain demand for high-throughput service providers. The country's national health system reimbursement policies determine which omics applications transition from research to routine clinical use. Cambridge and London academic medical centers represent early adopters of single-cell multi-omics workflows.
Omics Lab Services Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the omics services landscape. Full-service laboratories maintaining captive sequencing infrastructure face margin pressure from specialized bioinformatics boutiques that rent instrument access. Three archetypes dominate: integrated platform providers bundling hardware and analysis, pure-play service laboratories selling per-sample contracts, and cloud-native analytics firms unifying computational processing. Capacity expansion and strategic partnerships represent the dominant competitive moves, with procurement teams fragmenting vendor relationships between wet-lab and dry-lab providers.
Within the integrated platform tier, Thermo Fisher Scientific and Illumina occupy positions exemplifying divergent strategies around hardware ownership versus per-sample accessibility. BGI Group represents the scale-driven archetype with massive throughput infrastructure spanning multiple continents. Qiagen N.V. sits within the reagent and sample preparation specialization tier, anchoring upstream workflow components rather than downstream analysis services.
| Leading Market Players |
|---|
| Quest Diagnostics Incorporated |
| BGI Group |
| Thermo Fisher Scientific, Inc. |
| Flomics Biotech |
| Q2 Solutions |
| Agilent Technologies, Inc. |
| Illumina, Inc. |
| PhenoSwitch Bioscience |
| Qiagen N.V. |
| Others |
Cost & Logistics Intelligence
Modified nucleotide spot prices from German specialty chemical suppliers cascade through reagent manufacturing into three distinct service tiers, with clinical-grade sequencing contracts commanding substantial premiums over research-only workflows.
Pricing Analysis
Cost-down pressure on standard genomics services accelerates because pharmaceutical procurement teams now unbundle wet-lab production from bioinformatics interpretation. Three-tier pricing structure across premium, standard, and economy levels separates CAP/CLIA dual-accredited clinical trials work from research-grade sequencing and agricultural screening contracts. Price differentiation hinges on regulatory certification burden and per-sample data interpretation depth. Biotechnology firms lacking internal computational infrastructure show highest price sensitivity, while large pharmaceutical sponsors prioritize turnaround reliability over per-unit cost.
Supply Chain Analysis
Refurbished Illumina instrument flows from United States academic medical centers into Indian and Chinese service laboratories compress capital barriers for mid-tier entrants. Specialized polymerases and flow cell chemistry components originate predominantly from Germany and the United States, creating concentrated dependency on trans-Atlantic reagent shipments. Single-source vulnerability around proprietary sequencing consumables threatens service continuity during trade disruptions. Distribution runs through regional hub-and-spoke models anchored by BGI Group's Shenzhen infrastructure and Thermo Fisher Scientific's North American logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Omics lab services are consolidating around scale players with captive bioinformatics platforms, as reagent supply concentration and talent scarcity squeeze margin-stressed regional laboratories toward acquisition or exit.
For Market Incumbents: Lock in long-term reagent supply agreements with German and United States specialty chemical suppliers before capacity constraints tighten further. Acquire distressed bioinformatics boutiques in United States oncology hubs to preempt pharmaceutical sponsors from building captive analytical teams. Cloud-native platform integration represents the critical defensive lever against unbundling pressures.
For New Entrants and Emerging Players: Contract research organizations with fragmented sequencing relationships offer the most penetrable channel entry point for specialized analytical boutiques. India's CDSCO regulatory clarity window for oncology panels creates first-mover opportunity for reference laboratory partnerships with Bangalore and Hyderabad hospital networks. Lead with CLIA-validated liquid biopsy workflows rather than competing head-to-head on sequencing volume.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap proteomics specialists with mass spectrometry infrastructure in China and Germany, where multi-omic integration demand outpaces analytical capacity. Long-term viability centers on laboratories bundling wet-lab production with interpretive software platforms rather than pure-play service models. Monitor FDA companion diagnostic approval velocity as the primary inflection signal for clinical sequencing volume expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Bioinformatics Platform Integration | Unifies sample tracking and clinical reporting for mid-sized biopharma sponsors lacking internal infrastructure. |
| CLIA-Validated Liquid Biopsy Workflow Development | Captures clinical trial outsourcing from pharmaceutical sponsors seeking standardized circulating tumor DNA protocols. |
| Multi-Omic Service Bundling | Combines genomics-proteomics workflows to compress target validation cycles for pharmaceutical clients. |
| Regional Capacity Expansion in China | Positions laboratories to serve NMPA fast-track diagnostic innovators in Shanghai and Suzhou biotech clusters. |
| CAP/CLIA Dual Accreditation Investment | Enables simultaneous service to research and clinical markets despite parallel quality system overhead. |
Research Approach
Multi-period observation of sequencing platform placement rates, reagent pricing indices, and regulatory submission volumes anchored the trend analysis, supplemented by interviews with laboratory operations directors, pharmaceutical procurement managers, bioinformatics pipeline developers, and clinical trial assay specialists. Secondary validation drew from FDA 510(k) filings, EMA In Vitro Diagnostic Regulation guidance documents, NMPA priority review announcements, and CDSCO oncology panel framework publications. Bottom-up service provider revenue estimates triangulated against top-down pharmaceutical R&D outsourcing expenditure patterns.
Input-output matrices modeled capacity utilization, sample throughput, and pricing tier migration across service type, end user, technique, and application dimensions throughout the forecast period. CAGRs derived from segment-level growth rate convergence around macro drivers including precision medicine adoption curves and regulatory approval velocity. Industry-specific forecast inputs incorporated NGS platform replacement cycles and mass spectrometry operator training pipeline lags.
Caveats apply where reagent supply disruptions, GDPR enforcement shifts, or reimbursement policy fragmentation could materially shift the outlook from modeled trajectories. Practitioners should monitor FDA accelerated approval pathway expansion rates and China's NMPA fast-track queue depth for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Multiomics Market
Genomics
Genetic Leukemia Detection Testing Market
Genomics
Oligonucleotide Pool Market
Genomics
Genetic Testing Service Market
Genomics
Digital Genome Market
Genomics
Spatial OMICS Market
Genomics
Genomics Personalized Health Market
Genomics
Global Microbiome Sequencing Services Market
Genomics
North America Whole Exome Sequencing Market
Genomics
Glycan Sequencing Market
Genomics
Global Digital PCR Market
Genomics
Global Lab Automation in Genomics Market
Genomics
Genotyping Market
Genomics
Global Genomics Market
Genomics
Global Whole Genome Sequencing (WGS) Market
Genomics
Global Genotyping Assay Market