
 NGS-Based RNA-Sequencing Market | 2026-2036
NGS-Based RNA-Sequencing Market Size, Share, and Industry Trends Forecast 2026-2036
NGS-Based RNA-Sequencing Market Outlook
Pharmaceutical companies is realigning the end-use mix as transcriptome analysis and biomarker discovery displace legacy gene expression methods in drug pipelines. Illumina, Inc. dominates instrument placement across academic and commercial labs with its NovaSeq and NextSeq platforms. Thermo Fisher Scientific Inc. leverages its integrated reagent-to-analysis workflow to sustain pull-through chemistry revenue. Oxford Nanopore Technologies differentiates through real-time, amplification-free sequencing that extends utility into field-deployable and point-of-need settings.
NGS-based RNA-sequencing refers to massively parallel cDNA or direct RNA sequencing on high-density flow cells or nanopore arrays, generating millions to billions of reads per run with sensitivity down to single-transcript detection. The technology serves transcriptome quantification, splice-variant identification, and differential gene expression analysis for therapeutic target validation and diagnostic development. Single-cell sequencing commands premium instrument and reagent spend as researchers dissect cellular heterogeneity in tumor microenvironments and immune responses. Bulk RNA sequencing retains volume leadership in population-scale studies and clinical trial cohort profiling where cost-per-sample dominates procurement decisions. Kits and reagents capture recurring revenue streams with higher margins than capital equipment, while software segments compete on cloud-based pipeline accessibility and regulatory-compliant variant reporting.
The FDA qualifies biomarkers through its Voluntary Exploratory Data Submissions program, shaping how sequencing outputs enter drug approval pathways. The EMA's In Vitro Diagnostic Regulation and the EU AI Act impose conformity and algorithmic transparency requirements on software-integrated sequencing workflows marketed in Europe. China's NMPA accelerates local instrument registration under its innovation device pathway, redirecting vendor registration priorities. Stakeholders must monitor divergence between FDA guidance on next-generation sequencing-based oncology panels and EMA expectations for clinical-grade transcriptomic evidence, as this gap determines where product development resources yield fastest market access.
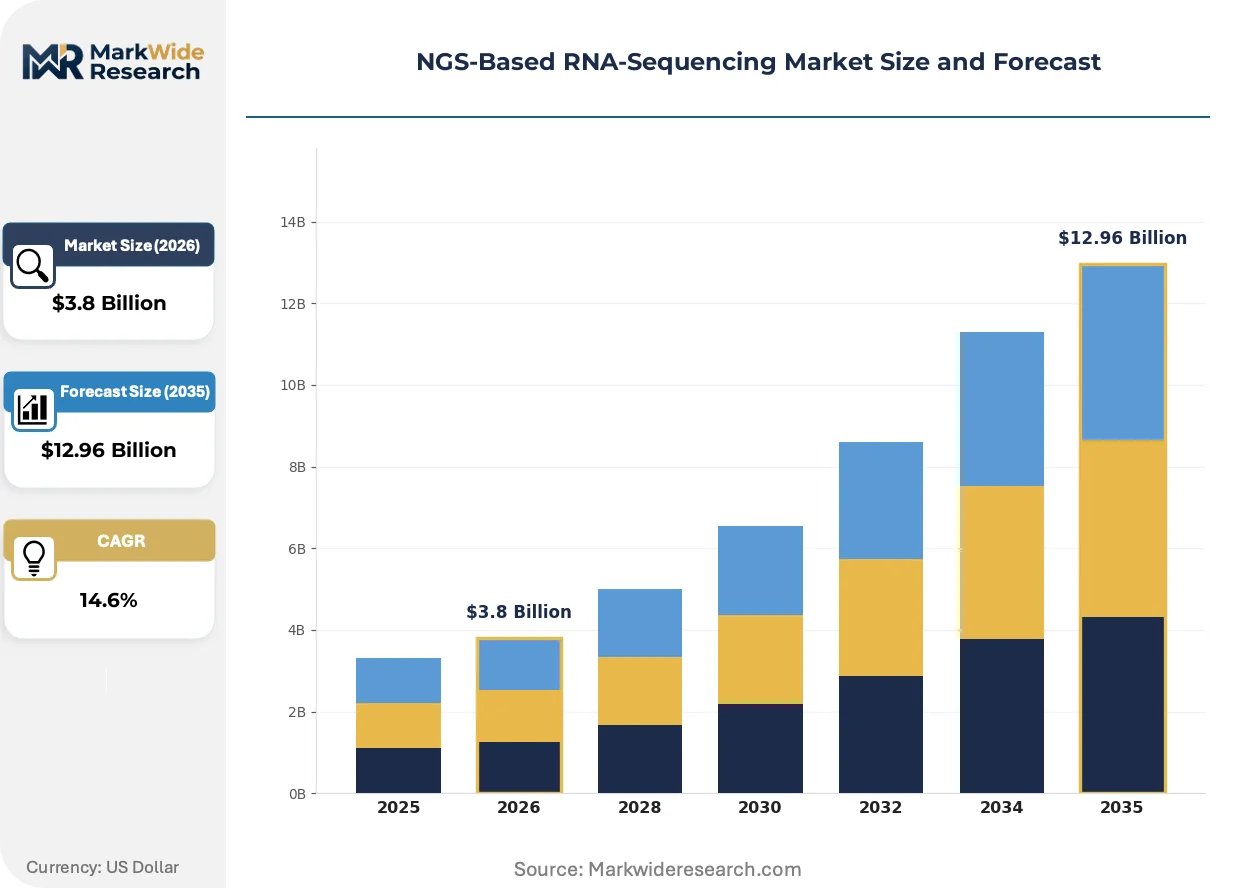
Market Dynamics
The transition from bulk RNA sequencing to single-cell and spatial transcriptomics is compressing run economics while elevating per-sample data complexity, forcing vendors to recalibrate platform architectures and software pipelines.
Growth Catalysts
- Companion diagnostic pathways:The FDA's Voluntary Exploratory Data Submissions program accelerates biomarker qualification, embedding transcriptomic evidence into oncology drug approvals.
- Spatial transcriptomics:Visium and MERFISH platforms map gene expression to tissue morphology, opening new therapeutic target discovery workflows in immuno-oncology.
- Boston-San Francisco corridor:Academic medical centers and venture-backed biotechs concentrate instrument procurement, creating dense consumable pull-through ecosystems.
Market Restraints
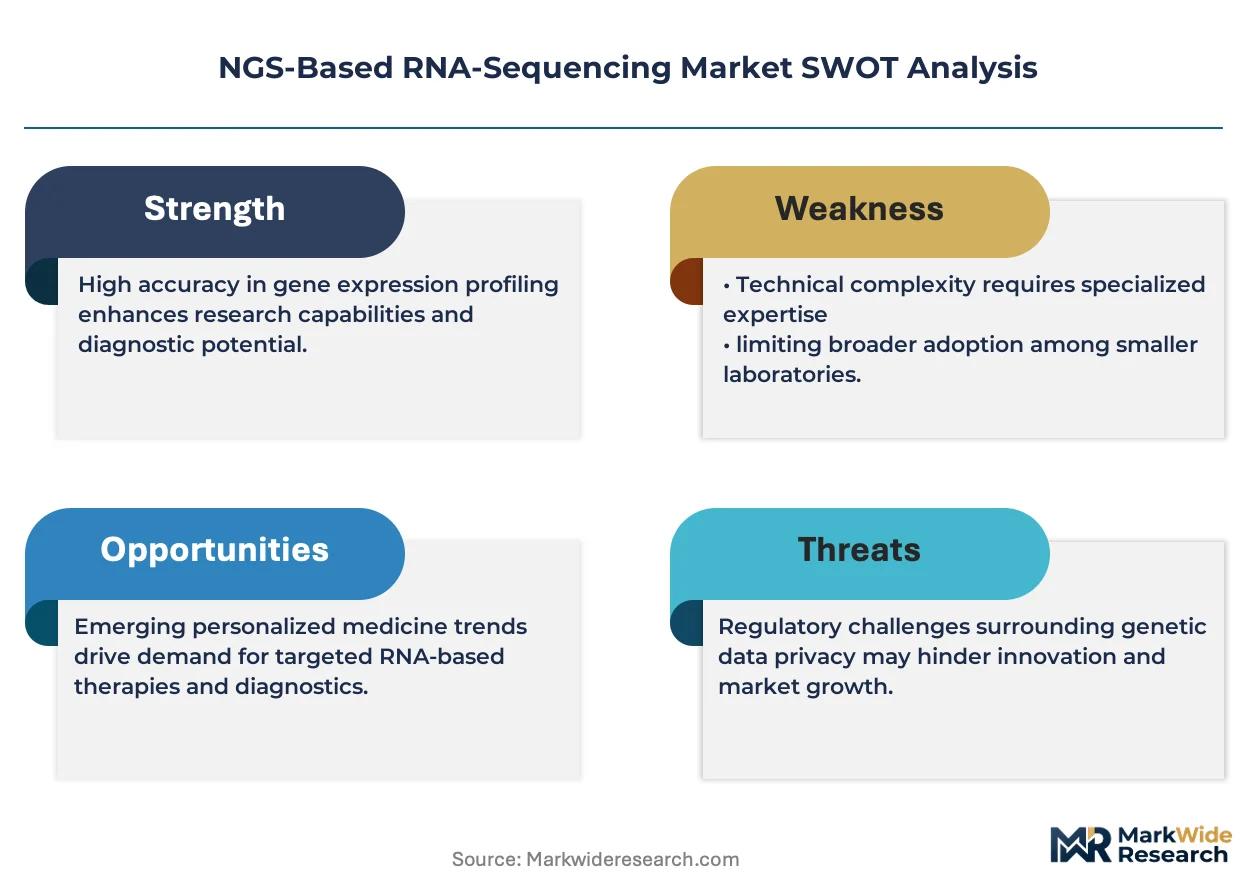
- Reagent cost structure:Library preparation kits and flow cell consumables account for 60-70% of per-sample spend, limiting access for resource-constrained research programs.
- Supply concentration:Flow cell manufacturing concentrates among three vendors, creating vulnerability to batch variability and allocation constraints.
- Technical limitation:Short-read platforms struggle with full-length transcript reconstruction, fragmenting alternative splicing analysis across multiple assays.
Strategic Opportunities
- Field-deployable sequencing:Oxford Nanopore's portable MinION devices enable point-of-need pathogen surveillance and outbreak response in low-infrastructure settings.
- China's innovation pathway:The NMPA accelerates local instrument registration, redirecting vendor priorities toward domestic manufacturing partnerships.
- Cloud-native bioinformatics:Containerized analysis pipelines on AWS and Google Cloud reduce on-premise compute capex for mid-scale sequencing operations.
Industry Challenges
- Bioinformatics talent scarcity:Computational biologists with dual expertise in statistics and molecular biology command premium compensation, constraining core facility expansion.
- ISO 15189 compliance timelines:Clinical laboratories face 12-18 month validation cycles for NGS-based diagnostic workflows, delaying revenue conversion from research to regulated testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | NGS-Based RNA-Sequencing Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kits, Reagents, Instruments, Software Technology: Single-Cell Sequencing, Bulk RNA Sequencing, Single-Molecule Sequencing, Amplification-Free Sequencing End User: Academic Research Institutes, Pharmaceutical Companies, Diagnostic Laboratories, Biotechnology Firms Application: Gene Expression Profiling, Biomarker Discovery, Transcriptome Analysis, Disease Research |
| Companies Covered | Illumina, Inc., Thermo Fisher Scientific Inc., Oxford Nanopore Technologies, Agilent Technologies, Inc., QIAGEN N.V., Pacific Biosciences, 10x Genomics, PerkinElmer, BGI Genomics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
NGS-Based RNA-Sequencing Market Strategic Shifts
Automation of wet-lab workflows and algorithmic standardization of variant interpretation are compressing turnaround times while expanding operator pools beyond PhD-level specialists.
Automated library preparation systems from Tecan and Hamilton Robotics are automating normalization, pooling, and quality control steps that previously required manual intervention. Mid-sized core facilities and contract research organizations adopt these platforms to increase throughput without proportional headcount expansion. The technology is automating error-prone liquid-handling steps, reducing technical replicate variance and improving cross-study comparability.
The EMA's In Vitro Diagnostic Regulation imposes clinical-grade performance documentation on transcriptomic assays marketed for patient stratification in Europe. Manufacturers must demonstrate analytical validity across intended-use populations, extending development timelines by 18-24 months for pan-European commercialization. Oncology companion diagnostic developers are responding by front-loading clinical validation studies to secure notified body certification ahead of drug approval synchronization.
Consolidated procurement through group purchasing organizations and academic buying consortia is compressing reagent pricing and bundling instrument service contracts. The University of California system and the Big Ten Academic Alliance negotiate multi-year consumable commitments in exchange for preferential pricing tiers. This concentration is most visible in the United States, where research funding agencies now require data management plan compliance as a condition of instrument grant awards.
NGS-Based RNA-Sequencing Market Segmentation
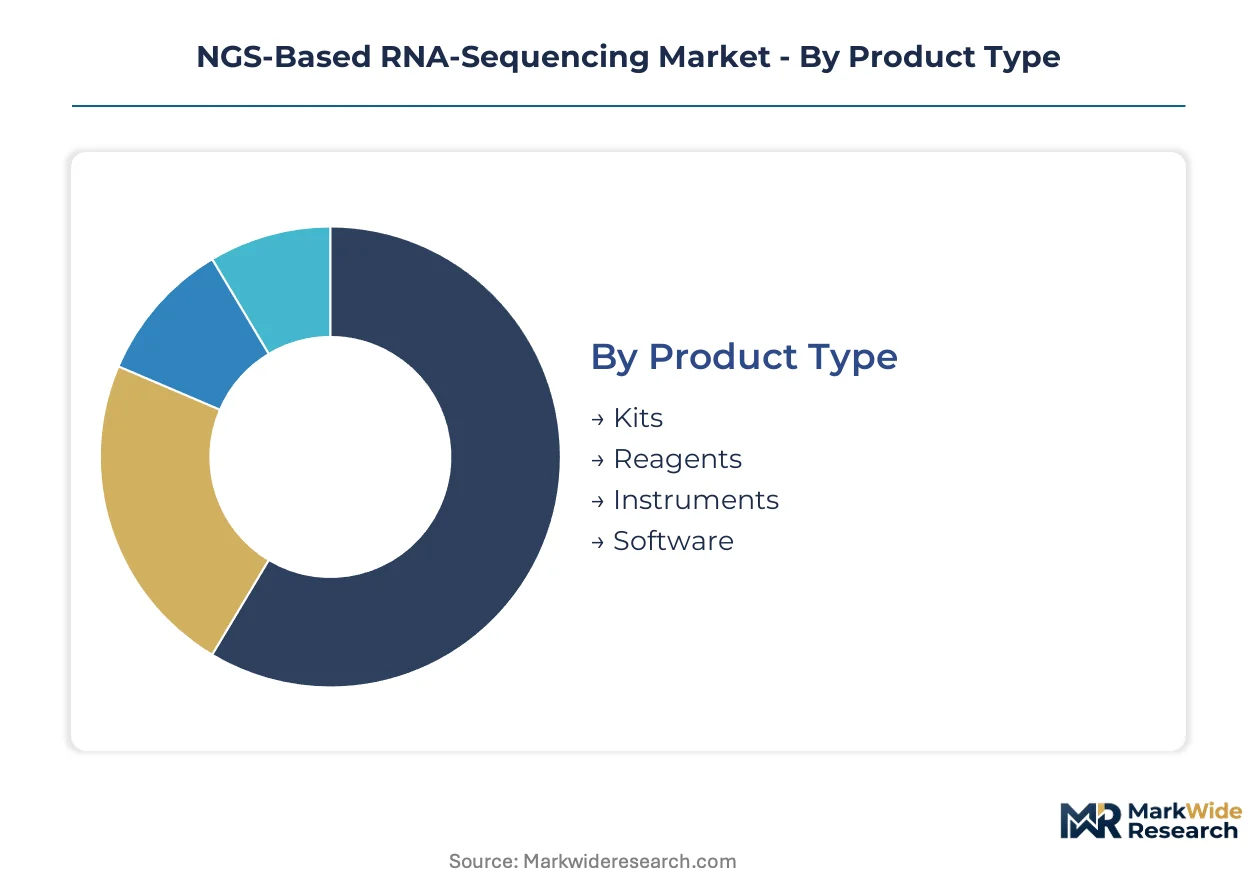
Segmentation in NGS-based RNA-sequencing reveals how revenue concentrates in recurring consumables versus capital equipment, and where technology transitions are reshaping procurement priorities across research and clinical settings.
Product Type:
Standalone reagent kits dominate pull-through economics, while integrated software platforms increasingly embed into cloud-based workflows rather than on-premise installations.
- Kits:Library preparation and RNA extraction kits constitute the highest-margin recurring revenue stream, with pharmaceutical companies in the United States driving volume through high-throughput screening programs. Reagent cost concentration limits access for smaller academic labs.
- Reagents:Flow cell consumables and sequencing chemistry account for 60-70% of per-sample spend, creating vendor lock-in effects as labs optimize protocols around specific chemistries. Supply batch variability remains a procurement risk.
- Instruments:Capital equipment spans benchtop sequencers to high-throughput production-scale platforms, with placement decisions increasingly bundled with multi-year reagent commitments.
- Software:Analysis pipelines and variant interpretation tools compete on regulatory-compliant reporting and AWS or Google Cloud integration, reducing on-premise compute requirements.
Volume placements concentrate in Kits; the faster expansion belongs to Software.
Technology:
Cost tiers separate premium single-cell platforms from economy bulk sequencing, with amplification-free methods commanding price premiums for field-deployable applications.
- Single-Cell Sequencing:Droplet-based and microwell platforms dissect cellular heterogeneity in tumor microenvironments, commanding premium instrument and reagent spend from immuno-oncology programs in Boston and San Francisco biotech clusters. Technical complexity limits adoption to well-funded core facilities.
- Bulk RNA Sequencing:Population-scale transcriptome quantification retains volume leadership in clinical trial cohort profiling where cost-per-sample dominates procurement decisions at academic medical centers.
- Single-Molecule Sequencing:Pacific Biosciences platforms enable full-length isoform characterization, addressing short-read limitations in alternative splicing analysis.
- Amplification-Free Sequencing:Oxford Nanopore's direct RNA sequencing eliminates PCR bias, extending utility into point-of-need pathogen surveillance and low-infrastructure outbreak response.
Commercial traction clusters in Bulk RNA Sequencing; the steepest expansion trajectory belongs to Single-Cell Sequencing.
End User:
Customer type determines purchasing authority structure, with pharmaceutical procurement teams negotiating enterprise-wide reagent contracts distinct from academic grant-funded instrument acquisitions.
- Academic Research Institutes:Grant-dependent funding cycles drive instrument placement through NIH and NSF awards, with data management plan compliance now a condition of funding. University of California and Big Ten Academic Alliance consortia consolidate bargaining power.
- Pharmaceutical Companies:Transcriptome analysis and biomarker discovery displace legacy gene expression methods in precision drug development pipelines, embedding sequencing into companion diagnostic strategies.
- Diagnostic Laboratories:ISO 15189 compliance and FDA validation requirements create 12-18 month revenue conversion timelines from research to regulated clinical testing.
- Biotechnology Firms:Venture-backed startups concentrate in Cambridge and South San Francisco, prioritizing scalable cloud-native analysis over on-premise infrastructure.
Instrument placements concentrate in Academic Research Institutes; the fastest share gains belong to Pharmaceutical Companies.
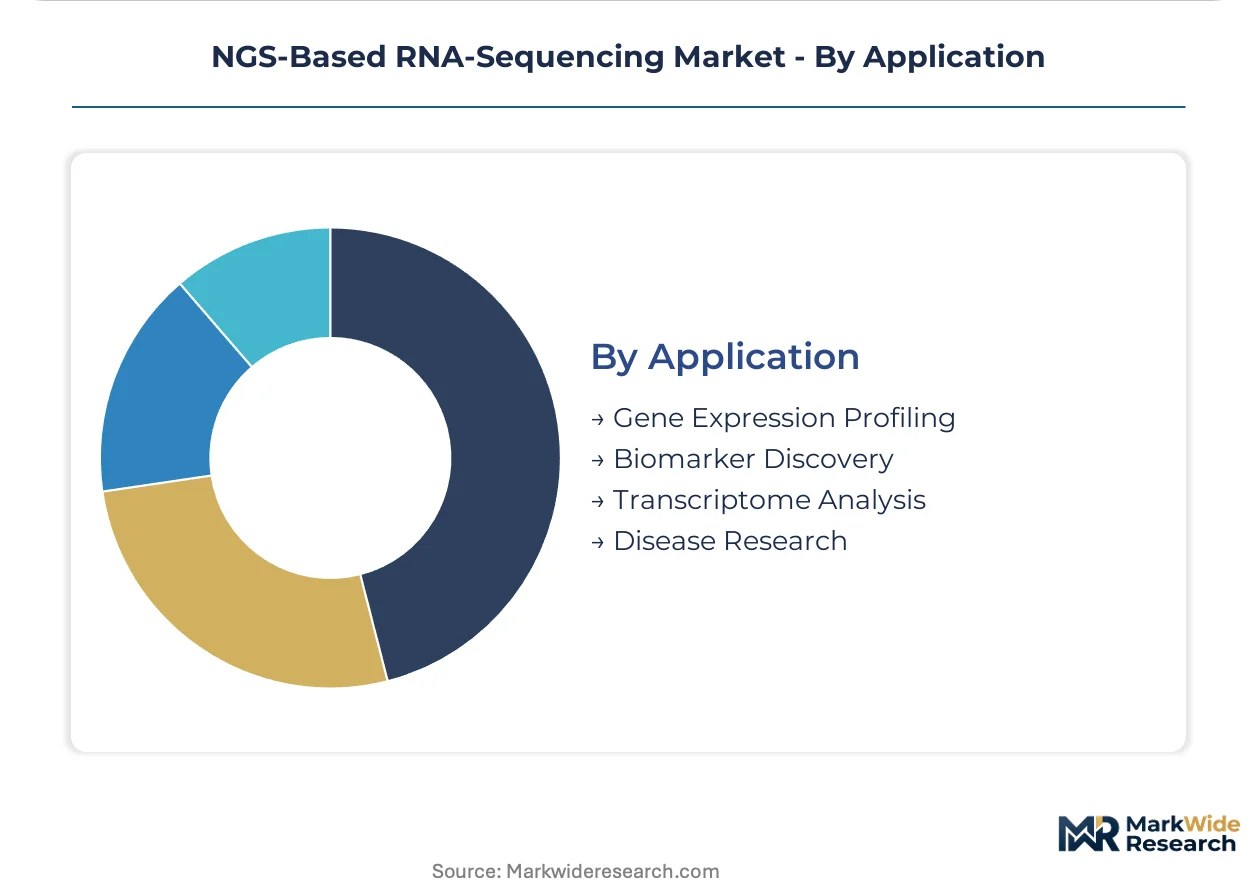
Application:
Maturity gradients separate established gene expression workflows from emerging spatial transcriptomics integration, with biomarker qualification pathways determining regulatory investment priorities.
- Gene Expression Profiling:Differential expression analysis remains the foundational application, with standardized protocols enabling cross-study comparability in population genomics initiatives.
- Biomarker Discovery:FDA Voluntary Exploratory Data Submissions program accelerates transcriptomic evidence integration into oncology drug approvals, front-loading clinical validation investment.
- Transcriptome Analysis:Splice-variant identification and fusion detection support therapeutic target validation, with short-read platforms fragmenting analysis across multiple assays.
- Disease Research:Infectious disease and neurodegeneration studies leverage single-cell resolution to map cellular response dynamics, particularly in NIH-funded consortia.
Protocol standardization centers on Gene Expression Profiling; the most rapid capability expansion belongs to Biomarker Discovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's biotech corridor and San Francisco's venture capital density create concentrated instrument pull-through ecosystems that anchor North American demand for sequencing infrastructure.
United States
FDA's Voluntary Exploratory Data Submissions program accelerates biomarker qualification timelines, embedding transcriptomic evidence directly into oncology drug approval pathways. The NIH's data management plan requirements now condition grant funding on sequencing infrastructure compliance. Academic medical centers in Boston and San Francisco drive NovaSeq and NextSeq placements through consolidated procurement consortia.
China
NMPA's innovation device pathway compresses local instrument registration timelines, redirecting vendor priorities toward domestic manufacturing partnerships. The dual carbon goals framework imposes energy efficiency standards on sequencing facility operations in Yangtze River Delta clusters. BGI Genomics anchors production scale in Shenzhen while Beijing-Tianjin-Hebei biotech parks absorb cloud-native analysis platform deployments.
Germany
EMA's In Vitro Diagnostic Regulation imposes clinical-grade performance documentation requirements on transcriptomic assays marketed for patient stratification. The CE marking process extends development timelines for pan-European commercialization of sequencing workflows. Heidelberg and Munich academic clusters concentrate single-cell platform adoption for immuno-oncology target discovery.
United Kingdom
Genomics England's population-scale sequencing initiatives sustain bulk RNA sequencing volume leadership in clinical trial cohort profiling. The Medicines and Healthcare products Regulatory Agency aligns with FDA guidance on companion diagnostic evidence standards. London's Francis Crick Institute and Cambridge biotech corridor generate dense consumable pull-through from precision medicine consortia.
Japan
PMDA's accelerated approval pathways for oncology therapeutics create synchronized demand for transcriptomic biomarker validation studies. METI's genomic medicine implementation plan funds core facility instrumentation in Osaka and Tokyo medical school networks. Kobe and Yokohama biotech clusters specialize in spatial transcriptomics integration for therapeutic target discovery.
NGS-Based RNA-Sequencing Market Competitive Environment
Top-tier vendors anchor instrument placement economics, while mid-tier specialists compete on workflow integration and geographic licensing arrangements. The market structures around three distinct player categories: integrated life science conglomerates with reagent-to-analysis portfolios, platform-focused sequencing specialists, and regional consumables manufacturers. Competitive moves concentrate on strategic partnerships for cloud-native pipeline development and capacity expansion into NMPA-fast-tracked manufacturing facilities.
Within the integrated systems tier, Illumina, Inc. and Thermo Fisher Scientific Inc. occupy positions that exemplify divergent strategic approaches to consumable lock-in and workflow automation. Oxford Nanopore Technologies anchors the amplification-free sequencing archetype, representing field-deployable platform differentiation. These three entities collectively illustrate how vendor concentration in flow cell manufacturing creates structural dependencies that reshape procurement negotiation dynamics across academic and pharmaceutical customer segments.
| Leading Market Players |
|---|
| Illumina, Inc. |
| Thermo Fisher Scientific Inc. |
| Oxford Nanopore Technologies |
| Agilent Technologies, Inc. |
| QIAGEN N.V. |
| Pacific Biosciences |
| 10x Genomics |
| PerkinElmer |
| BGI Genomics |
| Others |
Value Chain & Pricing Dynamics
Amplification-free sequencing chemistry transitions are compressing per-sample reagent costs while concentrating flow cell manufacturing among fewer vendors, simultaneously reshaping procurement economics and supplier bargaining power across academic and pharmaceutical buyer segments.
Pricing Analysis
Lead-time-driven pricing stratification rewards immediate availability with premium tiers while spot inventory trades at discounts. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and volume commitment, with ISO 15189-compliant clinical-grade kits commanding substantial markups over research-use-only alternatives. Pricing pressure stems from consolidated academic buying consortia negotiating multi-year consumable commitments. Pharmaceutical procurement teams exhibit lowest price sensitivity due to companion diagnostic timeline pressures, while resource-constrained academic labs drive aggressive cost-per-sample optimization.
Supply Chain Analysis
Specialized workforce availability in precision manufacturing hubs constrains flow cell and nanopore array production scaling in the United States, Singapore, and United Kingdom. Supply draws from high-purity silicon substrates, proprietary polymer chemistries, and rare-earth magnet assemblies for automated library preparation systems. Single-source vulnerability concentrates in flow cell coating technologies held by three vendors. Distribution runs through authorized distributors for capital equipment and direct-to-lab e-commerce portals for recurring reagent replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where FDA's evolving companion diagnostic guidance and EMA's In Vitro Diagnostic Regulation construct regulatory moats that favor incumbent players with validated quality management systems.
For Market Incumbents: Lock in consumable pull-through through multi-year reagent commitments bundled with instrument service contracts. Deepen backward integration into flow cell manufacturing to reduce batch variability exposure. Threaten margin compression from Oxford Nanopore's field-deployable platforms demands preemptive cloud-native bioinformatics investment. For New Entrants and Emerging Players: Cloud-native analysis pipelines offer technology-first wedge into mid-sized core facilities lacking computational infrastructure. White-space concentrates in China's NMPA-fast-tracked manufacturing partnerships and ISO 15189-compliant diagnostic laboratory services. Go-to-market through AWS and Google Cloud marketplace integrations bypasses traditional capital equipment sales cycles. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated life science conglomerates seeking reagent-to-analysis workflow consolidation. Long-term viability favors platform specialists with regulatory-compliant software stacks and captive consumable chemistry. Watch FDA biomarker qualification synchronization with oncology drug approvals as inflection signal for companion diagnostic valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA Voluntary Exploratory Data Submissions accelerates biomarker qualification for oncology drug pipelines. |
| Cloud-Native Platform Integration | AWS and Google Cloud containerized pipelines reduce on-premise compute capex for mid-scale operations. |
| Manufacturing Scale-Up | NMPA innovation device pathway redirects vendor priorities toward domestic Chinese production partnerships. |
| Strategic Partnership | Academic buying consortia negotiate multi-year consumable commitments for preferential pricing tiers. |
| Geographic Expansion | Boston and San Francisco biotech clusters anchor North American instrument placement density. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews with core facility directors, pharmaceutical regulatory affairs leads, diagnostic laboratory managers, and sequencing platform engineers. FDA 510(k) submissions, EMA CE marking databases, NIH grant award records, and academic procurement consortium contracts supplied validation benchmarks. Bottom-up instrument placement counts and top-down reagent revenue estimates underwent iterative triangulation.
Granularity-level modeling disaggregated volume and value across product type, technology tier, end-user category, and application area throughout the forecast period. CAGRs derived from segmented growth trajectory analysis incorporating single-cell platform adoption curves, bulk sequencing cost-per-sample decline rates, and software subscription expansion patterns. Forecast inputs included pharmaceutical pipeline biomarker qualification timelines and academic funding cycle volatility indices.
Several conditions sit outside the modeled scope, including unforeseen regulatory guidance revisions, supply chain disruptions from geopolitical trade restrictions, and technology substitution by emerging proteomics platforms. Forecasts reflect documented assumptions regarding instrument replacement cycles and reagent consumption intensity. Material deviation in FDA-EMA regulatory divergence or flow cell manufacturing concentration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Plant Genomics Market
Genomics
Global Genomics Market
Genomics
Global NGS Sample Preparation Market
Genomics
Global Blockchain in Genomic Data Management Market
Genomics
Predisposition Biomarkers Market
Genomics
Europe Hereditary Cancer Testing Market
Genomics
Global Single-Cell Genome Sequencing Market
Genomics
Pharmacogenomics Technology Market
Genomics
Global Metagenomic Sequencing Market
Genomics
Gene Sequencing Market
Genomics
Next Generation Sequencing Market
Genomics
Whole Exome Sequencing (WES) Market
Genomics
Next Generation Genomics Market
Genomics
Microbiome Sequencing Market
Genomics
Europe Genetic Testing Market
Genomics
Europe Cancer Biomarkers Market