
 Cytogenetic Systems Market | 2026-2036
Cytogenetic Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Cytogenetic Systems Market Analysis
Digital imaging sensors are recalibrating cost structures across fluorescence microscopy platforms. Agilent Technologies leverages its chromatography heritage to anchor reagent-supply contracts in clinical cytogenetics. MetaSystems competes through automated metaphase scanning systems that reduce technologist labor per case. PerkinElmer Inc extends its diagnostics footprint into prenatal screening workflows across North American hospital networks.
Cytogenetic systems comprise instruments, consumables, and software for visualizing chromosomal structure and detecting genetic abnormalities through techniques such as fluorescence in situ hybridization (FISH) with probe hybridization temperatures typically held at 37°C overnight. These platforms serve diagnostic laboratories identifying aneuploidies, translocations, and microdeletions in prenatal, oncological, and constitutional testing. Karyotyping remains the workhorse modality in hospital cytogenetics departments, though next generation sequencing is capturing the fastest expansion in oncology panels where resolution demands exceed optical microscopy limits. Research laboratories dominate instrument placement volume, while diagnostics centers generate the highest consumable pull-through per installed system.
The FDA regulates cytogenetic devices under 21 CFR 862 with Class II premarket notification requirements, while the EU Medical Device Regulation (MDR) imposes stricter clinical evidence standards for in vitro diagnostic compatibility. ISO 15189 accreditation shapes laboratory purchasing criteria for systems that integrate into quality-managed workflows. Stakeholders must weigh capital deployment between incremental automation of established karyotyping and the interoperability demands of sequencing-cytogenetics hybrid platforms.
Market Dynamics
The cytogenetic systems market pivots on the tension between optical microscopy automation and next-generation sequencing displacement, with clinical laboratories recalibrating capital allocation between established karyotyping workflows and hybrid cytogenetic-sequencing platforms.
Growth Catalysts
- FDA Class II Premarket Notification:The 21 CFR 862 framework elevates quality benchmarks for cytogenetic devices, compelling laboratories to upgrade instrumentation and expand compliant testing capacity.
- Oncology Diagnostics Expansion:Hospital-based cancer centers are scaling automated metaphase scanning to handle rising specimen volumes from solid tumor and hematological malignancy workups.
- Fluorescence In Situ Hybridization:FISH probe technologies operating at standardized 37°C hybridization protocols anchor consumable pull-through in prenatal and constitutional testing segments.
Market Restraints
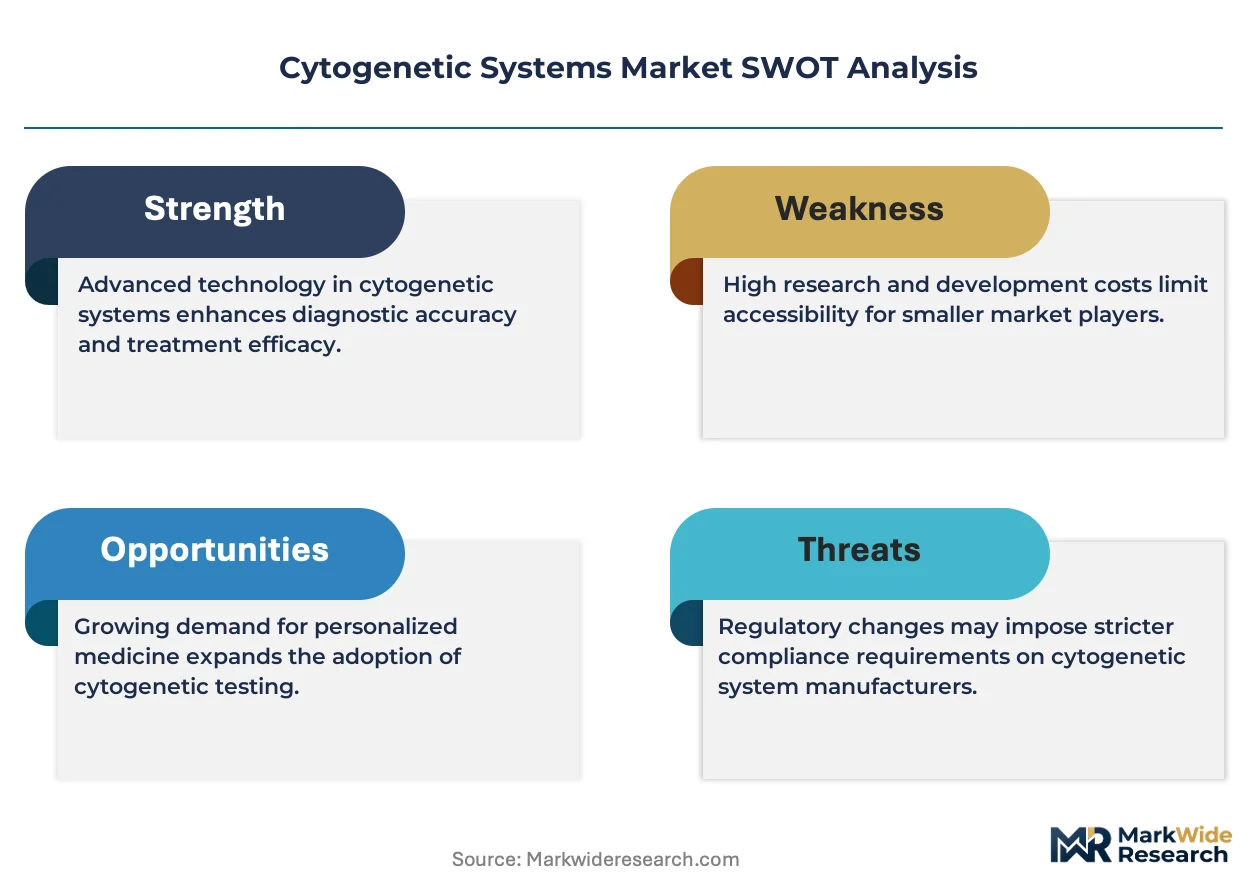
- Capital Equipment Intensity:Automated karyotyping platforms and high-resolution imaging systems demand substantial upfront investment, constraining mid-tier laboratory expansion.
- Reagent Supply Concentration:Specialty probe manufacturers and fluorescent dye suppliers concentrate in North American and Western European production clusters, creating geographic dependency.
- Resolution Ceiling:Optical microscopy techniques face inherent physical limits in detecting submicroscopic copy number variations, ceding ground to sequencing-based alternatives in complex oncology cases.
Strategic Opportunities
- India Diagnostic Laboratory Networks:Private hospital chains and reference laboratories in Mumbai and Delhi are building cytogenetics capacity to serve domestic prenatal screening demand.
- Cytogenetics-Sequencing Convergence:Hybrid platforms integrating automated imaging with targeted NGS panels enable laboratories to consolidate workflows and capture both structural and sequence-level abnormalities.
- EU Medical Device Regulation:The MDR's stricter clinical evidence requirements for in vitro diagnostic compatibility create first-mover advantages for manufacturers with robust technical documentation.
Industry Challenges
- Cytogenetic Technologist Shortage:Specialized training in chromosome analysis and FISH interpretation requires years of apprenticeship, limiting laboratory throughput expansion.
- ISO 15189 Accreditation Timelines:Quality management system certification for cytogenetic testing extends procurement cycles and delays instrument deployment in regulated markets.
- Legacy System Interoperability:Automated imaging platforms must interface with existing laboratory information systems and hospital electronic health records, complicating integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cytogenetic Systems Market |
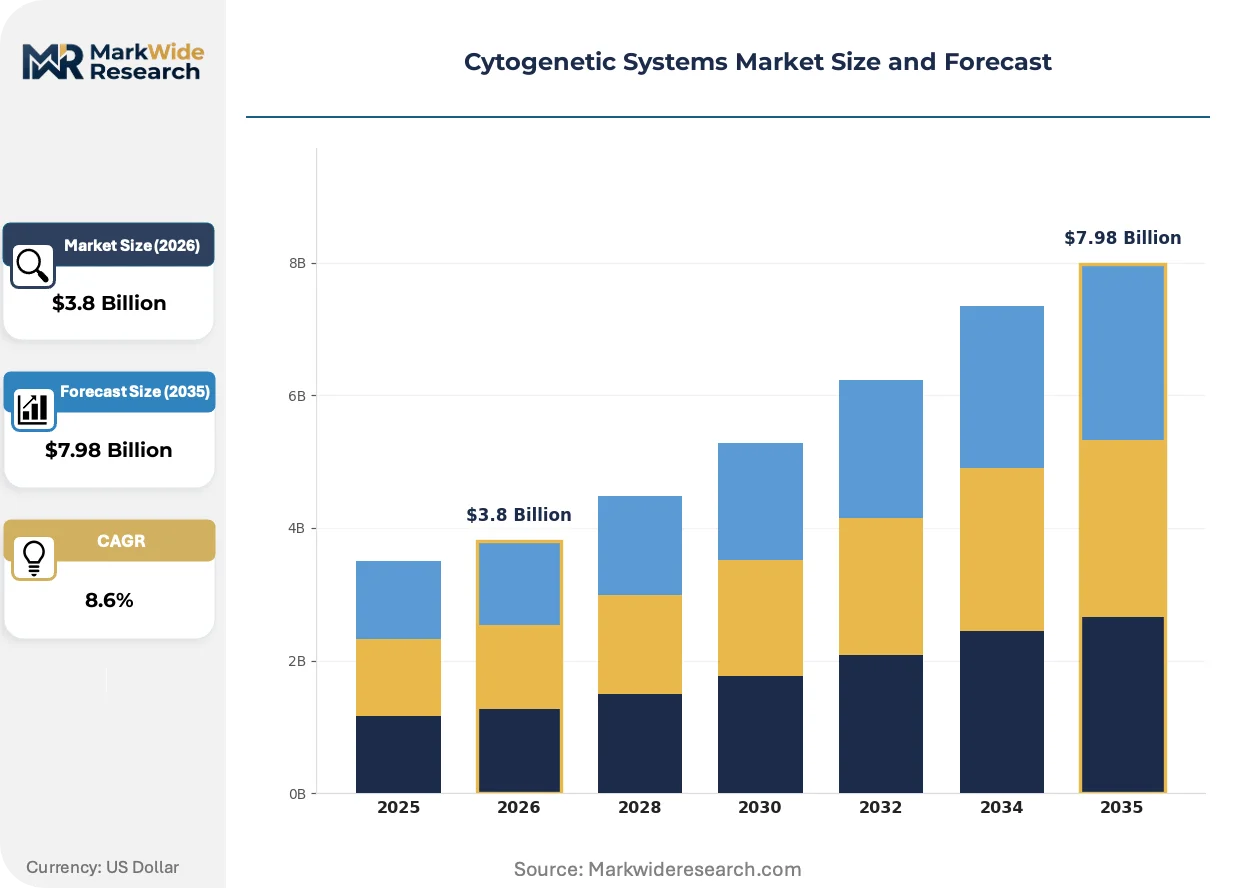
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluorescence In Situ Hybridization, Chromosomal Abnormality Testing, Karyotyping, Next Generation Sequencing End User: Research Laboratories, Hospitals, Diagnostics Centers, Academic Institutions Technology: Microarray Analysis, Polymerase Chain Reaction, Sequencing Technology, Digital Imaging Application: Oncology, Genetic Disorders, Prenatal Testing, Infectious Diseases |
| Companies Covered | Agilent Technologies, MetaSystems, ADS Biotec Inc, Laboratory Imaging s.r.o, Genial Genetics, Leica Biosystems Nussloch GmbH, Applied Spectral Imaging, PerkinElmer Inc, Cytocell Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cytogenetic Systems Market Emerging Trajectories
Digital imaging sensors and artificial intelligence classification algorithms are compressing analysis timelines and reshaping labor allocation across clinical cytogenetics departments worldwide.
High-resolution CMOS and sCMOS sensors paired with advanced image processing pipelines are rewriting cost structures in fluorescence microscopy. Academic medical centers and large reference laboratories in the United States are adopting these sensors to replace legacy CCD-based systems. The technology is enabling same-day karyotype reporting for urgent prenatal and oncology specimens, compressing competitive differentiation around turnaround time rather than resolution alone.
The EU Medical Device Regulation's 2017/746 framework is tightening clinical evidence requirements for cytogenetic analyzers marketed as in vitro diagnostic devices. Manufacturers must now generate performance evaluation data under notified body supervision before CE marking. European hospital laboratories are prioritizing suppliers with established MDR technical files, accelerating vendor consolidation toward established instrumentation firms.
Consolidated procurement by multi-site health systems is displacing decentralized purchasing in North American hospital networks. Integrated delivery networks in California, Texas, and New York are negotiating enterprise-wide cytogenetics contracts that bundle instruments, reagents, and software maintenance. This concentration shifts vendor relationships toward long-term service agreements and away from transactional equipment sales, with pricing transparency becoming a decisive selection criterion.
Cytogenetic Systems Market Segmentation
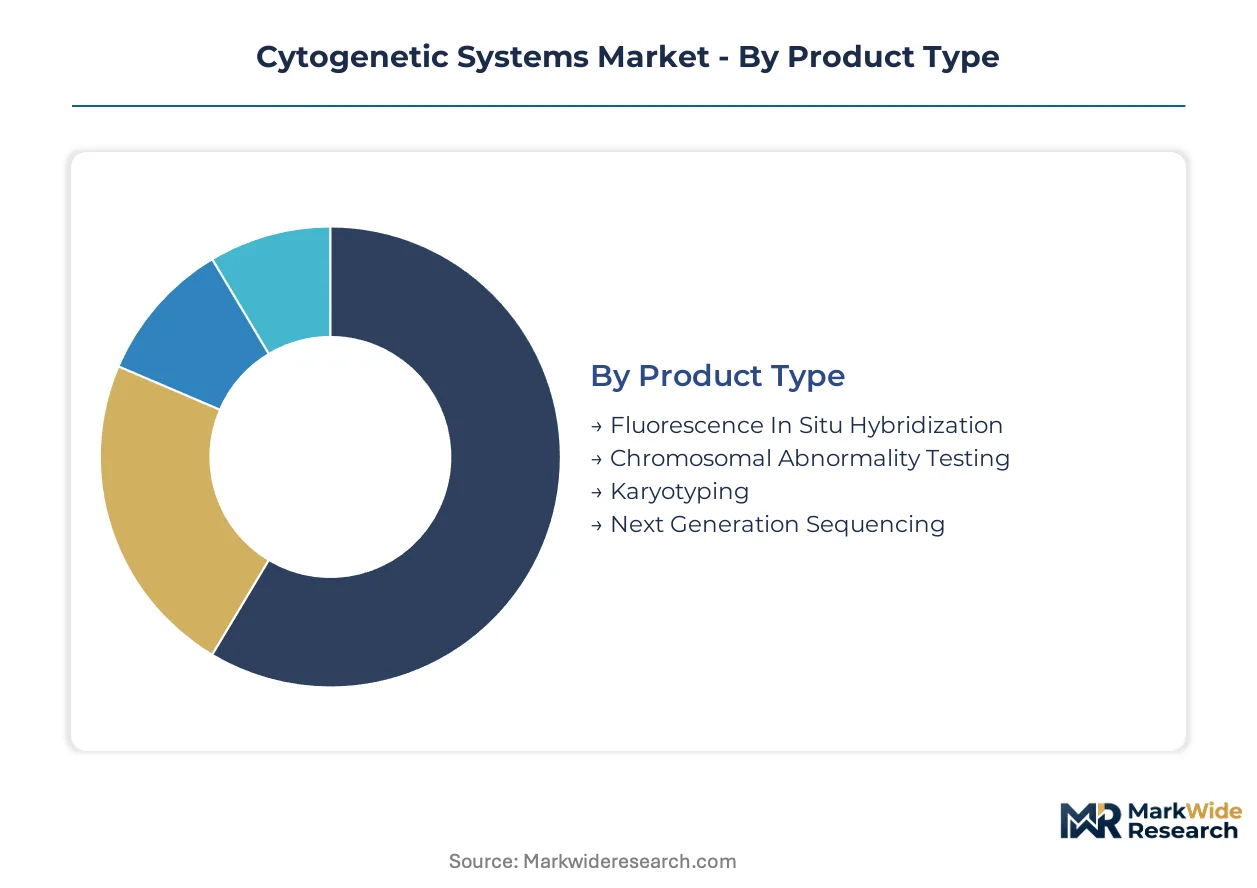
Cytogenetic systems fragment across four intersecting dimensions that shape procurement patterns and margin structures. Product type determines capital intensity and reagent pull-through. End user concentration dictates service bundling requirements and compliance tiers.
Product Type:
Standardization dominates fluorescence-based workflows while next-generation platforms demand extensive customization for oncology integration.
- Fluorescence In Situ Hybridization:Probe hybridization protocols at 37°C anchor consumable economics in prenatal and constitutional testing laboratories. United States reference laboratories drive installed base expansion through automated slide processing systems.
- Karyotyping:G-banded chromosome analysis remains the procedural default in hospital cytogenetics departments worldwide. Clinical laboratories in the United States consolidate high-throughput capacity around automated metaphase scanners that compress technologist labor per case.
- Chromosomal Abnormality Testing:Microdeletion and subtelomere panels serve pediatric genetics units with standardized probe sets.
- Next Generation Sequencing:Hybrid cytogenetic-sequencing platforms capture complex oncology cases where optical resolution limits apply.
Most installed capacity flows through Karyotyping. Expansion is steepest in Next Generation Sequencing.
End User:
Volume concentration separates research instrument placement from diagnostic consumable velocity.
- Research Laboratories:Academic medical centers and government institutes drive instrument shipment volume through grant-funded capital cycles. Specimen throughput per system stays lower than clinical settings, extending depreciation timelines.
- Diagnostics Centers:Commercial reference laboratories generate the highest reagent pull-through per installed platform through standardized FISH and karyotyping workflows. United States-based networks like LabCorp and Quest negotiate enterprise consumable contracts.
- Hospitals:In-house cytogenetics departments prioritize turnaround time for urgent prenatal and oncology specimens.
- Academic Institutions:Training programs and research consortia sustain demand for manual karyotyping workstations.
Diagnostics Centers command the steepest consumable velocity. Research Laboratories dominate absolute instrument placements.
Technology:
Resolution thresholds and automation readiness separate mature optical methods from emerging computational approaches.
- Digital Imaging:High-resolution CMOS and sCMOS sensors paired with AI classification algorithms compress analysis timelines in United States academic medical centers. Same-day karyotype reporting is becoming competitive standard for urgent specimens.
- Sequencing Technology:Targeted NGS panels capture copy number variations below optical microscopy detection limits in solid tumor workups. Integration with automated imaging platforms enables consolidated structural and sequence-level analysis.
- Microarray Analysis:Comparative genomic hybridization serves constitutional testing with standardized probe coverage.
- Polymerase Chain Reaction:qPCR-based aneuploidy screening anchors cost-sensitive prenatal testing segments.
Digital Imaging claims the fastest technology transition. Sequencing Technology is gaining share fastest in oncology applications.
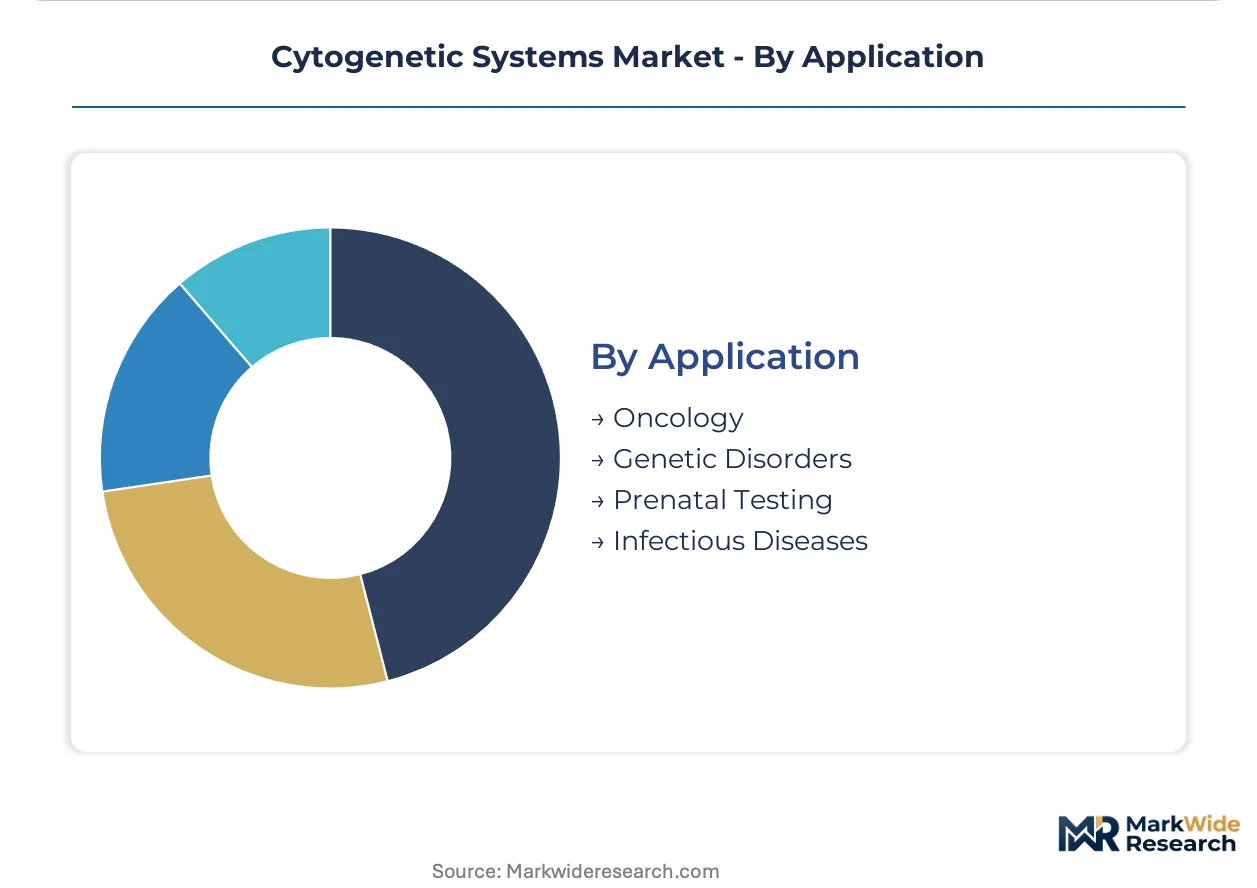
Application:
Clinical urgency and reimbursement density differentiate routine screening from complex malignancy workups.
- Oncology:Hematological malignancy and solid tumor cytogenetics demand highest resolution platforms with M-FISH and CGH capabilities. United States cancer centers automate metaphase scanning to handle rising specimen volumes from precision medicine programs.
- Prenatal Testing:Amniocentesis and chorionic villus sampling workflows sustain FISH probe consumption in maternal-fetal medicine units. Non-invasive prenatal screening displacement is compressing invasive procedure volumes in some markets.
- Genetic Disorders:Pediatric genetics units deploy karyotyping and microarray analysis for developmental delay evaluations.
- Infectious Diseases:Pathogen identification through FISH remains a niche application with limited commercial penetration.
Oncology concentrates the highest-value testing. Prenatal Testing sustains the broadest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States reference laboratories concentrate high-throughput cytogenetics capacity in Boston, San Francisco, and Research Triangle Park clusters. Germany and Switzerland anchor European instrument manufacturing and precision optics supply chains. Japan and South Korea drive sensor technology advancement for digital imaging platforms.
United States
FDA Class II premarket notification requirements under 21 CFR 862 compel laboratory upgrades to compliant instrumentation. Consolidated procurement by integrated delivery networks in California, Texas, and New York bundles instruments, reagents, and software maintenance into enterprise contracts. Academic medical centers in Boston and San Francisco adopt high-resolution CMOS sensors for same-day karyotype reporting.
Germany
EU Medical Device Regulation 2017/746 imposes stricter clinical evidence standards for in vitro diagnostic compatibility. Leica Biosystems Nussloch GmbH anchors precision optics manufacturing in Baden-Württemberg. Hospital laboratories in Munich and Heidelberg prioritize suppliers with established MDR technical files.
Switzerland
Swissmedic oversight aligns with EU MDR standards for cytogenetic analyzer market access. Precision engineering clusters in Basel and Zurich sustain optical component supply chains for fluorescence microscopy platforms. Research consortia at ETH Zurich and University of Geneva drive automated imaging algorithm development.
Japan
METI industrial policy supports domestic production of high-resolution imaging sensors for medical applications. PMDA regulatory timelines shape instrument registration strategies for multinational manufacturers. Tokyo and Osaka metropolitan areas concentrate hospital cytogenetics departments handling prenatal and oncology specimen volumes.
India
CDSCO medical device regulations tighten quality benchmarks for imported cytogenetic instrumentation. Private hospital chains in Mumbai and Delhi build cytogenetics capacity to serve domestic prenatal screening demand. Diagnostic laboratory networks in Bengaluru and Hyderabad negotiate reagent-supply contracts with global manufacturers.
Cytogenetic Systems Market Vendor Landscape
Global majors compete with regional champions across instrument manufacturing, reagent supply, and software integration dimensions. The vendor base stratifies into three tiers: diversified life science conglomerates with chromatography and diagnostics heritage, specialized microscopy and imaging firms with automated scanning capabilities, and niche probe manufacturers with FISH reagent expertise. Dominant competitive moves include strategic partnerships between instrument makers and reagent suppliers, plus technology licensing agreements for AI-powered image classification algorithms.
Within the diversified conglomerate tier, Agilent Technologies and PerkinElmer Inc occupy positions anchored by chromatography and diagnostics heritage respectively. MetaSystems exemplifies the specialized imaging archetype with automated metaphase scanning systems. Leica Biosystems Nussloch GmbH represents precision optics manufacturing concentration in German industrial clusters. These three archetypes—conglomerate-anchored, imaging-specialized, and optics-manufacturing—define competitive positioning across procurement cycles in academic medical centers and commercial reference laboratories.
| Leading Market Players |
|---|
| Agilent Technologies |
| MetaSystems |
| ADS Biotec Inc |
| Laboratory Imaging s.r.o |
| Genial Genetics |
| Leica Biosystems Nussloch GmbH |
| Applied Spectral Imaging |
| PerkinElmer Inc |
| Cytocell Ltd |
| Others |
Supply Flow & Price Mechanics
Rare earth oxide price indices for europium and terbium, critical for high-performance fluorescent dyes in FISH probe manufacturing, cascade through three pricing tiers from research-grade bulk reagents to GMP-certified diagnostic consumables. United States reference laboratories absorb premium markups for FDA-compliant probe sets while mid-tier hospital cytogenetics departments face cost compression from automated platform depreciation schedules.
Pricing Analysis
Input-cost pass-through from specialty fluorescent dyes and precision optical components stratifies pricing across premium, standard, and economy certification levels. Price differentiation hinges on FDA Class II premarket notification status and ISO 15189 accreditation tier, with MDR-compliant systems commanding 15-30% premiums in European procurement cycles. Pricing pressure stems from consolidated enterprise contracts at integrated delivery networks that bundle instruments, reagents, and software maintenance into multi-year agreements. Academic medical centers exhibit lowest price sensitivity due to grant-funded capital cycles, while private diagnostic laboratory networks in emerging markets face acute cost constraints.
Supply Chain Analysis
Domestic-content mandates under India's CDSCO medical device regulations and China's NMPA import substitution policies are reshaping sourcing strategies for multinational manufacturers. Supply concentration centers on Germany and Switzerland for precision optics, Japan for CMOS sensor fabrication, and the United States for specialty probe synthesis. The supply chain draws from rare earth elements for fluorescent dyes, high-purity optical glass for microscope objectives, and semiconductor-grade silicon for imaging sensors. Single-source vulnerability in specialty FISH probe manufacturing creates bottleneck exposure. Distribution runs through direct sales forces for enterprise hospital networks and specialized distributors for mid-tier clinical laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cytogenetic systems market represents a late-cycle quality story where laboratory purchasing committees prioritize MDR technical file completeness and FDA 510(k) clearance depth over raw specification metrics. Demand is shifting toward hybrid cytogenetic-sequencing platforms that consolidate structural and sequence-level analysis workflows.
For Market Incumbents: Anticipate displacement pressure from targeted NGS panels in complex oncology cases by deepening backward integration into fluorescent dye manufacturing and securing captive supply of rare earth elements for probe production. Accelerate MDR technical file investments to capture first-mover advantages as European hospital laboratories consolidate procurement toward compliant vendors. Prioritize AI-powered image classification algorithm development to compress analysis timelines and defend against sequencing-based substitutes. For New Entrants and Emerging Players: Launch via reagent-supply partnerships with established instrument manufacturers to bypass capital-intensive platform development, targeting India's private hospital chains in Mumbai and Delhi where cytogenetics capacity expansion outpaces domestic manufacturing capability. Focus white-space capture on automated slide processing systems for mid-tier diagnostic laboratories seeking ISO 15189 accreditation without enterprise-scale procurement leverage. Emphasize consumable pull-through economics over instrument margin in commercial negotiations. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized imaging firms possessing automated metaphase scanning technology and established AI classification pipelines. Long-term viability over the next decade rests on convergence positioning between optical microscopy and sequencing workflows rather than pure-play modality defense. Monitor FDA premarket notification submission volumes for hybrid cytogenetic-sequencing platforms as the critical inflection signal for technology displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical File Investment | European hospital laboratories prioritize suppliers with established notified body supervision records. |
| Hybrid Platform Development | Consolidated cytogenetic-sequencing workflows capture both structural and sequence-level abnormalities. |
| AI Image Classification Licensing | Academic medical centers adopt algorithm-driven analysis to enable same-day karyotype reporting. |
| Reagent Supply Contract Bundling | Integrated delivery networks in California and Texas negotiate enterprise-wide instrument-reagent-service agreements. |
| India Distribution Partnership | CDSCO regulatory alignment creates channel access for private hospital chains in Mumbai and Delhi. |
Methodological Framework
Coverage spans the United States, Germany, Switzerland, Japan, and India, with primary inputs from each market's laboratory stakeholders and regulatory environment. The analysis combines structured interviews with cytogenetic technologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation from FDA 510(k) databases, EU MDR notified body documentation, CDSCO medical device registrations, and hospital procurement contract disclosures. Bottom-up instrument shipment tracking and top-down diagnostic testing volume estimates provide cross-verification.
Granularity-level modeling disaggregates revenue across fluorescence in situ hybridization, karyotyping, chromosomal abnormality testing, and next-generation sequencing product types, with further subdivision by research laboratory, diagnostics center, hospital, and academic institution end users. Technology dimensions include digital imaging, sequencing technology, microarray analysis, and polymerase chain reaction. Application segmentation covers oncology, prenatal testing, genetic disorders, and infectious diseases. CAGRs derive from installed base expansion rates and consumable pull-through per system across the projection horizon. Forecast inputs incorporate regulatory approval timelines, ISO 15189 accreditation penetration, and hybrid platform adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of accelerated NGS displacement in oncology or prolonged MDR transition timelines in European markets. The analysis reflects assumptions regarding laboratory capital expenditure cycles, reagent supply contract renewal rates, and technologist workforce availability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
United States DNA Sequencing Products Market
Genomics
Whole Genome Amplification Market
Genomics
Prenatal Genetic Testing Market
Genomics
Genetic Testing Panels Market
Genomics
Animal Genetics Market
Genomics
AI in Genomics Market
Genomics
Global Blockchain in Genomic Data Management Market
Genomics
Hereditary Testing Market
Genomics
Next Generation Molecular Assay Market
Genomics
Global Genotyping Assay Market
Genomics
Kearns-Sayre Syndrome Market
Genomics
Latin America Next Generation Sequencing Market
Genomics
Whole Exome Sequencing (WES) Market
Genomics
Molecular Biomarkers for Cancer Detection Market
Genomics
DNA Diagnostics Market
Genomics
Mitochondrial DNA Market