
 Sequencing Electrophoresis Systems Market | 2026-2036
Sequencing Electrophoresis Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Sequencing Electrophoresis Systems Market Analytics
China's precision medicine infrastructure build-out is reconfiguring regional supply dynamics for sequencing electrophoresis hardware. Thermo Fisher Scientific leverages its vertically integrated reagent-instrument ecosystem to sustain pricing power in high-throughput installations. Bio-Rad Laboratories anchors its position through specialized capillary electrophoresis platforms that dominate forensic and clinical validation labs. Agilent Technologies competes on measurement precision and software analytics integration across genomics workflows.
Sequencing electrophoresis systems separate nucleic acid fragments by size and charge using capillary or gel matrices, with resolution thresholds reaching single-base discrimination for Sanger sequencing confirmation and quality control. These instruments serve as foundational tools for genomics research, clinical diagnostics, and pharmaceutical development requiring validated nucleic acid analysis. Capillary electrophoresis instruments command premium positioning due to their automation compatibility and regulatory acceptance in clinical settings, while microfluidic devices represent the fastest-expanding segment as labs miniaturize workflows and reduce reagent consumption. Automated systems concentrate margin pools through service contracts and consumable pull-through, though gel electrophoresis retains volume dominance in academic and entry-level research settings.
The FDA enforces quality system regulation and premarket notification requirements for clinical diagnostic electrophoresis platforms, while ISO 13485 and IEC 61010-1 standards govern design controls and electrical safety for international market access. The European Medicines Agency and In Vitro Diagnostic Regulation framework impose additional conformity assessment burdens for CE-marked clinical deployment. Stakeholders must monitor evolving harmonization between FDA breakthrough device pathways and EMA diagnostic performance standards when prioritizing product development portfolios and geographic registration sequencing.
Market Dynamics
Pharmaceutical companies are consolidating nucleic acid validation workflows into automated capillary platforms, compressing procurement cycles and elevating service contract attach rates as the dominant margin mechanism.
Growth Catalysts
- Clinical Laboratory Improvement Amendments:The FDA's CLIA complexity categorization creates regulatory pull-through for moderate-complexity electrophoresis systems in hospital-based molecular diagnostics labs.
- Forensic DNA databasing:Federal and state criminal justice programs in the United States fund capillary electrophoresis infrastructure for CODIS-compatible short tandem repeat analysis.
- Reagent-instrument bundling:Consumable pull-through economics lock research institutions into recurring revenue relationships with installed base vendors.
Market Restraints
- Fluorescent dye cost volatility:Rhodamine and FAM derivative supply concentration in Chinese chemical manufacturing creates input price instability for detection chemistry.
- Capillary array single-sourcing:Fused silica capillary supply concentrates among three German and Japanese specialty glass manufacturers, exposing buyers to allocation risk.
- Next-generation sequencing substitution:Illumina and MGI platforms displace Sanger confirmation workflows in high-volume genotyping applications, compressing addressable market for traditional electrophoresis.
Strategic Opportunities
- India's biotech manufacturing build-out:Contract research organizations in Hyderabad and Bengaluru require validated quality control systems for biosimilar nucleic acid characterization.
- Microfluidic electrophoresis convergence:Lab-on-chip integration with digital PCR workflows opens point-of-care diagnostic applications previously inaccessible to capillary formats.
- EU IVDR transition tailwind:The In Vitro Diagnostic Regulation's 2027 enforcement deadline accelerates replacement of legacy gel systems with CE-IVD certified automated platforms in European clinical labs.
Industry Challenges
- Electrophoresis method development expertise:Universities have reduced analytical chemistry training programs, narrowing the talent pool for assay optimization and troubleshooting.
- ISO 13485 certification timelines:Design history file compilation and notified body queue delays extend product registration cycles by 14-18 months for clinical diagnostic instruments.
- Legacy data system integration:Laboratory information management systems in pharmaceutical quality control environments require custom middleware for capillary electrophoresis data capture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sequencing Electrophoresis Systems Market |
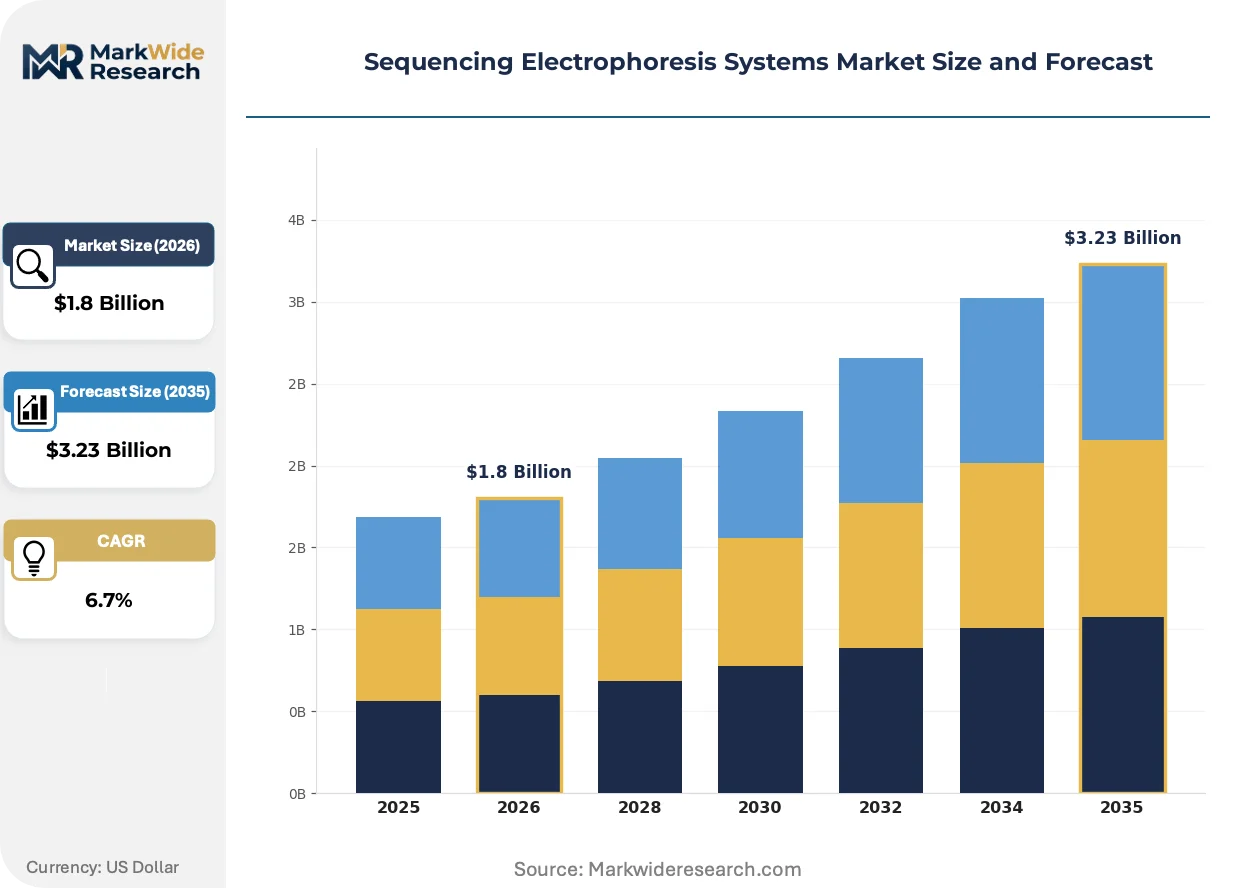
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capillary Electrophoresis, Gel Electrophoresis, Microfluidic Devices, Automated Systems End User: Research Laboratories, Diagnostic Centers, Academic Institutions, Pharmaceutical Companies Technology: DNA Sequencing, RNA Sequencing, Single-Cell Sequencing, Next-Generation Sequencing Application: Genomics, Proteomics, Drug Discovery, Forensic Analysis |
| Companies Covered | Thermo Fisher Scientific, Bio-Rad Laboratories, Agilent Technologies, Merck KGaA, QIAGEN, PerkinElmer, Danaher Corporation, GE Healthcare, Lonza Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sequencing Electrophoresis Systems Market Evolving Landscape
Workflow miniaturization and regulatory harmonization are compressing instrument footprints while expanding deployment settings beyond traditional core facilities into distributed testing environments.
Chip-based electrophoresis systems integrate sample preparation, separation, and detection onto polymer substrates, reducing reagent volumes by two orders of magnitude. Academic labs and field-based research stations adopt these platforms for rapid quality control checks. Benchtop capillary systems are rendering obsolete for low-throughput applications where portability and disposability outweigh resolution requirements.
The European Union's In Vitro Diagnostic Regulation imposes stricter clinical evidence requirements and post-market surveillance obligations on electrophoresis platforms deployed in diagnostic settings. Manufacturers must maintain technical documentation and performance monitoring systems that exceed predecessor directives. Small instrument vendors face consolidation pressure as notified body capacity constraints extend conformity assessment timelines.
Research institutions unbundle capital acquisition from service contracts, negotiating separate procurement for installation qualification, operational qualification, and annual maintenance. Independent service organizations capture aftermarket revenue previously retained by original equipment manufacturers. This pattern concentrates in United States academic medical centers with dedicated metrology and validation groups.
Sequencing Electrophoresis Systems Market Segmentation
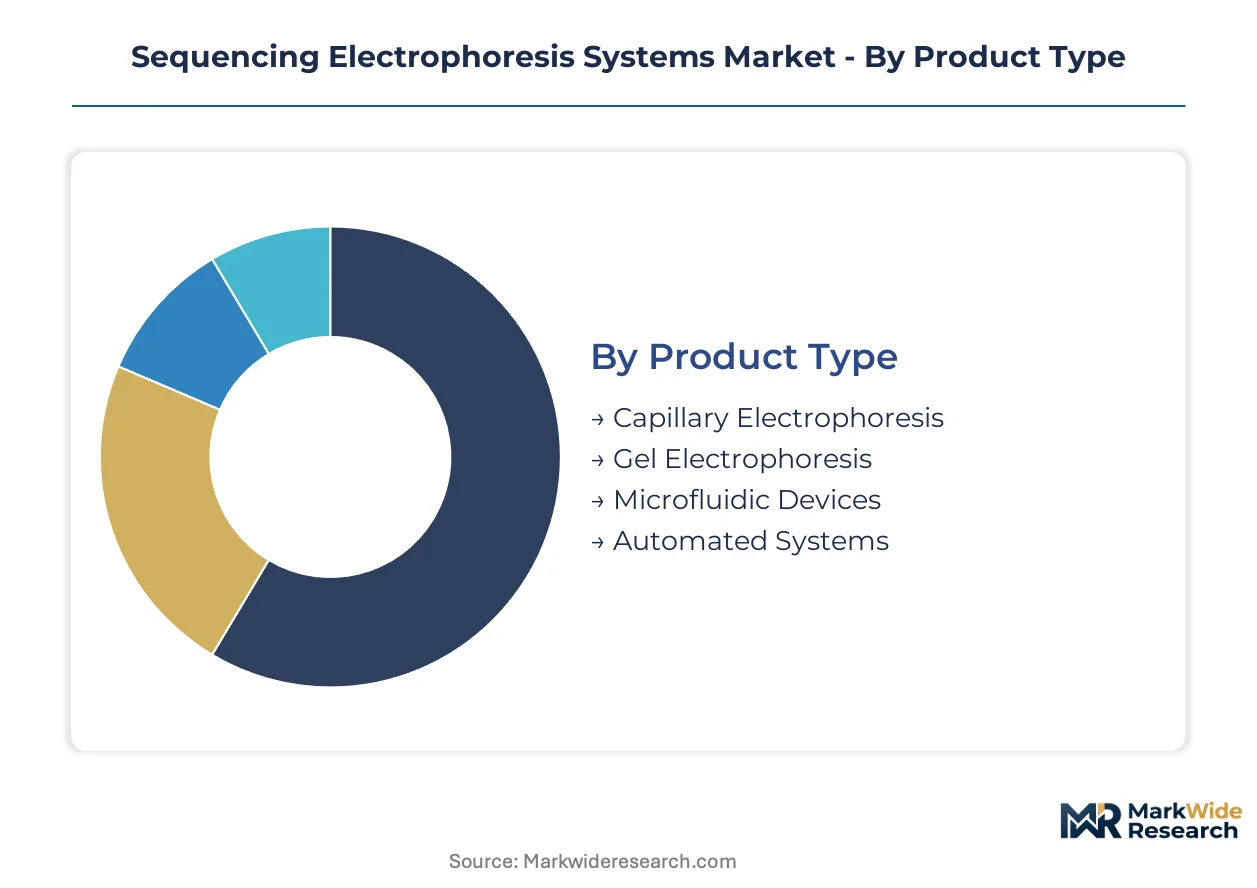
Sequencing electrophoresis systems fragment across multiple technical and commercial dimensions, with product architecture and end-use workflow requirements determining pricing tiers and service contract structures. Understanding these segment boundaries clarifies where automation investments concentrate versus where legacy formats retain viability.
Product Type:
Capillary and gel formats anchor opposite ends of the automation spectrum, with emerging microfluidic architectures disrupting throughput economics at the mid-range.
- Capillary Electrophoresis:Fused silica arrays with fluorescence detection achieve single-base resolution for Sanger confirmation and forensic STR analysis. Pharmaceutical quality control labs in the United States and Germany drive replacement cycles as ISO 13485-certified platforms displace older open-gel systems.
- Gel Electrophoresis:Slab gel formats with intercalating dyes remain the entry-level standard for educational training and basic PCR product verification. Academic institutions in India and Brazil sustain volume demand where capital constraints preclude automated alternatives.
- Microfluidic Devices:Polymer chip substrates integrate separation channels with embedded electrodes, cutting reagent volumes by 99% versus capillary formats.
- Automated Systems:Robotic sample handling with LIMS integration commands premium positioning in high-throughput clinical diagnostic environments.
The dominant share belongs to Capillary Electrophoresis, while Microfluidic Devices are gaining share fastest through point-of-care diagnostic applications.
End User:
Procurement authority and validation requirements diverge sharply between regulated pharmaceutical environments and grant-funded academic settings.
- Research Laboratories:Core facilities at institutions like the Broad Institute and Sanger Centre consolidate multi-user access to high-capillary-count systems. Funding agency mandates for data reproducibility are accelerating instrument replacement cycles.
- Diagnostic Centers:Hospital-based molecular pathology labs require CLIA-compliant moderate-complexity platforms with locked assay protocols. The FDA's quality system regulation shapes vendor selection criteria and service contract negotiations.
- Academic Institutions:Undergraduate teaching labs and individual investigator grants favor lower-throughput gel and entry-level capillary systems.
- Pharmaceutical Companies:Quality control and biosimilar characterization workflows demand validated systems with complete design history files.
Pharmaceutical Companies command the highest average selling prices, though Diagnostic Centers are expanding procurement most quickly through hospital consolidation.
Technology:
Sequencing chemistry type determines resolution requirements and detection modality, with workflow integration needs favoring multi-technology platform investments.
- DNA Sequencing:Fragment analysis and Sanger confirmation remain the foundational application, with capillary electrophoresis serving as the gold standard for variant validation. Clinical labs in the United States processing hereditary cancer panels maintain installed bases of 96-capillary systems.
- RNA Sequencing:Quality control for library preparation and fragment size distribution requires high-sensitivity detection of low-concentration samples. Transcriptomics core facilities are upgrading to laser-induced fluorescence systems with extended dynamic range.
- Single-Cell Sequencing:Extremely low input volumes from individual cells push detection limits, favoring microfluidic integration with digital PCR.
- Next-Generation Sequencing:Fragment analyzer validation of library insert sizes precedes Illumina and MGI platform loading, creating companion diagnostic demand for electrophoresis systems.
DNA Sequencing retains the largest installed base, while Single-Cell Sequencing is climbing the fastest as spatial transcriptomics workflows proliferate.
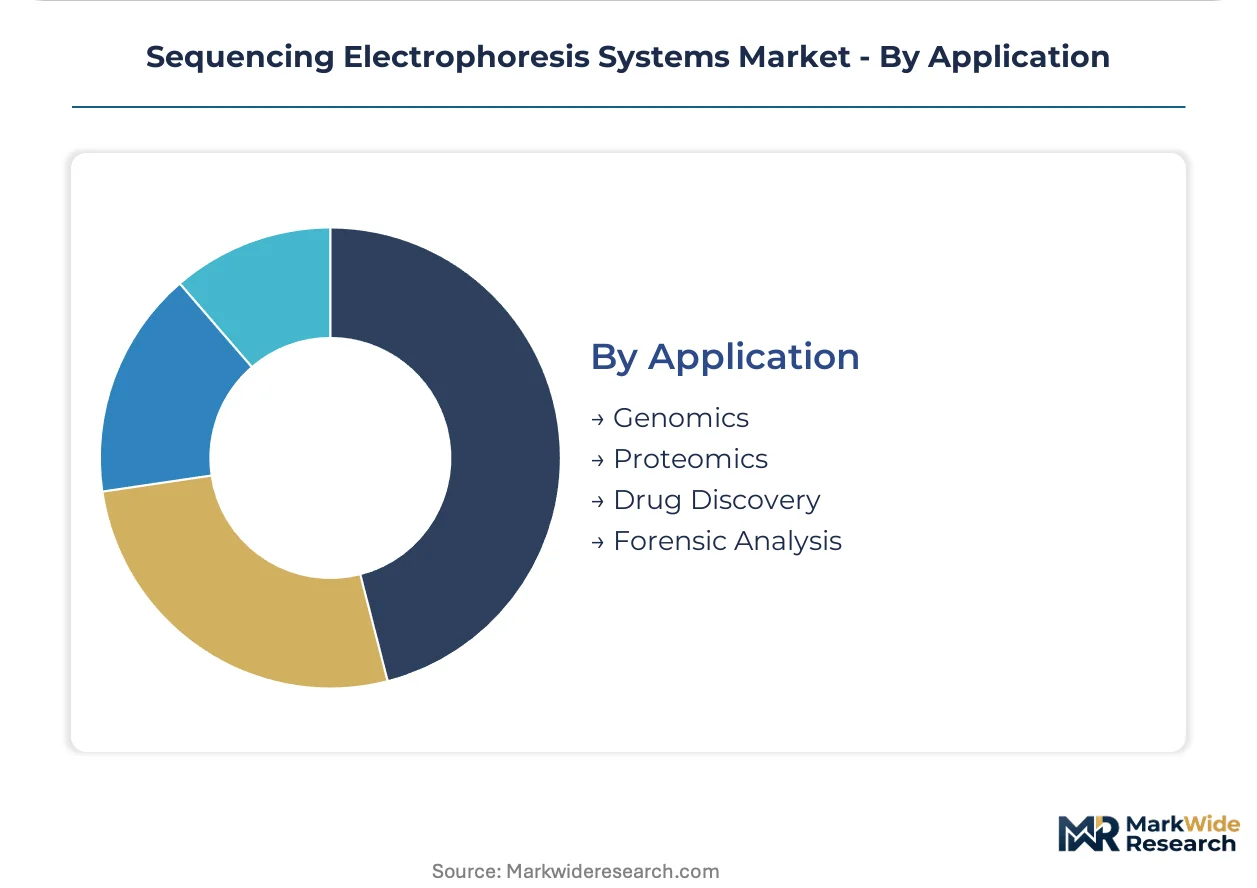
Application:
Regulatory pathway and reimbursement status create divergent margin profiles across clinical versus research-only deployment settings.
- Genomics:Germline and somatic variant analysis in inherited disease and oncology settings requires documented analytical performance for CLIA and CAP accreditation. Precision medicine programs in China are driving regional demand for CE-IVD certified platforms.
- Proteomics:SDS-PAGE and native gel electrophoresis for protein separation and western blot confirmation retain strong demand in bioprocess development. Contract manufacturing organizations in South Korea require validated systems for biosimilar comparability studies.
- Drug Discovery:Target validation and biomarker development workflows favor flexible platforms with multi-application software.
- Forensic Analysis:CODIS database expansion and rapid DNA programs mandate specific capillary configurations for STR amplification.
Genomics captures the dominant revenue position, while Forensic Analysis is expanding most quickly through federal and state criminal justice funding cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA quality system regulation anchors the United States as the dominant geography, while China's precision medicine build-out and Germany's ISO 13485 certification ecosystem reshape regional procurement patterns for sequencing electrophoresis infrastructure.
United States
Pharmaceutical quality control labs and forensic DNA databasing programs drive instrument replacement cycles. The FDA's CLIA complexity categorization and premarket notification requirements shape vendor selection for hospital-based molecular diagnostics. Boston and San Diego biotech clusters concentrate multi-user core facility installations serving precision medicine research.
China
National precision medicine infrastructure investments and biosimilar manufacturing expansion accelerate capillary electrophoresis procurement. NMPA medical device registration rules and GB standards compliance requirements filter market access for imported platforms. Yangtze River Delta research institutes in Shanghai and Suzhou deploy high-capillary-count systems for genomics workflows.
Germany
ISO 13485-certified instrument manufacturing and notified body concentration attract clinical diagnostic platform development. EMA diagnostic performance standards and EU IVDR conformity assessment timelines extend product registration cycles for CE-marked deployment. Baden-Württemberg precision engineering clusters supply fused silica capillary arrays to global instrument vendors.
India
Contract research organization expansion in biosimilar nucleic acid characterization creates demand for validated quality control systems. CDSCO medical device rules and import licensing requirements structure procurement pathways for foreign manufacturers. Hyderabad and Bengaluru biotech corridors require Sanger confirmation platforms for regulatory submission support.
Japan
Transcriptomics core facilities and single-cell sequencing workflows upgrade detection systems for low-input volume applications. PMDA quality management system requirements and JIS standards govern design controls for domestic clinical deployment. Kanto region research institutes in Tokyo and Tsukuba consolidate multi-technology platform investments.
Sequencing Electrophoresis Systems Market Competitive Landscape
Vertically integrated life science conglomerates and specialized analytical instrument manufacturers split the market into distinct capability tiers. Thermo Fisher Scientific's reagent-instrument bundling and Bio-Rad Laboratories' forensic specialization exemplify contrasting margin capture strategies. Consolidation pressure intensifies as notified body capacity constraints and ISO 13485 certification timelines favor scale players with dedicated regulatory affairs infrastructure. Strategic partnerships for microfluidic chip supply and geographic expansion into India's CRO corridor represent dominant competitive moves.
Among diversified life science tools providers, Thermo Fisher Scientific exemplifies the vertically integrated archetype through its captive reagent production and global service infrastructure. Bio-Rad Laboratories occupies a position within the specialized analytical tier, with its capillary electrophoresis platforms serving forensic and clinical validation labs. Agilent Technologies represents the measurement precision archetype, competing on software analytics integration across genomics workflows. These three anchors illustrate how strategic positioning around bundling economics, application specialization, and data ecosystem integration determines competitive outcomes in sequencing electrophoresis procurement.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Agilent Technologies |
| Merck KGaA |
| QIAGEN |
| PerkinElmer |
| Danaher Corporation |
| GE Healthcare |
| Lonza Group |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese fluorescent dye manufacturing is compressing margins for detection chemistry suppliers while simultaneously creating procurement leverage for instrument vendors negotiating reagent-instrument bundles. This utilization asymmetry drives divergent pricing postures between consumable producers and systems integrators.
Pricing Analysis
Geographic price spreads between United States pharmaceutical quality control labs and Indian contract research organizations exceed two-to-one for equivalent capillary electrophoresis platforms. Three-tier pricing structure across premium, standard, and economy levels segments by ISO 13485 certification status and service contract bundling intensity. Cost compression in economy-tier gel systems is intensifying because academic budget constraints limit upgrade cycles. Diagnostic centers exhibit lowest price sensitivity due to CLIA compliance requirements locking assay protocols.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk planning for fused silica capillary arrays. Manufacturing concentrates in Germany, Japan, and the United States for precision glass components, while China supplies bulk fluorescent dyes and polymer chip substrates. The supply chain rests on rhodamine derivative chemistry and fused silica raw materials vulnerable to allocation bottlenecks. Distribution runs through authorized dealer networks for clinical systems and direct academic procurement for research-grade platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service contract attach rates are expanding faster than hardware shipments as pharmaceutical labs unbundle validation support from capital acquisition. This recurring-revenue layer now commands margin premiums exceeding instrument sales in mature installed bases.
For Market Incumbents: Harden regulatory affairs infrastructure against ISO 13485 certification timeline extensions that favor scale players with dedicated quality teams. Deepen backward integration into captive reagent production to defend bundling economics against independent consumable suppliers. Prioritize forensic DNA databasing program relationships where CODIS-compliant configurations create switching costs. For New Entrants and Emerging Players: Build out microfluidic electrophoresis platforms for point-of-care diagnostic applications where capillary formats face footprint constraints. India's biosimilar CRO corridor offers the most penetrable geography for validated quality control systems lacking entrenched vendor relationships. Pursue hospital system partnerships leveraging EU IVDR transition urgency to displace legacy gel installations. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated platforms with captive consumable pull-through. Five-to-ten year viability favors manufacturers with notified body relationships and CE-IVD technical documentation libraries. Monitor Illumina and MGI platform substitution rates as the inflection signal for Sanger confirmation workflow displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Reagent-Instrument Bundling | Consumable pull-through economics lock research institutions into recurring vendor relationships. |
| ISO 13485 Certification Investment | Design history file capabilities accelerate clinical diagnostic platform registration timelines. |
| Microfluidic Platform Development | Lab-on-chip integration opens point-of-care applications inaccessible to capillary formats. |
| Forensic DNA Databasing Partnership | CODIS-compatible STR analysis configurations create federally funded replacement cycles. |
| EU IVDR Compliance Pathway | CE-IVD technical documentation captures European clinical lab replacement demand. |
Research Methodology
The analysis maps capillary electrophoresis, gel electrophoresis, microfluidic devices, and automated systems segments, each validated through laboratory directors, regulatory affairs managers, and biomedical engineers at pharmaceutical quality control labs, hospital molecular pathology departments, and academic core facilities. Primary interviews combined with secondary validation from FDA 510(k) filings, EMA CE marking databases, ISO 13485 certification registries, and hospital procurement records. Bottom-up instrument shipment tracking and top-down reagent consumption estimates were triangulated.
Assumptions held fixed include regulatory pathway requirements for clinical diagnostic deployment and technology substitution rates for next-generation sequencing platforms. Segmentation dimensions modeled include product architecture, end-user workflow requirements, sequencing chemistry type, and application setting across the analysis window. CAGRs derived from installed base replacement cycles and consumable pull-through coefficients. Forecast inputs incorporated CLIA complexity categorization trends and precision medicine infrastructure investment trajectories.
Stress conditions across fluorescent dye supply concentration, capillary array allocation risk, and ISO 13485 notified body queue delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about regulatory harmonization between FDA breakthrough device pathways and EMA diagnostic performance standards. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Europe Epigenetics Market
Genomics
Next Generation Molecular Assay Market
Genomics
Global Nutrigenomics Market
Genomics
Europe Whole Exome Sequencing Market
Genomics
Single-Cell Omics Market
Genomics
United States Cancer Biomarkers Market
Genomics
Global NGS Sample Preparation Market
Genomics
Mitochondrial DNA Market
Genomics
Genetic Material Market
Genomics
Global Molecular Cytogenetics Market
Genomics
Hereditary Testing Market
Genomics
Transcriptomics Technologies Market
Genomics
SNP Genotyping Market
Genomics
Global Clinical Oncology Next Generation Sequencing Market
Genomics
Global Gene Amplification Technologies Market
Genomics
NGS-Based RNA-Sequencing Market