
 Middle East and Africa Micro Invasive Glaucoma Surgery (MIGS) Devices Market | 2026-2036
Middle East and Africa Micro Invasive Glaucoma Surgery (MIGS) Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Micro Invasive Glaucoma Surgery (MIGS) Devices Market Foresight
Biocompatible titanium is recalibrating stent manufacturing economics across the MIGS supply chain, displacing legacy polymers in high-durability implant designs. Glaukos Corporation leverages vertical integration in micro-scale fabrication to sustain cost advantages in intraocular shunt production. Alcon Inc. anchors its regional position through specialized distribution networks spanning Gulf ophthalmology clinics. Santen Pharmaceutical Co., Ltd. differentiates via R&D intensity in drug-device combination platforms for glaucoma management.
Micro Invasive Glaucoma Surgery devices constitute miniature implantable or disposable instruments designed to reduce intraocular pressure through trabecular meshwork bypass, suprachoroidal shunting, or subconjunctival filtration, typically measuring less than one millimeter in critical dimensions and requiring ab-interno surgical placement without scleral flap creation. Stents command the dominant revenue share within device type segmentation due to established clinical validation and surgeon familiarity, while shunts represent the fastest-expanding category as next-generation biocompatible materials improve long-term patency rates. Hospitals capture the largest end-user volume owing to capital-intensive surgical infrastructure requirements, though ambulatory surgical centers are gaining procedural share where same-day discharge protocols align with payer cost-containment objectives.
South Africa's Health Products Regulatory Authority, Saudi Food and Drug Authority, and UAE Ministry of Health and Prevention collectively govern MIGS device market access through divergent registration timelines and clinical evidence requirements, with Gulf regulators increasingly harmonizing standards toward CE-mark recognition to accelerate approval pathways. South Africa's national health insurance expansion is reshaping public-sector procurement specifications for ophthalmic surgical devices. Stakeholders must monitor evolving reimbursement banding decisions across national health systems, as these determinations will dictate whether MIGS procedures remain concentrated in private fee-for-service channels or penetrate publicly funded care networks.
Market Dynamics
Hospital procurement departments across the Gulf Cooperation Council are consolidating MIGS device purchasing into multi-year framework agreements, compressing vendor margins while locking in surgical volume commitments. This purchasing concentration is restructuring competitive positioning around supply chain reliability rather than product differentiation alone.
Growth Catalysts
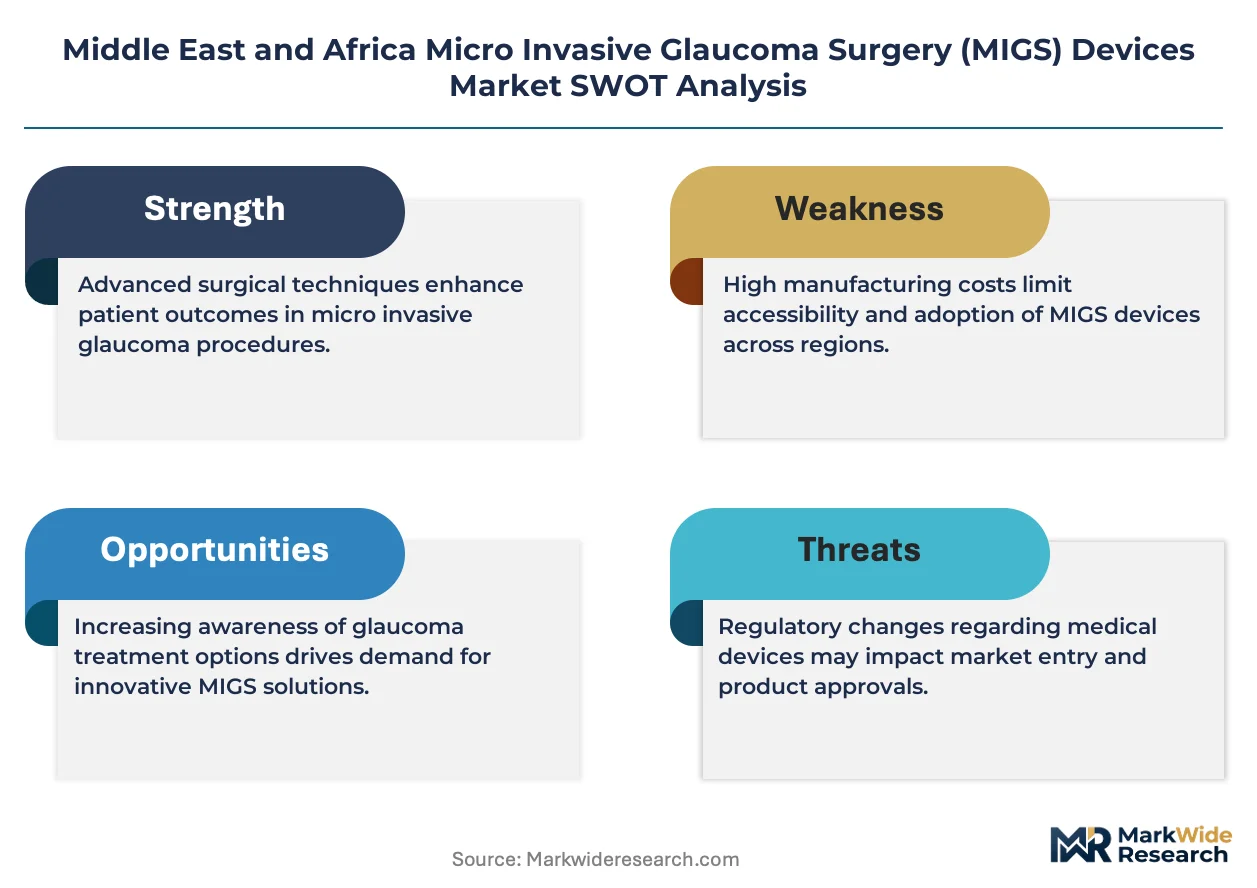
- Saudi Food and Drug Authority harmonization:The SFDA's accelerated CE-mark recognition pathway is reducing ophthalmic device registration timelines from eighteen months to under nine months, enabling faster product launches for European-manufactured stents.
- Tertiary eye care center expansion:Saudi Arabia's government health transformation programs are prioritizing minimally invasive surgical interventions, directing capital expenditure toward MIGS-capable surgical suites in Riyadh and Jeddah.
- Biocompatible titanium adoption:Advanced micro-scale fabrication techniques are enabling thinner-walled stent designs with improved long-term patency, expanding addressable patient populations to earlier-stage glaucoma cases.
Market Restraints
- Import dependency concentration:MIGS device supply chains remain concentrated through European distribution hubs, exposing Gulf markets to euro-denominated cost volatility and extended replenishment cycles.
- Surgeon training bottlenecks:Ab-interno surgical placement requires specialized microsurgical skills that remain scarce outside South Africa's academic medical centers and select Saudi teaching hospitals.
- Reimbursement banding uncertainty:South Africa's national health insurance expansion has not finalized ophthalmic surgical procedure codes, creating procurement paralysis in public-sector channels.
Strategic Opportunities
- Ambulatory surgical center penetration:UAE Ministry of Health and Prevention same-day discharge protocols are enabling MIGS procedural migration from hospital inpatient settings to specialized ophthalmology day clinics in Dubai and Abu Dhabi.
- Drug-device combination platforms:Convergence of sustained-release pharmaceutical formulations with implantable shunt architectures offers differentiated positioning for premium pricing in private fee-for-service networks.
- Nigeria and Kenya market development:Underpenetrated West and East African markets present first-mover advantages for distributors establishing specialized ophthalmology supply relationships ahead of competitive entry.
Industry Challenges
- Microsurgical skill pipeline gaps:Gulf ophthalmology residency programs produce fewer than fifty glaucoma-fellowship-trained surgeons annually, constraining procedural volume expansion regardless of device availability.
- Multi-jurisdiction registration complexity:Divergent clinical evidence requirements across South Africa's Health Products Regulatory Authority, Saudi Food and Drug Authority, and UAE Ministry of Health and Prevention force redundant submission preparation and extended approval timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Micro Invasive Glaucoma Surgery (MIGS) Devices Market |
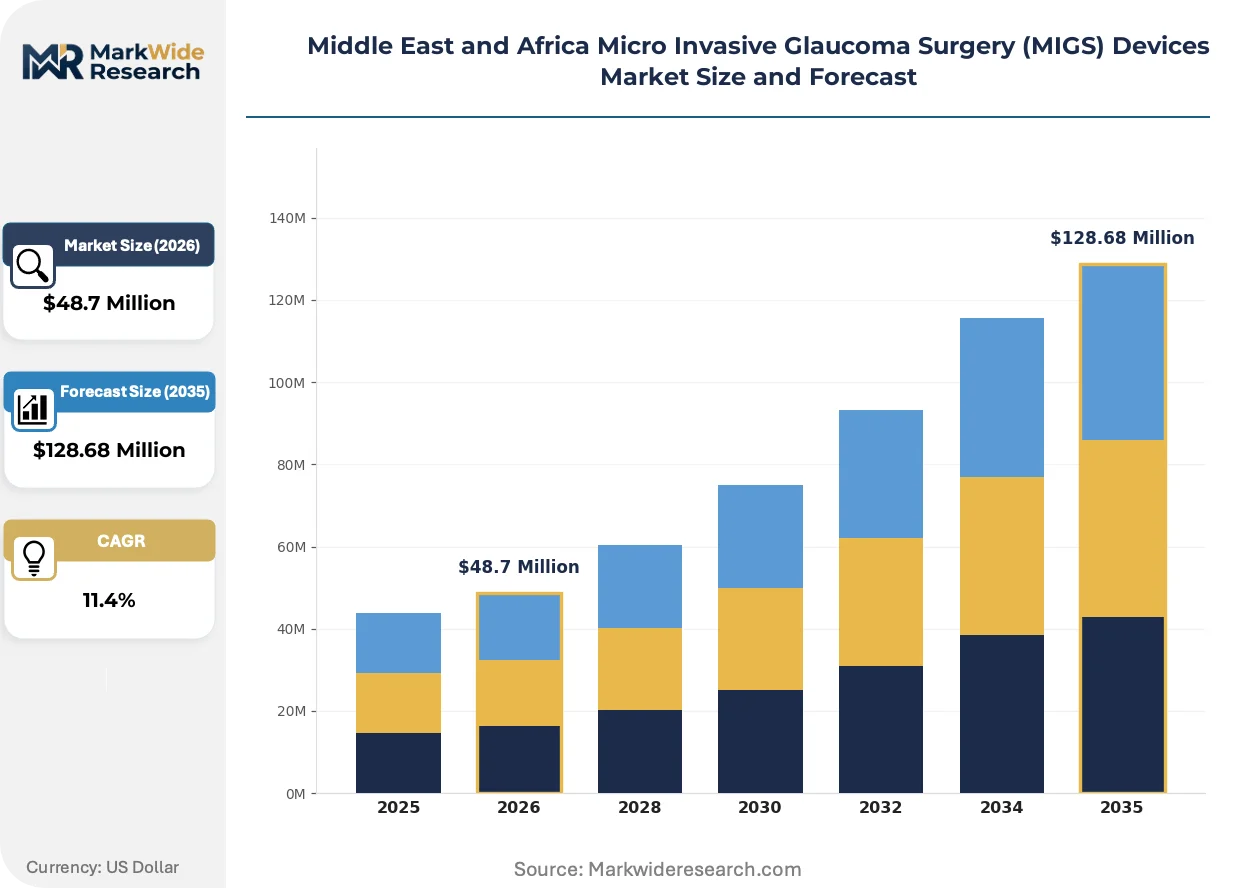
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $128.68 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Shunts, Implants, Stents, Cannulas End User: Ophthalmology Clinics, Hospitals, Ambulatory Surgical Centers, Research Institutions Delivery Mode: In-Person, Telemedicine, Mobile Units, Patient-Centric Approaches Application: Primary Glaucoma, Secondary Glaucoma, Ocular Hypertension, Others |
| Companies Covered | Glaukos Corporation, Alcon Inc., AbbVie Inc., Santen Pharmaceutical Co., Ltd., New World Medical Inc., iSTAR Medical SA, Ivantis Inc., Novartis International AG, Allergan plc, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Micro Invasive Glaucoma Surgery (MIGS) Devices Market Shifts & Advancements
Active materials science breakthroughs are compressing implant dimensions while extending functional durability, fundamentally altering the economics of high-volume MIGS device manufacturing. These advances are enabling new competitive entry strategies focused on cost-engineered alternatives to established premium platforms.
Biocompatible titanium is absorbing market preference from legacy polymer substrates in next-generation stent architectures. Saudi tertiary eye care centers are adopting titanium-based designs at accelerating pace for trabecular meshwork bypass procedures. The material shift is absorbing cost premiums through simplified sterilization protocols and reduced explantation rates, compressing total cost-of-ownership calculations for hospital procurement departments.
SFDA regulatory harmonization toward CE-mark recognition is streamlining ophthalmic device market access pathways across the Gulf Cooperation Council. This policy convergence eliminates redundant local clinical trials for European-manufactured products, accelerating commercialization timelines. South African regulators are observing this harmonization model, with Health Products Regulatory Authority officials engaging in bilateral discussions to align registration requirements.
Same-day discharge protocols are restructuring channel economics for MIGS device distribution. Ambulatory surgical centers in UAE and Saudi Arabia are displacing hospital-based procurement for routine glaucoma interventions, favoring distributors with specialized ophthalmology logistics capabilities. This channel migration is most visible in Dubai's healthcare free zones, where dedicated ophthalmology day clinics concentrate surgical volume away from general hospital infrastructure.
Middle East and Africa Micro Invasive Glaucoma Surgery (MIGS) Devices Market Segmentation
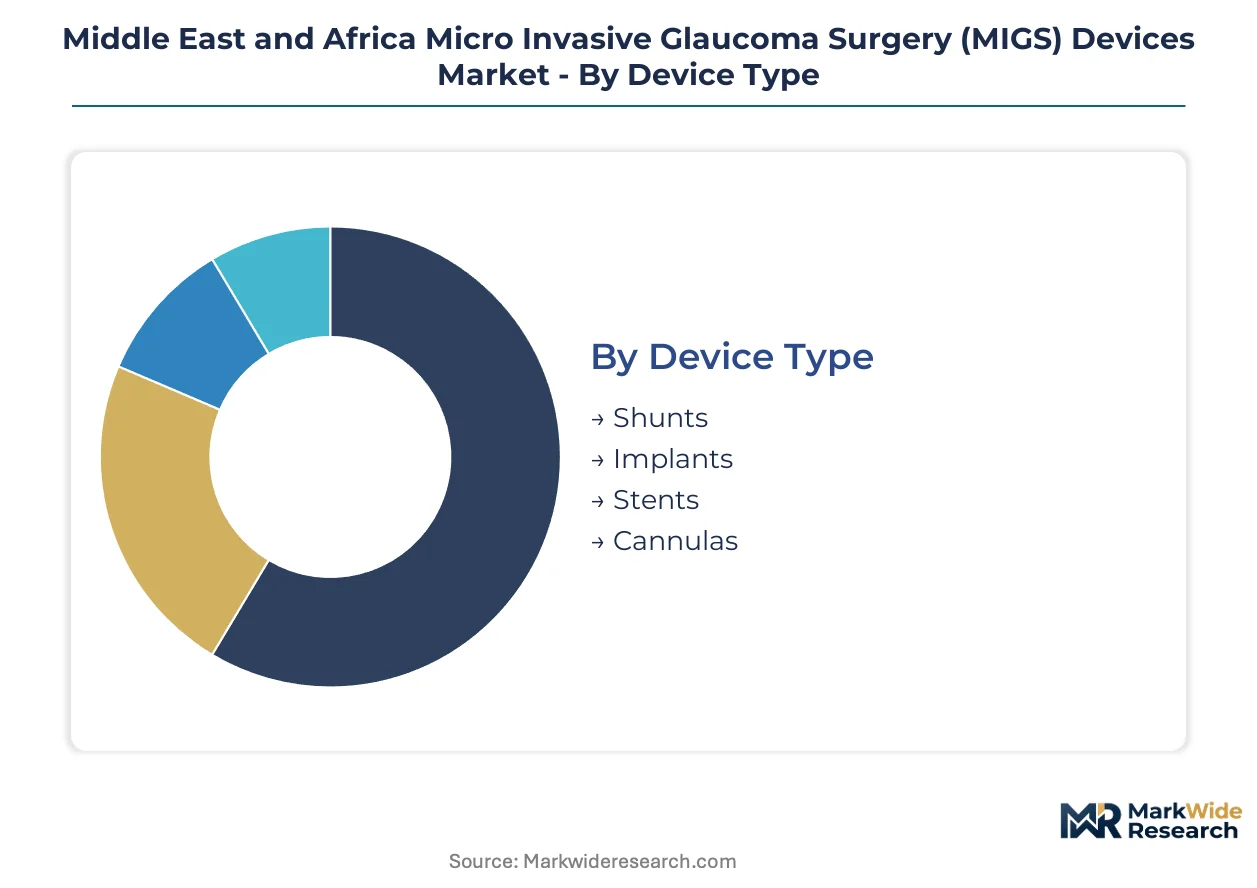
Device configuration determines procurement economics and clinical workflow integration across Middle East and Africa ophthalmology networks. Segment boundaries reflect divergent reimbursement pathways, surgical infrastructure requirements, and patient risk stratification protocols that reshape vendor positioning.
Device Type:
Procurement departments weigh total cost-of-ownership against patency durability when allocating capital across implant categories.
- Stents:Titanium-alloy trabecular meshwork bypass devices dominate hospital purchasing frameworks due to established SFDA registration pathways and surgeon familiarity. Saudi tertiary centers in Riyadh and Jeddah concentrate demand for premium stent platforms under government health transformation capital allocations.
- Shunts:Suprachoroidal and subconjunctival filtration implants constructed from advanced biocompatible polymers are expanding addressable populations to earlier-stage glaucoma cases. UAE ambulatory surgical centers in Dubai Healthcare City are adopting next-generation shunt architectures for same-day discharge protocols.
- Implants:Drug-device combination platforms integrate sustained-release pharmaceutical formulations with implantable architectures.
- Cannulas:Disposable ab-interno delivery instruments support procedural standardization across high-volume surgical networks.
Volume sits with stents; growth tilts toward shunts.
End User:
Surgical infrastructure intensity and reimbursement banding determine channel economics for device distribution.
- Hospitals:Capital-intensive MIGS-capable surgical suites with dedicated ophthalmology operating theaters capture the largest procedural volumes. Saudi Arabia's Ministry of Health directs equipment procurement toward tertiary eye care centers in Riyadh, Jeddah, and Dammam under Vision 2030 health transformation programs.
- Ambulatory Surgical Centers:Specialized ophthalmology day clinics in Dubai Healthcare City and Abu Dhabi are displacing hospital-based procurement for routine interventions. UAE Ministry of Health and Prevention same-day discharge protocols enable procedural migration to lower-cost settings.
- Ophthalmology Clinics:Private fee-for-service networks in South Africa's urban centers concentrate diagnostic and pre-surgical patient flow.
- Research Institutions:Academic medical centers in Cape Town and Johannesburg generate clinical evidence for regulatory submissions.
Procurement concentrates in hospitals; expansion accelerates in ambulatory surgical centers.
Delivery Mode:
Patient access geography and reimbursement structure determine service configuration across public and private networks.
- In-Person:Traditional surgical consultation and procedure delivery through fixed-site ophthalmology facilities remains the dominant access pathway. Gulf Cooperation Council hospital procurement departments prioritize in-person surgical capacity in framework agreements.
- Telemedicine:Remote pre-operative screening and post-operative monitoring protocols are penetrating South Africa's private insurance networks. Western Cape tele-ophthalmology programs extend specialist reach to underserved rural populations.
- Mobile Units:Deployable screening and surgical support vehicles serve dispersed populations in Kenya and Nigeria.
- Patient-Centric Approaches:Coordinated care pathways integrate diagnosis, intervention, and follow-up across multiple touchpoints.
Service delivery anchors on in-person encounters; telemedicine gains fastest in South Africa.
Application:
Disease severity and progression risk stratification guide device selection and reimbursement eligibility.
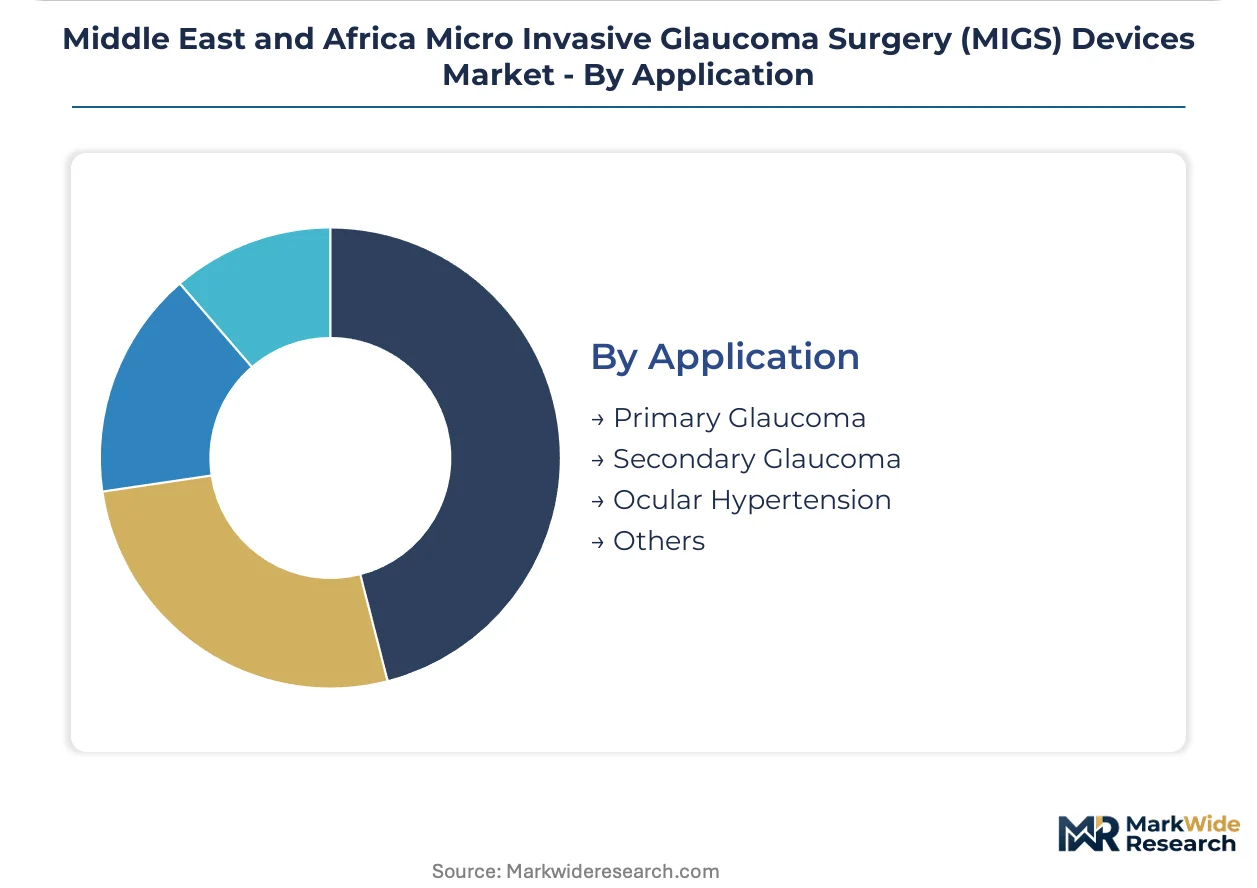
- Primary Glaucoma:Open-angle and angle-closure variants constitute the predominant surgical indication across Middle East and Africa markets. Saudi tertiary centers prioritize minimally invasive intervention for primary open-angle cases before trabeculectomy escalation.
- Secondary Glaucoma:Post-surgical, traumatic, and uveitic etiologies require specialized device configurations. South African academic medical centers concentrate complex secondary case referral patterns.
- Ocular Hypertension:Elevated intraocular pressure without optic nerve damage represents a preventive intervention opportunity.
- Others:Pediatric and congenital glaucoma variants command specialized pediatric ophthalmology infrastructure.
Procedure volume clusters in primary glaucoma; secondary applications command premium pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Saudi Arabia's tertiary eye care centers and South Africa's academic medical corridors, with procurement frameworks across the Gulf Cooperation Council reshaping vendor economics. Government health transformation programs and regulatory harmonization initiatives are accelerating device entry timelines.
Saudi Arabia
Riyadh and Jeddah tertiary centers drive stent procurement volumes under Vision 2030 capital allocations. The Saudi Food and Drug Authority's CE-mark recognition pathway compresses registration timelines from eighteen months to under nine months. Eastern Province hospital networks are expanding MIGS-capable surgical suites in Dammam and Khobar.
United Arab Emirates
Dubai Healthcare City ophthalmology day clinics are displacing hospital-based procurement for routine interventions. The UAE Ministry of Health and Prevention's same-day discharge protocols enable procedural migration to ambulatory settings. Abu Dhabi's specialized ophthalmology centers concentrate shunt adoption for earlier-stage glaucoma cases.
South Africa
Cape Town and Johannesburg academic medical centers generate clinical evidence for regulatory submissions across the continent. The Health Products Regulatory Authority is streamlining ophthalmic device registration pathways. Western Cape tele-ophthalmology programs extend specialist reach to underserved rural populations.
Nigeria
Lagos and Abuja private fee-for-service networks concentrate diagnostic patient flow for glaucoma interventions. The country's national pharmaceutical regulator is observing Gulf regulatory harmonization models. West African distributors are establishing specialized ophthalmology supply relationships ahead of competitive entry.
Kenya
Nairobi private insurance networks are piloting remote pre-operative screening protocols for MIGS candidacy. The central health ministry is evaluating same-day discharge frameworks for ophthalmic surgery. East African mobile screening units serve dispersed populations beyond fixed-site infrastructure.
Middle East and Africa Micro Invasive Glaucoma Surgery (MIGS) Devices Market Competitive Landscape
Vertical integration into micro-scale fabrication dominates the current landscape, with vendors consolidating supply chain control over titanium-alloy stent production. The vendor base fragments across European-manufactured premium platforms and emerging cost-engineered alternatives. Three archetypes occupy distinct positions: integrated device manufacturers with captive fabrication capabilities, specialized ophthalmology distributors with regional logistics networks, and drug-device combination platform developers. M&A activity and strategic distribution partnerships constitute the dominant competitive moves.
Among integrated device manufacturers, Glaukos Corporation and Alcon Inc. anchor the premium-tier segment through specialized fabrication and distribution capabilities. Santen Pharmaceutical Co., Ltd. occupies a position within the drug-device combination archetype, exemplifying R&D intensity in sustained-release pharmaceutical integration. These three entities represent contrasting strategic vectors: fabrication control, regional logistics scale, and pharmaceutical convergence.
| Leading Market Players |
|---|
| Glaukos Corporation |
| Alcon Inc. |
| AbbVie Inc. |
| Santen Pharmaceutical Co., Ltd. |
| New World Medical Inc. |
| iSTAR Medical SA |
| Ivantis Inc. |
| Novartis International AG |
| Allergan plc |
| Others |
Supply & Pricing Matrix
European titanium-alloy feedstock price indices cascade through Gulf procurement frameworks, compressing margins for polymer-based stent manufacturers while rewarding backward-integrated fabricators with captive titanium sourcing. Hospital purchasing committees in Riyadh and Jeddah exploit this raw-material arbitrage to renegotiate multi-year framework agreements.
Pricing Analysis
High-volume stent contracts trade margin for procurement security, while low-volume shunt platforms capture premium pricing through clinical differentiation. Three-tier pricing structure across premium titanium-alloy, standard polymer, and economy cannula levels stratifies by material certification grade and surgeon training tier. Pricing pressure stems from Gulf Cooperation Council hospital consolidation into centralized purchasing authorities. Ambulatory surgical centers in Dubai Healthcare City exhibit highest price sensitivity; tertiary eye care centers in Saudi Arabia show lowest sensitivity due to government transformation program funding.
Supply Chain Analysis
Domestic-content thresholds in Saudi Arabia's Vision 2030 industrial localization mandates are reshaping sourcing patterns, pressuring distributors to establish regional sterilization and packaging capabilities. Manufacturing concentrates in Germany, Switzerland, and the United States for precision micro-fabrication equipment and titanium-alloy raw material. Component dependencies include biocompatible titanium billet, polymer resin grades, and single-use cannula extrusions. Single-source vulnerability runs through European distribution hubs for CE-marked finished devices. Distribution runs through specialized ophthalmology logistics networks with cold-chain and sterile-handling capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The MIGS device sector occupies a material-transition inflection, with biocompatible titanium architectures displacing legacy polymer substrates across next-generation stent platforms. Procurement committees now weight total cost-of-ownership calculations that favor durability over upfront device pricing.
For Market Incumbents: Hedge titanium-alloy supply exposure through long-term offtake agreements with European feedstock suppliers, insulating against euro-denominated volatility that threatens margin stability. Deepen backward integration into micro-scale fabrication to defend against emerging cost-engineered entrants from Asian manufacturing hubs. Prioritize SFDA registration pathway maintenance as Gulf regulatory harmonization accelerates competitive entry timelines. For New Entrants and Emerging Players: Begin with drug-device combination platforms in South Africa's private fee-for-service networks, where reimbursement flexibility permits premium pricing for sustained-release pharmaceutical integration. Target Nigeria and Kenya's underpenetrated markets through mobile screening partnerships that build surgeon referral relationships ahead of fixed-site infrastructure. Pursue distributor-acquisition routes rather than direct sales buildout to leverage established ophthalmology logistics capabilities. For Investors and Strategic Acquirers: The window for entry favors specialized ophthalmology distributors with Gulf Cooperation Council regulatory relationships and hospital system contracts. Long-term viability rests on consolidation plays that aggregate procurement scale across fragmented national markets. Watch SFDA registration timeline compression as the signal for competitive entry acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Optimization | SFDA harmonization reduces European manufacturer entry timelines from eighteen months to under nine months. |
| Hospital System Partnership | Multi-year framework agreements with Saudi tertiary centers lock in surgical volume commitments. |
| Backward Integration into Titanium Fabrication | Captive micro-scale production insulates against feedstock price volatility and sterilization cost inflation. |
| Drug-Device Combination Development | Sustained-release pharmaceutical integration commands premium positioning in private fee-for-service networks. |
| Ambulatory Surgical Center Channel Expansion | UAE same-day discharge protocols enable procedural migration from hospital inpatient settings. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews across glaucoma surgeons, hospital procurement managers, biomedical engineers, and GPO contracts administrators. SFDA submission databases, CE marking registries, South African Health Products Regulatory Authority filings, and Gulf hospital procurement databases supplied quantitative foundations. Bottom-up device shipment modeling and top-down healthcare expenditure triangulation validated segment-level estimates.
Granularity extended to device type, end-user channel, and application severity across the projection horizon, with separate modeling for Saudi Arabia, UAE, South Africa, Nigeria, and Kenya. CAGRs derived from surgical volume forecasts, reimbursement banding trajectories, and regulatory approval pipeline analysis. Titanium-alloy price indices and surgeon fellowship completion rates served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; stent volume estimates carry tighter precision than emerging shunt categories due to established procurement reporting. Forecasts reflect assumptions around regulatory harmonization pace, reimbursement expansion timing, and surgeon training pipeline expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Pressure-Volume Loop Systems Market
Medical Devices
Germany Drug Delivery Devices Market
Medical Devices
Global Gynecology Robotic Surgery Market
Medical Devices
Veterinary Ultrasound Devices Market
Medical Devices
Medical Bionic Implant Market
Medical Devices
Gracey Curette Market
Medical Devices
Interatrial Shunt Market
Medical Devices
Global Large Volume Wearable Injectors Market
Medical Devices
Global IVF Devices and Consumables Market
Medical Devices
Pharma Robots Market
Medical Devices
Inhaled Corticosteroid Device Market
Medical Devices
Digital Respiratory Devices Market
Medical Devices
Transcutaneous Oximetry Systems Market
Medical Devices
Phototherapy Lamps Market
Medical Devices
North America Electric Wheelchair Market
Medical Devices
Organ Preservation Market