
 Middle East and Africa Sleep Apnea Devices Market | 2026-2036
Middle East and Africa Sleep Apnea Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Sleep Apnea Devices Market Foresight
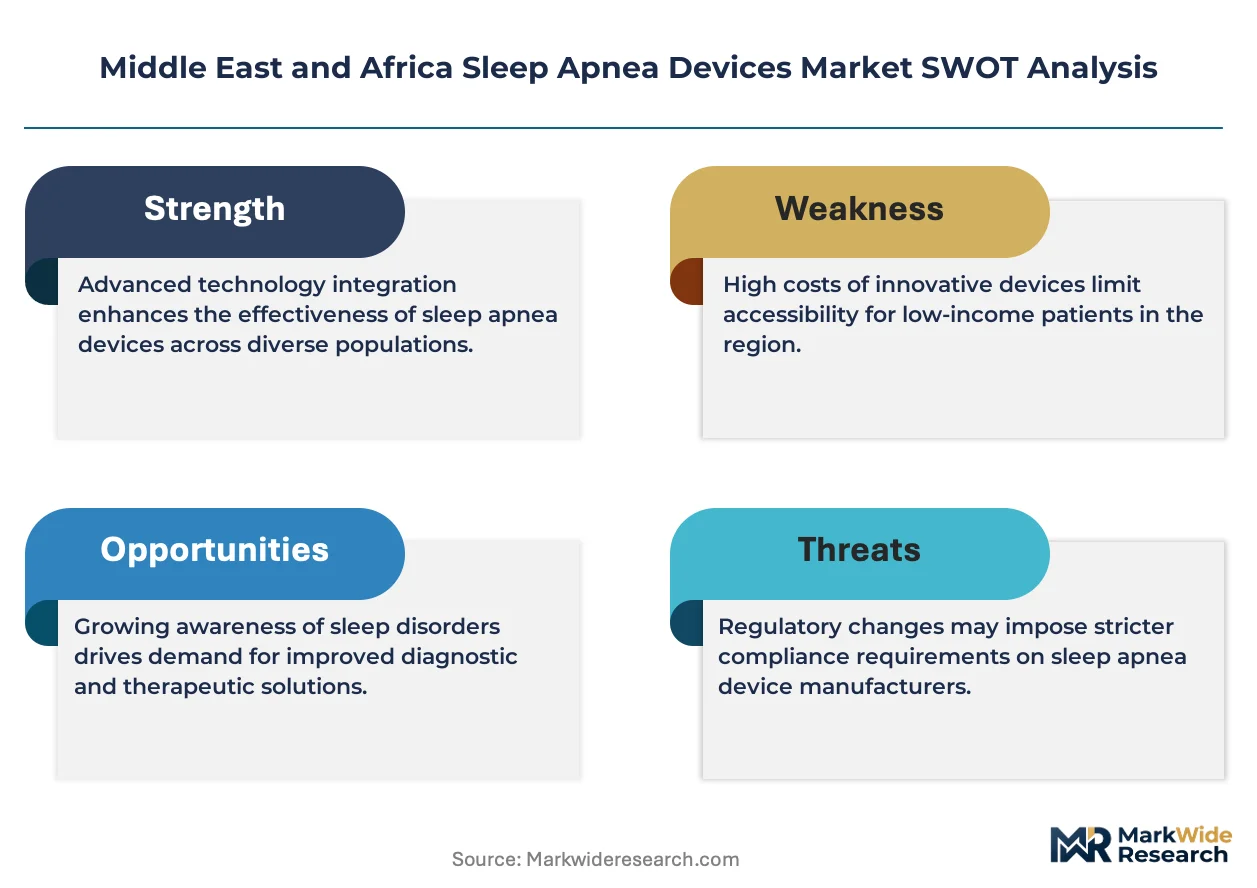
Remote patient monitoring subscriptions is shifting how sleep apnea devices generate recurring revenue across the Middle East and Africa. ResMed Inc leverages cloud-connected therapy platforms to sustain long-term patient engagement beyond hardware sales. Fisher & Paykel Healthcare Corp Ltd anchors its regional presence through humidification systems bundled with core ventilation devices. Koninklijke Philips NV competes on integrated diagnostic-to-therapy workflows that span home and clinical environments.
Sleep apnea devices encompass positive airway pressure systems, oral appliances, and adaptive ventilation units designed to maintain patent airways during sleep through continuous or bilevel airflow delivery, typically operating at pressures between 4 and 20 cm H2O. These systems serve the primary commercial purpose of reducing apnea-hypopnea indices and preventing cardiovascular sequelae in diagnosed patients. CPAP Devices occupy the dominant revenue position due to established clinical guidelines and insurer familiarity, while Digital Therapeutics within the Technology dimension represents the fastest-expanding margin pool as software-enabled adherence tools command premium positioning. Home Care Settings within the End User category is structurally outpacing hospital channels as miniaturization and telehealth integration reduce the need for inpatient sleep studies.
SFDA in Saudi Arabia and MOHAP in the UAE enforce medical device registration requirements that shape import timelines and product standardization for sleep apnea equipment entering Gulf markets. South Africa's Health Products Regulatory Authority applies IEC 60601 electrical safety standards to ventilation devices, creating compliance thresholds that filter lower-tier suppliers. BIS certification requirements for India-origin components indirectly influence supply chain configurations for regional distributors. Stakeholders must monitor how Gulf Cooperation Council harmonization of medical device regulations alters single-market approval pathways and competitive entry costs.
Market Dynamics
Remote patient monitoring subscriptions are restructuring revenue architecture across Middle East and Africa sleep apnea markets, compressing hardware margins while expanding recurring software income streams. Cloud-connected therapy platforms now anchor competitive positioning as manufacturers compete on patient adherence data rather than device specifications alone.
Growth Catalysts
- Saudi SFDA Registration Harmonization:Streamlined medical device approval pathways under Gulf Cooperation Council alignment reduce import timelines for positive airway pressure systems entering Riyadh and Jeddah distribution networks.
- Home Care Miniaturization:Portable diagnostic wearables eliminate hospital sleep study bottlenecks, enabling direct-to-patient screening in UAE residential settings and South African urban peripheries.
- Digital Therapeutics Integration:Software-enabled adherence platforms command premium positioning as insurers in Dubai and Cape Town recognize remote monitoring for reimbursement eligibility.
Market Restraints
- Import Duty Volatility:Fluctuating customs classifications for ventilation devices across Nigerian and Kenyan ports create landed cost uncertainty for distributors managing multi-country portfolios.
- South African Rand Exposure:Currency depreciation against dollar-denominated component sourcing raises working capital requirements for local assembly operations serving SADC markets.
- Reimbursement Fragmentation:Inconsistent national health insurance coverage criteria between Egypt's Ministry of Health and private Egyptian payers delay patient access decisions.
Strategic Opportunities
- Nigeria's Undiagnosed Pool:Lagos and Abuja present substantial untreated sleep apnea prevalence as cardiovascular screening programs expand awareness among hypertensive patient cohorts.
- Telehealth Convergence:Integration of video consultation platforms with cloud-connected CPAP devices enables remote titration adjustments, reducing specialist clinic dependency in Ethiopian and Kenyan markets.
- MOHAP Reimbursement Expansion:Dubai's health authority pilot programs for home-based sleep testing create precedent for broader UAE coverage of diagnostic-to-therapy workflows.
Industry Challenges
- Respiratory Therapist Scarcity:Gulf sleep clinics face recruitment bottlenecks for polysomnography-certified technicians capable of interpreting complex airflow data from adaptive ventilation units.
- IEC 60601 Certification Delays:South African HPRA electrical safety testing timelines extend product launch windows by four to six months for humidification system integrations.
- Legacy Hospital Inventory:Tethered diagnostic equipment in Cairo and Alexandria medical centers resists replacement by wireless alternatives due to capital depreciation schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Sleep Apnea Devices Market |
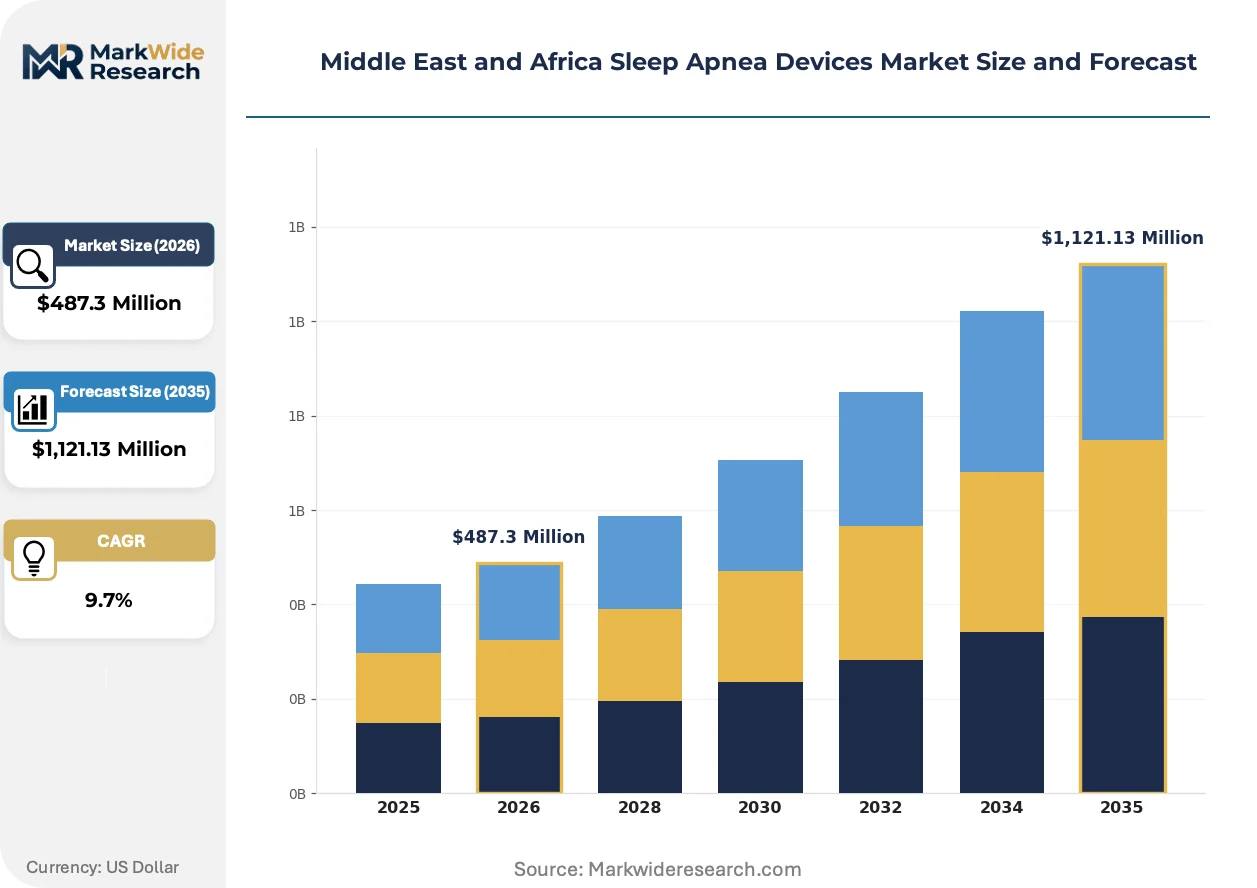
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,121.13 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CPAP Devices, BiPAP Devices, Adaptive Servo Ventilation, Oral Appliances End User: Hospitals, Home Care Settings, Sleep Clinics, Long-term Care Facilities Distribution Channel: Direct Sales, Online Retail, Medical Stores, Distributors Technology: Digital Therapeutics, Wearable Monitors, Smart Devices, Oxygen Concentrators |
| Companies Covered | BMC Medical, SOMNOmedics, ResMed Inc, Nihon Kohden Corp, ZOLL Medical Corporation, Koninklijke Philips NV, Natus Medical, Compumedics, Fisher & Paykel Healthcare Corp Ltd, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Sleep Apnea Devices Market Shifts & Advancements
Device architecture is fragmenting into interoperable subsystems as manufacturers decouple sensors, processors, and delivery mechanisms to enable patient-customized configurations. This decomposition is accelerating competitive entry by specialized component suppliers.
Adaptive ventilation hardware is modularizing across Middle East and Africa markets. CPAP and bilevel systems now separate airflow generators from humidification modules and data transmission units. Sleep clinics in Riyadh and Johannesburg are adopting mix-and-match configurations to match patient severity profiles. This modularization is compressing replacement cycles as individual components upgrade independently.
SFDA and MOHAP are tightening cybersecurity requirements for cloud-connected medical devices under harmonized Gulf data protection frameworks. Manufacturers must demonstrate encryption standards and breach response protocols before market authorization. Home care settings face the steepest compliance burden as patient-generated health data flows across borders to centralized monitoring centers.
Subscription-based adherence monitoring is displacing upfront device sales in Dubai and Cape Town reimbursement structures. Payers now bundle hardware provision with ongoing software analytics, shifting margin capture toward patient engagement duration. South African national health insurance reforms are piloting this model in public sector procurement, with private insurers observing outcomes before broader adoption.
Middle East and Africa Sleep Apnea Devices Market Segmentation
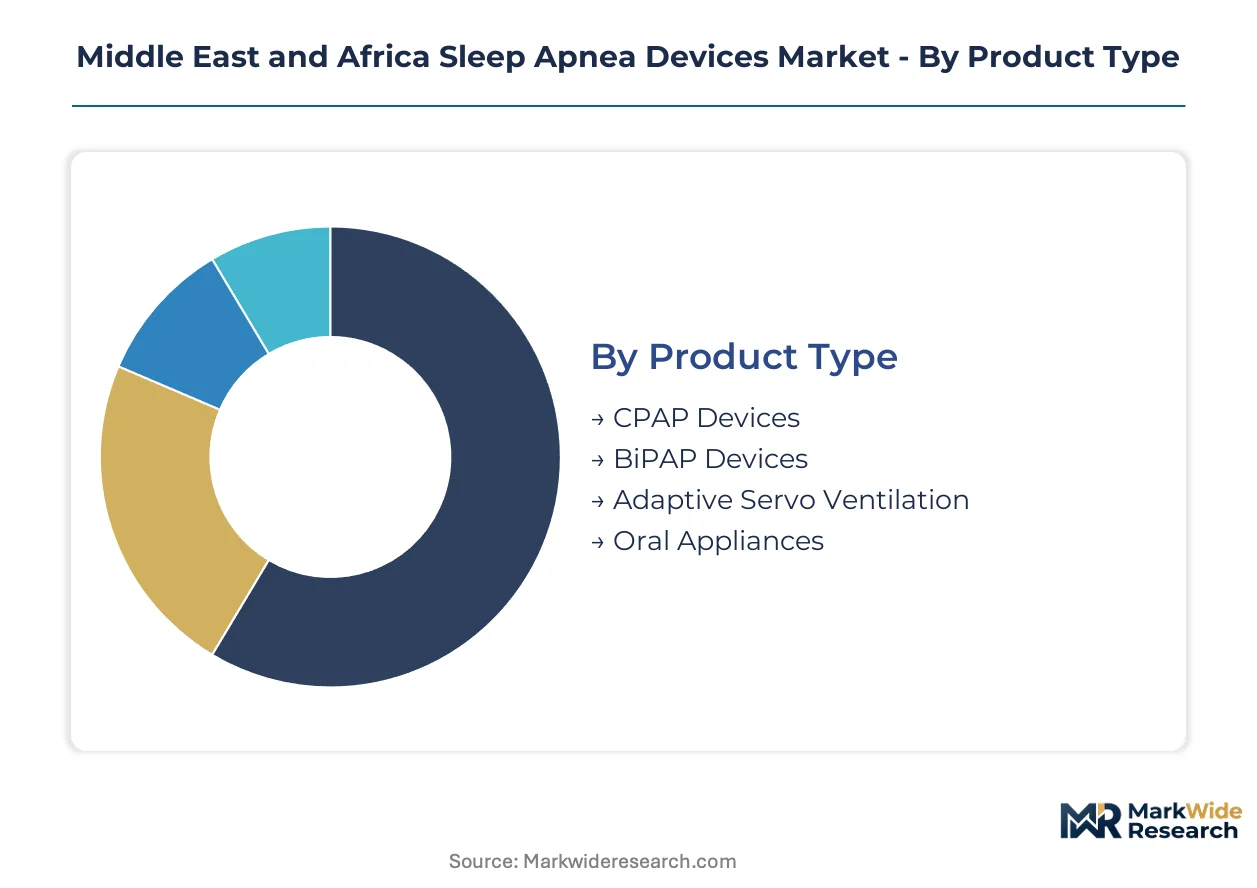
Sleep apnea device procurement across the Middle East and Africa fragments across clinical severity, care setting infrastructure, and reimbursement pathway maturity. Understanding where each segment sits within integrated diagnostic-to-therapy workflows versus standalone deployment shapes go-to-market economics and margin capture potential for manufacturers and distributors.
Product Type:
Integration depth varies sharply: CPAP and BiPAP systems anchor fully embedded therapy ecosystems with cloud connectivity, while oral appliances and adaptive ventilation occupy more modular, standalone positions in treatment hierarchies.
- CPAP Devices:Continuous positive airway pressure systems deliver airflow at fixed pressures between 4 and 20 cm H2O through nasal or full-face interfaces. Demand concentrates in Saudi Arabian home care settings where SFDA registration harmonization accelerates import timelines and government healthcare privatization expands patient access to subsidized therapy.
- BiPAP Devices:Bilevel positive airway pressure systems alternate between inspiratory and expiratory pressure settings, serving patients with central sleep apnea or complex respiratory comorbidities. Sleep clinics in Dubai and Cape Town drive procurement as pulmonologists prescribe pressure-variable therapy for patients failing CPAP titration protocols.
- Adaptive Servo Ventilation:Algorithm-driven pressure modulation responds to patient respiratory patterns in real-time, targeting Cheyne-Stokes respiration in heart failure patients. South African cardiovascular centers in Johannesburg and Pretoria represent the primary addressable patient pool.
- Oral Appliances:Mandibular advancement devices and tongue-retaining splints offer non-invasive alternatives for mild-to-moderate obstructive sleep apnea. Private dental practices in Abu Dhabi and Riyadh prescribe these for CPAP-intolerant patients seeking discreet therapy options.
Volume placements concentrate in CPAP Devices; the faster expansion belongs to Adaptive Servo Ventilation as cardiovascular comorbidity screening expands across Gulf health systems.
End User:
Care setting economics diverge sharply: hospital and sleep clinic channels absorb capital-intensive diagnostic infrastructure, while home care and long-term facilities prioritize portable, reimbursable therapeutic delivery.
- Hospitals:Tertiary medical centers in Cairo and Alexandria maintain polysomnography laboratories with tethered diagnostic suites. Capital depreciation schedules and specialist staffing constraints limit replacement demand for wireless alternatives.
- Home Care Settings:Miniaturized diagnostic wearables and cloud-connected therapy platforms enable direct-to-patient screening and treatment. UAE residential demand accelerates as MOHAP pilots expand reimbursement eligibility for remote monitoring subscriptions.
- Sleep Clinics:Dedicated respiratory centers in Riyadh and Jeddah combine diagnostic interpretation with therapy initiation. Gulf Cooperation Council regulatory harmonization reduces equipment procurement lead times for independent clinic operators.
- Long-term Care Facilities:Nursing homes and rehabilitation centers in South Africa's Western Cape manage chronic ventilation dependency. SADC market currency exposure raises working capital requirements for device leasing arrangements.
Revenue concentration sits with Home Care Settings; the steepest expansion trajectory belongs to Sleep Clinics as privatization deepens across Saudi Arabia's secondary cities.
Distribution Channel:
Channel economics reflect patient journey fragmentation: direct and distributor pathways serve institutional procurement with service bundling, while retail and online channels capture patient-initiated replacement and accessory demand.
- Direct Sales:Manufacturer field teams negotiate enterprise contracts with hospital networks and sleep clinic chains. Saudi Arabia's National Unified Procurement Company consolidates demand for ministry-affiliated facilities.
- Online Retail:E-commerce platforms serve CPAP mask and tubing replacement demand from diagnosed patients. South African rand volatility complicates dollar-denominated inventory planning for cross-border fulfillment.
- Medical Stores:Brick-and-mortar durable medical equipment suppliers in Lagos and Abuja stock entry-level devices. Nigerian import duty classification uncertainty creates landed cost variability across port entries.
- Distributors:Regional wholesalers manage multi-country portfolios across East African and Levant markets. Kenyan and Ethiopian customs processing delays extend order-to-delivery cycles for adaptive ventilation systems.
Transaction volume clusters in Distributors; the fastest share gain belongs to Online Retail as patient digital literacy and mobile payment penetration deepen across Gulf urban centers.
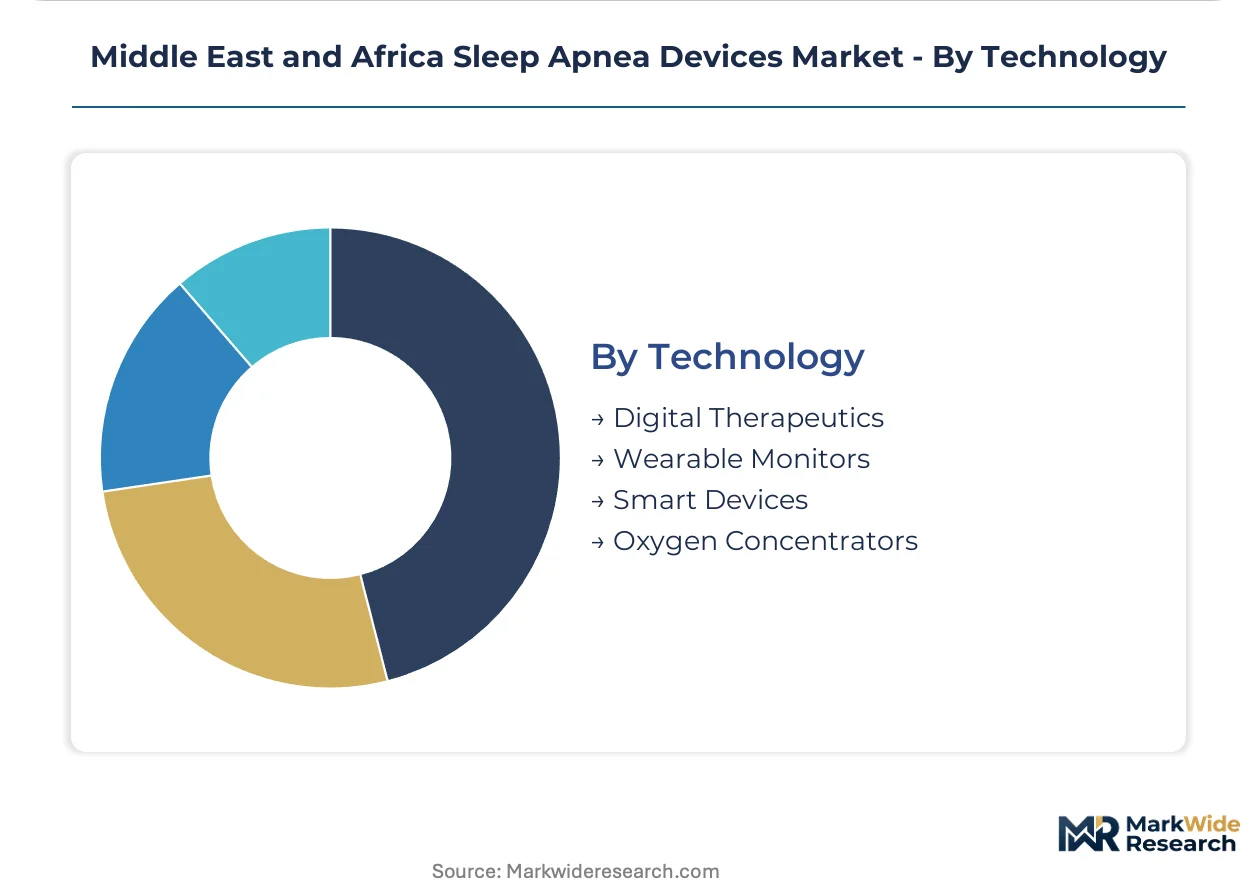
Technology:
Technology positioning spans software-enabled adherence platforms, biometric hardware, and gas delivery infrastructure—each commanding distinct margin profiles and regulatory scrutiny under Gulf cybersecurity frameworks.
- Digital Therapeutics:Cloud-based adherence analytics and behavioral intervention apps command premium positioning in Dubai and Cape Town reimbursement structures. Subscription revenue models displace upfront hardware sales as insurers recognize remote monitoring for eligibility.
- Wearable Monitors:Finger pulse oximeters and chest-band respiratory sensors enable home-based sleep study screening. South African urban peripheries adopt these to eliminate hospital sleep lab bottlenecks.
- Smart Devices:Bluetooth-enabled CPAP machines transmit compliance data to centralized monitoring centers. SFDA and MOHAP cybersecurity requirements tighten encryption and breach response protocols for cross-border data flows.
- Oxygen Concentrators:Pressure-swing adsorption units supplement hypoxemic sleep apnea therapy in high-altitude Ethiopian and Kenyan markets. BIS certification requirements for India-origin components influence supply chain configurations.
Margin capture concentrates in Digital Therapeutics; the most rapid climb belongs to Smart Devices as telehealth convergence enables remote titration adjustments reducing specialist clinic dependency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device consumption across the Middle East and Africa outpaces regional manufacturing capacity, creating import dependency concentrated in Gulf distribution hubs. Saudi Arabia and the UAE absorb the majority of positive airway pressure systems, while South Africa anchors sub-Saharan assembly and clinical training infrastructure.
Saudi Arabia
Government healthcare privatization and SFDA registration harmonization accelerate patient access to subsidized CPAP therapy. The National Unified Procurement Company consolidates ministry-affiliated facility demand, streamlining enterprise contracts for sleep clinic chains. Riyadh and Jeddah host the densest sleep clinic networks, where pulmonologists drive adaptive ventilation prescriptions for complex respiratory cases.
United Arab Emirates
MOHAP pilot programs for home-based sleep testing expand reimbursement eligibility for remote monitoring subscriptions. Dubai's health authority creates precedent for diagnostic-to-therapy workflow coverage, attracting digital therapeutics providers to establish regional headquarters. Abu Dhabi's private dental practices prescribe oral appliances for CPAP-intolerant patients seeking discreet alternatives.
South Africa
National health insurance reforms pilot subscription-based adherence monitoring in public sector procurement, with private insurers observing outcomes. Health Products Regulatory Authority applies IEC 60601 electrical safety standards that filter lower-tier suppliers from SADC market entry. Johannesburg and Pretoria cardiovascular centers drive adaptive servo ventilation demand for Cheyne-Stokes respiration patients.
Egypt
Inconsistent national health insurance coverage criteria between the Ministry of Health and private payers delay patient access decisions. Cairo and Alexandria medical centers maintain tethered polysomnography laboratories resistant to wireless replacement due to capital depreciation schedules. Cardiovascular screening programs in tertiary hospitals expand sleep apnea awareness among hypertensive cohorts.
Nigeria
Lagos and Abuja present substantial untreated sleep apnea prevalence as cardiovascular screening penetrates urban middle-class populations. Import duty volatility across Nigerian ports creates landed cost uncertainty for distributors managing multi-country portfolios. Brick-and-mortar durable medical equipment suppliers stock entry-level devices while navigating customs classification ambiguity.
Middle East and Africa Sleep Apnea Devices Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the Middle East and Africa sleep apnea market, with integrated manufacturers maintaining Gulf distribution networks while software specialists capture recurring revenue through cloud platforms. The vendor base clusters around three strategic archetypes: diversified respiratory conglomerates with full diagnostic-to-therapy portfolios, specialized ventilation equipment suppliers focused on humidification and airway delivery systems, and digital health platforms monetizing adherence analytics through subscription models. Dominant competitive moves include strategic partnerships with regional distributors to navigate SFDA and MOHAP regulatory pathways, plus portfolio diversification into wearable diagnostics and remote patient monitoring services.
Among diversified respiratory conglomerates, Koninklijke Philips NV and ResMed Inc exemplify integrated diagnostic-to-therapy positioning across hospital and home care environments. Fisher & Paykel Healthcare Corp Ltd occupies a specialized tier focused on humidification systems bundled with core ventilation devices. These three companies anchor competitive dynamics in Gulf Cooperation Council markets, where cloud-connected platforms and regulatory compliance capabilities determine procurement outcomes for ministry and private hospital contracts.
| Leading Market Players |
|---|
| BMC Medical |
| SOMNOmedics |
| ResMed Inc |
| Nihon Kohden Corp |
| ZOLL Medical Corporation |
| Koninklijke Philips NV |
| Natus Medical |
| Compumedics |
| Fisher & Paykel Healthcare Corp Ltd |
| Others |
Supply & Pricing Matrix
Polymer resin and electronic sensor costs flow from East Asian suppliers through Dubai distribution hubs into tiered device pricing across Gulf Cooperation Council markets, with IEC 60601 certification expenses filtering lower-tier competitors from premium positioning in South African rand-denominated procurement.
Pricing Analysis
Margin tightening in economy-tier CPAP systems reflects Nigerian import duty volatility and Kenyan customs processing delays that compress distributor working capital. Pricing stratifies across premium, standard, and economy tiers based on cloud connectivity bundling and SFDA registration status. Cost-down pressure on humidification modules accelerates because South African currency depreciation raises dollar-denominated component sourcing expenses. Hospital procurement committees in Cairo exhibit highest price sensitivity; Dubai sleep clinics with MOHAP reimbursement eligibility show lowest.
Supply Chain Analysis
SFDA and MOHAP cybersecurity certification requirements for cloud-connected devices create gating thresholds that filter non-compliant manufacturers from Gulf market entry. Component sourcing concentrates in India, China, and Malaysia for pressure sensors, blower motors, and humidification chambers. Supply chain risk centers on single-source vulnerability for adaptive ventilation algorithm processors. Distribution runs through Dubai and Johannesburg regional hubs serving multi-country portfolios across East Africa and the Levant.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where SFDA registration harmonization under Gulf Cooperation Council alignment creates a barrier-to-entry moat for manufacturers with established regulatory affairs infrastructure.
For Market Incumbents: To counter modularization-driven component replacement cycles, deepen software subscription revenue through remote patient monitoring platforms and establish captive humidification module production in India to mitigate BIS certification delays for regional distributors. For New Entrants and Emerging Players: MOHAP reimbursement expansion for home-based sleep testing in Dubai opens a window for digital therapeutics specialists to penetrate the UAE market through telehealth-integrated diagnostic workflows rather than hardware-centric positioning. For Investors and Strategic Acquirers: South African national health insurance reform pilot outcomes are the leading indicator that subscription-based adherence monitoring will scale across SADC public sector procurement, favoring acquisition targets with cloud-connected platform architecture and established HPRA compliance records.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Registration Pathway Investment | Accelerates Gulf market entry timelines for positive airway pressure systems in Riyadh distribution networks. |
| Cloud Platform Integration | Enables recurring revenue capture through remote patient monitoring subscriptions in Dubai reimbursement structures. |
| Humidification Module Backward Integration | Reduces BIS certification exposure for India-origin components serving Johannesburg assembly operations. |
| Hospital System Partnership | Secures enterprise procurement contracts with Saudi Arabia's National Unified Procurement Company. |
| Reimbursement Strategy Development | Aligns product positioning with MOHAP pilot programs for home-based sleep testing eligibility. |
Research Methodology
Document review covered SFDA and MOHAP regulatory filings, IEC 60601 certification databases, and hospital procurement records, complemented by interviews with sleep clinic pulmonologists, biomedical engineers at Cairo tertiary centers, GPO contracts managers in Johannesburg, and regional distribution heads across Dubai and Lagos. Secondary sources included customs trade data for ventilation device imports, Health Products Regulatory Authority safety bulletins, and Gulf Cooperation Council harmonization directives. Bottom-up demand modeling from patient diagnosis rates and top-down market sizing from manufacturer shipment data were triangulated for validation.
Segmentation outputs across product type, end user, distribution channel, and technology dimensions were projected over the analysis window using patient access expansion assumptions tied to national health insurance reform pilots. CAGRs were derived from fitted growth curves incorporating sleep clinic network density, reimbursement pathway maturity, and digital therapeutics penetration rates. Forecast inputs included polysomnography technician availability constraints and cloud connectivity infrastructure deployment timelines.
The model assumes a particular technology adoption path; alternative pathways for adaptive servo ventilation algorithm integration would alter the outlook for cardiovascular center demand in Johannesburg and Pretoria. Forecasts reflect assumptions about SFDA-MOHAP regulatory harmonization pace and South African rand stability. A model refresh is warranted upon material change in Gulf Cooperation Council medical device registration timelines or Nigerian customs classification rulings for ventilation equipment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Cervical Artificial Discs Market
Medical Devices
Global Stereotaxic Instrument Market
Medical Devices
Japan Anesthesia Devices Market
Medical Devices
High Frequency Ventilators Market
Medical Devices
Transcranial Doppler Devices Market
Medical Devices
Non-Rebreathing Oxygen Mask Market
Medical Devices
Deaver Retractor Market
Medical Devices
Global Blood Banking Devices Market
Medical Devices
Benign Prostatic Hyperplasia (BPH) Treatment Devices Market
Medical Devices
Asia-Pacific Refractive Surgery Devices Market
Medical Devices
Cryoablation System Market
Medical Devices
High Pressure Contrast Media Injectors Market
Medical Devices
Peripheral Micro Catheters Market
Medical Devices
MRI Safe Defibrillator Market
Medical Devices
Global Non-Surgical Skin Tightening Devices Market
Medical Devices
High Flow Oxygen Therapy Devices Market