
 MRI Compatible IV Infusion Pumps Market | 2026-2036
MRI Compatible IV Infusion Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
MRI Compatible IV Infusion Pumps Market Analysis
Magnetic field immunity certification up to 3.0 Tesla is redrawing procurement criteria across hospital systems. Becton, Dickinson and Company leverages its infusion platform scale to dominate North American contracts. iRadimed Corporation specializes in MRI-conditional pump engineering and anchors the premium non-magnetic segment. Medtronic Plc. extends its therapy portfolio into radiology-compatible delivery systems, competing on integrated care pathways.
MRI compatible IV infusion pumps are electromechanical drug delivery devices engineered with non-ferrous alloys, fiber-optic sensors, and RF-shielded circuitry to operate safely within static magnetic fields up to 3.0 Tesla or higher, primarily used for continuous therapeutic administration during diagnostic or interventional MRI procedures. Volumetric pumps lead hospital procurement due to established clinical workflows and broader drug compatibility, while syringe pumps capture the fastest growth in pediatric and anesthesia applications where precision dosing outweighs throughput. Smart pump technology with dose error reduction software commands the strongest margin pool as liability and safety protocols harden across acute care settings.
FDA 510(k) premarket notification and CE marking under the EU MDR govern device safety claims, with both frameworks requiring demonstrated magnetic field compatibility and electromagnetic interference immunity as conditions for market access. The EPA and OSHA indirectly shape demand through workplace safety rules on clinical equipment maintenance and electromagnetic exposure limits in healthcare facilities. Stakeholders must monitor evolving MRI field strength standards and corresponding pump certification thresholds as 7.0 Tesla systems expand from research into clinical deployment.
Market Dynamics
FDA 510(k) clearance pathways for non-magnetic medical devices are tightening performance benchmarks and forcing manufacturers to recertify legacy platforms. This regulatory compression is accelerating R&D cycles while hospital procurement teams rewrite vendor qualification criteria around 3.0 Tesla compatibility thresholds.
Growth Catalysts
- EU MDR CE marking expansion:The Medical Device Regulation mandates electromagnetic interference testing that validates pump operation within high-field MRI environments, creating compliance-driven replacement cycles across European hospital networks.
- Pediatric anesthesia suites:Precision dosing requirements in neonatal and pediatric MRI procedures are pulling syringe pump configurations into interventional radiology departments previously served by volumetric alternatives.
- 7.0 Tesla clinical deployment:Research-to-clinic translation of ultra-high-field MRI systems in Germany and Japan is generating demand for next-generation pumps certified beyond current 3.0 Tesla standards.
Market Restraints
- Non-ferrous alloy supply concentration:Titanium and specialized aluminum sourcing depends on a limited supplier base in aerospace-adjacent metallurgy, exposing manufacturers to input cost volatility and allocation constraints.
- Fiber-optic sensor technical limitation:Current optical flow measurement technology exhibits drift under rapid temperature fluctuations within MRI bore environments, complicating long-duration infusion reliability.
- CE marking timeline friction:EU MDR notified body capacity bottlenecks are extending certification cycles, delaying market entry for redesigned pump platforms.
Strategic Opportunities
- India diagnostic imaging expansion:Government hospital modernization programs and private radiology chain growth are creating first-mover advantage for MRI-conditional pump suppliers establishing local service infrastructure.
- Interventional MRI therapy convergence:Real-time MRI-guided cardiac ablation and tumor cryotherapy procedures require synchronized drug delivery, opening integrated system partnerships with surgical device manufacturers.
- Outcome-based equipment leasing:Hospital capital constraint pressures are favoring rental and performance-guarantee models over outright purchase, enabling recurring revenue streams and captive consumable attachment.
Industry Challenges
- RF engineering talent scarcity:Specialized expertise in radiofrequency shielding design and electromagnetic compatibility testing is concentrated within aerospace and defense sectors, complicating recruitment for medical device R&D teams.
- Legacy hospital IT integration:Smart pump connectivity with existing electronic medical record systems and wireless drug library management requires customized interface development, prolonging deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MRI Compatible IV Infusion Pumps Market |
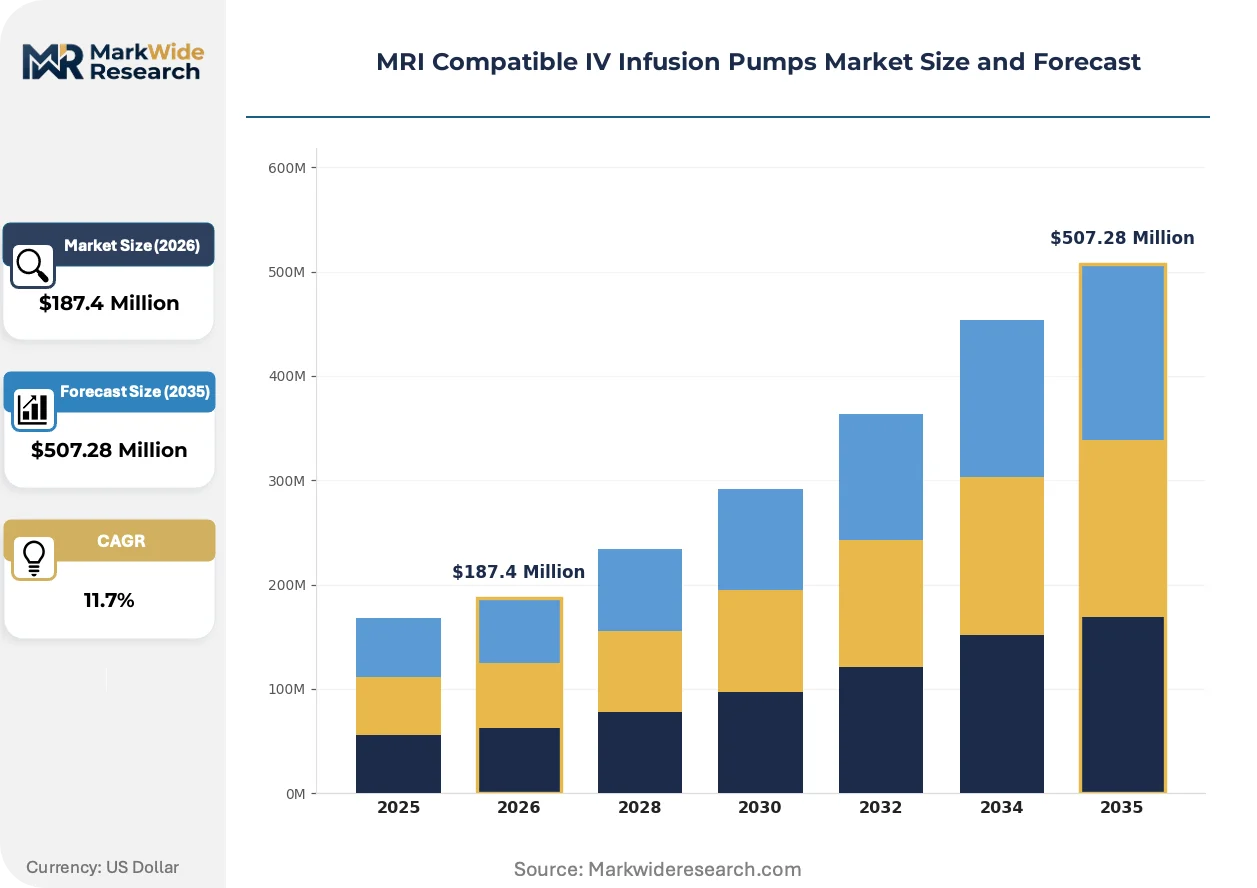
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Volumetric Pumps, Syringe Pumps, Enteral Pumps, PCA Pumps End User: Hospitals, Ambulatory Surgical Centers, Home Care Settings, Clinics Technology: Microprocessor-Controlled, Smart Pumps, Battery-Operated, Infusion Systems Application: Oncology, Pain Management, Nutritional Support, Antibiotic Therapy |
| Companies Covered | Becton, Dickinson and Company, Medtronic Plc., iRadimed Corporation, Arcomed AG, Smiths Medical, B. Braun Melsungen AG, Fresenius SE & Co. KGaA, ICU Medical, Baxter International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MRI Compatible IV Infusion Pumps Market Emerging Trajectories
Magnetic field immunity certification thresholds are climbing as clinical MRI systems migrate toward 7.0 Tesla, forcing hardware architecture redesigns across the installed base. This technical escalation is compressing product lifecycles and redrawing competitive differentiation around materials science capabilities rather than software features alone.
Piezoelectric actuation mechanisms are displacing traditional motor-driven pumping in next-generation MRI-conditional devices. Pediatric and anesthesia specialists at academic medical centers are piloting these platforms for nanoliter-precision applications. The shift is compressing addressable market share for conventional electromagnetic pump architectures that cannot achieve comparable field immunity without excessive shielding mass.
EU MDR Article 10 technical documentation requirements now mandate electromagnetic compatibility validation as a condition for CE marking renewal. Manufacturers face portfolio-wide recertification investments to maintain European market access. German and Swiss hospital procurement consortia are leveraging this compliance burden to consolidate vendor lists around pre-certified platforms, accelerating supplier concentration.
Consolidated purchasing through regional hospital networks is displacing decentralized radiology department procurement autonomy. Integrated delivery networks in the United States and university hospital alliances in France are centralizing infusion pump standardization decisions. Radiology suites within these systems are losing individual vendor selection authority to system-wide clinical engineering committees.
MRI Compatible IV Infusion Pumps Market Segmentation
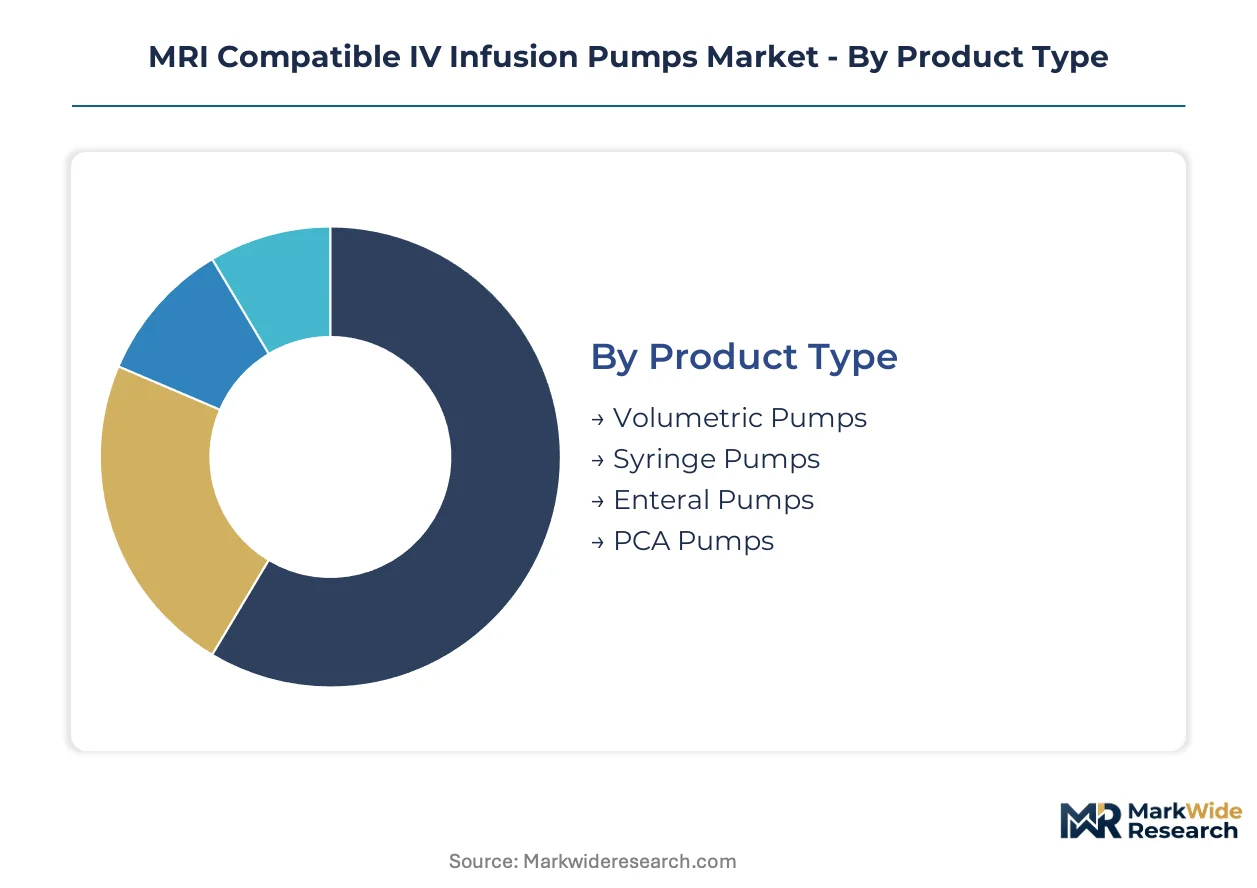
Segmentation in the MRI compatible IV infusion pumps market reveals how procurement decisions diverge across clinical settings and technical specifications. Understanding these divides helps manufacturers align R&D investments with the highest-value pockets of demand.
Product Type:
Margin pools concentrate in configurations that balance precision dosing with magnetic field immunity certification costs.
- Volumetric Pumps:These devices employ peristaltic or piston mechanisms with non-ferrous housings to deliver large-volume infusions in oncology and critical care settings. Hospital radiology departments in the United States and Germany favor these systems for their throughput and established drug library compatibility, though fiber-optic sensor drift under temperature fluctuation complicates long-duration reliability.
- Syringe Pumps:Built around lead-screw actuators with titanium alloy chassis, these pumps achieve nanoliter precision essential for pediatric anesthesia and neonatal MRI procedures. Academic medical centers in Japan are deploying these units for interventional radiology suites where dose accuracy outweighs flow rate capacity.
- Enteral Pumps:Specialized for gastric and jejunal feeding within MRI environments, these systems utilize polymer-based drive mechanisms isolated from magnetic field interference.
- PCA Pumps:Patient-controlled analgesia configurations incorporate tamper-resistant non-magnetic housings for post-operative pain management during extended MRI monitoring.
The dominant share belongs to Volumetric Pumps, while Syringe Pumps is closing the gap fastest.
End User:
Procurement authority is migrating from individual radiology departments toward centralized hospital system committees, reshaping vendor access patterns.
- Hospitals:Integrated delivery networks in the United States and university hospital alliances in France concentrate purchasing decisions for MRI suites, radiology departments, and hybrid operating theaters. Capital constraint pressures are pushing these institutions toward leasing models with performance guarantees.
- Ambulatory Surgical Centers:Freestanding facilities perform interventional MRI-guided procedures requiring portable, battery-conditional pump systems with rapid setup protocols.
- Home Care Settings:Emerging demand for outpatient MRI-compatible infusion reflects expanding home-based chemotherapy administration in markets with favorable reimbursement frameworks.
- Clinics:Private radiology chains in India and diagnostic imaging centers in Germany represent first-mover opportunities for suppliers establishing localized service infrastructure.
Hospitals command the installed base majority, though Ambulatory Surgical Centers are expanding most quickly as outpatient procedure volumes rise.
Technology:
Certification burden under FDA 510(k) and EU MDR is concentrating investment in platforms that preemptively address electromagnetic compatibility validation.
- Microprocessor-Controlled:Foundational architectures with RF-shielded circuitry and fiber-optic communication links form the baseline for 3.0 Tesla compatibility certification.
- Smart Pumps:Dose error reduction software and wireless drug library management command premium pricing in acute care settings where liability protocols have hardened. These systems face integration friction with legacy hospital IT infrastructure.
- Battery-Operated:Lithium-polymer power systems with magnetic isolation enable portable deployment across multiple MRI suites without fixed electrical tethering.
- Infusion Systems:Integrated platforms combining pump hardware with consumable ecosystems and data analytics for outcome-based contracting.
Smart Pumps capture the steepest margin expansion, while Battery-Operated configurations are gaining traction fastest in ambulatory and mobile imaging deployments.
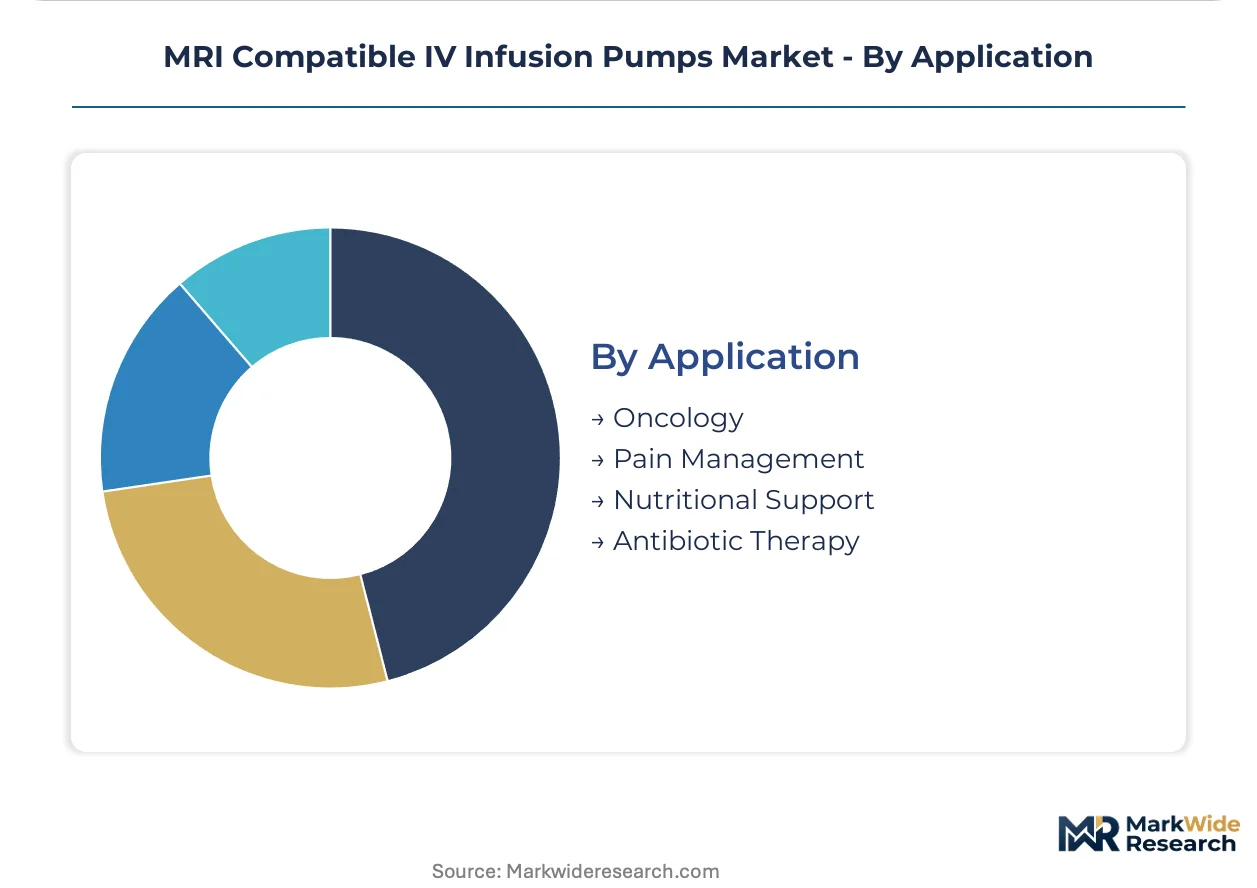
Application:
Clinical workflow complexity determines whether throughput or precision dosing takes priority in pump specification.
- Oncology:Chemotherapy administration during interventional MRI for tumor localization and ablation monitoring requires extended infusion duration with magnetic field stability.
- Pain Management:Continuous regional anesthesia and patient-controlled analgesia in MRI-guided orthopedic and spinal procedures demand rapid-response flow adjustment without electromagnetic interference.
- Nutritional Support:Enteral feeding during prolonged MRI examinations for pediatric and neurologically compromised patients.
- Antibiotic Therapy:Extended-duration antimicrobial infusion for osteomyelitis and joint infection imaging protocols.
Oncology holds the largest procedure volume attachment, while Pain Management is climbing the fastest as interventional MRI expands into orthopedic and spinal surgery suites.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across procurement environments. German hospital systems absorb premium pricing for 3.0 Tesla certification without volume trade-offs. Indian diagnostic chains negotiate aggressively on unit cost while accepting shorter service warranties.
United States
Integrated delivery networks concentrate purchasing for MRI suites across multiple hospital campuses. FDA 510(k) clearance timelines for non-magnetic devices have lengthened, forcing manufacturers to front-load electromagnetic compatibility testing. The Texas Medical Center in Houston operates one of the densest clusters of interventional MRI facilities, driving demand for synchronized drug delivery systems.
Germany
University hospital alliances standardize infusion pump specifications across radiology and anesthesia departments. EU MDR notified body capacity constraints extend CE marking renewal cycles for legacy platforms. The Heidelberg-Mannheim medical technology corridor hosts concentrated R&D activity in piezoelectric actuation for next-generation MRI-conditional devices.
Japan
Academic medical centers deploy syringe pumps for nanoliter-precision applications in pediatric MRI suites. METI funding programs accelerate domestic certification of 7.0 Tesla-compatible delivery systems. The Kansai region, anchored by Osaka University Hospital, leads clinical translation of ultra-high-field MRI-guided interventions.
India
Private radiology chains expand MRI capacity faster than public hospital modernization programs. CDSCO import licensing requirements for electromedical equipment create compliance delays for non-domestic manufacturers. Maharashtra's Mumbai-Pune corridor attracts first-mover suppliers establishing localized service infrastructure for MRI-conditional pump maintenance.
Switzerland
Swissmedic maintains stringent electromagnetic compatibility validation requirements that exceed baseline EU MDR thresholds. University Hospital of Zurich and Geneva University Hospitals operate as early adopters for 7.0 Tesla clinical systems. The Basel-Zurich pharmaceutical-medtech cluster generates demand for infusion pumps integrated with MRI-guided drug development protocols.
MRI Compatible IV Infusion Pumps Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the MRI compatible IV infusion pumps market. Large diversified medical device corporations leverage infusion platform scale to dominate North American hospital contracts. Specialized non-magnetic engineering firms occupy premium positioning through dedicated MRI-conditional certification. Mid-tier European manufacturers compete on modular system integration for hybrid operating theaters. Competitive moves concentrate on strategic partnerships with surgical device manufacturers and outcome-based equipment leasing models that convert capital sales to recurring revenue streams.
Among diversified medical technology conglomerates, Becton, Dickinson and Company and Medtronic Plc. exemplify scale-driven archetypes with broad therapy portfolio extension into radiology-compatible delivery. iRadimed Corporation occupies a specialist position as a dedicated non-magnetic pump engineering firm. These three entities represent contrasting strategic postures: platform breadth versus focused certification depth versus integrated care pathway positioning.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Medtronic Plc. |
| iRadimed Corporation |
| Arcomed AG |
| Smiths Medical |
| B. Braun Melsungen AG |
| Fresenius SE & Co. KGaA |
| ICU Medical |
| Baxter International Inc. |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation contracts with aerospace-adjacent titanium suppliers lock in both fiber-optic sensor access and price visibility for manufacturers targeting 3.0 Tesla certification. These arrangements insulate Becton, Dickinson and Company and iRadimed Corporation from spot-market volatility in non-ferrous alloys while committing capital years ahead of FDA 510(k) submission timelines.
Pricing Analysis
FDA 510(k) clearance dictates the pricing tier structure across the MRI compatible IV infusion pumps landscape. Three-tier pricing structure across premium, standard, and economy levels separates 7.0 Tesla-certified systems with piezoelectric actuation from legacy 3.0 Tesla electromagnetic platforms and refurbished hospital auction units. Price differentiation hinges on electromagnetic compatibility validation depth and after-sales service bundling with localized biomedical engineering support. Cost compression in the standard tier is intensifying because EU MDR notified body bottlenecks delay recertification revenue recognition. Pediatric anesthesia departments at academic medical centers exhibit lowest price sensitivity, while private radiology chains in India negotiate aggressively on unit cost.
Supply Chain Analysis
Inventory buffers for fiber-optic flow sensors stretch to six months given single-source dependencies on Japanese photonics manufacturers. Titanium alloy chassis fabrication concentrates in Germany, Switzerland, and the United States, drawing from aerospace metallurgy suppliers with dual-use export control exposure. Lithium-polymer battery cells, RF-shielding copper mesh, and piezoelectric ceramic actuators constitute critical component dependencies. Single-source vulnerability in fiber-optic sensor production creates chokepoint risk if METI-funded domestic capacity expansion disrupts cross-border allocation. Distribution runs through hospital GPO contracts in North America, university hospital alliance frameworks in Germany, and direct service infrastructure investments in India's Maharashtra corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as integrated delivery networks in the United States and university hospital alliances in France displace decentralized radiology department procurement autonomy. This consolidation fragments vendor access and hardens price-performance benchmarks.
For Market Incumbents: Consolidate certification depth as the primary defensive moat. Accelerate 7.0 Tesla validation programs ahead of clinical deployment in Germany and Japan to preempt emerging piezoelectric specialists. Deepen backward integration into fiber-optic sensor supply through captive partnerships with photonics manufacturers, reducing single-source vulnerability while capturing margin pool expansion from smart pump software attach rates. For New Entrants and Emerging Players: Lead with localized service infrastructure as the go-to-market wedge. Target India's private radiology chains in the Mumbai-Pune corridor where CDSCO import licensing delays create first-mover advantage for domestic assembly partnerships. Focus on battery-operated portable configurations for ambulatory surgical centers, the fastest-expanding end-user segment with lowest incumbent lock-in. For Investors and Strategic Acquirers: Capital is best deployed toward specialized non-magnetic engineering firms with completed EU MDR technical documentation and established piezoelectric actuation R&D pipelines. Long-term viability over the projection horizon rests on electromagnetic compatibility validation capabilities rather than scale economics alone. Watch FDA 510(k) clearance timeline compression as the signal for competitive inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Premarket Submission | Clearance validates electromagnetic immunity claims for 3.0 Tesla hospital contracts. |
| EU MDR CE Marking Pathway | Notified body certification unlocks German and Swiss university hospital procurement. |
| Hospital System Partnership | Integrated delivery network standardization displaces radiology department autonomy. |
| Software Companion Development | Dose error reduction modules command premium pricing in acute care liability environments. |
| Reimbursement Strategy | CMS coding alignment determines outpatient MRI infusion coverage expansion. |
Methodological Framework
Initial hypotheses were tested against primary input from hospital biomedical engineers, radiology department heads, GPO contracts managers, and infusion therapy specialists and refined through secondary validation. FDA 510(k) premarket notification databases, EU MDR notified body technical documentation, hospital procurement contract registries, and CMS reimbursement coding records anchored quantitative triangulation. Bottom-up patient procedure volume estimates and top-down medical device spending allocations were cross-referenced for convergence.
Variance decomposition across the analysis window isolates volume, price, and mix effects within each segmentation dimension. The modeling framework incorporates product type, end-user facility tier, technology certification level, magnetic field strength compatibility, and regional regulatory cluster as core stratification variables. CAGRs were derived from logistic diffusion curves fitted to installed base replacement cycles and clinical MRI system upgrade trajectories. Forecast inputs include EU MDR notified body capacity constraints and METI funding disbursement patterns for 7.0 Tesla clinical translation.
The analysis sits within stated boundaries; outcomes outside sustained FDA 510(k) clearance timeline stability or accelerated 7.0 Tesla clinical deployment would require recalibration. Forecasts reflect documented assumptions regarding electromagnetic compatibility validation cost trajectories and fiber-optic sensor reliability improvements. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Intravenous Access Devices Market
Medical Devices
Disposable Lancets Market
Medical Devices
Venturi Mask Market
Medical Devices
At-Home Blood Collection Kits and Devices Market
Medical Devices
Global Healthcare Nanotechnology (Nanomedicine) Market
Medical Devices
Incubator Devices Market
Medical Devices
Craniomaxillofacial Plate and Installation Tools Market
Medical Devices
Electronic Pill Market
Medical Devices
Digital Orthodontics Market
Medical Devices
Minimally Invasive Neurosurgery Devices Market
Medical Devices
Endoscope Reprocessing Device Market
Medical Devices
Reusable Resuscitators Market
Medical Devices
Occlusion Balloon Catheter Market
Medical Devices
Respiratory Inhaler Devices Market
Medical Devices
Urinary Incontinence Devices Market
Medical Devices
Non-Invasive Ultrasound Stimulation Market