
 Motorcycle Catalyst Market | 2026-2036
Motorcycle Catalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Motorcycle Catalyst Market Insights
European substrate producers is pivoting toward metal-supported catalyst architectures for high-displacement motorcycles. BASF leverages its washcoat chemistry portfolio to anchor premium OEM supply contracts across German and Italian motorcycle brands. Johnson Matthey competes through specialized palladium-rhodium formulations that sustain thermal durability under stop-start urban riding conditions.
A motorcycle catalyst is an emissions control device mounted within the exhaust system, typically comprising a ceramic or metallic monolith substrate coated with precious metal washcoats containing platinum, palladium, and rhodium, designed to convert carbon monoxide, hydrocarbons, and nitrogen oxides into harmless gases through redox reactions at operating temperatures between 200°C and 600°C. Three-way catalysts dominate current OEM fitment due to their simultaneous oxidation and reduction capability in stoichiometric air-fuel conditions. Metal-supported configurations occupy the fastest-growing technology tier as manufacturers seek reduced thermal mass for quicker light-off compliance.
Euro 5 standards enforced by the European Commission, EPA Tier 3 motorcycle regulations in the United States, and Bharat Stage VI norms administered by India's Central Pollution Control Board collectively mandate measurable reductions in hydrocarbon and nitrogen oxide emissions. These frameworks compel catalyst suppliers to validate conversion efficiency across broader temperature and flow rate windows. Stakeholders must monitor evolving test-cycle protocols and precious metal sourcing constraints to calibrate product roadmaps and supply agreements.
Market Dynamics
Metal-supported catalyst architectures are compressing thermal mass requirements and forcing substrate suppliers to retool production lines for thinner foil geometries that achieve Euro 5 light-off targets.
Growth Catalysts
- Euro 5 Enforcement:The European Commission's tightened tailpipe standards mandate 75% hydrocarbon reduction from Euro 4 baselines, compelling OEMs to fit three-way catalysts on all displacement classes.
- India's Bharat Stage VI Rollout:The Central Pollution Control Board's real-driving-emission protocols extend catalyst durability requirements to 160,000 kilometers, expanding addressable hardware volumes.
- Stop-Start Urban Riding Patterns:Thermal cycling degradation in congested Southeast Asian traffic forces palladium-rhodium formulation upgrades that sustain conversion efficiency across broader temperature windows.
Market Restraints
- Palladium Supply Concentration:Russian and South African mining output volatility exposes washcoat suppliers to input cost spikes that compress margin structures on fixed-price OEM contracts.
- Ceramic Substrate Obsolescence Risk:Cordierite monoliths face displacement from metallic alternatives in displacement segments above 500cc where thermal shock resistance determines compliance.
- EPA Tier 3 Test-Cycle Expansion:The United States Environmental Protection Agency's cold-start emission measurement extensions lengthen validation timelines and freeze specification lock-ins.
Strategic Opportunities
- Vietnam Manufacturing Cluster Expansion:Honda and Yamaha supplier parks in Vinh Phuc Province lack captive catalyst production, creating white space for localized substrate coating facilities.
- Electric Motorcycle Aftermarket Retrofit:Range-extender hybrids and fuel-cell two-wheelers require oxidation catalysts for reformate cleanup, opening adjacent application demand.
- Indonesia's Domestic Content Requirements:Ministry of Industry localization mandates for LCGC motorcycle platforms force foreign OEMs to source catalysts from qualified domestic suppliers.
Industry Challenges
- Precious Metal Assay Expertise Scarcity:Washcoat formulation chemists with palladium-rhodium ratio optimization experience command premium compensation that strains mid-tier supplier cost structures.
- Homologation Timeline Compression:Euro 5+ and Bharat Stage VI Phase 2 convergence in 2024-2025 test windows overloads certification laboratory capacity and delays product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorcycle Catalyst Market |
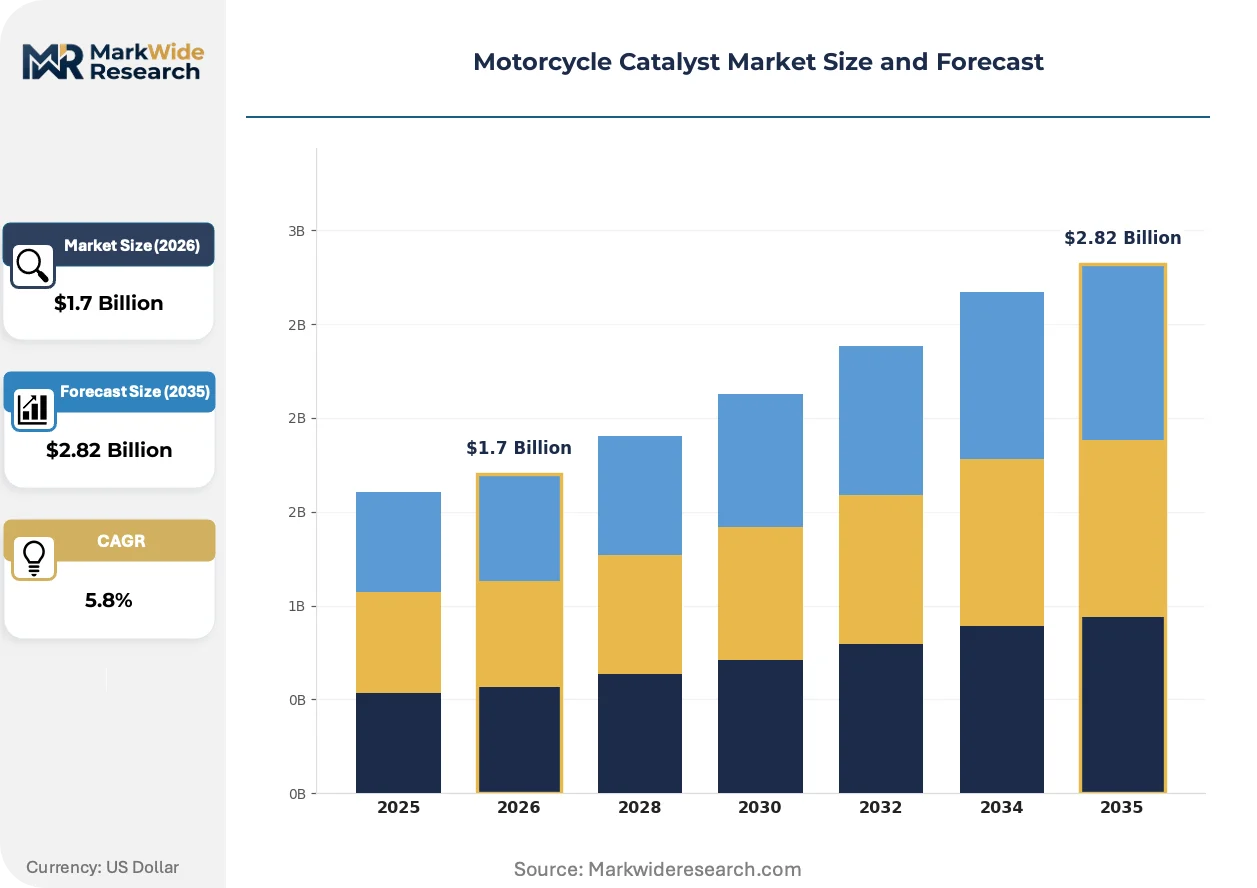
| Market Size in 2026 | $1.7 Billion |
| Market Size in 2035 | $2.82 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Three-way Catalysts, Diesel Oxidation Catalysts, Selective Catalytic Reduction Catalysts, Exhaust Gas Oxygen Sensors Technology: Metal Supported, Ceramic Supported, Hybrid, Washcoat Technology Application: Motorcycle Manufacturing, Aftermarket Services, Fuel Efficiency Improvement, Emissions Control End User: OEMs, Tier-1 Suppliers, Service Centers, Individual Consumers |
| Companies Covered | BASF, Johnson Matthey, Umicore, Cataler Corporation, Heraeus Holding, NGK Insulators, Tenneco, Clariant, Haldor Topsoe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorcycle Catalyst Market Trends and Innovations
Substrate architecture, regulatory test protocols, and procurement specifications are simultaneously tightening, forcing suppliers to coordinate R&D roadmaps across three disconnected clock speeds.
Corrugated metal foil substrates with optimized channel geometry are expanding into high-performance motorcycle segments where rapid light-off compliance determines market access. Italian and German OEMs specify these configurations for 800cc-plus engines that cycle through urban traffic. The technology is expanding into mid-displacement commuter platforms as Euro 5+ draft requirements signal tighter cold-start limits.
REACH authorization requirements for hexavalent chromium in catalyst housing coatings are forcing stainless steel supplier qualifications across European supply chains. The European Chemicals Agency's sunset date enforcement compresses surface treatment vendor transition timelines. Catalyst integrators in Germany and Italy now dual-source housing materials to mitigate authorization uncertainty.
Volume-based precious metal procurement contracts are fragmenting as OEMs shift to conversion-efficiency guarantees with penalty clauses. Tier 1 exhaust system suppliers absorb metal price volatility in exchange for performance warranties. This reconfiguration concentrates most visibly in Indian OEM supply agreements where Bharat Stage VI durability claims extend to seven-year vehicle lifespans.
Motorcycle Catalyst Market Segmentation
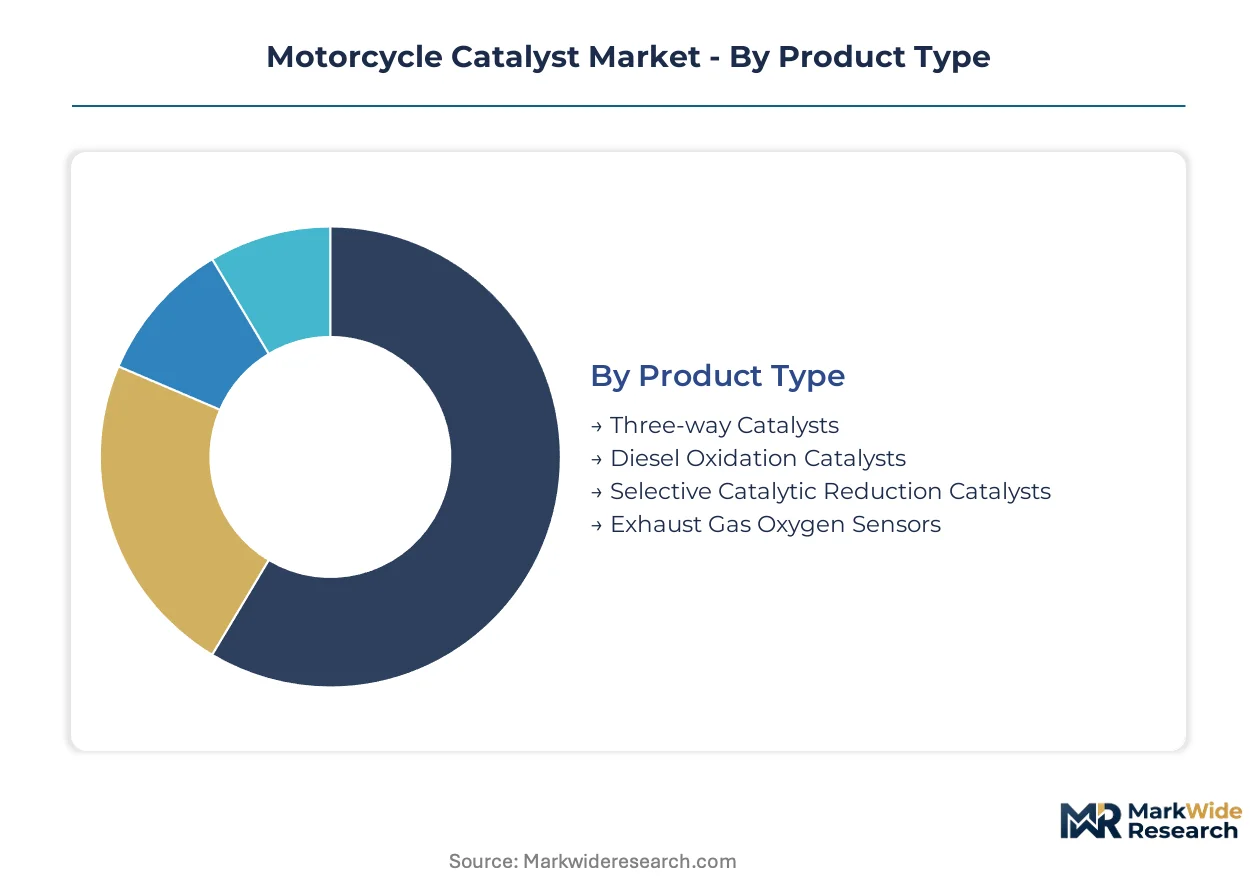
Segmentation in the motorcycle catalyst market reflects divergent compliance pressures across displacement classes and manufacturing tiers. Suppliers must align substrate architectures with distinct thermal durability requirements while calibrating procurement channels to OEM captive production versus fragmented aftermarket demand.
Product Type:
OEM sourcing decisions pivot on simultaneous oxidation-reduction capability under stoichiometric conditions, with displacement-specific thermal profiles dictating washcoat formulation complexity.
- Three-way Catalysts:Platinum-palladium-rhodium washcoats enable simultaneous CO, HC, and NOx conversion in closed-loop fuel-injected engines. Euro 5 mandates across Germany, Italy, and India are concentrating demand in 125cc-500cc commuter platforms where cost-per-unit constraints dominate supplier negotiations.
- Diesel Oxidation Catalysts:Platinum-based formulations oxidize particulate matter and hydrocarbons in compression-ignition motorcycle engines, predominantly Thai and Indian commercial three-wheeler applications. Bharat Stage VI enforcement by India's Central Pollution Control Board is expanding fitment rates in 400cc-plus diesel commuter segments.
- Selective Catalytic Reduction Catalysts:Urea-dosing architectures for large-displacement diesel motorcycles remain niche, constrained by packaging volume and AdBlue infrastructure gaps in Southeast Asian markets.
- Exhaust Gas Oxygen Sensors:Zirconia-based lambda sensors enable closed-loop catalyst control; demand concentrates in Euro 5 and EPA Tier 3 markets requiring real-time air-fuel ratio correction.
Three-way catalysts lead on scale; diesel oxidation catalysts lead on momentum in commercial vehicle applications.
Technology:
Thermal mass reduction and light-off speed requirements are reconfiguring substrate selection criteria across displacement tiers.
- Metal Supported:Corrugated ferritic stainless steel foils achieve 40% faster light-off than ceramic alternatives through reduced thermal mass. Italian and German OEMs specify these for 800cc-plus performance motorcycles where Euro 5 cold-start limits determine market access.
- Ceramic Supported:Cordierite monoliths retain cost advantage in high-volume Asian commuter production, though thermal shock vulnerability above 600°C limits deployment in premium displacement segments.
- Hybrid:Composite metal-ceramic substrates optimize cost-performance balance for mid-displacement platforms, gaining traction in Indian and Vietnamese OEM supply chains.
- Washcoat Technology:Alumina-ceria-zirconia carrier formulations with precious metal dispersion engineering determine conversion efficiency; REACH authorization pressures on hexavalent chromium coatings are forcing European housing supplier transitions.
Metal supported architectures are climbing the fastest; ceramic supported retains volume dominance in cost-sensitive production.
Application:
Regulatory enforcement timelines and vehicle lifecycle positioning create divergent margin structures across installation channels.
- Motorcycle Manufacturing:OEM fitment accounts for catalyst volume concentration, with Euro 5, Bharat Stage VI, and EPA Tier 3 mandates driving specification lock-ins during platform development cycles.
- Aftermarket Services:Replacement demand emerges from catalyst theft, thermal degradation, and regulatory retrofit requirements; service networks in São Paulo and Mexico City report elevated replacement rates due to stop-start traffic degradation.
- Fuel Efficiency Improvement:Secondary catalyst positioning for lean-burn optimization remains experimental, constrained by motorcycle engine control system complexity.
- Emissions Control:Standalone retrofit systems for pre-regulation vehicle fleets face homologation barriers in European and North American jurisdictions.
Manufacturing leads on scale; aftermarket services leads on margin expansion potential.
End User:
Procurement authority concentration and technical specification control determine supplier relationship structures.
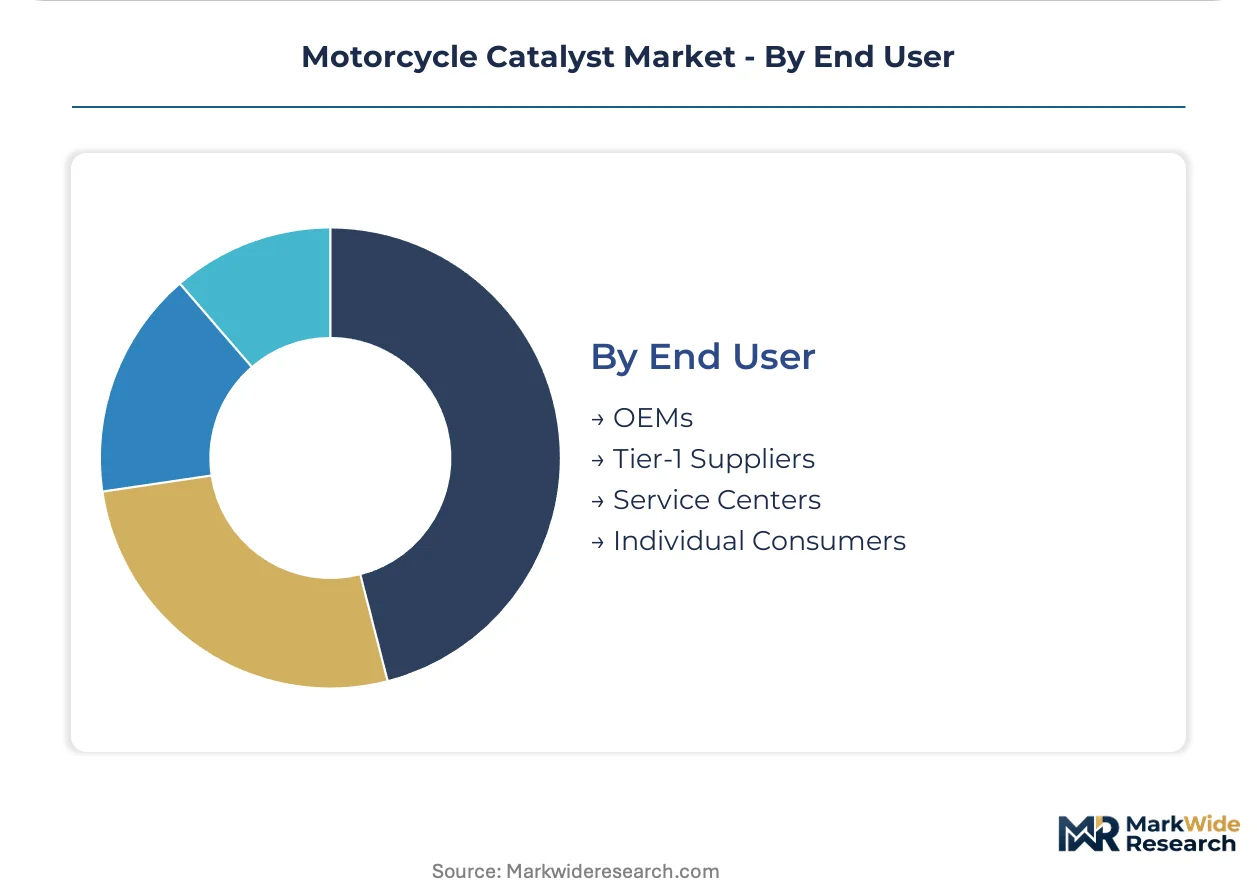
- OEMs:Honda, Yamaha, and Bajaj Auto exercise direct catalyst sourcing authority for captive engine platforms, negotiating conversion-efficiency guarantees with precious metal price volatility absorption clauses.
- Tier-1 Suppliers:Akrapovič, Termignoni, and domestic Indian exhaust system integrators specify substrates and washcoats under OEM-directed supply agreements, managing homologation documentation.
- Service Centers:Authorized dealer networks and independent repair chains procure replacement catalysts through distributor channels, with pricing sensitivity varying by vehicle age and regulatory inspection stringency.
- Individual Consumers:Direct retail purchases remain marginal, concentrated in enthusiast segments seeking performance exhaust upgrades with integrated catalyst solutions.
OEMs lead on scale; Tier-1 suppliers lead on technical specification influence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping catalyst production geography as manufacturers migrate toward jurisdictions with lower compliance costs yet retained export access to regulated markets. This dynamic concentrates investment in Asian manufacturing clusters where domestic volume and certified export capacity overlap.
India
Bajaj Auto and Hero MotoCorp are scaling Bharat Stage VI-compliant platforms for domestic sale and African export. The Central Pollution Control Board's durability mandates to 160,000 kilometers force palladium-rich formulation upgrades. Catalyst coating facilities cluster in Pune and Chennai supplier parks adjacent to Honda and Yamaha assembly lines.
Germany
BMW and KTM specify metal-supported architectures for 800cc-plus engines facing Euro 5+ cold-start limits. KBA type-approval protocols compress homologation timelines for new substrate geometries. Stuttgart and Munich host washcoat R&D centers serving captive premium OEM supply chains.
Vietnam
Honda and Yamaha supplier parks in Vinh Phuc Province lack localized catalyst production, creating white space for substrate coating joint ventures. Ministry of Industry localization mandates for LCGC platforms accelerate domestic sourcing requirements. Ho Chi Minh City distributors manage aftermarket replacement flows into Cambodian and Laotian markets.
Italy
Ducati and Piaggio demand rapid light-off compliance for urban stop-start riding profiles. ECHA REACH authorization pressures on hexavalent chromium coatings force stainless steel housing supplier transitions. Modena and Bologna exhaust system integrators specify corrugated foil substrates under German OEM-directed agreements.
Thailand
Commercial three-wheeler diesel oxidation catalyst demand expands under tightening commercial vehicle norms. Board of Investment incentives attract Japanese catalyst suppliers to Eastern Seaboard industrial zones. Bangkok-based Tier-1 exhaust fabricators manage specification lock-ins for ASEAN export programs.
Motorcycle Catalyst Market Competitive Landscape
German and Belgian producers anchor the premium chemistry tier; Japanese and Korean substrate specialists hold volume manufacturing positions. The supplier base concentrates around three strategic archetypes: precious metal washcoat formulators, monolith substrate fabricators, and integrated exhaust system integrators. Capacity expansion and backward integration into precious metal procurement represent the dominant competitive vectors.
Within the washcoat formulation tier, BASF and Johnson Matthey exemplify archetypes of European chemical conglomerates with captive catalyst divisions. Umicore occupies a position bridging precious metal trading and applied coating technology. These three entities represent the concentration of OEM-facing specification authority, though their market presence manifests through divergent geographic emphases and partnership structures rather than direct product competition.
| Leading Market Players |
|---|
| BASF |
| Johnson Matthey |
| Umicore |
| Cataler Corporation |
| Heraeus Holding |
| NGK Insulators |
| Tenneco |
| Clariant |
| Haldor Topsoe |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed producers in India and Thailand anchor volume manufacturing, compressing margin structures for private-equity-rolled-up European specialists who must absorb palladium price volatility through fixed-price OEM contracts. This ownership bifurcation creates divergent pricing discipline: state-supported coating facilities accept lower returns to secure employment and export revenue, while Western chemical conglomerates defend premium positioning through conversion-efficiency guarantees.
Pricing Analysis
Distributor margins in aftermarket channels absorb the widest spread, with authorized dealer networks commanding markup premiums over independent repair chains in São Paulo and Mexico City. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and precious metal loading, with Euro 5-compliant systems separating from Bharat Stage VI economy tiers. Pricing pressure stems from palladium supply concentration in Russian and South African mining jurisdictions. Tier-1 exhaust integrators exhibit lowest price sensitivity due to pass-through clauses, while individual consumers in enthusiast segments show highest elasticity.
Supply Chain Analysis
Certification gating through KBA type-approval in Germany, Central Pollution Control Board validation in India, and EPA Tier 3 compliance in the United States fragments supplier qualification timelines. Production concentrates in India, Germany, and Vietnam, with substrate coating facilities clustering adjacent to Honda and Yamaha assembly parks. Raw material dependencies center on palladium and rhodium from South African concentrates, ferritic stainless steel foils from Japanese mills, and alumina-ceria-zirconia carriers from Belgian chemical processors. Single-source vulnerability in precious metal assay expertise strains mid-tier supplier cost structures. Distribution runs through captive OEM supply agreements for manufacturing volumes and fragmented distributor networks for aftermarket replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards geographic arbitrage between India's localization-mandated domestic content requirements and Vietnam's white-space supplier park deficits, exploiting a regulatory cost differential that forces foreign OEMs to source from qualified domestic suppliers in one jurisdiction while lacking localized production in the other.
For Market Incumbents: Deepen backward integration into precious metal procurement to offset washcoat margin compression from fixed-price OEM contracts. Lock in corrugated foil substrate capacity expansion in Vinh Phuc Province ahead of Honda and Yamaha localization mandates. Counter ceramic substrate obsolescence risk through hybrid metal-ceramic composite development for mid-displacement Indian commuter platforms. For New Entrants and Emerging Players: Direct-to-Tier-1 digital procurement platforms offer the lowest-friction entry vector into the Vietnamese aftermarket, bypassing established distributor relationships in Ho Chi Minh City. Target the 125cc-250cc economy motorcycle segment where cost-per-unit constraints have delayed metal-supported architecture adoption. Pursue coating facility joint ventures with Eastern Seaboard Board of Investment incentive zones in Thailand. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier washcoat formulators lacking palladium-rhodium ratio optimization expertise but holding valid Central Pollution Control Board and KBA certifications. Five-to-ten year viability hinges on metal-supported substrate technology transition completion. Monitor Euro 5+ draft cold-start limit announcements as the inflection signal for accelerated metal-foil substrate demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precious Metal Procurement | Absorbs palladium price volatility that compresses fixed-price OEM contract margins. |
| Corrugated Foil Substrate Capacity Expansion | Captures Euro 5+ rapid light-off compliance requirements for 800cc-plus German and Italian motorcycles. |
| Localized Coating Facility Joint Venture | Addresses Vietnam's white-space deficit in Vinh Phuc Province supplier parks. |
| Hybrid Metal-Ceramic Composite Development | Optimizes cost-performance balance for Bharat Stage VI mid-displacement Indian commuter platforms. |
| REACH-Compliant Housing Supplier Qualification | Mitigates ECHA authorization uncertainty on hexavalent chromium surface treatments. |
Research Methodology
Multiple input streams — washcoat formulation chemists at European chemical conglomerates, procurement leads at Japanese and Indian OEMs, Tier-1 exhaust system integrators in Italy and Germany, and aftermarket distributors in São Paulo and Ho Chi Minh City — were reconciled against customs records, Central Pollution Control Board certification databases, KBA type-approval filings, and vehicle production statistics from IHS Markit. Bottom-up unit economics across displacement classes and top-down precious metal consumption estimates were triangulated to calibrate market sizing.
Data-stream reconciliation across the projection horizon applied segmentation by catalyst architecture, displacement class, regulatory compliance tier, and regional manufacturing cluster. CAGRs were derived from fitted growth curves against enforcement timelines for Euro 5, Bharat Stage VI Phase 2, and EPA Tier 3 test-cycle expansions. Forecast inputs incorporated palladium loadings per substrate geometry, thermal durability testing failure rates, and localization mandate compliance deadlines.
The model assumes a particular technology adoption path; alternative pathways for electric motorcycle range-extender hybridization would alter the outlook for oxidation catalyst demand in reformate cleanup applications. Forecasts reflect assumptions on regulatory enforcement adherence, precious metal supply continuity, and OEM platform development cycles. A model refresh is warranted upon material change in Euro 5+ cold-start limit specifications or Central Pollution Control Board durability mandate extensions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Saudi Arabia Automotive Lubricants Market
Automotive Parts
Automotive Engine Cam Cover Market
Automotive Parts
Global Automotive Parts Remanufacturing Market
Automotive Parts
Automotive Control Arms Market
Automotive Parts
Automotive Fuel Delivery System Market
Automotive Parts
France Automotive Parts Aluminium Die Casting Market
Automotive Parts
Automotive Piston Engine System Market
Automotive Parts
Connecting Rods Market
Automotive Parts
Poland Passenger Vehicles Lubricants Market
Automotive Parts
Australia Automotive Parts Magnesium Die Casting Market
Automotive Parts
Mexico Automotive Actuators Market
Automotive Parts
Automotive Mechanical Control Cable Market
Automotive Parts
AWD Coupling System Market
Automotive Parts
South Korea Automotive Airfilters Market
Automotive Parts
Automotive Oil and Valve Stem Seals Market
Automotive Parts
Global Rubber Transmission Belts Market