
 Saudi Arabia Automotive Lubricants Market | 2026-2036
Saudi Arabia Automotive Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Automotive Lubricants Market Analytics
The Saudi Green Initiative is decoupling lubricant demand from pure volume growth by mandating lifecycle performance standards across government fleets. Petromin Corporation leverages its integrated refining and blending footprint to dominate domestic supply chains. TotalEnergies competes through specialized high-temperature formulations calibrated for desert operating conditions. ExxonMobil Corporation anchors its position via direct partnerships with original equipment manufacturers serving the Kingdom's expanding heavy-duty segment.
Saudi Arabia automotive lubricants are formulated hydrocarbon-based or synthetic fluid systems engineered to reduce friction, dissipate heat, and prevent wear in internal combustion and transmission assemblies, with viscosity grades typically spanning SAE 0W-20 to 15W-40 for passenger applications. Engine Oil occupies the largest value share due to shortened drain intervals in high-ambient-temperature environments, while Synthetic Oil registers the fastest structural expansion as fleet operators prioritize extended service life and fuel economy gains. Passenger Vehicles retain volume leadership, though Heavy-Duty Vehicles concentrate margin pools through bulk procurement contracts and technical service agreements.
Saudi Standards, Metrology and Quality Organization (SASO) specifications, SFDA environmental compliance protocols, and the Saudi Energy Efficiency Center's transport directives collectively shape product formulation requirements and market access conditions. The Kingdom's national petroleum regulator enforces base oil quality benchmarks that align lubricant performance with Vision 2030 industrial localization targets. Stakeholders must monitor regulatory alignment between domestic specifications and evolving OEM warranty standards to preserve competitive positioning.
Market Dynamics
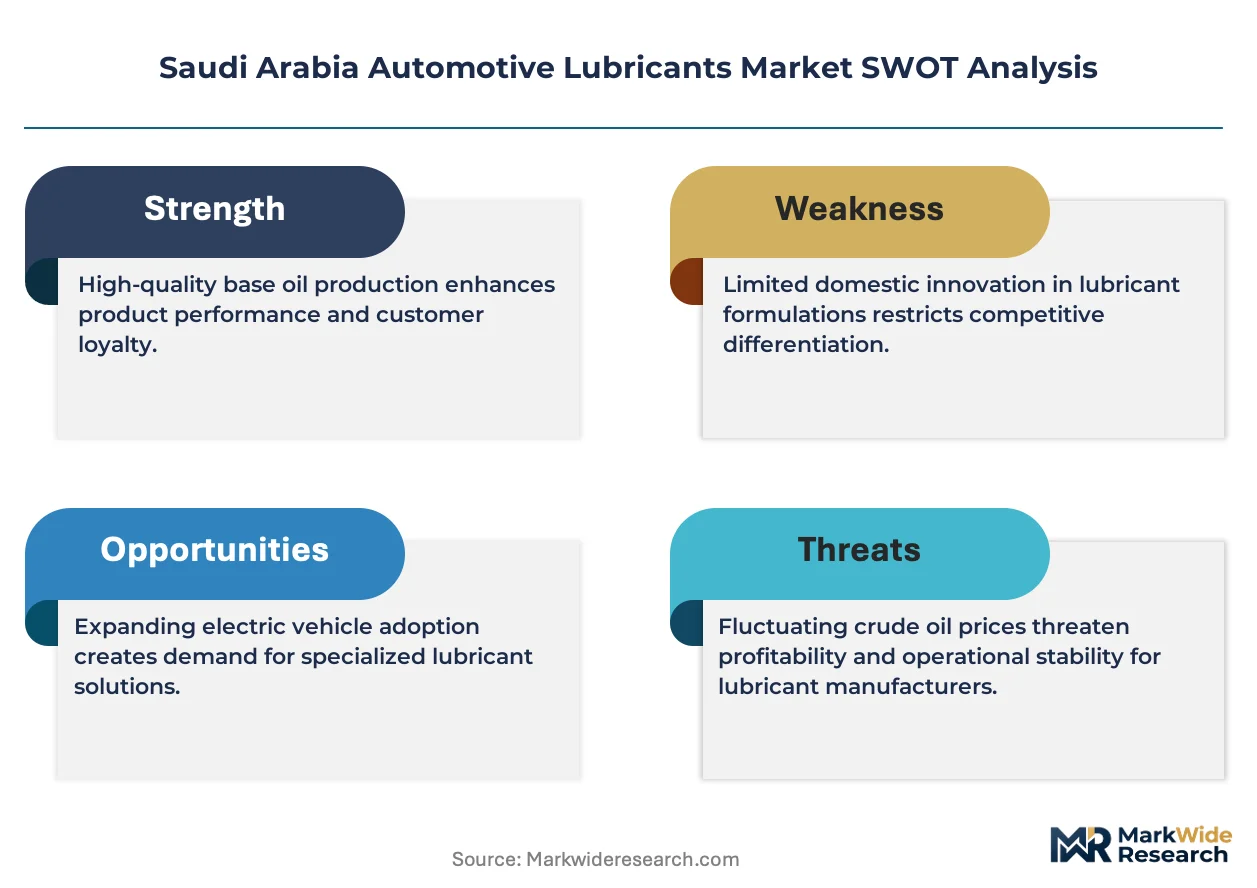
SASO's Euro 5-equivalent emission standards are compressing formulation tolerances and forcing rapid portfolio turnover across domestic blenders. The mandate's viscosity-grade implications are redistributing competitive advantage toward integrated refiners with captive Group II/III base oil supply.
Growth Catalysts
- Fleet Preventive Maintenance Expansion:Commercial vehicle operators in the Eastern Province are institutionalizing oil analysis programs. This extends drain intervals while increasing premium synthetic volumes per vehicle.
- Petrochemical Integration:Jubail Industrial City's base oil production clusters enable just-in-time blending operations. Domestic supply security reduces import dependency for critical Group III feedstocks.
- Saudi Green Initiative Mandates:Government fleet lifecycle performance standards are creating certified-lubricant procurement preferences. Compliance unlocks multi-year supply contracts with state transport entities.
Market Restraints
- Base Oil Import Concentration:Specialty additive packages and advanced ester base stocks remain concentrated with European and US suppliers. Currency volatility amplifies landed cost unpredictability for domestic blenders.
- Technical Substitution Pressure:Battery electric commercial vehicle pilots in Riyadh logistics corridors threaten long-term engine oil demand. Thermal management fluids for electric drivetrains require entirely different formulation competencies.
- Drain Interval Extension:Synthetic oil performance gains are compressing absolute volume demand. Fleet operators achieve 15,000+ kilometer intervals versus 5,000-kilometer conventional schedules.
Strategic Opportunities
- Neom Megacity Construction Equipment:Heavy-duty mining and earthmoving fleets in the northwest corridor require severe-duty lubricants. Technical service agreements with project consortiums offer multi-year revenue visibility.
- Red Sea Coastal Marine Applications:Fishing vessel and port handling equipment segments remain underpenetrated by synthetic formulations. Salt-air corrosion protection creates premium positioning opportunities.
- SASO Certification Pre-Positioning:Early alignment with evolving warranty standards from European OEMs serving the Kingdom creates competitive moats. Certification investments block smaller blenders from premium segments.
Industry Challenges
- Formulation Chemist Scarcity:Blending operations in Dammam and Jeddah compete for talent with upstream petrochemical salaries. Specialized lubricant chemistry expertise requires expatriate recruitment with visa complexity.
- Legacy Testing Infrastructure:Domestic laboratories lack full OECD 301 biodegradability certification capacity. Export-oriented synthetic lines face delays validating environmental claims for EU-bound shipments.
- Channel Inventory Reconfiguration:Traditional distributor networks carry 90-day conventional oil stocks. Rapid synthetic-grade transitions strand working capital and erode distributor margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Automotive Lubricants Market |
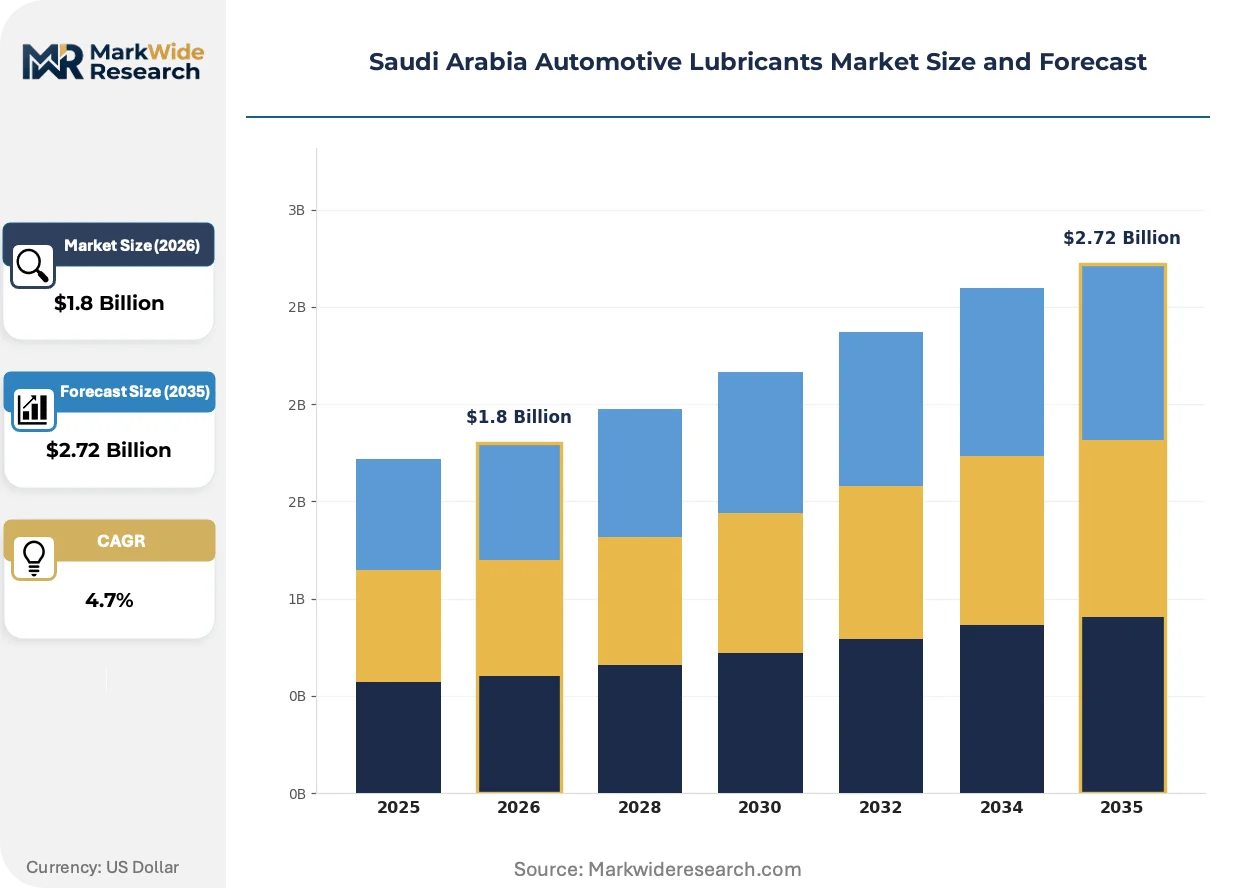
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Gear Oil, Brake Fluid Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy-Duty Vehicles Base Oil: Mineral Oil, Synthetic Oil, Semi-Synthetic Oil, Bio-Based Oil Distribution Channel: Retail Stores, Online Platforms, Auto Service Centers, Wholesalers |
| Companies Covered | Petromin Corporation, TotalEnergies, ExxonMobil Corporation, PETRONAS Lubricants International, Chevron Corporation, BP PLC (Castrol), Royal Dutch Shell PLC, AMSOIL Inc, FUCHS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Automotive Lubricants Market Evolving Landscape
Formulation chemistry is pivoting toward lower-viscosity grades that satisfy thermal stress demands without sacrificing hardware protection. This technical tension is driving additive package innovation and base oil quality tiering across domestic supply chains.
Polyalphaolefin (PAO) synthetic base stocks are absorbing the performance requirements previously met by heavier mineral formulations. Heavy-duty fleet operators in the Kingdom's central corridor are specifying PAO-based 5W-30 grades for new Euro 5-compliant tractors. The technology is absorbing margin compression from extended drain intervals by commanding per-liter premiums that offset volume declines.
SASO's alignment with ACEA European Oil Sequences is tightening NOACK volatility specifications and sulfated ash limits. Domestic blenders must reformulate mid-tier passenger car motor oils to retain OEM warranty approvals. The passenger vehicle service-fill segment is responding fastest, with quick-lube chains pre-certifying SASO-compliant synthetics ahead of enforcement deadlines.
Fleet procurement departments are consolidating lubricant purchasing under national maintenance contracts. Individual vehicle-level buying is yielding to centralized tender processes with technical service bundling. This concentration is most visible in the cement and construction materials sector, where Aramco-linked contractors specify single-source lubricant agreements across thousand-vehicle fleets.
Saudi Arabia Automotive Lubricants Market Segmentation
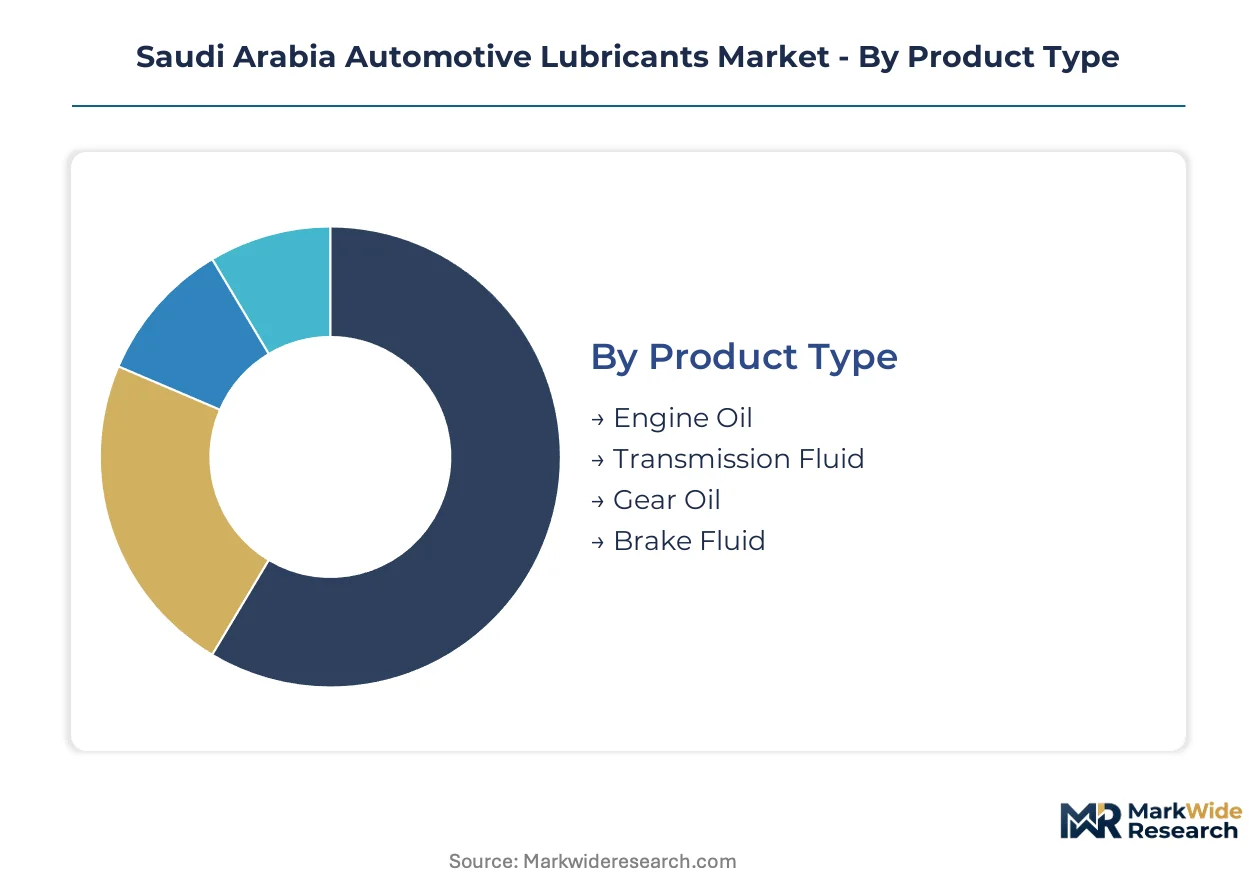
Segmentation in the Saudi Arabia Automotive Lubricants Market reveals how formulation chemistry, vehicle duty cycles, and procurement channels create distinct margin pools. Understanding these divides helps suppliers align technical capabilities with the Kingdom's regulatory trajectory and fleet modernization priorities.
Product Type:
Standardization dominates high-volume categories where SASO specifications compress formulation variance, while specialized segments reward technical differentiation with premium positioning.
- Engine Oil:Hydrocarbon-based or synthetic fluid systems formulated for friction reduction and thermal management in internal combustion engines. Demand concentrates in the Eastern Province fleet corridors, where high ambient temperatures and dust exposure compress drain intervals and elevate consumption rates per vehicle.
- Transmission Fluid:Viscosity-stabilized formulations engineered for automatic and manual gearbox assemblies under sustained load conditions. Adoption is accelerating in Riyadh logistics hubs as commercial operators upgrade to automated manual transmissions for fuel economy compliance under Saudi Energy Efficiency Center directives.
- Gear Oil:Extreme-pressure lubricants for differential and axle assemblies in heavy-duty applications.
- Brake Fluid:Hygroscopic glycol-ether or silicone-based hydraulic fluids meeting DOT specifications for high-temperature fade resistance.
Most installed capacity flows through Engine Oil. Expansion is steepest in Transmission Fluid.
Application:
Volume concentration sits with light-duty personal transport, while margin extraction depends on technical service bundling in commercial segments.
- Passenger Vehicles:Light-duty cars and SUVs requiring SAE 0W-20 to 5W-30 grades for gasoline and diesel powertrains. Service-fill demand clusters in Jeddah and Dammam quick-lube networks, where synthetic conversion rates are climbing fastest among younger vehicle cohorts.
- Heavy-Duty Vehicles:Mining trucks, construction equipment, and long-haul tractors operating under severe-duty cycles. Procurement concentrates with Aramco-linked contractors and cement sector fleets in the Central Province, where bulk contracts specify 15W-40 and 10W-40 synthetic blends with embedded oil analysis programs.
- Commercial Vehicles:Medium-duty delivery and distribution trucks serving urban logistics corridors.
- Two-Wheelers:Motorcycles and scooters requiring dedicated 4-stroke and 2-stroke formulations.
Passenger Vehicles absorb the largest volume share. Heavy-Duty Vehicles command the highest per-liter margins through technical service integration.
Base Oil:
Feedstock quality tiers separate commodity blenders from integrated refiners with captive Group II/III supply from Jubail Industrial City.
- Synthetic Oil:Polyalphaolefin (PAO) and Group III hydrocracked base stocks engineered for thermal stability and extended drain intervals. Fleet operators in the northwest Neom construction corridor are specifying synthetic grades for earthmoving equipment, where downtime costs exceed lubricant premiums by an order of magnitude.
- Mineral Oil:Solvent-refined Group I base stocks serving price-sensitive service-fill segments and older vehicle populations. Demand persists in traditional distributor networks carrying 90-day inventory cycles, though working capital strain is accelerating synthetic conversion.
- Semi-Synthetic Oil:Blended formulations combining mineral and synthetic base stocks for mid-tier positioning.
- Bio-Based Oil:Ester and vegetable-derived formulations targeting biodegradability specifications for marine and environmentally sensitive applications.
Synthetic Oil is climbing the fastest as drain interval extension and Euro 5 compliance reshape fleet procurement criteria. Mineral Oil retains volume leadership in the independent aftermarket.
Distribution Channel:
Channel power is consolidating toward national maintenance contracts and direct OEM partnerships, marginalizing traditional stock-and-sell distributors.
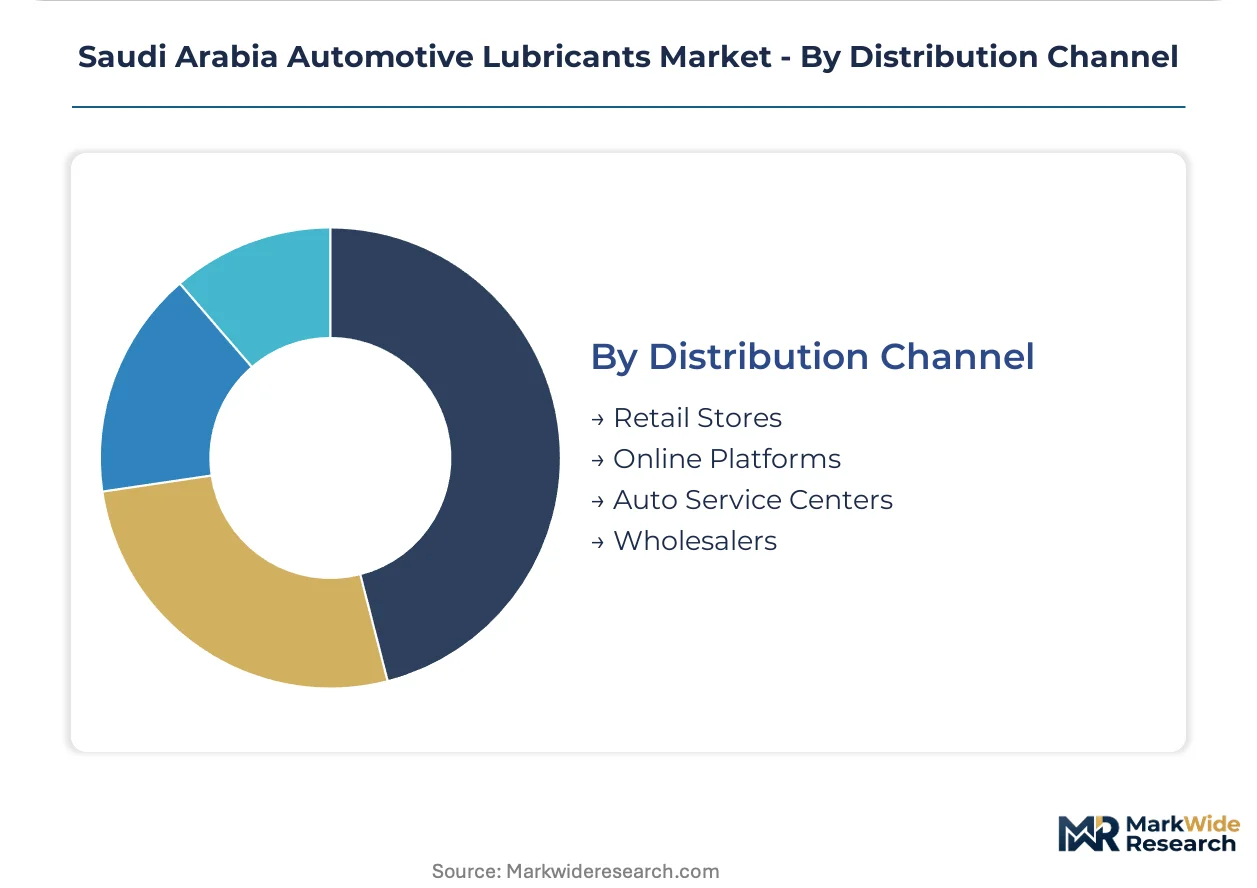
- Auto Service Centers:Quick-lube chains and dealership service bays performing bulk oil changes with specification-compliant formulations. SASO pre-certification requirements are concentrating volume with chains capable of inventory transparency and technical training investment.
- Wholesalers:Regional distributors supplying independent garages and rural service points. The Eastern Province wholesale network leverages proximity to Jubail blending operations for just-in-time replenishment, though margin compression from synthetic transitions is stranding conventional oil inventories.
- Retail Stores:Hypermarkets and automotive specialty outlets serving DIY consumers and small independent workshops.
- Online Platforms:E-commerce channels for packaged lubricant sales with delivery logistics.
Auto Service Centers capture the largest revenue flow. Online Platforms are expanding most quickly among younger vehicle owners seeking specification transparency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Kingdom's lubricant industry traces its scale to the 1970s petrochemical buildout around the Arabian Gulf, when integrated refining clusters established feedstock dominance for downstream blending operations.
Eastern Province
Jubail Industrial City's petrochemical integration supplies captive Group II and III base oils to domestic blenders. SASO's Euro 5-equivalent standards accelerate formulation turnover here faster than elsewhere. Fleet operators in Dammam logistics corridors institutionalize oil analysis programs that extend drain intervals while elevating synthetic volumes.
Riyadh
The Central Province concentrates heavy-duty procurement through Aramco-linked contractors and cement sector fleets. Battery electric commercial vehicle pilots in Riyadh logistics corridors threaten long-term engine oil demand. Centralized tender processes with technical service bundling now dominate fleet purchasing decisions.
Western Region
Jeddah quick-lube networks drive passenger vehicle synthetic conversion among younger vehicle cohorts. Red Sea coastal marine applications for fishing vessels and port equipment remain underpenetrated by advanced formulations. Salt-air corrosion protection creates premium positioning opportunities for specialized products.
NEOM Northwest
Heavy-duty mining and earthmoving fleets in the megacity construction corridor require severe-duty lubricants. Fleet operators specify synthetic grades where downtime costs exceed lubricant premiums substantially. Technical service agreements with project consortiums offer multi-year revenue visibility for qualified suppliers.
Saudi Arabia Automotive Lubricants Market Competitive Landscape
Capital-heavy integrated refiners compete with asset-light specialized blenders for positioning across Saudi Arabia's tiered demand structure. The market exhibits moderate consolidation at the top, with national champions leveraging captive feedstock supply against multinational formulators importing additive packages. Two strategic archetypes dominate: vertically integrated domestic producers with Jubail base oil access, and global majors competing through OEM partnerships and high-temperature formulation expertise. Competitive intensity centers on SASO certification pre-positioning and national maintenance contract capture.
Among integrated domestic champions, Petromin Corporation anchors the supply chain through its refining and blending footprint. TotalEnergies and ExxonMobil Corporation represent the multinational archetype, occupying positions calibrated to desert operating conditions and heavy-duty OEM relationships respectively.
| Leading Market Players |
|---|
| Petromin Corporation |
| TotalEnergies |
| ExxonMobil Corporation |
| PETRONAS Lubricants International |
| Chevron Corporation |
| BP PLC (Castrol) |
| Royal Dutch Shell PLC |
| AMSOIL Inc |
| FUCHS |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between SASO-compliant synthetics and conventional mineral formulations manifests in both pricing power and supply chain configuration across the Kingdom. Premium synthetic tiers command substantial per-liter premiums through embedded technical service agreements, while commodity mineral grades compete on working capital efficiency in distributor networks anchored to Jubail feedstock proximity.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels organizes the market around base oil quality tiers and drain interval performance. Price differentiation rests on SASO certification status and captive Group III supply access from Jubail refiners. Cost compression in the mineral tier is intensifying because stranded 90-day inventory cycles erode distributor margins. Fleet procurement departments show least price sensitivity, while independent quick-lube operators in Jeddah and Dammam remain most responsive to per-liter differentials.
Supply Chain Analysis
Dual-sourcing requirements from Aramco-linked contractors and cement sector fleets mandate multi-supplier qualification for critical additive packages. Geographic supply concentration draws from the United States, Germany, and Belgium for specialty ester base stocks and performance additive systems. Raw material dependencies center on Group II/III base oils from Jubail, polyalphaolefin feedstocks from European refiners, and dispersant-detergent packages from US chemical specialists. Single-source vulnerability sits with advanced additive technology concentrated among three global suppliers. Distribution runs through national maintenance contracts with technical service bundling, marginalizing traditional stock-and-sell wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's automotive lubricants sector functions as a regulatory compounder where SASO's Euro 5-equivalent emission standards continuously revalue formulation capabilities and certification assets.
For Market Incumbents: To counter battery electric commercial vehicle pilots threatening long-term engine oil demand, deepen captive supply of Group III base oils through Jubail refinery expansions and secure multi-year technical service agreements with Neom construction consortiums. Certification investment in biodegradability testing infrastructure unlocks EU-bound synthetic export lines and blocks smaller blenders from premium segments. For New Entrants and Emerging Players: E-commerce channels with specification transparency tools offer the most penetrable route into younger vehicle owner segments in Jeddah and Riyadh. Target Red Sea coastal marine applications for fishing vessels and port handling equipment where salt-air corrosion protection creates premium positioning opportunities with minimal incumbent technical service presence. White-space exists in bio-based formulations for environmentally sensitive applications. For Investors and Strategic Acquirers: Consolidation pressure builds where domestic blenders lack captive base oil supply and face stranded conventional inventory from rapid synthetic transitions. Long-term viability favors integrated refiners with backward control over Group II/III feedstocks and SASO pre-certification alignment with European OEM warranty standards. The signal to watch is fleet procurement department consolidation under national maintenance contracts, which accelerates share capture by technical-service-capable suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Group III Base Oil Production | Jubail refinery expansions reduce import dependency and secure synthetic formulation feedstock supply. |
| SASO Certification Pre-Positioning | Early alignment with European OEM warranty standards blocks smaller blenders from premium fleet segments. |
| Technical Service Agreement Expansion | Multi-year contracts with Neom and Aramco-linked contractors provide revenue visibility through construction cycles. |
| Digital Channel Development | E-commerce platforms with specification transparency capture younger vehicle owners in Jeddah and Riyadh. |
| Bio-Based Formulation Investment | Biodegradability certification unlocks marine applications and EU-bound export opportunities. |
Research Methodology
Direct dialogue with lubricant formulation chemists, fleet procurement directors at Aramco-linked contractors, quick-lube chain operations managers, and SASO regulatory affairs specialists grounded the qualitative assessment. Secondary validation drew from SASO technical specifications, Saudi Energy Efficiency Center transport directives, Jubail Industrial City production disclosures, and trade flow data from the General Authority for Statistics. Bottom-up demand modeling across vehicle parc segments triangulated with top-down petrochemical capacity analysis.
Segmented volume and value estimates emerged from disaggregated modeling across product type, application, base oil tier, and distribution channel dimensions throughout the forecast period. CAGRs were derived from regression analysis of historical consumption patterns against regulatory enforcement timelines and fleet modernization cycles. Industry-specific inputs included drain interval extension rates from oil analysis program adoption and synthetic conversion velocity in passenger versus commercial segments.
The model assumes a particular technology adoption path; alternative pathways for battery electric commercial vehicle penetration would alter the outlook for engine oil demand trajectories. Forecasts reflect assumptions about SASO regulatory alignment with evolving OEM standards and the pace of petrochemical integration in Jubail. Deviation in fleet procurement consolidation speed or base oil feedstock cost volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Road Marking Machine Market
Automotive Parts
Morocco Automotive Engine Oils Market
Automotive Parts
Indonesia Automotive Lubricants Market
Automotive Parts
Engine Bearings Market
Automotive Parts
South America Automotive Engine Oils Market
Automotive Parts
Global Car Air Filter Market
Automotive Parts
Power Liftgate Market
Automotive Parts
Morocco Commercial Vehicles Lubricants Market
Automotive Parts
Poland Passenger Vehicles Lubricants Market
Automotive Parts
Smoke Spill Motor Market
Automotive Parts
Latin America Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Fuel Delivery System Market
Automotive Parts
South Korea Automotive Parts Aluminium Die Casting Market
Automotive Parts
Global Plastics for Passenger Cars Market
Automotive Parts
Global Truck Refrigeration Unit Market
Automotive Parts
Global Passenger Vehicles Lubricants Market