
 Connecting Rods Market | 2026-2036
Connecting Rods Market Size, Share, and Industry Trends Forecast 2026-2036
Connecting Rods Market Outlook
Aluminum is broadening its share in passenger car connecting rod specifications as OEMs pursue mass reduction targets. MAHLE GmbH leverages integrated forging and surface treatment capabilities across European and Asian production footprints. Bharat Forge Ltd. anchors high-volume supply contracts with Indian and global commercial vehicle OEMs through its Pune and Mundhwa facilities.
A connecting rod is a rigid mechanical link that transmits reciprocating motion from the piston to the crankshaft, typically manufactured from forged steel or aluminum alloys with tolerances measured in micrometers to withstand cyclic compressive and tensile loads exceeding 15,000 psi. Steel designs dominate heavy-duty and high-performance applications where fatigue resistance governs specification, while aluminum variants capture share in light-duty automotive engines where weight reduction delivers fuel economy gains. The forged design segment holds the largest share of output value due to capital intensity and material utilization rates, though machined billet configurations command premium positioning in motorsport and aerospace engine rebuild channels.
EPA fuel economy standards, Euro 7 emissions rules from the European Commission, and India's BIS automotive component quality norms collectively tighten material certification and traceability requirements for connecting rod suppliers seeking OEM qualification. China's GB standards for automotive forgings and SAMR market access protocols add compliance layers for exporters targeting domestic Chinese engine production. Stakeholders must monitor evolving alloy specifications and emissions-driven engine downsizing trends to align capacity investments with shifting demand toward lighter, higher-specific-strength connecting rod architectures.
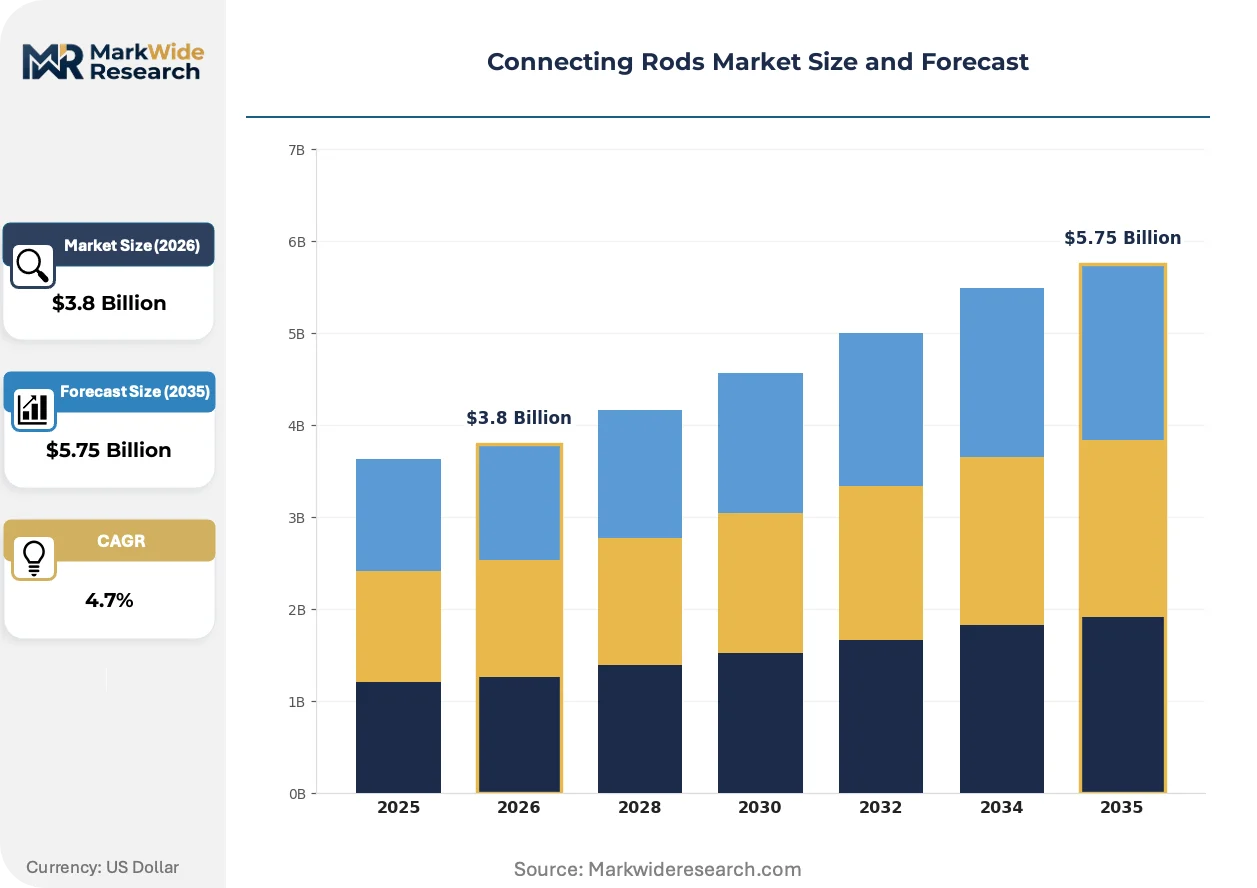
Market Dynamics
Steel-to-aluminum substitution in passenger car engines is compressing per-unit mass while forcing capital reallocation across forging capacity. Corporate Average Fuel Economy standards and Euro 7 emissions benchmarks are accelerating this material transition.
Growth Catalysts
- Corporate Average Fuel Economy standards:US EPA mandates are compelling OEMs to adopt aluminum connecting rods in light-duty engines, directly stimulating demand for forged aluminum alloys with higher specific strength.
- India's PLI scheme for automotive components:Production-linked incentives are attracting forging investments into Maharashtra and Gujarat, expanding domestic supply capacity for commercial vehicle OEMs.
- Engine downsizing architectures:Turbocharged small-displacement designs are multiplying connecting rod counts per vehicle platform while requiring lighter reciprocating assemblies.
Market Restraints
- Aluminum ingot price volatility:LME aluminum price swings are compressing margin predictability for suppliers locked into annual OEM supply agreements with fixed pricing terms.
- Forging press capacity concentration:Large-diameter crankshaft-quality steel billet supply concentrates among a limited set of European and Japanese specialty steel producers, creating single-source vulnerability.
- Fatigue performance ceiling:Aluminum alloys face persistent fatigue limit constraints under cyclic loads exceeding 12,000 psi, restricting penetration in heavy-duty diesel applications where steel remains mandatory.
Strategic Opportunities
- India light commercial vehicle expansion:Maharashtra-Gujarat corridor OEMs are localizing engine production, creating demand for high-volume forged steel rod supply with shorter logistics loops than European imports.
- Additive manufacturing convergence:Hybrid forged-billet geometries combined with topology-optimized machining are enabling custom lightweight designs for low-volume performance engine builders.
- China's dual carbon goals:MIIT emissions benchmarks are accelerating aluminum adoption in domestic passenger car engines, opening qualification pathways for certified foreign suppliers.
Industry Challenges
- Metallurgical talent scarcity:Forging process engineers with crankshaft-quality steel expertise are aging out of European and Japanese workforces faster than training pipelines replenish.
- Euro 7 certification timelines:European Commission traceability requirements are extending OEM qualification cycles for new alloy specifications, delaying revenue recognition on R&D investments.
- Legacy ERP integration:Tier-2 forgers in India and China face friction connecting ISO-certified quality systems to OEM mandate real-time production data feeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connecting Rods Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Steel, Aluminum, Titanium, Composite Application: Automotive Engines, Marine Engines, Industrial Engines, Aerospace Engines Design: Forged, Cast, Welded, Machined End User: OEMs, Aftermarket Providers, Dealerships, Engine Rebuilders |
| Companies Covered | MAHLE GmbH, Albon Engineering & Manufacturing, CP Carrillo, Linamar Corporation, Arrow Precision Ltd., JD Norman Industries, Tianrun Crankshaft Co., Ltd., Wiseco Piston Co., Ltd., Bharat Forge Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connecting Rods Market Strategic Shifts
Connecting rod manufacturing is fragmenting into material-specific process chains, with aluminum forging and steel forging diverging in equipment, alloy sourcing, and quality protocols. This bifurcation is reshaping supplier specialization strategies.
Modular forging cell architectures are modularizing production flexibility across aluminum and steel grades. Tier-1 suppliers in Germany and Japan are deploying quick-change die systems that switch between alloy families within single shift cycles. This equipment convergence is modularizing capital efficiency, allowing mid-volume producers to serve mixed-material OEM platforms without dedicated lines.
REACH substance restrictions on hexavalent chromium surface treatments are forcing conversion to trivalent chemistries or PVD coatings across European supply chains. The industrial consequence is elevated process validation costs and extended OEM approval timelines for converted coating lines. Passenger car engine programs with Euro 7 launch commitments are most affected, with suppliers accelerating trivalent line investments to maintain qualification status.
Aftermarket procurement is consolidating through certified rebuild networks that bypass traditional distributor channels. Engine remanufacturers in the US and Germany are sourcing connecting rods directly from forging houses with ISO 9001 and IATF 16949 credentials, disintermediating legacy parts wholesalers. This channel compression is most visible in North American heavy-duty truck engine rebuilds, where fleet operators prioritize single-source traceability over distributor breadth.
Connecting Rods Market Segmentation
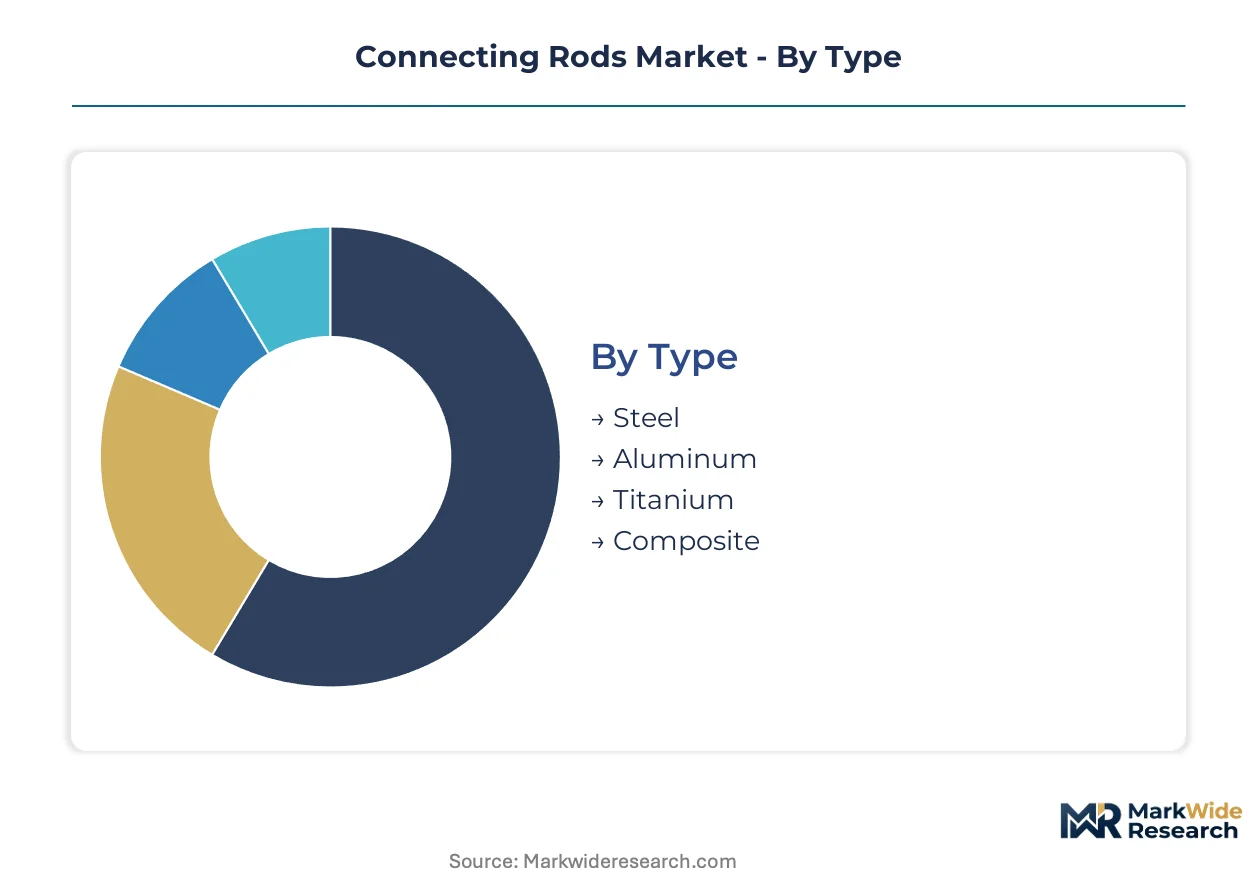
Connecting rod procurement splits sharply between mass-market automotive programs and low-volume specialty applications, with material and design choices cascading through forging capacity allocation and margin structures. Understanding these segment boundaries clarifies where capital deployment concentrates and where qualification barriers protect incumbent positions.
Type:
Steel commands volume share in heavy-duty platforms while aluminum captures the premium-mass growth corridor, with titanium and composite variants occupying narrow performance niches.
- Steel:Forged from crankshaft-quality micro-alloyed billets with fatigue limits exceeding 15,000 psi, steel rods anchor commercial vehicle and high-performance gasoline engine specifications. Demand concentrates in India's Maharashtra-Gujarat corridor where Bharat Forge and local OEMs source forged steel for light commercial vehicle production, though aluminum substitution is compressing share in passenger car displacement ranges below 2.0 liters.
- Aluminum:A356-T6 and 7075-T73 alloys deliver 40-50% mass reduction versus steel equivalents, with specific strength gains from controlled forging and T6 heat treatment protocols. MAHLE GmbH and Japanese Tier-1 suppliers are expanding aluminum forging capacity across European and Asian footprints to serve Euro 7-compliant passenger car engines, with China's MIIT dual carbon goals accelerating domestic qualification pathways for certified foreign suppliers.
- Titanium:Ti-6Al-4V forgings command aerospace and motorsport positioning where strength-to-weight ratios above 200 kN·m/kg justify unit costs 8-12x steel equivalents.
- Composite:Carbon fiber-reinforced polymer connecting rods remain experimental, limited to racing prototype validation by Formula 1 and WEC engine builders.
Today's leader: Steel. Tomorrow's challenger: Aluminum.
Application:
Automotive volume dwarfs other end-uses, yet marine and industrial segments sustain specialty forging margins through specification complexity and certification longevity.
- Automotive Engines:Passenger car and light commercial vehicle programs generate 70%+ of unit demand, with turbocharged downsized architectures multiplying rod counts per platform while demanding lighter reciprocating assemblies. Steel-to-aluminum substitution is most advanced here, driven by EPA Corporate Average Fuel Economy mandates and Euro 7 emissions benchmarks compressing per-unit mass.
- Marine Engines:Saltwater corrosion resistance and extended overhaul intervals favor forged steel and surface-hardened designs, with demand clustering in Mediterranean and Southeast Asian shipbuilding centers.
- Industrial Engines:Stationary power generation and construction equipment specifications prioritize fatigue life over mass reduction, sustaining steel forging demand with 15-25 year replacement cycles.
- Aerospace Engines:Piston aviation and auxiliary power units require superalloy and titanium forgings with FAA/EASA traceability, representing sub-1% of volume but premium pricing multiples.
Automotive volume anchors capacity planning. Aerospace margins attract specialty investment.
Design:
Forging economics favor high-volume automotive programs while casting and welding retain cost-positioned niches, and machined billets serve rebuild channels.
- Forged:Closed-die forging with flashless precision trimming delivers 85%+ material utilization and grain-flow alignment critical for fatigue resistance. This design holds the largest share of output value due to capital intensity and material utilization rates, with German and Japanese Tier-1 suppliers deploying modular forging cells that switch between aluminum and steel grades within single shift cycles.
- Machined:CNC-machined billet configurations command premium positioning in motorsport and aerospace engine rebuild channels where lot sizes below 100 units preclude forging die economics.
- Cast:Investment casting captures select industrial engine applications where near-net-shape geometries reduce machining burden on iron-based alloys.
- Welded:Fabricated steel assemblies persist in legacy agricultural and marine engine rebuild markets with minimal performance requirements.
Forging dominates new equipment supply. Machining captures the aftermarket premium.
End User:
OEM procurement consolidates through platform-level supply agreements while aftermarket channels fragment across rebuild networks and distributor tiers.
- OEMs:Passenger car and commercial vehicle manufacturers source connecting rods through multi-year platform contracts with IATF 16949-qualified Tier-1 forgers, with real-time production data feeds now mandatory for qualification.
- Aftermarket Providers:Engine remanufacturers in the US and Germany source directly from ISO 9001-certified forging houses, disintermediating legacy parts wholesalers in heavy-duty truck rebuild channels.
- Dealerships:Authorized service networks procure through OEM captive parts operations, maintaining traceability chains for warranty coverage.
- Engine Rebuilders:Independent rebuilders access connecting rods through distributor tiers or direct forging relationships based on volume scale and certification requirements.
OEMs set specification standards. Aftermarket rebuilders are consolidating procurement relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta manufacturing cluster anchors connecting rod production volume, with Shanghai, Suzhou, and Ningbo housing integrated forging operations serving domestic and export engine programs. India's Maharashtra-Gujarat corridor and Germany's automotive belt represent the other dominant supply nodes.
China
Domestic passenger car OEMs are localizing aluminum forging capacity to meet MIIT dual carbon targets for fleet emissions reduction. GB standards for automotive forgings and SAMR market access protocols govern supplier qualification for foreign exporters. Yangtze River Delta facilities are expanding modular forging cells that switch between steel and aluminum grades within single shift cycles.
India
Light commercial vehicle OEMs are scaling engine production in Maharashtra and Gujarat, generating demand for high-volume forged steel rod supply. The PLI scheme for automotive components attracts forging investments into Pune and Mundhwa, expanding domestic capacity. Bharat Forge anchors supply contracts with reduced logistics loops versus European imports.
Germany
Premium passenger car manufacturers drive aluminum connecting rod specifications to satisfy Euro 7 emissions benchmarks from the European Commission. REACH substance restrictions on hexavalent chromium surface treatments force conversion to trivalent chemistries or PVD coatings. Baden-Württemberg and Bavaria host Tier-1 suppliers deploying quick-change die systems across mixed-material platforms.
United States
Heavy-duty truck engine rebuilders consolidate procurement through direct forging relationships, disintermediating legacy parts distributors. EPA Corporate Average Fuel Economy mandates compel light-duty OEMs to adopt aluminum rods in downsized turbocharged architectures. Michigan and Ohio anchor aftermarket demand from fleet operators prioritizing single-source traceability.
Japan
Specialty steel producers concentrate crankshaft-quality billet supply for fatigue-critical applications where aluminum alloys face performance ceilings. METI industrial policy supports forging process automation to offset metallurgical talent scarcity. Aichi and Osaka prefectures house integrated operations serving both domestic OEMs and export markets.
Connecting Rods Market Competitive Environment
Global majors compete with regional champions across forging capacity and alloy specialization, creating a tiered structure where scale-driven Tier-1 suppliers coexist with mid-volume specialists and national champions. The market fragments along material lines, with steel-forging incumbents defending heavy-duty positions while aluminum-focused players capture passenger car growth. Three archetypes dominate: integrated automotive suppliers with multi-material capabilities, regional forging houses serving commercial vehicle OEMs, and precision specialists in motorsport and aerospace rebuild channels. Capacity expansion and strategic partnerships represent the primary competitive vectors, with suppliers pursuing geographic proximity to high-volume engine programs.
Within the integrated automotive supplier tier, MAHLE GmbH and Linamar Corporation exemplify multi-regional production footprints spanning European and Asian markets. Bharat Forge Ltd. anchors the regional champion archetype through high-volume supply positioning in Indian commercial vehicle corridors. Among precision specialists, CP Carrillo occupies the premium motorsport and rebuild channel where machined billet configurations command positioning above forging economics. These three represent distinct capability configurations rather than direct substitutes, with customer procurement patterns sorting across OEM platform scale, performance requirements, and geographic proximity.
| Leading Market Players |
|---|
| MAHLE GmbH |
| Albon Engineering & Manufacturing |
| CP Carrillo |
| Linamar Corporation |
| Arrow Precision Ltd. |
| JD Norman Industries |
| Tianrun Crankshaft Co., Ltd. |
| Wiseco Piston Co., Ltd. |
| Bharat Forge Ltd. |
| Others |
Value Chain & Pricing Dynamics
Material-grade bifurcation between forged steel and aluminum connecting rods manifests in divergent pricing structures and supply chain footprints. Premium aluminum specifications command valuation multiples over commodity steel equivalents, with OEM qualification barriers and alloy certification costs determining supplier pricing power across European and Asian production corridors.
Pricing Analysis
Input-cost pass-through from LME aluminum volatility and specialty steel billet premiums shapes contract negotiations between Tier-1 forgers and automotive OEMs. Three-tier pricing structure across premium, standard, and economy levels separates IATF 16949-certified suppliers from ISO 9001 aftermarket providers and uncertified rebuild channels. Pricing pressure stems from annual fixed-price agreements locking suppliers into margin compression when raw material costs spike. Commercial vehicle OEMs in India exhibit highest price sensitivity due to localization mandates, while German premium passenger car manufacturers prioritize fatigue performance over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Volkswagen, Toyota, and Mahindra platform programs, with real-time production data feeds now mandatory for qualification. Geographic supply concentration centers on China's Yangtze River Delta, India's Maharashtra-Gujarat corridor, and Germany's Baden-Württemberg automotive belt. Raw material dependencies draw from European and Japanese crankshaft-quality steel producers, LME-traded aluminum ingot markets, and domestic Chinese forging-grade alloy suppliers. Single-source vulnerability concentrates in large-diameter billet supply from specialized European and Japanese steel mills. Distribution runs through Tier-1 integrated suppliers for OEM programs and direct forging relationships for North American heavy-duty truck rebuilders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as Euro 7 emissions benchmarks and EPA Corporate Average Fuel Economy standards force OEM procurement toward premium aluminum specifications with enhanced traceability requirements.
For Market Incumbents: To counter aluminum alloy fatigue performance ceilings in heavy-duty applications, defend steel forging positions through backward integration into crankshaft-quality billet supply and capacity expansion in India's PLI-subsidized Maharashtra-Gujarat corridor. Prioritize trivalent chromium conversion investments to maintain European qualification status under REACH substance restrictions. For New Entrants and Emerging Players: India's PLI scheme for automotive components in Maharashtra and Gujarat opens a window for forging investments serving localized light commercial vehicle engine production. Target aluminum forging qualification for Chinese domestic OEMs pursuing MIIT dual carbon goals, with go-to-market positioning through modular forging cells enabling mixed-material platform service. For Investors and Strategic Acquirers: Consolidation pressure builds where metallurgical talent scarcity in European and Japanese workforces outpaces training pipeline replenishment. Long-term viability favors specialty steel forging capabilities with aerospace traceability or aluminum forging operations with OEM platform certification. Monitor Euro 7 certification timeline extensions as inflection indicators for R&D investment recovery periods.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Forging Cell Deployment | Quick-change die systems enable aluminum-steel grade switching within single shift cycles across German and Japanese Tier-1 footprints. |
| Backward Integration into Billet Supply | Captive crankshaft-quality steel production mitigates single-source vulnerability from European and Japanese specialty mills. |
| Trivalent Chromium Line Conversion | REACH-compliant surface treatment investments preserve European OEM qualification status ahead of Euro 7 launch commitments. |
| PLI-Subsidized Capacity Expansion | Maharashtra-Gujarat forging investments capture localized demand from Indian commercial vehicle OEMs with reduced logistics costs. |
| Direct Aftermarket Procurement Relationships | ISO 9001-certified forging houses bypass legacy distributors to serve North American heavy-duty truck engine rebuilders. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and metallurgical forging specialists with secondary validation against vehicle production databases, IHS Markit registration data, SEC filings from listed automotive suppliers, and trade flow records from customs authorities. Bottom-up segment sizing and top-down macroeconomic triangulation anchored volume and value estimates.
Segment-weighting approaches modeled demand across material type, application category, design configuration, and end-user channel throughout the forecast period. CAGRs derived from production volume trajectories, content-per-vehicle assumptions for turbocharged downsized architectures, and steel-to-aluminum substitution elasticity parameters calibrated against EPA and Euro 7 regulatory compliance timelines.
Revisions become necessary when aluminum ingot price volatility exceeds historical bands, Euro 7 certification timelines extend beyond baseline assumptions, or Indian PLI scheme disbursement delays alter capacity investment schedules. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global Automotive Springs and Damper Market
Automotive Parts
Automotive Hydraulic Filter System Market
Automotive Parts
North America Gear Market
Automotive Parts
Die Cast Parts for Electric Vehicle Market
Automotive Parts
Automotive Trailing Arm Market
Automotive Parts
Automotive Oil Pans Market
Automotive Parts
Air Suspension Systems Market
Automotive Parts
Indonesia Automotive Lubricants Market
Automotive Parts
Argentina Automotive Lubricants Market
Automotive Parts
India Automotive Lubricants Market
Automotive Parts
Uae Commercial Vehicles Lubricants Market
Automotive Parts
Vehicle Jump Starter Market
Automotive Parts
France Passenger Vehicles Lubricants Market
Automotive Parts
Russia Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Windshield Washer System Market
Automotive Parts
North America Automotive Airfilters Market