
 Europe Motorcycle Market | 2026-2036
Europe Motorcycle Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Motorcycle Market Analytics
A wide capital-intensity divergence between mass-market assemblers and premium engineering houses is reorganizing competitive tiers across the continent. KTM AG leverages its Austrian motorsport pedigree to dominate performance-oriented segments with aggressive R&D spending. BMW Motorrad sustains manufacturing scale through integrated Munich-area production that anchors its touring motorcycle dominance. Piaggio Group competes across multiple European price points through its diversified brand architecture spanning scooters and motorcycles.
A motorcycle is a two-wheeled motorized vehicle powered by an internal combustion engine or electric motor, typically featuring a tubular steel or aluminum frame, chain or shaft final drive, and hydraulic disc braking systems designed for individual or dual-rider transportation across varied road surfaces. Cruisers and touring motorcycles occupy the highest margin pools as aging European riders prioritize comfort and long-distance capability over raw performance. Sports bikes retain volume leadership in Southern European markets where younger demographics favor aggressive styling and track-derived technology. The 126-400cc engine capacity band captures the fastest growth trajectory as urban congestion charges and fuel costs push commuters toward mid-displacement machines.
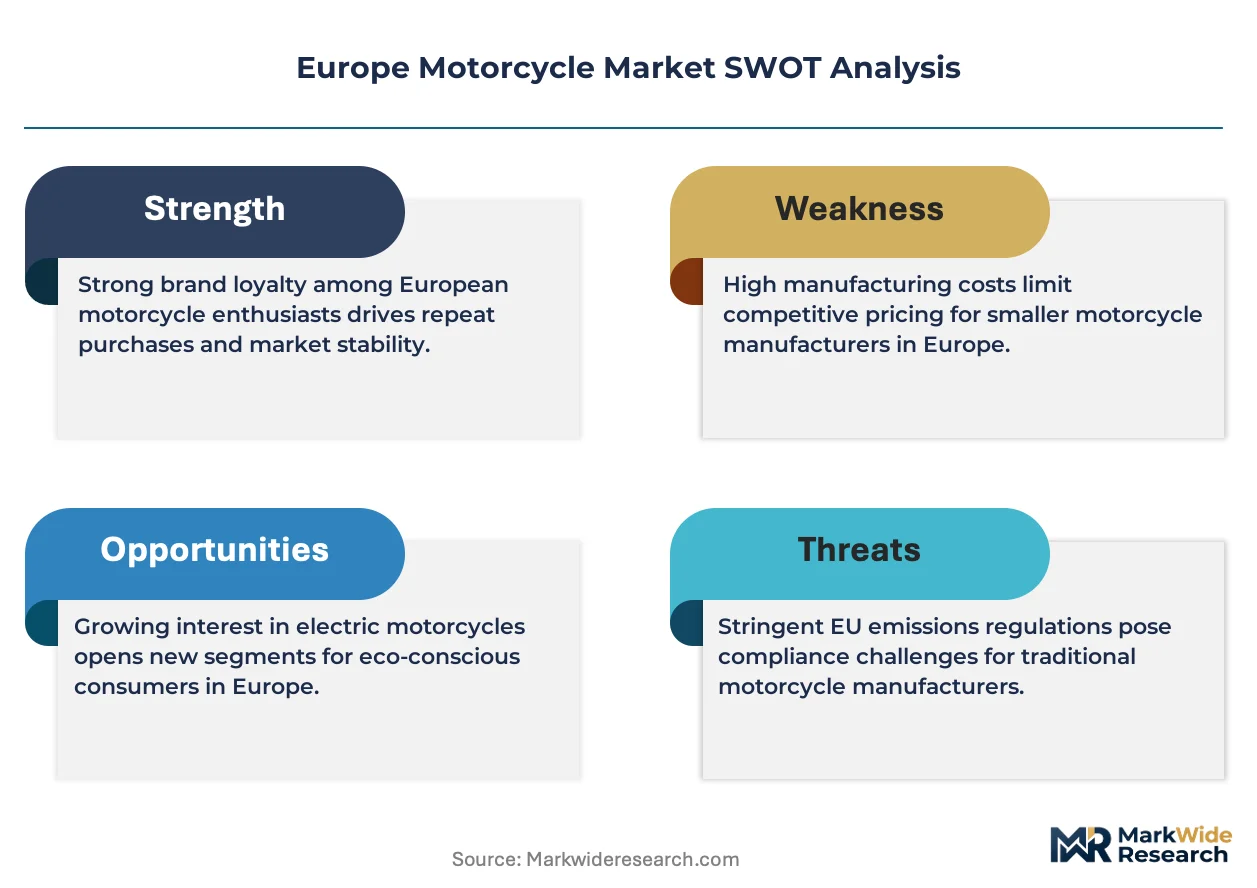
The European Commission enforces Euro 5+ emissions standards through type-approval protocols that force manufacturers to invest in catalytic converter refinement and electronic fuel injection precision. ECHA manages REACH chemical compliance for paints, coatings, and battery materials that constrain supply chain sourcing across member states. CE marking requirements under the EU Machinery Directive govern safety-critical components including lighting systems and braking performance. Stakeholders must monitor the EU Green Deal's emerging transport decarbonization mandates to determine electrification investment timing and platform development priorities.
Market Dynamics
The Euro 5+ emissions standards are compressing engine architectures while simultaneously accelerating electric platform investments across European manufacturing clusters. This regulatory pressure is forcing a fundamental reorganization of powertrain sourcing and R&D allocation throughout the continent.
Growth Catalysts
- Urban congestion charging:Municipal toll schemes in Milan, Paris, and London exempt sub-125cc motorcycles, redirecting commuter demand toward two-wheeled mobility. City councils are expanding low-emission zones that favor motorized two-wheelers over passenger cars.
- REACH chemical compliance:ECHA's substance restrictions on paints and coatings are standardizing supply chain practices that reduce long-term liability exposure for assemblers. This framework creates predictable material sourcing conditions across member states.
- Battery energy density gains:Lithium-ion cell improvements are extending electric motorcycle range into viable inter-city territory, unlocking touring applications previously reserved for internal combustion engines.
Market Restraints
- Steel and aluminum input volatility:Tubular frame and swingarm production faces margin pressure from commodity price swings that resist hedging at mid-tier manufacturer scale.
- Semiconductor supply concentration:Electronic fuel injection and ride-by-wire systems depend on chip sourcing from concentrated Asian foundries, creating vulnerability in just-in-time assembly schedules.
- Homologation cost barriers:Euro 5+ type-approval testing expenses disproportionately burden sub-400cc producers, consolidating volume toward larger engineering houses with captive certification resources.
Strategic Opportunities
- Eastern European underpenetration:Poland, Romania, and Bulgaria exhibit motorcycle ownership rates below Western European averages, presenting whitespace for affordable electric commuter platforms.
- Battery-swapping infrastructure:Service station networks in dense urban cores enable range-anxiety mitigation without requiring residential charging access for apartment-dwelling riders.
- EU Green Deal transport decarbonization:Emerging mandates for fleet electrification create procurement pull from municipal and corporate vehicle pools seeking zero-emission two-wheeler alternatives.
Industry Challenges
- Power electronics skill scarcity:Motor control firmware and battery management system expertise concentrates within automotive and consumer electronics sectors, forcing motorcycle manufacturers to compete for talent outside traditional hiring pools.
- Platform certification timelines:Electric powertrain homologation under UNECE regulations requires extended validation cycles that delay model launches and compress selling seasons.
- Dealer network electrification readiness:Service technicians trained on internal combustion diagnostics require reskilling for high-voltage system maintenance, straining aftermarket support capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Motorcycle Market |
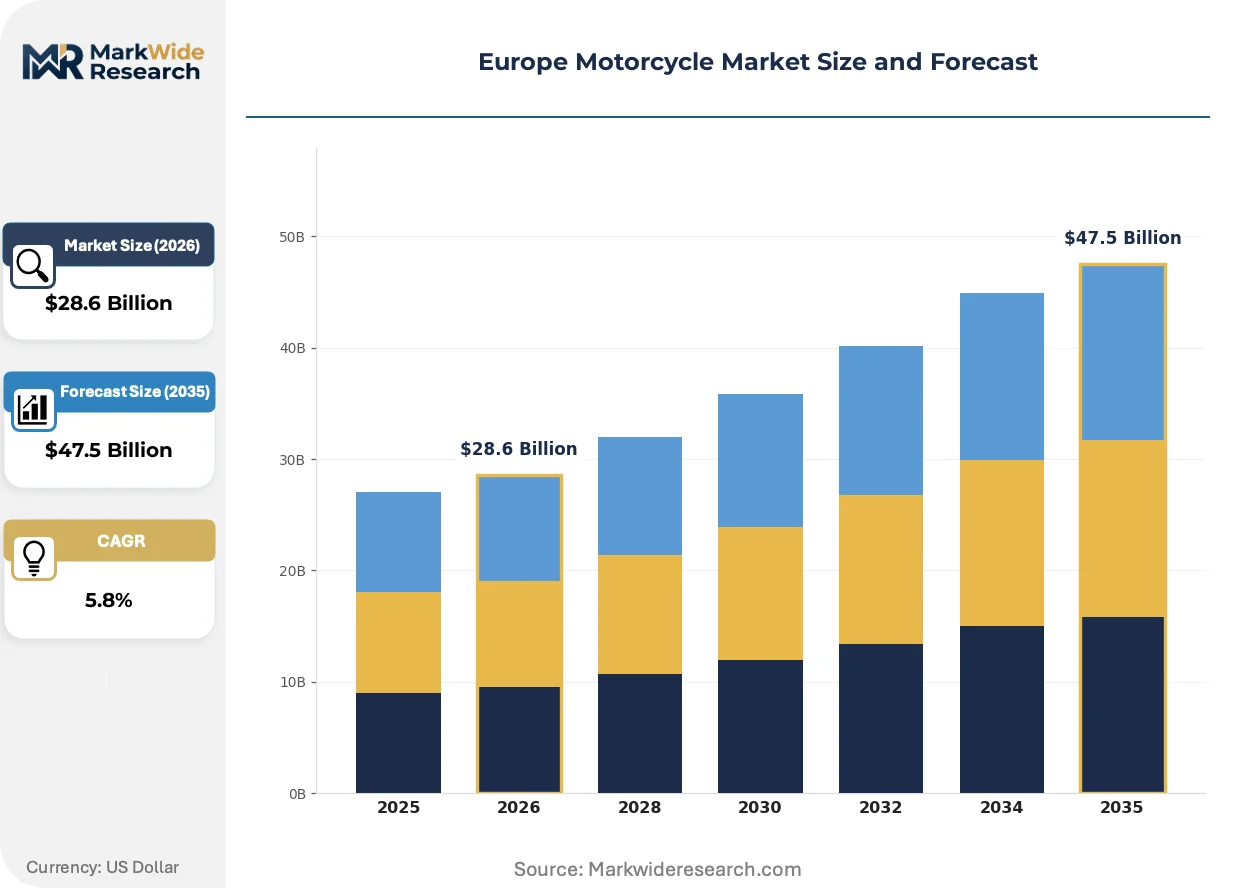
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cruisers, Touring, Sports Bikes, Dirt Bikes Engine Capacity: Under 125cc, 126-400cc, 401-750cc, Above 750cc Customer Type: Retail Consumers, Fleet Operators, Rental Services, Commercial Users Distribution Channel: Dealerships, Online Retail, Direct Sales, Service Centers |
| Companies Covered | Ducati Motor Holding, Piaggio Group, Honda Motor Co., Ltd., Aprilia, Triumph Motorcycles, Yamaha Motor Co., Ltd., KTM AG, Husqvarna Motorcycles, BMW Motorrad, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Motorcycle Market Evolving Landscape
Electrification is fragmenting the traditional displacement-based segmentation logic while connected vehicle architectures introduce software-defined functionality to historically mechanical product categories.
Silicon carbide power semiconductors are displacing traditional IGBT modules in electric motorcycle motor controllers, enabling higher switching frequencies that reduce thermal management mass. Premium manufacturers in Germany and Italy are adopting these components for performance-oriented models. This transition is compressing controller package sizes while extending peak power duration during aggressive riding.
The EU Green Deal's emerging transport decarbonization mandates are accelerating fleet electrification procurement requirements for municipal and corporate vehicle pools. Manufacturers must now engineer platforms capable of satisfying both private consumer and institutional buyer specifications simultaneously. Southern European markets with warmer climates and shorter average trip distances are responding fastest to these procurement signals.
Subscription-based battery service models are emerging as an alternative to outright powertrain ownership, separating vehicle purchase from energy storage capital commitment. Urban commuters in Paris and Barcelona are piloting these arrangements through manufacturer-backed mobility platforms. This behavioral shift is most visible among younger demographics lacking residential charging infrastructure or capital for battery replacement reserves.
Europe Motorcycle Market Segmentation
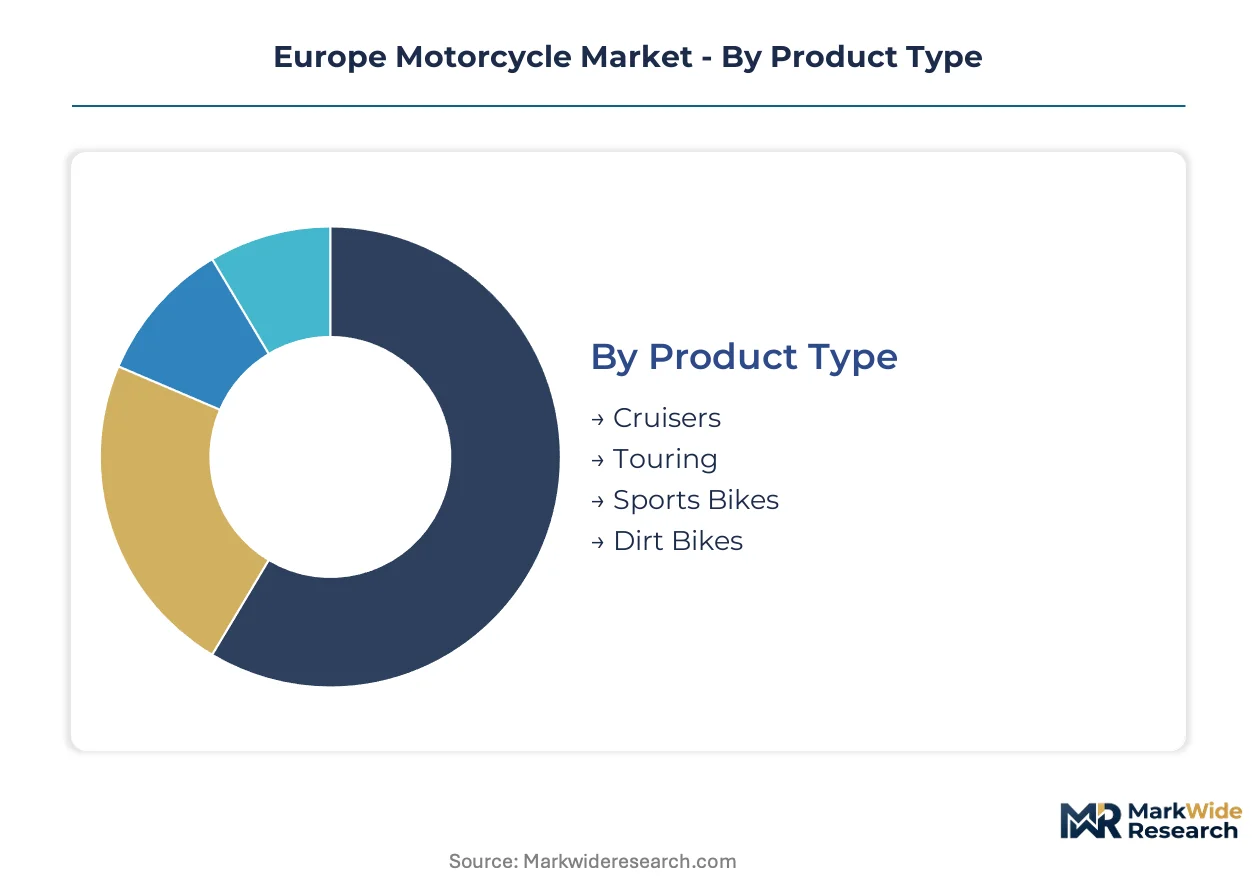
Segmentation in the Europe Motorcycle Market reveals how Euro 5+ compliance costs and urban mobility incentives are redistributing volume across displacement categories and customer types. Manufacturers must align platform development with the divergent requirements of private commuters, fleet electrification mandates, and premium touring enthusiasts.
Product Type:
Regulatory differentiation under Euro 5+ standards creates divergent homologation burdens across product categories, with high-margin segments absorbing certification costs more readily than price-sensitive entry tiers.
- Cruisers:These motorcycles feature low-slung ergonomics, V-twin or parallel-twin engines tuned for low-end torque, and relaxed riding positions optimized for extended highway journeys. Aging rider demographics in Germany and France concentrate demand here, with comfort prioritization offsetting premium pricing. Established volume favors Cruisers; emerging adoption favors Sports Bikes.
- Touring:Full-fairing designs integrate luggage systems, heated grips, and advanced electronics for multi-day travel across European motorway networks. BMW Motorrad's Munich-area production anchors this segment, where integrated manufacturing scale supports the highest margin pools in continental motorcycle retail.
- Sports Bikes:Track-derived aerodynamics, high-revving inline-four engines, and aggressive ergonomics target younger riders in Italy and Spain. Southern European markets sustain volume leadership despite Euro 5+ power-to-weight compliance challenges.
- Dirt Bikes:Lightweight frames, long-travel suspension, and knobby tires serve off-road recreation and competitive enduro racing. Austrian and Italian manufacturers leverage motorsport pedigree to maintain technology leadership in this specialized category.
Margin concentration separates Touring from Cruisers through equipment integration depth; Sports Bikes and Dirt Bikes compete on technology transfer from racing programs rather than manufacturing scale.
Engine Capacity:
Cost tier stratification aligns with urban congestion charging exemptions and fuel economy pressures, compressing demand toward mid-displacement machines that balance municipal toll avoidance with inter-city capability.
- Under 125cc:Single-cylinder engines with automatic transmissions dominate Paris and Milan commuter corridors, where municipal low-emission zones exempt sub-125cc motorcycles from congestion charges. Piaggio Group's Italian production clusters anchor supply for this price-sensitive tier.
- 126-400cc:Parallel-twin and single-cylinder architectures deliver sufficient power for highway merging while maintaining fuel efficiency advantages over larger displacements. This band captures the steepest expansion trajectory as fuel costs and urban toll schemes redirect commuter preferences.
- 401-750cc:Versatile platforms serve touring commuters and entry-level enthusiasts seeking upgrade pathways from smaller machines. Euro 5+ catalytic converter requirements disproportionately burden this mid-tier, consolidating volume toward engineering houses with captive certification resources.
- Above 750cc:Large-displacement inline-four, V-twin, and boxer engines power premium touring and performance segments where emission compliance costs absorb into higher price points. German and Italian manufacturers dominate through integrated powertrain development.
Urban toll policy favors Under 125cc; highway capability and touring comfort favor Above 750cc.
Customer Type:
Application divergence separates individual mobility preferences from institutional procurement requirements, with fleet electrification mandates creating new demand channels distinct from traditional retail patterns.
- Retail Consumers:Individual purchasers select motorcycles for commuting, recreation, and lifestyle expression across all product and displacement categories. Italian and Spanish markets exhibit the highest retail penetration rates in continental Europe.
- Fleet Operators:Municipal and corporate vehicle pools procure electric motorcycles under EU Green Deal decarbonization mandates, requiring platforms that satisfy institutional specifications alongside consumer models. Southern European cities with warmer climates and shorter trip distances respond fastest to these procurement signals.
- Rental Services:Short-term mobility platforms in Barcelona and Paris pilot subscription-based battery service models, separating vehicle purchase from energy storage capital commitment. Younger demographics lacking residential charging infrastructure drive adoption here.
- Commercial Users:Courier and delivery services utilize lightweight motorcycles for urban logistics, prioritizing reliability and operating cost over performance specifications. Congestion zone exemptions in London and Milan reinforce demand concentration.
Volume concentration favors Retail Consumers; policy-driven electrification favors Fleet Operators.
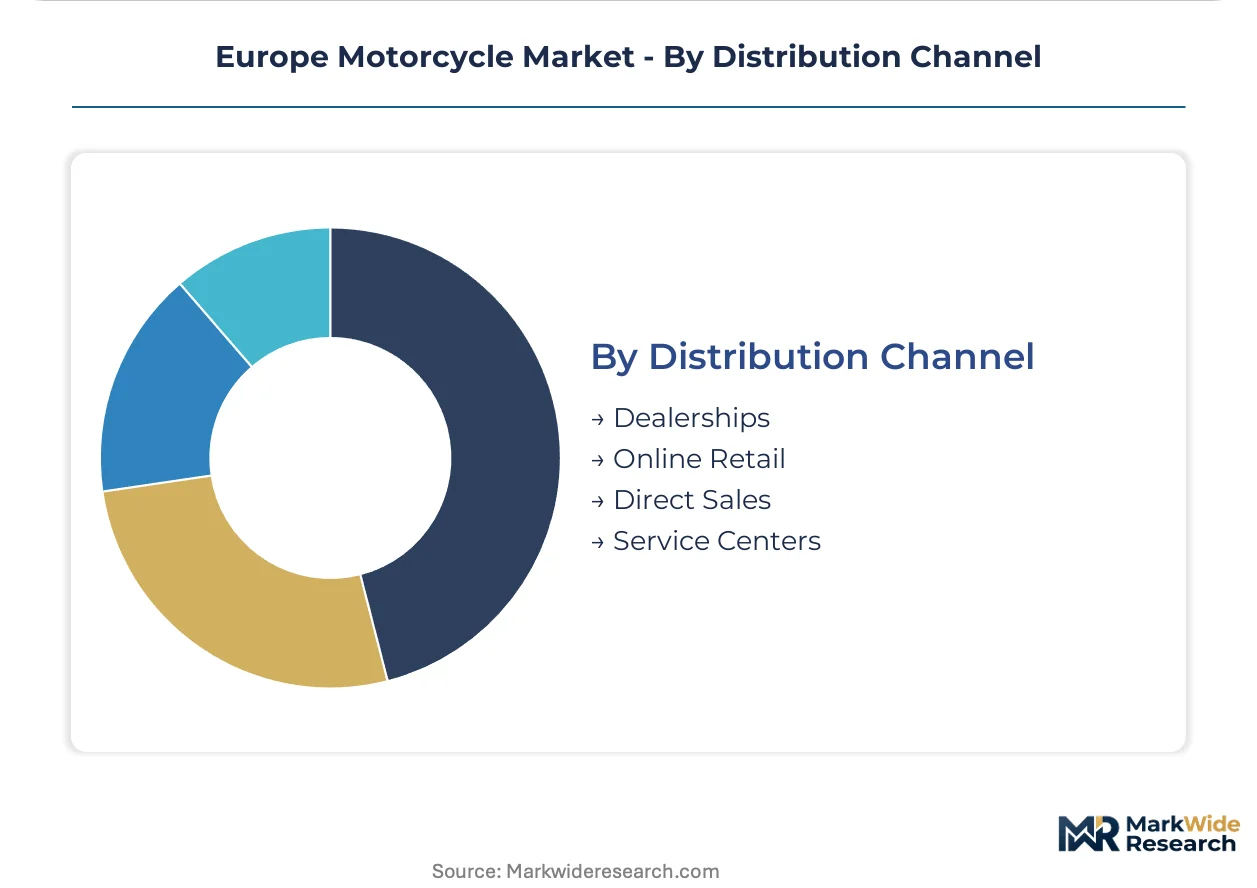
Distribution Channel:
Geography of service capacity determines channel effectiveness, with high-voltage maintenance requirements constraining electrification readiness across traditional dealer networks.
- Dealerships:Authorized retail networks provide test rides, financing, and warranty service across urban and suburban catchments. German and French dealer density supports premium brand penetration.
- Online Retail:Direct-to-consumer platforms reduce geographic constraints for accessories and pre-owned sales, though new motorcycle transactions remain limited by homologation documentation requirements. Digital channels expand fastest in Northern European markets with mature e-commerce infrastructure.
- Direct Sales:Manufacturer-owned showrooms in major metropolitan centers control brand presentation and capture full margin on premium models. BMW Motorrad and KTM AG operate flagship direct retail in Munich and Mattighofen.
- Service Centers:Independent and authorized maintenance facilities face reskilling imperatives for high-voltage system diagnostics as electric motorcycle penetration accelerates. Technician scarcity constrains aftermarket capacity expansion.
Established infrastructure favors Dealerships; electrification transition favors Service Centers with reskilling investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian buyers demonstrate the lowest price elasticity for premium motorcycles, while Eastern European markets exhibit acute sensitivity to acquisition costs. German purchasers occupy a middle position, balancing engineering quality expectations against total cost of ownership. French commuter demand concentrates in sub-400cc tiers where congestion exemptions drive volume.
Italy
Milan and Bologna commuter corridors sustain dense scooter penetration, with younger riders in Rome and Naples favoring sports bike aesthetics. ECHA REACH compliance shapes paint and coating specifications across Piaggio and Ducati supplier networks. The Emilia-Romagna manufacturing cluster anchors continental production volume for sub-125cc urban mobility platforms.
Germany
BMW Motorrad's Munich-area integrated manufacturing supports touring motorcycle dominance among aging riders prioritizing comfort and long-distance capability. KBA type-approval protocols enforce stringent Euro 5+ homologation standards that consolidate certification resources toward larger engineering houses. Bavaria's motorsport technology corridor transfers racing-derived electronics into production motorcycle platforms.
France
Paris municipal low-emission zones exempt sub-125cc motorcycles from congestion charges, redirecting commuter demand toward lightweight two-wheeled mobility. ANSM and CNIL frameworks govern connected vehicle data handling as manufacturers deploy telematics systems. The Île-de-France region hosts manufacturer-backed subscription battery service pilots targeting apartment-dwelling riders lacking residential charging infrastructure.
Spain
Barcelona and Madrid urban cores exhibit rapid adoption of electric motorcycle fleets under municipal decarbonization procurement mandates. The EU Green Deal transport decarbonization framework creates institutional demand channels distinct from traditional retail patterns. Catalan manufacturing partnerships concentrate on battery-swapping infrastructure development for dense metropolitan service station networks.
Poland
Warsaw and Krakow motorcycle ownership rates remain below Western European averages, presenting whitespace for affordable electric commuter platform entry. National regulators align with EU Machinery Directive CE marking requirements for safety-critical component certification. Silesian industrial zones attract component sourcing investments as manufacturers seek Eastern European supply chain diversification.
Europe Motorcycle Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the European motorcycle market. Premium engineering houses with integrated manufacturing scale dominate high-margin touring and performance segments, while mass-market assemblers compete on platform flexibility and multi-brand portfolio breadth. Two strategic archetypes define competitive positioning: motorsport-derived performance specialists and diversified mobility conglomerates with scooter-to-motorcycle range coverage. Dominant competitive moves include captive powertrain development for emission compliance and strategic partnerships for electric platform battery sourcing.
Within the diversified mobility tier, Piaggio Group and Honda Motor Co., Ltd. occupy positions spanning entry-level commuter scooters through mid-displacement motorcycles. BMW Motorrad anchors the premium integrated manufacturing archetype from its Munich-area production base. KTM AG represents the motorsport-derived performance specialist, transferring Austrian racing pedigree into production motorcycle platforms across multiple displacement categories.
| Leading Market Players |
|---|
| Ducati Motor Holding |
| Piaggio Group |
| Honda Motor Co., Ltd. |
| Aprilia |
| Triumph Motorcycles |
| Yamaha Motor Co., Ltd. |
| KTM AG |
| Husqvarna Motorcycles |
| BMW Motorrad |
| Others |
Value Network & Pricing Analysis
Integrated Munich-area manufacturing scale at BMW Motorrad and Piaggio's Emilia-Romagna clusters compress per-unit fixed costs while elevating price floors for mid-tier competitors lacking comparable capacity utilization. This scale asymmetry funnels margin capture toward engineering houses with captive certification resources and tilts competitive dynamics against sub-400cc assemblers facing Euro 5+ homologation burdens.
Pricing Analysis
After-sales revenue from service contracts and genuine parts sustains lifetime value per unit well beyond initial transaction margins. Three-tier pricing structure across premium touring, standard commuter, and economy scooter levels reflects certification grade and equipment integration depth. Pricing pressure stems from semiconductor sourcing volatility that compresses margins on electronically complex models. Fleet operators exhibit acute price sensitivity under municipal procurement mandates, while individual touring enthusiasts absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Inventory lead times for lithium-ion cells and silicon carbide semiconductors extend beyond traditional component procurement cycles, straining just-in-time assembly schedules. Manufacturing concentration in Italy, Germany, and Austria anchors European motorcycle production, with tubular steel frames and aluminum swingarms drawing from Silesian and Bavarian metalworking zones. Single-source vulnerability concentrates in Asian foundries supplying electronic fuel injection chipsets. Distribution runs through authorized dealer networks requiring high-voltage technician reskilling for electrification readiness.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Motorcycle Market represents a high-growth electrification disruption as Euro 5+ emissions standards and EU Green Deal mandates force powertrain platform transitions across all displacement categories.
For Market Incumbents: Shield existing market position through captive battery management system development and backward integration into power electronics sourcing. KTM AG's motorsport-derived R&D spending demonstrates how technology leadership defends against emerging electric-native entrants. Certification investment at Munich-area facilities consolidates homologation resources that smaller competitors cannot replicate.
For New Entrants and Emerging Players: Differentiate on battery-swapping infrastructure partnerships targeting apartment-dwelling urban commuters in Paris and Barcelona lacking residential charging access. Eastern European underpenetration in Poland and Romania presents whitespace for affordable electric commuter platforms below established Western European price points. Direct-to-fleet sales channels bypass dealer network barriers while capturing municipal procurement volume.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors diversified mobility conglomerates with scooter-to-motorcycle portfolio breadth over pure-play performance specialists. Long-term viability across the electrification transition hinges on powertrain platform flexibility and service network electrification readiness. Monitor battery energy density announcements as the critical inflection signal for touring segment electric viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium-ion cell allocation from South Korean or Chinese suppliers for electric platform launches. |
| Power Electronics Partnership | Accesses silicon carbide motor controller expertise from automotive sector talent pools. |
| Dealer Network Reskilling Program | Equips service technicians for high-voltage diagnostics under EU Machinery Directive safety protocols. |
| Battery-Swapping Infrastructure Joint Venture | Deploys metropolitan service station networks in Barcelona and Paris to mitigate range anxiety. |
| Eastern European Manufacturing Footprint | Establishes assembly capacity in Poland or Romania to serve price-sensitive markets below Western European cost bases. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, dealership operations managers, and municipal fleet procurement officers; and secondary validation against KBA type-approval databases, EU Machinery Directive CE marking records, ECHA REACH substance restriction filings, and vehicle production registries. Bottom-up volume modeling triangulated against top-down macroeconomic demand indicators.
Across the projection horizon, the analytical framework segmented volume and value by product type, engine capacity tier, customer archetype, and distribution channel. CAGRs were derived from regression analysis of historical registration patterns against regulatory inflection points and urban mobility policy shifts. Forecast inputs incorporated battery energy density improvement curves and Euro 5+ compliance cost trajectories.
Material uncertainties — semiconductor supply disruption, battery raw material price volatility, and EU Green Deal mandate acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision as electrification technology and regulatory frameworks evolve. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Europe Two-Wheeler Market
Bikes and Motorcycles
Global Bicycle Derailleur Market
Bikes and Motorcycles
United Arab Emirates E-Bike Market
Bikes and Motorcycles
Bike Computer Market
Bikes and Motorcycles
Switzerland E-Bike Market
Bikes and Motorcycles
Two Wheeler Seats Market
Bikes and Motorcycles
China Two Wheeler Market
Bikes and Motorcycles
Motorcycle Wheels Market
Bikes and Motorcycles
E-Mountain Bike Market
Bikes and Motorcycles
Motorcycle Horns Market
Bikes and Motorcycles
Cargo Bike Market
Bikes and Motorcycles
Latin America Two-Wheeler Market
Bikes and Motorcycles
Child Bike Seats Market
Bikes and Motorcycles
Folding Bicycle Market
Bikes and Motorcycles
Global Motorcycles Brake Caliper Market
Bikes and Motorcycles
Sweden E-Bike Market