
 Automotive Fuel Delivery System Market | 2026-2036
Automotive Fuel Delivery System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Fuel Delivery System Market Analysis
German Tier-1 suppliers is recalibrating production footprints across Central European plants to align with shifting OEM demand for high-pressure direct injection hardware. Robert Bosch GmbH leverages its in-house semiconductor capacity to control injector driver module supply. TI Fluid Systems Plc anchors its competitive position through thermal management integration with fuel line architectures. Continental AG differentiates via mechatronic pump systems that reduce NVH profiles in downsized engines.
An automotive fuel delivery system comprises pumps, injectors, regulators, and filtration elements engineered to maintain precise fuel pressure between 35 and 200 bar depending on injection topology, with direct injection architectures requiring the highest operating thresholds to achieve stratified charge combustion. Electronic fuel injection dominates value generation as port and direct injection technologies displace remaining carbureted applications in emerging markets; direct injection commands premium positioning due to precision machining requirements for injector nozzles. OEMs capture the largest demand share in the end-user dimension, though aftermarket providers sustain margin pools in filter replacement cycles and injector refurbishment services.
EPA regulates evaporative emissions and onboard diagnostics under Clean Air Act authority, while Euro 7 standards through EMA and member state type-approval bodies mandate real-driving emission verification that elevates fuel system sealing and pressure control specifications. NHTSA fuel economy standards indirectly shape injector spray pattern optimization targets as manufacturers seek combustion efficiency gains. Stakeholders must monitor the trajectory of synthetic fuel compatibility requirements and their implications for elastomer seal materials across existing platform architectures.
Market Dynamics
High-pressure direct injection architectures are compressing component supplier margins as OEMs consolidate sourcing around integrated pump-injector modules capable of 350 bar operation. This technical threshold escalation favors suppliers with captive machining and semiconductor capabilities.
Growth Catalysts
- EPA Tier 3 particulate limits:Gasoline direct injection systems require advanced fuel pressure control and sealed evaporative circuits, expanding hardware content per vehicle in US-bound production.
- Southeast Asian assembly hub expansion:Thailand, Indonesia, and Vietnam are scaling light commercial vehicle output, pulling electronic fuel injection module demand from regional suppliers.
- Euro 7 real-driving emission protocols:EMA-mandated verification elevates fuel system sealing specifications and onboard diagnostic precision across European type-approval cycles.
Market Restraints
- Specialized alloy input volatility:Inconel and hardened steel prices for high-pressure injector nozzles fluctuate with aerospace and energy sector demand, compressing foundry margins.
- Semiconductor supply concentration:Driver ICs for piezoelectric injectors depend on concentrated East Asian foundry capacity, creating allocation risk during automotive demand spikes.
- Solid-state battery trajectory:Long-term electrification roadmaps from major OEMs threaten downstream investment returns on internal combustion fuel system platforms.
Strategic Opportunities
- Synthetic fuel compatibility gap:E-fuel and renewable diesel chemistries stress existing elastomer seals, creating retrofit and next-generation material specification windows for seal suppliers.
- Aftermarket refurbishment channels:Injector cleaning and remanufacturing services capture margin pools as fleet operators extend vehicle lifecycles under total cost of ownership pressures.
- Thermal-fuel integration:Convergence of fuel line architectures with engine cooling circuits enables module suppliers to expand content per vehicle beyond discrete component sales.
Industry Challenges
- Piezoelectric actuator calibration expertise:The specialized physics knowledge required for nanosecond-precision injector control exceeds available talent pools in traditional hydraulic engineering regions.
- Multi-standard certification timelines:Simultaneous EPA, Euro 7, and China VI validation cycles compress development windows and multiply testing costs for global platform suppliers.
- Legacy port injection integration:Downsized turbocharged engines retaining port injection for particulate control require dual-circuit fuel system architectures that multiply component count and assembly complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Fuel Delivery System Market |
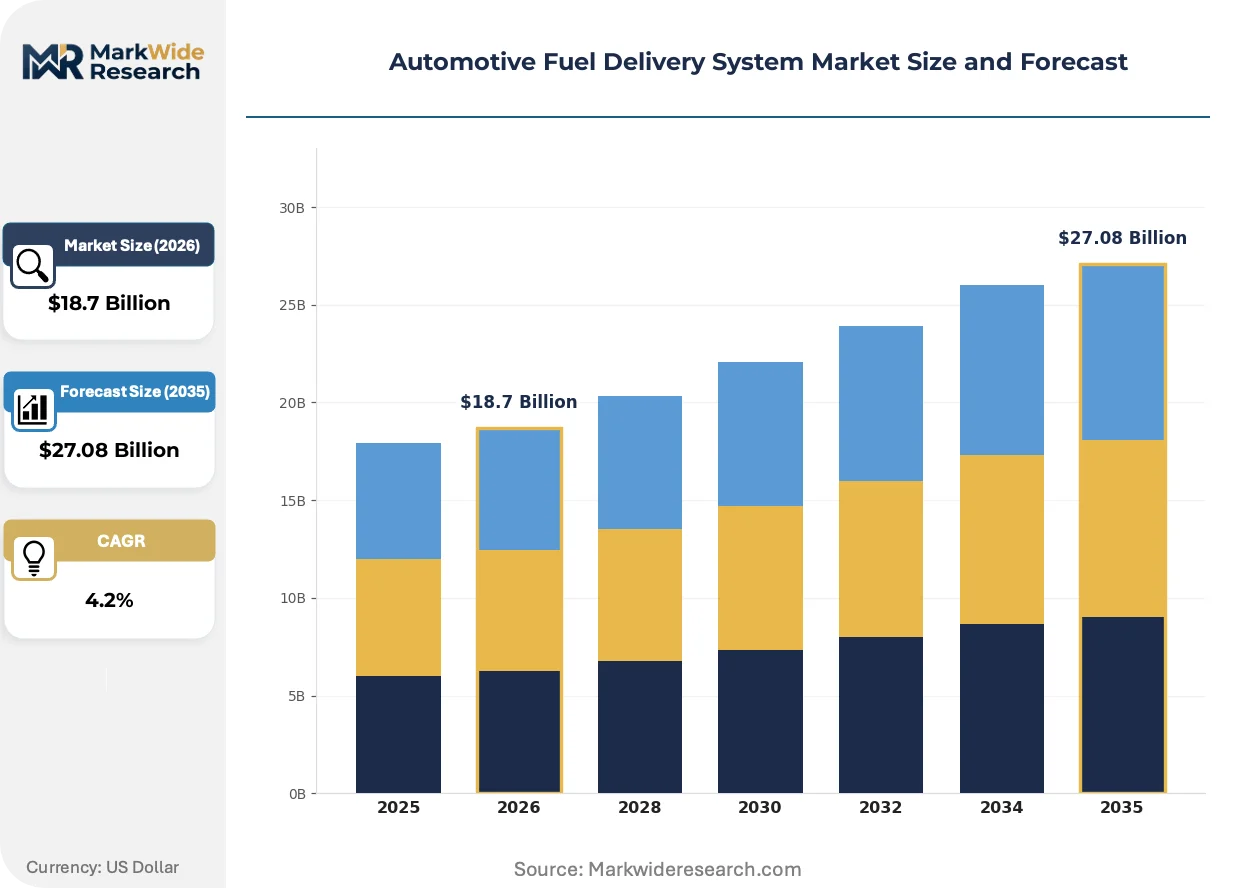
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuel Pumps, Fuel Injectors, Fuel Filters, Pressure Regulators Technology: Electronic Fuel Injection, Carbureted Systems, Direct Injection, Port Injection End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Installation: Onboard, Aftermarket, Retail, Dealerships |
| Companies Covered | Magna International Inc., TI Fluid Systems Plc, Robert Bosch GmbH, Marelli Holdings Co. Ltd., AISIN Corp., Continental AG, Hitachi Astemo Ltd., BorgWarner Inc., DENSO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Fuel Delivery System Market Emerging Trajectories
Electrification-adjacent combustion optimization is redirecting engineering resources toward precision fuel metering and thermal integration rather than displacement expansion. Component boundaries are dissolving as mechatronic systems replace discrete hardware.
Gasoline direct injection is overtaking port fuel injection as the dominant topology for spark-ignition engines, with stratified charge operation enabling lean combustion and particulate filter avoidance. OEMs in Europe and China are mandating GDI adoption for new gasoline platforms by 2027. This topology shift is compressing demand for conventional intake manifold fuel rails while expanding precision machining requirements for multi-hole injector nozzles.
REACH restrictions on perfluoroalkyl substances are forcing seal material transitions in fuel system elastomers, with ECHA evaluations driving fluorocarbon replacement timelines. Compounders must validate hydrogenated nitrile and thermoplastic alternatives under accelerated aging protocols. German and French suppliers face the steepest reformulation curves given their concentration in high-pressure sealing applications.
Fleet operators are unbundling injector refurbishment from dealer service networks, with independent remanufacturers capturing commercial vehicle aftermarket volume through mobile calibration units. Third-party channels now handle approximately one-third of heavy-duty injector exchanges in North America. This channel fragmentation pressures OEM captive parts pricing while elevating diagnostic equipment demand among independent garages.
Automotive Fuel Delivery System Market Segmentation
Technology topology and procurement channel structure determine margin capture and competitive positioning in automotive fuel delivery. Segmentation reveals where precision machining requirements concentrate value and where aftermarket refurbishment sustains recurring revenue pools.
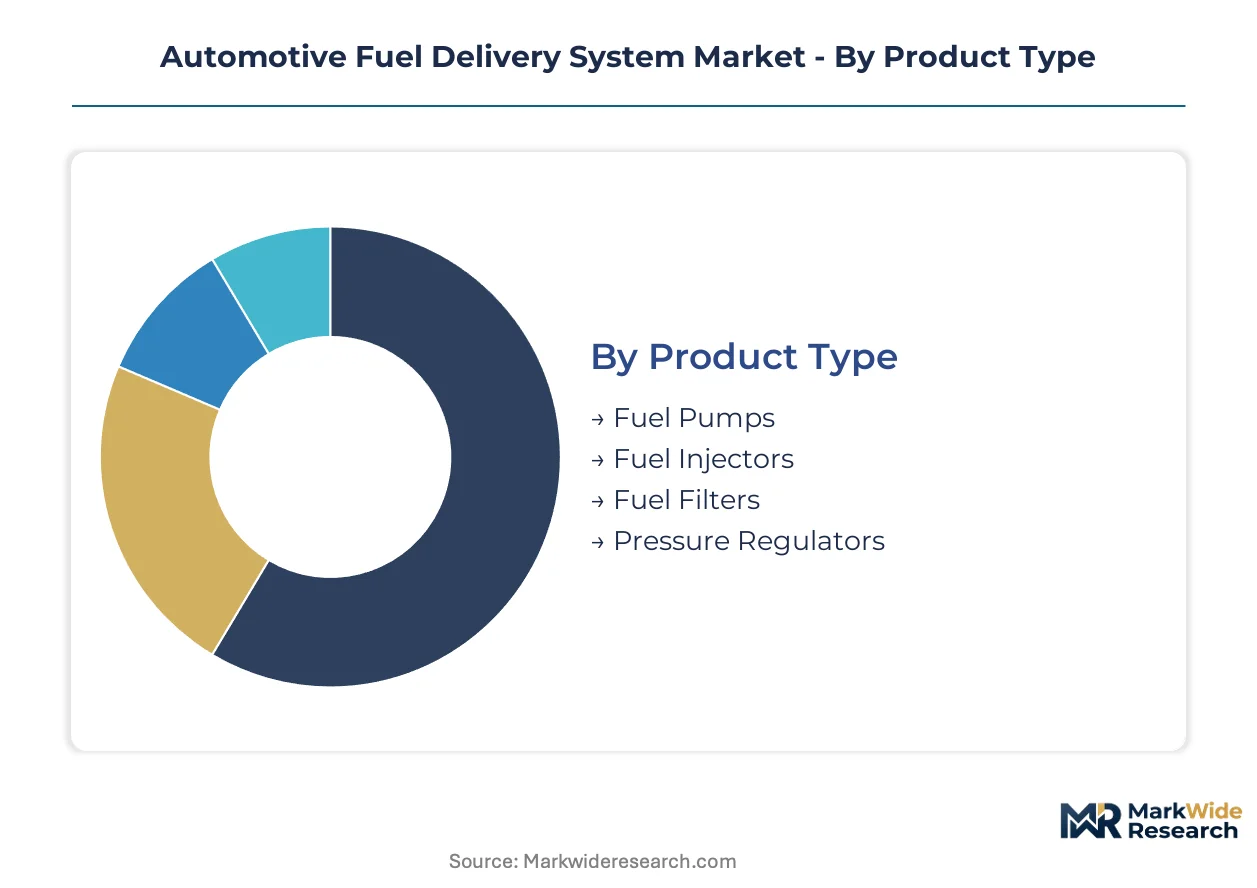
Product Type:
Pressure thresholds and material specifications differentiate component economics across the hardware stack.
- Fuel Pumps:High-pressure gasoline direct injection demands 350 bar capable pump modules with integrated mechatronic control. Demand concentrates in Germany and China as OEMs consolidate sourcing around integrated pump-injector architectures for downsized turbocharged engines.
- Fuel Injectors:Multi-hole nozzle geometries machined from Inconel and hardened steel enable stratified charge combustion with nanosecond pulse precision. Southeast Asian light commercial vehicle assemblers in Thailand and Indonesia are expanding procurement of electronic fuel injection modules as regional hub capacity scales.
- Fuel Filters:Media configurations balance particulate retention against flow restriction across synthetic fiber and cellulose blends.
- Pressure Regulators:Diaphragm-actuated and electronic feedback variants maintain rail pressure stability across transient load conditions.
Fuel pumps lead on scale; fuel injectors lead on momentum.
Technology:
Injection topology selection drives capital allocation toward precision manufacturing or legacy service support.
- Electronic Fuel Injection:Sensor-driven pulse width modulation replaces mechanical metering across port and direct configurations. EPA Tier 3 particulate limits and Euro 7 real-driving emission protocols are accelerating displacement of carbureted architectures in remaining emerging market applications.
- Direct Injection:Cylinder-head-mounted injectors achieve 200+ bar operating pressure for lean stratified operation. China and European OEMs are mandating gasoline direct injection adoption for new spark-ignition platforms, compressing demand for conventional intake manifold fuel rails.
- Port Injection:Intake valve targeting persists in downsized turbocharged engines requiring dual-circuit architectures for particulate control.
- Carbureted Systems:Mechanical venturi metering retains residual demand in small-engine and vintage vehicle applications.
Electronic fuel injection leads on scale; direct injection leads on momentum.
End User:
Channel structure determines pricing power and technical specification authority.
- OEMs:Platform engineering teams specify integrated thermal-fuel architectures and validate 150,000-mile durability cycles.
- Tier-1 Suppliers:Bosch, Continental, and TI Fluid Systems anchor procurement consolidation through captive machining and semiconductor capabilities.
- Aftermarket Providers:Independent remanufacturers capture heavy-duty injector exchange volume through mobile calibration units, now handling approximately one-third of North American commercial vehicle refurbishment demand.
- Vehicle Assemblers:Thailand, Indonesia, and Vietnam assembly hubs pull electronic fuel injection module procurement from regional supplier networks.
OEMs lead on scale; aftermarket providers lead on momentum.
Installation:
Service channel configuration shapes margin retention and customer access economics.
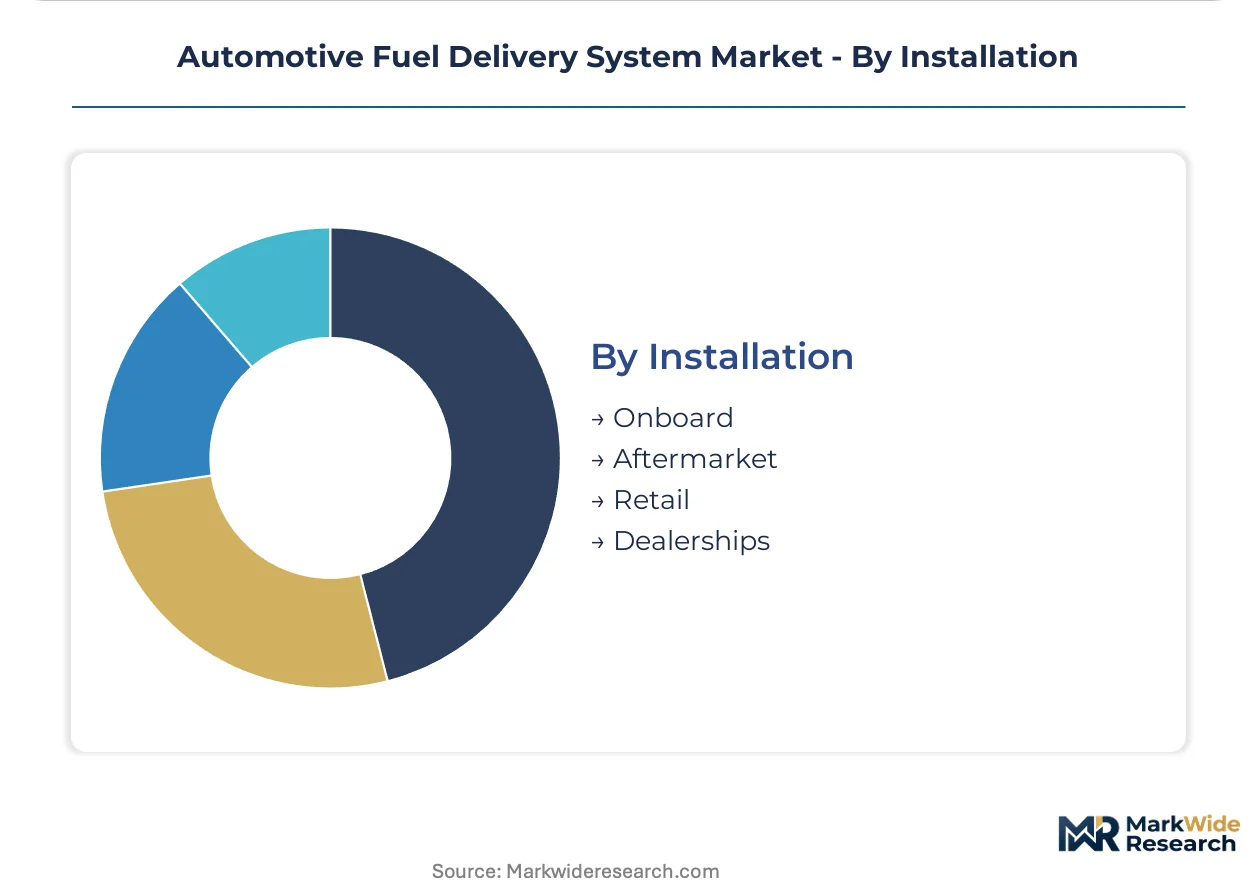
- Onboard:Factory-integrated fuel lines and pump modules ship as calibrated assemblies to assembly plants.
- Dealerships:OEM-captive service networks retain warranty-linked injector replacement and diagnostic calibration revenue.
- Aftermarket:Independent garages and mobile service units capture fleet operator volume under total cost of ownership pressures.
- Retail:Consumer-direct filter replacement and additive sales sustain margin pools in consumable categories.
Onboard installation leads on scale; aftermarket channels lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration patterns track regulatory arbitrage opportunities as OEMs relocate assembly capacity toward jurisdictions with lower compliance costs per unit. Southeast Asian hubs capture light commercial vehicle sourcing as European and North American emission standards tighten. Supplier footprints recalibrate toward regional assembly clusters to minimize logistics exposure and tariff friction.
Germany
High-pressure direct injection hardware demand concentrates around Stuttgart and Munich engineering corridors. Euro 7 real-driving emission protocols through EMA elevate fuel system sealing specifications across type-approval cycles. Continental AG and Robert Bosch GmbH anchor Tier-1 supplier consolidation through captive machining and semiconductor capabilities in Baden-Württemberg.
China
Gasoline direct injection adoption accelerates as domestic OEMs mandate the topology for new spark-ignition platforms by 2027. MIIT-administered China VI emission standards enforce onboard diagnostic precision and evaporative emission control. Yangtze River Delta clusters around Shanghai and Suzhou host precision machining capacity for multi-hole injector nozzles.
United States
EPA Tier 3 particulate limits expand hardware content per vehicle for gasoline direct injection systems in US-bound production. NHTSA fuel economy standards indirectly shape injector spray pattern optimization targets. Detroit-area engineering centers coordinate validation cycles for 350 bar pump-injector modules.
Thailand
Light commercial vehicle assembly hub expansion pulls electronic fuel injection module procurement from regional supplier networks. Board of Investment incentives attract Tier-1 component manufacturing for export-oriented production. Eastern Economic Corridor provinces concentrate fuel system module assembly for Indonesian and Vietnamese re-export.
Japan
Piezoelectric injector calibration expertise concentrates in Nagoya and Tokyo engineering centers. METI industrial policy supports next-generation combustion efficiency research through public-private partnerships. Kanto region suppliers manage semiconductor allocation risk for driver ICs through captive foundry relationships.
Automotive Fuel Delivery System Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue thermal-fuel integration and synthetic fuel compatibility niches. The supplier base concentrates around integrated module architectures capable of 350 bar operation, compressing margins for discrete component specialists. Three archetypes dominate: diversified industrial conglomerates with captive semiconductor capacity, precision machining specialists with aerospace-grade alloy expertise, and thermal systems integrators leveraging fuel line convergence. Competitive moves center on backward integration into driver IC supply and geographic co-location with OEM assembly hubs.
Within the diversified industrial tier, Robert Bosch GmbH and Continental AG exemplify scale-driven positioning through in-house production of critical subsystems. TI Fluid Systems Plc occupies a specialist position anchoring thermal-fuel integration architectures. These three entities represent distinct strategic postures: semiconductor-captive control, mechatronic systems integration, and thermal management convergence.
| Leading Market Players |
|---|
| Magna International Inc. |
| TI Fluid Systems Plc |
| Robert Bosch GmbH |
| Marelli Holdings Co. Ltd. |
| AISIN Corp. |
| Continental AG |
| Hitachi Astemo Ltd. |
| BorgWarner Inc. |
| DENSO Corporation |
| Others |
Supply Flow & Price Mechanics
Euro 7 real-driving emission protocols gate qualified supply access for high-pressure fuel system components, concentrating premium-tier pricing power among suppliers with EMA-validated sealing architectures and captive semiconductor capacity in Germany and China.
Pricing Analysis
Distributor margin compression runs through the aftermarket refurbishment channel as independent remanufacturers capture fleet operator volume through mobile calibration units. Three-tier pricing structure across premium, standard, and economy levels separates OEM-validated injector modules from gray-market alternatives and unbranded consumables. Price differentiation hinges on certification grade and volume scale, with Tier 1 procurement contracts commanding 15-20 point premiums over independent garage sourcing. OEM platform engineering teams exhibit lowest price sensitivity due to warranty-linked durability requirements, while independent aftermarket channels face acute cost compression under total cost of ownership pressures.
Supply Chain Analysis
Single-source vulnerability sits with East Asian foundry capacity for piezoelectric injector driver ICs, creating allocation risk during automotive demand spikes. Component sourcing draws from Germany, China, and Japan for precision-machined Inconel nozzles, hardened steel pump housings, and fluorocarbon elastomer seals. Raw material dependencies rest on aerospace-grade alloy feedstock, semiconductor wafer supply, and hydrogenated nitrile compound formulations. Tariff exposure threatens margin stability across transatlantic pump-injector module shipments. Distribution runs through OEM-captive assembly plant delivery, Tier 1 supplier consolidation hubs, and independent aftermarket logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Southeast Asian assembly hub expansion in Thailand and Indonesia captures cost advantages against tightening Euro 7 compliance investments in European engineering corridors.
For Market Incumbents: Hedge long-term platform obsolescence risk by diversifying into thermal-fuel integration architectures and synthetic fuel compatibility testing. Solid-state battery roadmaps from major OEMs threaten downstream returns on internal combustion fuel systems. Backward integration into driver IC supply and geographic co-location with Yangtze River Delta OEM clusters defend margin position against semiconductor allocation volatility. For New Entrants and Emerging Players: Capture aftermarket refurbishment volume through mobile diagnostic calibration units targeting North American heavy-duty fleet operators. Independent remanufacturers now handle one-third of commercial vehicle injector exchanges, with channel fragmentation accelerating. Synthetic fuel seal retrofit services present the most penetrable white-space as E-fuel chemistries stress existing elastomer specifications. For Investors and Strategic Acquirers: Valuations sit cheapest among precision machining specialists with aerospace-grade alloy expertise but lacking captive semiconductor capacity. Five-to-ten year viability hinges on dual-circuit fuel system architectures for downsized turbocharged engines retaining port injection. Watch for EPA Tier 3 enforcement intensity as the signal indicating sustained hardware content per vehicle versus accelerated electrification displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Supply | Robert Bosch GmbH's captive foundry relationships mitigate piezoelectric driver IC allocation risk during demand spikes. |
| Thermal-Fuel Architecture Convergence | TI Fluid Systems Plc anchors competitive positioning through engine cooling circuit integration with fuel line modules. |
| Synthetic Fuel Compatibility Certification | E-fuel and renewable diesel validation creates retrofit revenue windows as ECHA drives fluorocarbon seal replacement timelines. |
| Geographic Manufacturing Footprint Expansion | Eastern Economic Corridor provinces in Thailand concentrate module assembly for Indonesian and Vietnamese re-export demand. |
| Aftermarket Refurbishment Channel Development | Independent remanufacturers capture margin pools through mobile calibration units handling heavy-duty injector exchanges. |
Methodological Framework
Multiple input streams — OEM platform engineering specifications, Tier 1 supplier production data, and aftermarket channel shipment records — were reconciled through structured primary interviews with fuel system procurement directors, powertrain calibration engineers, and independent remanufacturer operations heads. Secondary validation drew from EPA emission certification databases, EMA type-approval registries, MIIT China VI compliance filings, and vehicle production statistics from IHS Markit registration data. Bottom-up component demand modeling and top-down OEM platform penetration estimates were cross-referenced to anchor volume assumptions.
Data-stream reconciliation across the projection horizon applied segmentation dimensions spanning injection topology, pressure threshold tier, vehicle class, and regional production cluster. CAGRs were derived from fitted growth curves calibrated to OEM platform launch timelines and regulatory phase-in schedules. Industry-specific forecast inputs included gasoline direct injection adoption mandates from European and Chinese OEMs, piezoelectric injector penetration rates, and thermal-fuel integration content per vehicle trajectories.
Electrification roadmap acceleration, semiconductor supply disruption recurrence, and synthetic fuel infrastructure deployment delays are the dominant revision risks to modeled demand. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and OEM platform engineering decisions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
United States Passenger Vehicles Lubricants Market
Automotive Parts
United States Automotive Glass Market
Automotive Parts
Industrial Gearbox and Gear Motors Market
Automotive Parts
Argentina Commercial Vehicles Lubricants Market
Automotive Parts
Splined Sleeves Market
Automotive Parts
Power Steering Oil Market
Automotive Parts
Wiper Systems Market
Automotive Parts
Automotive Antifreeze Market
Automotive Parts
Global Automotive Gasket and Seal Market
Automotive Parts
Automotive Oil and Valve Stem Seals Market
Automotive Parts
Mexico Automotive Parts Zinc Die Casting Market
Automotive Parts
Steering Wheel Armature Market
Automotive Parts
Mexico Automotive Parts Aluminum Die Casting Market
Automotive Parts
Automotive Canister Market
Automotive Parts
Global Automotive Auxiliary Brake Market
Automotive Parts
Automotive Engine Cooling Fan Market