
 Automotive Engine Cam Cover Market | 2026-2036
Automotive Engine Cam Cover Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Engine Cam Cover Market Analysis
Tool-and-die engineering talent scarcity is reorganizing supplier competitiveness across the cam cover value chain. MAHLE sustains broad geographic manufacturing reach through its powertrain division footprint. Continental AG dominates integrated systems supply to German premium vehicle platforms. Dana Incorporated anchors North American commercial vehicle cam cover sourcing through its long-standing OEM relationships.
An automotive engine cam cover seals the cylinder head's camshaft compartment, typically cast from aluminum alloy A380 or fiber-reinforced polyamide to withstand oil exposure and cyclic thermal loading between minus forty and one hundred fifty degrees Celsius. Its primary function prevents lubricant leakage while managing crankcase pressure and reducing valve train noise radiation. Aluminum product types retain the largest installed base owing to decades of foundry process maturity and recyclability, though magnesium variants capture margin pools in performance segments where grams of weight reduction command premium pricing. Plastic compositions accelerate fastest among installation-method categories as snap-on designs eliminate fastener inventories and shorten assembly line cycle times.
EPA fuel economy mandates and NHTSA safety standards jointly pressure OEMs toward lighter cam cover materials without sacrificing structural integrity under crash loads. EU REACH chemical restrictions and ECHA substance-of-very-high-concern listings constrain sealant and coating chemistries available to European suppliers. Stakeholders must monitor how China's MIIT new-energy vehicle production quotas redirect internal combustion engine component procurement volumes toward hybrid architectures requiring redesigned cam cover thermal management.
Market Dynamics
Tool-and-die engineering scarcity concentrates competitive advantage among suppliers with captive casting expertise, while EPA Corporate Average Fuel Economy standards accelerate lightweight material substitution across powertrain architectures.
Growth Catalysts
- EPA fuel economy mandates:OEMs redesign cam covers in aluminum and magnesium alloys to shave grams from powertrain mass and meet fleet-average efficiency thresholds.
- China MIIT new-energy vehicle quotas:Hybrid engine architectures require redesigned thermal management profiles, expanding cam cover procurement volumes for dual-powertrain platforms.
- Snap-on plastic designs:Fiber-reinforced polyamide compositions eliminate fastener inventories and compress assembly line cycle times at tier-one integrators.
Market Restraints
- Aluminum ingot price volatility:A380 alloy feedstock costs fluctuate with LME trading patterns, squeezing foundry margins on fixed-price OEM contracts.
- German supplier concentration:Continental AG and MAHLE control premium integrated-systems supply, creating bottleneck risk for second-tier automakers seeking dual-source strategies.
- EU REACH chemical restrictions:ECHA substance-of-very-high-concern listings constrain sealant and coating chemistries, forcing reformulation cycles that delay platform launches.
Strategic Opportunities
- India commercial vehicle expansion:Domestic truck and bus production growth creates unmet demand for cost-optimized aluminum cam covers in non-premium segments.
- 48V mild-hybrid proliferation:Belt-driven starter-generator architectures require cam-integrated sensors and ventilation routing, opening module-level supplier opportunities.
- Closed-loop aluminum recycling:OEM sustainability targets favor foundries with in-house scrap reprocessing, rewarding capital investment in secondary smelting capacity.
Industry Challenges
- Tool-and-die engineering attrition:Retirement waves among mold designers outpace vocational pipeline output, extending prototype development timelines.
- Multi-material bonding certification:Aluminum-to-polyamide hybrid covers face protracted validation cycles under NHTSA crash-load and thermal-cycling protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Engine Cam Cover Market |
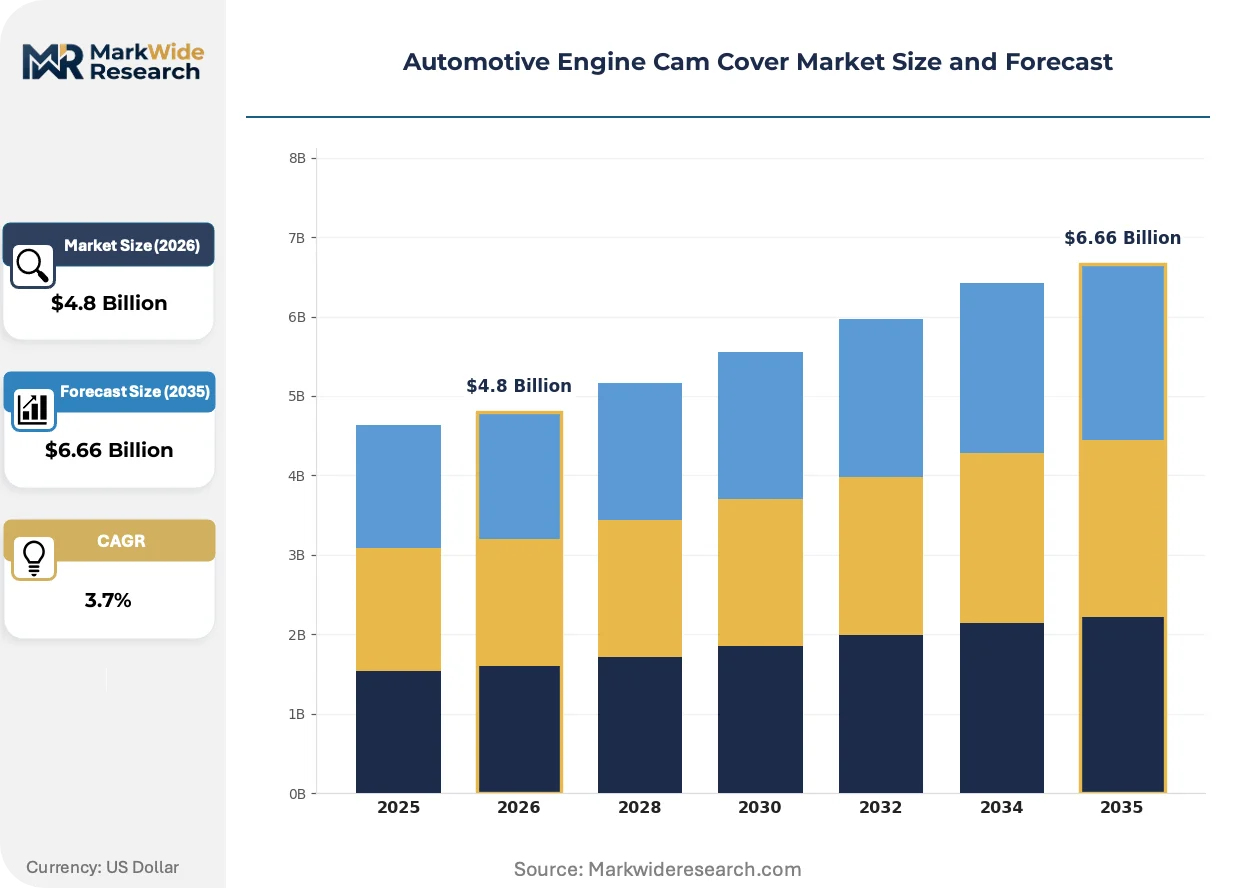
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Plastic, Magnesium, Composite End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Installation Method: Bolt-On, Snap-On, Adhesive, Clip-On Performance Feature: Weight Reduction, Leak Prevention, Heat Resistance, Noise Reduction |
| Companies Covered | Mitsui Kinzoku, Trelleborg, Dana Incorporated, Denso Corporation, MAHLE, Valeo S.A., Continental AG, Röchling Group, Aisin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Engine Cam Cover Market Emerging Trajectories
Material substitution and regulatory chemistry constraints are compressing traditional foundry process advantages while redistributing value toward integrated module suppliers with simulation-driven design capabilities.
Magnesium alloy AZ91D is supplanting aluminum A380 in performance vehicle segments where single-digit gram reductions justify premium pricing. BMW M GmbH and Mercedes-AMG have shifted cam cover procurement toward magnesium die-casting suppliers for turbocharged inline-six architectures. This substitution is compressing the addressable market for conventional aluminum foundries while expanding margin pools for specialized magnesium processors with hot-chamber expertise.
EPA emission enforcement timelines and EU REACH chemical restrictions are jointly constraining coating and sealant formulations available to North American and European suppliers. ECHA substance-of-very-high-concern listings now cover several legacy gasket polymers, forcing compounders to qualify bio-based alternatives under compressed validation schedules. European premium OEMs are responding by consolidating procurement with suppliers holding pre-certified material libraries.
Automaker engineering teams now specify cam covers as thermal-acoustic modules rather than discrete castings, bundling sensors, ventilation valves, and noise-attenuation baffles into single part numbers. Tier-one integrators capture this value migration by offering design-to-cost programs that internalize simulation and rapid prototyping. This behavior shift is most visible in German premium platforms, where Continental AG and MAHLE have displaced standalone foundries from early-stage development.
Automotive Engine Cam Cover Market Segmentation
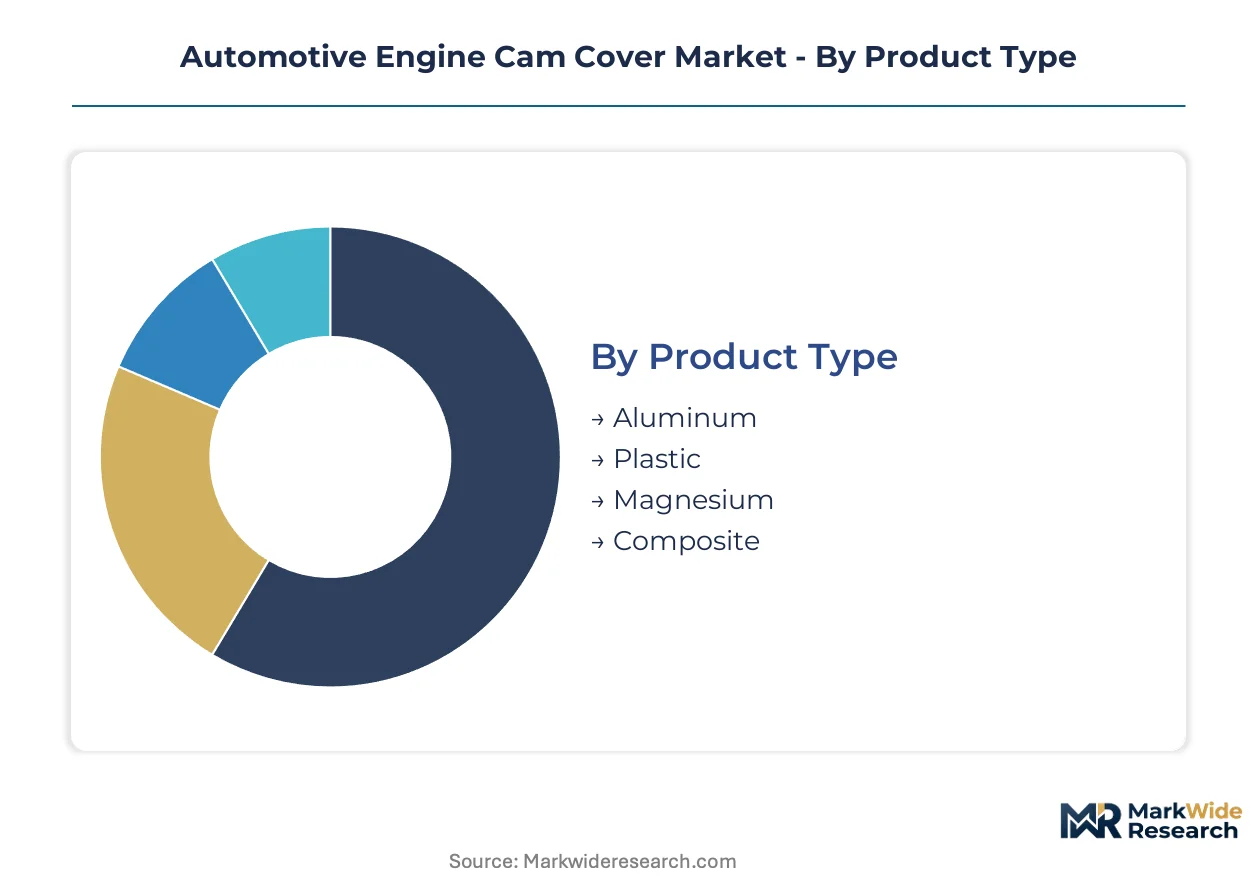
Cam cover procurement splits across material technologies, supply chain tiers, assembly methods, and functional specifications. Each dimension carries distinct regulatory exposure and margin profiles that shape supplier positioning and OEM sourcing strategies.
Product Type:
EPA Corporate Average Fuel Economy thresholds and EU CO2 fleet mandates create divergent material incentives across regional supply bases.
- Aluminum:Cast A380 alloy dominates installed base through foundry process maturity and scrap recyclability. China, Germany, and the United States concentrate procurement volumes where domestic smelting capacity anchors cost structures.
- Plastic:Fiber-reinforced polyamide formulations accelerate fastest among material categories as snap-on designs eliminate fastener inventories and compress assembly cycle times at tier-one integrators.
- Magnesium:AZ91D alloy captures premium performance segments where single-digit gram reductions command pricing power.
- Composite:Hybrid aluminum-polyamide constructions face protracted NHTSA crash-load validation cycles.
Aluminum handles the majority of throughput; plastic is expanding most quickly on share.
End User:
Supply chain tier determines design influence timing and margin capture mechanics.
- OEMs:Vehicle manufacturers specify thermal-acoustic modules rather than discrete castings, bundling sensors and ventilation valves into single part numbers. German premium platforms consolidate procurement with integrators holding pre-certified material libraries under ECHA substance restrictions.
- Tier-1 Suppliers:Continental AG and MAHLE displace standalone foundries from early-stage development through design-to-cost programs that internalize simulation and rapid prototyping capabilities.
- Aftermarket Providers:Replacement demand concentrates in commercial vehicle segments where extended service intervals drive leak-prevention prioritization.
- Vehicle Assemblers:Contract manufacturers in emerging production hubs source cost-optimized aluminum variants for non-premium truck and bus platforms.
OEMs command the design specification authority; tier-one suppliers capture the fastest margin expansion through module integration.
Installation Method:
Assembly line throughput economics and fastener inventory reduction reshape method selection across production footprints.
- Snap-On:Clip-integrated polyamide covers eliminate torque-sequence labor and reduce assembly cycle times. MIIT new-energy vehicle quotas in China accelerate adoption for hybrid platform throughput targets.
- Bolt-On:Traditional threaded fastener retention retains dominance in aluminum and magnesium architectures where structural load paths demand positive mechanical attachment.
- Adhesive:Bonded sealing approaches face REACH-constrained chemistry qualification timelines in European supply bases.
- Clip-On:Hybrid mechanical-adhesive retention serves cost-optimized segments in India commercial vehicle expansion.
Bolt-on methods retain volume leadership; snap-on configurations show the steepest adoption trajectory.
Performance Feature:
Functional specification hierarchies vary by powertrain architecture and regulatory enforcement intensity.
- Leak Prevention:Primary specification across all segments given crankcase pressure management and oil containment liability. ECHA substance-of-very-high-concern listings force gasket polymer reformulation cycles that delay platform launches.
- Weight Reduction:Gram-level mass targets intensify under EPA fuel economy mandates, favoring magnesium substitution in performance segments and plastic in volume production.
- Heat Resistance:Thermal cycling between minus forty and one hundred fifty degrees Celsius demands material stability under 48V mild-hybrid belt-driven starter-generator architectures.
- Noise Reduction:Acoustic attenuation baffle integration shifts value toward module suppliers with simulation-driven NVH capabilities.
Leak prevention anchors baseline procurement requirements; weight reduction is climbing the fastest on specification priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cam cover procurement patterns diverge sharply by geography. China favors plastic snap-on designs for hybrid throughput. Germany specifies magnesium-intensive modules for performance segments. The United States balances aluminum cost efficiency against EPA fleet mandates.
China
MIIT new-energy vehicle quotas accelerate hybrid platform deployment, expanding procurement for dual-powertrain thermal management systems. GB standards for automotive plastics tighten material specifications for under-hood applications. Yangtze River Delta foundries and injection molders concentrate capacity for domestic OEMs and joint-venture partners.
Germany
Premium vehicle manufacturers specify magnesium AZ91D cam covers for turbocharged inline-six architectures where gram-level reductions command pricing premiums. REACH chemical restrictions constrain sealant formulations, consolidating procurement with suppliers holding pre-certified material libraries. Baden-Württemberg engineering clusters anchor Continental AG and MAHLE module development capabilities.
United States
EPA Corporate Average Fuel Economy thresholds pressure powertrain mass reduction without sacrificing structural integrity under NHTSA crash-load protocols. IRA domestic content provisions incentivize North American aluminum smelting and secondary recycling investments. Michigan and Ohio foundry networks supply Detroit Three OEMs with A380 alloy castings for truck and SUV platforms.
Japan
METI carbon neutrality roadmaps redirect supplier R&D toward lightweight material qualification for hybrid and range-extender architectures. JIS standards govern thermal cycling performance between minus forty and one hundred fifty degrees Celsius. Kanto region precision die-casters serve Toyota, Honda, and Nissan with high-volume aluminum and magnesium supply contracts.
India
Commercial vehicle production expansion creates unmet demand for cost-optimized aluminum cam covers in non-premium truck and bus segments. PLI scheme incentives for automotive component manufacturing attract foundry investment from multinational tier-one suppliers. Maharashtra and Gujarat industrial corridors concentrate domestic fabrication capacity for Ashok Leyland and Tata Motors procurement.
Automotive Engine Cam Cover Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in cam cover supply. Continental AG and MAHLE occupy the module-integration apex, displacing standalone foundries from early-stage platform development. Dana Incorporated anchors North American commercial vehicle sourcing through captive OEM relationships. Competitive dynamics center on design-to-cost program capture and geographic manufacturing footprint expansion.
Within the integrated systems tier, Continental AG and MAHLE exemplify the shift toward thermal-acoustic module bundling. Dana Incorporated represents North American commercial vehicle specialization. Mitsui Kinzoku occupies a position in precision metalworking for Asian OEM supply chains. These three anchors illustrate how competitive positioning stratifies across geographic strongholds and powertrain architecture specializations.
| Leading Market Players |
|---|
| Mitsui Kinzoku |
| Trelleborg |
| Dana Incorporated |
| Denso Corporation |
| MAHLE |
| Valeo S.A. |
| Continental AG |
| Röchling Group |
| Aisin Corporation |
| Others |
Supply Flow & Price Mechanics
Magnesium alloy AZ91D substitution for aluminum A380 in German performance platforms simultaneously redistributes supply geography toward Baden-Württemberg hot-chamber specialists and compresses pricing power at conventional foundries serving volume OEMs.
Pricing Analysis
Long-term offtake contracts dominate procurement between German premium OEMs and integrated module suppliers, insulating Continental AG and MAHLE from aluminum ingot volatility while exposing standalone foundries to spot-market A380 alloy swings. Price differentiation separates magnesium-intensive performance tiers from aluminum volume production, with gram-level weight reduction commanding premium positioning under EPA fleet mandates. Cost compression in standard aluminum castings is intensifying because Chinese Yangtze River Delta capacity expansion feeds global oversupply. Tier-one integrators exhibit lowest price sensitivity due to design-to-cost program capture, whereas India commercial vehicle assemblers prioritize cost-optimized bolt-on aluminum variants.
Supply Chain Analysis
Inventory cycles at Yangtze River Delta injection molders run shorter than Baden-Württemberg die-casting lead times, reflecting divergent automation levels across plastic and metal supply bases. Geographic concentration centers on China, Germany, and the United States, with each anchor feeding distinct OEM ecosystems through captive regional networks. Raw material flows draw from LME-traded aluminum ingot, AZ91D magnesium primary production, and glass-fiber reinforced polyamide resin streams. Single-source vulnerability concentrates in German premium module supply where Continental AG and MAHLE control integrated thermal-acoustic development. Distribution runs through tier-one integrators directly to OEM platform engineering teams, bypassing traditional foundry-to-assembler channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in automotive powertrain components are shifting value capture toward module-level suppliers as OEMs bundle sensors, ventilation valves, and NVH attenuation into single part numbers, eroding standalone casting margins.
For Market Incumbents: Shield core module relationships by deepening design-to-cost program engagement with German premium OEMs before 48V mild-hybrid architectures consolidate procurement further. Prioritize captive magnesium hot-chamber capacity investment to defend margin pools against aluminum foundry commoditization. Counter plastic snap-on substitution threat through integrated sensor-embedded aluminum offerings that polyamide cannot replicate.
For New Entrants and Emerging Players: Lead with India commercial vehicle expansion where Ashok Leyland and Tata Motors procurement remains fragmented among local fabricators lacking thermal-acoustic simulation capabilities. Target cost-optimized aluminum bolt-on segments underserved by integrated module suppliers. Pursue PLI scheme qualification to anchor Maharashtra or Gujarat manufacturing footholds before multinational tier-one consolidation accelerates.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-held aluminum foundries lacking module integration capabilities and exposed to Chinese overcapacity pricing. Long-term viability favors specialized magnesium processors and plastic injection molders with hybrid-platform thermal management qualifications. Watch 48V mild-hybrid production ramp rates as inflection signal for cam-integrated sensor demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Module Integration Investment | Bundles sensors and ventilation valves into single part numbers for German premium OEMs. |
| Magnesium Capacity Expansion | Captures gram-reduction premium pricing under EPA Corporate Average Fuel Economy thresholds. |
| India Manufacturing Footprint | Positions for PLI scheme benefits serving Ashok Leyland and Tata Motors commercial platforms. |
| Closed-Loop Aluminum Recycling | Aligns with IRA domestic content provisions and OEM sustainability procurement criteria. |
| Snap-On Plastic Design Qualification | Compresses assembly cycle times for MIIT new-energy vehicle hybrid throughput targets. |
Methodological Framework
Cross-validation between OEM platform engineering disclosures and tier-one supplier procurement patterns anchors the qualitative findings in this study. Primary interviews with powertrain component procurement managers, foundry operations directors, thermal management simulation engineers, and aftermarket distribution heads informed demand-side and supply-side dynamics. Secondary validation drew from EPA fuel economy filings, NHTSA crash-test protocols, ECHA substance-of-very-high-concern listings, MIIT new-energy vehicle production databases, and vehicle registration data. Bottom-up segment sizing triangulated against top-down powertrain production forecasts.
Sensitivity analysis around aluminum ingot price trajectories, magnesium alloy availability, and hybrid platform penetration rates stress-tested projection robustness across the analysis window. The analytical framework modeled segmentation across material technology, installation method, performance feature specification, and supply chain tier, with propulsion architecture and regional production cluster as cross-cutting dimensions. CAGRs derived from regression against historical procurement volumes, adjusted for regulatory enforcement intensity and OEM fleet-mix shifts. Forecast inputs included EPA Corporate Average Fuel Economy compliance timelines and China MIIT new-energy vehicle quota implementation.
Forecasts assume regulatory continuity in EPA, EU REACH, and China MIIT regimes; material policy shifts would require re-modeling. Outputs reflect assumptions around hybrid platform thermal management redesign cycles and tool-and-die engineering pipeline recovery. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Auxiliary Oil Cooler Market
Automotive Parts
Europe Passenger Vehicles Lubricants Market
Automotive Parts
Windshield Repair Kit Market
Automotive Parts
Odometer Market
Automotive Parts
Global Automotive Cylinder Liner Market
Automotive Parts
Industrial Shock Absorbers Market
Automotive Parts
Australia Automotive Parts Magnesium Die Casting Market
Automotive Parts
Norway Automotive Engine Oils Market
Automotive Parts
Suspension Bump Stopper Market
Automotive Parts
UK Automotive Parts Zinc Die Casting Market
Automotive Parts
Camshaft Bearings Market
Automotive Parts
Saudi Arabia Automotive Lubricants Market
Automotive Parts
South Africa Electric Power Steering Market
Automotive Parts
Automotive Exhaust System Market
Automotive Parts
Tappet Market
Automotive Parts
Russia Passenger Vehicles Lubricants Market