
 Shoulder Fixed Weapons Market | 2026-2036
Shoulder Fixed Weapons Market Size, Share, and Industry Trends Forecast 2026-2036
Shoulder Fixed Weapons Market Intelligence
A long-standing procurement focus on conventional Military Forces is unwinding as Special Operations Units gain budget and mission scope. This shift favors suppliers with modular, multi-purpose systems. Saab AB specializes in lightweight anti-armor weapons suited for these new operational contexts. Thales Group competes with advanced guidance and sensor packages, while RTX Corporation leverages its extensive portfolio in guided missile technologies.
Shoulder fixed weapons are man-portable systems, fired from the shoulder, encompassing both single-use and reloadable launchers. They provide infantry squads with direct-fire capability against armor, aircraft, or structures at ranges often exceeding 500 meters. Multi-Purpose systems are displacing single-function Anti-Tank or Anti-Aircraft variants due to enhanced operational flexibility. Advanced Guided Missiles with fire-and-forget capabilities command a significant price premium over less sophisticated unguided rockets.
Procurement is governed by national defense standards, like those from the U.S. Department of Defense, and interoperability mandates such as NATO STANAGs. ISO 9001 compliance is a baseline for manufacturers targeting contracts in the United States, Germany, and France. Investment decisions must balance the high cost of advanced guided systems with the volume needs of conventional infantry.
Market Dynamics
A shift in procurement from conventional armies to Special Operations Units is the market's central force. This change prioritizes demand for modular, lightweight, and multi-purpose systems suited for asymmetric conflicts.
Growth Catalysts
- Military Modernization Programs:Defense upgrades in countries like India drive procurement of new systems to replace aging anti-tank weapons, enhancing infantry combat power.
- Lightweight Material Integration:Use of carbon composites reduces launcher weight, improving soldier mobility and enabling deployment by smaller, agile dismounted teams.
- Asymmetric Warfare Focus:Demand from Special Operations Units for versatile, multi-purpose systems grows with the prevalence of irregular conflict scenarios.
Market Restraints
- High System Cost:The significant price of advanced fire-and-forget guided missiles restricts their widespread issuance to conventional infantry, limiting procurement volumes.
- Export Control Regimes:Strict international arms transfer regulations, including U.S. government end-user verification, create administrative hurdles and delays for export sales.
- Logistical Complexity:Reloadable systems require a complex munition supply chain, while single-use weapons present challenges for training sustainability and disposal.
Strategic Opportunities
- Urban Warfare Systems:Developing weapons with reduced backblast creates a market for systems designed for close-quarters combat in dense urban environments.
- Networked Fire Control:Integrating launchers with battle management systems enables real-time target data sharing, improving squad-level accuracy and coordination.
- Marine Corps Modernization:Equipping naval infantry forces with modern anti-structure capabilities addresses a specific and growing modernization requirement in key regions.
Industry Challenges
- Legacy System Integration:Making new digital fire control systems interoperate with older analog command networks presents a significant technical hurdle for end-users.
- Component Supply Bottlenecks:The supply chain for critical parts like advanced seekers is highly concentrated, creating risks of production delays and price instability.
- Interoperability Mandates:Evolving NATO STANAGs require manufacturers to invest in frequent redesigns and costly recertification processes to ensure compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shoulder Fixed Weapons Market |
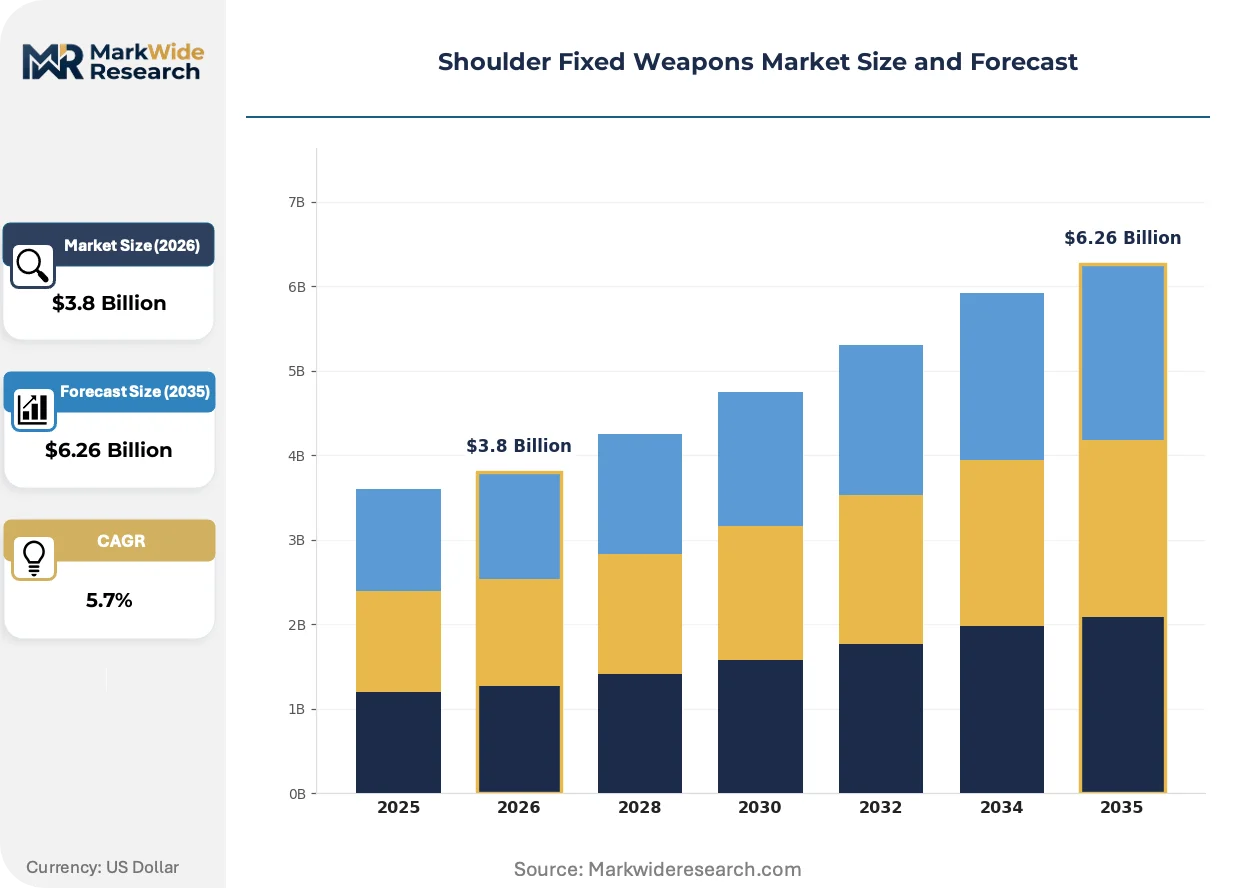
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-Tank, Anti-Aircraft, Anti-Personnel, Multi-Purpose Technology: Guided Missiles, Unguided Rockets, Heat-Seeking, Laser-Guided, Wire-Guided Application: Infantry Support, Vehicle Mounting, Reconnaissance, Defensive Operations End User: Military Forces, Special Operations Units, Paramilitary Groups, Homeland Security Agencies |
| Companies Covered | Lockheed Martin Corporation, Saab AB, Thales Group, MBDA, RTX Corporation, RAFAEL Advanced Defense Systems Ltd., Raytheon Company, BAE Systems plc, Northrop Grumman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shoulder Fixed Weapons Market Strategic Shifts & Innovations
The market's evolution is defined by a push for embedded intelligence and operational flexibility. Development focuses on enhancing user effectiveness in complex environments, moving beyond simple improvements in range or destructive power.
Multi-purpose warhead technology enables a single missile to engage diverse targets including armor, fortifications, and personnel. Special Operations Forces and rapid deployment infantry are primary adopters, valuing the tactical versatility it provides. This technology is decomposing the traditional market divide between dedicated anti-tank and anti-structure weapons, creating a consolidated multi-role category.
NATO STANAGs governing munition interoperability and data protocols are becoming more prescriptive. This regulatory pressure compels manufacturers to design systems with modular, open architectures, facilitating component use from different suppliers. European defense programs are most affected, often requiring co-development to meet strict joint procurement mandates.
A notable behavioral change involves moving from acquiring standalone launchers to procuring integrated lethal-effects packages. This disrupts the legacy model of selling hardware in isolation, bundling simulators, training aids, and networked sights. This comprehensive procurement approach is most visible within the defense programs of the United States and Germany.
Shoulder Fixed Weapons Market Segmentation
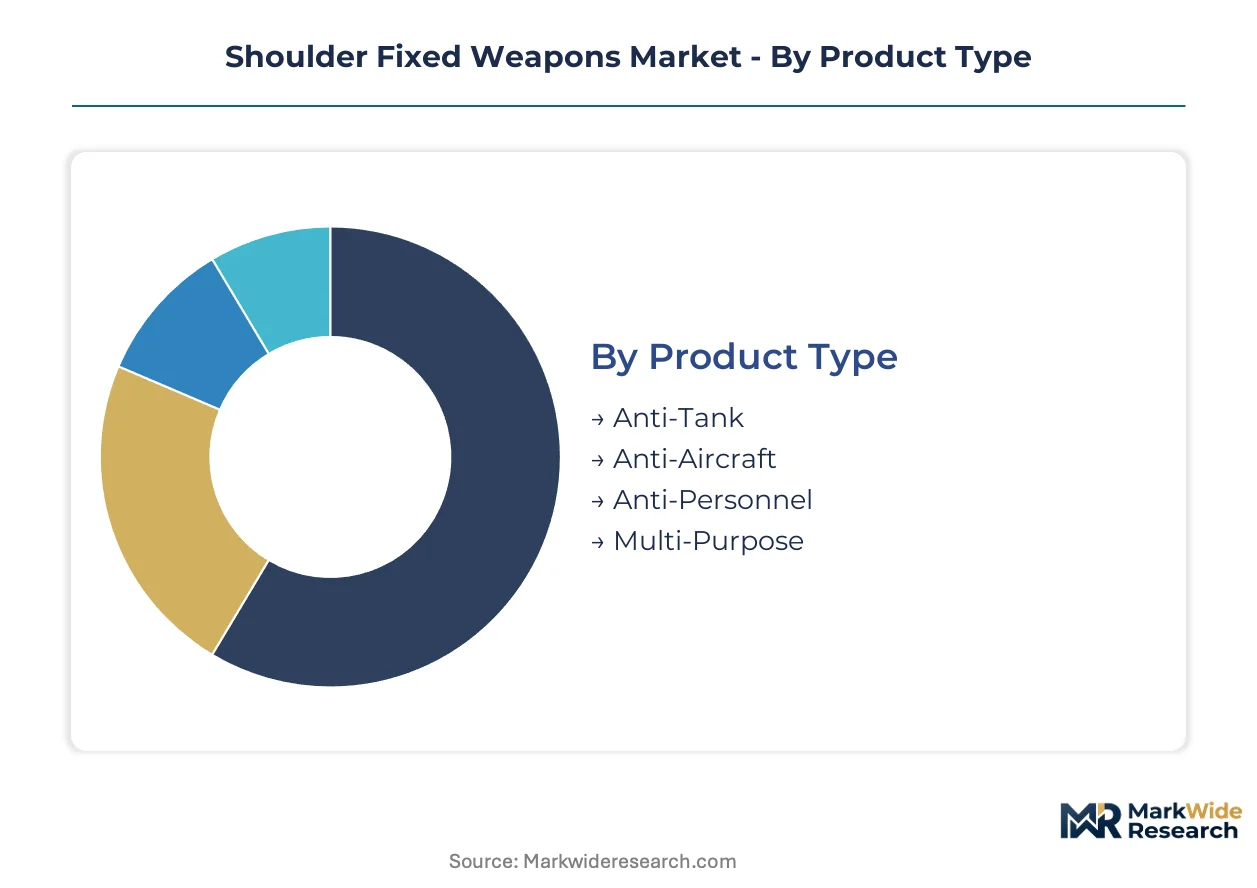
The Shoulder Fixed Weapons market segments across product type, underlying technology, primary application, and end-user categories. Understanding these distinctions helps identify where specialized capabilities drive procurement and where volume demand sustains established product lines. This segmentation illuminates the varied operational requirements shaping product development.
Product Type:
Margin pools within the product type category disproportionately accrue to systems offering advanced capabilities and multi-target versatility. Specialized warhead designs and integrated guidance modules elevate the value proposition for defense contractors.
- Multi-Purpose:These systems feature warheads capable of engaging diverse targets, including armored vehicles, fortified positions, and personnel, often through selectable detonation modes. Special Operations Forces prioritize these weapons for their tactical flexibility in complex operational environments like urban areas.
- Anti-Tank:Designed primarily to defeat main battle tanks and other heavy armored vehicles, these weapons typically employ shaped charges to penetrate reactive armor. India's military modernization programs drive significant demand for new anti-tank systems to replace aging platforms.
- Anti-Aircraft:These shoulder-fired missiles target low-flying aircraft or helicopters, utilizing infrared or other forms of guidance to intercept airborne threats. Conventional infantry units deploy these for point defense against aerial incursions.
- Anti-Personnel:Weapons in this category are optimized for engaging dismounted enemy combatants or light-skinned vehicles, often employing fragmentation warheads. Paramilitary groups and internal security forces utilize these for crowd control and area denial.
Anti-Tank systems hold installed capacity. Multi-Purpose systems are rotating up the share rankings.
Technology:
The cost tier of shoulder fixed weapons directly correlates with their technological sophistication, particularly regarding guidance and propulsion systems. Advanced technologies command premium pricing due to their precision and reduced collateral damage.
- Guided Missiles:These weapons incorporate sophisticated guidance systems, such as fire-and-forget capabilities, allowing the projectile to track its target autonomously after launch. RTX Corporation leverages its extensive portfolio in guided missile technologies for high-value contracts.
- Heat-Seeking:A type of guided missile, these systems detect and home in on the infrared signature emitted by aircraft engines or vehicle exhausts. This technology provides an effective countermeasure against airborne threats in various combat scenarios.
- Unguided Rockets:These simpler, less expensive projectiles rely on direct line-of-sight aiming and ballistic trajectories for impact. Many conventional infantry units still rely on unguided rockets for basic anti-armor or anti-structure roles.
- Laser-Guided:These missiles follow a laser beam or reflect off a laser spot designated by the operator or another platform, offering high precision against stationary or slow-moving targets. Special Operations Units use these for pinpoint strikes in urban settings.
- Wire-Guided:An older guidance method where a thin wire unspools from the missile, transmitting commands from the launcher to the projectile. These systems provide a cost-effective guided solution, particularly for anti-tank applications.
The market for Guided Missiles is expanding most quickly, driven by precision requirements, contrasting with Unguided Rockets' steady demand in volume-driven procurement.
Application:
Volume demand for shoulder fixed weapons varies significantly across different application areas, with infantry support representing the largest segment due to widespread military doctrine. Specialized applications often require tailored system configurations.
- Infantry Support:These weapons augment the firepower of dismounted infantry squads, providing immediate direct-fire capability against a range of threats, from armored vehicles to fortified positions. Military modernization programs in India focus heavily on enhancing infantry combat power.
- Defensive Operations:Systems deployed for defensive operations primarily protect fixed installations, forward operating bases, or high-value assets from ground or aerial attacks. These applications often involve pre-positioned systems or rapid response units.
- Vehicle Mounting:While primarily shoulder-fired, some systems can be adapted for mounting on light tactical vehicles, providing enhanced mobility and sustained firepower. Reconnaissance units sometimes integrate these for mobile anti-armor capability.
- Reconnaissance:Light, man-portable systems are crucial for reconnaissance teams needing discreet anti-armor or anti-structure capabilities without compromising mobility. Special Operations Units favor these for covert missions.
Demand for Infantry Support remains high, but Defensive Operations is gaining share fastest due to increasing threat complexities.
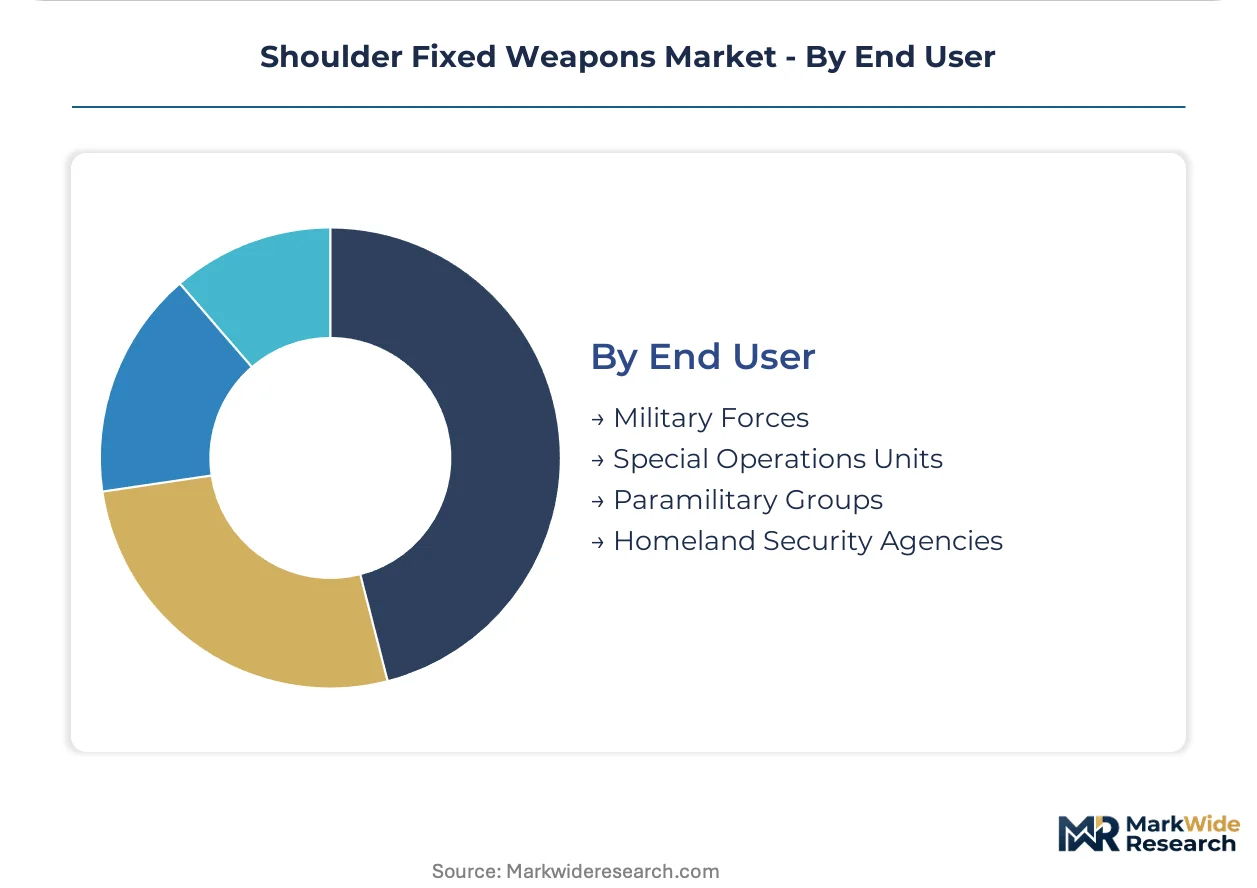
End User:
Customer type dictates procurement priorities, with Special Operations Units emphasizing modularity and multi-purpose capabilities over sheer volume. Conventional military forces balance cost-effectiveness with broad deployment needs.
- Special Operations Units:These elite forces prioritize lightweight, multi-purpose, and highly accurate systems for asymmetric warfare and rapid deployment scenarios. Saab AB specializes in anti-armor weapons suited for these operational contexts.
- Military Forces:Conventional military forces procure shoulder fixed weapons for widespread issuance to infantry battalions, focusing on robust, easy-to-operate systems with established logistical support. Procurement is governed by national defense standards like those from the U.S. Department of Defense.
- Paramilitary Groups:These non-state or semi-state actors acquire weapons based on availability, cost, and suitability for irregular warfare tactics. Logistical complexity for reloadable systems presents challenges for these groups.
- Homeland Security Agencies:These agencies procure specialized systems for critical infrastructure protection, counter-terrorism operations, and urban security, often with requirements for reduced collateral damage. Urban warfare systems with reduced backblast are highly valued here.
The Military Forces segment shows substantial investment, while Special Operations Units procurement is driven by mission-specific needs and advanced technology requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Operations Units drive demand for shoulder fixed weapons globally, with key procurement hubs emerging in nations investing heavily in defense modernization. These specialized units prioritize versatile, lightweight systems for asymmetric conflicts. Military forces also maintain significant volume demand across various regions.
India
India's military modernization programs fuel significant demand for new shoulder fixed weapons, replacing aging anti-tank platforms to enhance infantry combat power. The PLI scheme supports domestic defense manufacturing, encouraging local production of advanced systems. Bengaluru and Hyderabad clusters focus on defense R&D and production, developing next-generation munitions.
United States
United States procurement is driven by both Special Operations Units and conventional military forces, seeking advanced, multi-purpose systems. U.S. Department of Defense standards govern all acquisitions, ensuring interoperability and performance. The defense industry in cities like Orlando, Florida, and Huntsville, Alabama, develops advanced guided systems and fire control technologies.
Germany
German investment decisions balance the high cost of advanced guided systems with the volume needs of conventional infantry. Manufacturers targeting German contracts must meet ISO 9001 compliance as a baseline. Munich's defense sector pioneers networked fire control solutions, integrating launchers with battle management systems.
France
French procurement is heavily influenced by NATO STANAGs and joint European defense programs requiring modular, open architectures. Manufacturers target contracts demanding strict ISO 9001 compliance for quality assurance. The aerospace and defense cluster around Toulouse develops advanced sensor packages and guidance modules for precision weapons.
Israel
Israel focuses on urban warfare systems and advanced guidance solutions to meet specific regional security requirements. The Ministry of Defense drives local defense innovation, prioritizing systems with reduced collateral damage. Tel Aviv's high-tech defense ecosystem develops cutting-edge precision munitions and counter-terrorism weapon systems.
Shoulder Fixed Weapons Market Key Industry Players
Player mix skews toward large, integrated defense contractors, complemented by specialized technology developers. This market structure features a tiered competitive landscape. Strategic archetypes include multi-national prime contractors, niche guidance system providers, and composite material innovators. Companies engage in portfolio diversification and technology licensing to maintain competitive advantage.
Within the advanced guided missile segment, RTX Corporation leverages its extensive portfolio in guided missile technologies for high-value contracts. Saab AB, a Swedish-based defense and security company, represents a key player specializing in lightweight anti-armor weapons suited for new operational contexts. Thales Group, a French multinational, exemplifies providers offering advanced guidance and sensor packages, competing on technological sophistication.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Saab AB |
| Thales Group |
| MBDA |
| RTX Corporation |
| RAFAEL Advanced Defense Systems Ltd. |
| Raytheon Company |
| BAE Systems plc |
| Northrop Grumman Corporation |
| Others |
Cost & Logistics Intelligence
Extended lead times for advanced guidance modules directly impact the supply chain's agility and influence overall system pricing. This dynamic shapes procurement cycles for specialized shoulder fixed weapons.
Pricing Analysis
The pricing gap between advanced guided missiles and unguided rockets remains significant, reflecting their differing technological sophistication. Per-unit transactional pricing dominates, with value-based differentiation for advanced fire-and-forget capabilities. Customization levels for multi-purpose warheads and compliance with NATO STANAGs drive price differentiation. Pricing softness stems from the high cost of advanced systems restricting widespread conventional infantry issuance. Special Operations Units are least price-sensitive, valuing precision, while paramilitary groups are highly price-sensitive.
Supply Chain Analysis
Port congestion and container availability challenges impact the inbound logistics of critical components for shoulder fixed weapons. Geographic supply concentration for advanced seekers centers primarily in the United States and Europe, particularly France and Germany. Raw material dependencies include carbon composites for launchers and specialized rare-earth elements for guidance systems. Single-source vulnerability for advanced seekers represents a structural risk. Distribution runs through direct sales to national defense ministries and authorized defense contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a fragmentation opportunity, driven by the shift towards Special Operations Units prioritizing modular, multi-purpose systems for asymmetric warfare. These evolving mission requirements create distinct niches for specialized weapon development.
For Market Incumbents: Compound existing R&D investments in multi-purpose warhead technology to maintain a competitive edge against emerging threats. Expand manufacturing capacity for composite materials, reducing reliance on external suppliers and mitigating component supply bottlenecks. The threat of new entrants with agile development cycles necessitates continuous innovation in networked fire control. Investing in ISO 9001 certification across all product lines strengthens market access in key European defense programs.
For New Entrants and Emerging Players: A service-layer gap exists in integrating legacy systems with new digital fire control networks, which incumbents often under-serve. Target urban warfare systems with reduced backblast for homeland security agencies and special operations, a highly penetrable segment. Develop modular launcher platforms that allow for easy upgrades and customization. A strong go-to-market angle involves offering comprehensive lethal-effects packages, bundling training and simulators, to address evolving procurement models.
For Investors and Strategic Acquirers: Long-term, this sits as a technology-driven consolidation play because advanced guidance and material science capabilities are highly concentrated. Seek acquisition targets with proven expertise in fire-and-forget guidance systems or lightweight composite manufacturing. Focus on mid-cap specialists possessing proprietary advanced seeker technology. The increasing interoperability mandates from NATO STANAGs serve as a key signal to watch for further market consolidation opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: Next-Gen Multi-Purpose System | This initiative directly addresses the growing demand from Special Operations Units for versatile battlefield capabilities. |
| Strategic Partnership: Guidance Technology Integration | Collaborating with Thales Group enhances precision and fire-and-forget capabilities for future weapon platforms. |
| Capacity Expansion: Composite Launcher Production | Increasing output of lightweight launchers supports broader deployment by agile dismounted teams. |
| Acquisition of Specialist Firm: Advanced Seeker Developer | Securing critical component supply chains for advanced seekers mitigates production delays and price instability. |
| Certification Program: NATO STANAG Compliance | Ensuring interoperability with alliance standards unlocks significant procurement opportunities within European defense programs. |
Research Approach
A standing panel of defense procurement officers, Special Operations commanders, and R&D engineers provided ongoing calibration for this study. Primary interviews with industry stakeholders, including manufacturers like Saab AB and RTX Corporation, were combined with secondary validation. This included analysis of U.S. Department of Defense procurement reports, NATO STANAG documents, and trade data. Bottom-up and top-down triangulation ensured data consistency across all segments.
Outputs were validated against external benchmarks from national defense budgets and military modernization program spending across the analysis window. The analytical framework modeled segmentation dimensions by product type, technology, application, and end-user categories. Compound annual growth rates were derived from historical trends and projected procurement shifts. Key forecast inputs included anticipated defense spending by India and projected integration rates of networked fire control systems.
Forecasts assume regulatory continuity in U.S. and European export control regimes; material policy shifts would require re-modeling. The analysis reflects current geopolitical tensions and technological development trajectories. Component supply bottlenecks and evolving interoperability mandates represent key risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Asia-Pacific Cruise Missile Market
Weapons and Ammunition
Guns and Accessories Market
Weapons and Ammunition
North America Small Arms Market
Weapons and Ammunition
Next-Generation Assault Rifles Market
Weapons and Ammunition
Europe Ammunition Market
Weapons and Ammunition
Space Weapons Market
Weapons and Ammunition
Light Weapons Market
Weapons and Ammunition
North America Nuclear Bombs and Missiles Market
Weapons and Ammunition
Missile Launching Systems Market
Weapons and Ammunition
Land-Based Remote Weapon Stations Market
Weapons and Ammunition
Asia-Pacific Medium and Large Caliber Ammunition Market
Weapons and Ammunition
Automatic Weapons Market
Weapons and Ammunition
Artillery Ammunition Market
Weapons and Ammunition
Military Fire Control Systems Market
Weapons and Ammunition
Large Caliber Ammunition Market
Weapons and Ammunition
Asia-Pacific Ammunition Market