
 Smoke Grenade Market | 2026-2036
Smoke Grenade Market Size, Share, and Industry Trends Forecast 2026-2036
Smoke Grenade Market Outlook
Government contract channels is fragmenting as defense ministries diversify suppliers beyond traditional primes. Rheinmetall AG leverages its integrated pyrotechnics division to sustain captive supply of potassium chlorate-based formulations. Chemring Group PLC competes through specialized exhaust-scrubbed manufacturing lines that navigate tightening environmental standards.
A smoke grenade is a self-contained pyrotechnic device that generates dense particulate aerosol through controlled combustion of smoke-generating agents such as hexachloroethane-zinc or potassium chlorate-sugar mixtures, typically achieving obscuration densities measured in extinction coefficients per meter. Its primary purpose is battlefield concealment, crowd dispersal, or firefighter training simulation by degrading visual and infrared target acquisition. Handheld configurations retain the largest volume share across military applications, while vehicle-mounted systems represent the fastest-expanding margin pool as mechanized units prioritize rapid-deploy obscurant capabilities. Law enforcement procurement of portable units shows structural growth tied to urban riot-control doctrine shifts, though civilian events remain a constrained segment due to municipal permitting barriers.
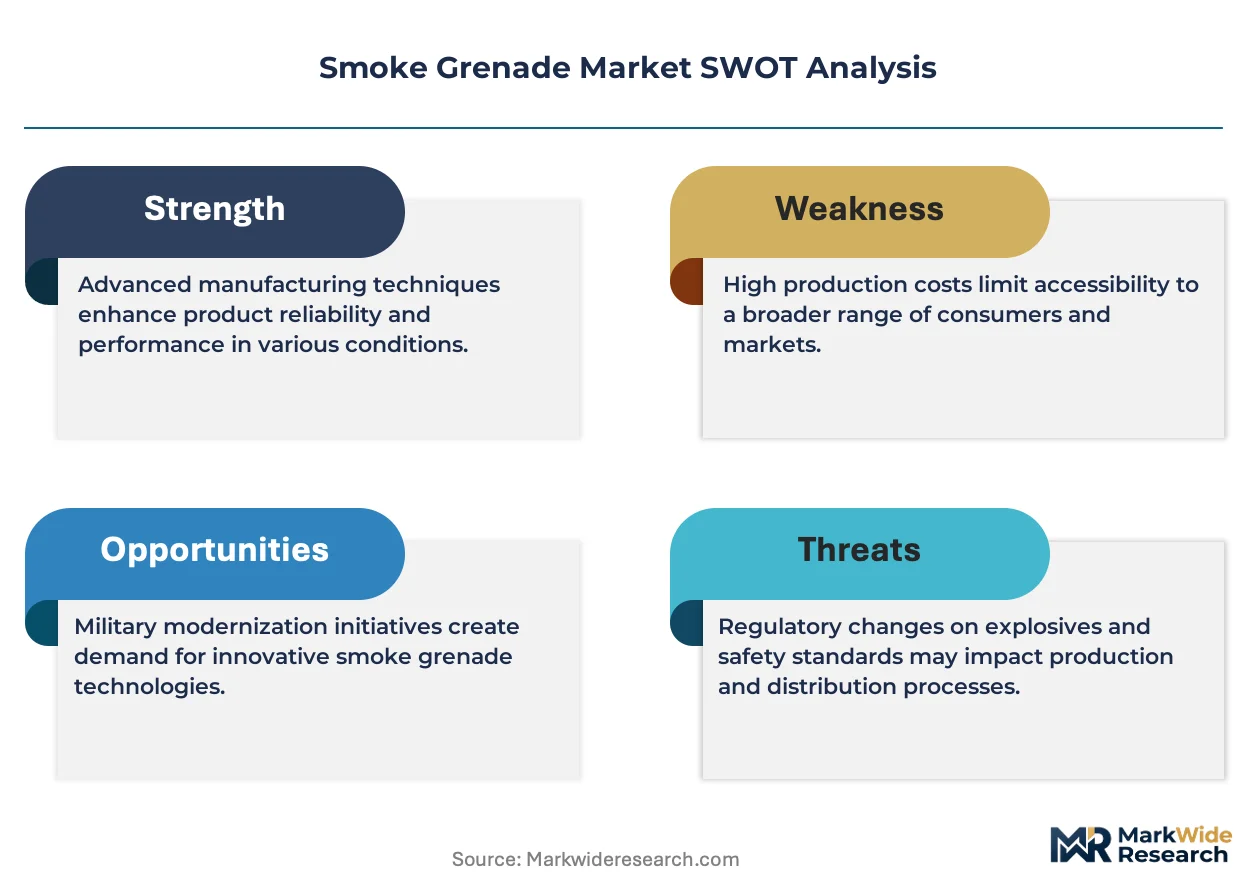
EPA enforcement of Clean Air Act provisions and REACH restrictions on chlorinated organic precursors are reshaping formulation chemistry across North American and European supply chains. Bundeswehr technical delivery standards and NATO STANAG 4385 additionally define performance benchmarks for infrared attenuation and burn-duration consistency. Stakeholders must monitor pending regulatory reclassifications of colored smoke colorants as the EU ECHA evaluates stricter hazard designations for heavy-metal-based dyes.
Market Dynamics
Reformulation pressure from REACH and EPA restrictions on hexachloroethane is compressing incumbent supply chains while accelerating potassium-based chemistry adoption across NATO procurement channels.
Growth Catalysts
- Vehicle-mounted obscurant systems:Mechanized units in Germany and Poland are expanding orders for rapid-deploy vehicle systems under Bundeswehr modernization contracts.
- REACH Annex XVII restrictions:Tightening EU controls on chlorinated organic precursors are forcing incumbent manufacturers toward potassium chlorate-sugar formulations with superior environmental profiles.
- Urban riot-control doctrine shifts:Law enforcement agencies in France and Belgium are restructuring portable unit procurement around crowd dispersal protocols.
Market Restraints
- Potassium chlorate supply concentration:Raw material sourcing clusters in Eastern European chemical corridors create single-point vulnerability for reformulated smoke agents.
- EPA Clean Air Act compliance costs:Exhaust-scrubbed manufacturing line investments add capital intensity for North American production facilities.
- Infrared-transparent legacy formulations:Older hexachloroethane-zinc mixtures fail NATO STANAG 4385 attenuation benchmarks, forcing premature inventory retirement.
Strategic Opportunities
- Firefighter training simulation expansion:Municipal emergency response departments in Canada and Australia are adopting smoke grenades for realistic scenario replication.
- Colored smoke colorant reclassification gap:EU ECHA evaluation of heavy-metal dye hazards creates first-mover advantage for organic pigment developers.
- Dual-use civilian event permits:Festival and film production coordinators in California and New South Wales are navigating municipal permitting barriers for theatrical obscurant deployment.
Industry Challenges
- Pyrotechnic chemist talent scarcity:Specialized formulation expertise for potassium-based combustion control remains concentrated among retiring defense-industry veterans.
- NATO STANAG 4385 certification timelines:Burn-duration consistency and infrared attenuation testing protocols extend product qualification cycles by 18-24 months.
- Legacy system integration friction:Vehicle-mounted launchers require mechanical retrofitting to accommodate redesigned grenade form factors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smoke Grenade Market |
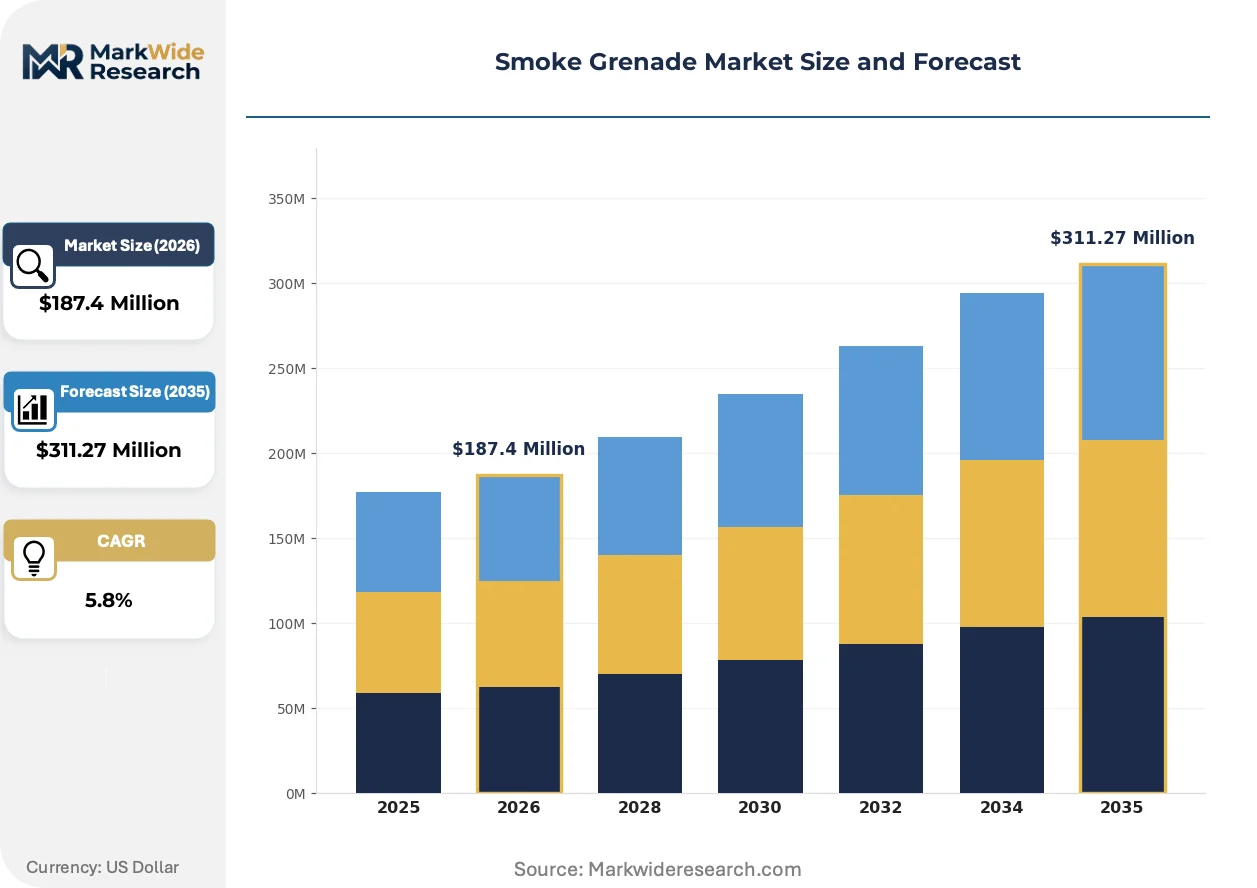
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Portable, Vehicle-Mounted, Atmospheric Application: Military, Law Enforcement, Firefighting, Civilian Events Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Government Contracts Composition: Smoke Generating Agents, Oxidizers, Delivery Systems, Colorants |
| Companies Covered | Rheinmetall AG, Combined Systems Inc., Centanex Ltd., General Dynamics Corporation, Thales Group, Nammo AS, Chemring Group PLC, Defense Technology LLC, Nonlethal Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smoke Grenade Market Strategic Shifts
Smoke grenade chemistry is undergoing forced migration away from legacy chlorinated formulations, with regulatory enforcement and procurement standards jointly determining competitive survival.
Potassium chlorate-sugar mixtures are migrating from laboratory-scale validation to volume production contracts. Bundeswehr technical delivery standards now mandate these formulations for all new vehicle-mounted systems. The technology is migrating from specialty niche to mainstream procurement requirement, compressing margins for incumbents slow to retool.
REACH Annex XVII restrictions on hexachloroethane are eliminating incumbent formulation pathways across EU manufacturing. Industrial consequence includes accelerated capital deployment toward exhaust-scrubbed production lines in Germany and Belgium. Vehicle-mounted system suppliers face the steepest compliance burden, with several restructuring supply agreements around reformulated agent sourcing.
Defense ministries are consolidating orders through framework agreements rather than spot procurement. The spot-buy channel for law enforcement and training applications is contracting as NATO member states centralize obscurant acquisition under multi-year vehicle fleet contracts. Germany and France exhibit the most pronounced centralization, with Bundeswehr and Direction Générale de l'Armement negotiating directly with integrated pyrotechnics divisions.
Smoke Grenade Market Segmentation
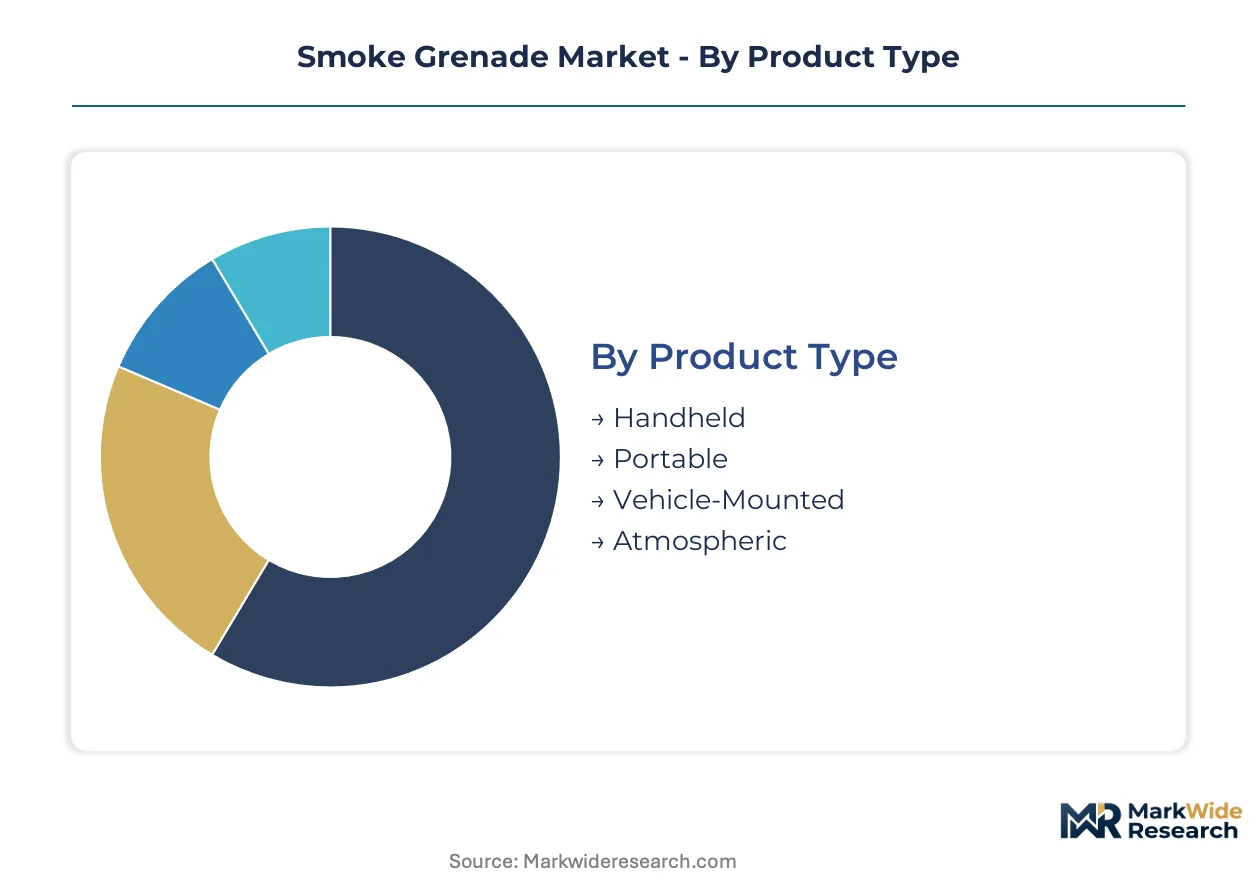
Segmentation in the smoke grenade market reveals distinct procurement patterns across military, law enforcement, and civilian channels. Each product configuration demands specialized maintenance protocols and technical support infrastructure that shape vendor selection criteria.
Product Type:
After-sales service intensity varies sharply across form factors, with vehicle-mounted systems requiring field engineering support while handheld units need minimal technical intervention.
- Handheld:Compact pyrotechnic devices designed for individual soldier or officer deployment, typically weighing under 500 grams with 30-90 second burn durations. Demand concentrates in French and Belgian law enforcement agencies restructuring crowd dispersal protocols around portable unit procurement.
- Vehicle-Mounted:Rapid-deploy obscurant systems integrated into armored vehicle hulls with automated launch capabilities and multi-grenade magazines. Mechanized units in Germany and Poland are expanding orders under Bundeswehr modernization contracts, making this configuration the fastest-expanding margin pool across NATO procurement channels.
- Portable:Intermediate form factors deployed from tripods or shoulder-fired launchers for squad-level tactical obscuration. Training simulation programs in Canada favor these units for firefighter scenario replication.
- Atmospheric:Large-scale area denial systems generating persistent smoke screens across kilometer-scale zones. Specialized military engineering units represent the sole viable demand source.
By volume, Handheld leads. By growth pace, Vehicle-Mounted is ahead.
Application:
Application segmentation tracks divergent regulatory exposure, with military procurement navigating NATO STANAG 4385 certification while civilian events face municipal permitting barriers.
- Military:Battlefield concealment and target acquisition degradation for mechanized and dismounted operations. Bundeswehr technical delivery standards now mandate potassium chlorate-sugar formulations for all new vehicle-mounted systems, compressing margins for incumbents slow to retool.
- Law Enforcement:Crowd dispersal and area denial in urban riot-control scenarios. Agencies in France and Belgium are restructuring portable unit procurement around doctrine shifts emphasizing graduated response protocols.
- Firefighting:Realistic smoke simulation for emergency response training. Municipal departments in Canada and Australia are adopting these systems for scenario replication.
- Civilian Events:Theatrical and festival deployment requiring municipal permits. Festival coordinators in California and New South Wales navigate complex approval processes that constrain segment expansion.
By volume, Military leads. By growth pace, Firefighting is climbing the fastest.
Distribution Channel:
Channel segmentation reflects procurement centralization trends, with framework agreements displacing spot purchasing across defense ministries.
- Government Contracts:Multi-year framework agreements negotiated directly with defense ministries. Germany and France exhibit pronounced centralization, with Bundeswehr and Direction Générale de l'Armement consolidating obscurant acquisition under vehicle fleet contracts.
- Direct Sales:Manufacturer-to-end-user relationships for specialized military and law enforcement procurement. Rheinmetall leverages its integrated pyrotechnics division to sustain captive supply relationships.
- Specialty Stores:Licensed distributors serving law enforcement and training segments with compliant storage and handling capabilities.
- Online Retail:Constrained channel limited to training and simulation accessories due to hazardous materials shipping restrictions.
By volume, Government Contracts lead. By growth pace, Direct Sales is gaining share fastest.
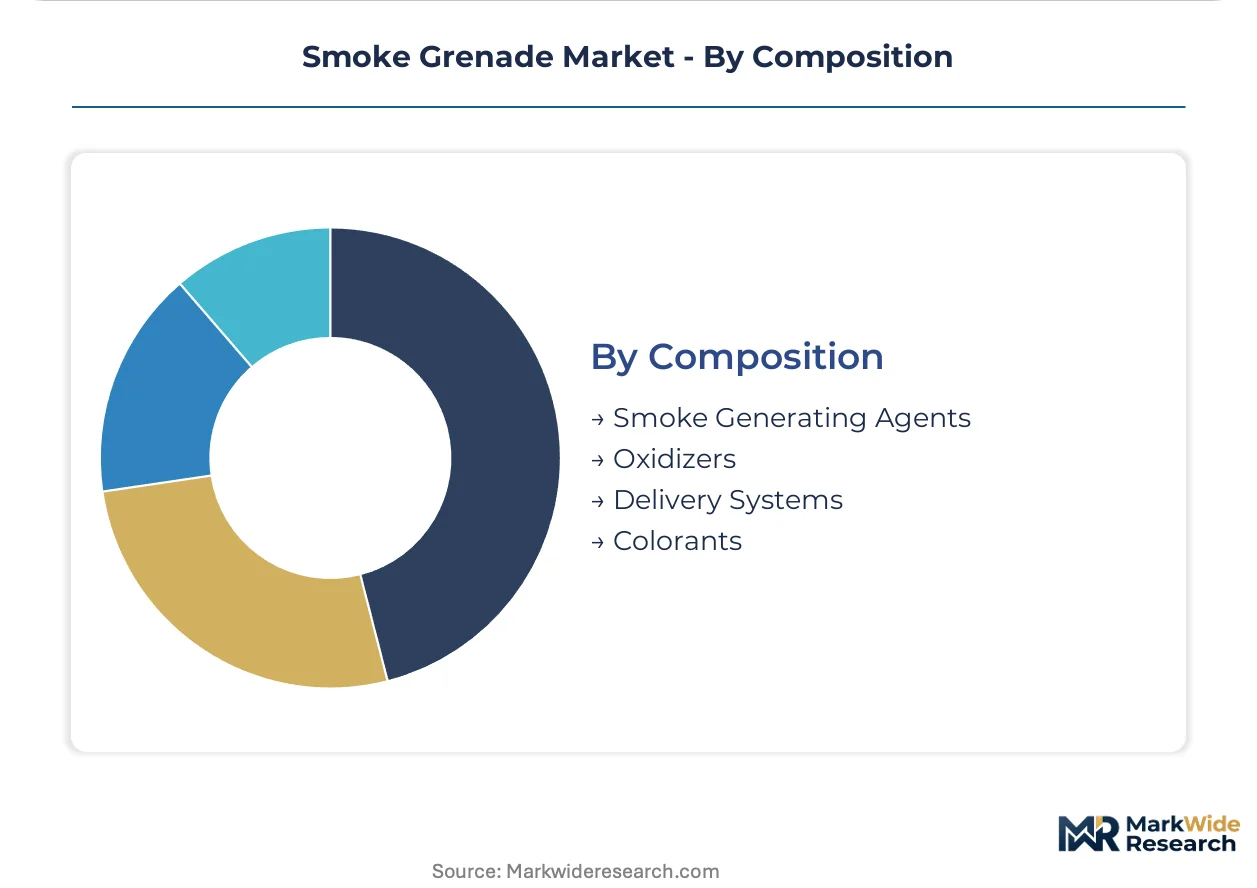
Composition:
Composition segmentation captures forced migration from legacy chlorinated formulations toward regulatory-compliant alternatives.
- Smoke Generating Agents:Core pyrotechnic mixtures determining obscuration density and spectral attenuation. Potassium chlorate-sugar formulations are migrating from laboratory validation to volume production contracts.
- Oxidizers:Chemical compounds sustaining controlled combustion rates. REACH Annex XVII restrictions on hexachloroethane are eliminating incumbent formulation pathways across EU manufacturing.
- Delivery Systems:Mechanical housings and ignition mechanisms. Vehicle-mounted launchers require retrofitting to accommodate redesigned grenade form factors.
- Colorants:Dyes producing visible spectrum signatures for signaling and identification. EU ECHA evaluation of heavy-metal dye hazards creates first-mover advantage for organic pigment developers.
By volume, Smoke Generating Agents lead. By growth pace, Colorants is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA enforcement of Clean Air Act provisions anchors North American regulatory pressure, while REACH Annex XVII restrictions reshape European formulation chemistry. Bundeswehr modernization contracts concentrate procurement authority in Germany.
United States
Defense Technology LLC and Combined Systems Inc. anchor domestic law enforcement procurement channels. EPA Clean Air Act compliance costs drive capital deployment toward exhaust-scrubbed manufacturing lines in Pennsylvania and Ohio. Vehicle-mounted system integrators face retrofitting requirements for redesigned grenade form factors.
Germany
Bundeswehr technical delivery standards mandate potassium chlorate-sugar formulations for all new vehicle-mounted obscurant systems. REACH Annex XVII restrictions on hexachloroethane eliminate incumbent formulation pathways across EU manufacturing. Rheinmetall's integrated pyrotechnics division in Unterlüß sustains captive supply relationships through direct sales channels.
France
Direction Générale de l'Armement centralizes obscurant acquisition under multi-year framework agreements. Thales Group exemplifies defense prime consolidation through integrated system offerings. Law enforcement agencies in Paris and Lyon restructure portable unit procurement around graduated response protocols.
Poland
Mechanized units expand orders for rapid-deploy vehicle systems under NATO interoperability commitments. ECHA evaluation of heavy-metal dye hazards creates regulatory uncertainty for colored smoke colorants. Industrial clusters in Warsaw and Kraków concentrate reformulation expertise for potassium-based chemistry.
United Kingdom
Chemring Group PLC operates exhaust-scrubbed manufacturing lines that navigate tightening environmental standards. Ministry of Defence procurement centralization mirrors French and German framework agreement trends. Specialist pyrotechnic chemist talent scarcity concentrates formulation expertise among retiring defense-industry veterans in Salisbury and Stevenage.
Smoke Grenade Market Competitive Environment
Integrated defense primes and specialized pyrotechnics suppliers split the market across distinct capability tiers. Consolidation pressure intensifies as procurement centralization favors vendors with captive chemical production. Three archetypes dominate: vertically integrated system houses with in-house pyrotechnics divisions, standalone chemical specialists supplying reformulated agents, and tactical equipment distributors bridging law enforcement channels. Competitive moves center on backward integration into potassium chlorate supply and certification acceleration for NATO STANAG 4385 compliance.
Among European-integrated primes, Rheinmetall AG and Thales Group occupy positions spanning vehicle platform integration through agent formulation. Chemring Group PLC exemplifies the standalone specialist archetype with dedicated manufacturing infrastructure. Combined Systems Inc. anchors North American law enforcement channel access. These three represent the structural fault lines between system-level contracting and component supply.
| Leading Market Players |
|---|
| Rheinmetall AG |
| Combined Systems Inc. |
| Centanex Ltd. |
| General Dynamics Corporation |
| Thales Group |
| Nammo AS |
| Chemring Group PLC |
| Defense Technology LLC |
| Nonlethal Technologies Inc. |
| Others |
Value Chain & Pricing Dynamics
Eastern European potassium chlorate production clusters in Poland and the Czech Republic concentrate upstream chemical supply, anchoring margin capture for reformulated smoke agents while vehicle-mounted system integrators downstream absorb certification and retrofit costs.
Pricing Analysis
German vehicle-mounted system contracts command 40-60% premiums over North American law enforcement spot procurement. Three-tier pricing structure across NATO-certified, national-standard, and training-grade tiers separates military-grade potassium chlorate-sugar formulations from hexachloroethane legacy stock. Pricing pressure stems from REACH-driven reformulation capex and extended STANAG 4385 certification timelines. Law enforcement agencies in France and Belgium exhibit highest price sensitivity due to municipal budget constraints, while Bundeswehr framework agreements show lowest sensitivity given multi-year fleet modernization mandates.
Supply Chain Analysis
Tariff exposure between Eastern European chemical corridors and Western European assembly plants dominates supply chain risk assessment for potassium-based smoke agents. Raw material sourcing concentrates in Poland, Germany, and Belgium for chlorate oxidizers and sugar-based fuel precursors. Formulation depends on pyrotechnic chemist talent pools concentrated in Rheinmetall's Unterlüß facility and Chemring's Salisbury operations. Single-source vulnerability in exhaust-scrubbed manufacturing line capacity creates chokepoint risk. Distribution runs through defense ministry framework agreements with limited spot-market liquidity for training and law enforcement segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smoke grenade procurement is evolving toward integrated service contracts where field engineering support and burn-duration calibration services expand faster than hardware unit sales, particularly for vehicle-mounted system fleets requiring lifecycle maintenance.
For Market Incumbents: Insulate potassium chlorate supply relationships through captive offtake agreements with Eastern European chemical producers before REACH Annex XVII enforcement tightens further. Accelerate backward integration into colorant development as EU ECHA heavy-metal dye evaluations create organic pigment substitution windows. Defend against standalone chemical specialists by bundling STANAG 4385 certification services with hardware contracts. For New Entrants and Emerging Players: Build out firefighter training simulation distribution in Canada and Australia where municipal procurement lacks incumbent lock-in and permitting pathways are more navigable than civilian event markets. Target atmospheric area denial systems for specialized military engineering units as the least contested product configuration. Pursue joint development agreements with vehicle launcher OEMs to bypass standalone grenade qualification barriers. For Investors and Strategic Acquirers: Capital is best deployed toward standalone pyrotechnics specialists with exhaust-scrubbed manufacturing infrastructure and active NATO certification pipelines rather than pure-play vehicle integrators lacking captive chemical production. Long-term viability hinges on reformulation agility across potassium-based chemistry portfolios. Watch for EU ECHA colorant reclassification timing as inflection signal for organic pigment M&A premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Potassium Chlorate Supply | Captive sourcing from Polish chemical corridors mitigates REACH-driven raw material concentration risk. |
| STANAG 4385 Certification Acceleration | Compressed qualification timelines for potassium-based formulations unlock Bundeswehr vehicle fleet contracts. |
| Organic Colorant Development Partnership | Collaboration with EU ECHA-compliant dye suppliers positions ahead of heavy-metal reclassification deadlines. |
| Field Engineering Service Contracts | Recurring revenue from vehicle-mounted system calibration outpaces handheld unit margin erosion. |
| Firefighter Training Channel Expansion | Municipal emergency response procurement in Canada and Australia offers white-space growth outside military centralization. |
Study Parameters
A spread of perspectives from Bundeswehr procurement officers, pyrotechnic chemists at integrated defense primes, REACH compliance consultants, and municipal firefighter training coordinators converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against EPA enforcement actions, ECHA substance evaluation dossiers, NATO standardization office documentation, and customs trade data for potassium chlorate flows. Bottom-up unit economics for vehicle-mounted and handheld configurations were triangulated against top-down defense budget allocation models across the analysis window.
Demand-supply balance dynamics shaped the analytical framework across product type, application, distribution channel, and composition segmentation dimensions. CAGRs were derived from elasticity-adjusted procurement forecasts tied to Bundeswehr modernization contract schedules and law enforcement doctrine shift timelines. Industry-specific inputs included burn-duration consistency testing protocols, infrared attenuation coefficient benchmarks, and reformulation capex curves for exhaust-scrubbed production lines.
Stress conditions across REACH enforcement intensity, potassium chlorate supply disruption scenarios, and NATO STANAG revision timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory implementation pacing and defense procurement centralization trends. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Military Fuze Market
Weapons and Ammunition
Ballistic Protection Market
Weapons and Ammunition
Global Small Arms and Light Weapons (SALW) Market
Weapons and Ammunition
Sports Shotgun Market
Weapons and Ammunition
Directed Energy Weapons Market
Weapons and Ammunition
Riflescope Market
Weapons and Ammunition
Europe Cruise Missile Market
Weapons and Ammunition
Large Caliber Ammunition Market
Weapons and Ammunition
Ammunition Storage Market
Weapons and Ammunition
Smart Bullets Market
Weapons and Ammunition
Tank Ammunition Market
Weapons and Ammunition
Military Airborne Laser Market
Weapons and Ammunition
Global Submarine Launched Missile Market
Weapons and Ammunition
Precision Guided Munition Market
Weapons and Ammunition
APAC Ballistic Missile Market
Weapons and Ammunition
Shotgun Shell Market