
 Land-Based Remote Weapon Stations Market | 2026-2036
Land-Based Remote Weapon Stations Market Size, Share, and Industry Trends Forecast 2026-2036
Land-Based Remote Weapon Stations Market Foresight
The EU Green Deal defense procurement criteria is pivoting land-based remote weapon station sourcing toward energy-efficient stabilized platforms and recyclable armor composites. Rheinmetall AG leverages its German manufacturing base and integrated armor supply chain to dominate European ground vehicle turret contracts. Kongsberg Defence & Aerospace anchors Nordic and NATO ally procurement through its Protector family of remote weapon systems. Elbit Systems Ltd. specializes in hybrid electro-optical and fire control integration for Middle Eastern and Asia-Pacific customers.
Land-based remote weapon stations are stabilized, remotely operated weapon mounting systems typically housing machine guns, automatic cannons, or anti-tank missiles with integrated sensors and fire control computers, designed to protect operators inside armored hulls while delivering precision fires across 360-degree arcs. Mobile systems lead procurement volumes as mechanized infantry and armored cavalry units prioritize vehicle-integrated survivability, while hybrid systems represent the fastest-expanding category due to their dual-mode manned and unmanned operation capability. Sensors and fire control systems command the technology margin pool because thermal imagers, laser rangefinders, and ballistic computers determine engagement accuracy under degraded visibility conditions.
NATO standardization agreements and the EU AI Act constrain autonomous targeting algorithms and mandate human-in-the-loop verification protocols for member state acquisitions. The U.S. Department of Defense and Germany's BAAINBw enforce divergent electromagnetic compatibility and cybersecurity certification pathways that fragment supplier compliance burdens. Turkey's SSB and India's DRDO operate parallel indigenous development programs with localized testing regimes that limit direct foreign platform entry. Stakeholders must monitor how export control expansions under the Wassenaar Arrangement and emerging national content requirements reshape component sourcing and joint venture structures across allied defense industrial bases.
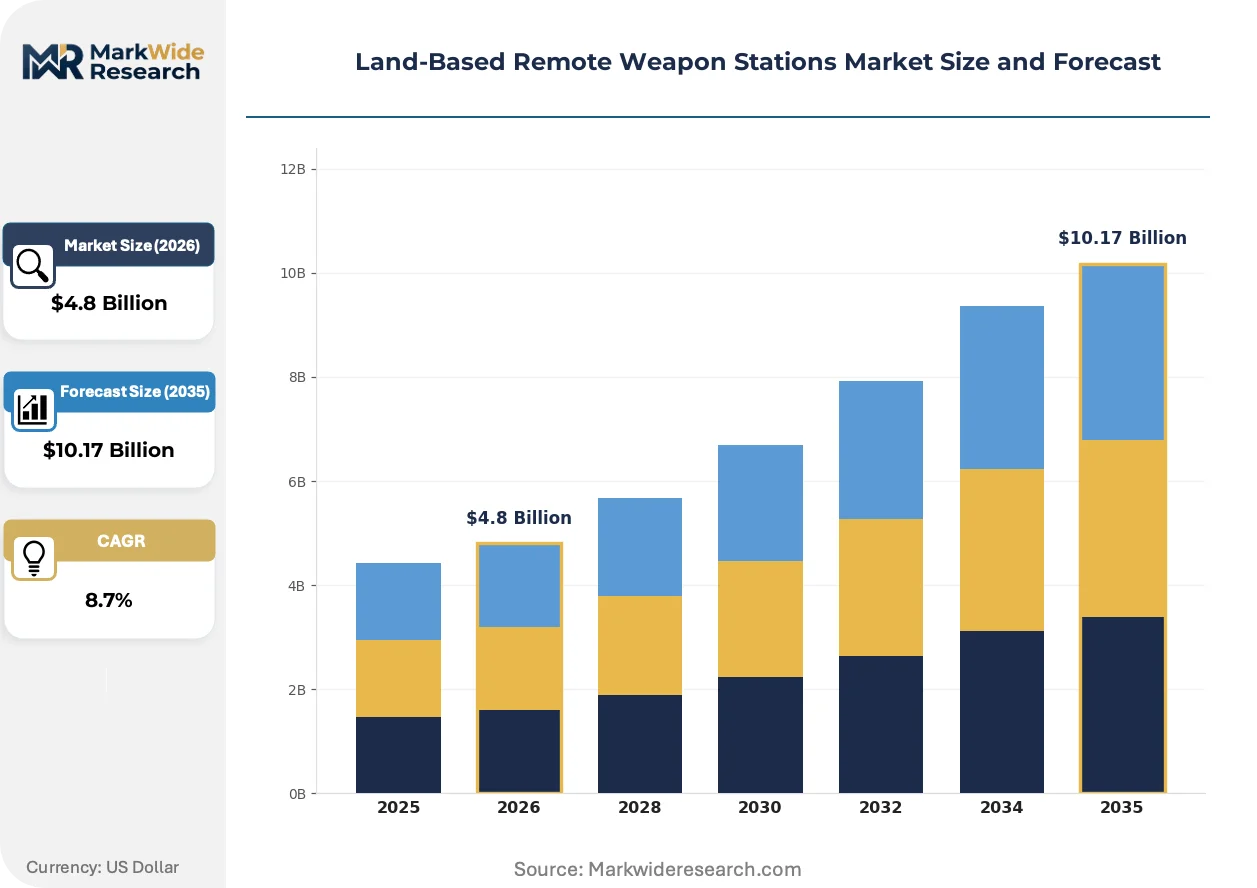
Market Dynamics
NATO mechanized infantry modernization is compressing procurement cycles for stabilized turret systems as member states replace Cold War-era armored platforms with integrated remote weapon stations. The EU Green Deal defense procurement criteria now mandates energy-efficient stabilized platforms and recyclable armor composites, forcing suppliers to requalify under dual-use environmental standards.
Growth Catalysts
- EU Green Deal procurement criteria:NATO member defense ministries now require energy-efficient stabilized platforms and recyclable armor composites in armored vehicle tenders, redirecting supplier R&D toward dual-use environmental compliance.
- Mechanized infantry survivability mandates:Ground forces across Germany, Turkey, and the United States prioritize 360-degree protected firepower for crewed vehicles, accelerating vehicle-integrated remote weapon station deployment.
- Hybrid electro-optical integration:Fire control computers combining thermal imagers, laser rangefinders, and ballistic solvers enable precision engagement under degraded visibility, expanding operational envelopes for armored cavalry units.
Market Restraints
- Gallium arsenide and germanium input volatility:Thermal imager and laser rangefinder production depends on constrained semiconductor substrates subject to export licensing delays and price swings.
- Divergent electromagnetic compatibility certification:The U.S. Department of Defense and Germany's BAAINBw enforce non-harmonized testing protocols, fragmenting supplier compliance engineering and extending qualification timelines.
- Autonomous targeting algorithm constraints:NATO standardization agreements and the EU AI Act mandate human-in-the-loop verification, limiting artificial intelligence integration in fire control systems and capping automation gains.
Strategic Opportunities
- Turkey's SSB indigenous development program:Localized testing regimes create openings for joint ventures with Turkish defense electronics firms seeking foreign electro-optical subsystem partnerships.
- India's DRDO parallel platform development:The country's armored vehicle modernization creates demand for technology transfer arrangements in stabilized turret fire control and sensor integration.
- Anti-tank missile module convergence:Dual-mode manned-unmanned operation capability is expanding fastest among hybrid systems, enabling suppliers to bundle missile and gun systems under unified remote control architectures.
Industry Challenges
- Cybersecurity certification timeline compression:NATO and EU member states now embed network hardening requirements into platform acceptance, forcing suppliers to parallel-track hardware and information assurance validation.
- Legacy vehicle hull integration complexity:Retrofitting stabilized turrets onto Cold War-era chassis requires structural reinforcement and power system upgrades that extend fielding schedules and multiply engineering risk.
- Ballistic computer software talent scarcity:Fire control algorithm development demands rare cross-disciplinary expertise combining physics modeling, real-time embedded systems, and military specification compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Land-Based Remote Weapon Stations Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static Systems, Mobile Systems, Hybrid Systems, Safety-Enhanced Systems Technology: Fire Control Systems, Sensors, Armor Technologies, Communication Interfaces End User: Military, Law Enforcement, Private Security, Defense Contractors Deployment: On-Ground Deployment, Training Facilities, Urban Environments, Remote Operations |
| Companies Covered | Elbit Systems Ltd., Kongsberg Defence & Aerospace, Rheinmetall AG, General Dynamics Corporation, FN Herstal, Rafael Advanced Defense Systems Ltd., RTX Corporation, BAE Systems plc, ASELSAN A.S., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Land-Based Remote Weapon Stations Market Shifts & Advancements
Electrification of turret drive systems and fire control architectures is compressing power train mass while expanding sensor payload capacity. Regulatory fragmentation across NATO procurement frameworks is accelerating supplier specialization by national qualification pathways.
Brushless electric turret drives are electrifying azimuth and elevation control, replacing hydraulic actuators with solid-state motor systems that reduce thermal signature and maintenance burden. Mechanized infantry vehicle integrators in Germany and the United States are specifying all-electric traverse systems for new-build platforms. This electrification is compressing turret power consumption profiles while enabling higher sustained slew rates for rapid target engagement.
The EU AI Act human-in-the-loop mandate is constraining autonomous target recognition deployment in NATO member acquisitions, forcing fire control developers to architect manual override protocols into every engagement sequence. Industrial consequence includes extended software validation cycles and redundant hardware pathways that add cost but preserve export eligibility. Stabilized turret suppliers serving European defense ministries are responding by segregating AI-enabled and non-AI product lines to maintain transatlantic sales flexibility.
Defense ministry technical authorities are unbundling sensor and fire control subsystem procurement from complete turret platform awards, enabling prime contractors to compete on integration while specialist firms capture electro-optical margin pools. Channel disruption concentrates in Germany and Turkey where armored vehicle primes now separately source thermal imagers, laser rangefinders, and ballistic computers. This pattern is most visible in Turkey's Altay and Germany's Puma follow-on programs, where subsystem competition has intensified supplier qualification demands.
Land-Based Remote Weapon Stations Market Segmentation
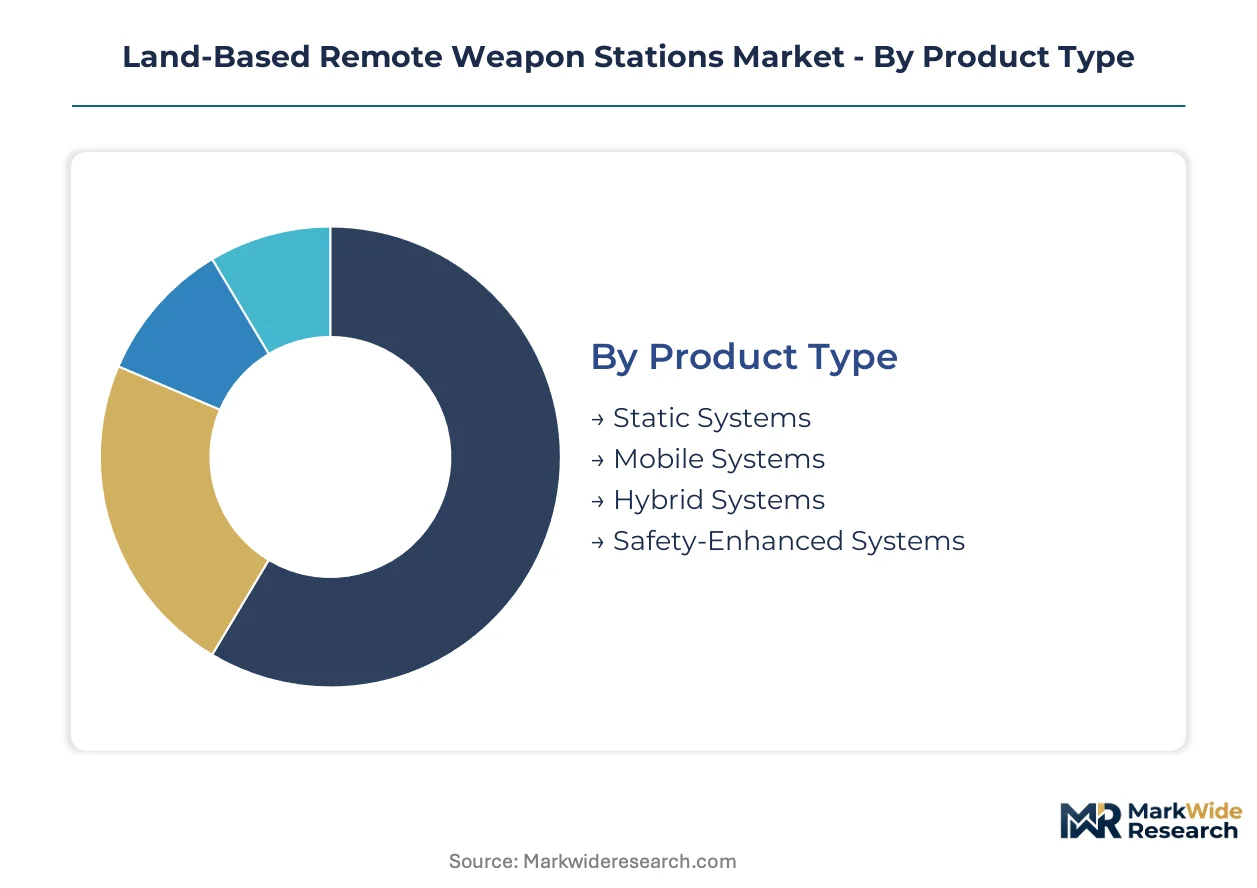
Segmentation in land-based remote weapon stations reveals how procurement priorities diverge across operational contexts. Technology integration depth, mobility requirements, and end-user mission profiles each reshape supplier positioning and margin capture differently.
Product Type:
Stabilization architecture and crew protection level define the product spectrum, with mobility integration determining platform complexity and fielding cost.
- Static Systems:Fixed-mount installations protect critical infrastructure and forward operating bases with 360-degree coverage from hardened emplacements. Demand concentrates in border security applications across Turkey and India's contested frontiers, driven by persistent cross-border infiltration threats and the need for persistent surveillance without crew exposure.
- Mobile Systems:Vehicle-integrated turrets mount on armored personnel carriers and infantry fighting vehicles with gyro-stabilized weapon platforms maintaining firing accuracy across terrain. Germany's Puma program and U.S. Army Stryker brigades anchor procurement volumes as mechanized units replace manned cupolas with under-armor remote operation.
- Hybrid Systems:Dual-mode architectures switch between manned and unmanned operation based on tactical conditions, offering commanders engagement flexibility. These configurations are expanding most quickly as NATO members seek future-proofing against autonomous warfare evolution while retaining human oversight compliance.
- Safety-Enhanced Systems:Redundant mechanical interlocks and ballistic shielding prioritize operator protection in training and garrison environments. Military police units and national guard formations in the United States specify these variants for domestic security roles with strict collateral damage prevention protocols.
Mobile Systems lead on scale; Hybrid Systems lead on momentum.
Technology:
Subsystem specialization is fragmenting supplier hierarchies as primes unbundle sensor and fire control procurement from complete platform awards.
- Fire Control Systems:Ballistic computers integrate laser rangefinding, meteorological sensors, and muzzle reference systems to calculate firing solutions in under one second. Turkish SSB and Indian DRDO armored vehicle programs are separately sourcing these subsystems, intensifying competition among specialist integrators.
- Sensors:Thermal imagers and daylight cameras provide target acquisition across degraded visibility conditions from smoke, dust, and darkness. Gallium arsenide substrate constraints are lengthening lead times for high-resolution thermal cores, compressing supplier margins on fixed-price contracts.
- Armor Technologies:Composite and ceramic protection modules shield turret mechanisms and ammunition stowage from small arms and fragmentation. EU Green Deal recyclable armor mandates are forcing reformulation of traditional epoxy-matrix composites toward thermoplastic alternatives.
- Communication Interfaces:Data links connect remote weapon stations to vehicle battle management systems and dismounted soldier networks. Cybersecurity certification under divergent U.S. and German electromagnetic compatibility regimes is extending qualification timelines for export-oriented suppliers.
Fire Control Systems command the technology margin pool; Sensors face the steepest supply chain compression.
End User:
Mission authority and rules of engagement stringency segment demand across institutional buyers with divergent procurement protocols.
- Military:Ground forces require hardened platforms with anti-tank missile integration and network-centric warfare compatibility. NATO mechanized infantry modernization is compressing procurement cycles as member states replace Cold War-era armored fleets.
- Law Enforcement:Police tactical units deploy lighter systems with strict collateral damage constraints for counter-terror and hostage rescue operations. Urban environment deployment limitations restrict caliber selection and explosive ammunition authorization.
- Private Security:Commercial contractors protecting critical infrastructure and convoy operations prioritize cost efficiency over military-grade survivability. Procurement runs through leasing arrangements rather than capital acquisition, shifting supplier revenue recognition patterns.
- Defense Contractors:System integrators and vehicle primes purchase subsystems for incorporation into complete platform offerings. Unbundled sourcing from Germany's BAAINBw and Turkey's SSB is expanding this channel's volume share.
Military dominates absolute demand; Defense Contractors are gaining share fastest through subsystem unbundling.
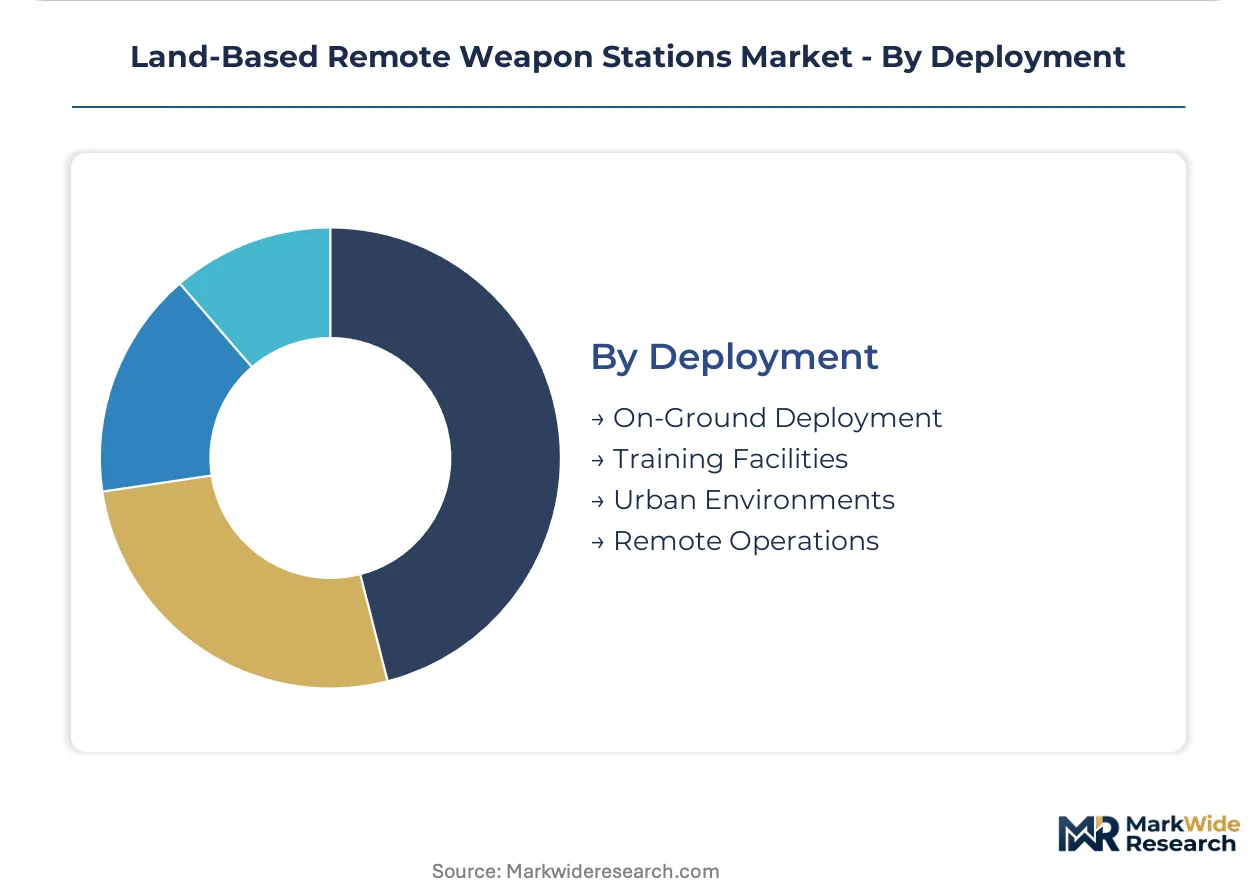
Deployment:
Environmental operating conditions determine environmental hardening requirements and maintenance burden profiles.
- On-Ground Deployment:Fielded systems operate across desert, arctic, and jungle conditions with sealed electronics and extended mean time between failures. Dust intrusion and thermal cycling drive reliability engineering priorities for Middle Eastern and Asia-Pacific customers.
- Training Facilities:Instrumented ranges with hit detection and simulation integration support crew proficiency without ammunition expenditure. Laser-based training adapters retrofit operational turrets, creating aftermarket attachment demand.
- Urban Environments:Elevated engagement angles and proximity fuse limitations constrain weapon selection for dense terrain operations. German and Turkish programs are specifying depression angle capabilities for street-level target engagement.
- Remote Operations:Beyond-line-of-sight control through unmanned ground vehicle platforms extends standoff distance for explosive ordnance disposal and reconnaissance missions. EU AI Act human-in-the-loop mandates constrain full autonomy deployment in European acquisitions.
On-Ground Deployment anchors procurement volumes; Remote Operations are climbing the fastest as unmanned platform integration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial conglomerates pioneered stabilized turret systems during Cold War mechanization programs, establishing design standards that persist across NATO procurement frameworks today.
United States
Army Stryker brigades and Marine Corps amphibious vehicle programs drive demand for under-armor remote weapon stations. The Department of Defense enforces MIL-STD-461 electromagnetic compatibility certification that fragments supplier qualification pathways. Huntsville, Alabama anchors systems integration activity where RTX Corporation and General Dynamics Corporation cluster around Army acquisition commands.
Germany
Puma infantry fighting vehicle follow-on contracts and Boxer armored vehicle exports compress procurement timelines for stabilized turrets. BAAINBw mandates divergent cybersecurity protocols that extend supplier validation cycles. Bavaria's Augsburg-Nuremberg corridor concentrates Rheinmetall AG manufacturing and subsystem supplier networks.
Turkey
Altay main battle tank serial production and Kirpi armored vehicle exports accelerate indigenous turret development. SSB operates localized testing regimes that limit direct foreign platform entry. Ankara's defense electronics cluster hosts ASELSAN A.S. and joint venture partners seeking electro-optical subsystem technology transfer.
Israel
Border security applications and active protection system integration drive hybrid remote weapon station procurement. The country's national defense procurement authority enforces human-in-the-loop verification for autonomous targeting algorithms. Haifa's defense technology corridor concentrates Rafael Advanced Defense Systems Ltd. and Elbit Systems Ltd. development facilities.
United Kingdom
Boxer armored vehicle program participation and Ajax reconnaissance vehicle fielding sustain demand for vehicle-integrated turrets. Ministry of Defence export licensing requirements reshape component sourcing for multinational programs. South Wales hosts BAE Systems plc armored systems integration and testing infrastructure.
Land-Based Remote Weapon Stations Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the land-based remote weapon stations market. The supplier base concentrates around integrated platform primes and specialist subsystem houses. Three archetypes dominate: European industrial conglomerates with captive armor supply chains, Nordic sensor-fire control integrators, and Israeli electro-optical specialists. Competitive moves center on subsystem unbundling to capture electro-optical margin pools and joint venture formation to satisfy indigenous content mandates.
Among Israeli defense electronics specialists, Elbit Systems Ltd. and Rafael Advanced Defense Systems Ltd. exemplify the hybrid electro-optical integration archetype. Rheinmetall AG anchors German manufacturing concentration. Kongsberg Defence & Aerospace represents Nordic platform integration expertise. These three occupy positions spanning the value chain from sensor cores to complete turret systems.
| Leading Market Players |
|---|
| Elbit Systems Ltd. |
| Kongsberg Defence & Aerospace |
| Rheinmetall AG |
| General Dynamics Corporation |
| FN Herstal |
| Rafael Advanced Defense Systems Ltd. |
| RTX Corporation |
| BAE Systems plc |
| ASELSAN A.S. |
| Others |
Supply & Pricing Matrix
Gallium arsenide substrate costs cascade through thermal imager production into three-tier pricing structures across premium, standard, and economy levels, with EU Green Deal compliance premiums layering onto German and Turkish armored vehicle tenders while legacy hull retrofit programs absorb margin compression through extended engineering risk.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates NATO-certified hybrid systems from national-program variants and export-restricted configurations. Price differentiation hinges on electromagnetic compatibility certification tier and sensor payload density. Cost compression in standard-tier fire control subsystems is intensifying because Turkish SSB and Indian DRDO unbundling concentrates procurement leverage with vehicle primes. Defense contractors exhibit highest price sensitivity due to fixed-price integration contracts, while military end-users prioritize performance over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with gallium arsenide and germanium substrate suppliers concentrated in Germany, the United States, and select Asian refining operations. Thermal imager production draws from constrained semiconductor feedstocks, precision optical glass, and rare-earth magnet assemblies for brushless turret drives. Tariff exposure on electro-optical components fragments supplier qualification across divergent U.S. MIL-STD-461 and German BAAINBw electromagnetic regimes. Distribution runs through prime contractor integration channels with subsystem unbundling accelerating direct procurement from sensor and fire control specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU AI Act human-in-the-loop mandates and NATO standardization agreements perpetually reshape supplier qualification requirements, embedding compliance investment into sustained demand cycles.
For Market Incumbents: Extend sensor-fire control integration depth to capture electro-optical margin pools unbundled from complete turret awards, while backward integration into gallium arsenide substrate sourcing defends against supply chokepoint exposure. Capacity addition in Bavaria's Augsburg-Nuremberg corridor and Huntsville, Alabama systems integration clusters reinforces proximity to BAAINBw and Department of Defense certification authorities.
For New Entrants and Emerging Players: Capture technology transfer arrangements in Turkish SSB and Indian DRDO indigenous development programs where localized testing regimes limit direct foreign platform entry. Joint venture structures with ASELSAN A.S. and domestic defense electronics firms represent the most penetrable path, leveraging electro-optical subsystem partnerships as the primary go-to-market angle.
For Investors and Strategic Acquirers: Consolidation pressure builds where ballistic computer software talent scarcity intersects with divergent cybersecurity certification timelines fragmenting mid-tier supplier viability. Long-term positioning favors acquisition targets with captive fire control algorithm development and dual-use environmental compliance credentials under EU Green Deal criteria. Watch for Wassenaar Arrangement export control expansions as the inflection signal reshaping component sourcing economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Formation | Localizes production for Turkish SSB and Indian DRDO indigenous program compliance. |
| Backward Integration into Substrates | Secures gallium arsenide supply against export licensing delays and price volatility. |
| Dual-Use Environmental Certification | Unlocks EU Green Deal defense procurement criteria for stabilized platform tenders. |
| Fire Control Specialist Acquisition | Captures margin pools from unbundled sensor and ballistic computer procurement. |
| Electromagnetic Compatibility Harmonization | Reduces engineering burden across divergent U.S. and German certification pathways. |
Research Methodology
Direct dialogue with armored vehicle program managers, defense electronics procurement leads, turret integration engineers, and electromagnetic compatibility certification specialists grounded the qualitative foundation. Secondary validation drew from NATO standardization agreement documentation, EU AI Act regulatory filings, Wassenaar Arrangement control lists, and national defense ministry tender records. Bottom-up platform deployment estimates and top-down defense budget allocation analysis were triangulated to anchor volume assumptions.
Segment-level outputs across the projection horizon reflect modeling of product type mobility architecture, technology subsystem specialization depth, end-user mission authority tier, and deployment environmental hardening requirements. CAGRs were derived from mechanized infantry modernization cycle timing, fleet replacement rates, and hybrid system adoption curves. Fire control computer integration complexity and sensor payload density served as industry-specific demand elasticity inputs.
Export licensing delays, semiconductor substrate supply disruptions, and autonomous targeting algorithm regulatory expansion are the dominant revision risks that could compress or extend procurement timelines. Forecasts reflect documented assumptions about NATO member defense spending continuity and indigenous program localization thresholds. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Aircraft Weapons Market
Weapons and Ammunition
US Small Caliber Ammunition Market
Weapons and Ammunition
Weapon Mounts Market
Weapons and Ammunition
Hypersonic Missile Market
Weapons and Ammunition
Weapons and Ammunition Market
Weapons and Ammunition
Electrical Weapon Market
Weapons and Ammunition
Weapon Night Sight Market
Weapons and Ammunition
Ammunition Belt Market
Weapons and Ammunition
Southeast Asia, Middle-East and Africa Small Arms and Ammunition Market
Weapons and Ammunition
Particle Beam Directed Energy Weapon Market
Weapons and Ammunition
Mortar Ammunition Market
Weapons and Ammunition
Sniper Rifle Market
Weapons and Ammunition
Electromagnetic Weapons Market
Weapons and Ammunition
Small and Medium Caliber Ammunition Market
Weapons and Ammunition
Man-Portable Anti-Armor Weapons Market
Weapons and Ammunition
Tank Ammunition Market