
 Airborne Weapon System Market | 2026-2036
Airborne Weapon System Market Size, Share, and Industry Trends Forecast 2026-2036
Airborne Weapon System Market Intelligence
The supply chain for specialized guidance components is narrowing, concentrating manufacturing with a few highly-vetted suppliers. Lockheed Martin Corporation leverages its extensive portfolio of fighter jets to secure long-term integration contracts. Raytheon Technologies Corporation specializes in advanced missile and radar guidance technologies, while BAE Systems plc sustains its position through European joint-platform initiatives.
An airborne weapon system comprises munitions and the integrated fire control, guidance, and launch mechanisms deployed from an aerial platform. These systems are defined by technical parameters like standoff range and terminal velocity, serving to project force for military operations. Integration with Unmanned Aerial Vehicles represents the fastest-growing platform compatibility segment. Demand for Directed Energy Systems is emerging, though conventional missiles and bombs still constitute the largest share by weapon type.
Market access is governed by stringent national and international arms control regulations, including the US International Traffic in Arms Regulations (ITAR) and the EU's Common Military List. Compliance with military-grade specifications, such as those set by the US Department of Defense and NATO STANAGs, is a prerequisite for procurement. Navigating complex export controls while investing in next-generation autonomous and hypersonic capabilities will determine future competitive advantage.
Market Dynamics
The central structural force shaping the market is the rapid integration of artificial intelligence into guidance and fire control systems. This technological shift enables autonomous targeting capabilities, fundamentally altering operational doctrines and driving procurement priorities for defense forces undertaking extensive modernization programs.
Growth Catalysts
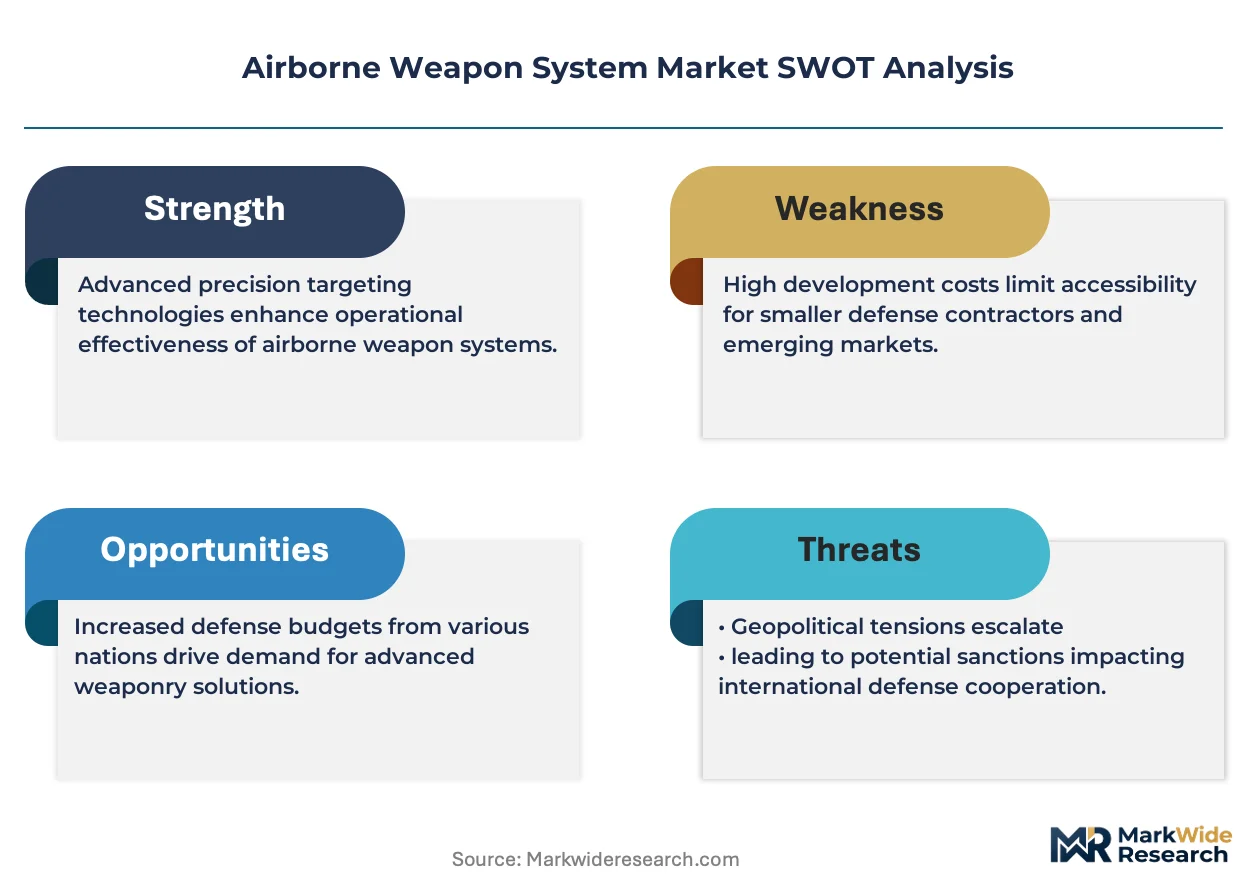
- Military Modernization Programs:National defense strategies in India, the United States, and key NATO member states are allocating significant budgets toward upgrading aerial combat capabilities, directly stimulating demand for advanced weapon systems.
- UAV Platform Proliferation:The expanding use of Unmanned Aerial Vehicles (UAVs) in both conventional military and counterterrorism operations creates a dedicated and fast-growing platform segment requiring compatible, lightweight, and precise munitions.
- AI-Powered Guidance:The development of autonomous targeting algorithms powered by artificial intelligence allows for greater precision, faster engagement cycles, and reduced operator burden, representing a significant performance leap over legacy systems.
Market Restraints
- Stringent Export Controls:Complex regulatory frameworks, including the US International Traffic in Arms Regulations (ITAR) and the EU Common Military List, create significant hurdles and lengthy approval processes for international sales, limiting market access.
- Supply Chain Concentration:The manufacturing of critical guidance and sensor components is concentrated among a small number of highly specialized, security-vetted suppliers, creating potential bottlenecks and pricing power imbalances for system integrators.
- High Development Costs:The research and development investment required for next-generation technologies like hypersonic and directed energy weapons is exceptionally high, restricting market entry to a few large, well-capitalized defense contractors.
Strategic Opportunities
- Directed Energy Systems:While conventional missiles and bombs dominate, the emerging field of Directed Energy Systems (DES) offers a new technological frontier for applications like drone defense and non-kinetic effects, creating a long-term growth opportunity.
- Hypersonic Weapon Integration:The convergence of hypersonic vehicle development with advanced autonomous guidance presents an opportunity to create a new class of high-speed, survivable standoff weapons that can overcome advanced air defenses.
- Modular Open-Architecture Systems:Designing weapons with modular, open-architecture principles allows for faster and more cost-effective upgrades, creating opportunities for specialized subsystem suppliers to compete for integration contracts on major platforms.
Industry Challenges
- Multi-Standard Compliance:Adherence to a complex web of military-grade specifications, such as US Department of Defense requirements and differing NATO STANAGs, complicates design, testing, and interoperability, extending development timelines.
- Legacy System Integration:Integrating advanced, software-defined weapon systems with older aircraft platforms and command-and-control networks presents significant technical challenges, risking performance degradation and cybersecurity vulnerabilities.
- Specialized Talent Shortages:A scarcity of engineers possessing dual expertise in both artificial intelligence and aerospace weapons engineering creates a critical bottleneck in the development of next-generation autonomous systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airborne Weapon System Market |
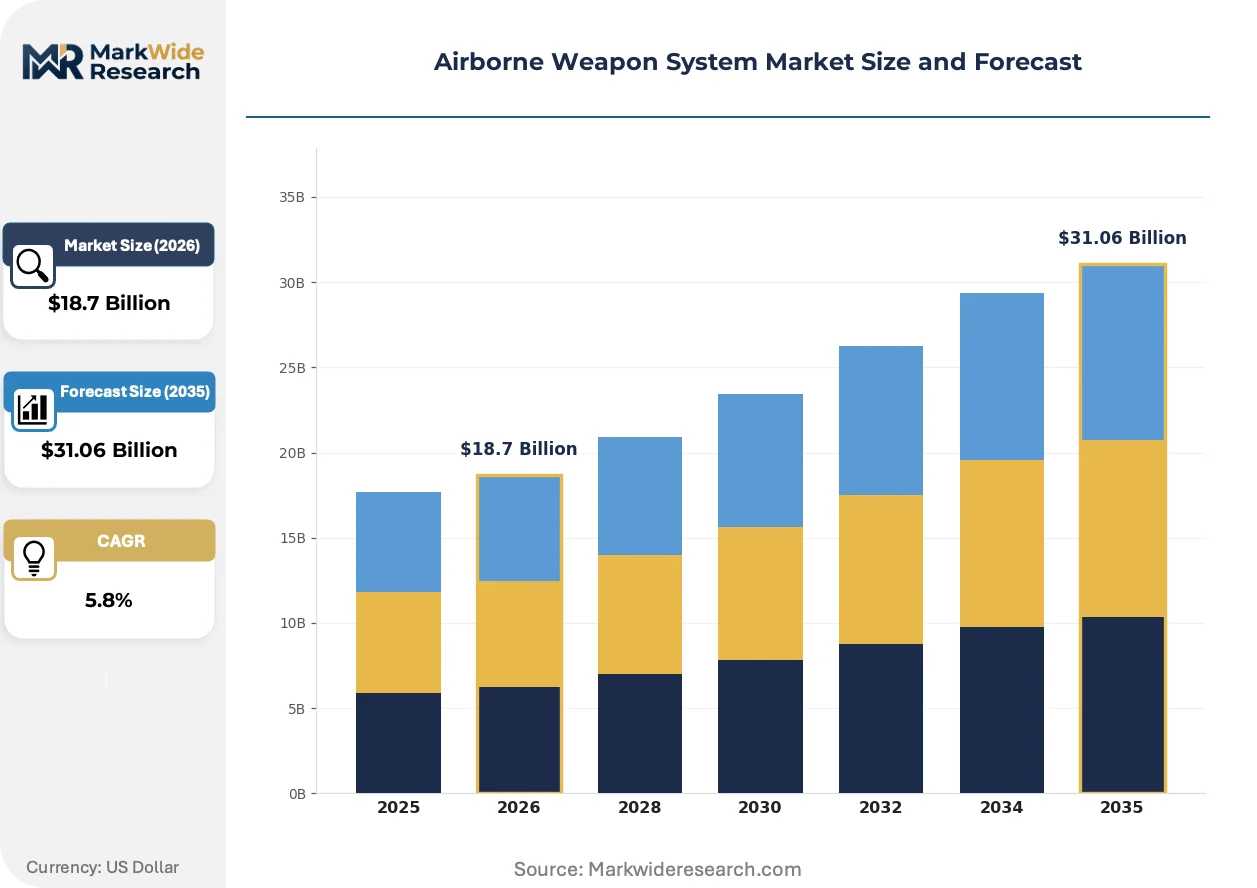
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Weapon Type: Missiles, Bombs, Rockets, Guns, Directed Energy Systems Platform Compatibility: Fixed-Wing Aircraft, Rotary-Wing Aircraft, Unmanned Aerial Vehicles, Airborne Early Warning Systems Guidance Technology: Inertial, GPS, Laser, Infrared, Radar End User: Defense Forces, Coast Guard, Homeland Security, Counterterrorism Units |
| Companies Covered | Lockheed Martin Corporation, The Boeing Company, Northrop Grumman Corporation, Raytheon Technologies Corporation, BAE Systems plc, Airbus SE, Leonardo S.p.A., Thales Group, Saab AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airborne Weapon System Market Strategic Shifts & Innovations
Technological evolution is pivoting the market from crew-operated munitions to autonomous, network-centric systems. This transition is driven by advancements in processing power and artificial intelligence, enabling weapons to perform complex targeting functions independently and collaboratively on the battlefield.
Digital twin technology is used to create high-fidelity simulations of entire weapon systems and their operational environments. Defense prime contractors and government agencies are adopting this approach for virtual design validation, mission planning, and predictive maintenance analysis. This methodology is virtualizing large parts of the physical prototyping and live-fire testing phases, which compresses development cycles and de-risks complex integration projects.
The EU AI Act and related ethical directives within NATO are establishing regulatory expectations for the deployment of autonomous functions in weapon systems. This compels developers to incorporate human-in-the-loop controls and explainable AI (XAI) to ensure meaningful human control over lethal force. The autonomous targeting systems segment is most affected, with auditable safety and ethical compliance becoming a critical procurement criterion for European militaries.
A clear demand-side pivot towards acquiring fully integrated platform-and-weapon packages is reshaping acquisition strategies. This model moves away from separate tenders for aircraft and munitions, favoring holistic, long-term contracts that bundle the weapon, launch platform, software, and through-life support. This trend is most prominent in large-scale fighter procurements in the United States and India, benefiting contractors with deep system integration capabilities.
Airborne Weapon System Market Segmentation
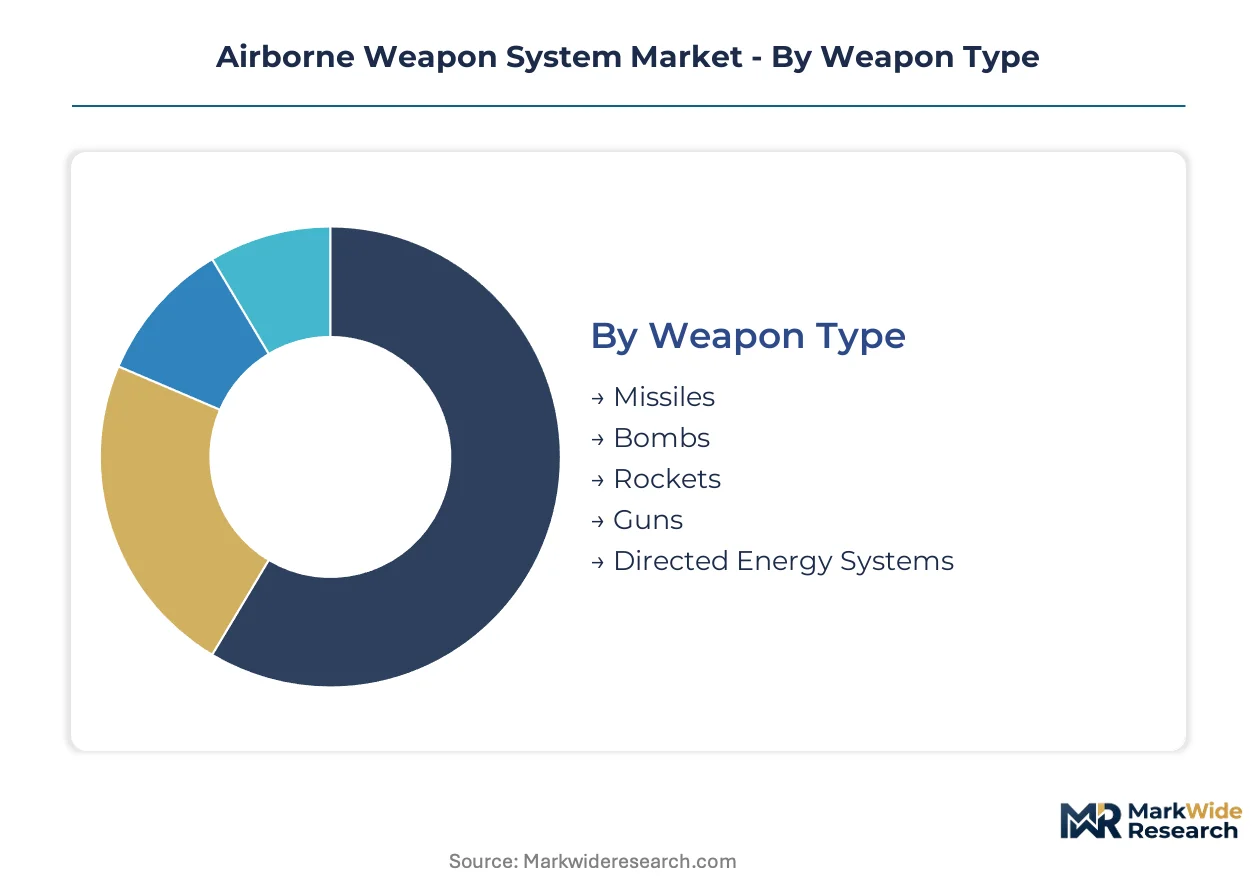
Understanding the segmentation of the airborne weapon system market clarifies where technological investments are concentrated and which operational requirements drive procurement. This detailed breakdown reveals the diverse applications and underlying technologies shaping the industry's growth trajectory.
Weapon Type:
The airborne weapon system market's weapon type segmentation shows a clear maturity spectrum, ranging from established munitions to advanced energy systems.
- Missiles:These guided projectiles deliver precise kinetic or explosive effects over long ranges, often incorporating advanced guidance for target acquisition and engagement. Demand for modern missile systems is high among global defense forces for air-to-air and air-to-ground combat roles.
- Directed Energy Systems:These emerging weapons utilize concentrated energy, such as lasers or microwaves, to achieve non-kinetic effects or to neutralize threats like drones. Significant research and development investment is flowing into DES for future air defense and counter-UAV applications.
- Bombs:Unguided or precision-guided explosive devices dropped from aircraft, providing area denial or targeted destruction.
- Rockets:Propelled munitions typically used for close air support or area suppression, often unguided but increasingly featuring precision variants.
- Guns:Fixed or turret-mounted firearms on aircraft, primarily used for air-to-air combat or close-in ground attack.
Missiles handle the majority of throughput; Directed Energy Systems are the fastest mover on share.
Platform Compatibility:
Platform compatibility segments delineate the application scope for airborne weapon systems across diverse aerial vehicles.
- Unmanned Aerial Vehicles:These remote-controlled or autonomous aircraft integrate lightweight, precise munitions for intelligence, surveillance, reconnaissance, and strike missions. The proliferation of UAVs in military and counterterrorism operations creates the fastest-growing platform segment.
- Fixed-Wing Aircraft:This segment includes fighter jets, bombers, and attack aircraft equipped with a broad array of air-to-air and air-to-ground weapon systems. Modernization programs in the United States and NATO member states drive consistent demand for integrated weapon packages for these platforms.
- Rotary-Wing Aircraft:Helicopters and tilt-rotors employ specialized weapon systems for close air support, anti-armor, and maritime interdiction roles.
- Airborne Early Warning Systems:These platforms primarily carry surveillance and communication equipment, but may integrate defensive self-protection measures or limited offensive capabilities.
Unmanned Aerial Vehicles offer significant operational adaptability, while fixed-wing platforms remain foundational for heavy ordnance delivery.
Guidance Technology:
Guidance technology segmentation highlights the various methods employed to achieve functional precision in weapon delivery.
- GPS:Global Positioning System guidance uses satellite signals to direct munitions to precise coordinates, enabling all-weather, day-night targeting. This technology is widely adopted across various weapon types due to its accuracy and relatively low cost integration.
- Inertial:Inertial guidance systems use onboard accelerometers and gyroscopes to track weapon position and velocity relative to a known starting point. This technology provides autonomous navigation, often paired with GPS for enhanced accuracy and redundancy.
- Laser:Laser guidance systems direct munitions by tracking a reflected laser beam from a target, providing high precision for specific point targets.
- Infrared:Infrared guidance systems detect heat signatures emitted by targets, commonly used in air-to-air missiles for "heat-seeking" capabilities.
- Radar:Radar guidance actively or passively tracks targets using radio waves, suitable for long-range engagements and adverse weather conditions.
GPS guidance systems are broadly integrated due to their widespread availability, whereas radar guidance often involves greater integration complexity.
End User:
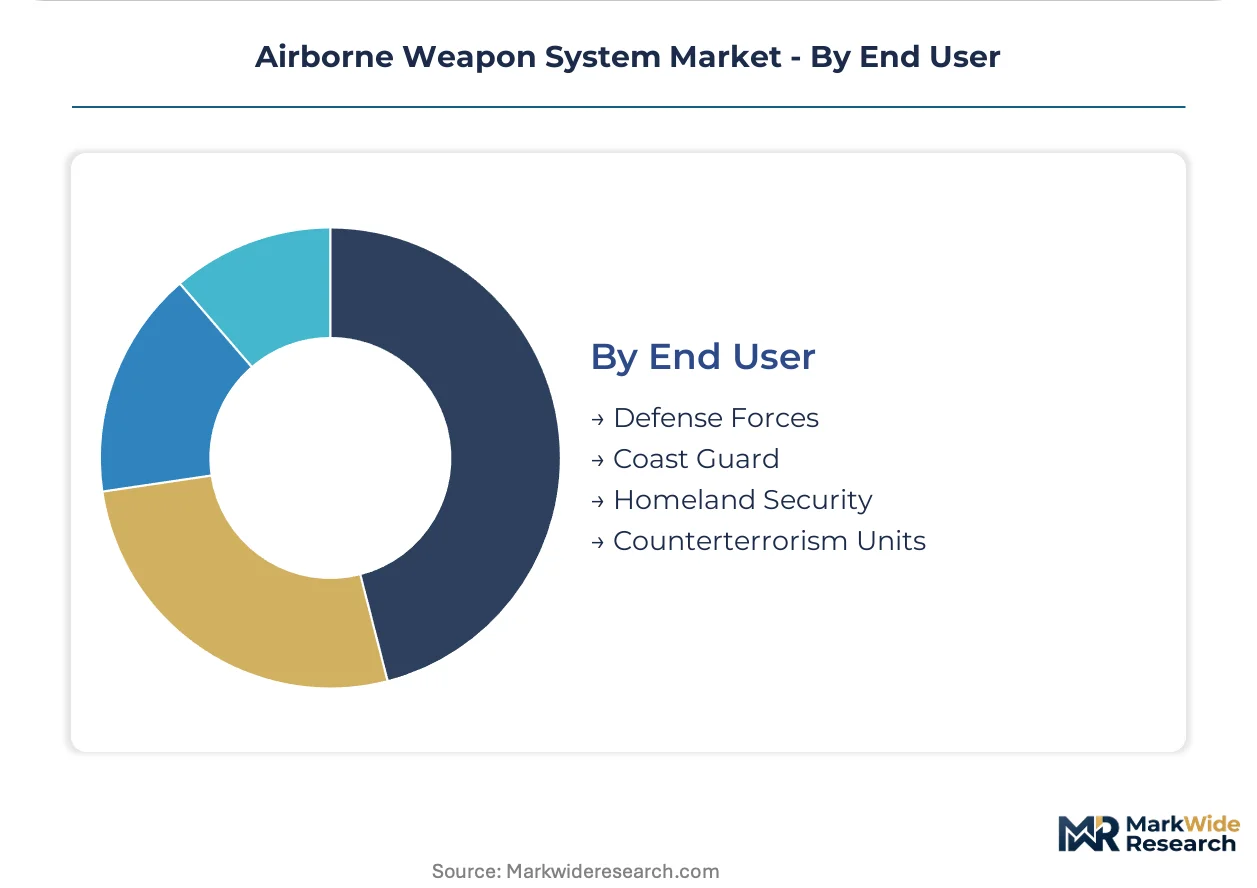
End-user segmentation reflects the strategic priorities and operational mandates of different defense and security organizations.
- Defense Forces:This segment encompasses national armies, navies, and air forces, representing the largest consumer of airborne weapon systems for conventional warfare and national defense. Military modernization programs globally drive substantial procurement within this category.
- Counterterrorism Units:These specialized units require highly precise, low-collateral-damage airborne weapon systems for targeted operations against terrorist organizations. The demand for compatible munitions for UAVs is particularly pronounced in this segment.
- Coast Guard:Maritime security agencies utilize airborne weapon systems for surveillance, interdiction, and search and rescue operations, often requiring specialized munitions for maritime targets.
- Homeland Security:Agencies focused on domestic security may employ airborne platforms with non-lethal or limited-lethal weapon systems for border patrol and critical infrastructure protection.
Defense Forces represent the largest procurement segment, but Counterterrorism Units exhibit specialized requirements for agile, precise munitions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the airborne weapon system market exhibits asymmetry, with the United States dictating premium rates due to its advanced technological base. Conversely, European nations often navigate complex joint procurement initiatives, influencing cost structures through collaborative defense spending.
United States
United States defense spending drives demand for hypersonic and autonomous weapon systems, supporting extensive military modernization programs. US Department of Defense requirements, alongside ITAR regulations, mandate stringent compliance for all procurement contracts. California's aerospace corridor, particularly around Los Angeles, leads in advanced R&D for next-generation guidance technologies.
India
India's national defense strategies are allocating significant budgets toward upgrading aerial combat capabilities, stimulating demand for advanced weapon systems. The PLI scheme encourages domestic manufacturing of defense components, reducing reliance on foreign suppliers. Bengaluru serves as a major aerospace hub, fostering indigenous development of integrated weapon packages.
United Kingdom
British defense forces prioritize advanced missile and radar guidance technologies for NATO joint-platform initiatives. UK export control regulations govern the international sales of sensitive airborne weapon components. Farnborough remains a key aerospace center, hosting significant research into future combat air systems.
France
French defense procurement focuses on integrated platform-and-weapon packages for European joint initiatives. The EU Common Military List and the EU AI Act influence development and export of autonomous weapon systems. Toulouse, home to Airbus, serves as a major industrial cluster for advanced aerial platforms.
Germany
German defense spending targets next-generation autonomous and hypersonic capabilities for NATO interoperability. German export controls and adherence to NATO STANAGs shape procurement and development. Munich's technology clusters contribute to advanced sensor and guidance system development for airborne platforms.
Airborne Weapon System Market Key Industry Players
Large-scale system integrators and specialized component manufacturers split the airborne weapon system market. This market exhibits consolidation among prime contractors due to high development costs and stringent regulatory barriers. Strategic archetypes include diversified defense primes and niche technology providers focusing on guidance or propulsion. Companies engage in strategic partnerships and technology licensing to navigate complex export controls and accelerate innovation.
Within the large-scale system integrator tier, Lockheed Martin Corporation exemplifies a diversified defense prime leveraging extensive platform portfolios. Raytheon Technologies Corporation occupies a position as a specialist in advanced missile and radar guidance technologies, anchoring a key component segment. BAE Systems plc, a UK-based entity, represents a significant player in European joint-platform initiatives, sustaining its presence through collaborative defense programs. These companies reflect the market's structure, where deep system integration capabilities and specialized technological expertise are critical for competitive advantage.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| The Boeing Company |
| Northrop Grumman Corporation |
| Raytheon Technologies Corporation |
| BAE Systems plc |
| Airbus SE |
| Leonardo S.p.A. |
| Thales Group |
| Saab AB |
| Others |
Cost & Logistics Intelligence
Transatlantic defense logistics corridors face cost dynamics shaped by concentrated supply chains for advanced components, leading to distinct price differentiation downstream. This market exhibits a direct relationship where the scarcity of highly specialized suppliers influences pricing power for system integrators.
Pricing Analysis
Configured-to-order pricing for integrated platform-and-weapon packages commands a premium due to extensive customization and long-term support requirements. The dominant pricing model is contract-based long-term offtake, driven by multi-year defense procurement cycles. Price differentiation stems from the customization level required for platform integration and adherence to stringent military-grade specifications like NATO STANAGs. Pricing softness for conventional munitions reflects increasing competition and technological obsolescence. Counterterrorism Units, with their specific needs for agile, precise munitions, exhibit higher price sensitivity compared to national Defense Forces procuring large-scale systems.
Supply Chain Analysis
US International Traffic in Arms Regulations (ITAR) and the EU Common Military List represent named restricted-technology controls limiting the international flow of airborne weapon system components. Supply concentration for specialized guidance components and advanced sensors primarily resides in the United States, Germany, and the United Kingdom. Raw material dependencies include rare earth elements for sensors and high-performance alloys for propulsion systems. A structural risk involves single-source vulnerability due to the small number of highly-vetted suppliers for critical subsystems. Distribution is largely integrator-led, with major defense primes managing complex sub-contractor networks for direct-to-government procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a high-growth disruption, fundamentally altered by the integration of AI-powered guidance systems enabling autonomous targeting capabilities.
For Market Incumbents: Build robust integration moats by securing long-term platform-and-weapon contracts with major defense forces. Invest heavily in next-generation autonomous and hypersonic capabilities to counter emerging AI-focused startups. Leverage extensive platform portfolios to offer holistic solutions, making R&D in AI-powered guidance a core lever against rapid technological shifts. Strategic partnerships for specialized components can mitigate supply chain risks.
For New Entrants and Emerging Players: Establish a beachhead in the modular open-architecture systems segment by offering specialized subsystems that enhance interoperability. The UAV-compatible munitions sector presents a penetrable segment due to demand for lightweight, precise armaments. Focus on technology licensing to larger primes or developing niche components for Directed Energy Systems. A go-to-market angle emphasizing cost-effectiveness and rapid integration can attract smaller defense programs.
For Investors and Strategic Acquirers: AI-centric guidance system developers and specialized sensor technology firms represent attractive acquisition targets. The market offers long-term viability, underpinned by sustained defense modernization cycles across key nations. Watch for increased defense spending allocations specifically for autonomous systems as a critical inflection indicator. Regulatory clarity on autonomous weapon deployment will also signal accelerated investment opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-Powered Guidance Modules | This initiative enhances targeting precision and reduces operator burden for future weapon systems. |
| Expand UAV-Compatible Munition Portfolio | This action addresses the fastest-growing platform segment, meeting demand for lightweight, precise armaments. |
| Form Joint Ventures for Directed Energy Systems | This strategy accelerates development in a new technological frontier for drone defense and non-kinetic effects. |
| Secure Long-Term Platform Integration Contracts | This move ensures stable revenue streams and reinforces market position for major system integrators. |
| Invest in Hypersonic Propulsion R&D | This effort creates a new class of high-speed, survivable standoff weapons to overcome advanced air defenses. |
Research Approach
The analysis maps weapon type categories and platform compatibility segments, each validated through primary interviews with defense procurement officers, aerospace engineers, system integrators, and regulatory compliance specialists. Secondary validation involved extensive review of US Department of Defense procurement reports, NATO standardization agreements, EU military spending reviews, and aerospace industry publications. This approach ensured a robust bottom-up and top-down triangulation of market data.
Assumptions regarding geopolitical stability and consistent defense budget allocations were held fixed across the analysis window, while technological advancements and regulatory shifts were varied. The forecast framework modeled segmentation dimensions including weapon type, platform compatibility, guidance technology, end user, geography, and military modernization spending cycles. Compound annual growth rates were derived from historical trends and projected technological advancements, with key inputs including defense budget allocations and UAV adoption rates.
Sensitivities concentrate around geopolitical conflicts, technological breakthroughs, and shifts in national defense policies, which could materially impact market trajectories. Forecasts reflect these assumptions, but major changes in arms control regulations or defense spending priorities would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
France Nuclear Bombs and Missiles Market
Weapons and Ammunition
Riflescope Market
Weapons and Ammunition
Guided Munitions Market
Weapons and Ammunition
Man-Portable Anti-Armor Weapons Market
Weapons and Ammunition
Vehicle Mounted Anti-Tank Missile System Market
Weapons and Ammunition
Weapon Mounts Market
Weapons and Ammunition
Global Submarine Launched Missile Market
Weapons and Ammunition
US Perforating Gun Market
Weapons and Ammunition
Bomb Suppression Blanket (BSB) Ballistic Blankets V50 Standard Market
Weapons and Ammunition
Global Artillery Systems Market
Weapons and Ammunition
Asia-Pacific Cruise Missile Market
Weapons and Ammunition
US Small Caliber Ammunition Market
Weapons and Ammunition
Command Fuzes Market
Weapons and Ammunition
Europe Medium and Large Caliber Ammunition Market
Weapons and Ammunition
Military Airborne Laser Market
Weapons and Ammunition
Manned Anti-Tank Guided Missile System Market