
 Beef Cattle Feed and Additives Market | 2026-2036
Beef Cattle Feed and Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Beef Cattle Feed and Additives Market Insights
Custom premix formulation is rewriting margin economics across the beef cattle feed value chain. Cargill, Incorporated leverages its vertically integrated grain procurement networks to control input costs across North American feedlots. BASF SE anchors its position through specialized amino acid and enzyme portfolios that reduce feed conversion ratios. Evonik Industries AG dominates methionine supply for high-performance finisher diets, sustaining pricing power in concentrated pockets.
Beef cattle feed and additives encompass nutritionally complete rations, concentrated supplements, and functional additives formulated to optimize rumen fermentation, growth performance, and carcass quality in Bos taurus and Bos indicus production systems. These inputs typically incorporate precise metabolizable energy densities of 2.9–3.2 Mcal/kg dry matter alongside balanced degradable and undegradable protein fractions to synchronize nitrogen availability with carbohydrate fermentation. Complete feed and premixes command the deepest margin pools where formulation complexity creates switching costs, while medicated formulations face structural pressure from regulatory withdrawal requirements. Protein meals derived from oilseed processing represent the fastest-growing ingredient category as soybean and canola meal displace fishmeal in cost-sensitive rations.
The EPA monitors veterinary feed directive compliance and antibiotic residue thresholds in US beef production, while the EU Green Deal's methane-reduction targets are reshaping additive demand toward ionophores and direct-fed microbials. BIS feed safety standards in India and China's MEE agricultural emissions protocols are fragmenting product registration requirements across origin markets. Stakeholders must calibrate R&D portfolios against divergent regulatory baselines rather than assuming harmonized approval pathways.
Market Dynamics
Precision methane-mitigation mandates from the EU Green Deal and F-Gas Regulation are forcing feed additive suppliers to restructure R&D portfolios around ionophores and direct-fed microbials. This regulatory compression is redrawing competitive boundaries between legacy formulation houses and biotechnology entrants.
Growth Catalysts
- EU methane-reduction mandates:The EU Green Deal's livestock emissions targets are accelerating demand for rumen-modifying additives across European feedlots.
- Precision formulation technology:Real-time near-infrared spectroscopy enables feedlots to adjust metabolizable energy densities dynamically, tightening feed conversion ratios.
- Brazilian feedlot corridor expansion:Mato Grosso and São Paulo operators are scaling precision-additive programs to capture premium export certification tiers.
Market Restraints
- Soybean meal price volatility:Oilseed processing margins fluctuate with Argentine crushing capacity, compressing protein meal cost predictability for premix formulators.
- Veterinary feed directive compliance costs:FDA residue monitoring and antibiotic withdrawal protocols impose documentation burdens that elevate operational overhead for medicated feed producers.
- Technical limitation in methionine bioavailability:Protected amino acid encapsulation remains inconsistent across high-temperature pelleting processes, constraining formulation precision.
Strategic Opportunities
- Underpenetrated Indian feedlot sector:BIS feed safety standard harmonization creates first-mover advantages for suppliers establishing premix distribution in Uttar Pradesh and Rajasthan.
- Regulatory tailwind from China's MEE protocols:Agricultural emissions monitoring mandates are opening state-procurement channels for methane-inhibiting additives in northern cattle provinces.
- Technology convergence:Blockchain-enabled feed traceability paired with rumen microbiome sequencing is enabling outcome-based pricing models for premium carcass quality programs.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in synchronizing degradable and undegradable protein fractions with carbohydrate fermentation profiles remains concentrated among retiring technical staff.
- Certification timeline compression:Divergent product registration requirements across EPA, EFSA, and China's SAMR are extending multi-jurisdiction approval cycles beyond typical R&D amortization periods.
- Legacy mill integration friction:Retrofitting existing pelleting infrastructure for temperature-sensitive probiotic inclusion demands capital outlays that strain mid-scale feed manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beef Cattle Feed and Additives Market |
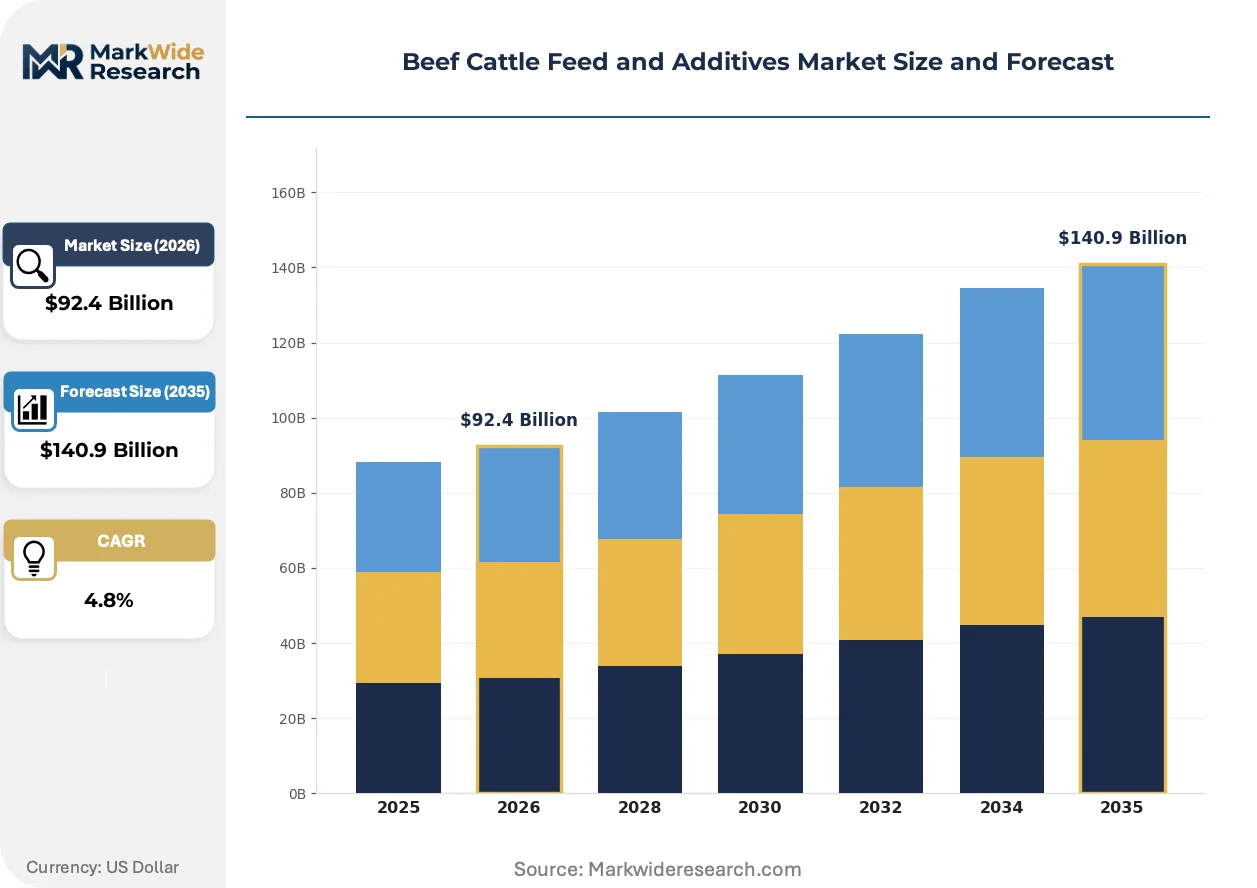
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $140.9 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Complete Feed, Supplements, Additives, Premixes Ingredient: Grains, Protein Meals, Vitamins, Minerals Formulation: Organic, Conventional, Medicated, Non-Medicated Feed Category: Calf Starter, Grower, Finisher, Maintenance |
| Companies Covered | Cargill, Incorporated, BASF SE, Evonik Industries AG, Archer Daniels Midland Company, DSM, Nutreco N.V., Kemin Industries, Alltech, Land O'Lakes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beef Cattle Feed and Additives Market Trends and Innovations
Biotechnology-enabled feed additives are compressing the traditional boundaries between nutrition and pharmaceutical intervention. Three convergent developments are restructuring how feedlots optimize rumen function and carcass outcomes.
Next-generation direct-fed microbials incorporating Saccharomyces cerevisiae and Propionibacterium strains are collapsing the performance gap between conventional ionophores and antibiotic-free production systems. Large-scale Brazilian feedlots are adopting these formulations at accelerated cadences to maintain EU export eligibility. The technology is collapsing historical trade-offs between growth promotion and residue compliance that structured supplier selection for decades.
The EU F-Gas Regulation's extension to livestock methane accounting is compelling additive suppliers to validate emissions-reduction claims through standardized life-cycle protocols. Industrial consequence includes mandatory third-party verification for any product marketed with environmental benefit positioning. High-performance finisher diet segments in Germany and France are responding by consolidating procurement around suppliers with established EFSA novel food approval pathways.
Feedlot procurement departments are consolidating supplier relationships around vertically integrated grain-procurement partners who can lock in metabolizable energy cost predictability across growing and finishing phases. Traditional independent premix distributors in the US Plains states are losing share to captive supply arrangements with major grain handlers. This concentration is most visible in Nebraska and Kansas feedlot clusters where margin compression has accelerated buyer consolidation.
Beef Cattle Feed and Additives Market Segmentation
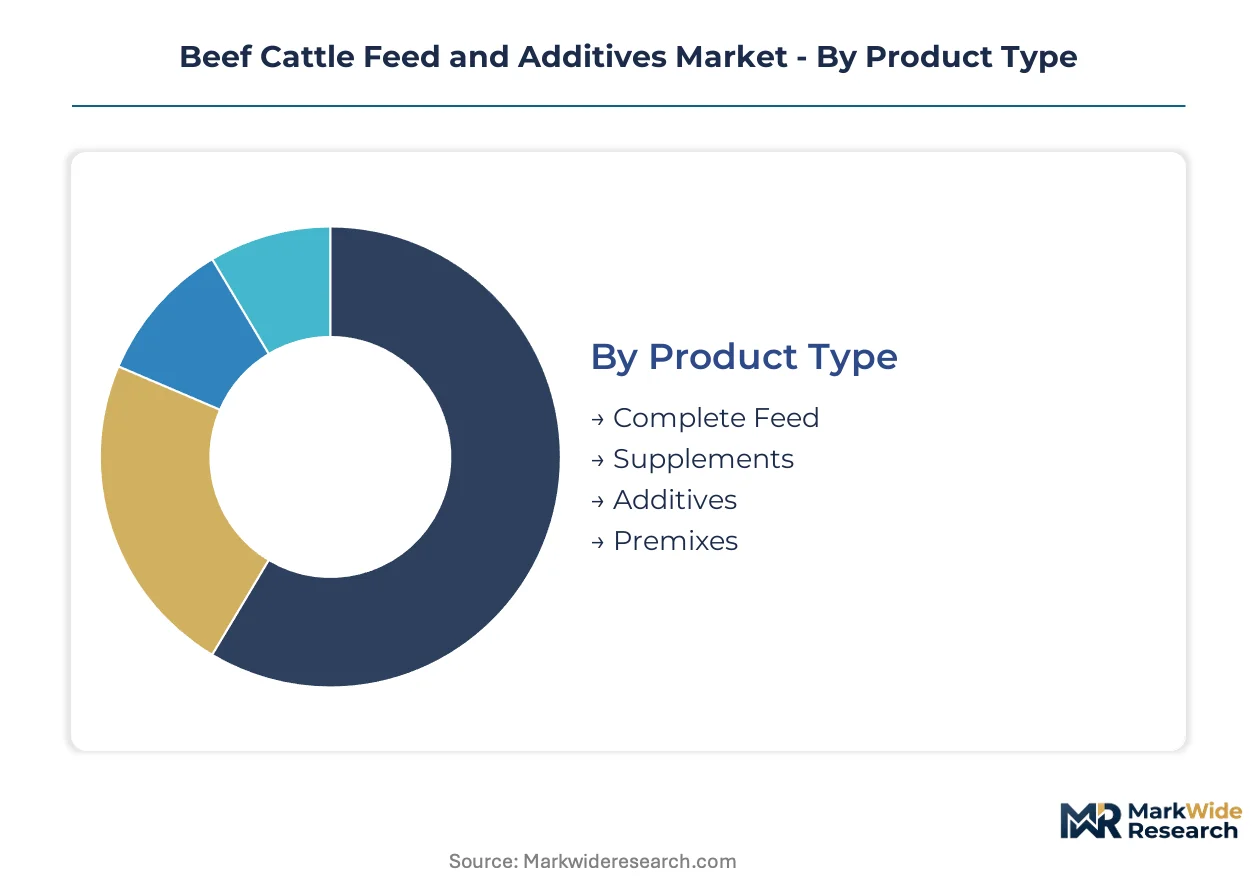
Segmentation in beef cattle feed and additives determines procurement cycles, inventory turnover, and margin capture across distinct production phases. Feedlot operators structure supplier relationships differently for high-velocity complete feeds versus slow-turn specialty additives.
Product Type:
Complete feed turns fastest through feed mill production schedules, while premixes and specialty additives cycle slowly due to formulation complexity and regulatory documentation burdens.
- Complete Feed:Nutritionally balanced rations delivering 2.9–3.2 Mcal/kg metabolizable energy density in ready-to-feed form. Demand concentrates in Nebraska and Kansas feedlot corridors where operators prioritize metabolizable energy cost predictability across growing and finishing phases.
- Additives:Functional inputs including ionophores, direct-fed microbials, and methane inhibitors formulated for targeted rumen modification. Procurement in Mato Grosso and São Paulo feedlots is accelerating as Brazilian operators scale precision-additive programs to capture premium EU export certification tiers.
- Supplements:Concentrated nutrient packages addressing specific dietary gaps in forage-based systems.
- Premixes:Micro-ingredient blends requiring precise inclusion rates and specialized mixing equipment.
Complete feed anchors the volume base while additives gain share at the steepest rate.
Ingredient:
Cost tiers separate commodity grains from value-added micronutrients, with protein meals occupying the volatile middle ground where oilseed processing margins fluctuate.
- Grains:Corn and sorghum providing fermentable carbohydrate bases for energy-dense finishing rations. Procurement in US Plains states consolidates around vertically integrated grain handlers who lock in cost predictability.
- Protein Meals:Soybean and canola meal displacing fishmeal in cost-sensitive rations. Argentine crushing capacity constraints create price volatility that compresses margin predictability for premix formulators sourcing across the Pampas grazing belt.
- Vitamins:Fat- and water-soluble micronutrients requiring stabilization against pelleting heat degradation.
- Minerals:Macro- and trace element supplements addressing regional soil deficiency patterns.
Grains dominate tonnage throughput while protein meals exhibit the most volatile cost structure.
Formulation:
Application context drives segmentation here, with organic and medicated variants serving distinct end-market certification requirements and regulatory compliance pathways.
- Conventional:Standard-formulation feeds using synthetic inputs and approved growth promoters. Production in North American feedlots maintains baseline cost efficiency where FDA veterinary feed directive compliance costs elevate operational overhead.
- Medicated:Feeds incorporating therapeutic or sub-therapeutic antibiotics with mandatory withdrawal protocols. Demand faces structural pressure from residue monitoring requirements and documentation burdens that strain mid-scale manufacturer balance sheets.
- Organic:Certified inputs meeting USDA National Organic Program or EU organic standards with restricted input lists.
- Non-Medicated:Antibiotic-free formulations relying on direct-fed microbials and precision nutrition.
Conventional formulations retain volume leadership while non-medicated alternatives expand most quickly.
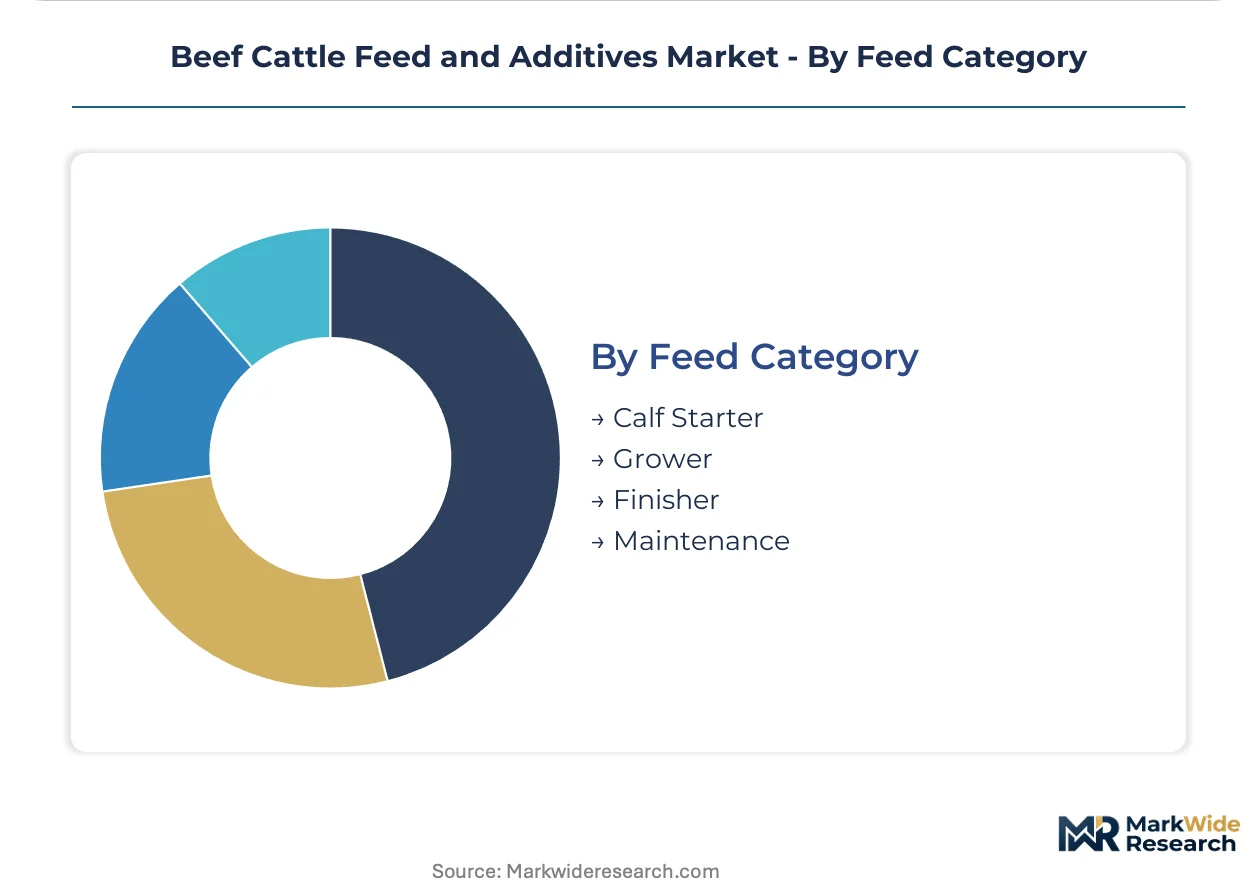
Feed Category:
Customer type segmentation aligns with cattle physiological stages, with finisher diets commanding premium formulation attention due to carcass quality impact.
- Finisher:High-energy rations optimizing intramuscular fat deposition and feed conversion ratios in the final 90-120 days. Evonik Industries AG dominates methionine supply for these diets, sustaining pricing power in concentrated pockets where protected amino acid encapsulation remains technically demanding.
- Grower:Transition rations balancing skeletal development with moderate energy density for yearling cattle. Formulation in southern Brazil's feedlot corridors emphasizes protein synchronization to capture premium export certification tiers.
- Calf Starter:Palatable, high-protein rations designed for rumen development in newly weaned animals.
- Maintenance:Baseline nutrition for breeding herds and backgrounding operations with minimal performance targets.
Finisher diets capture the deepest margin pools while grower formulations show the strongest volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Feedlot operators in Brazil demonstrate the lowest price elasticity for precision additives, while Argentine protein meal buyers face acute cost sensitivity due to crushing capacity constraints. Indian formulators occupy the middle ground, balancing BIS compliance investments against margin compression.
United States
Nebraska and Kansas feedlot corridors anchor North American demand for high-energy finisher rations with metabolizable energy cost predictability. FDA veterinary feed directive compliance elevates operational overhead for medicated feed producers. Cargill's vertically integrated grain procurement networks dominate procurement relationships across the Plains states.
Brazil
Mato Grosso and São Paulo operators scale precision-additive programs to capture premium EU export certification tiers. ANVISA alignment with international residue standards streamlines product registration for rumen-modifying additives. Southern feedlot corridors concentrate formulation expertise for Bos indicus production systems.
Argentina
Pampas grazing belt demand concentrates on protein synchronization for backgrounding operations ahead of feedlot entry. Crushing capacity constraints at Rosario and Bahía Blanca terminals create volatile soybean meal pricing that compresses premix margin predictability. Feedlot operators near Buenos Aires prioritize cost-efficient conventional formulations.
China
MEE agricultural emissions protocols open state-procurement channels for methane-inhibiting additives in northern cattle provinces. Shandong and Hebei feedlots face dual carbon goal pressure to document rumen fermentation modifications. Domestic premix distributors consolidate around suppliers with established SAMR registration pathways.
India
Uttar Pradesh and Rajasthan feedlots present first-mover opportunities as BIS feed safety standards harmonize with export market requirements. Central government livestock productivity programs subsidize precision nutrition adoption in dairy-cattle-beef crossover operations. Indigenous breed conservation mandates shape additive formulation priorities in Gujarat and Maharashtra.
Beef Cattle Feed and Additives Market Competitive Landscape
Capability concentration sits with specialized amino acid and enzyme suppliers; scale advantage sits with grain-handling conglomerates with captive feed manufacturing. The market structures around three tiers: multinational nutrition houses with EFSA and FDA approval portfolios, regional premix distributors with formulation chemist expertise, and commodity feed mills competing on metabolizable energy cost. Dominant competitive moves include backward integration into oilseed processing for protein meal security and technology licensing partnerships for direct-fed microbial strains.
Within the multinational nutrition tier, Cargill, Incorporated anchors North American feedlot supply relationships through grain procurement integration. BASF SE and Evonik Industries AG exemplify the specialized inputs segment, with the latter occupying a concentrated position in protected amino acid supply for high-performance finisher diets. These three entities represent distinct archetypes: captive supply chain control, diversified chemical platform leverage, and single-nutrient technical dominance.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| BASF SE |
| Evonik Industries AG |
| Archer Daniels Midland Company |
| DSM |
| Nutreco N.V. |
| Kemin Industries |
| Alltech |
| Land O'Lakes |
| Others |
Pricing and Supply Chain Analysis
The Paranaguá-Santos grain corridor anchors Brazilian feed additive pricing, with freight cost volatility transmitting directly into premix margin structures and downstream certification-tier price spreads across EU-bound beef exports.
Pricing Analysis
After-sales formulation services and precision nutrition consulting capture lifetime value beyond commodity feed transactions. Three-tier pricing structure across premium, standard, and economy levels separates EU-certified additive programs from conventional rations and unbranded commodity blends. Price differentiation hinges on metabolizable energy cost predictability and residue compliance documentation depth. Pricing pressure stems from Argentine soybean meal volatility compressing protein meal margins. Large-scale feedlot operators in Mato Grosso exhibit lowest price sensitivity; smallholder backgrounding operations in Rajasthan face acute cost constraints.
Supply Chain Analysis
Toll milling networks in Iowa, Illinois, and Indiana hold concentrated pelleting capacity for temperature-sensitive probiotic inclusion. Raw material sourcing draws from Corn Belt grain handlers, Argentine oilseed processors, and Chinese vitamin manufacturers. Supply chain risk centers on single-source dependency for protected amino acid encapsulation technology. Distribution runs through vertically integrated grain-procurement partners with captive premix formulation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision nutrition consulting and residue compliance documentation services expand faster than commodity feed tonnage, creating recurring revenue attachment opportunities for suppliers with EFSA and FDA approval portfolios.
For Market Incumbents: Entrench captive supply relationships by locking in metabolizable energy cost predictability across growing and finishing phases. Add backward integration into oilseed processing for protein meal security against Argentine crushing volatility. Deepen formulation chemist bench strength to offset retiring technical expertise concentration.
For New Entrants and Emerging Players: Build out blockchain-enabled feed traceability platforms targeting outcome-based pricing models for premium carcass quality programs. The underpenetrated Indian feedlot sector in Uttar Pradesh and Rajasthan offers lowest competitive density. Pursue BIS feed safety standard harmonization as regulatory entry credential.
For Investors and Strategic Acquirers: EU F-Gas Regulation extension to livestock methane accounting reshapes the acquisition landscape toward suppliers with validated emissions-reduction claims and third-party verification infrastructure. Long-term viability favors specialized amino acid and enzyme platforms over commodity grain-handling assets. Monitor SAMR registration pathway progress as inflection signal for China market access.
| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Approval Pathway | Unlocks premium EU export certification tiers for methane-inhibiting additive suppliers. |
| Backward Integration into Oilseed Processing | Secures protein meal cost predictability against Argentine crushing capacity constraints. |
| Precision Nutrition Consulting Services | Attaches recurring revenue to commodity feed transactions through formulation expertise. |
| Blockchain-Enabled Feed Traceability Platform | Enables outcome-based pricing models for premium carcass quality programs in Brazil. |
| BIS Feed Safety Standard Harmonization | Creates first-mover distribution advantages in Uttar Pradesh and Rajasthan feedlot corridors. |
Research Methodology
The analysis maps complete feed, premixes, additives, and supplements segments, each validated through feedlot procurement managers, formulation chemists, regulatory affairs specialists, and grain-handling executives. Primary fieldwork combined structured interviews with secondary validation against FDA veterinary feed directive filings, EFSA novel food approval databases, ANVISA residue standard alignments, and customs trade flow records. Bottom-up volume triangulation across ingredient categories reconciled with top-down value estimates from disclosed procurement contracts.
Forecast assumptions held EU Green Deal methane-reduction mandates and FDA antibiotic withdrawal protocols as fixed regulatory baselines while varying Brazilian feedlot corridor expansion rates and Indian BIS harmonization timelines. Segmentation modeling spanned product type, ingredient category, formulation certification, and feed category across the projection horizon. CAGRs derived from weighted average of historical volume elasticities and forward procurement contract pricing. Industry-specific inputs included metabolizable energy density specifications and protected amino acid bioavailability coefficients.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-procurement channels or accelerated EFSA approval timelines would shift outcomes. Quarterly review of SAMR registration progress, Argentine crushing margin reports, and EU export certification tier adoption rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
Swine Feed Market
Livestock Management
Roughage Feed Market
Livestock Management
Morocco Poultry Market
Livestock Management
Swine Artificial Insemination Market
Livestock Management
Europe Ruminant Feed Premix Market
Livestock Management
Colombia Animal Feed Market
Livestock Management
Cattle Management Software Market
Livestock Management
Pig Feed Market
Livestock Management
Poultry Feed Market
Livestock Management
Saudi Arabia Poultry Market
Livestock Management
Animal Artificial Insemination Market
Livestock Management
United States Swine Feed Market
Livestock Management
Animal Identification Market
Livestock Management
South America Swine Feed Market
Livestock Management
North America Ruminant Feed Market
Livestock Management
Equine Artificial Insemination Market