
 Swine Artificial Insemination Market | 2026-2036
Swine Artificial Insemination Market Size, Share, and Industry Trends Forecast 2026-2036
Swine Artificial Insemination Market Insights
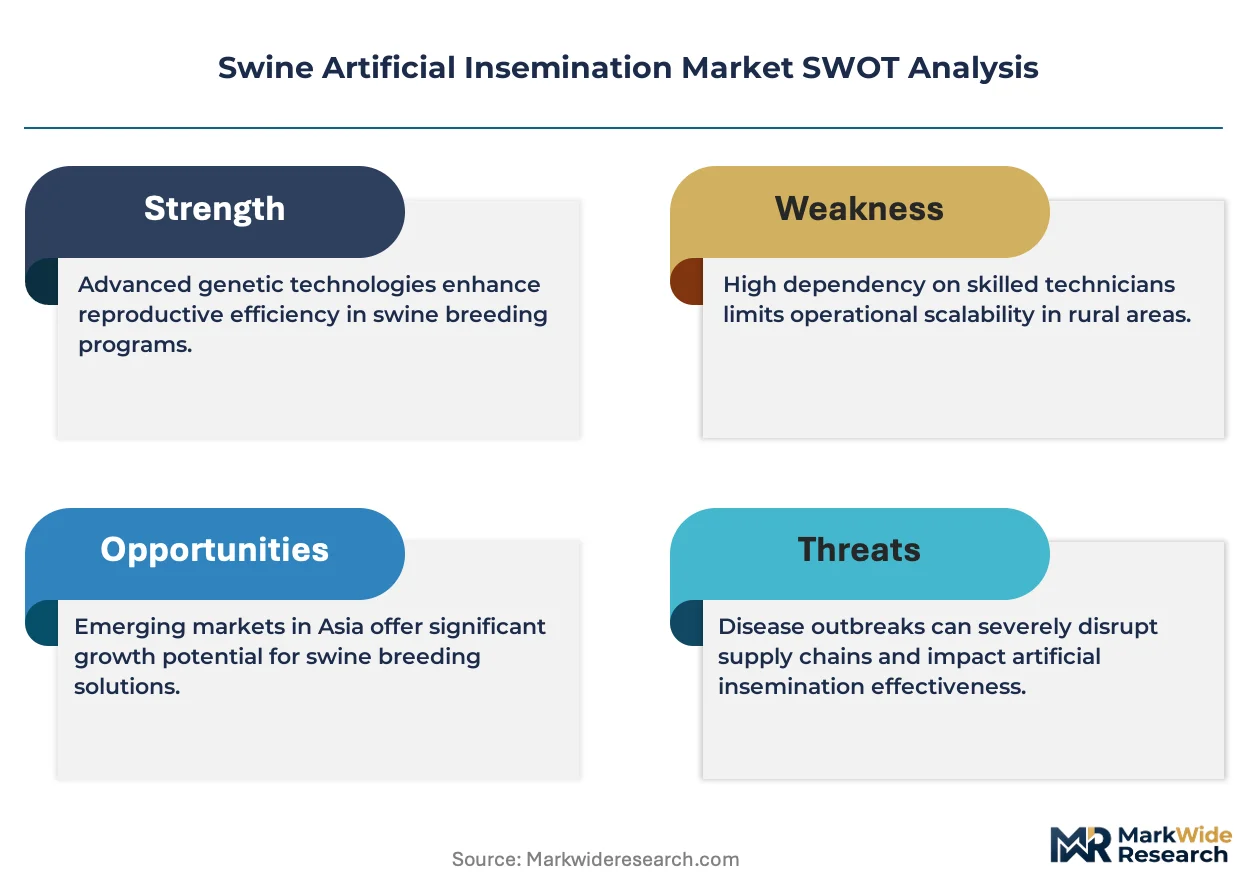
Multi-source procurement of swine genetics is restructuring supply relationships across the industry. Genus Plc leverages its global germplasm network to sustain breeding program continuity for integrated pork producers. MINITÜB GMBH anchors its position through specialized semen processing equipment and laboratory infrastructure. IMV Technologies competes across disposable insemination consumables and biosecurity-compliant collection systems.
Swine artificial insemination encompasses the clinical introduction of processed boar semen into the reproductive tract of estrus-synchronized sows, typically employing catheter-based delivery systems with fresh semen doses of 2-3 billion spermatozoa in 80-100 mL extender volumes. Fresh semen dominates commercial application due to higher conception rates and lower cryopreservation infrastructure requirements, while frozen semen concentrates in genetic improvement programs where long-distance transport of elite boar genetics justifies lower fertility margins. Large scale farms absorb the majority of insemination kit and hormonal treatment volumes, though smallholder farms represent a growing equipment segment as cooperative breeding associations consolidate procurement.
The USDA and FDA jointly oversee veterinary biologic standards and interstate semen movement protocols in the United States, while the EU Green Deal and F-Gas Regulation shape environmental compliance for cryogenic semen storage infrastructure across Denmark, Germany, and the Netherlands. China's NMPA and agricultural ministry enforce import quarantine and genetic material biosafety protocols that condition market access for foreign genetics suppliers. Stakeholders must monitor evolving gene editing regulatory frameworks and their potential reclassification of precision-bred germplasm under novel veterinary drug or food safety authorities.
Market Dynamics
Genetic improvement velocity is compressing breeding cycles across commercial pork operations, forcing semen logistics networks to synchronize with genomic selection timelines rather than traditional seasonal demand patterns.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants is accelerating investment in liquid nitrogen infrastructure for semen cryopreservation across Denmark, Germany, and the Netherlands.
- Large-scale integrated farm systems:Iowa and Sichuan Province operations are consolidating insemination services internally, absorbing equipment and consumable volumes that previously flowed through veterinary intermediaries.
- Genomic selection platforms:SNP-based breeding value predictions are shortening generation intervals, increasing the throughput requirements of semen collection and processing facilities.
Market Restraints
- Liquid nitrogen supply concentration:Cryogenic infrastructure depends on regional industrial gas suppliers, creating vulnerability for farms in peripheral agricultural zones.
- Elite boar genetic bottleneck:Top percentile terminal sire lines concentrate within a limited number of nucleus herds, amplifying disease transmission risks and supply disruption potential.
- Frozen semen fertility deficit:Post-thaw sperm viability remains substantially below fresh semen benchmarks, constraining adoption outside genetic improvement programs.
Strategic Opportunities
- Cooperative breeding associations:Smallholder consolidation in Eastern European markets creates procurement scale for shared laboratory infrastructure and semen distribution networks.
- China's import quarantine protocols:NMPA biosecurity requirements for foreign genetic material create localized production incentives for domestic boar studs and processing facilities.
- Sensor-integrated catheter systems:Convergence of disposable insemination equipment with intrauterine pressure monitoring enables precision deposition feedback for technician training.
Industry Challenges
- Cryobiology technician scarcity:Semen processing laboratories face recruitment gaps for personnel skilled in both reproductive physiology and quality control microscopy.
- Multi-jurisdiction certification complexity:USDA veterinary biologic standards, EU animal health directives, and national quarantine regimes impose overlapping compliance timelines for cross-border germplasm movement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Swine Artificial Insemination Market |
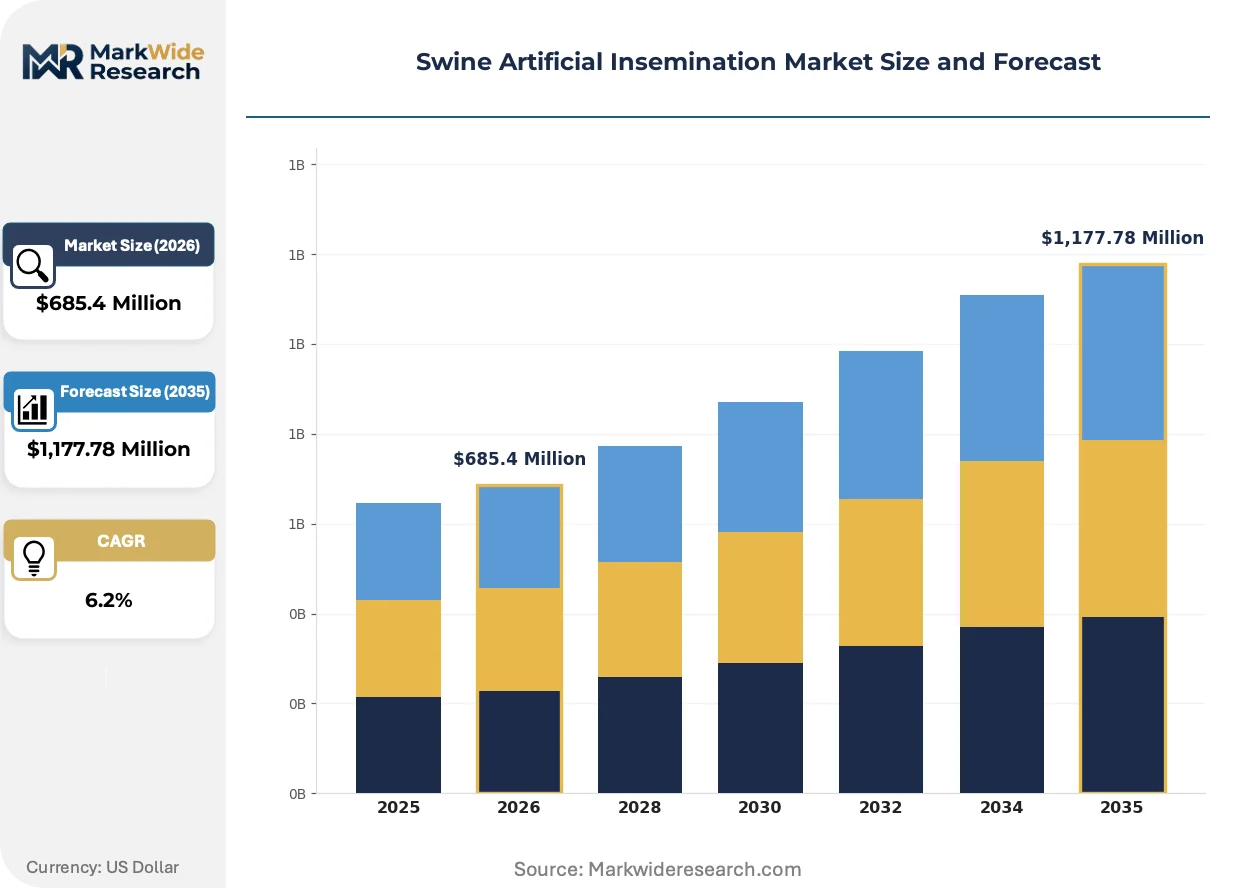
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Semen, Fresh Semen, Insemination Kits, Hormonal Treatments Application: Commercial Breeding, Genetic Improvement, Research, Hobby Farming Technology: Artificial Insemination, Ultrasound Monitoring, Semen Processing, Record Keeping End User: Large Scale Farms, Research Institutions, Smallholder Farms, Veterinary Clinics |
| Companies Covered | IMV Technologies, Genus Plc, Shipley Swine Genetics, Agtech Inc., Neogen Corporation, GenePro Inc., MINITÜB GMBH, Swine Genetics International, Hypor BV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Swine Artificial Insemination Market Trends and Innovations
Reproductive biotechnology is fragmenting into specialized service layers, with genetic evaluation, semen logistics, and insemination execution now frequently unbundled across distinct vendor relationships rather than integrated within single operations.
Disposable intrauterine catheter systems with integrated cervical lock mechanisms are displacing reusable equipment in large-scale sow farms. Danish and Dutch integrators are standardizing these single-use devices across company-owned multiplication units. The shift is modularizing insemination supply chains, separating equipment procurement from semen sourcing decisions.
The EU F-Gas Regulation is mandating refrigerant transitions in semen storage infrastructure, compelling cryogenic tank manufacturers to certify equipment for alternative cooling chemistries. Boar studs in Germany and the Netherlands are retrofitting existing liquid nitrogen systems ahead of compliance deadlines. Frozen semen distribution networks face the steepest adaptation costs given their dependence on vapor-phase storage integrity.
Integrated pork producers are unbundling insemination services from veterinary practice contracts, establishing direct procurement relationships with semen suppliers and equipment vendors. This disintermediation concentrates in North American and European operations with internal sow inventories exceeding ten thousand head. Sichuan Province farm clusters are replicating the model through cooperative purchasing platforms that aggregate smallholder demand.
Swine Artificial Insemination Market Segmentation
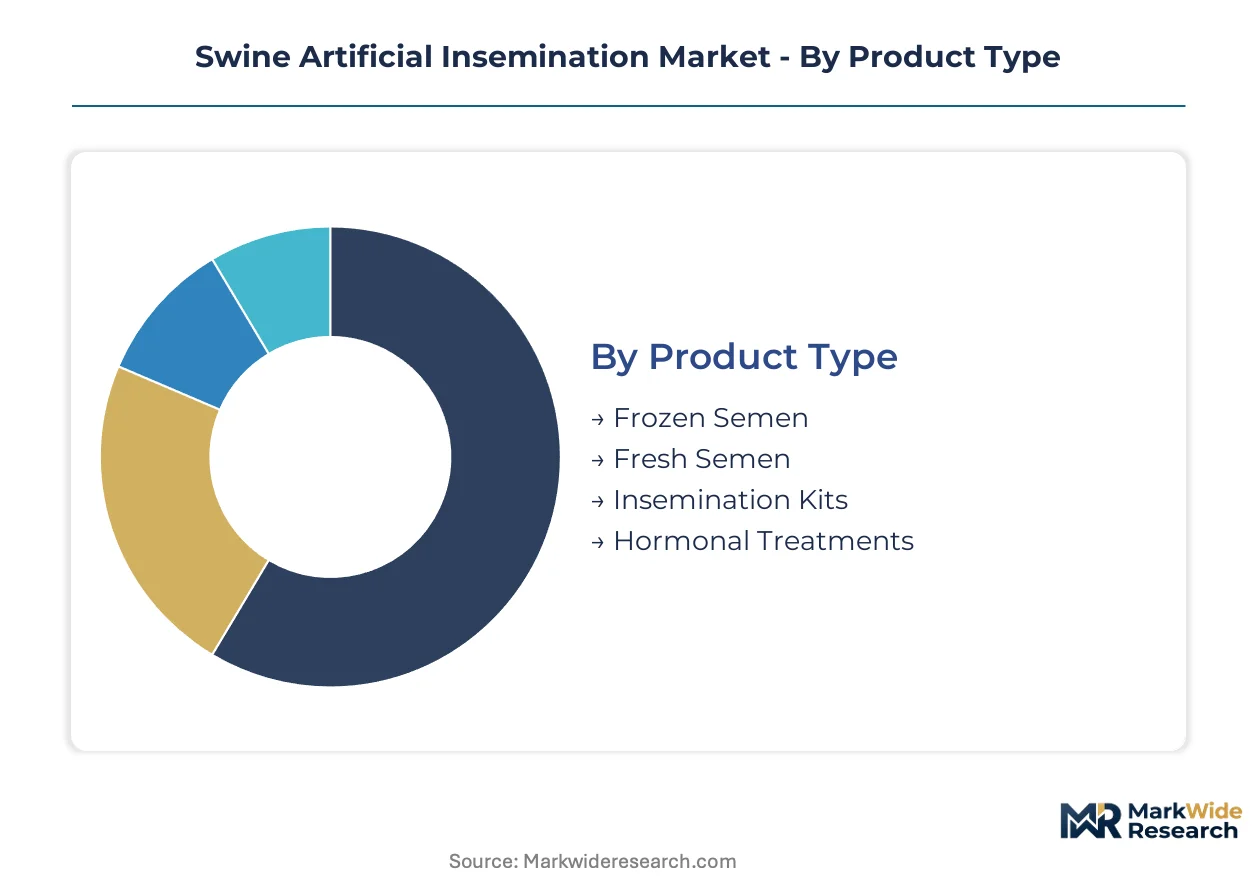
Swine artificial insemination markets fragment across product maturity curves and operational scale thresholds. Procurement patterns diverge sharply between integrated pork producers optimizing genetic throughput and smallholders prioritizing equipment accessibility over laboratory sophistication.
Product Type:
Cost tier determines adoption sequencing, with fresh semen dominating high-volume commercial operations while frozen alternatives command premium positioning for genetic improvement programs.
- Fresh Semen:Contains 2-3 billion spermatozoa in 80-100 mL extender volumes, maintaining higher post-collection viability than cryopreserved alternatives. Large-scale Iowa and Sichuan Province operations absorb the majority of fresh semen doses, driven by conception rate benchmarks that exceed frozen alternatives by substantial margins. The segment leads on scale.
- Frozen Semen:Requires liquid nitrogen vapor-phase storage infrastructure and specialized thaw protocols, trading fertility margins for genetic mobility across quarantine boundaries. Denmark and Germany boar studs are retrofitting cryogenic systems under EU F-Gas Regulation compliance timelines, expanding frozen distribution networks for elite terminal sire genetics. The segment leads on momentum.
- Insemination Kits:Disposable catheter systems with cervical lock mechanisms are displacing reusable equipment across Dutch and Danish company-owned multiplication units.
- Hormonal Treatments:Estrus synchronization protocols enable batch farrowing schedules that align semen logistics with genomic selection timelines.
Fresh semen leads on scale; frozen semen leads on momentum.
Application:
Volume concentration follows operational sophistication, with commercial breeding absorbing equipment and consumable flows that research and hobby segments cannot aggregate.
- Commercial Breeding:Integrated pork producers in North America and Europe are unbundling insemination services from veterinary contracts, establishing direct procurement relationships with semen suppliers. Iowa operations with internal sow inventories exceeding ten thousand head now internalize collection and processing infrastructure previously outsourced.
- Genetic Improvement:SNP-based breeding value predictions compress generation intervals, forcing semen logistics networks to synchronize with genomic selection timelines rather than seasonal demand patterns. Nucleus herds concentrate top percentile terminal sire lines, amplifying disease transmission risks across limited genetic bottlenecks.
- Research:Academic and institutional programs in China and the United States evaluate gene editing frameworks and precision-bred germplasm under evolving regulatory classifications.
- Hobby Farming:Cooperative breeding associations in Eastern Europe consolidate smallholder procurement for shared laboratory infrastructure and semen distribution networks.
Commercial breeding commands volume concentration; genetic improvement drives technology premium extraction.
Technology:
Supply concentration shapes vendor relationships, with semen processing and artificial insemination equipment frequently sourced from distinct suppliers rather than integrated procurement.
- Artificial Insemination:Catheter-based delivery systems dominate commercial application, with technician skill levels varying substantially between large-scale farm employees and veterinary clinic personnel.
- Ultrasound Monitoring:Real-time imaging enables precise estrus detection and pregnancy confirmation, reducing semen waste in high-throughput operations.
- Semen Processing:Quality control microscopy and cryobiology expertise concentrate in specialized boar studs, creating recruitment gaps for personnel skilled in both reproductive physiology and laboratory standards.
- Record Keeping:Digital pedigree tracking and genomic data management platforms are fragmenting into specialized service layers unbundled from insemination execution.
Semen processing anchors margin capture; record keeping expands most quickly through platform unbundling.
End User:
Customer type determines service configuration, with large-scale farms absorbing internalized infrastructure that smallholders must access through cooperative or veterinary intermediaries.
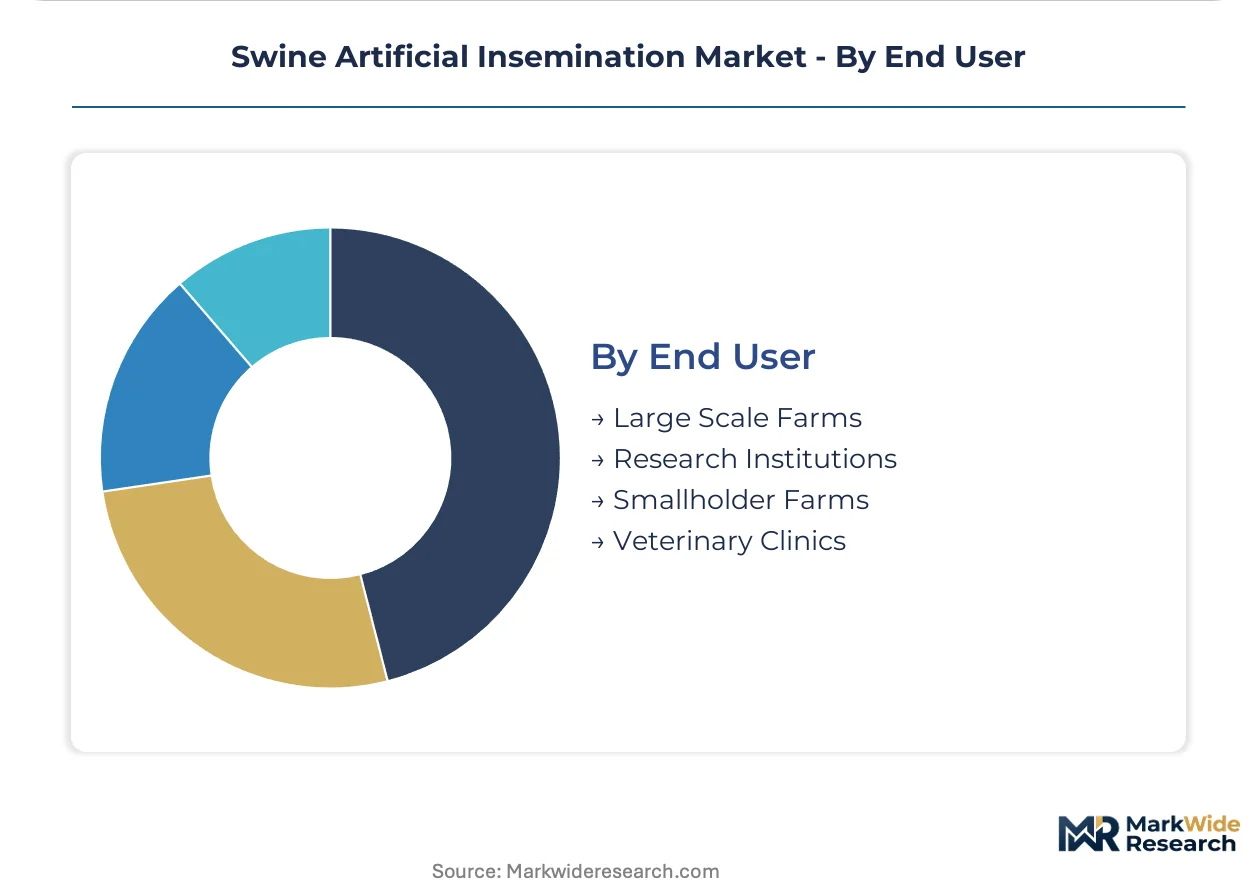
- Large Scale Farms:Operations across Iowa, Denmark, and China's Sichuan Province consolidate insemination services internally, absorbing equipment and consumable volumes that previously flowed through veterinary intermediaries. Direct procurement relationships with semen suppliers disintermediate traditional distribution channels.
- Smallholder Farms:Cooperative purchasing platforms in Sichuan Province and Eastern Europe aggregate fragmented demand for shared laboratory infrastructure and semen distribution networks, replicating the scale economics of integrated operations.
- Research Institutions:Academic programs evaluate gene editing regulatory frameworks and their potential reclassification of precision-bred germplasm under novel veterinary drug or food safety authorities.
- Veterinary Clinics:Traditional intermediaries face margin compression as large producers internalize insemination services, shifting toward smallholder and hobby farm segments.
Large scale farms dominate volume absorption; smallholder farms climb the fastest through cooperative consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Iowa's concentrated hog operations anchor commercial insemination demand, with Sichuan Province and Denmark forming complementary high-volume clusters. Regulatory divergence across these production centers shapes equipment compliance pathways and semen logistics infrastructure investments.
United States
Integrated pork producers across Iowa and North Carolina internalize insemination services previously outsourced to veterinary intermediaries. The USDA and FDA jointly oversee interstate semen movement protocols and veterinary biologic standards, creating multi-layer compliance requirements. Large-scale sow farms exceeding ten thousand head now establish direct procurement relationships with semen suppliers.
China
Sichuan Province farm clusters replicate North American disintermediation models through cooperative purchasing platforms aggregating smallholder demand. The NMPA and agricultural ministry enforce import quarantine and genetic material biosafety protocols that condition market access for foreign genetics suppliers. Domestic boar studs and processing facilities expand capacity to satisfy localized production incentives.
Denmark
Danish integrators standardize disposable intrauterine catheter systems across company-owned multiplication units. The EU F-Gas Regulation mandates refrigerant transitions in semen storage infrastructure, compelling cryogenic tank retrofitting ahead of compliance deadlines. Boar studs concentrate frozen semen distribution networks for elite terminal sire genetics.
Germany
German boar studs face steepest adaptation costs for vapor-phase storage integrity under EU F-Gas Regulation phasedown timelines. The ECHA and national agricultural authorities shape environmental compliance for cryogenic semen storage infrastructure. Lower Saxony and Bavaria host nucleus herds concentrating top percentile genetic lines.
Netherlands
Dutch company-owned multiplication units drive displacement of reusable insemination equipment by single-use devices with cervical lock mechanisms. The EU Green Deal and F-Gas Regulation accelerate investment in liquid nitrogen infrastructure for semen cryopreservation. Research institutions evaluate gene editing regulatory frameworks and precision-bred germplasm classifications.
Swine Artificial Insemination Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue sensor-integrated catheter systems and cooperative service platforms. The vendor base stratifies across germplasm networks, specialized semen processing equipment, and disposable consumables. Three archetypes dominate: global genetics suppliers with integrated germplasm networks, laboratory infrastructure specialists, and single-use device manufacturers. Competitive moves concentrate on vertical integration of insemination services and geographic expansion through cooperative breeding associations.
Among diversified genetics suppliers, Genus Plc occupies a position exemplifying global germplasm network architecture, while IMV Technologies represents the disposable consumables and biosecurity-compliant collection systems archetype. MINITÜB GMBH anchors the specialized laboratory infrastructure tier. These three entities collectively illustrate the unbundling trend separating equipment procurement from semen sourcing decisions across integrated pork operations.
| Leading Market Players |
|---|
| IMV Technologies |
| Genus Plc |
| Shipley Swine Genetics |
| Agtech Inc. |
| Neogen Corporation |
| GenePro Inc. |
| MINITÜB GMBH |
| Swine Genetics International |
| Hypor BV |
| Others |
Pricing and Supply Chain Analysis
The EU F-Gas Regulation gates qualified supply and premium-tier pricing access for cryogenic semen storage infrastructure, compelling retrofit investments that concentrate procurement power among Danish and Dutch integrators with internal liquid nitrogen systems while peripheral agricultural zones absorb cost pass-throughs from regional industrial gas suppliers.
Pricing Analysis
Input-cost pass-through from liquid nitrogen supply concentration and cryogenic tank retrofitting under EU F-Gas compliance timelines is compressing margins across frozen semen distribution networks. Three-tier pricing structure across premium elite genetics, standard commercial doses, and economy cooperative procurement reflects certification grade and volume scale differentiation. Pricing pressure stems from large-scale Iowa and Sichuan Province farms internalizing collection infrastructure previously outsourced. Smallholder cooperatives exhibit highest price sensitivity due to shared laboratory cost allocation, while nucleus herds with captive boar studs demonstrate lowest sensitivity.
Supply Chain Analysis
Dual-sourcing requirements for semen processing equipment and disposable consumables mandate multi-supplier qualification across integrated pork operations, with procurement managers maintaining parallel vendor relationships for catheter systems and extenders. Supply concentrates in Germany, Denmark, and the United States for specialized laboratory infrastructure and elite germplasm networks. Raw material dependencies center on pharmaceutical-grade extenders, medical-grade plastics for disposable catheters, and industrial gas supply for cryopreservation. Single-source vulnerability runs through concentrated elite boar genetic lines in limited nucleus herds. Distribution runs through direct procurement relationships displacing veterinary intermediaries in large-scale operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EU F-Gas phasedown timelines and China's NMPA biosecurity protocols are accelerating infrastructure replacement cycles and localized production incentives.
For Market Incumbents: Deploy backward integration into liquid nitrogen infrastructure to secure cryogenic supply continuity ahead of EU F-Gas compliance deadlines. Consolidate catheter manufacturing capacity in Denmark and the Netherlands to capture standardization momentum across company-owned multiplication units. Sensor-integrated catheter systems from emerging entrants threaten equipment margin structures; preemptive R&D investment in intrauterine pressure monitoring technology maintains pricing power. For New Entrants and Emerging Players: Capture cooperative breeding association procurement in Eastern European smallholder markets through shared laboratory service platforms. White-space concentration exists in Sichuan Province farm clusters replicating North American disintermediation models via aggregated demand platforms. Gene editing regulatory evaluation services for research institutions offer a specialized go-to-market angle with limited incumbent presence. For Investors and Strategic Acquirers: Roll-up economics work for regional boar stud operators because EU F-Gas retrofit costs are fragmenting cryogenic infrastructure ownership and creating distressed acquisition targets among undercapitalized processors. Five-to-ten year viability hinges on genomic selection platform integration rather than traditional seasonal logistics. The signal to watch is NMPA import quarantine protocol relaxation that would shift foreign genetics supplier market access materially.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Nitrogen Infrastructure Retrofit | EU F-Gas compliance deadlines in Germany and the Netherlands compel cryogenic tank replacement. |
| Cooperative Breeding Platform Launch | Sichuan Province and Eastern European smallholder aggregation replicates integrated farm economics. |
| Sensor-Integrated Catheter Development | Intrauterine pressure monitoring enables precision deposition feedback for technician training programs. |
| Domestic Boar Stud Capacity Expansion | China's NMPA biosecurity protocols create localized production incentives for foreign genetics suppliers. |
| Genomic Data Management Platform Integration | Digital pedigree tracking unbundles from insemination execution across North American operations. |
Research Methodology
Bottom-up sow farm modeling reconciled against top-down semen processing facility tracking forms the analytical core of this study. Primary interviews with boar stud operations managers, veterinary clinic procurement leads, integrated pork producer genetics directors, cooperative breeding association coordinators, and cryogenic equipment manufacturers were combined with secondary validation from USDA veterinary biologic filings, EU animal health directive databases, China NMPA import quarantine records, and trade customs data for semen extender chemicals. Cross-referencing bottom-up equipment shipment tallies against top-down farm inventory surveys ensures segmentation integrity.
Historical trendline analysis of fresh and frozen semen dose volumes, insemination kit deployments, and hormonal treatment shipments established baseline growth patterns across the projection horizon. Segmentation modeling incorporated product type maturity curves, application sophistication tiers, technology unbundling patterns, and end-user scale thresholds. CAGRs were derived from regression analysis against genomic selection adoption rates and regulatory compliance investment cycles. Industry-specific forecast inputs included SNP-based breeding value prediction penetration and EU F-Gas retrofit completion timelines.
Gene editing regulatory reclassification, liquid nitrogen supply disruption, and elite boar disease outbreak are the dominant revision risks to the forecast framework. Deviation in NMPA import protocol stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
Herd Management Software Market
Livestock Management
Poultry Feed Market
Livestock Management
Global Smart Ear Tags Market
Livestock Management
Roughage Feed Market
Livestock Management
Wagyu Beef Market
Livestock Management
Cattle Mineral Feeder Market
Livestock Management
South America Ruminant Feed Premix Market
Livestock Management
Pig Feed Market
Livestock Management
Morocco Poultry Market
Livestock Management
Colombia Animal Feed Market
Livestock Management
Europe Ruminant Feed Premix Market
Livestock Management
Layer Feed Market
Livestock Management
Cattle Management Software Market
Livestock Management
North America Ruminant Feed Market
Livestock Management
North America Swine Feed Market
Livestock Management
Smart Feeding Systems Market