
 Cattle Feeder Market | 2026-2036
Cattle Feeder Market Size, Share, and Industry Trends Forecast 2026-2036
Cattle Feeder Market Analysis
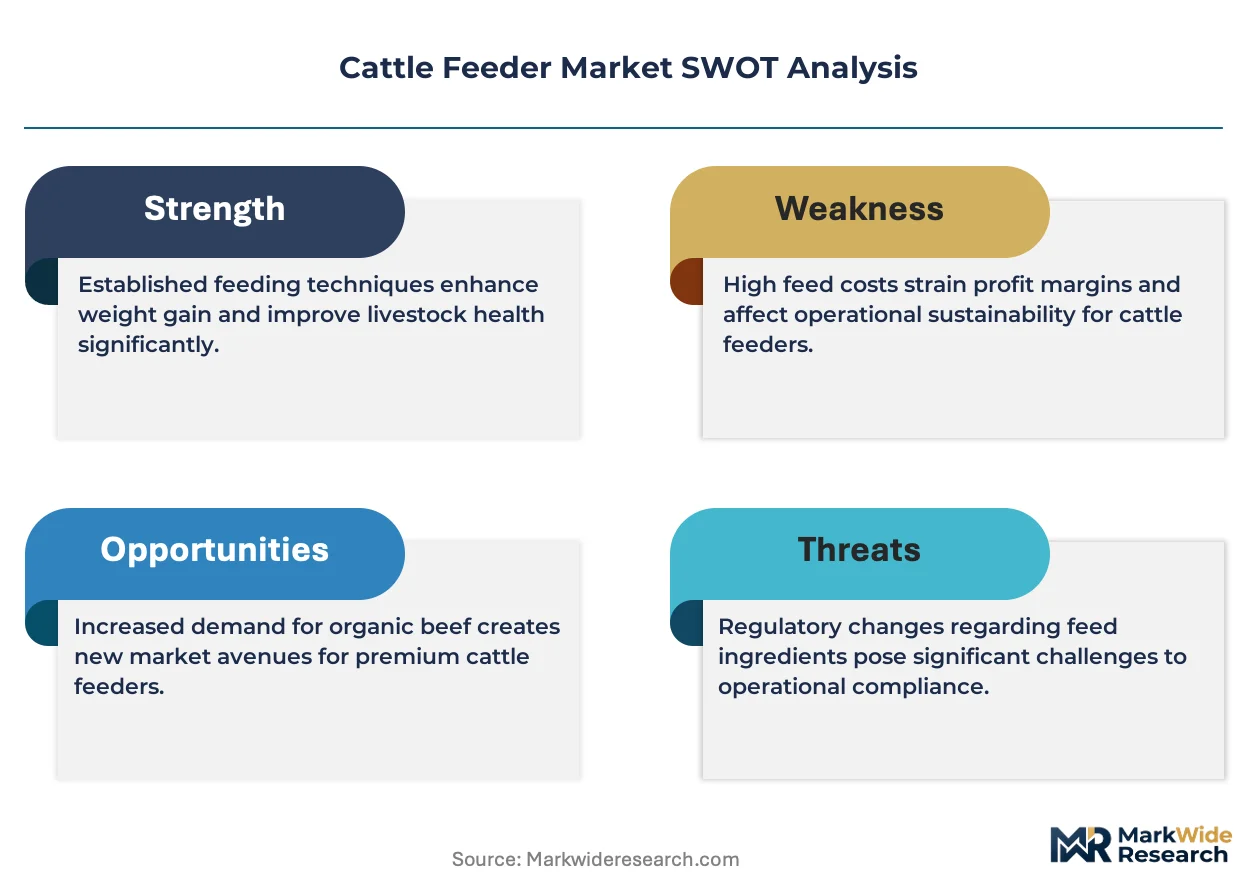
The cattle feeder supply base is restructuring around a sharp split between precision-engineered automated systems and basic bunk feeders serving price-sensitive ranchers. Cargill leverages its integrated grain-to-protein platform to control input costs across feed manufacturing and equipment placement. Nutreco N.V. anchors its position through R&D intensity in precision livestock nutrition, while Farmco competes on manufacturing scale in the commodity bunk feeder tier.
A cattle feeder is a mechanized or static vessel designed to dispense formulated rations to bovine animals, typically constructed from galvanized steel, concrete, or heavy-duty polyethylene with capacities ranging from portable 500-pound units to stationary systems exceeding 20 tons. Its primary commercial purpose is to minimize feed waste, standardize intake per head, and reduce labor hours in operations managing herds above 500 animals. Automated Feeders command the strongest margin pools as dairy farms above 1,000 head adopt IoT-linked dispensing, while TMR Mixers represent the fastest-growing category among feedlot operators seeking total mixed ration consistency. Silage Bunkers remain a mature, replacement-driven segment where price competition limits differentiation.
The US Environmental Protection Agency shapes demand through Clean Water Act runoff provisions that push feedlot operators toward covered, precision-delivery systems that reduce nutrient leaching. USDA Natural Resources Conservation Service cost-share programs further steer capital investment toward equipment meeting specified environmental performance thresholds. Stakeholders must monitor how emerging state-level methane accounting rules will redefine acceptable feeder configurations before the next equipment replacement cycle.
Market Dynamics
USDA conservation cost-share programs and EPA Clean Water Act enforcement are compressing the viable equipment pool toward precision nutrient-delivery systems that minimize runoff and methane emissions. This regulatory pressure is accelerating capital replacement cycles among feedlot operators and dairy cooperatives managing herds above 1,000 head.
Growth Catalysts
- IoT-linked dispensing systems:Dairy farms above 1,000 head deploy sensor-integrated feeders that adjust rations based on individual animal intake data, cutting labor hours and feed waste simultaneously.
- USDA NRCS Environmental Quality Incentives Program:Cost-share funding covers up to 75% of equipment costs for covered bunk systems that reduce nutrient leaching into watersheds.
- Midwest feedlot corridor consolidation:Large-scale operators in Nebraska, Kansas, and Texas are standardizing on automated TMR mixers to achieve ration consistency across multiple locations.
Market Restraints
- Galvanized steel price volatility:Input cost swings for feeder construction materials compress margins for commodity bunk feeder manufacturers serving price-sensitive ranchers.
- Precision equipment technical complexity:Automated systems require specialized calibration and maintenance protocols that exceed the technical capacity of smaller operations without on-staff veterinarians or nutritionists.
- Substitution by grazing management:Some cow-calf operations are extending rotational grazing periods to defer capital expenditure on stationary feeding infrastructure.
Strategic Opportunities
- Underpenetrated dairy regions in India:Cooperative dairy federations in Gujarat and Maharashtra are beginning to trial automated feeding as labor costs rise in peri-urban production zones.
- Convergence of methane monitoring and feed optimization:Integration of enteric emissions sensors with ration-dispensing algorithms creates premium positioning for equipment vendors serving carbon-conscious protein buyers.
- Direct-to-farm digital sales channels:Equipment financing platforms and telematics-enabled remote diagnostics are bypassing traditional dealer networks in the US Plains states.
Industry Challenges
- Electro-mechanical technician shortage:Automated feeder deployment outpaces the supply of service technicians capable of troubleshooting hydraulic drive systems and PLC controllers in rural locations.
- Legacy bunk integration complexity:Feedlots with existing concrete silage bunkers face structural modification costs when retrofitting precision-delivery attachments to meet new environmental performance thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cattle Feeder Market |
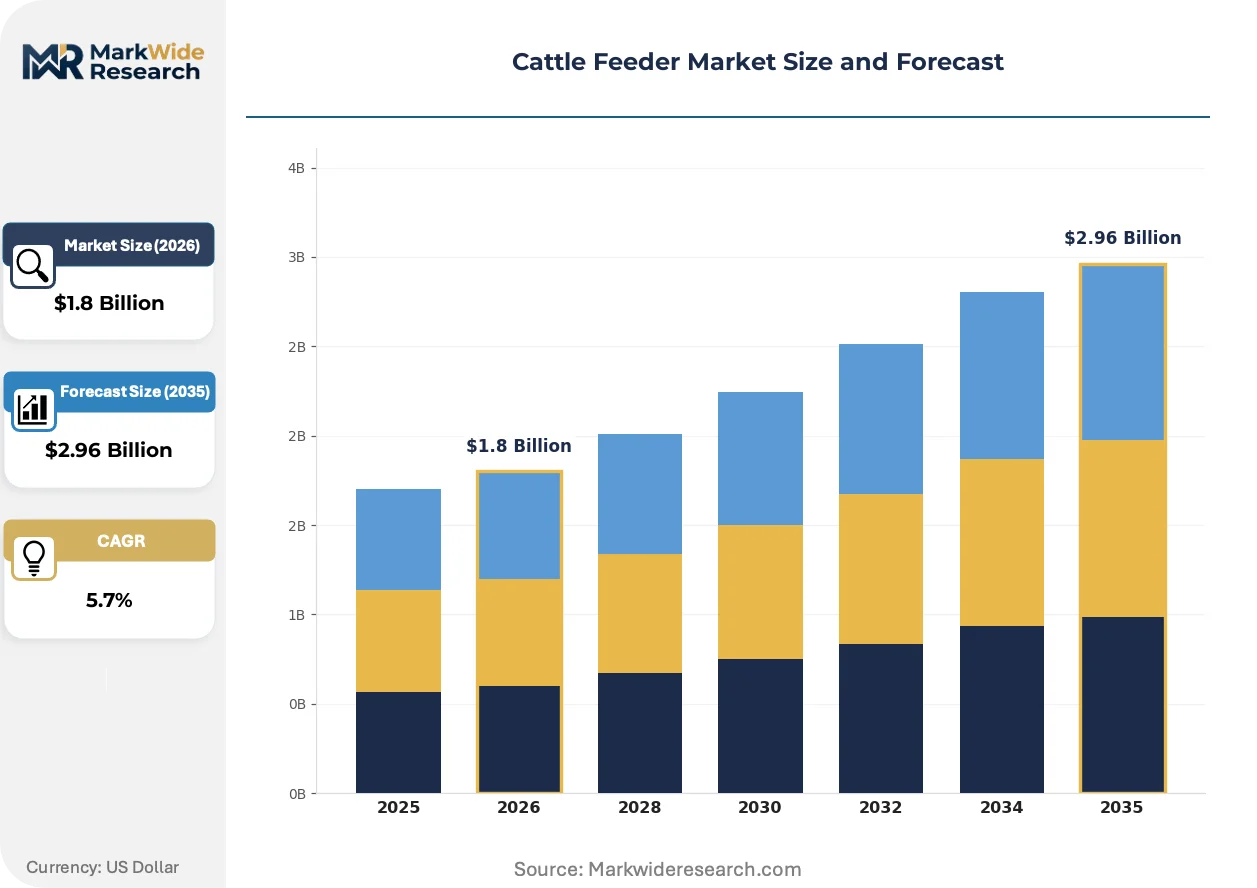
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Feeders, Bunk Feeders, TMR Mixers, Silage Bunkers Application: Bovine Nutrition, Feedlot Operations, Dairy Farming, Beef Production End User: Farmers, Ranchers, Agribusiness, Feed Manufacturers Technology: IoT Solutions, Mobile Feed Management, Data Analytics, RFID Tracking |
| Companies Covered | Cargill, Land O'Lakes, Nutreco N.V., BASF SE, Archer Daniels Midland Company, Farmco, HE SILOS, Bison Industries, Ahrens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cattle Feeder Market Emerging Trajectories
Feeder technology is bifurcating between premium automated systems with embedded analytics and stripped-down mechanical units for ranchers deferring capital outlays. This divergence is reshaping vendor R&D priorities and distribution channel economics.
Sensor-integrated TMR mixers with real-time dry-matter analysis are overtaking conventional batch-mixing equipment in US feedlots above 5,000 head. These systems adjust ingredient proportions based on instantaneous moisture readings, eliminating the need for manual sampling and laboratory testing. The technology is compressing the acceptable error margin for ration formulation from 5% to under 1%, forcing smaller mixer manufacturers to license sensing modules or exit the large-feedlot segment.
EPA regional enforcement of Clean Water Act Concentrated Animal Feeding Operation rules is mandating covered feed storage and precision delivery in the Chesapeake Bay and Mississippi River watersheds. Feedlot operators in Virginia, Maryland, and Iowa must document nutrient management plans that specify equipment capable of eliminating stormwater contact with feed. This is driving replacement demand for enclosed hopper systems ahead of standard depreciation schedules.
Buying committees at protein integrators are unbundling equipment procurement from nutrition consulting services that historically locked in feeder brand selection. Cargill Protein and JBS USA are issuing separate RFPs for hardware and ration formulation, opening vendor access for specialized equipment makers without captive nutrition platforms. This pattern is most visible in the Texas Panhandle and western Kansas feedlot clusters where integrators manage multiple contractor-operated yards.
Cattle Feeder Market Segmentation
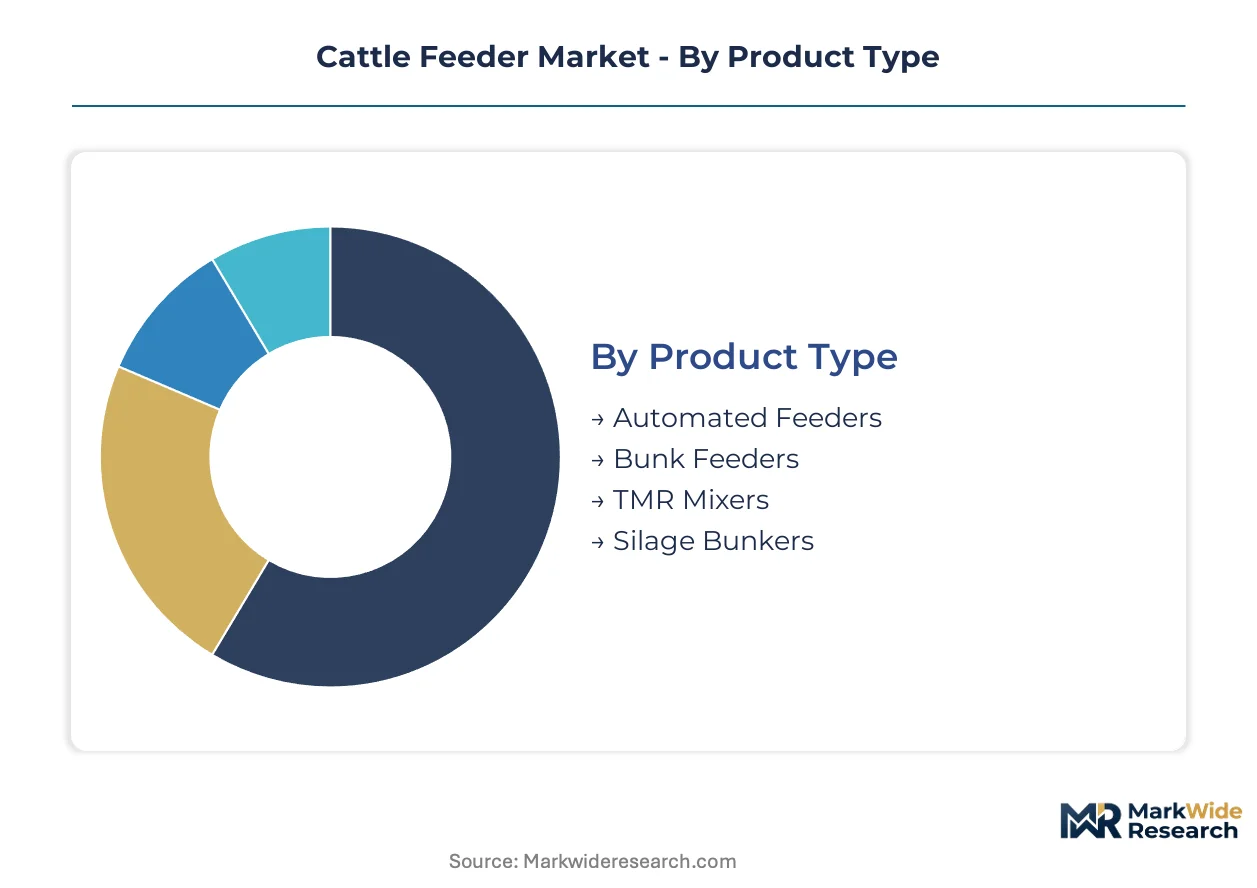
Cattle feeder procurement patterns diverge sharply across operation scale and regulatory exposure. Large integrators prioritize precision-delivery systems that satisfy EPA nutrient management mandates, while smaller ranchers defer capital outlays on basic bunk infrastructure.
Product Type:
Cost tier separates precision-engineered automated systems from commodity bunk feeders serving price-sensitive buyers.
- Automated Feeders:Sensor-integrated dispensing systems with PLC-controlled augers and real-time intake monitoring. Demand concentrates in US dairy operations above 1,000 head where labor costs and EPA runoff compliance drive replacement cycles.
- TMR Mixers:Horizontal or vertical auger systems blending forages, grains, and supplements into total mixed rations. Feedlot operators in Nebraska and Kansas standardize on these units to achieve ration consistency across contractor-managed yards.
- Bunk Feeders:Static trough systems constructed from galvanized steel or concrete for ad-libitum feeding. Ranchers in the Plains states deploy these for backgrounding operations where capital constraints limit automation investment.
- Silage Bunkers:Covered trench or above-ground structures for anaerobic feed storage. Replacement demand in the Midwest follows standard depreciation schedules with limited technology differentiation.
Bunk Feeders lead volumes today; TMR Mixers are gaining share fastest.
Application:
Volume scale and animal physiology dictate equipment specifications across distinct production phases.
- Feedlot Operations:Finishing yards managing 5,000-plus head require TMR mixers with precise ingredient control to optimize feed conversion ratios and meet buyer protein specifications.
- Dairy Farming:Parlor-linked feeding systems in Wisconsin and California deploy IoT-enabled dispensers that synchronize ration delivery with milking schedules and individual cow production records.
- Beef Production:Cow-calf and stocker operations rely on portable bunk feeders for rotational grazing systems where permanent infrastructure is impractical.
- Bovine Nutrition:Research and bull test stations utilize precision feeders for intake measurement studies supporting genetic selection programs.
Feedlot Operations anchor revenue today; Dairy Farming shows the steepest expansion trajectory.
End User:
Technical capacity and balance sheet strength determine automation adoption rates.
- Agribusiness:Integrated protein companies and cooperative federations deploy enterprise-scale feeding systems with centralized telemetry monitoring across multiple facility locations.
- Feed Manufacturers:Vertically integrated nutrition companies bundle equipment placement with formulation services, controlling input costs through captive feeder deployment.
- Farmers:Family dairy operations in the 200-500 head range represent the contested middle market where financing terms and service coverage drive vendor selection.
- Ranchers:Cow-calf producers prioritize equipment durability and field repairability over precision features, sustaining demand for mechanical bunk systems.
Agribusiness commands the premium tier; Farmers represent the largest addressable expansion pool.
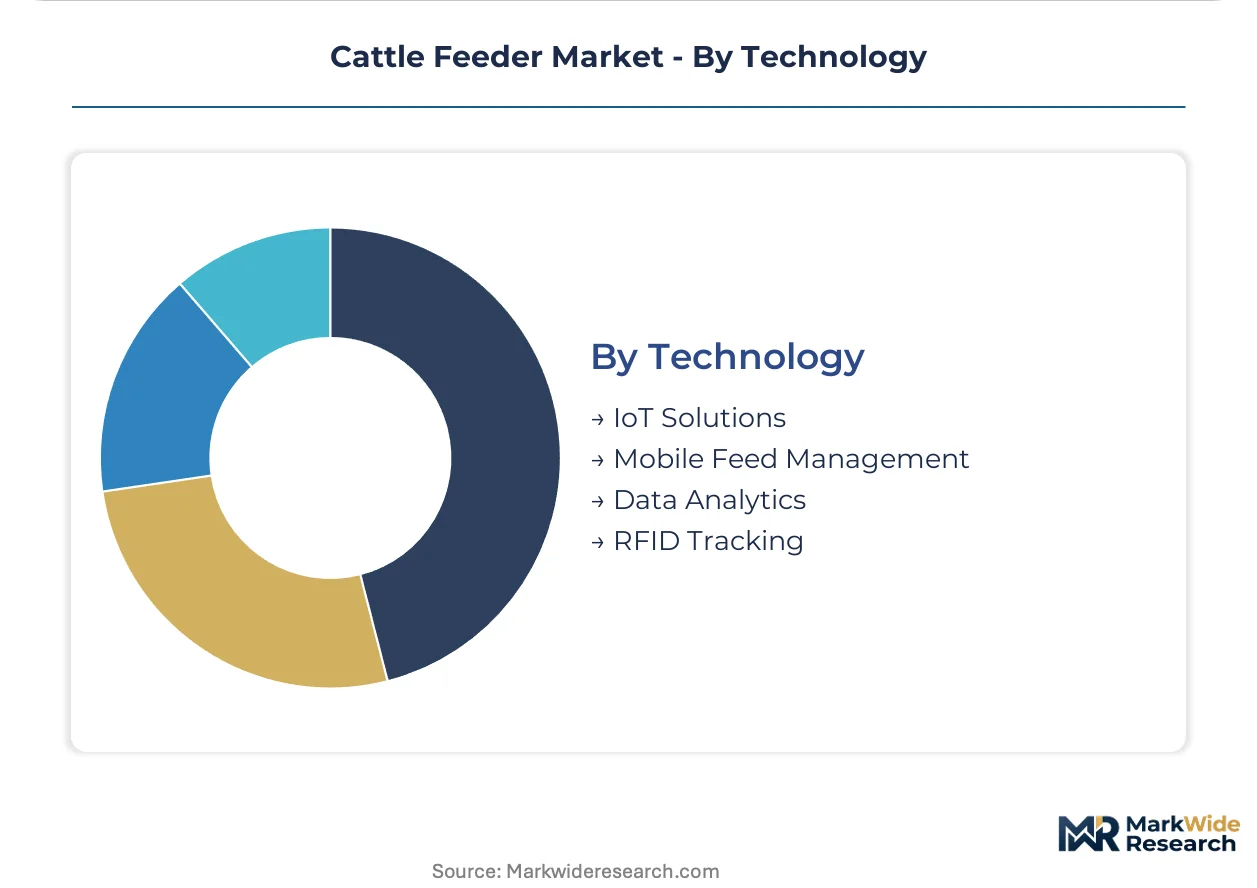
Technology:
Data infrastructure maturity separates early adopters from operations where connectivity gaps limit digital deployment.
- IoT Solutions:Cloud-connected feeders with edge computing capability process intake data locally while syncing herd management records to centralized platforms.
- Data Analytics:Machine learning models predicting feed conversion efficiency and health events require historical datasets that only large integrators have accumulated.
- Mobile Feed Management:Smartphone-based ration adjustment and alarm notification systems extend remote oversight to operations without dedicated office staff.
- RFID Tracking:Ear tag readers at feed bunks enable individual animal intake monitoring for genetic evaluation and early disease detection protocols.
IoT Solutions dominate current installations; Data Analytics is climbing the fastest as training datasets mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States deploys precision-feeding infrastructure at scale unmatched elsewhere, while India relies on manual labor and basic bunk systems that now face cost pressures from urban wage inflation.
United States
EPA Clean Water Act enforcement and USDA NRCS cost-share programs accelerate capital replacement in the Midwest feedlot corridor. Large integrators in Nebraska and Kansas standardize on TMR mixers with real-time dry-matter sensors to satisfy nutrient management mandates. The Texas Panhandle cluster sees buying committees unbundle equipment procurement from nutrition consulting services.
Brazil
Expansion of confinement finishing in Mato Grosso and Goiás drives demand for automated feeding systems as labor availability tightens during harvest seasons. Federal agricultural credit programs through Banco do Brasil reduce financing barriers for cooperatives adopting precision equipment. The São Paulo state dairy belt experiments with IoT-linked dispensers in peri-urban production zones facing land cost pressures.
China
Provincial environmental regulators in Shandong and Hebei impose nutrient runoff controls on feedlots near watersheds serving Beijing-Tianjin-Hebei. The Yangtze River Delta dairy region automates feeding to offset rising rural wages and attract younger workers to large-scale operations. Inner Mongolia's beef finishing sector consolidates around mechanized bunk systems as herding labor becomes scarce.
India
Cooperative dairy federations in Gujarat and Maharashtra trial automated feeding as peri-urban production zones face labor cost inflation. The National Dairy Development Board's equipment financing schemes lower adoption barriers for 200-500 head operations. Karnataka's precision livestock farming pilots integrate ration optimization with methane monitoring for carbon-conscious milk buyers.
Germany
EU Green Deal farm sustainability requirements and national fertilizer regulations push Bavarian dairy cooperatives toward precision nutrient delivery. The Lower Saxony feedlot belt retrofits covered bunk systems to meet tightened water protection zone rules. Baden-Württemberg's mid-scale family farms represent a contested market where financing terms and service coverage determine vendor selection.
Cattle Feeder Market Vendor Landscape
Top-tier vendors anchor the precision-automation segment, while commodity fabricators compete on manufacturing scale and field repairability for price-sensitive ranchers. The supply base splits sharply between sensor-integrated systems commanding premium margins and mechanical bunk feeders where steel price volatility compresses returns. Three archetypes dominate: integrated grain-to-protein platforms, R&D-intensive nutrition specialists, and scale-driven metal fabricators. Competitive moves center on backward integration into feed manufacturing and technology licensing partnerships to bypass traditional dealer networks.
Within the integrated platform tier, Cargill leverages captive grain handling and protein processing infrastructure to control input costs across equipment placement decisions. Nutreco N.V. exemplifies the nutrition-specialist archetype through precision livestock feeding R&D intensity. Farmco anchors the commodity fabrication segment where manufacturing throughput and distributor relationships determine competitive position. These three entities collectively illustrate how vendor strategy diverges between premium precision systems and durable mechanical units.
| Leading Market Players |
|---|
| Cargill |
| Land O'Lakes |
| Nutreco N.V. |
| BASF SE |
| Archer Daniels Midland Company |
| Farmco |
| HE SILOS |
| Bison Industries |
| Ahrens |
| Others |
Supply Flow & Price Mechanics
A sharp performance gap between precision-automated feeders and commodity bunk systems manifests in divergent margin structures and sourcing footprints across the cattle feeder supply base. Premium sensor-integrated systems command value-based pricing anchored to EPA compliance thresholds and labor savings, while mechanical bunk feeders trade on galvanized steel input costs and distributor markups in the Plains states.
Pricing Analysis
Capacity additions in Brazil and India are reshaping price floors for commodity bunk feeders as regional fabricators achieve manufacturing scale. Three-tier pricing structure across premium, standard, and economy levels reflects certification intensity—USDA NRCS cost-share eligibility, ISO 9001 quality systems, and bare mechanical functionality. Cost compression in the economy tier is intensifying because Brazilian cooperatives now self-fabricate basic units under federal credit programs. Ranchers in the cow-calf segment exhibit the highest price sensitivity, while dairy integrators above 1,000 head prioritize total cost of ownership over upfront capital outlay.
Supply Chain Analysis
Single-source vulnerability sits with Chinese galvanized steel mills supplying raw material to mid-tier fabricators across North America and Europe. Component sourcing draws from Germany for precision hydraulics, South Korea for industrial sensors, and domestic US foundries for structural steel. Tariff exposure on Chinese steel inputs threatens margin stability for commodity feeder manufacturers lacking alternative supplier qualification. Distribution runs through agricultural equipment dealer networks in the Midwest feedlot corridor, with direct-to-farm digital channels gaining traction among tech-enabled dairy operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cattle feeder market functions as a regulatory compounder where EPA Clean Water Act enforcement cycles and USDA conservation cost-share windows create predictable replacement demand spikes. Equipment procurement decisions increasingly hinge on documented nutrient management compliance rather than depreciation schedules alone.
For Market Incumbents: Acquire telemetry and remote diagnostics capabilities to defend against specialized IoT vendors bypassing traditional dealer networks. Cargill and Nutreco N.V. should deepen backward integration into sensor module sourcing to reduce dependency on Korean component suppliers. Certification investment in EPA-compliant covered bunk systems represents the critical lever for capturing NRCS cost-share flows. For New Entrants and Emerging Players: Enter via the underpenetrated 200-500 head dairy segment in India and the US Upper Midwest where financing terms and service coverage gaps persist. Gujarat and Maharashtra cooperative federations present the most penetrable geography for automated feeding trials. A hardware-as-a-service model with embedded maintenance contracts offers the strongest go-to-market angle against capital-constrained family operations. For Investors and Strategic Acquirers: Asymmetric upside sits with precision livestock nutrition specialists possessing captive R&D pipelines and existing dairy integrator relationships. Long-term viability over the coming decade favors vendors capable of converging methane monitoring with ration optimization algorithms. Watch for state-level methane accounting rule finalization in California and the EU as the signal for accelerated equipment replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Reduces Korean component dependency for US precision feeder vendors serving EPA-regulated feedlots. |
| Hardware-as-a-Service Launch | Lowers capital barriers for 200-500 head dairy operations in India and the US Upper Midwest. |
| Methane Monitoring Convergence | Positions equipment vendors for carbon-conscious protein buyers in California and EU Green Deal markets. |
| Direct-to-Farm Digital Channel Expansion | Bypasses traditional dealer networks in the Texas Panhandle and western Kansas feedlot clusters. |
| USDA NRCS Certification Investment | Unlocks 75% cost-share coverage eligibility for covered bunk systems in Chesapeake Bay and Mississippi River watersheds. |
Methodological Framework
Direct dialogue with dairy operations managers, feedlot procurement directors, agricultural equipment dealers, and EPA regional compliance officers grounded the qualitative foundation of this analysis. Secondary validation drew from USDA NRCS program documentation, EPA CAFO enforcement records, SEC 10-K filings of listed protein integrators, and customs data on galvanized steel trade flows. Bottom-up and top-down triangulation cross-checked equipment shipment volumes against herd size demographics and replacement cycle assumptions.
Bottom-up modeling aggregated segment-level demand across product type, application, and technology tiers, while top-down approaches validated aggregate market scale against protein production forecasts and feed conversion efficiency trends. Segmentation dimensions included automation level, herd size tier, regulatory exposure zone, and financing mechanism. CAGRs were derived from fitted growth curves incorporating equipment replacement cycles, regulatory milestone timing, and labor cost trajectory assumptions across major producing regions.
Inputs from equipment manufacturers and cooperative dairy federations were available through the study window; gaps in real-time feedlot capital expenditure intentions introduce uncertainty bands around near-term replacement demand timing. Forecasts reflect documented assumptions regarding EPA enforcement intensity and USDA program funding continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
Livestock Dewormers Market
Livestock Management
Cattle Management Software Market
Livestock Management
Europe Ruminant Feed Premix Market
Livestock Management
Animal Identification Market
Livestock Management
Hominy Feed Market
Livestock Management
Wagyu Beef Market
Livestock Management
North America Swine Feed Market
Livestock Management
Poultry Health Market
Livestock Management
Digital Livestock Farming Market
Livestock Management
Africa Alfalfa Hay Market
Livestock Management
Bird Feeder Market
Livestock Management
Feed Management Software Market
Livestock Management
North America Ruminant Feed Market
Livestock Management
Colombia Animal Feed Market
Livestock Management
Morocco Poultry Market
Livestock Management
Global Smart Ear Tags Market