
 Pig Feed Market | 2026-2036
Pig Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Pig Feed Market Analytics
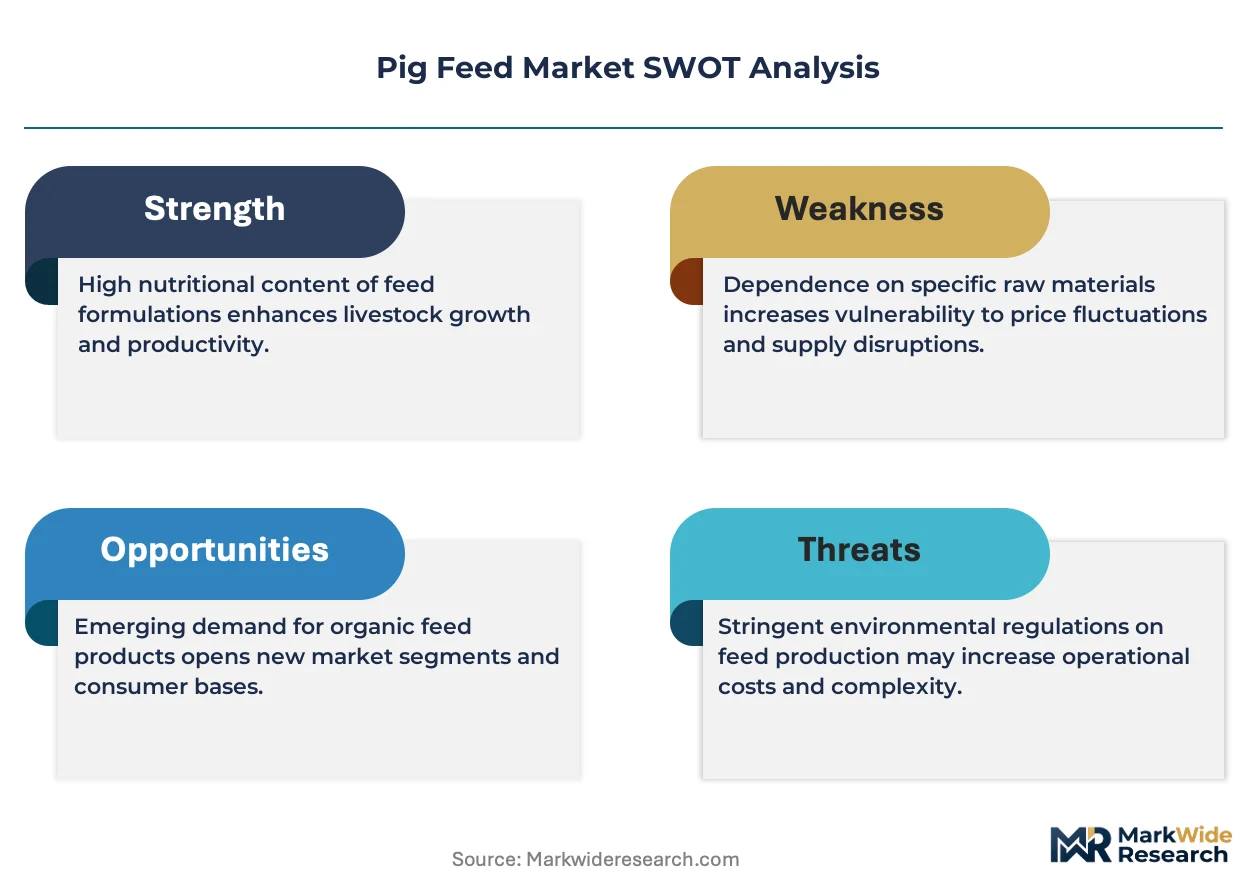
The premium-commodity split in pig feed is rebalancing around amino acid density and antibiotic-free certification. Cargill leverages its North American grain origination network to control input costs for high-margin specialty lines. New Hope Group anchors its position through captive swine operations in Sichuan and Hunan provinces. ForFarmers differentiates via precision nutrition services bundled with grower feed contracts in the Netherlands and Germany.
Pig feed comprises formulated rations combining cereal grains, protein meals, and micronutrients to optimize lean tissue deposition across growth stages, with typical finisher diets containing 16-18% crude protein and 3,200-3,400 kcal/kg metabolizable energy. Starter feed commands the highest per-kilogram margins due to stringent digestibility requirements for weaned piglets, while pelleted forms are displacing mash in automated feeding systems across commercial operations. Additive segments including enzymes and organic acids are expanding fastest as regulatory pressure on antibiotic growth promoters intensifies in major producing regions.
The EU Green Deal's Farm to Fork strategy and China's Ministry of Agriculture and Rural Affairs guidelines on reducing soybean meal inclusion are reshaping formulation standards and import dependency. The USDA and EPA jointly influence US feed manufacturing through grain subsidy programs and concentrated animal feeding operation permitting. Stakeholders must monitor divergence between regional maximum residue limits and carbon accounting frameworks as export market access hinges on dual compliance.
Market Dynamics
China's dual carbon goals and the EU Green Deal's Farm to Fork strategy are compressing formulation timelines and forcing feed mills to requalify ingredient sourcing across multiple regulatory jurisdictions simultaneously.
Growth Catalysts
- Antibiotic-free certification mandates:The EU's ban on zinc oxide as a growth promoter accelerates enzyme and organic acid adoption in weaner diets. Danish and Dutch mills now bundle phytase with acidifiers as standard.
- Vietnam's integrated pork clusters:Mekong Delta operations consolidate procurement through captive feed mills, creating volume commitments that stabilize ingredient hedging for soybean meal and fishmeal suppliers.
- Precision fermentation for amino acids:Microbial lysine and methionine production reduces dependency on soybean imports and enables low-protein formulations compliant with China's Ministry of Agriculture guidelines.
Market Restraints
- Soybean meal price volatility:Argentine drought cycles and US export policy swings transmit directly into finisher diet costs, compressing margins for independent mills without origination assets.
- Phosphorus supply concentration:Moroccan and Chinese phosphate rock dominance creates input risk for calcium-phosphate premixes used in starter feeds across Southeast Asian operations.
- Digestibility ceiling in alternative proteins:Insect meal and single-cell protein sources remain limited by palatability thresholds and amino acid bioavailability in piglet diets.
Strategic Opportunities
- Myanmar's underpenetrated commercial sector:Backyard farming still dominates pork supply; feed mill partnerships with emerging vertically integrated operations in Mandalay and Yangon regions offer first-mover positioning.
- Carbon credit monetization:The EU's Carbon Border Adjustment Mechanism creates premium pathways for feed verified under low-emission protocols, rewarding methane-reducing additives and deforestation-free soy certification.
- Blockchain-enabled ingredient traceability:Converging IoT sensors and distributed ledger systems allow real-time mycotoxin and origin verification, unlocking contract premiums from export-oriented slaughterhouses in Germany and Denmark.
Industry Challenges
- Formulation chemist scarcity:The shift from fixed-formula to dynamic least-cost modeling requires software proficiency and real-time commodity analytics that existing mill technical staff often lack.
- Pellet durability standardization:Automated feeding systems in Netherlands and Germany operations demand uniform pellet hardness, yet regional ingredient variation complicates die specification and cooling protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pig Feed Market |
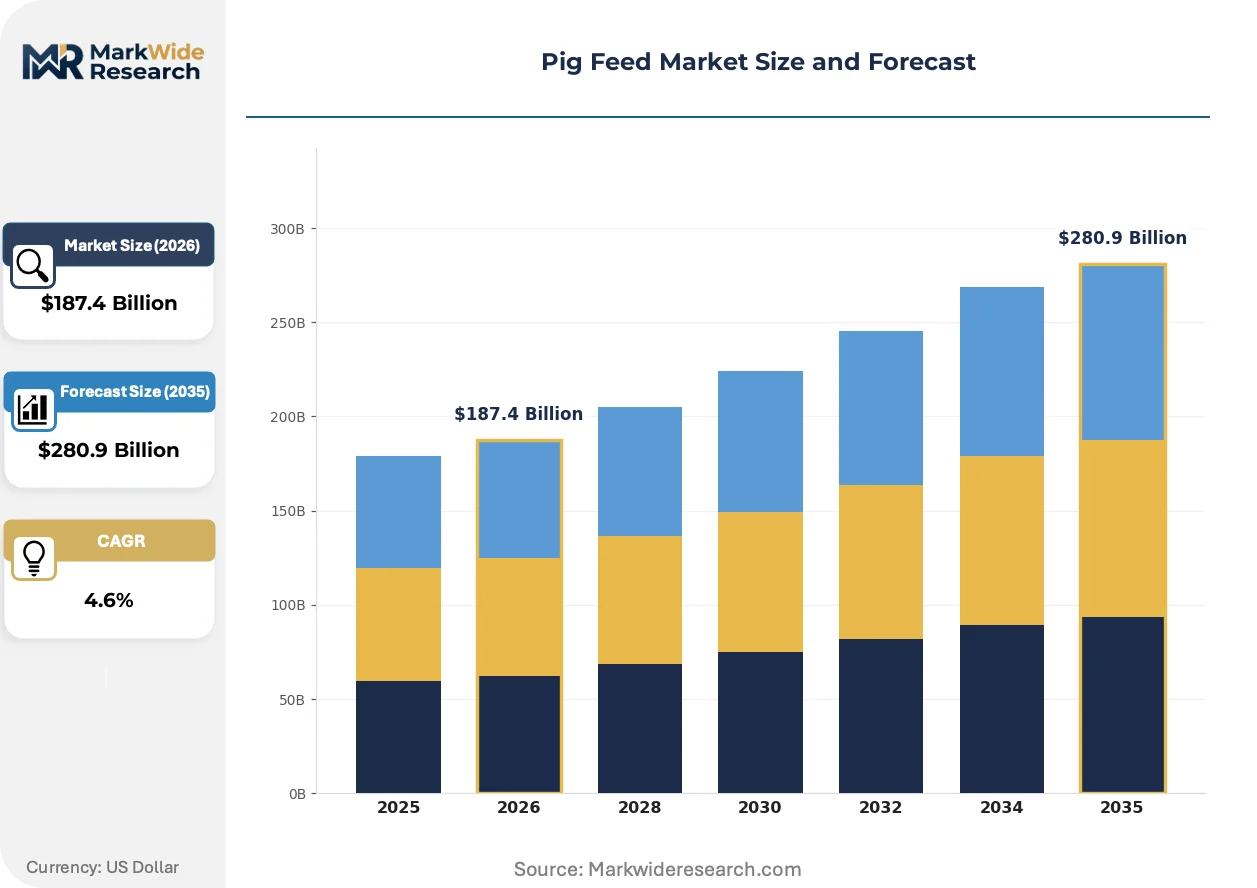
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $280.9 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Starter Feed, Grower Feed, Finisher Feed, Sow Feed Form: Pellets, Crumbles, Mash, Liquid Ingredient Type: Cereal Grains, Protein Meals, Vitamins, Additives Distribution Channel: Online Retail, Feed Stores, Wholesale Distributors, Cooperatives |
| Companies Covered | Twins Group, DBN Group, Cargill, AGRAVIS, ForFarmers, New Hope Group, Zhengbang Group, Wellhope, CP Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pig Feed Market Evolving Landscape
Feed manufacturing is pivoting from commodity blending toward nutritional precision, with digital tools and regulatory compliance frameworks now determining competitive differentiation more than raw material access alone.
Near-infrared spectroscopy paired with cloud-based formulation software is electrifying real-time diet adjustment in commercial operations. Large-scale farms in Denmark and Spain deploy inline NIR sensors to recalibrate amino acid density every four hours. This compression of formulation cycles is reducing feed conversion ratio variance and shrinking the performance gap between genetic potential and realized growth rates.
The EU's Corporate Sustainability Reporting Directive now mandates scope 3 emissions disclosure for imported feed ingredients. German and French pork producers pressure their mills to document deforestation-free soy and reduced-nitrogen excretion protocols. Southeast Asian exporters to European markets must build dual compliance systems that satisfy both EU Green Deal requirements and domestic environmental regulations.
Contract structures are fragmenting as slaughterhouses unbundle feed procurement from live animal purchasing. Polish and Romanian integrators now negotiate separate agreements for grower versus finisher phases, forcing mills to price risk at sub-batch granularity. This disintermediation of traditional supply relationships is most pronounced in regions where banking access allows farms to carry ingredient inventory directly.
Pig Feed Market Segmentation
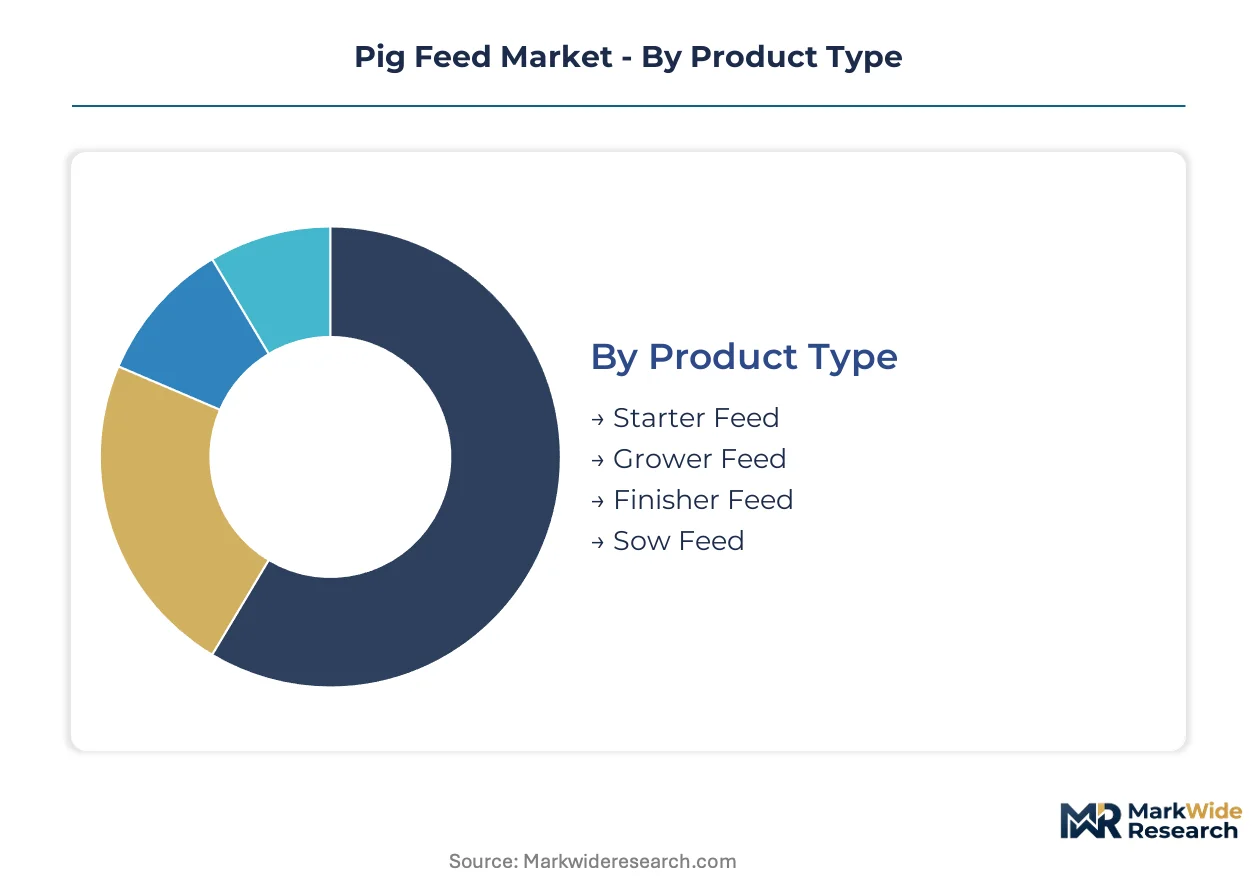
Feed segmentation in commercial pork production tracks nutritional density requirements across growth stages while capturing automation compatibility and regulatory compliance pathways. Formulation chemistry and distribution logistics now determine margin capture more than raw material procurement alone.
Product Type:
Formulation specifications diverge sharply across physiological stages, with digestibility coefficients and amino acid density setting technical boundaries for each category.
- Starter Feed:High-density formulations containing 20-22% crude protein and specialized enzyme blends support gut development in piglets from weaning through 15kg bodyweight. Demand concentrates in Denmark and the Netherlands where antibiotic-free mandates have intensified acidifier and probiotic inclusion rates. Dutch mills now bundle phytase with organic acid complexes as standard to meet EFSA digestibility thresholds.
- Grower Feed:Intermediate protein levels of 18-20% optimize lean tissue deposition between 15-50kg liveweight, with metabolizable energy targeting 3,200-3,400 kcal/kg. Vietnam's Mekong Delta integrated operations consolidate procurement through captive feed mills, creating volume commitments that stabilize soybean meal hedging for suppliers.
- Finisher Feed:Cost-optimized rations at 16-18% protein maximize feed conversion efficiency in final growth phases. Chinese mills under Ministry of Agriculture guidelines are reducing soybean meal inclusion through precision-fermented amino acid supplementation.
- Sow Feed:Reproductive-stage formulations adjust energy density for gestation versus lactation cycles. German operations emphasize body condition scoring integration with dynamic feeding systems.
Finisher feed leads on scale; starter feed leads on momentum.
Form:
Physical processing determines compatibility with automated feeding infrastructure and influences nutrient bioavailability through thermal treatment.
- Pellets:Steam-conditioned and die-pressed forms deliver uniform hardness critical for pneumatic distribution systems. Netherlands and Germany operations mandate pellet durability indices above 95% to prevent fines accumulation in automated lines.
- Crumbles:Broken pellet fragments bridge particle size preferences for younger animals while retaining thermal processing benefits. Spanish farms deploy crumbles in transition diets between starter and grower phases.
- Mash:Unprocessed meal forms persist in small-scale operations and manual feeding systems across Myanmar's backyard farming sector. Cost savings from eliminated pelleting energy offset higher feed conversion ratios.
- Liquid:Fermented slurry formulations enable wet-feeding systems with precise nutrient delivery. Danish integrators leverage liquid systems for antibiotic-free production lines requiring exact additive dosing.
Pellets dominate volume share; liquid forms are climbing the fastest on automation penetration.
Ingredient Type:
Raw material classification tracks nutritional function and regulatory scrutiny intensity across supply chains.
- Cereal Grains:Corn and wheat provide metabolizable energy foundations, with origin networks determining cost volatility exposure. Cargill's North American origination assets buffer margin compression for high-volume mills.
- Protein Meals:Soybean meal, rapeseed meal, and fishmeal supply essential amino acids with varying digestibility profiles. Argentine drought cycles transmit directly into finisher diet cost structures for mills without origination hedging.
- Vitamins:Fat- and water-soluble micronutrient premixes prevent deficiency syndromes in intensive production systems. Chinese premix manufacturers face requalification under dual carbon goals and reduced-antibiotic formulation standards.
- Additives:Enzymes, organic acids, and methane-reducing compounds represent the steepest expansion trajectory as regulatory pressure on antibiotic growth promoters intensifies. EU Green Deal Farm to Fork strategy accelerates phytase and xylanase adoption.
Cereal grains anchor volume; additives gain share fastest on regulatory displacement.
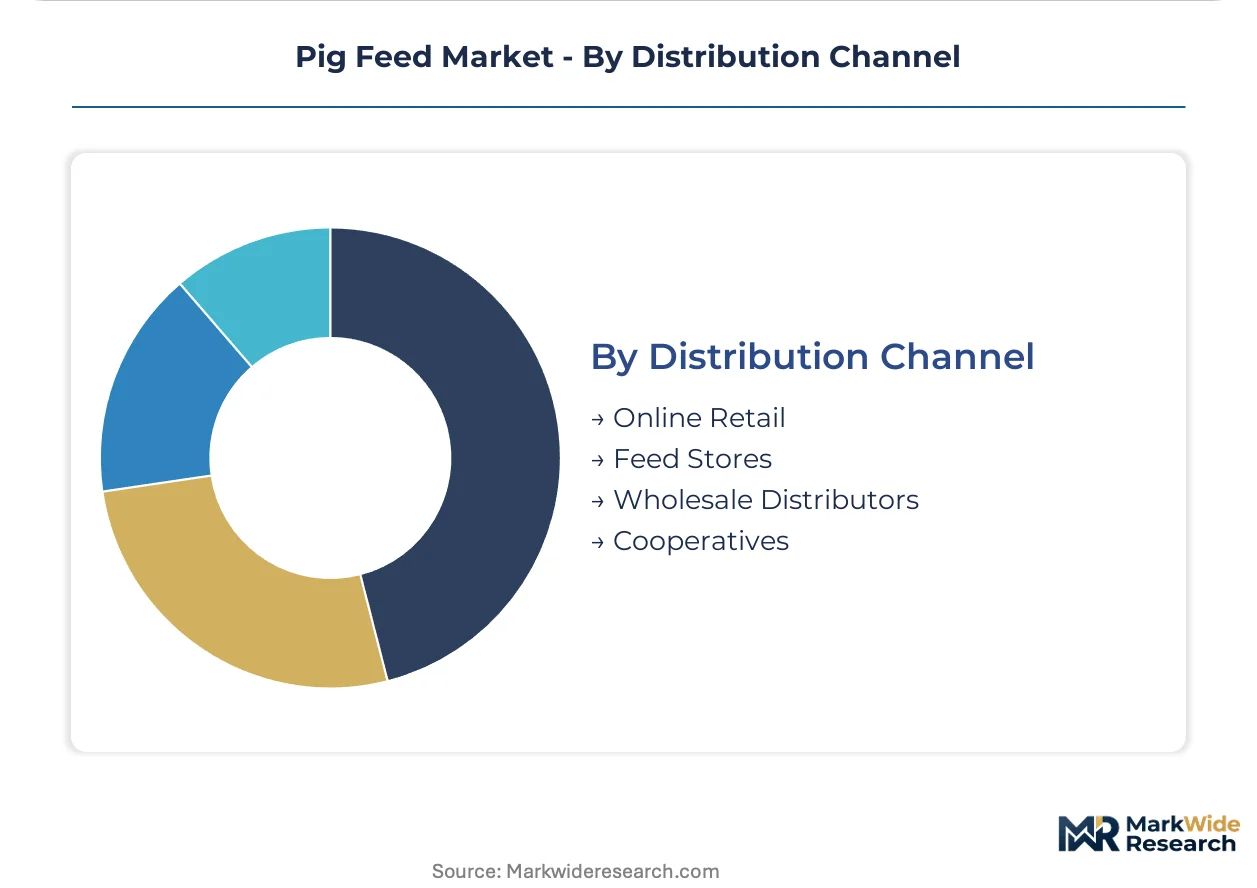
Distribution Channel:
Channel structure reflects farm scale consolidation and banking access that enables direct procurement versus intermediary dependence.
- Online Retail:Digital platforms with formulation calculators and delivery scheduling penetrate small-to-mid scale operations. Polish integrators unbundle feed procurement through separate grower and finisher phase contracts negotiated via proprietary portals.
- Feed Stores:Physical retail networks with technical consultation services dominate hobby farming and semi-commercial segments. Romanian backyard producers rely on store-based credit arrangements.
- Wholesale Distributors:Volume aggregators with logistics infrastructure serve independent mills lacking direct origination assets. Southeast Asian distributors buffer soybean meal price volatility through forward contracting.
- Cooperatives:Member-owned procurement bodies consolidate negotiating power for medium-scale farms. German and French pork producer cooperatives now mandate deforestation-free soy documentation under CSRD scope 3 disclosure requirements.
Wholesale distributors lead on scale; online retail leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation chemists and procurement specialists concentrate in Denmark, the Netherlands, and China's Sichuan basin, anchoring technical capability clusters that shape regional feed quality standards.
China
Dual carbon goals from the Ministry of Agriculture and Rural Affairs compress formulation timelines for low-protein diets. New Hope Group and Zhengbang Group anchor captive feed mill networks across Sichuan and Hunan provinces, integrating precision-fermented amino acids to reduce soybean meal dependency.
Vietnam
Mekong Delta integrated pork clusters consolidate procurement through captive mills, creating volume commitments that stabilize ingredient hedging. The Ministry of Agriculture and Rural Development enforces antibiotic residue limits that accelerate enzyme adoption in weaner diets. CP Group operates vertical feed-to-slaughter facilities in Can Tho and Dong Nai provinces.
Germany
The EU Green Deal's Farm to Fork strategy mandates scope 3 emissions disclosure for imported feed ingredients. EFSA digestibility thresholds intensify acidifier and probiotic inclusion rates. North Rhine-Westphalia and Lower Saxony host automated feeding system deployments requiring pellet durability indices above 95%.
Denmark
Antibiotic-free certification mandates from the Danish Veterinary and Food Administration accelerate phytase and organic acid bundling as standard practice. Precision nutrition services integrate with grower feed contracts across Jutland peninsula operations. Liquid feeding systems enable exact additive dosing for antibiotic-free production lines.
Netherlands
ForFarmers bundles precision nutrition services with automated feeding infrastructure in Gelderland and North Brabant provinces. The EU's Corporate Sustainability Reporting Directive pressures mills to document deforestation-free soy certification. Inline NIR sensors recalibrate amino acid density every four hours in large-scale operations.
Pig Feed Market Competitive Landscape
Capital-heavy grain origination networks compete with asset-light formulation specialists for margin capture in pig feed manufacturing. The vendor base stratifies across three tiers: integrated agribusiness conglomerates with captive protein operations, regional mill networks serving concentrated geographic clusters, and precision nutrition service providers bundling software with physical delivery. Consolidation pressure intensifies as slaughterhouses unbundle feed procurement from live animal purchasing, forcing mills to price risk at sub-batch granularity. Dominant competitive moves include backward integration into amino acid fermentation capacity and geographic expansion through mill acquisitions in underpenetrated Southeast Asian markets.
Among Chinese integrated agribusinesses, New Hope Group and Zhengbang Group exemplify the conglomerate archetype combining captive swine operations with feed manufacturing assets. Cargill represents the North American origination-heavy model, leveraging grain procurement networks to buffer margin compression. ForFarmers occupies a position within the European precision nutrition tier, bundling formulation software with automated feeding system compatibility. These three anchors illustrate divergent strategic responses to regulatory compression on antibiotic growth promoters and carbon disclosure mandates.
| Leading Market Players |
|---|
| Twins Group |
| DBN Group |
| Cargill |
| AGRAVIS |
| ForFarmers |
| New Hope Group |
| Zhengbang Group |
| Wellhope |
| CP Group |
| Others |
Value Network & Pricing Analysis
The EU Green Deal's Farm to Fork strategy gates qualified supply and premium-tier pricing access by mandating deforestation-free soy certification and scope 3 emissions disclosure for imported feed ingredients. Mills lacking verified low-carbon protocols face exclusion from German and Danish slaughterhouse contracts, compressing margins in standard-tier segments while rewarding compliant suppliers with contract premiums.
Pricing Analysis
The bundled-vs-unbundled service split separates precision nutrition packages from commodity feed transactions. Three-tier pricing structure across premium, standard, and economy levels tracks antibiotic-free certification, amino acid density, and automation compatibility. Cost compression in economy-tier mash feeds is intensifying because Argentine drought cycles transmit directly into finisher diet costs. Independent backyard producers in Myanmar exhibit highest price sensitivity; integrated Mekong Delta operations with captive mills demonstrate lowest sensitivity due to volume hedging.
Supply Chain Analysis
Logistics and freight costs anchor margin structures for soybean meal shipments from Argentina and the United States into Southeast Asian mill networks. Supply concentrates in China, Vietnam, and the Netherlands, with formulation chemist clusters in Denmark and Germany. Raw material dependencies center on Moroccan phosphate rock, Brazilian deforestation-free soy, and precision-fermented amino acids from Sichuan basin bioreactors. Single-source vulnerability in phosphate premixes for starter feeds creates input risk. Distribution runs through wholesale distributors with forward contracting capability, though online retail portals are gaining momentum among Polish and Romanian integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where antibiotic-free certification mandates from the EU and China's dual carbon goals continuously intensify formulation complexity and compliance investment requirements.
For Market Incumbents: To counter margin compression from unbundled procurement contracts, deepen backward integration into precision-fermented amino acid capacity in Sichuan and Hunan provinces. Acquire underpenetrated mill assets in Myanmar's Mandalay and Yangon regions to secure first-mover positioning before vertical consolidation accelerates.
For New Entrants and Emerging Players: Begin with liquid feeding system specialization for antibiotic-free production lines in Denmark and the Netherlands, where EFSA digestibility thresholds create technical barriers for established mash-feed incumbents. Target carbon credit monetization pathways under the EU Carbon Border Adjustment Mechanism as the most penetrable premium segment.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional mill networks serving concentrated geographic clusters without origination assets or formulation software capabilities. The long-term viability window favors precision nutrition service providers bundling NIR-enabled real-time diet adjustment with automated feeding infrastructure. Watch for divergence between regional maximum residue limits and carbon accounting frameworks as the inflection signal determining export market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amino Acid Fermentation | Reduces soybean meal dependency under China's Ministry of Agriculture low-protein guidelines. |
| Blockchain-Enabled Ingredient Traceability | Unlocks contract premiums from German and Danish export-oriented slaughterhouses. |
| Precision Nutrition Service Bundling | ForFarmers leverages inline NIR sensors to compress formulation cycles every four hours. |
| Geographic Expansion in Underpenetrated Markets | Myanmar's backyard farming sector offers first-mover positioning for commercial mill partnerships. |
| Carbon Credit Monetization Certification | EU Carbon Border Adjustment Mechanism rewards methane-reducing additives and deforestation-free soy. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with feed mill technical directors, procurement leads at integrated pork operations, formulation chemists, and regulatory affairs specialists at ministries of agriculture with secondary validation. Sources included customs and trade data on soybean meal and fishmeal flows, SEC filings from listed agribusiness conglomerates, EU Green Deal implementation guidance, and China's Ministry of Agriculture rural development bulletins. Bottom-up volume modeling across growth stage segments and ingredient categories triangulated against top-down macroeconomic projections.
Historical reference periods anchored the projection horizon through trend extrapolation and driver elasticity modeling. Segmentation dimensions covered product type, physical form, ingredient classification, and distribution channel, with regional regulatory clusters as an overlay dimension. CAGRs derived from weighted average growth contributions across starter, grower, finisher, and sow feed categories, incorporating precision fermentation adoption curves and antibiotic-free certification penetration rates as industry-specific forecast inputs.
Caveats apply where Argentine drought cycles, phosphate supply disruptions, or divergence between EU and Chinese maximum residue limits could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
Roughage Feed Market
Livestock Management
Poultry Feed Market
Livestock Management
Animal Identification Market
Livestock Management
Africa Ruminant Feed Premix Market
Livestock Management
Beef Cattle Feed and Additives Market
Livestock Management
Cattle Management Software Market
Livestock Management
Livestock Dewormers Market
Livestock Management
North America Ruminant Feed Market
Livestock Management
Smart Feeding Systems Market
Livestock Management
Africa Alfalfa Hay Market
Livestock Management
Europe Swine Feed Market
Livestock Management
Dairy Herd Management Market
Livestock Management
Poultry Health Market
Livestock Management
Cattle Squeeze Market
Livestock Management
Europe Ruminant Feed Premix Market
Livestock Management
Global Smart Ear Tags Market