
 Cattle Squeeze Market | 2026-2036
Cattle Squeeze Market Size, Share, and Industry Trends Forecast 2026-2036
Cattle Squeeze Market Outlook
Aftermarket service revenue is rewriting profit structures across the cattle squeeze industry. Priefert leverages its manufacturing scale to dominate replacement part fulfillment across the southern United States. Arrowquip differentiates through veterinary-specific configurations that anchor its position in clinic and research installations.
A cattle squeeze is a restraining apparatus engineered from galvanized steel tubing with hydraulic or manual headgates, designed to immobilize individual animals for veterinary treatment, tagging, or loading. Standard units accommodate cattle from 400 to 2,000 pounds with squeeze pressure adjustable between 150 and 600 psi to prevent injury while ensuring handler safety. Hydraulic product types command premium positioning in large-scale beef operations where throughput velocity determines facility economics. Dairy farm applications represent the fastest-expanding segment as robotic milking integration demands synchronized handling infrastructure.
The USDA Animal and Plant Health Inspection Service enforces handling facility standards under the Humane Methods of Slaughter Act, directly shaping equipment design requirements for federally inspected plants. OSHA workplace safety guidelines for agricultural operations mandate squeeze chute guarding and operator training, creating compliance-driven replacement cycles among commercial buyers. Stakeholders must monitor evolving state-level livestock welfare legislation and assess how pending hydraulic fluid environmental regulations could accelerate electric system development.
Market Dynamics
Hydraulic automation systems are compressing replacement cycles across commercial feedlots as throughput economics override capital preservation instincts. Beef processors now treat squeeze chute reliability as a direct input to daily slaughter capacity planning.
Growth Catalysts
- USDA Humane Methods of Slaughter Act:Federally inspected plants must maintain specific restraining equipment standards, forcing systematic upgrades at packing facilities.
- Robotic milking synchronization:Dairy operations integrating automated parlor systems require compatible handling infrastructure to maintain animal flow efficiency.
- Texas-Oklahoma-Kansas corridor concentration:Feedlot density in this region creates localized demand clusters that justify specialized service infrastructure investments.
Market Restraints
- Steel price volatility:Galvanized tubing constitutes the primary raw material input, with commodity swings directly pressuring manufacturer margins.
- Hydraulic fluid environmental compliance:Pending EPA regulations on petroleum-based hydraulic fluids threaten to accelerate R&D costs for alternative power systems.
- Manual system longevity:Existing manual squeeze chutes in smaller operations deliver 15-20 year service lives, delaying replacement demand.
Strategic Opportunities
- Dairy farm automation convergence:Integration of RFID health monitoring with squeeze chute controls creates premium positioning for synchronized system vendors.
- Electric actuator development:Battery-powered hydraulic alternatives eliminate fluid contamination risks while opening indoor facility applications.
- Aftermarket service unbundling:Predictive maintenance contracts based on usage telemetry generate recurring revenue independent of equipment sales cycles.
Industry Challenges
- Veterinary equipment certification timelines:ISO 10993 biocompatibility testing for contact surfaces extends product development cycles by 8-14 months.
- Legacy facility retrofit complexity:Existing concrete chute installations constrain hydraulic system integration without complete infrastructure reconstruction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cattle Squeeze Market |
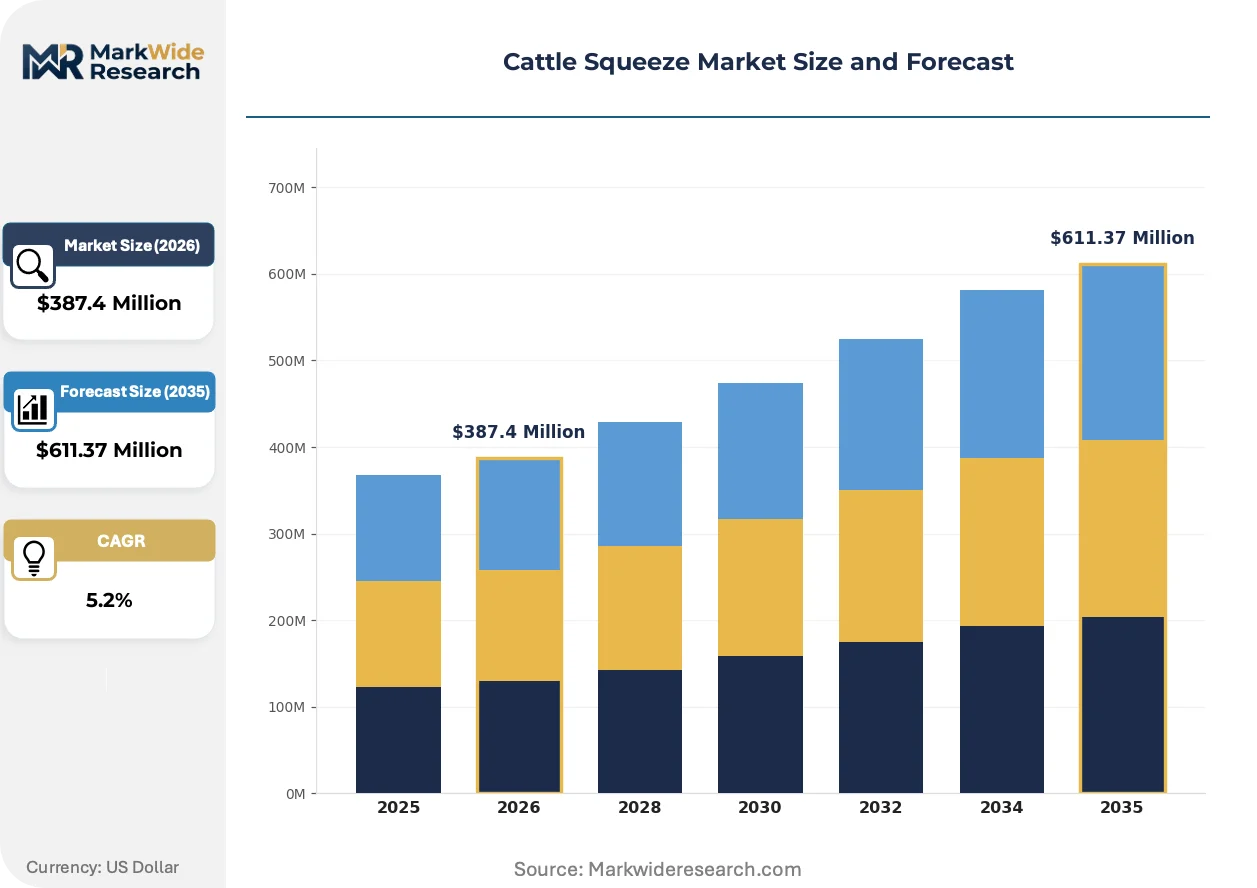
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $611.37 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic, Pneumatic, Manual, Electric Application: Dairy Farms, Beef Farms, Veterinary Clinics, Agricultural Shows End User: Farmers, Livestock Handlers, Veterinarians, Agricultural Suppliers Distribution Channel: Direct Sales, Online Retail, Distributors, Agricultural Fairs |
| Companies Covered | Priefert, Arrowquip, Herd Boss, Bale Baron, Ritchie, Tarter Farm and Ranch Equipment, Miller Manufacturing, Agromaster, Powder River, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cattle Squeeze Market Strategic Shifts
Sensor-enabled restraint systems are redefining handler-animal interaction protocols. Real-time pressure monitoring and automated release mechanisms are shifting equipment specifications from mechanical durability toward data integration capabilities.
Load cell integration within squeeze side panels enables precise pressure feedback to operators, preventing injury while maintaining immobilization effectiveness. Large-scale feedlot operators in Nebraska and Colorado are adopting these systems at replacement cycles compressed to 7-9 years. Traditional manual pressure adjustment based on visual animal cues is rendering obsolete as liability-conscious facilities mandate documented restraint protocols.
OSHA agricultural workplace safety guidelines are mandating operator guarding and emergency stop accessibility on all new installations. Equipment manufacturers must now engineer integrated safety cages and dual-control systems into standard configurations. Commercial beef packing plants face the steepest compliance costs, driving consolidation toward turnkey system providers who bundle training certification with equipment delivery.
Buying committees at integrated protein companies are unbundling equipment procurement from aftermarket service agreements. Traditional dealer networks that bundled installation, parts, and maintenance face disintermediation as direct manufacturer relationships capture multi-site contract value. This pattern concentrates most visibly across JBS and Tyson Foods facility networks, where centralized procurement functions negotiate enterprise pricing independent of local dealer territories.
Cattle Squeeze Market Segmentation
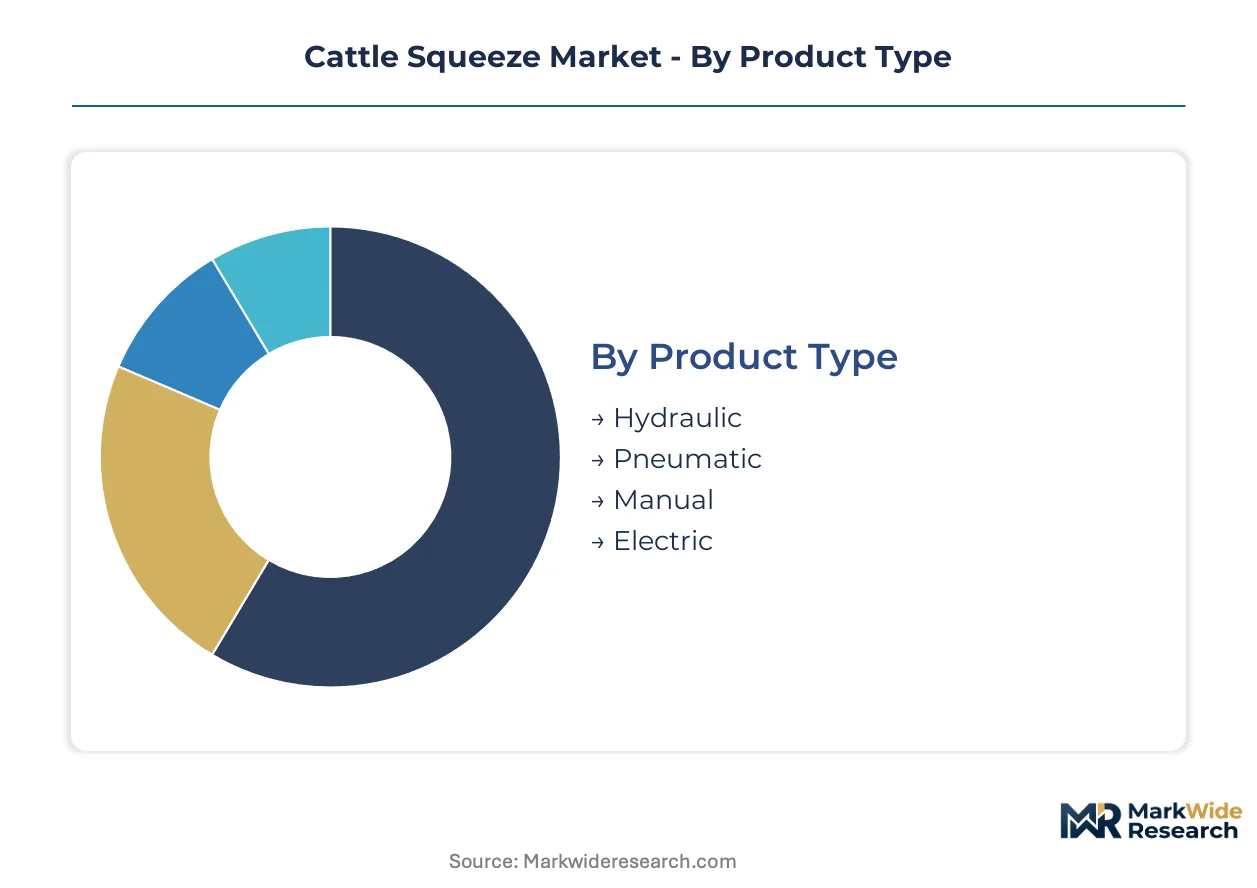
Segmentation in cattle squeeze equipment reveals divergent technology adoption curves across operational scales. Buyer priorities split between throughput velocity in commercial feedlots and capital efficiency in smaller holdings. Understanding these divides enables targeted product positioning and service model design.
Product Type:
Use-case spectrum spans from high-volume continuous operation to intermittent small-batch handling.
- Hydraulic:High-pressure fluid power systems deliver 150-600 psi squeeze force with programmable cycle times. Demand concentrates in Texas-Oklahoma-Kansas feedlot corridors where daily throughput exceeds 500 head and labor costs justify automation capital. Beef processors treat hydraulic reliability as direct input to slaughter capacity planning.
- Manual:Mechanical leverage systems using hand-operated rachet mechanisms require no external power. Demand persists in Missouri and Iowa cow-calf operations with herd sizes under 200 head where capital preservation overrides throughput concerns. Fifteen-to-twenty year service lives delay replacement cycles.
- Pneumatic:Compressed air systems suit indoor dairy parlors where hydraulic fluid contamination risks are prohibited. Wisconsin and Idaho operations with robotic milking integration favor these for synchronized animal flow.
- Electric:Battery-powered actuator systems eliminate fluid handling while enabling precise digital pressure control. Nebraska feedlots pilot these for EPA compliance anticipation.
Established volume favors hydraulic systems; emerging adoption favors electric configurations.
Application:
Operational context dictates equipment specification intensity and replacement frequency.
- Beef Farms:Commercial feedlot applications demand heavy-gauge galvanized construction with load cell integration for documented restraint protocols. Colorado and Kansas operations compress replacement cycles to 7-9 years as OSHA compliance mandates escalate.
- Dairy Farms:Robotic milking synchronization requirements are expanding fastest here. RFID health monitoring integration with squeeze chute controls creates premium positioning for synchronized system vendors in California and Wisconsin.
- Veterinary Clinics:Precision restraint for examination and minor procedures requires veterinary-specific configurations with biocompatible contact surfaces. ISO 10993 certification extends procurement timelines.
- Agricultural Shows:Portable lightweight units prioritize rapid setup and handler visibility over durability. Seasonal demand patterns concentrate in Texas and Oklahoma exhibition circuits.
Beef farms anchor current revenue; dairy farms are climbing the fastest.
End User:
Buyer sophistication and procurement authority vary sharply across user categories.
- Farmers:Owner-operators in the Texas Panhandle and western Kansas prioritize total cost of ownership and local service availability. Buying decisions integrate with facility expansion timelines.
- Veterinarians:Clinic and research installations demand precision control and documented protocols for liability protection. Procurement emphasizes certification and training bundling.
- Livestock Handlers:Contract labor operations prioritize equipment portability across multiple client sites. Rental and lease models gain traction.
- Agricultural Suppliers:Dealer networks in the southern United States face disintermediation as direct manufacturer relationships capture multi-site contract value.
Farmer volume dominates installed base; veterinarian specifications drive premium tier development.
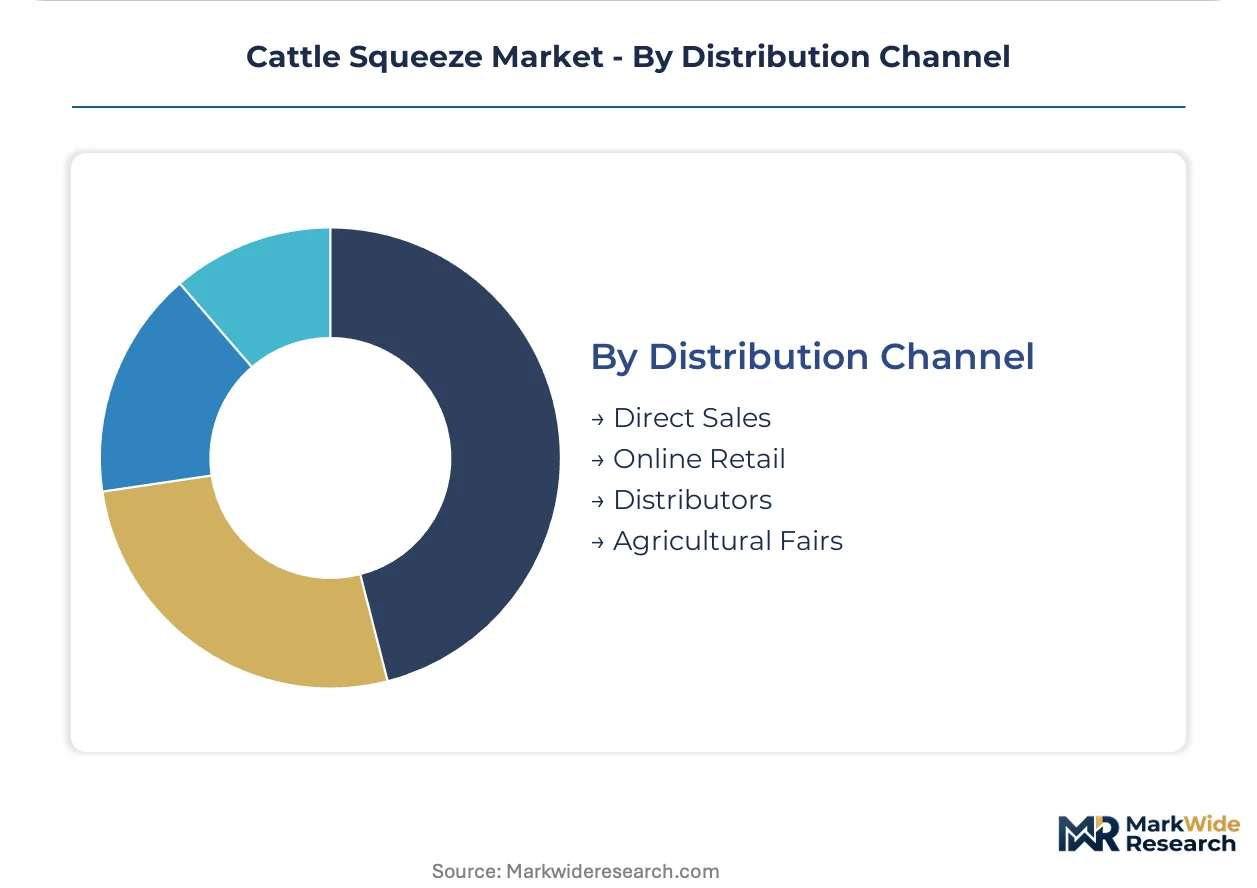
Distribution Channel:
Channel economics reflect buyer scale and service complexity requirements.
- Direct Sales:Manufacturer relationships with JBS and Tyson Foods centralized procurement functions bypass traditional dealer territories. Enterprise pricing negotiations cover multi-site installations.
- Distributors:Regional networks provide installation, parts, and maintenance bundling for mid-scale operations. Priefert leverages manufacturing scale to dominate replacement part fulfillment.
- Online Retail:Standardized manual units and replacement components suit smaller holders with straightforward specifications. Price transparency pressures margin.
- Agricultural Fairs:Demonstration and immediate purchase opportunities concentrate seasonal demand. Texas and Oklahoma exhibition circuits anchor manufacturer presence.
Distributor relationships defend current position; direct sales are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Large-scale feedlot operators in the Texas-Oklahoma-Kansas corridor absorb premium hydraulic systems as throughput economics justify capital intensity. Smaller cow-calf holdings in Missouri and Iowa preserve manual equipment through 15-20 year service cycles.
United States
Commercial beef feedlots drive hydraulic automation demand across the Texas Panhandle and western Kansas. USDA Animal and Plant Health Inspection Service enforces Humane Methods of Slaughter Act standards at federally inspected plants. The Texas-Oklahoma-Kansas corridor concentrates feedlot density, justifying specialized service infrastructure investments from major manufacturers.
Canada
Prairie province cattle operations prioritize cold-weather hydraulic reliability in Alberta and Saskatchewan facilities. Health Canada veterinary equipment guidelines shape biocompatibility requirements for contact surfaces. Calgary and Edmonton serve as distribution nodes for replacement part fulfillment across western Canadian beef operations.
Brazil
Integrated protein companies in Mato Grosso and São Paulo states adopt automated handling for export-compliant facilities. ANVISA veterinary equipment regulations govern certification timelines for clinic-grade installations. The Pantanal region's extensive ranching operations sustain manual system demand where capital constraints predominate.
Australia
Queensland and New South Wales feedlots integrate RFID health monitoring with squeeze chute controls for export traceability. The country's national agricultural safety regulator mandates operator guarding standards aligned with OSHA-equivalent protocols. Roma and Dalby processing clusters anchor hydraulic system adoption in the Maranoa region.
Argentina
Pampas region beef exporters modernize handling infrastructure to meet EU market access requirements. The country's national livestock service enforces welfare standards at export-oriented facilities. Buenos Aires province feedlots concentrate premium equipment demand while Patagonian operations retain legacy manual systems.
Cattle Squeeze Market Competitive Environment
Scale-driven manufacturers and veterinary-specialist fabricators split the market into divergent competitive spheres. Consolidation pressure concentrates among turnkey system providers bundling installation with training certification. Three archetypes dominate: southern US manufacturing-scale players, precision-focused veterinary equipment specialists, and regional fabrication shops serving price-sensitive holdings. Competitive moves center on aftermarket service unbundling and direct manufacturer relationships bypassing traditional dealer networks.
Among North American manufacturers, Priefert exemplifies manufacturing-scale archetypes leveraging replacement part logistics dominance. Arrowquip occupies a position within veterinary-specialist tier, anchoring clinic and research installation specifications. Tarter Farm and Ranch Equipment represents regional fabrication capacity serving mid-scale agricultural operations with standardized manual configurations.
| Leading Market Players |
|---|
| Priefert |
| Arrowquip |
| Herd Boss |
| Bale Baron |
| Ritchie |
| Tarter Farm and Ranch Equipment |
| Miller Manufacturing |
| Agromaster |
| Powder River |
| Others |
Value Chain & Pricing Dynamics
Chinese galvanized steel tubing concentration anchors cost structures for North American manufacturers, funneling margin capture toward aftermarket service tiers where replacement part logistics and predictive maintenance contracts generate recurring revenue independent of equipment sales cycles.
Pricing Analysis
Aftermarket service revenue streams drive lifetime value capture across the cattle squeeze industry. Three-tier pricing structure across premium hydraulic, standard pneumatic, and economy manual levels segments buyers by operational scale and throughput requirements. Pricing pressure stems from steel commodity volatility pressuring manufacturer margins on new equipment sales. Small cow-calf operations in Missouri and Iowa exhibit highest price sensitivity, preserving manual systems through extended service cycles, while commercial feedlots in Texas and Kansas absorb premium positioning for throughput velocity.
Supply Chain Analysis
Contract manufacturing for hydraulic power units concentrates among specialized industrial fluid power producers in the United States and Germany. Raw material flows draw from Chinese galvanized steel tubing, domestic steel forging for headgate mechanisms, and Canadian hydraulic component suppliers. Single-source vulnerability in specialized hydraulic valve assemblies creates bottleneck exposure for premium system manufacturers. Distribution runs through manufacturer-direct relationships with integrated protein companies alongside regional dealer networks providing installation and service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized veterinary equipment certification capabilities represent the scarcest asset in this market, with ISO 10993 biocompatibility testing expertise and hydraulic-electric hybrid engineering talent concentrated among a handful of incumbent manufacturers.
For Market Incumbents: Insulate market position by deepening backward integration into hydraulic power unit manufacturing to reduce single-source valve assembly exposure, while accelerating electric actuator R&D to preempt EPA petroleum-based hydraulic fluid restrictions. Capture multi-site contract value through direct manufacturer relationships that bypass traditional dealer territories serving JBS and Tyson Foods networks. For New Entrants and Emerging Players: Dairy farm robotic milking synchronization in California and Wisconsin represents the most penetrable entry point, where RFID health monitoring integration with squeeze chute controls creates premium positioning for synchronized system vendors. Battery-powered electric configurations for indoor parlors offer a regulatory-compliant wedge. Target veterinary clinic installations with precision control specifications and documented protocol bundling to anchor premium tier development. For Investors and Strategic Acquirers: Capital is best deployed toward turnkey system providers bundling installation with training certification, as OSHA compliance mandates escalate replacement cycles and consolidate procurement toward enterprise-ready vendors. Long-term viability hinges on aftermarket service unbundling capabilities and predictive maintenance contract infrastructure. Watch for state-level livestock welfare legislation acceleration as the inflection signal indicating compliance-driven replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Actuator Development | Battery-powered systems eliminate EPA petroleum-based hydraulic fluid compliance risks while opening indoor dairy facility applications. |
| Predictive Maintenance Contracts | Usage telemetry generates recurring revenue independent of equipment sales cycles across Texas-Oklahoma-Kansas feedlot corridors. |
| Veterinary Certification Investment | ISO 10993 biocompatibility testing capability extends product development timelines but anchors clinic and research installation specifications. |
| Direct Manufacturer Relationships | Centralized procurement at JBS and Tyson Foods captures multi-site contract value bypassing traditional dealer territories. |
| RFID Health Monitoring Integration | Synchronized animal flow systems with squeeze chute controls create premium positioning in California and Wisconsin dairy automation. |
Study Parameters
Cross-validation between primary interviews with feedlot operations managers, veterinary clinic procurement leads, hydraulic systems engineers, and aftermarket service directors and secondary validation through USDA Animal and Plant Health Inspection Service facility inspection records, OSHA agricultural workplace safety guideline documents, and SEC filings from integrated protein companies anchors the qualitative findings. Bottom-up equipment shipment data from regional dealer networks triangulates against top-down demand modeling from cattle inventory and feedlot capacity databases.
Calibration against historical replacement cycle patterns and documented compliance-driven upgrade timelines shapes the analytical framework across the analysis window. Segmentation dimensions span product type, application context, operational scale, and geographic feedlot density cluster. CAGRs derive from equipment shipment trajectories, cattle inventory projections, and regulatory compliance timeline assumptions. Industry-specific inputs include robotic milking adoption curves and state-level livestock welfare legislation tracking.
Practitioners should monitor EPA hydraulic fluid environmental regulation progression, galvanized steel commodity price movements, and integrated protein company capital expenditure disclosures for early signals of forecast revision triggers. Quarterly review of feedlot capacity utilization rates, dairy automation integration announcements, and veterinary equipment certification backlog indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
Morocco Poultry Market
Livestock Management
Animal Identification Market
Livestock Management
Europe Swine Feed Market
Livestock Management
Poultry Concentrate Market
Livestock Management
Africa Alfalfa Hay Market
Livestock Management
Equine Artificial Insemination Market
Livestock Management
South America Swine Feed Market
Livestock Management
Poultry Health Market
Livestock Management
Colombia Animal Feed Market
Livestock Management
Animal Artificial Insemination Market
Livestock Management
Europe Ruminant Feed Premix Market
Livestock Management
North America Swine Feed Market
Livestock Management
Roughage Feed Market
Livestock Management
Animal Feed Protease Market
Livestock Management
Cattle Head Catch Market
Livestock Management
Africa Ruminant Feed Premix Market