
 North America Ruminant Feed Market | 2026-2036
North America Ruminant Feed Market Size, Share, and Industry Trends Forecast 2026-2036
North America Ruminant Feed Market Analytics
The direct-to-producer distribution channel is rewriting procurement patterns across the North America ruminant feed landscape. Cargill, Incorporated leverages its grain origination network to secure captive corn supply across the Corn Belt. ADM Animal Nutrition competes through enzyme-adjuvant formulations that reduce feed conversion ratios in commercial dairies. Alltech anchors its position with yeast-based additive platforms targeting mycotoxin mitigation.
North America ruminant feed comprises formulated nutritional inputs designed for multi-compartment stomach physiology, typically incorporating 40-60% forage bases with protein concentrates, mineral premixes, and fermentation-enhancing additives to optimize volatile fatty acid production and microbial crude protein synthesis. Dry feed formulations dominate volume flows due to extended storage stability and mechanized handling compatibility, while concentrates command margin concentration through precision nutrient density and veterinary prescription tie-ins. Cattle applications absorb the largest share of compound feed tonnage, though sheep and goat segments exhibit faster specialty premix growth driven by small-scale producer premiumization.
The EPA enforces Clean Water Act discharge permits for concentrated animal feeding operations, compelling feed formulators to reduce phosphorus and nitrogen excretion through precision nutrition. The USDA's National Organic Program and various state-level agricultural departments enforce ingredient traceability and antibiotic-free certification pathways that reshape product development priorities. Stakeholders must monitor evolving state ballot initiatives on livestock confinement standards and their downstream feed specification impacts.
Market Dynamics
The EPA's revised Clean Water Act permitting for concentrated animal feeding operations is tightening nutrient management requirements, forcing feed formulators to redesign phosphorus and nitrogen excretion profiles through precision nutrition protocols.
Growth Catalysts
- Precision Nutrition Mandates:The EPA's Clean Water Act discharge permits compel commercial dairies and feedlots to adopt low-excretion formulations, creating sustained demand for amino acid-balanced rations and phytase-enhanced premixes.
- Texas Panhandle Concentration:The feedlot corridor's expansion drives bulk compound feed procurement at scale, concentrating volume flows and justifying dedicated manufacturing infrastructure.
- Enzyme-Adjuvant Platforms:Feed conversion ratio optimization through cellulase and xylanase additives is penetrating commercial dairy operations across the Upper Midwest, reducing cost per hundredweight of milk produced.
Market Restraints
- Corn Price Volatility:The Corn Belt's weather-dependent yields and ethanol sector competition create input cost instability that compresses formulation margins and complicates long-term contracting.
- Supply Concentration Risk:Three grain origination networks control the majority of captive corn supply across the Midwest, creating dependency vulnerabilities for independent feed mills.
- Antibiotic-Free Certification Friction:The USDA's National Organic Program traceability requirements extend certification timelines and raise compliance costs for producers transitioning conventional herds.
Strategic Opportunities
- Small-Ruminant Premiumization:Sheep and goat specialty premix segments in Texas and the Mountain West exhibit faster growth than cattle formulations, rewarding targeted product development.
- Direct-to-Producer Channels:Bypassing traditional distributor networks through cooperative procurement platforms is capturing margin previously allocated to intermediaries in the Upper Midwest dairy belt.
- Mycotoxin Mitigation Convergence:Yeast-based additives combined with rapid diagnostic testing are creating integrated contamination management protocols for humid Southern states.
Industry Challenges
- Formulation Talent Scarcity:The ruminant nutritionist pipeline is failing to match demand for professionals capable of balancing volatile fatty acid optimization with regulatory excretion limits.
- Legacy System Integration:Mechanized handling infrastructure designed for dry feed bulk flows requires costly retrofitting to accommodate liquid additive injection systems and precision delivery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Ruminant Feed Market |
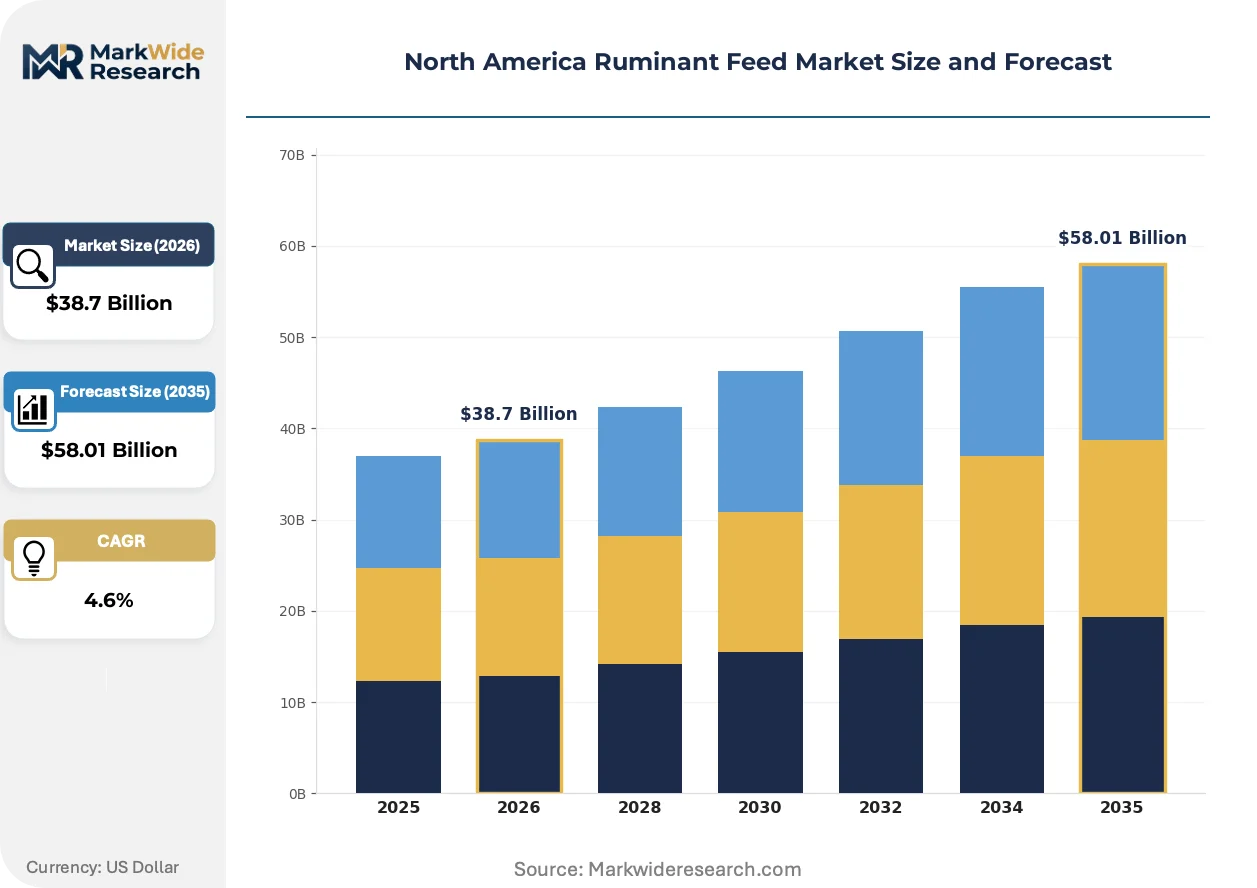
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $58.01 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet Feed, Dry Feed, Concentrates, Supplements Feed Ingredient: Corn, Barley, Soybean Meal, Alfalfa Ruminant Type: Cattle, Sheep, Goats, Buffalo Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Cargill, Incorporated, ADM Animal Nutrition, Nutreco N.V, Alltech, Lallemand Inc., Land O'Lakes, Inc., DSM, Kemin Industries Inc., ForFarmers Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Ruminant Feed Market Evolving Landscape
Formulation science is converging with environmental compliance and digital agriculture, reshaping how nutritional inputs are designed, delivered, and monitored across the value chain.
Precision fermentation-derived proteins are hybridizing with conventional soybean meal in commercial dairy rations, enabling amino acid profiles unattainable through commodity sourcing alone. Large cooperatives in Wisconsin and Minnesota are piloting these formulations at 10-15% inclusion rates. This convergence is compressing the cost-performance gap between novel and traditional protein sources while reducing land-use intensity.
The EPA's nutrient discharge enforcement is mandating real-time manure composition monitoring tied to feed ration adjustments, creating closed-loop management systems. Commercial feedlots in Nebraska and Kansas are deploying near-infrared spectroscopy for instant phosphorus and nitrogen prediction. The regulatory pressure is accelerating adoption of phytase superdosing and crystalline amino acid supplementation to stay below permit thresholds.
Cooperative procurement platforms are consolidating order flows from smaller Upper Midwest dairies into volume commitments that bypass traditional distributor markups. These aggregators negotiate directly with formulation houses, compressing channel margins and demanding customized premix specifications. The disintermediation is most advanced in Wisconsin and Michigan, where dairy cooperative density supports platform economics.
North America Ruminant Feed Market Segmentation
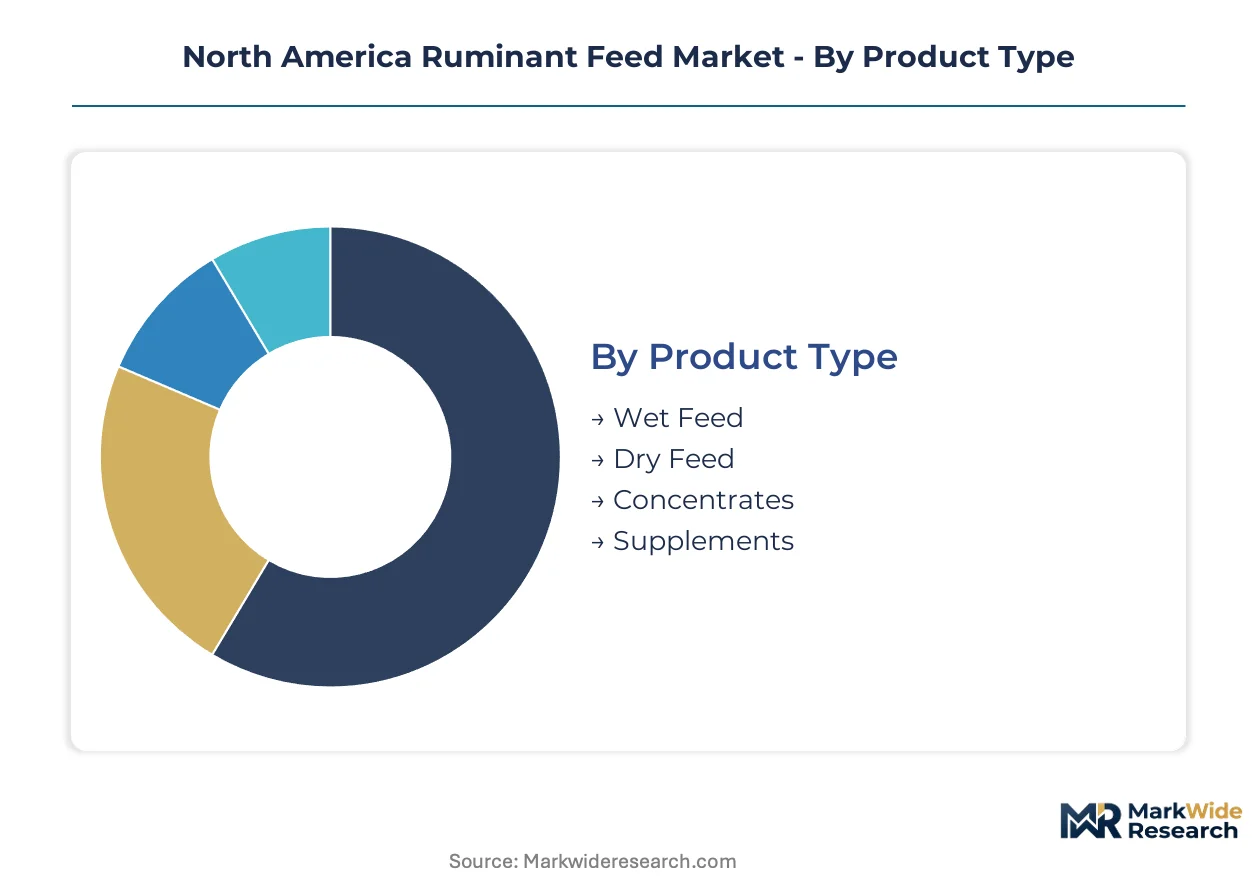
Feed formulators in North America structure product portfolios around handling logistics, ingredient sourcing security, and species-specific digestive physiology. Each segmentation dimension carries distinct margin profiles and service intensity requirements that reshape competitive positioning.
Product Type:
After-sales service intensity varies sharply across physical form factors, with liquid additive systems demanding technical support that dry bulk formulations rarely require.
- Dry Feed:Mechanized handling compatibility drives volume dominance across Texas Panhandle feedlots and Upper Midwest dairy operations. Extended storage stability reduces inventory risk for large cooperatives managing seasonal corn harvest flows.
- Concentrates:Precision nutrient density commands formulation premiums through veterinary prescription tie-ins and amino acid balancing for EPA phosphorus compliance. Commercial dairies in Wisconsin and Minnesota concentrate procurement here for milk production optimization.
- Wet Feed:Fermentation-enhanced silage and high-moisture corn require specialized storage infrastructure and rapid turnover logistics.
- Supplements:Mineral premixes and targeted additive packs serve small-scale producers seeking precision without full ration reformulation.
By volume, Dry Feed leads. By growth pace, Concentrates is climbing the fastest.
Feed Ingredient:
Cost tier stratification separates commodity grain flows from premium protein sourcing, with captive supply arrangements determining margin capture across the Corn Belt.
- Corn:Captive origination networks control the majority of Midwest supply, creating dependency vulnerabilities for independent mills. Ethanol sector competition and weather-dependent yields inject persistent cost instability into formulation economics.
- Soybean Meal:Amino acid profiles anchor protein concentrate value, with precision fermentation alternatives now hybridizing at 10-15% inclusion rates in Wisconsin and Minnesota pilot programs.
- Barley:Cool-season cultivation concentrates in northern Plains states with distinct fermentation characteristics for beef finishing rations.
- Alfalfa:Forage bases dominate dairy rations in California's Central Valley and intermountain hay regions.
Corn captures the largest tonnage share. Soybean Meal exhibits the steepest expansion trajectory through precision nutrition adoption.
Ruminant Type:
Customer type fragmentation separates large-scale commercial operations from smallholder premiumization patterns across distinct regional clusters.
- Cattle:Compound feed tonnage concentrates in feedlot corridors and commercial dairy belts, with Texas Panhandle infrastructure scaling for bulk procurement. Beef finishing and dairy lactation rations drive divergent formulation specifications.
- Sheep:Specialty premix growth accelerates in Texas and Mountain West operations targeting premium wool and lamb markets.
- Goats:Small-scale producer density in hobby farming and ethnic market supply chains supports faster specialty product development than cattle segments.
- Buffalo:Niche bison ranching operations in Great Plains states require distinct mineral supplementation protocols.
Cattle dominates absolute volume. Goats is gaining share fastest through small-ruminant premiumization.
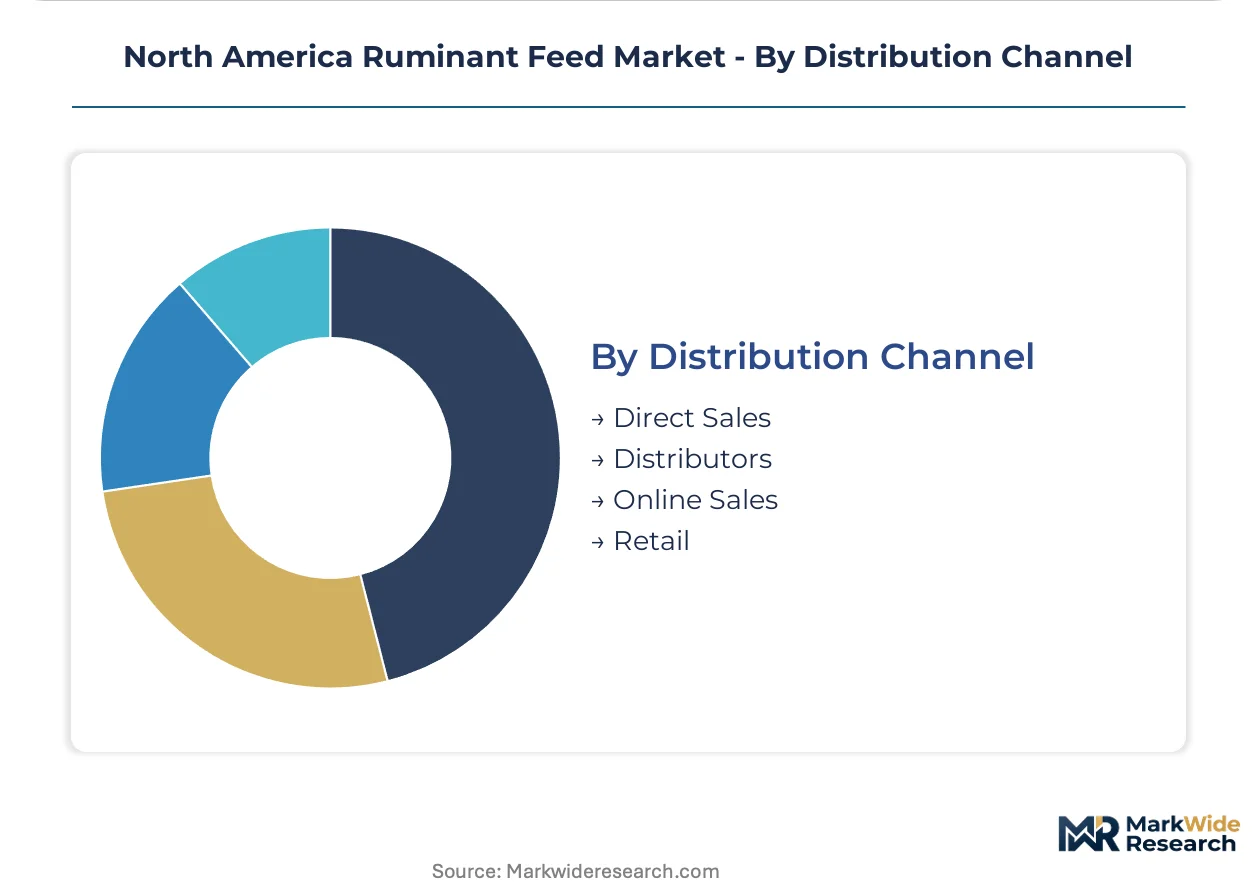
Distribution Channel:
Supply concentration in grain origination networks is producing divergent channel strategies, with cooperative platforms disintermediating traditional distributor markups.
- Direct Sales:Cooperative procurement platforms in Wisconsin and Michigan consolidate dairy order flows into volume commitments bypassing intermediaries. Cargill's grain origination network secures captive supply relationships across the Corn Belt.
- Distributors:Traditional feed dealers maintain relevance in regions lacking cooperative density or requiring technical service bundling.
- Online Sales:Digital procurement penetrates small-scale and hobby farming segments with premix and supplement ordering.
- Retail:Farm supply stores serve emergency and top-up purchasing for operations outside bulk delivery zones.
Direct Sales leads by volume in dairy-dense regions. Online Sales is expanding most quickly in underserved geographic pockets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EPA's Clean Water Act discharge permitting anchors regulatory pressure across the United States, compelling feed formulators to redesign phosphorus and nitrogen excretion profiles. Canada enforces parallel nutrient management protocols through provincial agricultural departments. Mexico's livestock sector operates under distinct federal environmental standards that diverge from US compliance frameworks.
United States
Commercial dairies in Wisconsin and Minnesota pilot precision fermentation proteins at 10-15% inclusion rates. The USDA's National Organic Program enforces antibiotic-free certification pathways that reshape product development priorities. The Texas Panhandle feedlot corridor concentrates bulk compound feed procurement at scale.
Canada
Prairie province feed mills source barley and wheat from cool-season cultivation belts in Alberta and Saskatchewan. Health Canada and PMRA regulate feed additive approvals and residue monitoring. Ontario's dairy cooperative density supports direct-to-producer procurement platforms bypassing traditional distributors.
Mexico
Northern border states import US corn and soybean meal for cattle finishing operations serving domestic beef markets. The country's federal environmental prosecutor enforces watershed protection standards for concentrated animal feeding operations. Jalisco's dairy belt around Guadalajara concentrates commercial herd nutrition program expansion.
North America Ruminant Feed Market Competitive Landscape
Grain-origination conglomerates and enzyme-adjuvant specialists split the market into distinct capability tiers. Three grain origination networks control captive corn supply across the Midwest, creating dependency vulnerabilities for independent mills. Competitive moves concentrate on backward integration into origination assets and precision nutrition formulation partnerships with commercial dairies.
Among North American agribusiness conglomerates, Cargill, Incorporated and ADM Animal Nutrition exemplify the grain-origination archetype through Corn Belt supply network control. Alltech represents the additive-specialist tier with yeast-based platforms targeting mycotoxin mitigation protocols.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| ADM Animal Nutrition |
| Nutreco N.V |
| Alltech |
| Lallemand Inc. |
| Land O'Lakes, Inc. |
| DSM |
| Kemin Industries Inc. |
| ForFarmers Inc. |
| Others |
Value Network & Pricing Analysis
The Texas Panhandle feedlot corridor's concentrated procurement scale compresses formulation margins for independent mills lacking captive corn origination networks. Cargill's grain elevator dominance across the Corn Belt translates into pricing power over downstream compound feed producers competing on cost.
Pricing Analysis
Price spreads between the Upper Midwest dairy belt and Southern humid-state operations reflect transportation cost differentials and mycotoxin risk premiums. Three-tier pricing structure across premium phytase-enhanced formulations, standard amino acid-balanced rations, and economy bulk blends stratifies the market. Cost compression in economy tiers is intensifying because ethanol sector competition for Corn Belt supply tightens ingredient availability. Small-scale goat and sheep producers exhibit highest price sensitivity, while commercial Texas feedlots leverage volume commitments for least-sensitive procurement.
Supply Chain Analysis
Tariff exposure between the United States and Canada disrupts barley and wheat flows for Prairie province feed mills. Geographic supply concentration centers on the United States, Canada, and Mexico for corn and soybean meal sourcing. Raw material dependencies rest on weather-dependent Corn Belt harvests, ethanol sector diversion, and precision fermentation protein alternatives. Single-source vulnerability pervades the three grain origination networks controlling captive supply. Distribution runs through cooperative procurement platforms disintermediating traditional dealer networks in Wisconsin and Michigan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America ruminant feed market represents a high-growth disruption as EPA Clean Water Act enforcement mandates precision nutrition redesign across concentrated animal feeding operations.
For Market Incumbents: Build formulation science moats through phytase superdosing and crystalline amino acid capabilities that satisfy tightening phosphorus discharge permits. Acquire enzyme-adjuvant specialists to defend against ADM's feed conversion ratio optimization platforms. Expand captive origination assets in the Corn Belt to secure supply against ethanol sector competition. For New Entrants and Emerging Players: Small-ruminant specialty premix segments in Texas and the Mountain West represent the most penetrable entry point, with goat and goat producer density outpacing cattle formulation growth. Direct-to-producer cooperative procurement platforms in Michigan and Wisconsin offer channel bypass opportunities. Target mycotoxin mitigation bundles combining yeast-based additives with rapid diagnostic testing for Southern state penetration. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision fermentation protein hybridizers and enzyme-adjuvant platform owners over commodity grain originators. Long-term viability concentrates in formulation houses capable of balancing volatile fatty acid optimization with regulatory excretion limits. Monitor EPA nutrient discharge enforcement intensity and state ballot initiative outcomes on livestock confinement standards as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Origination | Cargill's elevator network secures captive supply against ethanol sector competition across Iowa and Illinois. |
| Enzyme-Adjuvant Platform Development | ADM's cellulase formulations reduce feed conversion ratios for Upper Midwest commercial dairies. |
| Precision Fermentation Protein Piloting | Wisconsin and Minnesota cooperatives test 10-15% inclusion rates to reduce land-use intensity. |
| Cooperative Procurement Platform Launch | Wisconsin dairy density supports disintermediation bypassing traditional distributor markups. |
| Mycotoxin Mitigation Bundle Integration | Alltech's yeast-based additives combine with rapid diagnostics for humid Southern state protocols. |
Research Methodology
The analysis maps dry feed, concentrates, wet feed, and supplement form factors, each validated through interviews with commercial dairy nutritionists, feedlot procurement managers, cooperative platform operators, and EPA compliance officers. Primary fieldwork combined with secondary validation draws from USDA National Organic Program filings, EPA Clean Water Act permit databases, state agricultural department records, and Corn Belt grain elevator capacity reports. Bottom-up volume modeling and top-down value triangulation cross-checked formulation house revenue disclosures against cooperative procurement flow estimates.
Assumptions held fixed include EPA phosphorus discharge permit thresholds and USDA antibiotic-free certification pathways, while corn yield volatility and precision fermentation protein cost curves varied across the projection horizon. Segmentation dimensions modeled encompass physical form factor, ingredient sourcing tier, ruminant species, and distribution channel structure. CAGRs derived from historical compound feed tonnage trajectories and value-per-ton expansion tied to precision nutrition adoption. Industry-specific inputs incorporated phytase superdosing penetration rates and cooperative platform order flow consolidation.
Practitioners should monitor EPA enforcement intensity, state ballot initiative outcomes, and precision fermentation protein cost parity signals for early revision triggers. Forecasts reflect documented assumptions regarding regulatory stability and technology adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
Cattle Squeeze Market
Livestock Management
Swine Feed Market
Livestock Management
Animal Artificial Insemination Market
Livestock Management
Hominy Feed Market
Livestock Management
Saudi Arabia Poultry Market
Livestock Management
Cattle Head Catch Market
Livestock Management
Digital Livestock Farming Market
Livestock Management
China Swine Feed Market
Livestock Management
Wild Birds Products Market
Livestock Management
Roughage Feed Market
Livestock Management
Cattle Management Software Market
Livestock Management
Feed Management Software Market
Livestock Management
Smart Feeding Systems Market
Livestock Management
Swine Artificial Insemination Market
Livestock Management
South America Swine Feed Market
Livestock Management
Animal Identification Market