
 Animal Artificial Insemination Market | 2026-2036
Animal Artificial Insemination Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Artificial Insemination Market Analysis
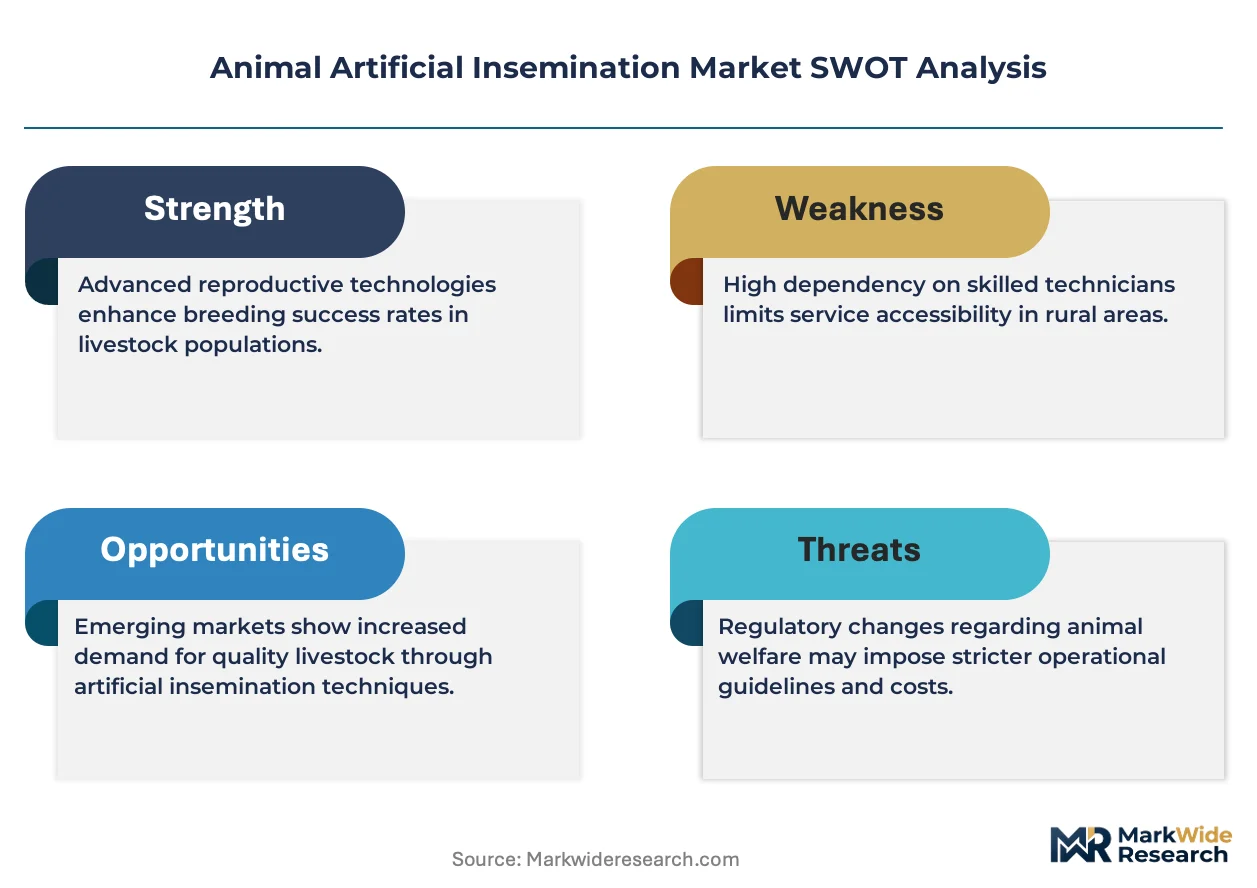
Subscription-based semen storage and liquid nitrogen monitoring services are restructuring procurement economics for livestock producers. Genus PLC leverages genomic testing integration to sustain premium pricing on high-index dairy bull semen. URUS Group LP anchors North American distribution through cooperative ownership structures that control breeder access to elite genetics. STgenetics specializes in gender-sorted semen technology that differentiates its product line from conventional offerings.
Animal artificial insemination encompasses the clinical introduction of processed spermatozoa into the female reproductive tract using specialized catheters, with semen preserved at minus 196 degrees Celsius in liquid nitrogen tanks for long-term viability. The technique enables selective breeding without live male animal transport, reducing disease transmission risk while accelerating genetic improvement in commercial herds. Frozen semen techniques dominate transaction volumes due to extended shelf life and international trade compatibility, though fresh semen techniques retain margin advantages in localized swine operations where conception rates run higher. Cattle breeding absorbs the largest share of AI equipment expenditure, particularly in Holstein dairy systems where individual cow genetic merit justifies per-dose premiums.
The USDA enforces semen import protocols through APHIS veterinary regulations that quarantine and test foreign genetic material before release. The EU enforces Directive 88/407/EEC standards for bovine semen collection and processing, while Brazil's MAPA inspects production facilities for compliance with international health codes. Breeders and service providers must monitor evolving genomic evaluation timelines and cryopreservation protocol patents that could shift competitive access to elite germplasm.
Market Dynamics
Genomic selection protocols are compressing genetic evaluation cycles from years to months, forcing semen suppliers to restructure inventory and pricing models around real-time index updates rather than static bull rankings.
Growth Catalysts
- USDA Traceability Mandates:The USDA's APHIS animal disease traceability rules now require documented semen chain-of-custody records, accelerating producer conversion from unrecorded natural service to documented AI protocols.
- Gender-Sorted Semen:Sexed semen technology enables dairy operators to generate 90% female offspring, eliminating the economic drag of male calf production in Holstein herds.
- Brazilian Feedlot Expansion:Mato Grosso state cattle operations are deploying timed artificial insemination at scale to synchronize calving with feedlot finishing cycles.
Market Restraints
- Liquid Nitrogen Supply Concentration:Cryogenic infrastructure depends on regional liquid nitrogen production clusters; supply disruptions in the US Gulf Coast affect semen storage viability across North American distribution networks.
- EU Directive 88/407/EEC Compliance Costs:Bovine semen collection facilities face mandatory health testing and processing standards that raise fixed costs for smaller European bull studs.
- Fresh Semen Substitution:Localized swine operations retain margin advantages with fresh semen techniques where conception rates exceed frozen alternatives, limiting frozen semen penetration in porcine breeding.
Strategic Opportunities
- Subscription Storage Services:Liquid nitrogen tank monitoring and semen inventory management offered as recurring revenue services restructure producer relationships from transactional to retained.
- Genomic-Testing Convergence:Integration of on-farm DNA testing with semen selection algorithms enables customized mating decisions at the individual cow level.
- Indian Dairy Modernization:India's National Dairy Development Board cooperative structure presents underpenetrated demand for AI services as herd sizes consolidate beyond natural service practicality.
Industry Challenges
- Certified Technician Shortage:Proper AI technique requires trained inseminators; veterinary schools and extension programs are not graduating sufficient certified practitioners to match herd expansion rates.
- Cryopreservation Patent Complexity:Semen freezing protocols and extenders remain protected by overlapping intellectual property portfolios, complicating new market entry for regional genetics suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Artificial Insemination Market |
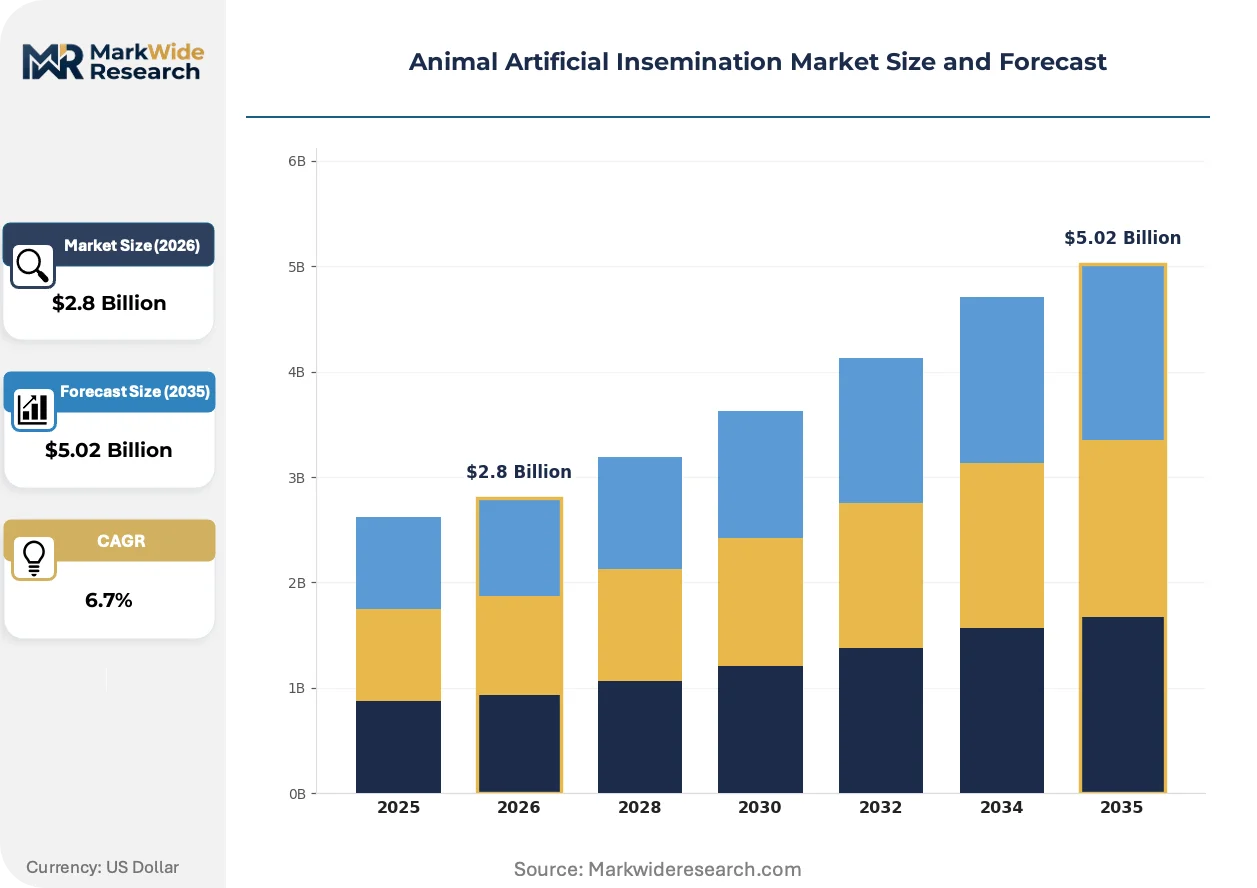
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Semen, AI Equipment, Catheters, Storage Tanks Application: Cattle Breeding, Swine Reproduction, Sheep Reproduction, Horse Breeding End User: Livestock Farms, Veterinary Clinics, Research Institutions, Breeding Organizations Technology: Frozen Semen Techniques, Fresh Semen Techniques, In Vitro Fertilization, Embryo Transfer Technologies |
| Companies Covered | SEMEX, URUS Group LP, Genus PLC, Swine Genetics International, STgenetics, Select Sires Inc., CRV, Neogen Corporation, IMV Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Artificial Insemination Market Emerging Trajectories
Portable insemination technologies and cloud-connected herd management systems are redistributing genetic decision-making from central bull studs to farm-level operators. These shifts compress information asymmetries and alter how premium genetics are priced and accessed.
Mobile semen thawing units equipped with precision temperature control are decentralizing insemination timing decisions. Dairy farm staff now perform timed AI without veterinary presence, cutting per-dose service costs by eliminating technician travel. This hardware diffusion is compressing the addressable market for traditional AI service businesses while expanding total procedure volumes.
REACH chemical registration requirements in Europe are forcing reformulation of semen extender cocktails. Traditional antibiotic preservatives face substitution pressure, compelling suppliers to validate novel cryoprotectant chemistries. Bovine semen processors with EU export ambitions are front-loading toxicology testing budgets to maintain market access.
Cooperative procurement consortia in Wisconsin and the Netherlands are consolidating semen purchasing into annual volume tenders. Individual dairy farmers surrender direct supplier relationships in exchange for negotiated index premiums and pooled liquid nitrogen logistics. This buyer concentration is visible most acutely in regions where dairy cooperative membership exceeds 60% of milk production volume.
Animal Artificial Insemination Market Segmentation
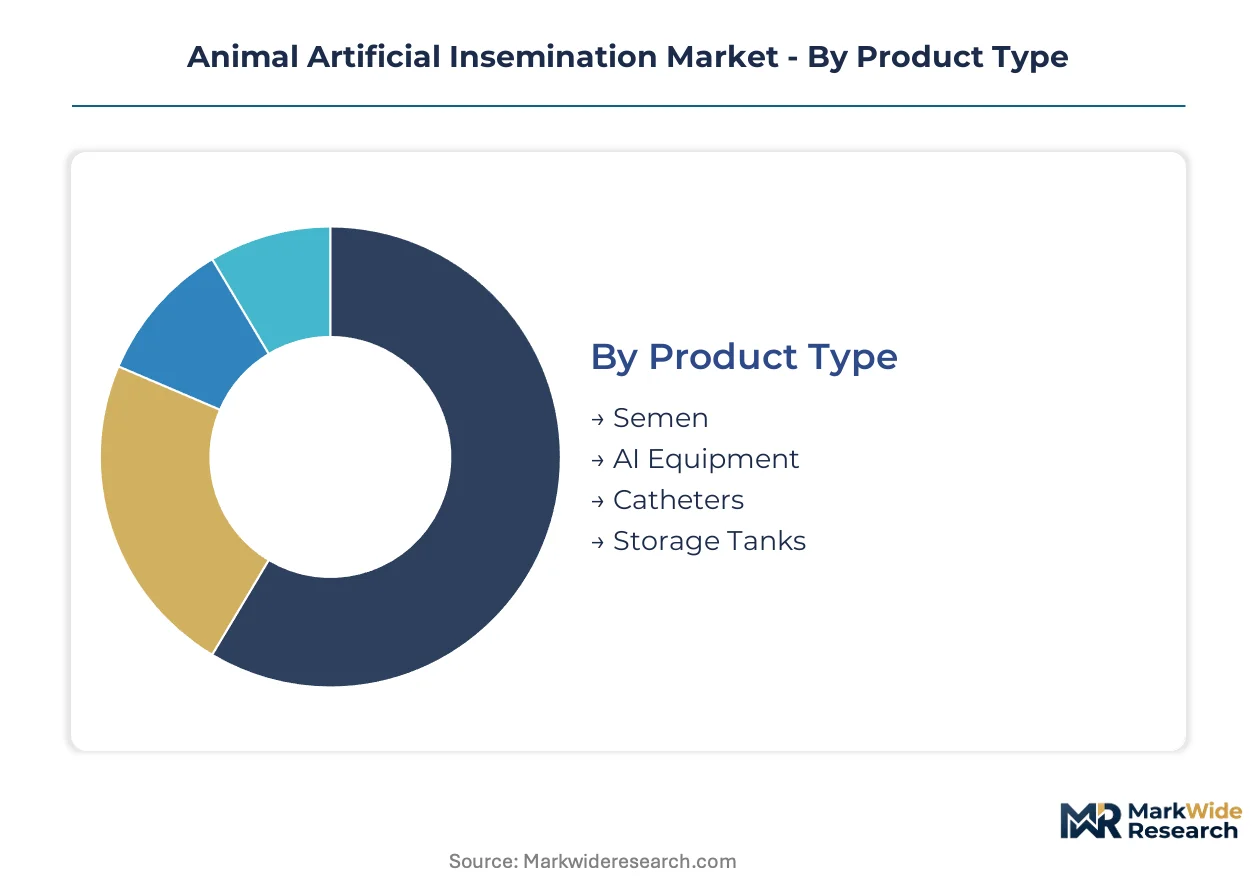
Segmentation in animal artificial insemination reveals how procurement decisions split between commodity genetics and precision breeding investments. Equipment choices and semen formats diverge sharply across herd sizes, with large operations demanding integrated systems while smaller farms prioritize per-dose flexibility.
Product Type:
Frozen semen dominates transaction volumes through extended shelf life, while fresh formats command localized premiums in specific applications.
- Semen:Processed spermatozoa preserved in liquid nitrogen at minus 196 degrees Celsius enables selective breeding without live animal transport. Dairy cooperatives in Wisconsin and the Netherlands are consolidating annual volume tenders for high-index dairy bull semen, compressing supplier margins while securing genetic access.
- AI Equipment:Portable insemination guns, thawing units, and precision temperature control systems decentralize procedure timing away from veterinary presence. Brazilian feedlot operators in Mato Grosso state are deploying mobile thawing infrastructure to synchronize timed AI with finishing cycles.
- Catheters:Single-use disposable sheaths and specialized breeding rods designed for species-specific reproductive tract anatomy.
- Storage Tanks:Vacuum-insulated liquid nitrogen dewars with automated level monitoring for semen inventory preservation.
Today's leader: Semen. Tomorrow's challenger: AI Equipment.
Application:
Species-specific breeding economics drive divergent technology adoption, with dairy cattle justifying per-dose premiums that swine operations cannot support.
- Cattle Breeding:Holstein dairy systems absorb the largest equipment expenditure share as individual cow genetic merit justifies premium semen pricing. Gender-sorted semen technology generates 90% female offspring, eliminating male calf production drag in commercial herds.
- Swine Reproduction:Localized operations retain fresh semen margin advantages where conception rates exceed frozen alternatives, limiting cryogenic penetration in porcine breeding.
- Sheep Reproduction:Seasonal breeding patterns and smaller flock sizes constrain AI adoption compared to year-round dairy systems.
- Horse Breeding:Thoroughbred registries and sport horse disciplines maintain specialized fresh-cooled semen logistics for elite stallion genetics.
Cattle breeding concentrates revenue; swine reproduction offers volume scale at thinner margins.
End User:
Procurement authority is shifting from individual producers toward cooperative structures that negotiate collective access to elite genetics.
- Livestock Farms:Commercial operations managing herd sizes beyond natural service practicality, particularly in India's consolidating dairy sector.
- Veterinary Clinics:Service providers performing AI procedures on a per-dose fee basis face compression from mobile thawing technologies.
- Research Institutions:Academic and government facilities developing cryopreservation protocols and genomic evaluation methodologies.
- Breeding Organizations:Breed associations and bull studs controlling germplasm distribution through certified technician networks.
Cooperative farms are gaining procurement leverage; independent clinics are losing service revenue to on-farm technologies.
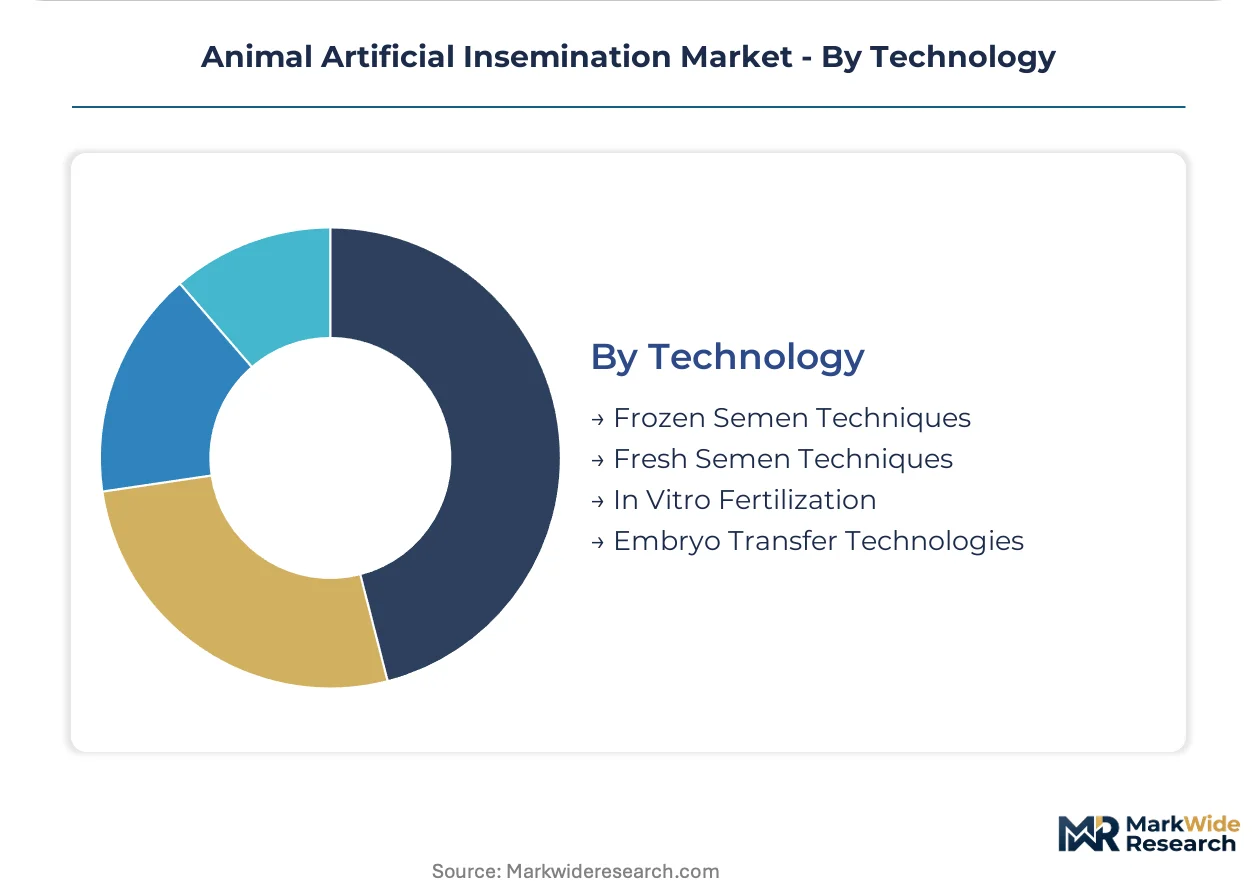
Technology:
Preservation format determines trade geography, with frozen techniques enabling international germplasm commerce while fresh methods serve regional markets.
- Frozen Semen Techniques:Cryogenic preservation in liquid nitrogen tanks supports extended storage and cross-border trade under USDA APHIS veterinary regulations. The technique dominates transaction volumes through shelf life advantages and international compatibility.
- Fresh Semen Techniques:Short-interval collection and delivery maintains higher conception rates in localized swine operations where transport distances permit rapid deployment.
- In Vitro Fertilization:Laboratory-based oocyte fertilization enables genetic rescue and elite embryo production from limited gamete sources.
- Embryo Transfer Technologies:Multiplication of superior female genetics through surrogate recipient programs accelerates herd improvement timelines.
Frozen semen anchors current trade flows; embryo transfer represents the steepest expansion trajectory for premium genetic multiplication.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Mato Grosso feedlots deploy timed AI protocols at scale, while Wisconsin dairy cooperatives negotiate collective semen tenders—revealing how geography shapes procurement concentration.
United States
USDA APHIS traceability mandates accelerate documented AI adoption across commercial herds. The agency's veterinary regulations require quarantine and testing of imported genetic material before release. Wisconsin dairy cooperatives consolidate annual volume tenders, compressing supplier margins while securing elite Holstein genetics.
Brazil
MAPA inspects production facilities for compliance with international health codes, raising barriers for foreign semen entry. Large-scale cattle operations in Mato Grosso state convert from natural service to timed artificial insemination protocols. Feedlot operators synchronize calving with finishing cycles using mobile thawing infrastructure.
Netherlands
EU Directive 88/407/EEC enforces bovine semen collection and processing standards that elevate fixed costs for smaller bull studs. Dairy cooperatives expand AI programs to boost herd genetic quality. Cooperative procurement consortia consolidate semen purchasing into annual tenders where membership exceeds 60% of milk production volume.
India
The National Dairy Development Board cooperative structure presents underpenetrated demand as herd sizes consolidate beyond natural service practicality. The country's central livestock regulator mandates health certification for imported genetic material. Maharashtra and Gujarat dairy belts see accelerating technician network expansion.
Germany
REACH chemical registration requirements force reformulation of semen extender cocktails, compelling toxicology testing investments. Bavarian and Lower Saxony dairy clusters drive equipment demand. Regional liquid nitrogen production infrastructure anchors cryogenic distribution networks across Central Europe.
Animal Artificial Insemination Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with genomic testing integrators commanding premium positioning while equipment fabricators compete on per-unit economics. The market structures around three tiers: multinational genetics conglomerates with cryogenic infrastructure, regional bull studs serving localized breeding programs, and equipment specialists delivering portable insemination hardware. Consolidation pressure runs highest in semen processing, where scale advantages in liquid nitrogen logistics and genomic database access create defensive moats. Strategic moves center on cooperative ownership structures that lock in breeder access and subscription-based service models that convert transactional semen sales into recurring revenue.
Within the multinational genetics tier, Genus PLC and URUS Group LP exemplify divergent approaches to market access—one leveraging genomic testing integration for premium pricing, the other anchoring North American distribution through cooperative ownership structures. STgenetics occupies a specialized position through gender-sorted semen technology that differentiates its product line from conventional offerings. These three entities represent the strategic archetypes now competing for herd-level procurement decisions: technology-differentiated premium positioning, cooperative-embedded volume capture, and specialized genetic sorting capabilities.
| Leading Market Players |
|---|
| SEMEX |
| URUS Group LP |
| Genus PLC |
| Swine Genetics International |
| STgenetics |
| Select Sires Inc. |
| CRV |
| Neogen Corporation |
| IMV Technologies |
| Others |
Supply Flow & Price Mechanics
Cooperative-owned bull studs in Wisconsin and the Netherlands anchor pricing discipline through pooled procurement power, compressing supplier margins while securing liquid nitrogen logistics and genomic database access for member dairies. This ownership concentration feeds back into supply chain configuration, as vertically integrated genetics conglomerates defend position through captive cryogenic infrastructure rather than price competition.
Pricing Analysis
Capacity additions in Brazil are reshaping price floors for conventional semen as Mato Grosso feedlot operators scale timed AI protocols. Three-tier pricing structure across premium, standard, and economy levels separates gender-sorted genomic lines from conventional frozen doses and unproven young sire collections. Cost compression in the standard tier is intensifying because Brazilian demand is converting from natural service faster than elite bull inventory expands. Smallholder dairy farms in India exhibit the highest price sensitivity, while Holstein cooperatives in Wisconsin and the Netherlands absorb premiums for high-index sexed semen with minimal volume elasticity.
Supply Chain Analysis
Regional distribution centers in Wisconsin, the Netherlands, and São Paulo state anchor hub-and-spoke patterns for liquid nitrogen tank replenishment and semen inventory staging. Geographic supply concentrates in the United States, the Netherlands, and Brazil, where bull studs cluster near dairy production belts and veterinary research universities. Raw material dependencies center on liquid nitrogen production, semen extender chemistries, and genomic testing reagents. Single-source vulnerability runs through US Gulf Coast liquid nitrogen production clusters, where hurricane disruptions propagate across North American storage networks. Distribution runs through cooperative procurement consortia that consolidate individual farm orders into annual volume tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: regulatory compliance costs in the European Union under Directive 88/407/EEC elevate fixed barriers that shield premium-priced US and Brazilian suppliers from direct price competition, while Indian dairy modernization offers cost-advantaged expansion terrain.
For Market Incumbents: Hedge genomic obsolescence risk by deepening backward integration into on-farm DNA testing platforms, converting static bull rankings into real-time index update services that lock in recurring revenue. Acquire certified technician training capacity to preempt the practitioner shortage threatening herd expansion rates in India and Brazil. Defend margin position through liquid nitrogen logistics control rather than semen price cuts. For New Entrants and Emerging Players: Direct-to-farm mobile thawing units and cloud-connected herd management apps offer white-space entry below the cooperative procurement tier, targeting mid-size Brazilian feedlots and Indian dairy cooperatives bypassed by volume tenders. Veterinary service marketplaces present the most penetrable channel, as traditional AI service businesses face compression from decentralized insemination timing. Pursue pay-per-procedure revenue models that eliminate upfront semen inventory risk for capital-constrained livestock farms. For Investors and Strategic Acquirers: Valuations sit cheapest among regional bull studs lacking captive cryogenic infrastructure or genomic database access, particularly in European markets where Directive 88/407/EEC compliance costs strain smaller operators. Long-term viability hinges on conversion from transactional semen sales to subscription-based storage and monitoring services. Watch liquid nitrogen supply contract renegotiations as the inflection signal: price spikes or availability constraints will accelerate consolidation toward vertically integrated genetics conglomerates with captive production assets.| Strategic Initiative | Industry Significance |
|---|---|
| Gender-Sorted Semen Scale-Up | Enables dairy operators to generate 90% female offspring, eliminating male calf production drag. |
| Subscription Storage Services | Converts transactional semen sales into recurring revenue through liquid nitrogen tank monitoring. |
| Genomic Testing Integration | Compresses genetic evaluation cycles from years to months, forcing real-time index pricing. |
| Mobile Thawing Infrastructure | Decentralizes insemination timing decisions away from veterinary presence, cutting per-dose service costs. |
| Technician Network Expansion | Addresses certified inseminator shortage constraining herd expansion in India and Brazil. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with bull stud operations managers, dairy cooperative procurement directors, veterinary extension specialists, and liquid nitrogen logistics coordinators with secondary validation against USDA APHIS veterinary regulations, EU Directive 88/407/EEC compliance filings, Brazil MAPA inspection records, and customs trade data on semen imports. Bottom-up farm-level demand estimates and top-down genetics industry revenue analysis were cross-referenced for triangulation.
Segment-weighting approaches modeled cattle breeding, swine reproduction, sheep reproduction, and horse breeding applications across frozen semen, fresh semen, in vitro fertilization, and embryo transfer technologies, with further stratification by herd size tiers and cooperative versus independent procurement structures. CAGRs were derived from trend extrapolation adjusted for regulatory mandate timing and technician network expansion rates. Cryogenic infrastructure investment cycles and genomic evaluation protocol patent expirations served as industry-specific forecast inputs.
Regulatory enforcement variance, liquid nitrogen supply disruptions, and genomic index volatility are the dominant revision risks to the baseline projection. Forecasts reflect documented assumptions on cooperative membership penetration and AI technician graduation rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
Cattle Mineral Feeder Market
Livestock Management
Herd Management Software Market
Livestock Management
United States Swine Feed Market
Livestock Management
Digital Livestock Farming Market
Livestock Management
Global Smart Ear Tags Market
Livestock Management
Swine Feed Market
Livestock Management
North America Ruminant Feed Market
Livestock Management
Morocco Poultry Market
Livestock Management
Dairy Herd Management Market
Livestock Management
Feed Management Software Market
Livestock Management
South America Swine Feed Market
Livestock Management
Swine Artificial Insemination Market
Livestock Management
Bird Feeder Market
Livestock Management
Africa Ruminant Feed Premix Market
Livestock Management
Cattle Management Software Market
Livestock Management
China Swine Feed Market