
 Roughage Feed Market | 2026-2036
Roughage Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Roughage Feed Market Analytics
EU Green Deal sustainability criteria is pivoting the cost-of-entry calculus for roughage feed suppliers seeking access to European livestock operations. Purina Mills LLC leverages its extensive distribution network to sustain premium positioning across North American dairy cooperatives. ADM anchors its roughage procurement through backward integration into agricultural origination networks. Anderson Hay specializes in high-grade alfalfa products for export markets with stringent phytosanitary requirements.
Roughage feed comprises dried or ensiled plant materials—typically containing 18% or more crude fiber on a dry matter basis—derived from grass, legume, or cereal crop residues and processed through field curing, baling, or anaerobic fermentation for preservation. Its primary commercial purpose is to stimulate rumen function, maintain digestive health, and provide structural carbohydrates in ruminant and equine diets. Alfalfa and grass silage dominate value pools in dairy-intensive regions where energy-corrected milk yields depend on consistent fiber quality. The baled form retains strong share in beef cattle and horse segments due to handling convenience and storage stability, while pelleted formats are gaining traction in automated feeding systems for large-scale goat and sheep operations.
The EU F-Gas Regulation and REACH frameworks govern emissions from feed processing and chemical inputs used in preservation, compelling suppliers to certify low-carbon production methods for market access. USDA grading standards and FDA feed safety rules under the Food Safety Modernization Act shape product specifications and traceability requirements for U.S. domestic and export channels. Stakeholders must monitor evolving carbon border adjustment mechanisms and decide whether to invest in region-specific certification or consolidate sourcing within protected trade blocs.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is compressing the supplier base by imposing carbon-intensity thresholds on imported roughage, forcing feed mills to requalify sourcing networks or exit European channels entirely.
Growth Catalysts
- Dairy fat premiums:North American cooperatives are expanding silage rations to capture butterfat price differentials, pulling additional alfalfa and grass volumes into domestic supply chains.
- REACH low-carbon certification:The EU chemical framework is creating compliant product premiums for roughage suppliers who document fermentation emissions and fertilizer inputs.
- Integrated beef-dairy systems:Brazilian operators are scaling year-round silage programs to displace volatile grain concentrate costs and lock in margin stability.
Market Restraints
- Fertilizer input volatility:Ammonia and potash price swings compress alfalfa grower margins and destabilize contracted feed supply to dairies.
- Water-stressed production zones:Western US hay output faces recurring allocation cuts from state-level water rights adjudication.
- Preservative chemical restrictions:The EU F-Gas Regulation limits propionic acid and other mold inhibitors, forcing shorter storage windows for exported baled products.
Strategic Opportunities
- Automated feeding infrastructure:Large-scale goat and sheep operations in Spain and Italy are adopting pelleted roughage formats compatible with robotic delivery systems.
- Carbon credit stacking:The EU Green Deal's carbon farming initiative allows certified silage producers to monetize methane avoidance from reduced grain dependency.
- Phytosanitary-grade alfalfa:Export demand from Japan and South Korea for weed-seed-free, laboratory-tested hay creates price premiums above commodity bales.
Industry Challenges
- Qualified nutritionist scarcity:Dairy operations struggle to staff ruminant diet formulation specialists capable of balancing fiber quality against energy density targets.
- Multi-jurisdiction traceability:Suppliers must reconcile USDA grading, FDA Food Safety Modernization Act lot tracking, and EU organic equivalency audits simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roughage Feed Market |
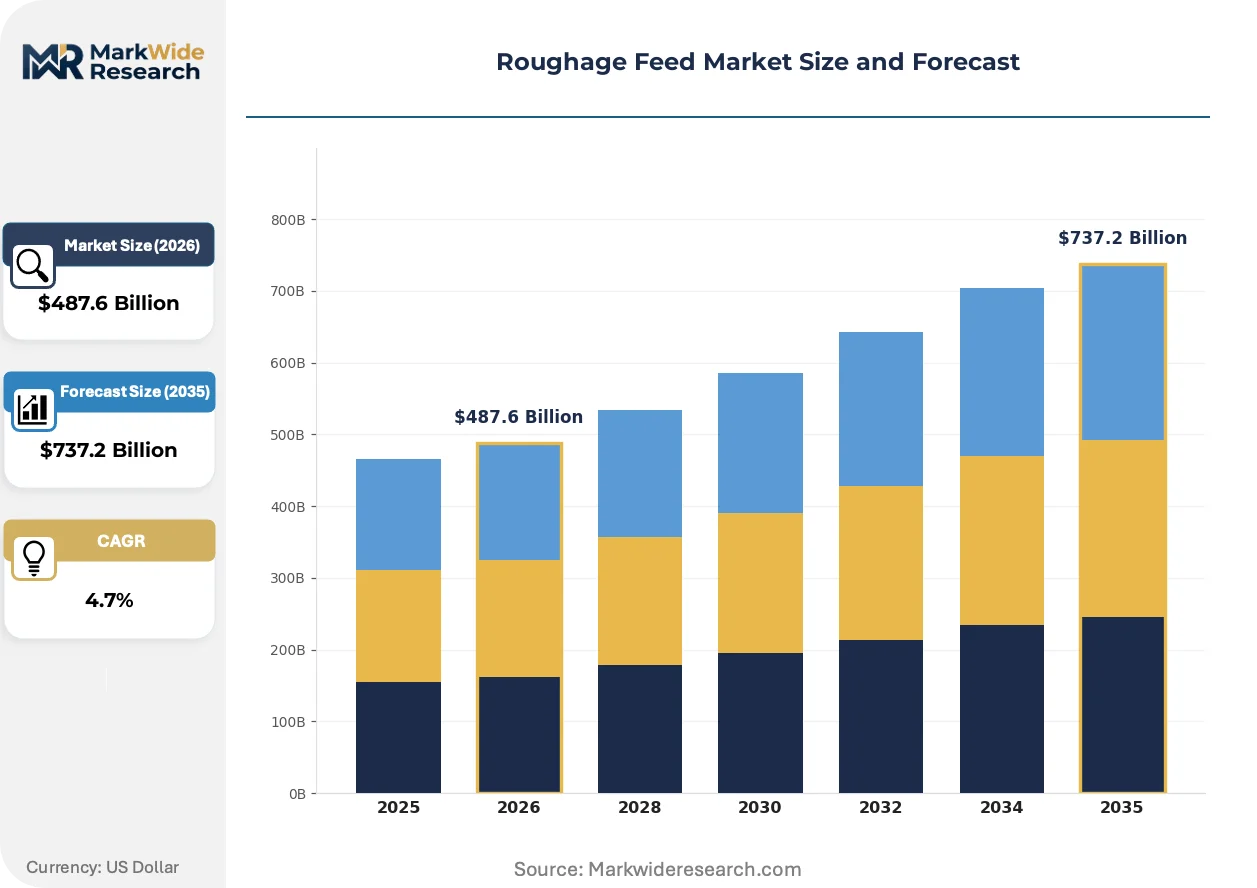
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $737.2 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feed Type: Alfalfa, Timothy Hay, Barley Straw, Grass Silage Animal Type: Cattle, Sheep, Goats, Horses Form: Pelleted, Chopped, Baled, Loose Nutritional Content: High Fiber, Low Protein, Medium Energy, Custom Blend |
| Companies Covered | The VanDrie Group, Barenbrug SA, Al Dahra ACX, Inc., Purina Mills LLC, Feed One, AFGRI Animal Feeds, Anderson Hay, Land O'Lakes, Inc., ADM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roughage Feed Market Evolving Landscape
Near-infrared spectroscopy and robotic baling systems are compressing quality variance and labor dependency across roughage harvesting operations, while regulatory carbon accounting and buyer procurement consolidation reshape commercial terms.
Spectroscopic analysis technology deployed at harvest is automating real-time moisture and crude fiber measurement, enabling on-the-go cutting decisions that preserve nutritional value. Large dairy cooperatives in Wisconsin and California are retrofitting harvest fleets with these sensors at replacement cycle. The technology is automating grade segregation previously handled by manual core sampling, compressing the price spread between top-tier and standard alfalfa lots.
The EU F-Gas Regulation and accompanying REACH amendments are tightening disclosure requirements for chemical preservatives used in baled hay export shipments. Suppliers must now submit full toxicity profiles for mold inhibitors and fermentation aids to ECHA for pre-market notification. Dairy feed importers in the Netherlands and Denmark are responding by shifting procurement toward ensiled products with lower chemical dependency, favoring European-origin grass silage over North American baled hay.
Consolidated procurement by multi-site dairy operators is displacing spot-market purchasing through multi-year supply contracts with embedded quality specifications and price adjustment clauses. These arrangements transfer inventory risk to suppliers while guaranteeing volume commitments to large-scale feed mills. The pattern is most visible in California's Central Valley, where three cooperatives now contract directly with Idaho and Nevada hay growers, bypassing traditional dealer networks and compressing regional price transparency.
Roughage Feed Market Segmentation

Roughage feed segmentation reflects divergent supply chain requirements across preservation methods, animal physiology, and nutritional specifications. Feed mills configure procurement and processing infrastructure around these axes to match ruminant digestive needs with regional forage availability.
Feed Type:
Composition and fiber density differentiate roughage categories, with protein content and digestibility driving end-use matching.
- Alfalfa:Legume-based roughage containing 18-22% crude protein and elevated calcium levels supports high-producing dairy rations. Wisconsin and California dairies contract directly with Idaho growers to secure consistent RFV (Relative Feed Value) grades above 150.
- Grass Silage:Anaerobically fermented forage preserves moisture and digestible energy through lactic acid stabilization. Irish and Dutch cooperatives favor grass silage for year-round fiber supply, reducing dependency on imported dry hay.
- Timothy Hay:Cool-season grass with moderate protein (8-10%) and high palatability serves equine markets and low-protein dairy rations.
- Barley Straw:High-lignin cereal residue provides bulk fiber for dry cow maintenance and bedding applications.
Alfalfa leads on scale; grass silage leads on momentum.
Animal Type:
Species-specific digestive capacity and production intensity shape roughage formulation priorities and volume concentration.
- Cattle:Ruminants with four-chambered stomachs require structural fiber (minimum 25% NDF) to maintain rumen pH and cud chewing. Large-scale dairy operations in the US and Brazil dominate tonnage consumption through TMR (Total Mixed Ration) systems.
- Sheep:Smaller rumen volume demands finer particle size and higher energy density per unit dry matter. Spanish and Italian producers are automating pelleted roughage delivery for intensive lamb finishing systems.
- Goats:Selective browsers tolerate coarser, brush-based roughage with higher tannin content than cattle.
- Horses:Hindgut fermenters need low-sugar, dust-free hay to prevent colic and respiratory issues; quality premiums for certified weed-free bales exceed commodity pricing.
Cattle dominates volume; sheep is climbing fastest in mechanized feeding adoption.
Form:
Physical processing determines storage economics, labor requirements, and compatibility with automated distribution systems.
- Baled:Compressed and twine-wrapped forage enables outdoor storage and long-distance transport. Traditional rectangular bales retain share in US beef cattle and equine segments due to handling familiarity and dealer network density.
- Pelleted:Ground and extruded roughage reduces particle size variability and integrates with robotic feeding equipment. Goat and sheep operations in Mediterranean Europe are converting to pelleted systems to cut labor costs.
- Chopped:Field-processed forage with theoretical length of cut (TLOC) at 3-5 inches optimizes silage packing density and anaerobic preservation.
- Loose:Uncompressed hay requires enclosed storage and manual handling, limiting adoption to small-scale equine and hobby farm segments.
Baled leads on installed base; pelleted shows steepest expansion trajectory.
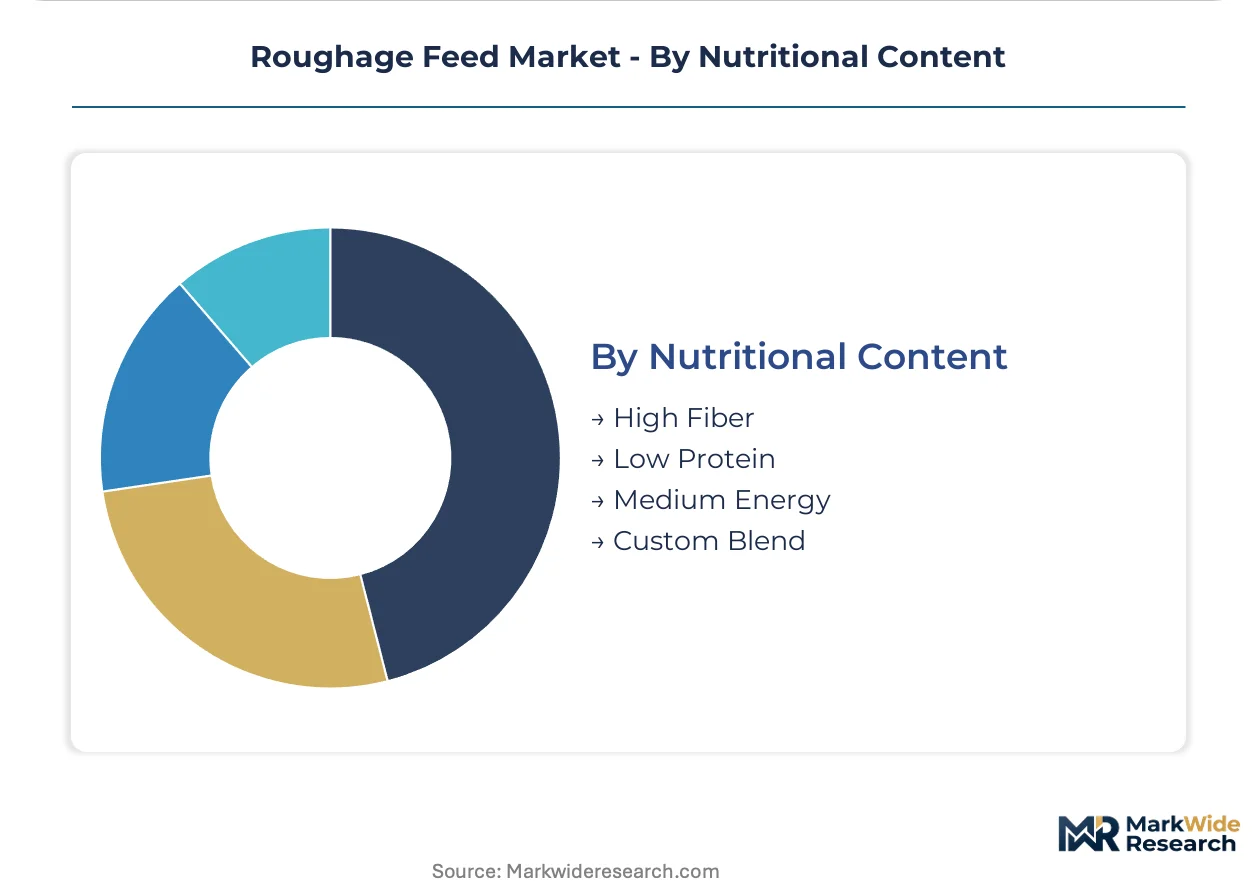
Nutritional Content:
Formulation precision separates commodity roughage from premium-priced, performance-optimized feed grades.
- High Fiber:NDF levels above 45% stimulate rumination and buffer acidosis in high-concentrate dairy diets. Nutritionists in California's Central Valley specify high-fiber alfalfa to balance corn silage energy density.
- Medium Energy:Moderate digestibility (60-65% NDFd) suits growing heifer rations and mid-lactation dairy cows.
- Low Protein:Crude protein below 10% matches dry cow requirements and prevents metabolic disorders in late gestation.
- Custom Blend:Prescription-mixed roughage combines multiple forage sources to hit target nutrient specifications.
High fiber commands the largest volume commitment; custom blend is gaining share fastest among precision livestock operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Roughage feed production originated in the irrigated valleys of the western United States during the early twentieth century, where alfalfa cultivation for draft horses and dairy cattle established quality standards that persist in export markets today.
United States
California dairies in the Central Valley and Wisconsin cooperatives drive alfalfa demand through butterfat premium capture and rumen health optimization. The FDA Food Safety Modernization Act mandates lot-level traceability for interstate hay shipments. Idaho growers in the Snake River Plain now contract directly with processors, bypassing traditional dealer networks and compressing regional price spreads.
Brazil
Integrated beef-dairy operators in São Paulo and Minas Gerais states are scaling year-round silage programs to displace volatile grain concentrate costs. ANVISA governs feed additive registrations and preservative approvals for imported materials. The cerrado region around Goiânia has emerged as a silage production cluster where large-scale operators lock in multi-year supply contracts with integrated processors.
Germany
Dairy cooperatives in Lower Saxony and Bavaria prioritize grass silage for year-round fiber supply, reducing dependency on North American dry hay imports. The EU F-Gas Regulation and REACH framework impose carbon-intensity disclosure requirements on imported baled products. The Münsterland region hosts concentrated feed milling capacity where processors requalify sourcing networks to meet Farm to Fork sustainability thresholds.
Netherlands
High-density dairy operations in Friesland and Gelderland favor ensiled grass and maize silage for consistent fiber quality in robotic milking systems. ECHA pre-market notification requirements for mold inhibitors are shifting procurement toward lower-chemical European-origin forage. The port of Rotterdam serves as a distribution hub where importers consolidate shipments from Irish and German silage suppliers.
Japan
Equine and dairy operations in Hokkaido and northern Honshu demand phytosanitary-certified, weed-seed-free alfalfa with laboratory-tested quality parameters. The Ministry of Agriculture, Forestry and Fisheries enforces strict import inspection protocols for hay shipments. The Tomakomai port zone concentrates customs-clearing infrastructure where specialized inspectors verify phytosanitary compliance before inland distribution.
Roughage Feed Market Competitive Landscape
The competitive structure tilts toward diversified agricultural conglomerates with captive origination networks and specialized forage exporters with phytosanitary certification capabilities. Three archetypes dominate: integrated agribusinesses controlling upstream supply through backward integration, regional hay specialists leveraging geographic proximity to premium dairy markets, and export-focused operators with laboratory-grade quality assurance infrastructure. Capacity consolidation and multi-year contract proliferation represent the dominant competitive moves, as large-scale dairy operators displace spot-market purchasing with embedded quality specifications and price adjustment clauses.
Among North American agricultural conglomerates, ADM and Land O'Lakes, Inc. exemplify the integrated archetype through upstream control over origination networks and direct contracting with growers. Anderson Hay occupies a position within the export-specialist tier, anchoring phytosanitary-grade supply chains serving Asian markets with stringent laboratory-testing requirements.
| Leading Market Players |
|---|
| The VanDrie Group |
| Barenbrug SA |
| Al Dahra ACX, Inc. |
| Purina Mills LLC |
| Feed One |
| AFGRI Animal Feeds |
| Anderson Hay |
| Land O'Lakes, Inc. |
| ADM |
| Others |
Value Network & Pricing Analysis
Phytosanitary-grade certification divergence separates premium alfalfa destined for Japanese dairy and equine markets from commodity bales feeding domestic beef operations, with this quality bifurcation manifesting in both farmgate price multiples and the geographic clustering of testing infrastructure around export corridors.
Pricing Analysis
Bundled laboratory certification and logistics services command substantial premiums over unbundled commodity transactions. Three-tier pricing structure across premium, standard, and economy levels tracks RFV grades, phytosanitary compliance, and volume commitment terms. Pricing pressure stems from fertilizer input volatility compressing grower margins in water-stressed western US production zones. Spot-market buyers in domestic beef channels exhibit highest price sensitivity, while Japanese importers under MAFF protocols demonstrate lowest elasticity.
Supply Chain Analysis
Return flows of rejected bales and reprocessing into pelletized formats create secondary value recovery channels that shape inventory management and quality control investments. Geographic concentration centers on Idaho and California in the US, São Paulo state in Brazil, and Lower Saxony in Germany. Supply chains draw from ammonia-dependent alfalfa cultivation, potash-intensive grass silage programs, and fossil fuel-powered harvesting fleets. Single-source vulnerability concentrates in western US water rights adjudication. Distribution runs through cooperative procurement networks displacing traditional dealer intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Roughage feed procurement operates as a geographic-arbitrage play where EU carbon-intensity thresholds under Farm to Fork create compliance cost differentials against North American originators lacking equivalent certification infrastructure.
For Market Incumbents: Cement multi-year supply contracts with embedded quality specifications to lock in volume commitments before cooperative procurement consolidation eliminates spot-market participation. Invest in backward integration into irrigation-efficient acreage to defend against western US water allocation cuts threatening supply security. Prioritize ECHA pre-market notification completion for mold inhibitors to preserve European channel access. For New Entrants and Emerging Players: The premium-economy price-point gap in phytosanitary-certified hay creates entry opportunity for laboratory-capable regional operators. Target Spanish and Italian goat and sheep automation segments where pelleted roughage adoption outpaces established supply capacity. Pursue direct contracting with Mediterranean robotic feeding system integrators as primary go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where cooperative procurement scale demands supplier balance-sheet capacity beyond regional hay specialist thresholds. Frame long-term viability around carbon farming initiative monetization and methane avoidance credit stacking. Acquire export-specialist operators with captive phytosanitary testing infrastructure. Monitor EU carbon border adjustment mechanism implementation timing as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Irrigation-Efficient Acreage | Snake River Plain and Central Valley land acquisitions secure supply against water rights adjudication. |
| ECHA Pre-Market Notification for Preservatives | REACH compliance preserves Netherlands and Denmark dairy feed import channel access. |
| Pellet Production Capacity Expansion | Automated feeding system compatibility captures Spanish and Italian goat and sheep demand. |
| Carbon Farming Initiative Certification | EU Green Deal methane avoidance credits monetize reduced grain dependency in silage systems. |
| Phytosanitary Laboratory Infrastructure Investment | MAFF-compliant testing capability unlocks Japanese Hokkaido dairy and equine market premiums. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with dairy cooperative procurement directors, alfalfa grower association executives, feed mill operations managers, and regulatory affairs specialists at export-focused processors informed demand-side and supply-side perspectives. Secondary sources include USDA National Agricultural Statistics Service hay production data, EU Farm to Fork strategy implementation documents, ECHA chemical inventory disclosures, and Japanese MAFF import inspection protocols. Bottom-up acreage and yield modeling triangulates against top-down consumption estimates from national dairy herd statistics.
Granularity-level framing applies country-specific production cost structures, regional water stress indices, and phytosanitary certification penetration rates. Segmentation dimensions modeled include feed type, animal species, physical form, and nutritional content tier. CAGRs derive from trend extrapolation of butterfat premium capture rates, cooperative procurement contract proliferation, and robotic feeding system adoption curves across the analysis window. Silage-based feeding program expansion in integrated Brazilian beef-dairy systems and EU carbon farming initiative participation rates serve as industry-specific forecast inputs.
Caveats apply where fertilizer price volatility, water rights adjudication outcomes, or carbon border adjustment mechanism implementation timing could materially shift the outlook. Forecasts reflect assumptions regarding cooperative procurement consolidation velocity and phytosanitary certification capacity expansion. Practitioners should monitor western US state-level water allocation rulings and EU Green Deal secondary legislation publication for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
North America Ruminant Feed Market
Livestock Management
North America Swine Feed Market
Livestock Management
Animal Identification Market
Livestock Management
Feed Management Software Market
Livestock Management
Cattle Management Software Market
Livestock Management
Animal Artificial Insemination Market
Livestock Management
Cattle Feeder Market
Livestock Management
Pig Feed Market
Livestock Management
Livestock Dewormers Market
Livestock Management
South America Ruminant Feed Market
Livestock Management
Beef Cattle Feed and Additives Market
Livestock Management
Poultry Feed Market
Livestock Management
Layer Breeding System Market
Livestock Management
Europe Feed Binders Market
Livestock Management
Saudi Arabia Poultry Market
Livestock Management
Dairy Herd Management Market