
 Poultry Health Market | 2026-2036
Poultry Health Market Size, Share, and Industry Trends Forecast 2026-2036
Poultry Health Market Intelligence
The reliance on broad-spectrum, therapeutic antibiotics is collapsing the distinction between routine health maintenance and outbreak response. Zoetis leverages its extensive portfolio of vaccines and diagnostics to capture value from this preventative shift. Boehringer Ingelheim differentiates through its focus on innovative biologics and integrated health programs for large-scale producers. Ceva Sante Animale competes by specializing in vaccine technologies for hatchery applications.
Poultry health encompasses products and services for preventing, diagnosing, and treating diseases in domesticated birds like chickens and turkeys. Key technologies include recombinant vector vaccines providing multi-pathogen immunity and PCR-based diagnostics for rapid pathogen detection. The vaccines segment commands the largest share, driven by disease prevention strategies within large-scale commercial farms. Feed additives, especially non-antibiotic growth promoters, are expanding quickly to meet regulatory and consumer demands.
Frameworks from the US FDA and Europe's EMA strictly limit antibiotic use, creating market space for vaccines and supplements. Simultaneously, gaining access to markets like China requires adherence to veterinary drug standards set by the NMPA. Stakeholders must now weigh investments in advanced diagnostics against the cost of new preventative health programs to ensure profitability.
Market Dynamics
Intensifying regulatory pressure to phase out antibiotic growth promoters is the central force reconfiguring the poultry health market. This is compelling a structural pivot from therapeutic treatment towards preventative strategies, fundamentally altering product demand and research and development priorities for animal health companies.
Growth Catalysts
- Regulatory Mandates:Policies like the European Union's ban on prophylactic antibiotic use directly stimulate demand for alternatives, particularly for non-antibiotic feed additives and vaccines to maintain flock health and productivity in commercial settings.
- Production Intensification:The expansion of large-scale, vertically integrated poultry operations in countries like Brazil and India necessitates sophisticated disease prevention programs to protect high-density flocks and secure export revenues.
- Advanced Diagnostics:The wider availability of rapid, on-farm diagnostic tools, such as PCR-based assays, enables earlier pathogen detection, facilitating more targeted and effective interventions that reduce economic losses from disease outbreaks.
Market Restraints
- High Cost of Biologics:The significant upfront investment required for advanced vaccines and innovative biologics, compared to cheaper conventional antibiotics, poses a substantial economic barrier for smaller, independent poultry farmers.
- Viral Mutation Rates:The rapid genetic evolution of pathogens like the Avian Influenza virus constantly challenges vaccine efficacy, demanding continuous research and reformulation efforts which increases development costs and timelines.
- Supply Chain Bottlenecks:Production of many poultry vaccines depends on a consistent supply of specific pathogen-free (SPF) eggs, a market dominated by a few specialized suppliers, creating vulnerability to supply disruptions.
Strategic Opportunities
- Geographic Expansion:Markets in Southeast Asia and Africa, where commercial poultry production is rapidly industrializing, represent significant growth opportunities for companies offering integrated health management solutions and vaccine technologies.
- Data-Driven Health Management:Integrating real-time diagnostic data with farm management software allows for the development of predictive analytics models that can anticipate disease risks and optimize preventative health protocols for large flocks.
- Hatchery Automation:Developing automated, in-ovo vaccination technologies offers a key opportunity to improve vaccine delivery consistency, reduce labor dependency, and enhance early-life immunity for commercially raised birds.
Industry Challenges
- Navigating Regulatory Divergence:Producers face significant complexity in managing differing maximum residue limits (MRLs) and approval standards for veterinary drugs and feed additives across major export destinations like the EU, China, and Japan.
- Veterinary Skill Gaps:A shortage of veterinarians and technicians with specialized training in poultry science and modern diagnostics hinders the effective implementation of advanced health programs on commercial farms, particularly in developing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poultry Health Market |
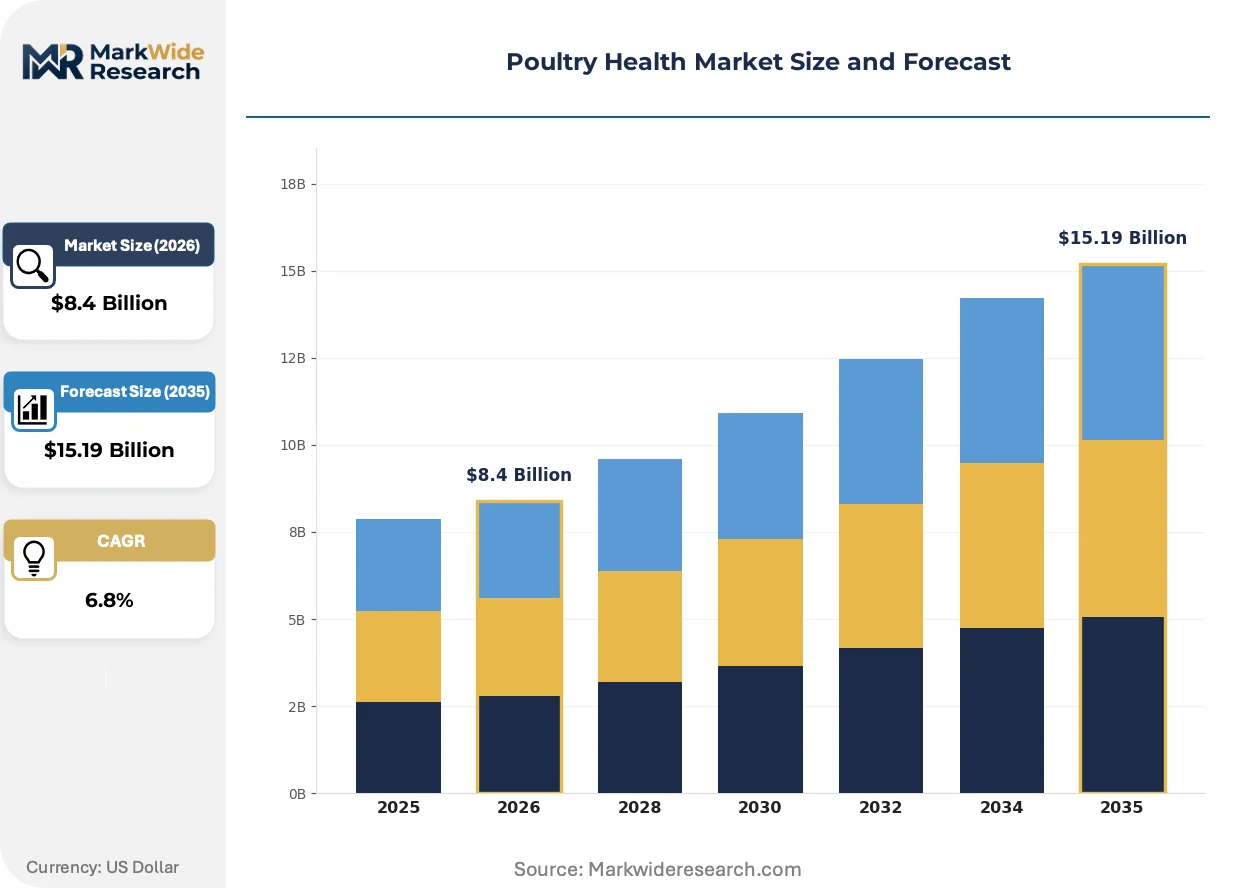
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Antibiotics, Feed Additives, Vitamins & Supplements, Diagnostics Application: Disease Prevention, Growth Promotion, Disease Treatment, Reproductive Health, Immune Support End User: Commercial Farms, Backyard Farmers, Hatcheries, Veterinary Clinics, Research Institutions Distribution Channel: Direct Sales, Pharmacies, Agricultural Cooperatives, E-commerce Platforms, Veterinary Distributors |
| Companies Covered | Boehringer Ingelheim, Zoetis, Merck & Co., Ceva Sante Animale, Elanco, Phibro Animal Health Corporation, Bayer AG, IDEXX Laboratories, Virbac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poultry Health Market Strategic Shifts & Innovations
The poultry health sector is transitioning from a model of reactive disease treatment to one of proactive and predictive flock management. This evolution is driven by the convergence of advanced biotechnology in vaccines and diagnostics with data analytics platforms for large-scale farm operations.
Recombinant vector vaccines are engineered to express antigens from multiple pathogens, conferring broad immunity from a single administration. Large-scale commercial producers in the United States and Brazil are adopting this technology to streamline vaccination schedules and reduce animal handling stress. This multi-pathogen protection technology is displacing the conventional method of administering several separate live attenuated vaccines, simplifying complex hatchery processes.
Regulations from China's National Medical Products Administration (NMPA) are imposing stricter controls on antibiotic usage in animal agriculture to combat antimicrobial resistance. This policy forces producers to overhaul their health management protocols, creating a significant market pull for antibiotic alternatives. The feed additives segment, especially probiotics, prebiotics, and organic acids, is most affected as companies reformulate diets to support gut health and growth without relying on traditional antibiotics.
A notable shift in purchasing behavior involves large poultry integrators moving away from buying individual products toward procuring comprehensive health service packages. This disrupts the traditional role of distributors by bundling customized vaccines, diagnostic surveillance, and performance monitoring into outcome-based contracts. This trend is most advanced in North America, where producers seek to de-risk operations and ensure flock health meets stringent retailer and consumer standards.
Poultry Health Market Segmentation
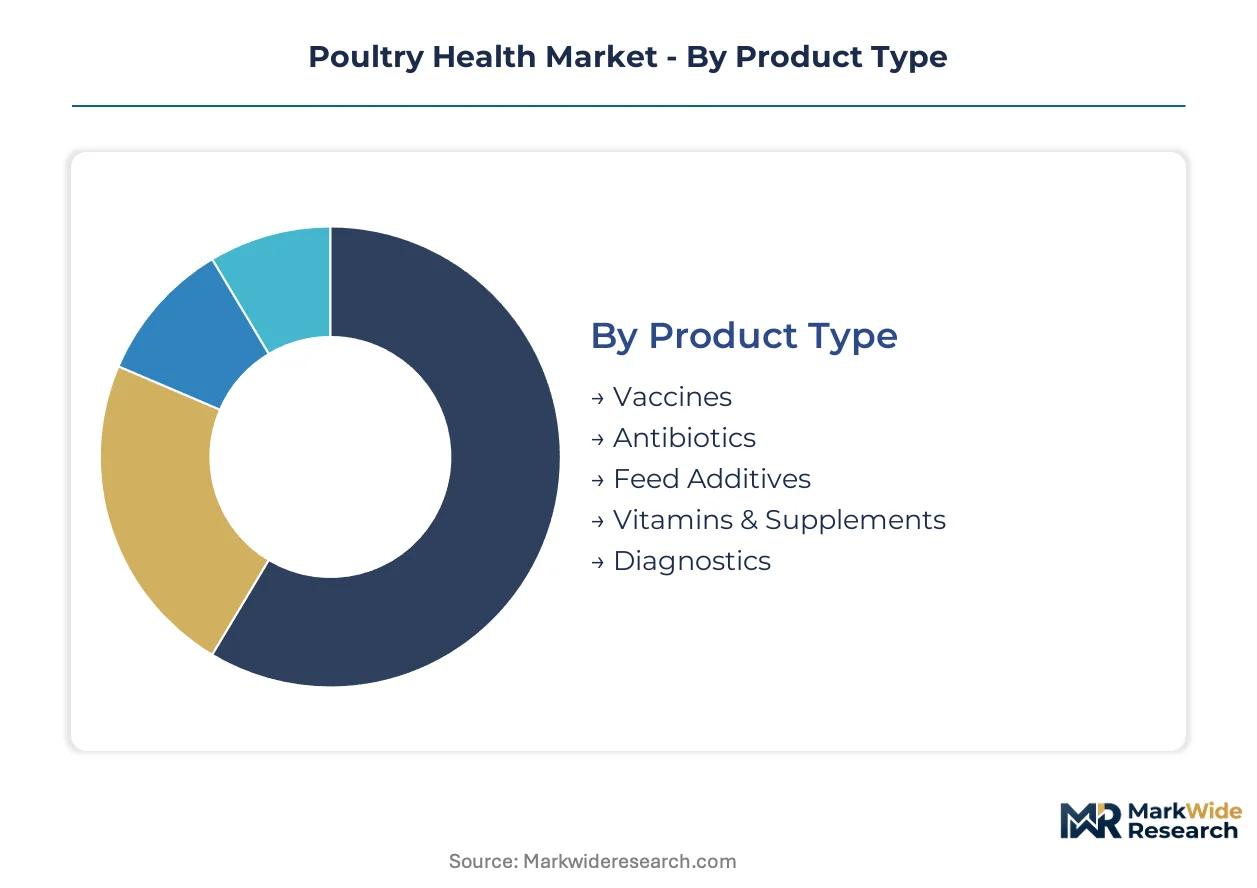
Understanding the distinct segments within the poultry health market is critical for stakeholders to align product development and market entry strategies. This granular analysis reveals specific demand drivers and competitive dynamics across various product types, applications, end users, and distribution channels.
Product Type:
The product type segmentation for poultry health reflects varying degrees of market maturity and regulatory influence across different geographic regions, impacting product development and adoption rates.
- Vaccines:These biological preparations provide active acquired immunity to specific diseases, often through attenuated or inactivated pathogens. Demand for vaccines is accelerating in countries like Brazil and the United States, driven by stringent disease prevention protocols on large commercial farms and regulatory pressure from the FDA and EMA to reduce antibiotic use.
- Feed Additives:These non-nutritive substances enhance feed utilization, growth, or health when added to animal diets. The segment is experiencing rapid expansion in regions like Europe and China, as producers reformulate diets with probiotics, prebiotics, and organic acids to comply with NMPA and EU regulations limiting antibiotic growth promoters.
- Antibiotics:These antimicrobial compounds treat bacterial infections in poultry. Their use is becoming increasingly restricted globally, particularly in developed markets, due to concerns over antimicrobial resistance.
- Vitamins & Supplements:These products provide essential nutrients and boost overall flock health and immunity. They are widely adopted to support bird welfare and productivity, especially during stress periods.
- Diagnostics:Tools and services for identifying diseases and pathogens, including PCR-based assays and serological tests. Rapid diagnostics enable early intervention and targeted treatment strategies on commercial poultry operations.
Vaccines command the established base. The steepest expansion runs through Feed Additives.
Application:
The application segments highlight a strategic shift in investment priorities, moving from reactive, high-cost interventions toward more proactive, cost-effective health management strategies.
- Disease Prevention:This involves proactive measures like vaccination, biosecurity, and nutritional management to prevent disease outbreaks. Large-scale commercial farms prioritize prevention to protect high-density flocks and ensure consistent production.
- Growth Promotion:Strategies and products aimed at enhancing the growth rate and feed conversion efficiency of poultry. This application is increasingly relying on non-antibiotic alternatives due to global regulatory changes and consumer demand.
- Disease Treatment:Therapeutic interventions to cure existing diseases in infected birds. While still necessary for outbreak response, this application is diminishing in prominence compared to preventative approaches due to regulatory mandates.
- Reproductive Health:Focuses on optimizing the fertility, hatchability, and overall reproductive performance of breeder flocks. This is crucial for maintaining a sustainable supply chain in commercial poultry operations.
- Immune Support:Products and practices designed to bolster the natural immune system of birds. These applications reduce susceptibility to various pathogens and improve overall resilience.
Disease Prevention applications are critical for large-scale operations. Growth Promotion alternatives are gaining significant traction.
End User:
The end-user landscape delineates distinct customer needs and purchasing volumes, ranging from large-scale industrial operations to specialized scientific facilities.
- Commercial Farms:Large-scale, industrial poultry operations that produce birds for meat or eggs. These entities represent the largest segment, driving demand for integrated health solutions, advanced vaccines, and diagnostics.
- Hatcheries:Facilities where eggs are incubated and hatched, providing day-old chicks to commercial farms. Hatcheries are key adopters of in-ovo vaccination technologies and early-life immunity programs, particularly in North America.
- Backyard Farmers:Small-scale poultry keepers, often for personal consumption or local sales. This segment typically uses less sophisticated health products and relies on basic preventative measures.
- Veterinary Clinics:Professional animal health facilities providing diagnostic, treatment, and consultation services for poultry. These clinics serve both commercial and backyard farmers, offering specialized expertise.
- Research Institutions:Academic and private organizations conducting studies on poultry diseases, nutrition, and genetics. These institutions drive innovation in new vaccines, diagnostics, and treatment protocols.
Commercial Farms represent the dominant purchasing power. Hatcheries are increasingly central to early-life health interventions.
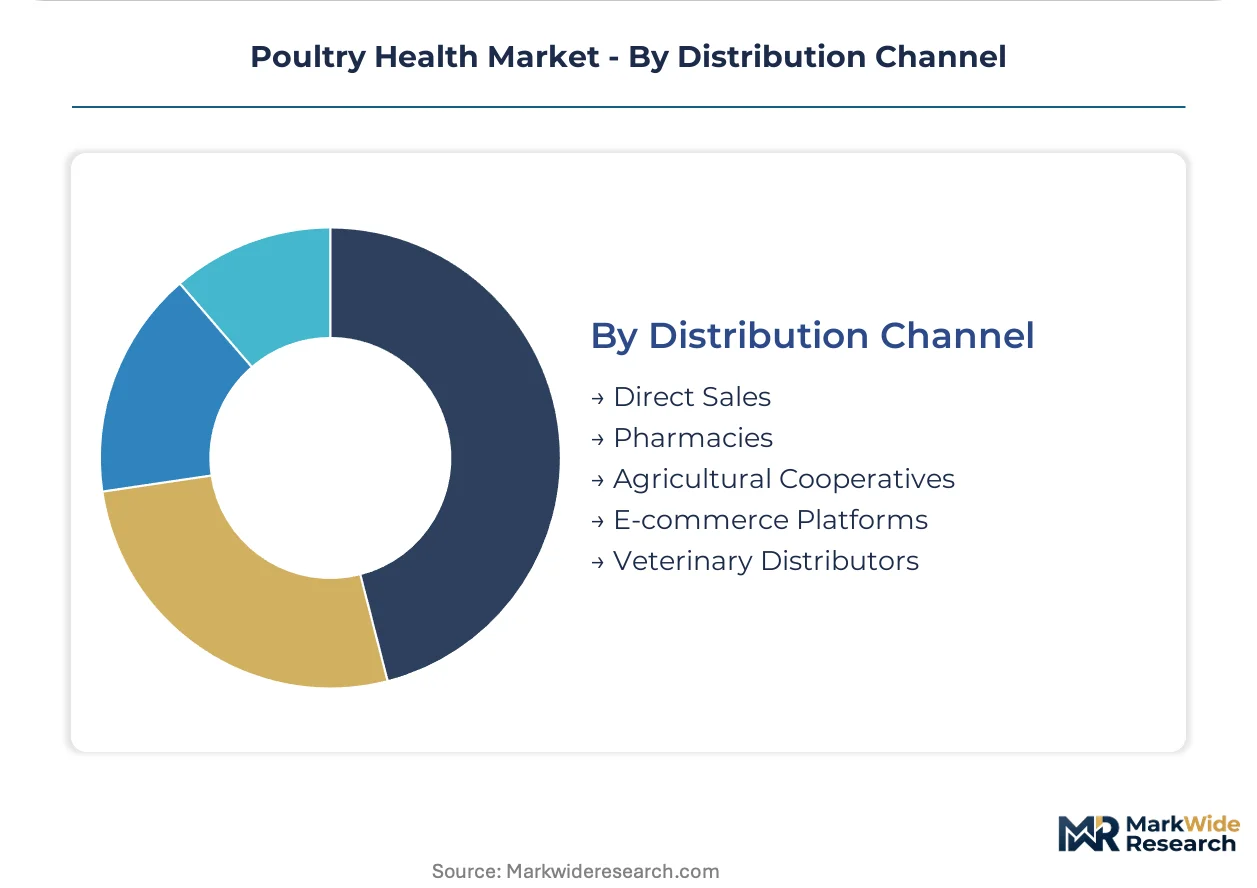
Distribution Channel:
Distribution channels are evolving, with some segments exhibiting high supplier concentration while others are fragmented and undergoing digital transformation.
- Direct Sales:Manufacturers selling products directly to large commercial farms or integrated poultry producers. This channel allows for customized solutions and strong customer relationships, common for advanced biologics.
- Veterinary Distributors:Specialized companies that supply a wide range of animal health products to veterinary clinics and smaller farms. They offer broad market reach and logistical support across diverse geographies.
- Pharmacies:Retail outlets that dispense veterinary medicines, particularly antibiotics and other regulated treatments. This channel often serves smaller farms and individual poultry owners.
- Agricultural Cooperatives:Member-owned organizations that provide various services, including bulk purchasing of poultry health products, to their farmer members. These cooperatives enhance access for independent producers.
- E-commerce Platforms:Online marketplaces offering poultry health products for purchase and delivery. This channel is expanding, providing convenience and wider product selection, especially for smaller-scale buyers.
Direct Sales facilitates strategic partnerships with large integrators. E-commerce Platforms are expanding access for diverse end-users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The poultry health market exhibits varied demand elasticity across regions, with advanced economies and major exporters prioritizing sophisticated preventative solutions, while other regions demonstrate greater price sensitivity for basic health interventions. Regulatory frameworks and production intensification significantly shape regional market dynamics, driving demand for specific product types and health management approaches.
United States
United States commercial poultry operations demand advanced health solutions for large, integrated flocks. The FDA's stringent regulations on antibiotic use continue to drive the adoption of vaccines and non-antibiotic feed additives. Major poultry-producing states in the Southeast, such as Georgia and Arkansas, actively implement comprehensive disease prevention programs.
Brazil
Brazil's position as a leading poultry exporter necessitates robust disease control and prevention strategies. ANVISA's veterinary drug standards ensure product quality for both domestic consumption and international trade. Southern states like Paraná and Santa Catarina are centers for large-scale poultry integrators adopting advanced health management.
China
China's massive poultry industry is undergoing a significant transformation driven by consumer health concerns and regulatory shifts. The NMPA's strict limits on antibiotic growth promoters accelerate the demand for non-antibiotic feed additives. Shandong province, a major poultry hub, actively invests in alternative health solutions for its extensive farms.
Germany
Germany's poultry sector emphasizes high animal welfare standards and disease prevention, aligning with European Union directives. The EMA's rigorous approval process for veterinary medicinal products ensures efficacy and safety for the market. Lower Saxony, a region with dense livestock farming, sees strong uptake of advanced vaccines and biologics.
India
India's rapidly growing commercial poultry production drives increased demand for effective disease management and nutritional supplements. The CDSCO oversees veterinary drug approvals, ensuring product quality in an expanding market. Andhra Pradesh, a key poultry belt, focuses on implementing preventative health programs to support its large-scale farms.
Poultry Health Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the poultry health market. The market exhibits a tiered structure, with large, diversified animal health companies alongside specialized vaccine and feed additive providers. Strategic archetypes include global pharmaceutical giants leveraging existing R&D and focused biotech firms innovating in specific preventative solutions. Companies primarily engage in portfolio diversification, expanding their offerings to cover diagnostics, vaccines, and non-antibiotic feed additives.
Within the advanced animal health sector, Boehringer Ingelheim occupies a position as an innovator in biologics and integrated health programs. Zoetis exemplifies a diversified portfolio approach, leveraging extensive vaccine and diagnostic capabilities to serve large commercial farms. Ceva Sante Animale sits within the specialized vaccine technology segment, particularly focusing on hatchery applications. These companies anchor the market for sophisticated preventative solutions, reflecting the industry's pivot away from therapeutic antibiotics.
| Leading Market Players |
|---|
| Boehringer Ingelheim |
| Zoetis |
| Merck & Co. |
| Ceva Sante Animale |
| Elanco |
| Phibro Animal Health Corporation |
| Bayer AG |
| IDEXX Laboratories |
| Virbac |
| Others |
Cost & Logistics Intelligence
NMPA and EU regulations strictly gate supply qualification and simultaneously drive price differentiation for compliant poultry health products. These regulatory frameworks necessitate significant investment in product development and approval, influencing pricing strategies across the market.
Pricing Analysis
Comprehensive health service packages drive lifetime value for animal health companies in the poultry health market. The dominant pricing structure involves contract-based long-term offtake agreements for large commercial integrators. Price differentiation stems from the certification level of biologics and the customization level of integrated health programs. Pricing pressure stems from large commercial farms seeking cost-efficient preventative solutions. Smaller, independent poultry farmers exhibit the highest price sensitivity for basic health interventions.
Supply Chain Analysis
Maintaining consistent inventory of specific pathogen-free (SPF) eggs is a critical lead-time consideration for vaccine manufacturers. The supply chain for poultry health products concentrates in major production hubs like Brazil, the United States, and specific global suppliers of SPF eggs. Raw material dependencies include specialized antigens for vaccines, specific feed additives, and diagnostic reagents. Single-source vulnerability for SPF eggs constitutes a significant supply chain risk. Direct sales models dominate distribution to large commercial farms, while veterinary distributors serve smaller operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The poultry health market presents a defensive moat story, primarily due to regulatory entrenchment and high switching costs associated with integrated health programs. These structural advantages reinforce market positions for established players.
For Market Incumbents: Secure long-term supply agreements for critical raw materials, such as specific pathogen-free eggs, to mitigate single-source vulnerabilities. Invest heavily in next-generation recombinant vector vaccines that offer multi-pathogen immunity to stay ahead of viral mutation threats. Deepen vertical integration into data analytics platforms to offer predictive health management services, countering emerging biotech firms. Expand market share in rapidly industrializing regions like Southeast Asia through strategic partnerships.
For New Entrants and Emerging Players: Differentiate on advanced data analytics platforms that offer predictive insights for flock health management, moving beyond traditional product sales. Target underpenetrated segments in developing regions, particularly in Africa, with cost-effective, non-antibiotic feed additive solutions. Focus on niche applications, such as novel in-ovo vaccination technologies for hatchery automation. Implement outcome-based contracts with regional integrators as a go-to-market angle.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across the biologics and advanced diagnostics sub-segments, signaling significant R&D investment. The market offers long-term viability driven by sustained global demand for poultry protein. Acquisition targets should prioritize specialized diagnostics providers or biotech firms with novel vaccine platforms. Speed of regulatory approval for new non-antibiotic solutions serves as a critical signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Advancing vaccine candidates through clinical trials ensures regulatory compliance and market access in key geographies. |
| Manufacturing Scale-Up | Scaling production of specific pathogen-free eggs addresses critical supply bottlenecks for vaccine manufacturing. |
| Strategic Partnership | Partnering with data analytics firms enhances predictive flock health management capabilities for large integrators. |
| Geographic Expansion | Expanding operations into Southeast Asia captures growth from rapidly industrializing commercial poultry production. |
| Regulatory Approval Pathway | Navigating NMPA approval for novel feed additives opens access to China's massive poultry market. |
Research Approach
A spread of perspectives from poultry veterinarians, commercial farm managers, animal health R&D directors, and regulatory affairs specialists converged on the working assumptions for this analysis. Primary interviews provided qualitative insights, validated against secondary data from FDA, EMA, and NMPA regulatory filings. Industry association reports and scientific literature on disease prevalence further informed market dynamics, employing both bottom-up and top-down triangulation.
The segmentation dimensions modeled include product type, application, end user, distribution channel, and regional production intensity. An analytical framework derived compound annual growth rates from historical data analysis and projected growth drivers across the analysis window. Industry-specific forecast inputs included poultry population growth rates, disease prevalence trends, and anticipated regulatory changes concerning antibiotic use.
The analysis sits within stated boundaries; outcomes outside unforeseen zoonotic disease outbreaks or major shifts in global trade policies would require recalibration. Forecasts reflect assumptions concerning technological advancements and market acceptance. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Management
North America Swine Feed Market
Livestock Management
South America Ruminant Feed Premix Market
Livestock Management
Beef Cattle Feed and Additives Market
Livestock Management
Europe Ruminant Feed Premix Market
Livestock Management
Cattle Squeeze Market
Livestock Management
Bird Feeder Market
Livestock Management
Swine Feed Market
Livestock Management
Colombia Animal Feed Market
Livestock Management
United States Swine Feed Market
Livestock Management
Animal Feed Protease Market
Livestock Management
Animal Identification Market
Livestock Management
South America Swine Feed Market
Livestock Management
Equine Artificial Insemination Market
Livestock Management
Layer Breeding System Market
Livestock Management
Morocco Poultry Market
Livestock Management
Livestock Dewormers Market