
 Monosodium Glutamate Market | 2026-2036
Monosodium Glutamate Market Size, Share, and Industry Trends Forecast 2026-2036
Monosodium Glutamate Market Intelligence
The gap between premium fermented MSG and commodity-synthetic grades is expanding as food manufacturers reformulate recipes for cleaner labels. Ajinomoto Co., Inc. leverages proprietary fermentation biotechnology to anchor the premium tier with consistent purity specifications. Fufeng Group competes on manufacturing scale, operating some of the world's largest amino acid fermentation facilities in Shandong Province. Meihua Holdings Group Co., Ltd. differentiates through backward integration into corn starch and sugar feedstocks, controlling input costs across volatile agricultural cycles.
Monosodium glutamate is the sodium salt of glutamic acid, typically manufactured through bacterial fermentation of carbohydrate feedstocks such as molasses or corn starch, yielding crystals with purity levels exceeding 99 percent. It functions primarily as a flavor enhancer that amplifies umami perception without contributing distinct taste of its own. Food Grade MSG dominates value capture given its integration into processed foods, instant noodles, and savory seasonings for consumer markets. Pharmaceutical Grade represents the fastest-expanding category as drug formulators adopt MSG as an excipient in parenteral nutrition and tablet binders. Powder form leads volume shipments due to superior dissolution characteristics and packaging efficiency in industrial kitchens.
FDA governs MSG labeling under the Food Allergen Labeling and Consumer Protection Act framework, requiring declaration on packaged foods and shaping reformulation decisions by U.S. processors. EFSA maintains maximum level guidelines for MSG in foodstuffs, while China's SAMR enforces GB standards for fermentation purity and contaminant thresholds that determine export eligibility. Stakeholders must monitor evolving clean-label certifications and regional purity mandates that increasingly bifurcate acceptable specifications between premium and commodity supply tiers.
Market Dynamics
Fermentation technology maturation in Shandong Province and Hebei Province concentrates global MSG supply capacity, while clean-label reformulation mandates from FDA and EFSA bifurcate demand into premium purity tiers versus commodity grades.
Growth Catalysts
- Instant Noodle Industrialization:Southeast Asian food processors integrate MSG into standardized seasoning packets for mass-market distribution, creating steady volume pull from Thailand, Indonesia, and Vietnam manufacturing clusters.
- EFSA Purity Guidelines:Maximum level frameworks for foodstuffs drive manufacturers toward fermented grades with documented contaminant thresholds, rewarding facilities with certified fermentation biotechnology.
- Corn Starch Feedstock Abundance:North American and Chinese agricultural surplus lowers input cost volatility for carbohydrate-based bacterial fermentation, stabilizing production economics across agricultural cycles.
Market Restraints
- Molasses Price Volatility:Sugar cane harvest fluctuations in Brazil and India transmit directly to fermentation input costs, compressing margins for facilities without captive starch alternatives.
- Shandong Supply Concentration:Amino acid fermentation capacity clustering in eastern China creates geographic risk exposure to regional energy rationing, environmental enforcement actions, and logistics bottlenecks.
- Yeast Extract Substitution:Natural umami alternatives gain traction in European clean-label formulations, displacing synthetic MSG in premium sauce and seasoning applications.
Strategic Opportunities
- Pharmaceutical Excipient Expansion:Parenteral nutrition and tablet binder applications represent underpenetrated demand within drug formulation, with USP-grade specifications commanding purity premiums over food-grade equivalents.
- US FDA Labeling Clarity:Food Allergen Labeling and Consumer Protection Act declaration requirements create competitive advantage for fermented-origin MSG with documented non-GMO and allergen-free certification chains.
- E-commerce Bulk Procurement:Industrial kitchens and mid-scale processors in India and Brazil bypass traditional distributor networks through platform-based direct sourcing, reducing working capital requirements.
Industry Challenges
- Fermentation Biologist Scarcity:Industrial microbiology and process optimization expertise concentrates at legacy amino acid facilities, constraining new entrant scale-up timelines and technology transfer success rates.
- GB Standard Certification Lag:China's SAMR export eligibility protocols require extended laboratory validation cycles, delaying market access for facilities upgrading from domestic-only to international purity specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Monosodium Glutamate Market |
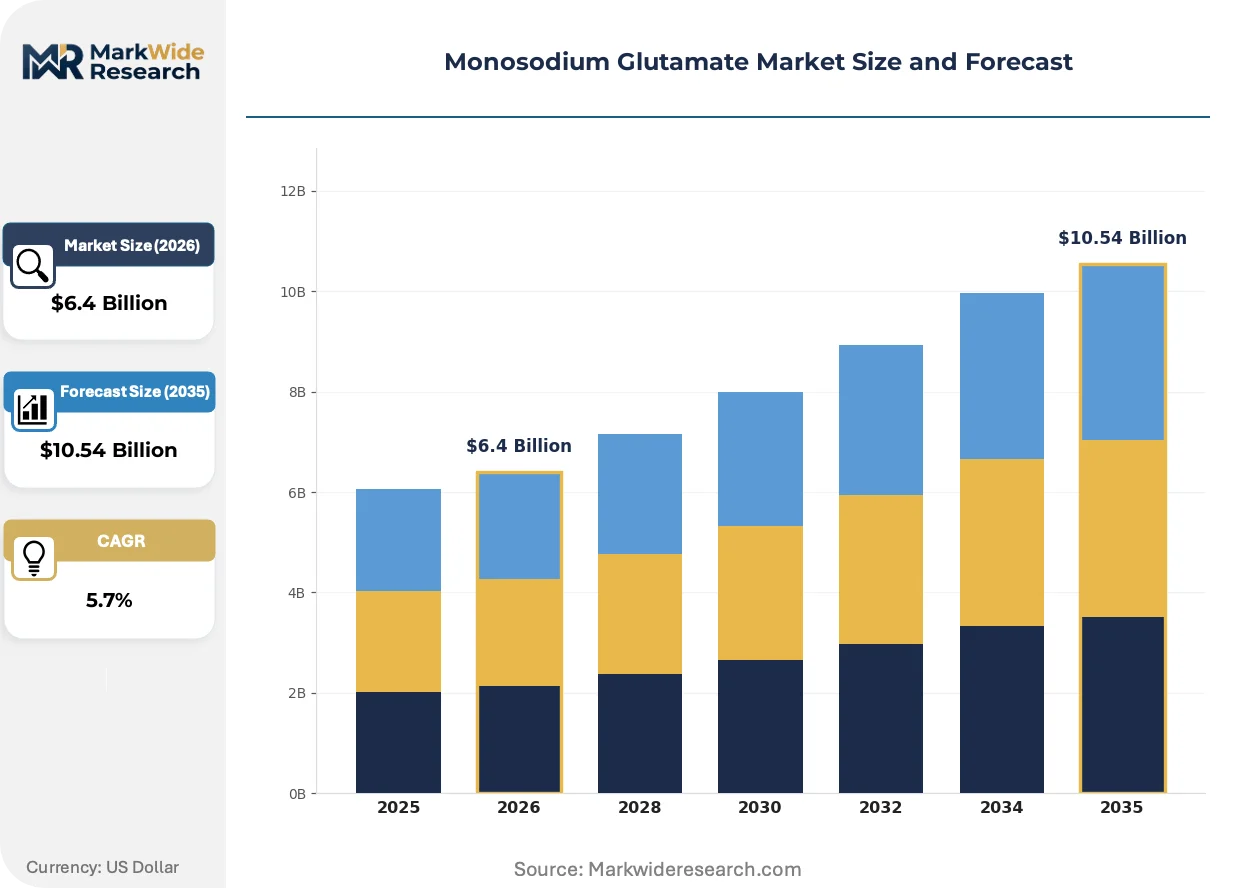
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $10.54 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Feed Grade, Pharmaceutical Grade, Industrial Grade Form: Granular, Powder, Liquid, Crystal End User: Food Industry, Animal Feed, Pharmaceuticals, Cosmetics Application: Flavoring Agent, Preservative, Enhancer, Nutritional Additive |
| Companies Covered | Ajinomoto Co., Inc., Fufeng Group, Meihua Holdings Group Co., Ltd., Ningxia Eppen Biotech Co., Ltd., COFCO, Vedan International (Holdings) Limited, Cargill Incorporated, Kerry Group, Shandong Qilu Biotechnology Group Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Monosodium Glutamate Market Strategic Shifts & Innovations
Continuous fermentation monitoring systems and biosensor integration are compressing batch-to-batch variability, enabling real-time purity adjustment that satisfies tightening pharmaceutical and food-grade specifications simultaneously.
Electrochemical biosensors embedded in fermentation vessels is electrifying process control precision for glutamic acid conversion efficiency. Ajinomoto and Fufeng Group deploy these systems at commercial scale, reducing off-spec product rates and energy intensity per ton of crystalline output. This capability gap separates integrated biotech operators from commodity assemblers dependent on offline quality testing.
REACH registration requirements for food-contact substances are tightening contaminant documentation burdens on European imports. Facilities without full supply chain chemical disclosure face exclusion from formulated food manufacturing contracts, redirecting procurement toward SAMR-certified Chinese exporters with pre-validated dossiers. Pharmaceutical-grade specifications now migrate into premium food applications as a defensive compliance posture.
Specification-driven procurement now dominates industrial buyer behavior, with instant noodle manufacturers and savory seasoning compounders demanding certificate-of-analysis documentation for every lot. Traditional spot-market purchasing through trading houses loses share to direct mill relationships with embedded quality assurance protocols, compressing intermediary margins across Southeast Asian distribution channels. Thailand and Vietnam processors lead this transition, leveraging scale to negotiate vendor-managed inventory arrangements.
Monosodium Glutamate Market Segmentation
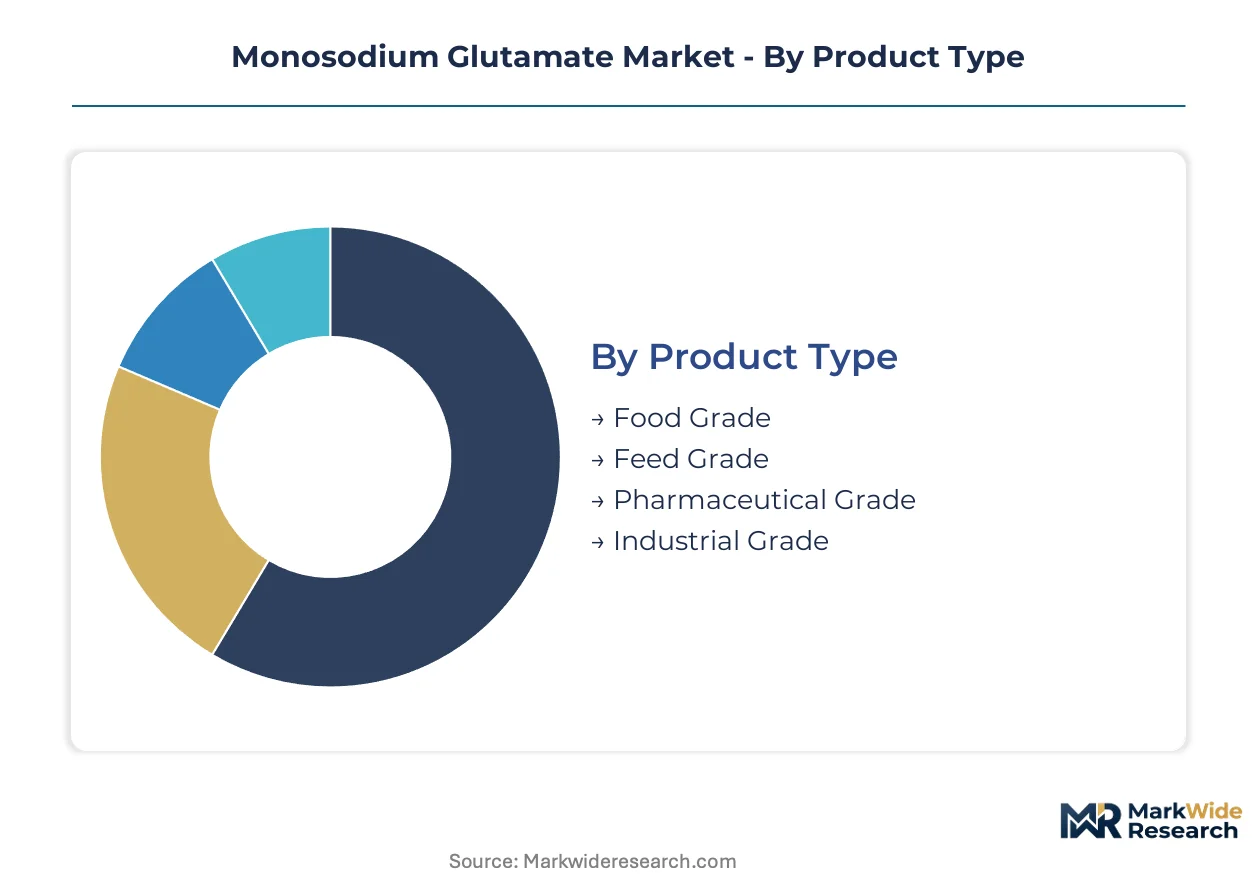
Monosodium glutamate manufacturers configure production lines around purity thresholds and dissolution requirements that vary sharply across buyer categories. Specification-driven procurement now dominates, with food processors, pharmaceutical formulators, and feed compounders each demanding distinct certificate-of-analysis documentation.
Product Type:
Buyers in this category separate by contamination tolerance and regulatory documentation burden rather than unit economics alone.
- Food Grade:Crystalline sodium glutamate meeting FCC and GB standards for fermentation purity dominates procurement volumes from instant noodle manufacturers and savory seasoning compounders across Southeast Asia. Thai and Indonesian processors integrate this grade into standardized seasoning packets where consistent umami intensity reduces batch-to-batch reformulation costs.
- Pharmaceutical Grade:USP-grade specifications with documented endotoxin limits and heavy metal thresholds command substantial purity premiums over food-grade equivalents. Parenteral nutrition formulators in the United States and tablet binder applications in Europe drive adoption as drug manufacturers seek excipients with pre-validated regulatory dossiers.
- Feed Grade:Lower purity specifications acceptable for animal nutrition applications, primarily serving poultry and swine feed compounders seeking palatability enhancement.
- Industrial Grade:Technical specifications for non-food chemical synthesis and industrial fermentation feedstock applications.
Volume sits with Food Grade; growth tilts toward Pharmaceutical Grade.
Form:
Industrial kitchens and automated manufacturing lines select dissolution speed and packaging density as primary technical filters.
- Powder:Superior dissolution characteristics and packaging efficiency dominate volume shipments to industrial kitchens and mid-scale processors. Southeast Asian instant noodle manufacturers specify powder form for rapid integration into aqueous seasoning slurries without mechanical dispersion equipment.
- Granular:Reduced dust generation and improved flowability suit automated dosing systems in large-scale seasoning compound operations. Brazilian and Indian processors increasingly specify granular form for pneumatic conveying systems that minimize workplace exposure and cross-contamination risk.
- Liquid:Pre-dissolved solutions for ready-to-use sauce and broth applications where hydration time constraints eliminate solid-phase handling.
- Crystal:Visual purity signaling for premium retail packaging and specialty culinary applications.
Procurement concentrates in Powder; specification migration favors Granular.
End User:
Regulatory jurisdiction and clean-label positioning requirements create divergent sourcing strategies across buyer verticals.
- Food Industry:Processed food manufacturers, instant noodle producers, and savory seasoning compounders generate the dominant demand pull. EFSA maximum level guidelines and FDA Food Allergen Labeling requirements drive reformulation toward fermented-origin grades with documented non-GMO certification chains.
- Animal Feed:Poultry and swine nutritionists deploy MSG as a palatability enhancer in high-density feed formulations where intake stimulation improves feed conversion ratios.
- Pharmaceuticals:Drug formulators expanding parenteral nutrition and solid dosage applications require USP-grade specifications with validated endotoxin and bioburden documentation.
- Cosmetics:Niche applications in personal care formulations leveraging humectant and skin-conditioning properties.
Demand anchors in Food Industry; steepest expansion trajectory runs through Pharmaceuticals.
Application:
Functional role in formulation determines purity requirements and regulatory scrutiny intensity.
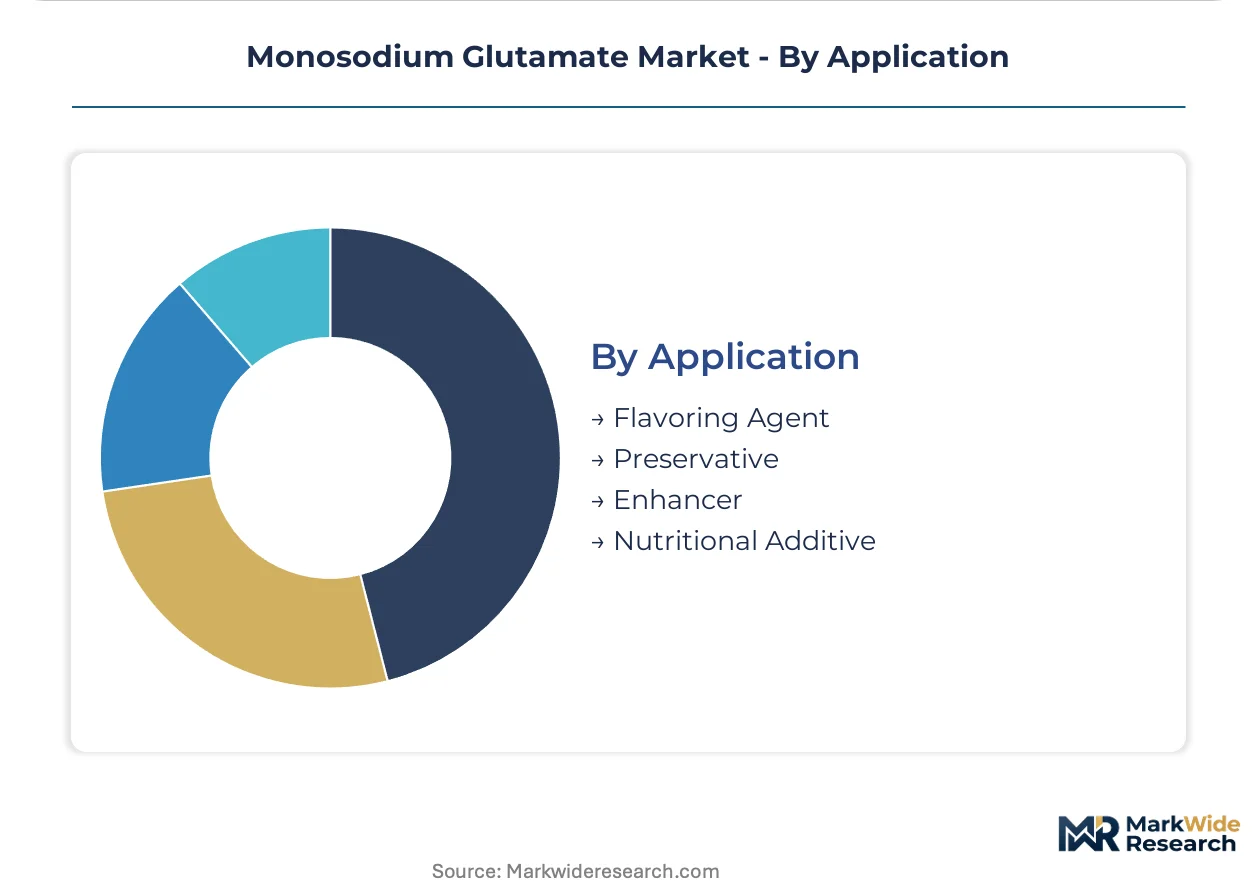
- Flavoring Agent:Primary umami amplification function in processed foods, instant noodles, and savory seasonings without contributing distinct taste of its own. Southeast Asian food processors standardize on this application for mass-market distribution where consistent sensory performance reduces consumer rejection rates.
- Nutritional Additive:Glutamate bioavailability applications in specialized nutrition and clinical feeding protocols where sodium-controlled formulations require precise amino acid supplementation.
- Preservative:Secondary antimicrobial synergy in high-moisture food systems.
- Enhancer:Synergistic amplification of other flavor compounds in complex seasoning matrices.
Deployment concentrates in Flavoring Agent; specification evolution favors Nutritional Additive.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong Province's fermentation corridor concentrates over half of global MSG manufacturing capacity, with Weifang and Jinan industrial clusters anchoring amino acid production networks that feed processors across Southeast Asia, North America, and Europe.
China
Instant noodle industrialization and savory seasoning mass production drive procurement volumes from Thai and Indonesian food processors. SAMR enforces GB standards for fermentation purity and contaminant thresholds that determine export eligibility for facilities in Hebei and Shandong provinces. The Shandong Peninsula fermentation belt faces periodic energy rationing and environmental enforcement actions that disrupt supply continuity.
United States
Pharmaceutical formulators expanding parenteral nutrition applications generate demand pull for USP-grade specifications with validated endotoxin documentation. FDA governs MSG labeling under the Food Allergen Labeling and Consumer Protection Act framework, requiring declaration on packaged foods and shaping reformulation decisions by domestic processors. New Jersey and Illinois pharmaceutical corridors host excipient compounders integrating MSG into tablet binder and clinical nutrition formulations.
Thailand
Standardized seasoning packet production for mass-market instant noodle distribution creates steady volume demand from integrated food manufacturing complexes. The country's national food safety regulator aligns with Codex Alimentarius frameworks while enforcing local purity mandates for imported fermentation inputs. Bangkok-Perimeter industrial zones host seasoning compounders that specify powder-form MSG for rapid aqueous slurry integration.
Germany
Clean-label sauce and seasoning reformulation drives displacement of synthetic MSG by yeast extract alternatives in premium European formulations. EFSA maximum level guidelines for foodstuffs shape manufacturer procurement toward fermented grades with documented contaminant thresholds. North Rhine-Westphalia's food processing belt hosts seasoning innovators testing natural umami substitutes in reduced-sodium product lines.
Brazil
Mid-scale industrial kitchens and meat processing facilities expand MSG utilization for palatability enhancement in high-volume foodservice operations. ANVISA governs food additive safety assessments and labeling requirements that influence import sourcing from Chinese fermentation facilities. São Paulo state's food manufacturing corridor drives granular-form specification for pneumatic conveying systems that minimize workplace exposure.
Monosodium Glutamate Market Key Industry Players
Premium-margin players sit above commodity-margin players across purity certification and fermentation technology dimensions, with three-tier competitive separation between integrated biotech operators, scale-driven fermenters, and trading-dependent assemblers. The vendor base clusters around fermentation biotechnology ownership versus feedstock control versus distribution reach. Strategic archetypes include backward-integrated agricultural processors, proprietary fermentation technology licensors, and specification-focused pharmaceutical excipient suppliers. Dominant competitive moves encompass capacity expansion in Shandong and Hebei provinces, plus technology licensing partnerships that transfer continuous fermentation monitoring capabilities.
Among Japanese and Chinese fermentation specialists, Ajinomoto Co., Inc., Fufeng Group, and Meihua Holdings Group Co., Ltd. occupy positions across the premium-to-commodity spectrum. Ajinomoto represents the proprietary biotechnology archetype with documented non-GMO certification chains. Fufeng exemplifies scale-driven manufacturing concentration within Shandong Province's amino acid corridor. Meihua Holdings anchors feedstock-integrated positioning through upstream control over corn starch and sugar inputs. Ningxia Eppen Biotech Co., Ltd. and Vedan International (Holdings) Limited sit within regional specialist tiers serving domestic and neighboring markets.
| Leading Market Players |
|---|
| Ajinomoto Co., Inc. |
| Fufeng Group |
| Meihua Holdings Group Co., Ltd. |
| Ningxia Eppen Biotech Co., Ltd. |
| COFCO |
| Vedan International (Holdings) Limited |
| Cargill Incorporated |
| Kerry Group |
| Shandong Qilu Biotechnology Group Co. |
| Others |
Cost & Logistics Intelligence
Continuous fermentation monitoring systems are compressing batch-to-batch variability while simultaneously concentrating production economics among facilities with capital-intensive biosensor integration. This technological bifurcation rewards integrated biotech operators with documented purity certification chains while marginalizing commodity assemblers dependent on offline quality testing.
Pricing Analysis
USP-grade purity specifications with validated endotoxin documentation anchor price premiums over food-grade equivalents. Three-tier pricing structure across pharmaceutical, premium food, and commodity fermentation grades reflects certification burden and contaminant threshold documentation. Pricing pressure stems from yeast extract substitution in European clean-label formulations. Pharmaceutical formulators show lowest price sensitivity given regulatory validation requirements, while instant noodle manufacturers in Southeast Asia prioritize volume scale over purity premiums.
Supply Chain Analysis
Single-source vulnerability sits with Shandong Province's amino acid fermentation corridor, where Weifang and Jinan industrial clusters concentrate over half of global crystalline output. Corn starch and molasses feedstocks draw from North American agricultural surplus and Brazilian sugar cane harvests respectively. Tariff exposure on Chinese fermentation exports to North American pharmaceutical formulators creates procurement uncertainty. Distribution runs through direct mill relationships with embedded quality assurance protocols, compressing traditional trading house margins across Southeast Asian channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where clean-label certification mandates and fermentation technology gaps force commodity-grade assemblers toward acquisition or exit.
For Market Incumbents: Anchor defensive positioning through backward integration into corn starch feedstocks and continuous fermentation monitoring deployment. Yeast extract substitution in European premium formulations threatens volume share; counter with USP-grade certification investment for pharmaceutical excipient expansion. Prioritize capacity addition in Hebei Province to diversify beyond Shandong concentration risk. For New Entrants and Emerging Players: Mid-scale Brazilian and Indian industrial kitchens bypassing distributor networks represent underserved buyer archetypes with platform-based procurement preferences. Pharmaceutical-grade specifications for parenteral nutrition applications offer the most penetrable segment given validated endotoxin documentation scarcity. Pursue go-to-market angles through e-commerce bulk procurement platforms with embedded certificate-of-analysis transparency. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated biotech operators seeking fermentation technology transfer and SAMR-certified export infrastructure. Long-term viability favors facilities with captive feedstock control and real-time purity adjustment capabilities. Watch for GB standard certification lag resolution as inflection indicator for international market access scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Fermentation Monitoring Deployment | Biosensor integration at Ajinomoto and Fufeng Group facilities reduces off-spec product rates and energy intensity per ton. |
| Backward Integration into Corn Starch Feedstocks | Meihua Holdings controls input costs across volatile agricultural cycles through upstream agricultural processing ownership. |
| USP-Grade Certification Investment | Pharmaceutical excipient specifications command purity premiums over food-grade equivalents in parenteral nutrition applications. |
| Direct Mill Relationship Development | Thai and Vietnamese processors negotiate vendor-managed inventory arrangements that compress intermediary distribution margins. |
| Hebei Province Capacity Diversification | Geographic expansion beyond Shandong fermentation corridor mitigates energy rationing and environmental enforcement disruption risk. |
Research Approach
Trade databases, SAMR regulatory filings, and fermentation technology patent records formed the secondary backbone of this analysis. Primary interviews with plant managers at Shandong and Hebei Province facilities, procurement leads at Thai instant noodle manufacturers, and pharmaceutical excipient compounders in New Jersey and Illinois validated secondary findings. Bottom-up volume estimates from individual facility capacities and top-down demand calibration from end-use consumption patterns were triangulated for cross-verification.
Historical trendline analysis of amino acid fermentation output and instant noodle seasoning packet production established baseline growth trajectories across the projection horizon. The analytical framework modeled segmentation dimensions including product grade tier, crystalline form factor, and end-use vertical. CAGRs were derived from regression analysis of purity premium expansion and pharmaceutical excipient adoption curves. Forecast inputs incorporated EFSA maximum level guideline evolution and FDA Food Allergen Labeling enforcement patterns.
Revisions become necessary when molasses price volatility exceeds historical bands or when SAMR export eligibility protocols extend laboratory validation cycles beyond typical durations. Forecasts reflect documented assumptions regarding fermentation biotechnology maturation and clean-label certification penetration. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
North America Feed Additives Market
Food Additives and Ingredients
Mexico Food Additives Market
Food Additives and Ingredients
France Food Enzymes Market
Food Additives and Ingredients
Food Binders Market
Food Additives and Ingredients
Carrageenan Gum Market
Food Additives and Ingredients
Russia Food Enzymes Market
Food Additives and Ingredients
Agar Agar Gum Market
Food Additives and Ingredients
Germany Anticaking Market
Food Additives and Ingredients
Fruit Ripening Agents Market
Food Additives and Ingredients
Amaranth (E123) Market
Food Additives and Ingredients
Food Grade Sodium Selenite Market
Food Additives and Ingredients
Quillaja Saponaria Ingredient Market
Food Additives and Ingredients
Mexico Food Emulsifiers Market
Food Additives and Ingredients
South Africa Food Enzymes Market
Food Additives and Ingredients
China Food Preservatives Market
Food Additives and Ingredients
Distilled Monoglycerides Market