
 Mexico Food Additives Market | 2026-2036
Mexico Food Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Food Additives Market Foresight
Software-defined formulation services is shifting how additive portfolios reach Mexican food manufacturers. Cargill Incorporated leverages its Guadalajara technical center to anchor custom premix development for regional tortilla and snack producers. Kerry Group plc competes through taste and nutrition integration, while Chr. Hansen A/S specializes in natural color and culture systems for dairy applications.
Food additives comprise functional substances—preservatives, emulsifiers, colorants, and flavor enhancers—added to processed foods at concentrations typically below one percent by weight to extend shelf stability, modify texture, or standardize sensory profiles. Preservatives dominate current volume as Mexican beverage and bakery producers combat tropical climate spoilage risks. Flavor enhancers represent the fastest-expanding margin pool, driven by sodium-reduction reformulations in instant noodle and seasoning categories.
COFEPRIS maintains additive approval lists and maximum usage limits under NOM-051 labeling standards, while SENASICA enforces residue controls for export-bound products. These frameworks compel manufacturers to document supply chain provenance and reformulate around restricted synthetics. Stakeholders must monitor pending clean-label regulatory consultations that could delist artificial colorants from infant and school food categories.
Market Dynamics
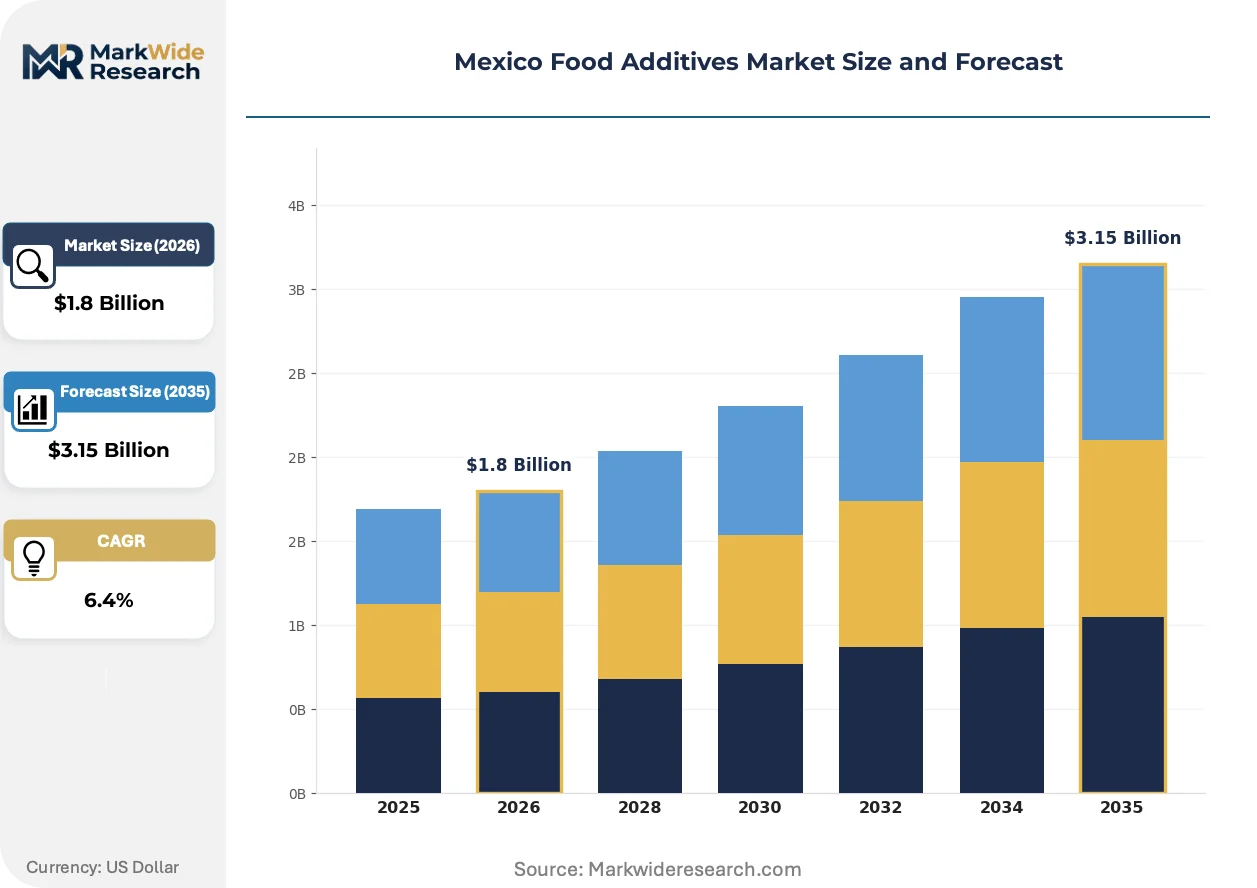
COFEPRIS enforcement of NOM-051 labeling standards is compressing formulation timelines for Mexican food manufacturers. Clean-label mandates are forcing reformulation of legacy portfolios while tropical climate conditions sustain baseline demand for shelf-stability solutions.
Growth Catalysts
- Processed meat expansion:Jalisco-based poultry processors are scaling additive-intensive curing and preservation systems to serve export contracts. COFEPRIS residue protocols align with SENASICA export requirements, streamlining dual-compliance.
- Clean-label regulatory tailwind:Pending COFEPRIS consultations on artificial colorant restrictions in infant foods are accelerating natural colorant qualification programs. Reformulation service providers are capturing margin from technical support contracts.
- Tropical climate spoilage risk:Nuevo León beverage and bakery clusters face accelerated microbial degradation. Preservative demand concentrates in high-humidity production zones where ambient storage conditions degrade unprotected formulations.
Market Restraints
- Import dependency for specialty inputs:Natural colorants and high-purity emulsifiers concentrate in European and US supplier bases. Tariff exposure and currency volatility compress margin predictability for Mexican formulators.
- Technical limitation in natural preservation:Clean-label antimicrobials lack the broad-spectrum efficacy of synthetic alternatives. Reformulated products exhibit shorter shelf stability, constraining distribution radius for regional brands.
- Regulatory friction from dual-track compliance:COFEPRIS domestic standards diverge from FDA and EFSA export requirements. Manufacturers serving both markets face duplicated testing and documentation burdens.
Strategic Opportunities
- Underpenetrated northern border states:Chihuahua and Sonora industrial food production lags Jalisco and Nuevo León in additive sophistication. Cross-border supply chain integration with US Southwest processors creates technical upgrade demand.
- Regulatory tailwind from school food mandates:COFEPRIS proposals to restrict artificial additives in federally subsidized school nutrition programs would create mandated replacement demand. Natural flavor and color systems would capture protected procurement channels.
- Technology convergence in encapsulation:Lipid and polymer encapsulation systems are converging with precision fermentation-derived actives. Combined platforms enable targeted release of sensitive bioactives in tropical distribution conditions.
Industry Challenges
- Reformulation technical talent scarcity:Food chemistry specialists with dual expertise in regulatory compliance and sensory science command premium compensation. Jalisco technical centers face recruitment competition from multinational R&D operations.
- Legacy equipment incompatibility:Natural emulsifiers and hydrocolloids require modified shear and temperature parameters. Capital retrofit costs delay clean-label transitions for mid-scale tortilla and snack producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Food Additives Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Preservatives, Flavor Enhancers, Colorants, Emulsifiers Application: Beverages, Bakery, Confectionery, Dairy End User: Food Manufacturers, Restaurants, Home Cooks, Caterers Distribution Channel: Online Retail, Supermarkets, Wholesalers, Distributors |
| Companies Covered | DuPont de Nemours Inc., The Archer Daniels Midland Company, Cargill Incorporated, Ingredion Inc., Kerry Group plc, Chr. Hansen A/S, Tate & Lyle PLC, Brenntag AG, Koninklijke DSM N.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Food Additives Market Shifts & Advancements
Biotechnology-derived functional ingredients are displacing petroleum-based synthetics in Mexican formulation portfolios. Encapsulation and fermentation platforms are converging to address stability challenges in tropical supply chains.
Precision fermentation for natural preservatives is absorbing capital allocation from chemical synthesis investments. Guadalajara-area beverage manufacturers are piloting postbiotic antimicrobial systems at commercial scale. This technology is absorbing market share from traditional benzoate and sorbate applications as COFEPRIS scrutiny intensifies on synthetic residue labeling.
COFEPRIS alignment consultations with Codex Alimentarius standards are harmonizing maximum usage limits for cross-border products. Mexican exporters to the US face simplified dual-compliance documentation under streamlined residue testing protocols. Dairy and processed meat segments are accelerating qualification of GRAS-notified ingredients to preempt regulatory divergence.
Direct technical service contracts are displacing traditional distributor-mediated additive procurement. Nuevo León snack manufacturers are engaging formulation houses for embedded R&D partnerships rather than transactional ingredient purchasing. Jalisco tortilla producers exhibit the most advanced adoption of co-development models with premix suppliers.
Mexico Food Additives Market Segmentation
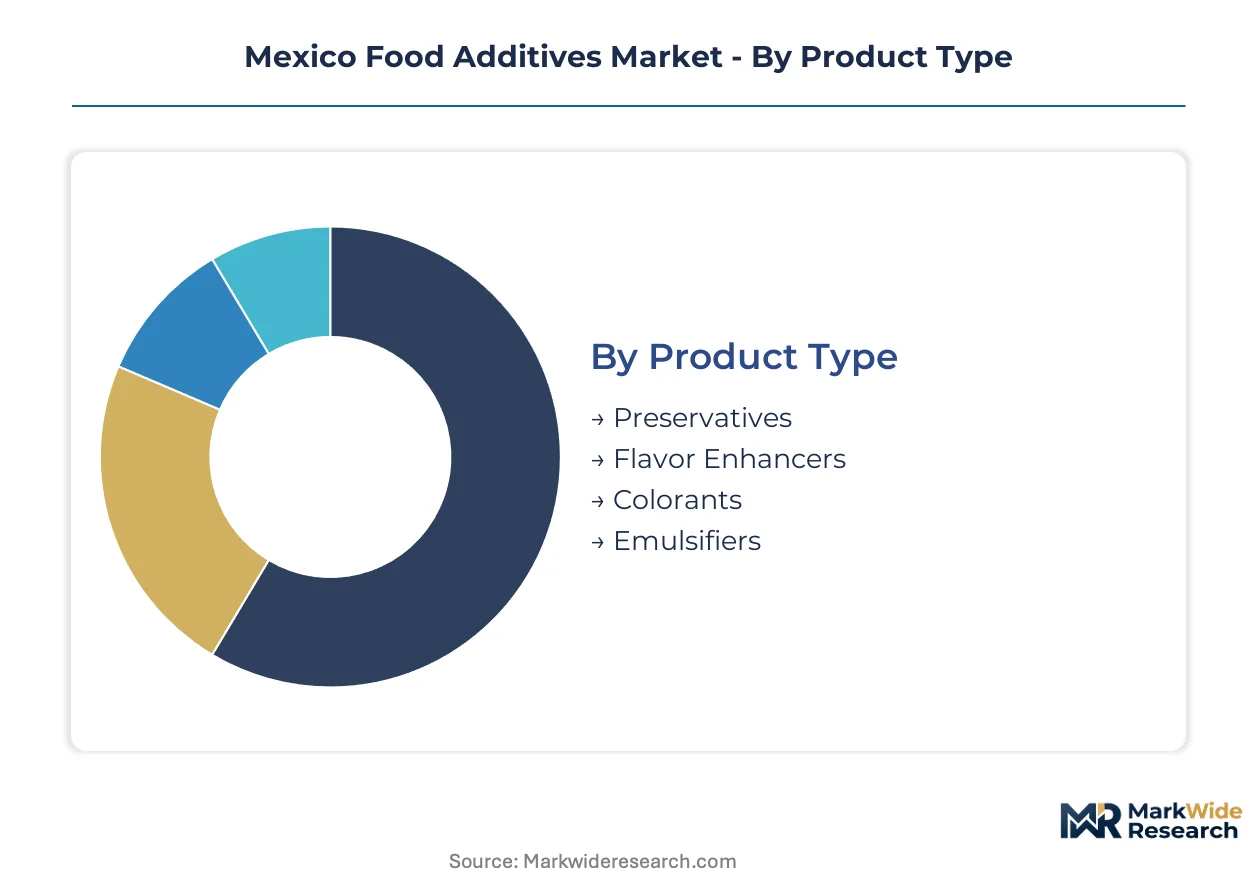
COFEPRIS regulatory tiers and tropical climate requirements create divergent demand profiles across additive categories. Manufacturers segment procurement strategies between mass-market shelf-stability solutions and premium clean-label qualifications serving export contracts.
Product Type:
Volume concentrates in synthetic preservation systems, while premium margins concentrate in natural replacement technologies.
- Preservatives:Benzoates and sorbates dominate current procurement volumes among Nuevo León beverage processors combating high-humidity spoilage. Tropical storage conditions sustain baseline demand despite COFEPRIS pressure on residue labeling.
- Flavor Enhancers:Sodium-reduction reformulations in Jalisco-based instant noodle and seasoning production represent the steepest expansion trajectory. Yeast extracts and nucleotides displace monosodium glutamate in clean-label portfolios.
- Colorants:Carmine, annatto, and turmeric systems absorb migration demand from synthetic azo dyes. Infant food restrictions accelerate natural qualification timelines.
- Emulsifiers:Lecithin and mono-diglyceride blends serve tortilla and snack texture modification. Shear-sensitive natural alternatives require equipment retrofit investment.
Today's leader: Preservatives. Tomorrow's challenger: Flavor enhancers.
Application:
Commercial significance clusters around ambient-stable categories where climate risk intersects with export opportunity.
- Beverages:Carbonated and juice processors in Jalisco deploy acidulants and antimicrobial blends for extended ambient distribution. COFEPRIS maximum usage limits constrain formulation flexibility.
- Bakery:Mold inhibitors and crumb softeners address accelerated staling in tropical retail conditions. Nuevo León industrial bakeries drive emulsifier procurement scale.
- Confectionery:Glazing agents and acid regulators standardize shelf appearance across humidity-variable supply chains. Natural color migration lags other categories due to heat stability requirements.
- Dairy:Cultures and stabilizers support Chihuahua cheese production clusters. Chr. Hansen technical service contracts concentrate in this application.
Beverages command current volume leadership; dairy posts the strongest clean-label premium capture.
End User:
Procurement sophistication stratifies between industrial scale and fragmented foodservice operations.
- Food Manufacturers:Integrated premix procurement and embedded R&D partnerships characterize Jalisco tortilla and snack producers. Direct technical service contracts displace distributor relationships.
- Restaurants:Chain operators standardize seasoning and sauce bases through centralized procurement. Clean-label menu claims drive additive specification upgrades.
- Home Cooks:Retail-packaged seasoning blends and colorants serve traditional preparation needs. Supermarket penetration concentrates in urban centers.
- Caterers:Institutional volume demands shelf-stable prepared components. School nutrition procurement faces pending artificial additive restrictions.
Food manufacturers anchor current value; restaurants represent the fastest-climbing service segment.
Distribution Channel:
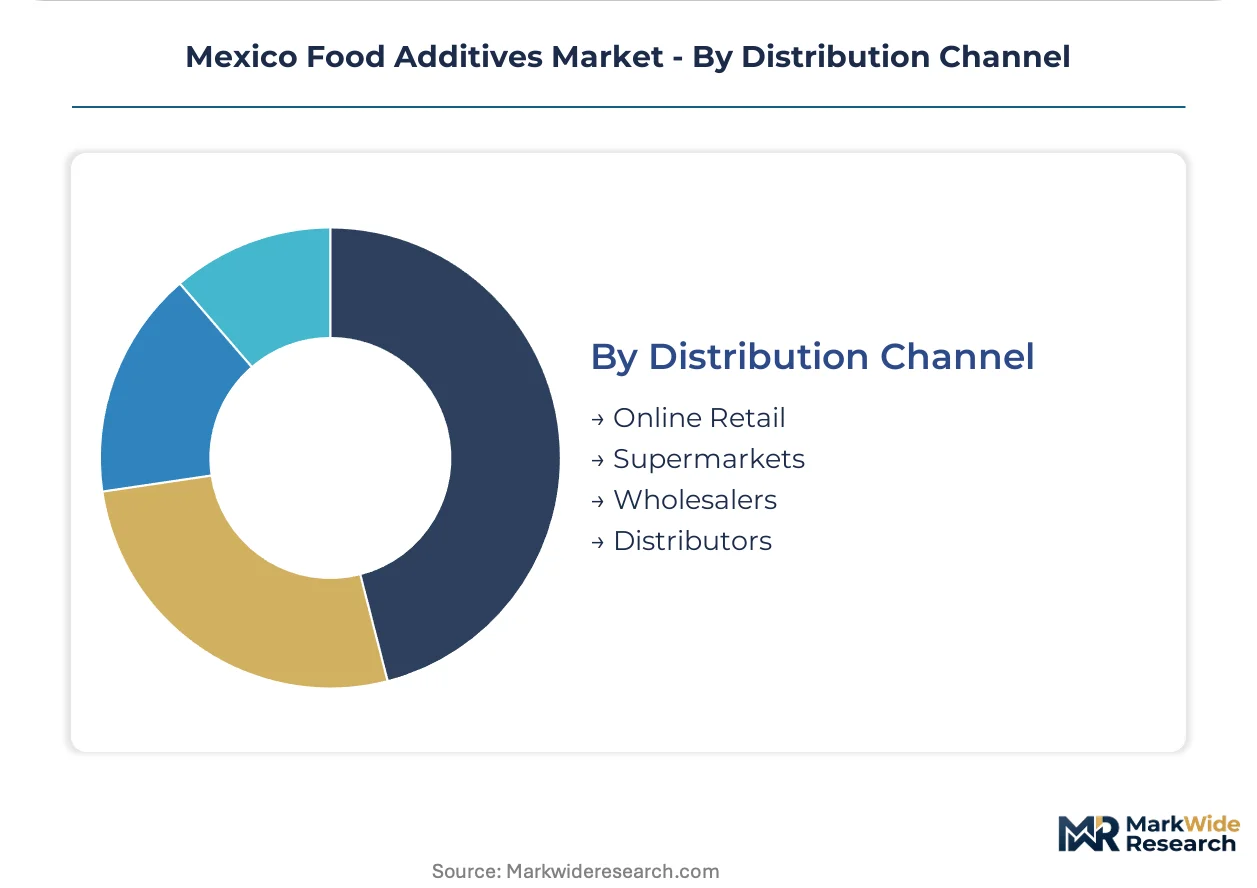
Channel selection correlates with customer technical support requirements and order scale thresholds.
- Online Retail:Specialty natural colorants and small-batch preservatives serve artisan producers. E-commerce penetration lags industrial procurement channels.
- Supermarkets:Consumer-facing retail packs dominate home cook and small caterer access. Private-label expansion pressures branded additive positioning.
- Wholesalers:Bulk preservative and emulsifier distribution serves mid-scale tortilla operations in Guadalajara metropolitan area.
- Distributors:Traditional channel retains processed meat and dairy ingredient flows. Technical service integration erodes pure distribution margins.
Distributors retain volume leadership; embedded formulation partnerships capture expanding margin pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
COFEPRIS regulatory stringency exceeds Central American counterparts, while Jalisco and Nuevo León industrial clusters concentrate additive procurement at volumes unmatched elsewhere in Latin America. Mexican food manufacturers navigate tighter clean-label mandates than regional peers, driving qualification timelines for natural replacement technologies.
Nuevo León
Beverage and bakery processors in Monterrey metropolitan area drive preservative demand for high-humidity distribution challenges. COFEPRIS NOM-051 enforcement compels reformulation documentation for ambient-stable products. Industrial clusters along the Monterrey-Saltillo corridor anchor emulsifier procurement scale for tortilla and snack texture modification.
Jalisco
Guadalajara-area poultry processors scale additive-intensive curing systems for export contract compliance. SENASICA residue protocols align with COFEPRIS domestic standards, streamlining dual-track certification. Technical service contracts concentrate in Zapopan formulation centers serving regional tortilla and instant noodle producers.
Chihuahua
Cheese production clusters face clean-label culture system upgrades for US export qualification. COFEPRIS consultations on artificial additive school food restrictions create mandated replacement demand. Ciudad Juárez cross-border supply chains integrate with El Paso-area processors for technical specification alignment.
Sonora
Seafood processing corridors drive natural preservative adoption for temperature-sensitive distribution. Hermosillo industrial zones lag Jalisco in additive sophistication, creating technical upgrade opportunities. Cross-border logistics with Arizona processors accelerate GRAS-notified ingredient qualification timelines.
Bajío Region
Aguascalientes and Querétaro automotive-adjacent foodservice manufacturing concentrates institutional seasoning procurement. COFEPRIS pending infant food colorant restrictions accelerate natural qualification programs in regional dairy operations. San Luis Potosí distribution hubs connect northern production with central Mexico consumption corridors.
Mexico Food Additives Market Competitive Landscape
Top-tier vendors anchor multinational premix development, while regional distributors and local formulators occupy fragmented mid-market tiers. The vendor base stratifies between integrated nutrition platforms and specialized single-category suppliers. Strategic archetypes include fermentation-derived natural preservative specialists, encapsulation technology licensors, and embedded R&D service providers. Competitive moves concentrate on technical service contract expansion and direct manufacturer partnership models displacing traditional distribution.
Within the integrated nutrition platform tier, Cargill Incorporated and Kerry Group plc occupy positions exemplifying premix and taste-system convergence. Chr. Hansen A/S represents the specialized natural culture and colorant archetype, anchoring dairy-focused technical service concentration. These three entities illustrate the competitive spectrum from broad formulation integration to targeted biotechnology specialization.
| Leading Market Players |
|---|
| DuPont de Nemours Inc. |
| The Archer Daniels Midland Company |
| Cargill Incorporated |
| Ingredion Inc. |
| Kerry Group plc |
| Chr. Hansen A/S |
| Tate & Lyle PLC |
| Brenntag AG |
| Koninklijke DSM N.V. |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap distributors across Guadalajara and Monterrey metropolitan clusters anchor procurement flows while compressing margin capture for multinational premix suppliers. Their consolidated buying power shapes price discipline in preservative and emulsifier categories where COFEPRIS documentation burdens favor established supplier relationships.
Pricing Analysis
Capacity additions in Nuevo León beverage processing are reshaping price floors for acidulant and antimicrobial blends. Contract-based long-term offtake dominates procurement, with price differentiation hinging on COFEPRIS certification tier and volume scale commitments. Cost compression in synthetic preservatory tiers is intensifying because natural replacement qualification timelines extend buyer switching costs. Mid-scale tortilla producers exhibit highest price sensitivity; export-qualified meat processors show least.
Supply Chain Analysis
Single-source vulnerability sits with European natural colorant specialists and US fermentation-derived preservative platforms. Geographic supply concentration centers on Germany, Denmark, and the United States for high-purity emulsifiers and precision fermentation actives. Raw material dependencies include corn-derived lecithin, palm-based mono-diglycerides, and annatto seed extracts. Tariff exposure on specialty inputs creates structural risk. Distribution runs through embedded technical service contracts displacing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
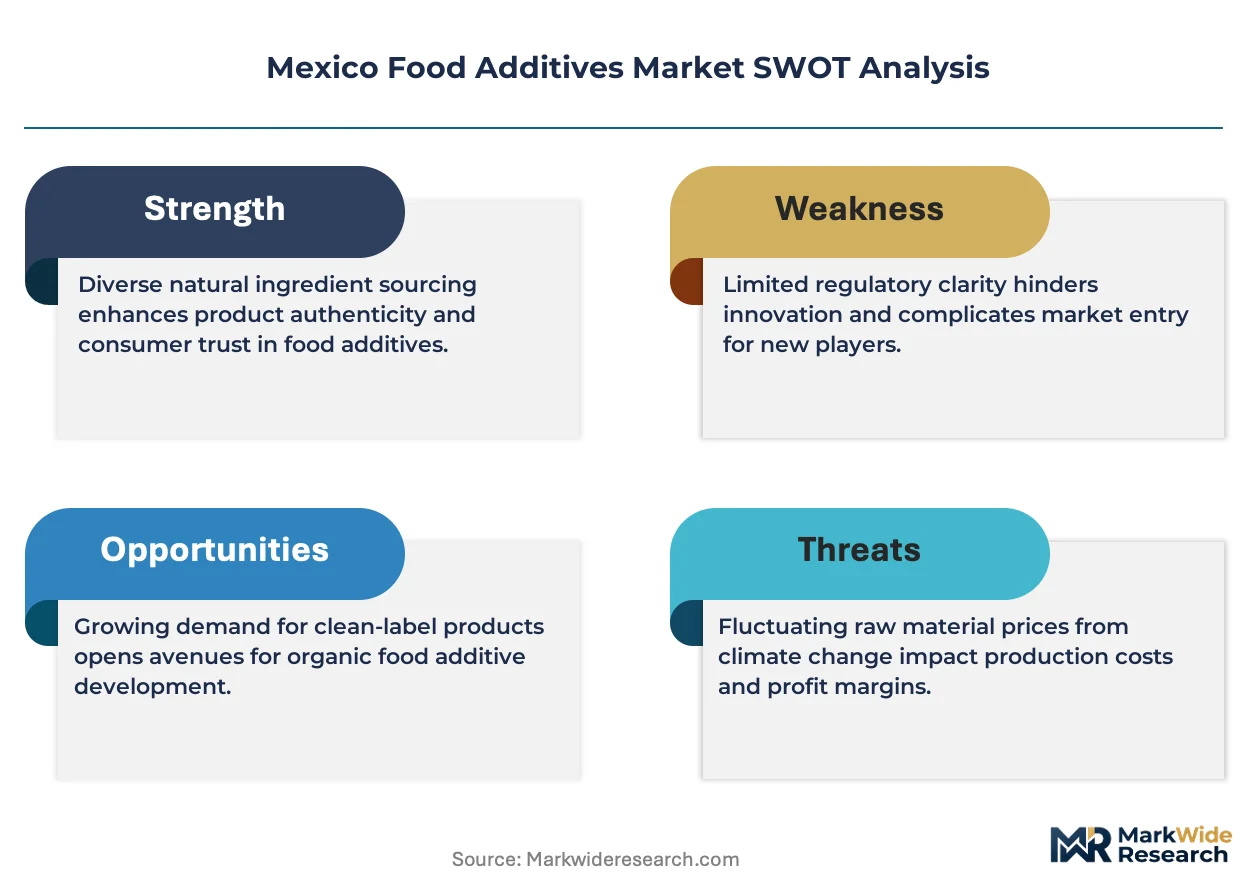
COFEPRIS pending artificial colorant restrictions in infant and school nutrition categories compound demand for natural replacement technologies, creating regulatory-mandated procurement windows.
For Market Incumbents: Deploy embedded R&D partnership models to lock Jalisco tortilla and Nuevo León snack producers into multi-year technical service contracts. Deepen backward integration into natural preservative fermentation capacity to offset import dependency on European suppliers. Precision fermentation scale-up in Guadalajara technical centers counters emerging biotechnology specialist entrants. For New Entrants and Emerging Players: Encapsulation technology platforms targeting tropical stability challenges offer white-space entry. Chihuahua cheese production clusters and Sonora seafood processing corridors present the most penetrable geographies given lagging additive sophistication. Direct technical service contracts with mid-scale processors bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among regional distributors lacking technical service capabilities. Natural preservative fermentation specialists and encapsulation technology licensors offer strongest five-to-ten-year viability given COFEPRIS clean-label trajectory. Watch pending school nutrition mandate finalization as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Guadalajara pilot facilities absorb capital shifting from synthetic preservative production. |
| Embedded R&D Partnerships | Jalisco tortilla producers adopt co-development models with premix suppliers. |
| Natural Colorant Qualification Programs | Infant food restrictions accelerate carmine and annatto system validation timelines. |
| Cross-Border Supply Chain Integration | Chihuahua and Sonora processors align with US Southwest technical specifications. |
| Encapsulation Technology Licensing | Lipid and polymer systems enable targeted release in tropical distribution conditions. |
Research Methodology
Coverage spans Jalisco, Nuevo León, Chihuahua, Sonora, and the Bajío Region, with primary inputs from each. Primary interviews with food formulation chemists, COFEPRIS regulatory consultants, procurement directors at industrial bakeries, and technical service managers at premix suppliers combined with secondary validation from COFEPRIS NOM-051 regulatory filings, SENASICA residue protocols, customs trade data on specialty additive imports, and SEC filings of multinational ingredient suppliers. Bottom-up facility-level capacity estimates and top-down category spend analysis enabled triangulation.
Rate-of-change decomposition across product type, application, end user, and distribution channel dimensions structured the analytical framework. CAGRs were derived from segmented volume and value build-ups across the projection horizon. Modeled inputs included COFEPRIS maximum usage limit revisions, tropical climate spoilage incidence rates, and export contract qualification timelines for SENASICA compliance.
The model holds under stable COFEPRIS regulatory enforcement and sustained tropical climate conditions; deviation in clean-label mandate acceleration or peso volatility would shift trajectory. Forecasts reflect documented assumptions about natural replacement technology adoption curves and cross-border supply chain integration pace. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Mexico Food Acidulants Market
Food Additives and Ingredients
Dairy Enzymes Market
Food Additives and Ingredients
Brazil Food Emulsifiers Market
Food Additives and Ingredients
Germany Food Enzymes Market
Food Additives and Ingredients
Canada Food Emulsifiers Market
Food Additives and Ingredients
Xanthan Gum Market
Food Additives and Ingredients
Food and Beverages Color Fixing Agents Market
Food Additives and Ingredients
Global Gamma Linolenic Acid Market
Food Additives and Ingredients
North America Dehydrated Onion Market
Food Additives and Ingredients
Japan Feed Additives Market
Food Additives and Ingredients
France Food Acidulants Market
Food Additives and Ingredients
Africa Anti Caking Agent Market
Food Additives and Ingredients
Germany Feed Additives Market
Food Additives and Ingredients
Russia Food Enzymes Market
Food Additives and Ingredients
Erythorbic Acid Market
Food Additives and Ingredients
Chocolate Wax Market