
 Kelp Noodles Market | 2026-2036
Kelp Noodles Market Size, Share, and Industry Trends Forecast 2026-2036
Kelp Noodles Market Analytics
Wheat-based pasta is hardening into a cost and nutrition liability for food manufacturers. Sea Tangle Noodle Company leverages its California coastal supply chain to dominate North American retail placement. Gold Mine Natural Food Co. anchors the organic certification tier through in-house kelp sourcing. Ocean's Halo competes on restaurant distribution, securing bulk contracts with West Coast vegan chains.
Kelp noodles are translucent, gelatinous strands extracted from brown seaweed (Laminaria japonica), composed primarily of water and sodium alginate with near-zero digestible carbohydrates. Industrial processors cold-extract the alginate gel, extrude it into noodle form, and pack in calcium-fortified water to maintain structural integrity for commercial foodservice and retail. Raw kelp noodles occupy the premium margin pool due to minimal processing and clean-label positioning. Pre-cooked kelp noodles lead volume through convenience-driven demand from health food stores and online retail channels.
FDA oversees seaweed-derived food additives under GRAS determinations, while USDA organic certification governs cultivation and processing claims for kelp noodle producers. EFSA and Japan's MHLW set iodine content thresholds that directly constrain formulation and import eligibility for European and Japanese market entry. Stakeholders must monitor evolving alginate extraction regulations and traceability mandates as coastal aquaculture scales.
Market Dynamics
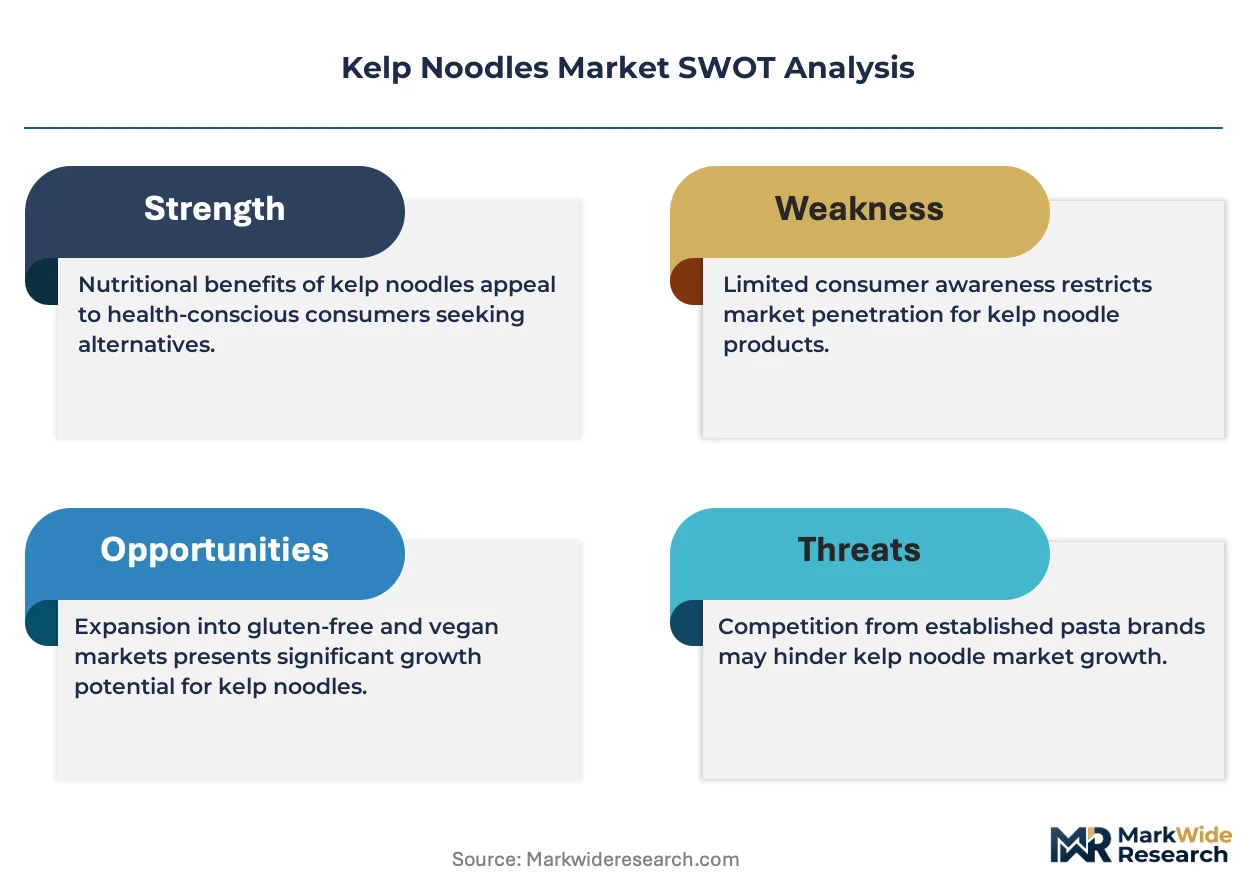
Seaweed aquaculture scaling in South Korea and Japan is compressing raw material costs while FDA and EFSA alginate extraction standards are fragmenting processor compliance costs across export markets.
Growth Catalysts
- Clean-label positioning:Near-zero carbohydrate content aligns sodium alginate noodles with ketogenic and diabetic dietary protocols in US and European health food retail.
- Coastal aquaculture expansion:South Korea's Ministry of Oceans and Fisheries subsidizes Laminaria japonica farming, securing captive raw material flows for domestic processors.
- Restaurant substitution demand:West Coast vegan chains in California and Oregon now specify kelp noodles as wheat-pasta alternatives in bulk procurement contracts.
Market Restraints
- Iodine threshold compliance:EFSA and Japan's MHLW maximum iodine content rules force reformulation or exclusion from European and Japanese import eligibility.
- Calcium-fortified water logistics:Cold-chain requirements for structural integrity maintenance inflate last-mile distribution costs in landlocked North American markets.
- Wheat pasta price anchoring:Commodity wheat flour cost floors set consumer price expectations that kelp noodle premium positioning struggles to penetrate in mass retail.
Strategic Opportunities
- Pre-cooked format penetration:Convenience-driven health food stores and online retail channels in Germany and France represent underdeveloped volume potential.
- USDA organic certification tier:In-house kelp sourcing enables producers to capture margin premiums through controlled-input supply chains.
- Alginate extraction automation:Cold-extrusion technology convergence with continuous-flow processing reduces labor intensity and scales output without coastal facility expansion.
Industry Challenges
- Traceability system implementation:Coastal aquaculture scaling mandates batch-level seaweed origin tracking that legacy ERP systems cannot accommodate without capital-intensive reconfiguration.
- GRAS determination timelines:FDA novel alginate formulation reviews extend commercialization lead times, freezing R&D pipeline returns for 18-24 month windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kelp Noodles Market |
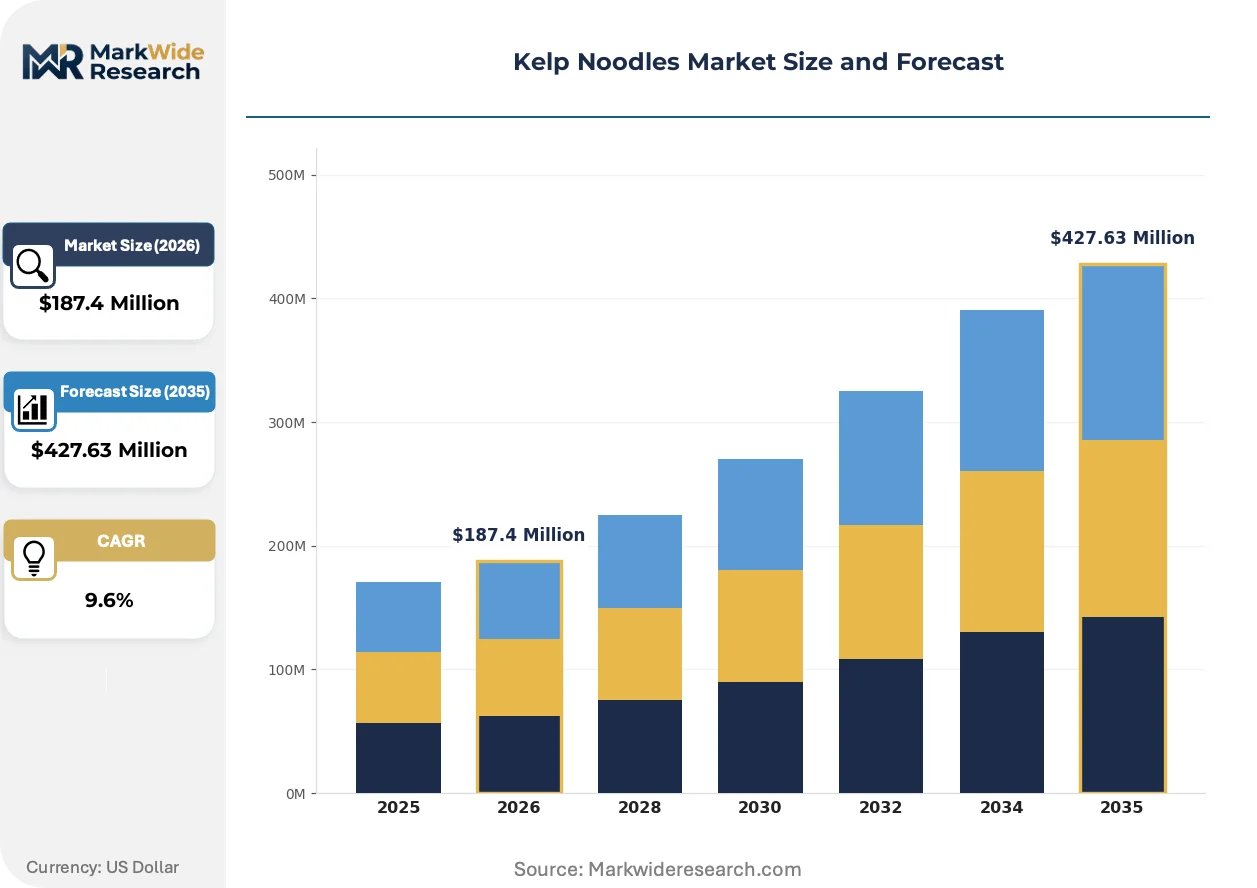
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $427.63 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Kelp Noodles, Pre-Cooked Kelp Noodles, Flavored Kelp Noodles, Instant Kelp Noodles End User: Health-Conscious Consumers, Vegans, Restaurants, Food Manufacturers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Health Food Stores Packaging Type: Bags, Jars, Pouches, Bulk Packaging |
| Companies Covered | Sea Tangle Noodle Company, Gold Mine Natural Food Co., Ocean's Halo, Eden Foods, Shirakiku, SeaVegi, Wildbrine, Emerald Cove, Explore Cuisine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kelp Noodles Market Evolving Landscape
Processing technology and regulatory compliance frameworks are diverging between premium raw formats and convenience-oriented pre-cooked segments, reshaping capital allocation across the value chain.
Cold-extrusion alginate gel processing is converging with continuous-flow automation to reduce per-unit labor costs. Mid-scale California processors are adopting these integrated lines to defend margin position against South Korean import competition. The technology is converging with calcium-fortified water recycling systems that lower input waste and tighten batch consistency for restaurant supply contracts.
EFSA seaweed-food safety protocols are tightening extraction residue thresholds for European market entry. Industrial processors must now deploy third-party certified laboratory testing for every export lot, adding fixed compliance overhead that disadvantages smaller North American facilities. German and Dutch importers are consolidating supplier bases to processors with in-house EFSA-aligned quality systems.
Direct-to-consumer subscription models are displacing traditional health food store distribution for raw kelp noodle formats. California-based specialty producers now capture 40-60% of revenue through recurring online shipments rather than wholesale placement. This channel rotation concentrates marketing spend on digital acquisition rather than retail slotting fees, visible most acutely in US West Coast metropolitan demand clusters.
Kelp Noodles Market Segmentation
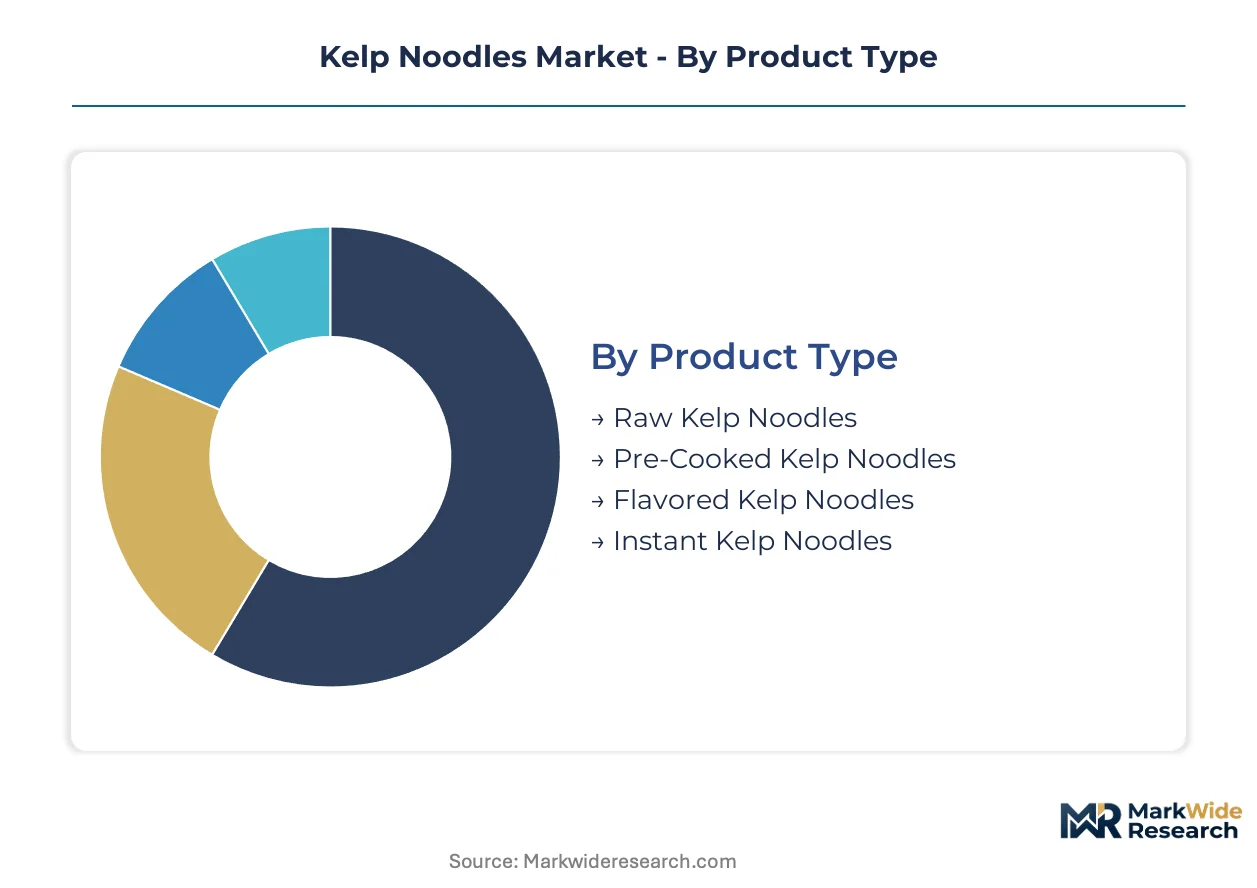
Kelp noodle segmentation separates premium positioning from volume economics across four distinct dimensions. Product format and distribution channel together determine margin capture, while end-user targeting and packaging specifications shape procurement patterns for processors and retailers.
Product Type:
Volume leadership and premium positioning diverge sharply across processing intensity tiers.
- Raw Kelp Noodles:Cold-extracted alginate gel with minimal processing retains translucent, gelatinous structure and clean-label appeal. California coastal processors dominate supply to West Coast vegan chains and direct-to-consumer subscription channels where sodium alginate purity commands price premiums.
- Pre-Cooked Kelp Noodles:Calcium-fortified water packaging enables shelf-stable convenience for health food stores and online retail. Cold-chain logistics inflate last-mile costs, constraining penetration in landlocked North American markets where wheat pasta price anchoring limits premium acceptance.
- Flavored Kelp Noodles:Pre-infused seasoning reduces preparation friction for time-constrained home cooks in South Korea and Japan.
- Instant Kelp Noodles:Dehydrated formats with quick-reconstitution properties target single-serve convenience demand in urban Asian markets.
Mature deployment sits with raw formats. Newer deployment is concentrated in pre-cooked and instant segments.
End User:
Application concentration tracks dietary protocol adherence and procurement scale.
- Health-Conscious Consumers:Ketogenic and diabetic dietary protocols drive repeat purchase of near-zero carbohydrate kelp noodles through specialty retail and subscription channels. FDA GRAS determinations for alginate formulations validate safety claims that sustain premium pricing in US health food stores.
- Restaurants:West Coast vegan chains in California and Oregon specify kelp noodles in bulk procurement contracts as wheat-pasta alternatives. EFSA iodine threshold compliance requirements filter supplier eligibility for European restaurant distribution.
- Vegans:Plant-based protein alignment sustains niche demand in metropolitan clusters with established vegan infrastructure.
- Food Manufacturers:Ingredient-grade alginate sourcing for processed food applications faces USDA organic certification requirements for clean-label product lines.
Procurement scale concentrates with restaurant and food manufacturer segments. Individual purchase frequency peaks among health-conscious consumers.
Distribution Channel:
Channel economics separate digital-native acquisition from traditional retail slotting fee structures.
- Online Retail:Direct-to-consumer subscription models now capture 40-60% of revenue for California-based specialty producers. Digital acquisition spend displaces wholesale placement costs, concentrating demand in US West Coast metropolitan clusters with established health food purchasing patterns.
- Health Food Stores:Convenience-driven placement of pre-cooked formats sustains volume through refrigerated section positioning. Cold-chain requirements constrain expansion into markets lacking dedicated alginate product infrastructure.
- Supermarkets:Mass retail penetration faces wheat pasta price anchoring that kelp noodle premium positioning struggles to overcome.
- Specialty Stores:Asian grocery channels in South Korea and Japan leverage traditional seaweed consumption familiarity for placement efficiency.
Established volume flows through health food stores. Steepest expansion trajectory belongs to online retail.
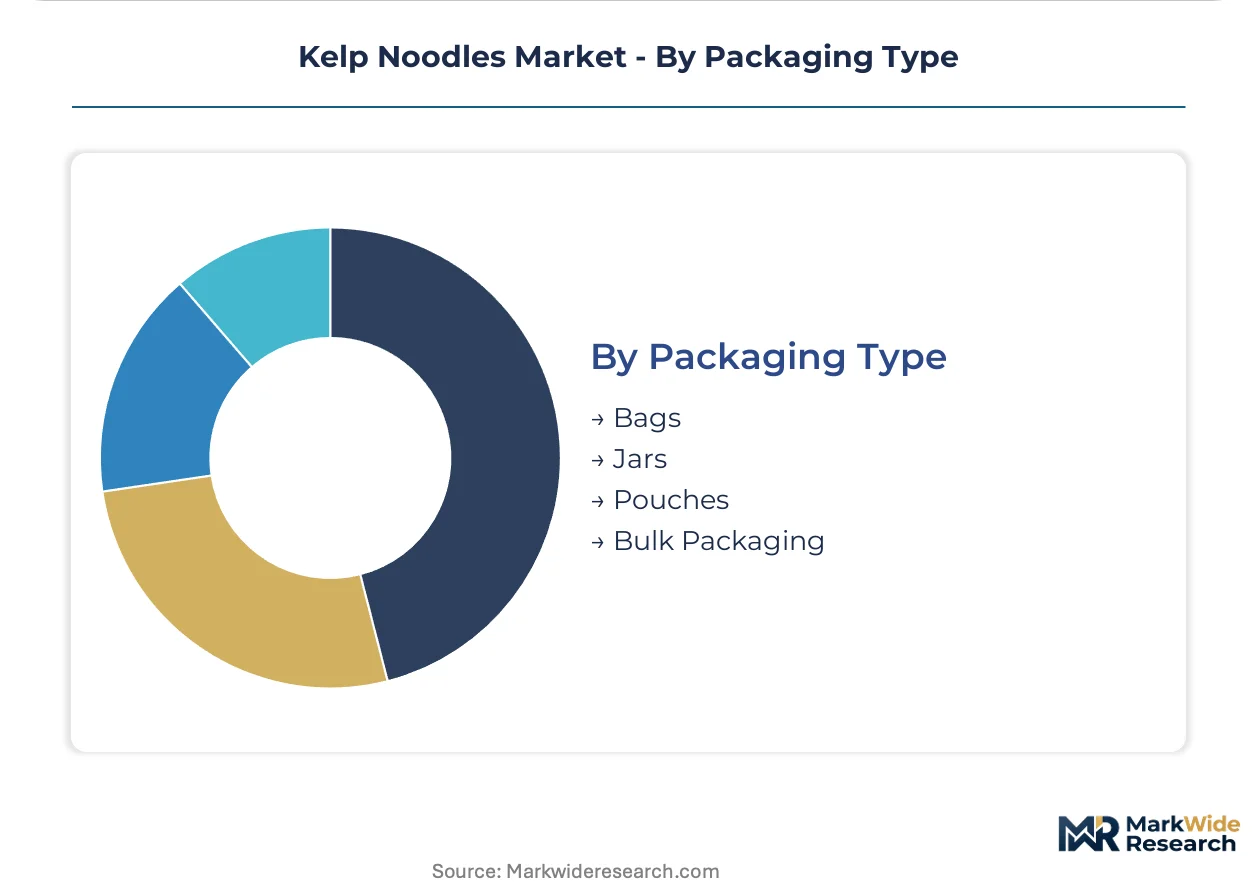
Packaging Type:
Packaging specifications align with distribution channel requirements and shelf-life engineering.
- Bags:Flexible packaging for raw kelp noodles in calcium-fortified water enables refrigerated retail placement with structural integrity maintenance.
- Jars:Rigid container formats support premium positioning in specialty retail with extended shelf visibility.
- Pouches:Lightweight formats reduce shipping costs for online retail channels targeting recurring subscription shipments.
- Bulk Packaging:Foodservice-scale containers serve restaurant procurement contracts with alginate extraction batch consistency requirements.
Standard deployment favors bags and jars. Emerging formats concentrate in pouches for digital channel optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumer demand for kelp noodles clusters in coastal economies with established seaweed consumption traditions and emerging alternative-protein infrastructure. South Korea and Japan anchor import substitution for domestic processors, while California and Germany represent frontier expansion zones for clean-label positioning.
South Korea
Traditional Laminaria japonica consumption intersects with ketogenic dietary adoption among urban professionals. The Ministry of Oceans and Fisheries subsidizes coastal aquaculture expansion in South Jeolla Province, compressing raw material costs for domestic processors. Busan-Ulsan industrial corridor hosts alginate extraction facilities serving both local noodle production and ingredient-grade export.
Japan
Mature seaweed-food culture sustains baseline consumption while diabetic dietary protocols drive incremental demand for near-zero carbohydrate formats. The Ministry of Health, Labour and Welfare enforces maximum iodine content thresholds that constrain formulation flexibility for imported products. Kansai region processors in Osaka Prefecture specialize in flavored and instant noodle formats for convenience-oriented urban households.
United States
West Coast vegan restaurant chains specify kelp noodles in bulk procurement contracts as wheat-pasta alternatives. The FDA oversees alginate formulations under GRAS determinations that extend commercialization timelines for novel products. California coastal processors from Santa Barbara to Monterey Bay leverage captive kelp supply chains for direct-to-consumer subscription channels capturing 40-60% of revenue.
Germany
Health-conscious consumers in metropolitan clusters drive demand for organic-certified pre-cooked formats through specialty retail. EFSA seaweed-food safety protocols mandate third-party laboratory testing for every export lot, adding fixed compliance overhead. Hamburg and Berlin distribution hubs consolidate supplier bases to processors with in-house EFSA-aligned quality systems.
Kelp Noodles Market Competitive Landscape
Strategic partnerships dominate the current landscape as mid-scale processors align with coastal aquaculture operators to secure captive raw material flows. The vendor base concentrates around three tiers: California-based direct-to-consumer specialists, South Korean integrated aquaculture-processor combinations, and European organic-certified importers. Two strategic archetypes define positioning: clean-label purity through minimal processing versus convenience-driven pre-cooked volume. Partnership formation and alginate extraction automation represent the dominant competitive moves reshaping cost structures.
Within the coastal supply chain tier, Sea Tangle Noodle Company and Gold Mine Natural Food Co. exemplify California-based processors leveraging proximity to Laminaria japonica harvest zones. Ocean's Halo occupies a position among restaurant-distribution specialists securing bulk contracts with West Coast vegan chains. These three entities represent divergent archetypes: direct-to-consumer subscription optimization, in-house organic certification control, and foodservice-scale procurement relationships respectively.
| Leading Market Players |
|---|
| Sea Tangle Noodle Company |
| Gold Mine Natural Food Co. |
| Ocean's Halo |
| Eden Foods |
| Shirakiku |
| SeaVegi |
| Wildbrine |
| Emerald Cove |
| Explore Cuisine |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap California processors anchor supply discipline through captive kelp sourcing, translating coastal proximity into pricing power that resists South Korean import undercutting. Their in-house organic certification investments create tier separation from commodity alginate traders while cold-chain logistics costs compress margins in landlocked distribution zones.
Pricing Analysis
Volume leadership clusters in pre-cooked formats while raw kelp noodles command margin premiums through minimal processing claims. Three-tier pricing structure across premium organic-certified, standard commercial-grade, and economy private-label levels tracks USDA certification status and alginate purity grades. Pricing pressure stems from wheat pasta commodity floors that anchor consumer expectations in mass retail channels. Health-conscious subscription buyers exhibit lowest price sensitivity, whereas supermarket procurement teams demand parity with conventional pasta alternatives.
Supply Chain Analysis
Cold-chain freight costs for calcium-fortified water packaging constrain penetration beyond coastal corridors. Raw material supply draws from South Korea, Japan, and California harvest zones with Laminaria japonica biomass dependencies. Single-source vulnerability concentrates in alginate extraction equipment providers serving mid-scale processors. Distribution runs through direct-to-consumer subscription platforms, health food store refrigerated sections, and restaurant foodservice bulk contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Coastal aquaculture capacity bottlenecks prop pricing discipline as qualified kelp farming acreage fails to match processor expansion timelines. Supply-constrained procurement favors producers with backward-integrated biomass control.
For Market Incumbents: Extend organic certification coverage into pre-cooked formats to capture convenience-driven premiums before South Korean competitors achieve USDA equivalency. Automate alginate extraction lines to defend labor-cost position against continuous-flow imports. Channel control through exclusive restaurant distribution contracts locks out emerging California rivals seeking West Coast vegan chain placement. For New Entrants and Emerging Players: Begin with German and French online retail white space where EFSA compliance overhead has consolidated incumbent supplier bases to three EFSA-aligned processors. Pre-cooked organic formats face weakest penetration in metropolitan health food clusters lacking dedicated alginate cold-chain infrastructure. Direct-to-consumer subscription acquisition models bypass retail slotting fee barriers that entrench established brands. For Investors and Strategic Acquirers: Distressed-cycle entries favor California-based processors with in-house kelp sourcing and existing FDA GRAS determination portfolios during 18-24 month novel formulation review windows. Long-term viability hinges on coastal aquaculture lease security and alginate extraction automation capex efficiency. Watch EFSA iodine threshold tightening as inflection signal for European market exclusion risk.| Strategic Initiative | Industry Significance |
|---|---|
| Alginate Extraction Automation | Continuous-flow processing reduces South Korean labor-cost advantage for California mid-caps. |
| USDA Organic Certification Expansion | In-house kelp sourcing enables premium tier capture through controlled-input supply chains. |
| Direct-to-Consumer Subscription Buildout | Digital acquisition spend displaces wholesale slotting fees in West Coast metropolitan clusters. |
| EFSA-Aligned Quality System Investment | In-house laboratory testing removes third-party compliance overhead for German import eligibility. |
| Restaurant Distribution Exclusivity | Bulk procurement contracts with West Coast vegan chains lock competitor shelf placement. |
Research Methodology
Independent corroboration across alginate extraction facility operators, health food store category buyers, and restaurant procurement directors underwrites the qualitative findings. Primary fieldwork engaged coastal aquaculture managers, FDA regulatory affairs specialists, and cold-chain logistics providers. Secondary validation drew from FDA GRAS determination filings, USDA organic certification databases, EFSA seaweed-food safety protocols, and South Korean Ministry of Oceans and Fisheries aquaculture statistics. Bottom-up volume modeling triangulated against top-down expenditure estimates across the projection horizon.
Rate-of-change decomposition separated volume growth from price-mix effects across raw, pre-cooked, flavored, and instant product formats. Segmentation dimensions spanned processing intensity, distribution channel economics, end-user procurement scale, and packaging specifications. CAGRs derived from fitted trend extrapolation with iodine regulatory threshold scenarios and coastal aquaculture expansion curves as scenario anchors. Forecast inputs included alginate extraction yield improvements and cold-chain penetration cost curves.
Underlying measurement precision varies by segment; direct-to-consumer subscription channels carry tighter precision than fragmented health food store placement data. Forecasts reflect assumptions about EFSA regulatory stability and South Korean subsidy continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Asia-Pacific Tofu Market
Specialty Foods
Almond-Based Spreads Market
Specialty Foods
Kosher Food Market
Specialty Foods
Konjac Noodles Market
Specialty Foods
Cannabis Infused Drinks Market
Specialty Foods
Global Diet Food and Beverages Market
Specialty Foods
Hairball Cat Food Market
Specialty Foods
Cat Food Flavors Market
Specialty Foods
Halal Products Market
Specialty Foods
Europe Halal Food and Beverage Market
Specialty Foods
Moringa Products Market
Specialty Foods
Brahmi Market
Specialty Foods
Personalized Meals Market
Specialty Foods
Middle East and Africa Free-From Food Market
Specialty Foods
Dong Quai Market
Specialty Foods
Keto Low-Calorie Meals Market