
 Food Grade Sodium Selenite Market | 2026-2036
Food Grade Sodium Selenite Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Sodium Selenite Market Insights
Pharmaceutical-grade purity specifications is redrawing competitive boundaries in food grade sodium selenite. BASF SE leverages its integrated selenium chemistry platform to sustain supply security for premium formulations. Orffa International Holding B.V. anchors its position through specialized premix expertise across European livestock markets. American Elements competes on ultra-high-purity material output for biotechnology applications.
Food grade sodium selenite is a white crystalline sodium salt of selenious acid, typically supplied at minimum 98.5% purity with controlled heavy metal limits below 10 ppm, manufactured through controlled oxidation of selenium dioxide followed by neutralization with sodium carbonate or hydroxide; it serves primarily as a bioavailable selenium source for human nutritional fortification and animal feed supplementation. Powder formulations dominate volume throughput due to blending compatibility with flour and premix matrices, while liquid concentrates represent the fastest-expanding format as beverage fortification protocols standardize. The animal feed end user segment occupies the deepest margin pool, driven by livestock producers seeking optimized selenium yeast alternatives.
The FDA's GRAS notification framework and the EPA's selenium discharge guidelines jointly determine manufacturing site economics and product registration pathways for domestic suppliers. REACH compliance across the European Union constrains import sourcing flexibility, pushing regional buyers toward ECHA-registered suppliers with full substance dossiers. Stakeholders must monitor evolving maximum residue limits from Codex Alimentarius and national food safety authorities, as these thresholds directly determine formulation viability across export markets.
Market Dynamics
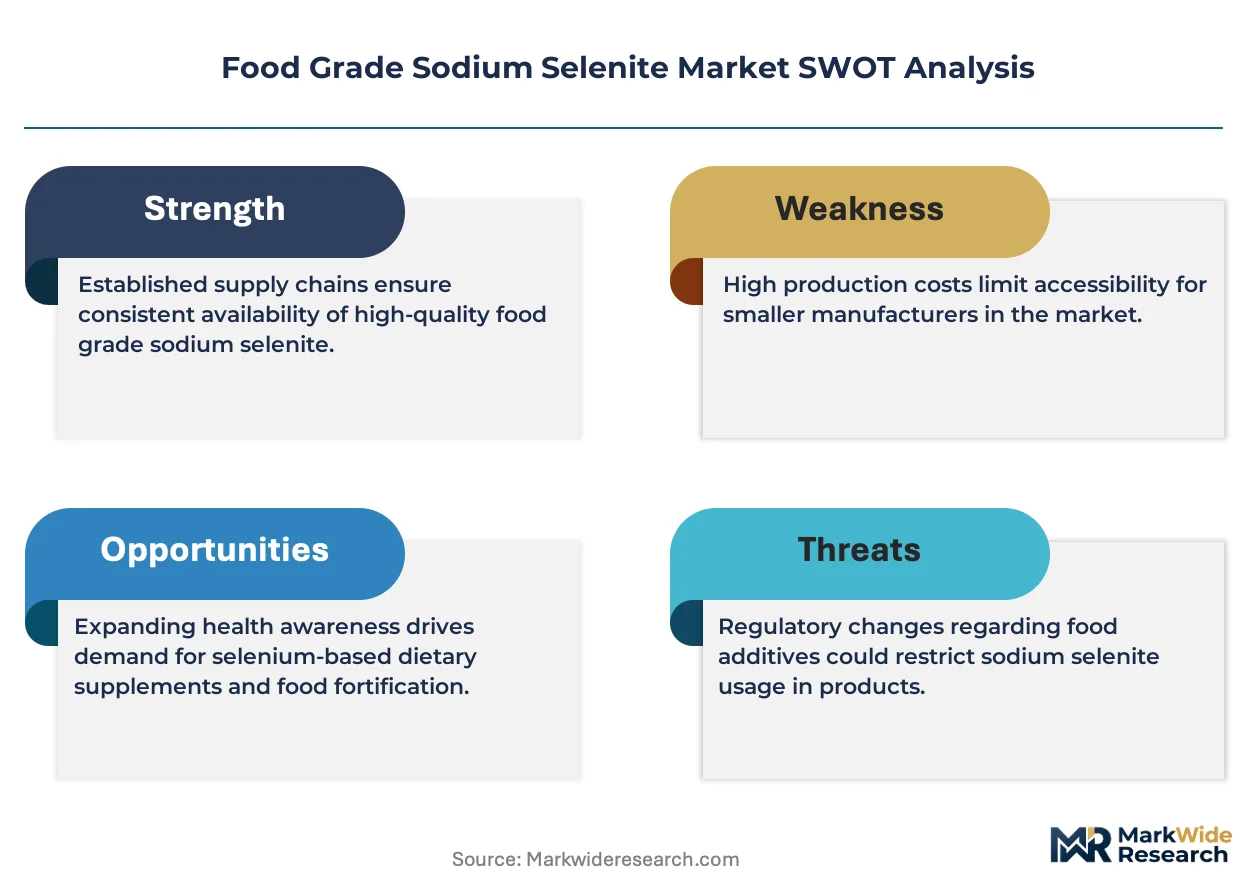
Pharmaceutical-grade purity specifications are compressing margins for commodity-grade suppliers while rewarding integrated selenium chemistry platforms with captive reduction capabilities and heavy metal control systems.
Growth Catalysts
- GRAS notification pathway:The FDA's streamlined food additive clearance process accelerates new formulation approvals for human nutritional fortification applications.
- Livestock productivity mandates:China's feed additive production scaling creates concentrated demand for bioavailable selenium sources in broiler and swine operations.
- Selenium yeast displacement:Inorganic sodium selenite offers cost stability versus organic selenium alternatives in ruminant feed premixes.
Market Restraints
- Elemental selenium price volatility:Mining concentration in specific geographies exposes processors to raw material cost swings.
- REACH dossier requirements:ECHA registration burdens constrain import flexibility for European compound feed manufacturers.
- Selenomethionine substitution:Organic selenium forms capture premium livestock segments with superior bioavailability claims.
Strategic Opportunities
- Beverage fortification protocols:Liquid concentrate formats open packaged water and functional drink channels previously inaccessible to powder matrices.
- Biotechnology applications:Ultra-high-purity specifications serve cell culture media and diagnostic reagent producers with specialized material needs.
- Codex Alimentarius harmonization:Emerging market regulators adopting international maximum residue limits reduce export registration friction.
Industry Challenges
- Analytical chemistry talent scarcity:Selenium speciation testing and heavy metal validation require specialized laboratory capabilities in short supply.
- Multi-jurisdiction registration timelines:Parallel FDA, EFSA, and national food safety authority approvals extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Sodium Selenite Market |
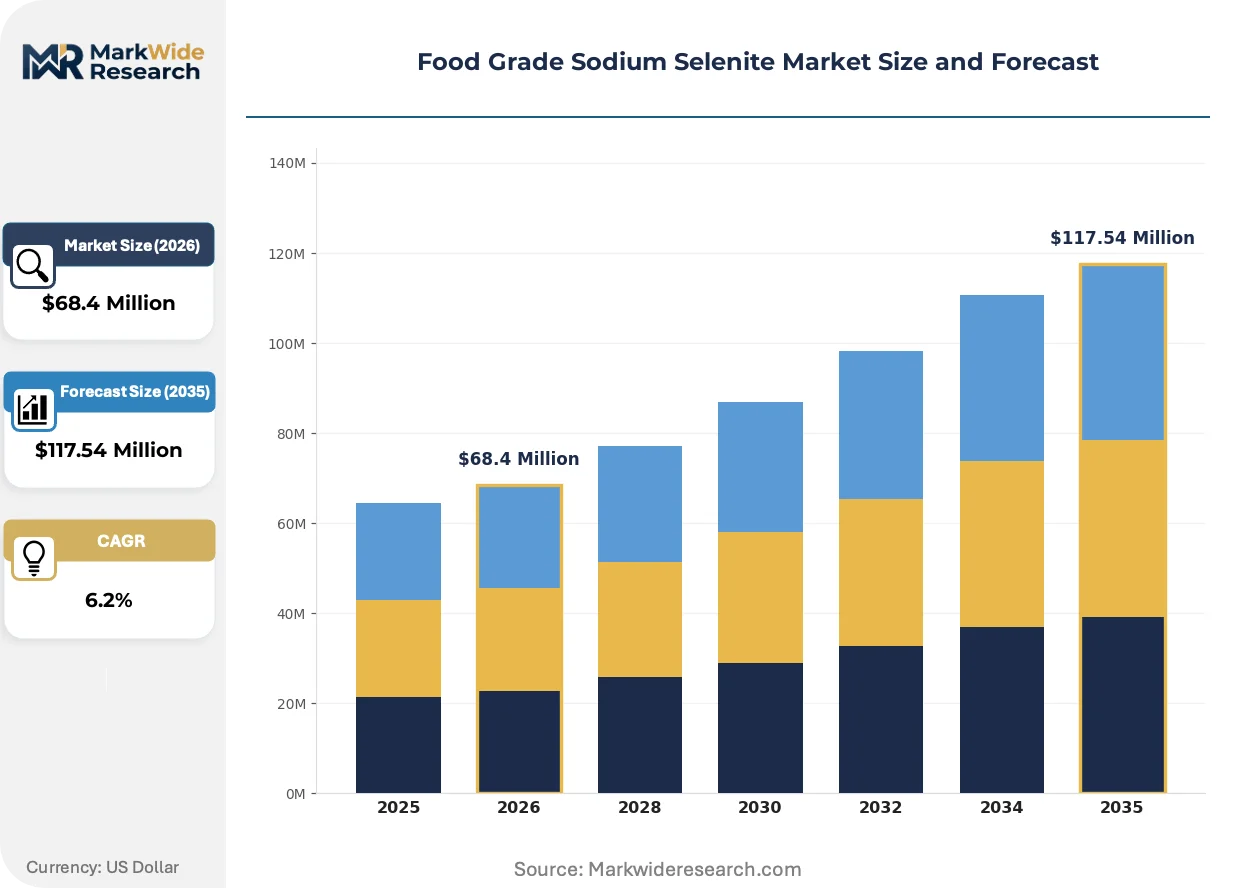
| Market Size in 2026 | $68.4 Million |
| Market Size in 2035 | $117.54 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Tablet, Liquid End User: Agriculture, Supplements, Animal Feed, Pharmaceuticals Packaging Type: Bags, Drums, Bottles, Pouches Distribution Channel: Online, Wholesale, Retail, Direct Sales |
| Companies Covered | American Elements, Salvi Chemical Industries Ltd., Orffa International Holding B.V., Jinhua Additives Co., Ltd., Vital Materials Co., Limited, BASF SE, Sisco Research Laboratories Pvt. Ltd., HiMedia Laboratories, Spectrum Laboratory Products, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Sodium Selenite Market Trends and Innovations
Manufacturing technology and regulatory frameworks are simultaneously tightening purity thresholds and opening new application vectors for selenium compounds across human and animal nutrition.
Controlled crystallization and spray-drying technologies are bifurcating the supplier base into integrated chemical platforms and toll-manufacturing dependent traders. Pharmaceutical-grade producers with in-house selenium dioxide oxidation and carbonate neutralization capabilities capture premium formulation contracts. Commodity-grade traders face margin compression as beverage fortification protocols standardize on sub-5 ppm heavy metal specifications.
REACH authorization requirements are forcing European feed compounders toward ECHA-registered suppliers with complete substance dossiers. The regulation's downstream user obligations transfer compliance burden to importers without registration certificates. German and Dutch premix manufacturers now prioritize domestic or fully-registered sourcing over cost-optimized third-country alternatives.
Direct procurement relationships between livestock integrators and selenium chemical producers are displacing traditional distributor intermediaries in animal nutrition channels. Large poultry and swine operations in the US Corn Belt negotiate volume contracts bypassing regional feed additive distributors. This channel compression concentrates volume with integrated chemical platforms capable of technical service and premix formulation support.
Food Grade Sodium Selenite Market Segmentation
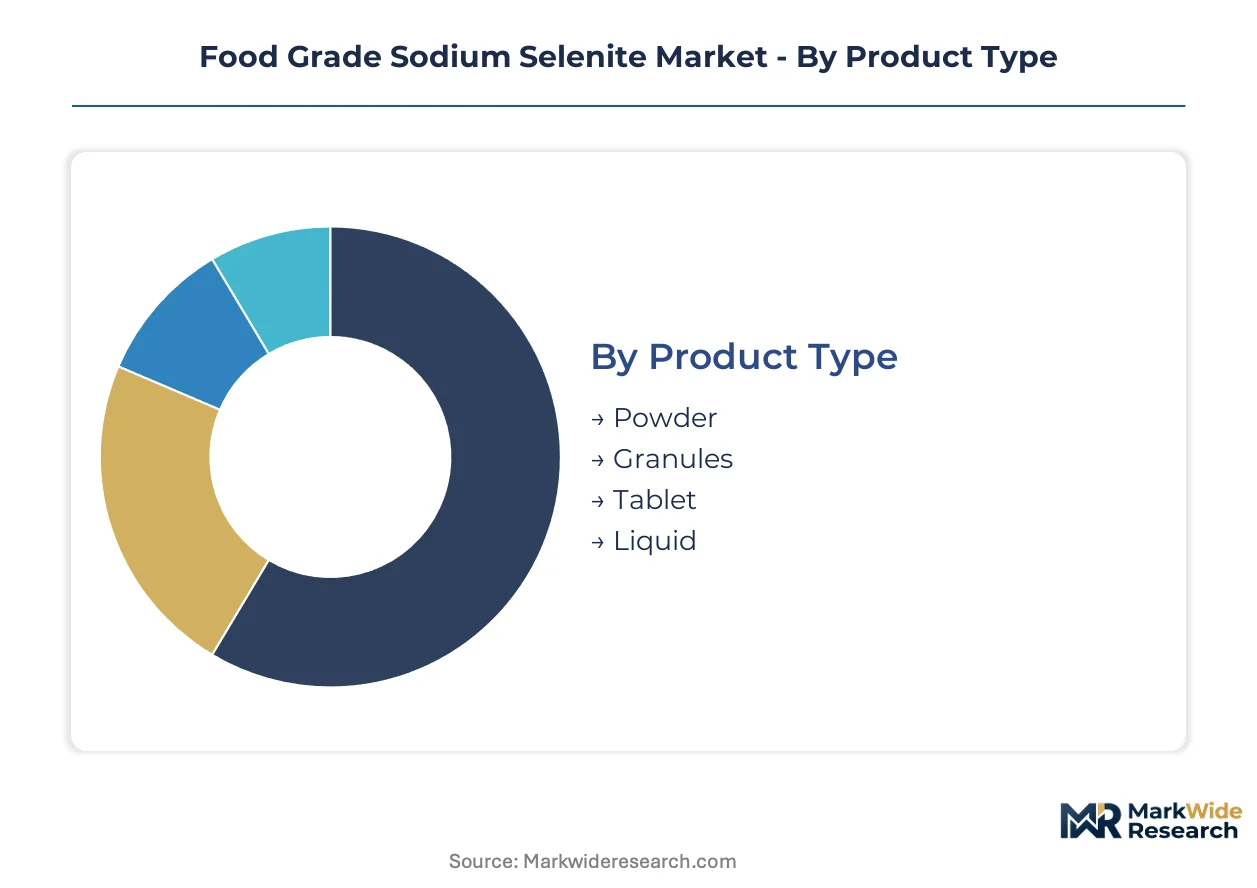
Sodium selenite formulations diverge sharply in handling economics and bioavailability performance. Material format determines blending compatibility with flour matrices, premix uniformity, and beverage solubility thresholds. Packaging and channel selection directly impact contamination risk during selenium's journey from chemical processor to end-formulator.
Product Type:
Powder and liquid formats face divergent substitution pressures from organic selenium alternatives, with solubility advantages determining defensibility against selenomethionine displacement.
- Powder:Crystalline particles sized for homogeneous dispersion in dry premixes and flour fortification. China's feed additive producers absorb the largest powder volumes for broiler and swine premix manufacturing. Selenium yeast substitution threatens ruminant applications where bioavailability claims carry premium pricing power.
- Liquid:Concentrated aqueous solutions standardized for beverage fortification protocols. Packaged water producers in North American and European markets drive uptake as functional drink categories formalize selenium dosing specifications. Format expansion depends on sub-5 ppm heavy metal certification that commodity traders struggle to secure.
- Granules:Agglomerated particles reducing dust exposure during handling. Specialized feed mills in Germany and the Netherlands specify granules for automated dosing systems.
- Tablet:Compressed forms for direct-to-consumer supplement packaging. Contract manufacturers serving dietary supplement brands in the US source tablet-grade material for mineral complex formulations.
Powder retains volume leadership; liquid holds the steepest expansion curve.
End User:
Cost tier stratification separates commodity-grade animal feed applications from pharmaceutical-grade human nutrition, with margin capture concentrating at purity extremes.
- Animal Feed:Premix manufacturers and livestock integrators constitute the deepest demand pool. US Corn Belt poultry operations negotiate direct procurement contracts bypassing regional distributors. Selenium yeast alternatives capture premium segments with superior bioavailability claims in ruminant nutrition.
- Supplements:Dietary supplement formulators drive human nutritional fortification demand. FDA GRAS notifications accelerate new product approvals for mineral complex tablets and capsules.
- Agriculture:Foliar application and soil amendment uses in selenium-deficient regions. Chinese domestic production scaling supports regional crop biofortification programs.
- Pharmaceuticals:Ultra-high-purity specifications for cell culture media and diagnostic reagents. Biotechnology producers require heavy metal limits below 10 ppm with full ECHA dossier documentation.
Animal Feed commands the largest volume share; Pharmaceuticals posts the highest unit margins.
Packaging Type:
Volume throughput and contamination sensitivity dictate packaging selection, with multi-wall barriers dominating selenium's oxidation-prone chemistry.
- Bags:Multi-layer paper-plastic laminates for powder and granule shipments. Standard unit loads for flour mill and feed compounder procurement.
- Drums:Steel or fiber containers for liquid concentrates and bulk powder. REACH-registered suppliers in Germany favor drum formats for ECHA-compliant substance tracking.
- Bottles:Pharmaceutical-grade amber glass or HDPE for laboratory and small-batch supplement manufacturing.
- Pouches:Flexible single-serve and sample formats for supplement brand marketing and trial distribution.
Bags move the highest tonnage; pouches gain share in direct-to-consumer channels.
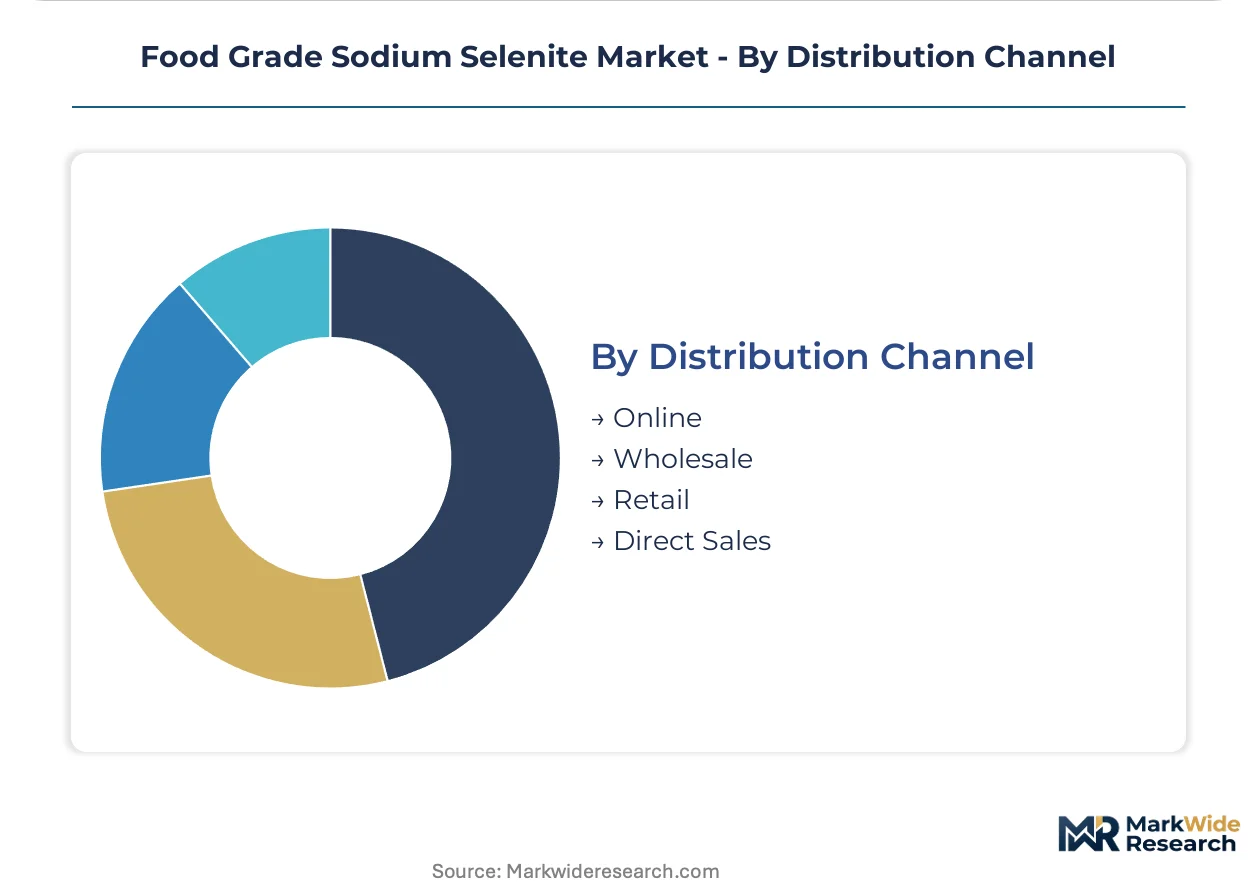
Distribution Channel:
Customer scale and technical service requirements are compressing intermediary layers, with direct relationships displacing traditional distributor networks.
- Direct Sales:Volume contracts between selenium chemical producers and livestock integrators or premix manufacturers. Large US poultry and swine operations negotiate technical service-inclusive agreements.
- Wholesale:Regional distributors serving mid-tier feed compounders and smaller supplement manufacturers. REACH registration requirements constrain European wholesale import flexibility.
- Online:E-procurement platforms for laboratory chemicals and small-batch supplement ingredients. Biotechnology researchers source ultra-high-purity grades through specialized chemical marketplaces.
- Retail:Limited application given sodium selenite's industrial chemical classification and handling restrictions.
Direct Sales captures the largest revenue concentration; Online expands most quickly in laboratory segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese feed additive buyers exhibit the highest price elasticity, squeezing margins on standard-grade powder, while European pharmaceutical and biotechnology purchasers absorb premium pricing for REACH-registered, ultra-high-purity material without volume contraction.
China
Domestic feed additive production scaling drives concentrated demand for powder-grade sodium selenite in broiler and swine premix manufacturing. The Ministry of Agriculture and Rural Affairs maintains selenium inclusion limits in compound feed standards. Shandong Province hosts the densest cluster of selenium chemical processors serving regional livestock integrators with direct procurement contracts.
United States
Large poultry operations in the US Corn Belt negotiate volume contracts bypassing regional distributors, compressing intermediary margins. FDA GRAS notifications accelerate dietary supplement formulation approvals for mineral complex tablets. Greater Chicago serves as the primary distribution hub for Midwest feed compounders seeking technical service-inclusive supply agreements.
Germany
Premix manufacturers in Lower Saxony and North Rhine-Westphalia prioritize ECHA-registered suppliers with complete REACH substance dossiers. The German Federal Office of Consumer Protection and Food Safety enforces strict maximum residue limits for selenium in animal feed. Bavaria's biotechnology corridor demands ultra-high-purity grades for cell culture media applications with heavy metal limits below 10 ppm.
Netherlands
Specialized feed mills in Gelderland specify granule formats for automated dosing systems in livestock operations. ECHA registration requirements constrain import sourcing flexibility, favoring domestic or fully-registered European suppliers. The Rotterdam port cluster handles bulk powder shipments for redistribution across Benelux compound feed manufacturers.
India
Dietary supplement formulators in Maharashtra and Gujarat drive human nutritional fortification demand for tablet-grade material. The Food Safety and Standards Authority of India monitors selenium levels in fortified foods through mandatory testing protocols. Mumbai-Pune industrial corridor houses contract manufacturers serving domestic and export supplement brands with mineral complex formulations.
Food Grade Sodium Selenite Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated selenium chemistry platforms commanding premium formulation contracts while commodity traders face margin compression. The supplier base bifurcates into pharmaceutical-grade producers with captive reduction capabilities and toll-manufacturing dependent distributors. Three archetypes dominate: integrated chemical platforms with heavy metal control systems, specialized premix and formulation experts, and ultra-high-purity material specialists for biotechnology applications. Competitive moves concentrate on direct procurement relationships with livestock integrators and REACH dossier completion for European market access.
Within the integrated chemical platform tier, BASF SE and American Elements exemplify divergent strategic positioning. BASF SE anchors European supply security through its selenium chemistry platform, while American Elements occupies the ultra-high-purity segment for biotechnology applications. Orffa International Holding B.V. represents the specialized premix expertise archetype across European livestock markets. These three companies illustrate how purity specifications and registration capabilities determine competitive boundaries more than scale alone.
| Leading Market Players |
|---|
| American Elements |
| Salvi Chemical Industries Ltd. |
| Orffa International Holding B.V. |
| Jinhua Additives Co., Ltd. |
| Vital Materials Co., Limited |
| BASF SE |
| Sisco Research Laboratories Pvt. Ltd. |
| HiMedia Laboratories |
| Spectrum Laboratory Products, Inc. |
| Others |
Pricing and Supply Chain Analysis
REACH dossier requirements gate both supplier qualification and price differentiation simultaneously, forcing European compound feed manufacturers toward ECHA-registered sources while compressing margins for commodity-grade traders lacking registration certificates. This regulatory threshold bifurcates the market into premium-tier pharmaceutical-grade producers and cost-optimized standard-grade suppliers.
Pricing Analysis
Technical service contracts and formulation support agreements drive lifetime value beyond base material sales. Three-tier pricing structure across pharmaceutical-grade, feed-grade, and agricultural-grade levels separates ultra-high-purity specifications for biotechnology applications from standard powder for livestock premixes. Cost compression in feed-grade powder intensifies because Chinese domestic production scaling creates surplus capacity. Livestock integrators in the US Corn Belt exhibit highest price sensitivity, while German biotechnology purchasers absorb premium pricing without volume contraction.
Supply Chain Analysis
Inventory cycles stretch 8-12 weeks for REACH-registered drum shipments to European premix manufacturers, versus 4-6 weeks for standard bagged powder to Asian feed compounders. Manufacturing concentrates in China, Germany, and the United States, with Shandong Province hosting the densest selenium chemical processor cluster. Elemental selenium feedstock draws from mining operations in Canada, Australia, and Kazakhstan. Single-source vulnerability runs through China's dominance in selenium dioxide oxidation capacity. Distribution runs through direct procurement relationships displacing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward livestock integrators as direct procurement contracts displace regional distributors, concentrating volume with integrated chemical platforms capable of technical service delivery.
For Market Incumbents: Compound defensive positioning by completing ECHA substance dossiers for European market access and anchoring supply security through captive selenium dioxide oxidation capabilities. Selenomethionine substitution threatens ruminant feed applications with superior bioavailability claims. Backward integration into elemental selenium sourcing insulates against raw material cost swings from mining concentration. For New Entrants and Emerging Players: Differentiate on beverage fortification protocols by securing sub-5 ppm heavy metal certification that commodity traders struggle to obtain. Liquid concentrate formats for packaged water and functional drinks represent the most penetrable white space. Target North American and European supplement manufacturers with technical service-inclusive supply agreements bypassing established distributor networks. For Investors and Strategic Acquirers: REACH authorization timelines reshape the acquisition landscape toward ECHA-registered suppliers with complete substance dossiers. Long-term viability centers on integrated selenium chemistry platforms with heavy metal control systems rather than toll-manufacturing dependent traders. Watch for Codex Alimentarius maximum residue limit harmonization across emerging markets as inflection signal for export registration friction reduction.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Dossier Completion | ECHA registration unlocks European compound feed manufacturer procurement channels. |
| Backward Integration into Elemental Selenium | Captive reduction capabilities insulate against mining geography concentration risks. |
| Liquid Concentrate Format Expansion | Beverage fortification protocols open packaged water channels previously inaccessible to powders. |
| Direct Procurement Relationship Development | Livestock integrators in the US Corn Belt negotiate volume contracts bypassing distributors. |
| Ultra-High-Purity Certification Investment | Sub-10 ppm heavy metal limits serve Bavaria biotechnology corridor cell culture media demand. |
Research Methodology
Initial hypotheses were tested against primary input from selenium chemical plant managers, premix manufacturer procurement leads, livestock integrator nutrition directors, and REACH compliance consultants, and refined through secondary validation against customs trade data, ECHA registration databases, FDA GRAS notification filings, and compound feed industry association reports. Bottom-up volume estimates from end-use consumption patterns were triangulated with top-down production capacity assessments across registered manufacturing facilities.
Variance decomposition across purity grade, end-use application, packaging format, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers. Forecast inputs incorporated selenium yeast displacement elasticity in ruminant nutrition and beverage fortification protocol standardization timelines.
Forecasts assume regulatory continuity in REACH authorization procedures and FDA GRAS notification frameworks; material policy shifts would require re-modeling. Selenium speciation testing capability scarcity and multi-jurisdiction registration timeline extensions represent specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Antimicrobial Additives Market
Food Additives and Ingredients
Beverage Acidulants Market
Food Additives and Ingredients
United Kingdom Food Colorants Market
Food Additives and Ingredients
Global Canthaxanthin Market
Food Additives and Ingredients
Beverage Clouding Agent Market
Food Additives and Ingredients
Food Grade Magnesium Derivatives Market
Food Additives and Ingredients
Global Baking Powder Market
Food Additives and Ingredients
China Monosodium Glutamate (MSG) Market
Food Additives and Ingredients
Gardenia Food Color Market
Food Additives and Ingredients
Agar Agar Gum Market
Food Additives and Ingredients
Natural Food and Beverage Preservatives Market
Food Additives and Ingredients
Potassium Propionate Market
Food Additives and Ingredients
Food Grade Acetic Acid Market
Food Additives and Ingredients
Italy Sodium Reduction Ingredients Market
Food Additives and Ingredients
Food Stabilizer Systems Market
Food Additives and Ingredients
Asia-Pacific Food Emulsifier Market