
 North America Feed Additives Market | 2026-2036
North America Feed Additives Market Size, Share, and Industry Trends Forecast 2026-2036
North America Feed Additives Market Analytics
Premium traceability tiers is decoupling from commodity bulk supply in North American feed additives as integrators demand verified mycotoxin binders and enzyme cocktails with full chain-of-custody documentation. Cargill Incorporated leverages its captive grain handling network to pre-condition additive blends at origination points. BASF SE anchors its position through in-house fermentation capacity for natamycin and organic acid production. Kemin Industries differentiates via specialized antioxidant and mold-inhibitor formulations tailored to high-heat extrusion environments.
Feed additives comprise biologically active substances including vitamins, amino acids, minerals, and acidifiers that are incorporated into compound feeds at inclusion rates typically ranging from 0.01% to 5% by weight to enhance nutrient digestibility, preserve feed integrity, or support animal physiological function. Amino acid formulations, particularly lysine, methionine, and threonine, dominate value contribution as synthetic production economics displace protein meal dependence in least-cost ration formulations. Phytase and non-starch polysaccharide enzymes represent the fastest-expanding product class as corn-soy diet reformulation reduces phosphorus excretion compliance costs for contract growers. Poultry application channels command disproportionate margin pools due to short grow-out cycles and intensive veterinary oversight requirements.
The FDA's Veterinary Feed Directive and state-level feed regulatory programs administered through the Association of American Feed Control Officials constrain antibiotic growth promoter access, compelling reformulation toward ionophore coccidiostats and botanical extracts. The Canadian Food Inspection Agency and Mexico's national sanitary authority enforce parallel residue monitoring protocols that shape cross-border ingredient approval timelines and label claim substantiation requirements. Stakeholders must monitor pending EPA nutrient management rulemakings and emerging state ballot initiatives on livestock housing density that could redirect additive demand toward gut health and stress mitigation categories.
Market Dynamics
The FDA's Veterinary Feed Directive has fundamentally restructured antibiotic inclusion protocols across United States livestock operations, redirecting capital flows toward phytogenic and acidifier alternatives while compressing legacy growth promoter margins.
Growth Catalysts
- Regulatory Phase-Out Mandates:The FDA's Veterinary Feed Directive and parallel Canadian Food Inspection Agency protocols eliminate sub-therapeutic antibiotic use, forcing integrators toward ionophore coccidiostats and botanical extracts.
- Phosphorus Extraction Economics:Phytase enzyme adoption accelerates as corn-soy diet reformulation reduces compliance costs for contract growers facing EPA nutrient management scrutiny.
- Texas Panhandle Concentration:Broiler and layer integrators operating at scale in the Texas Panhandle and Corn Belt states generate concentrated demand for verified mycotoxin binders with full chain-of-custody documentation.
Market Restraints
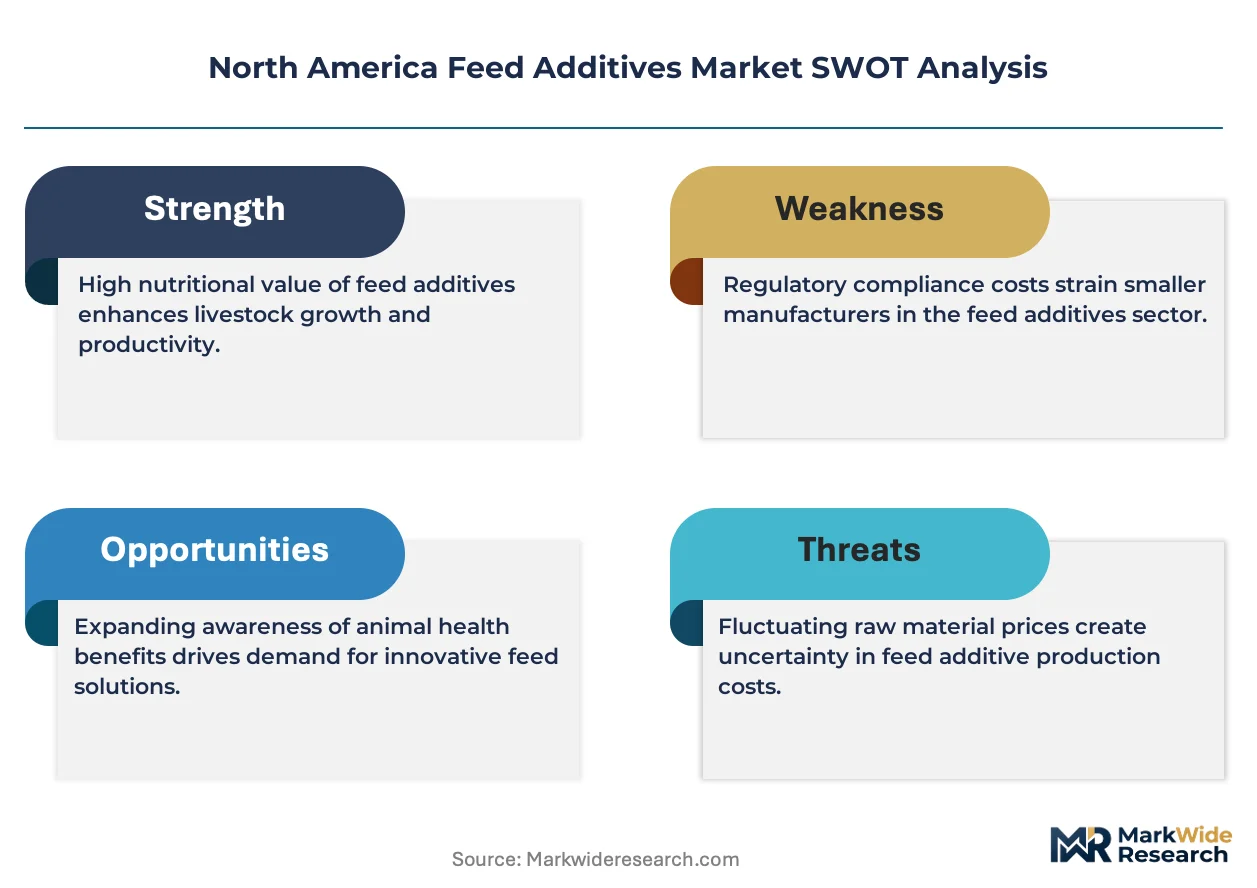
- Fermentation Input Volatility:Organic acid and natamycin production costs fluctuate with corn dextrose and soybean meal feedstock pricing, squeezing margin stability for in-house fermentation operators.
- Cross-Border Approval Friction:Mexico's national sanitary authority enforces residue monitoring protocols that extend label claim substantiation timelines, delaying product launches in integrated North American supply chains.
- Protein Meal Substitution Ceiling:Synthetic amino acid economics face physical limits in least-cost ration formulations where crude protein minimums constrain full displacement of fish meal and blood meal.
Strategic Opportunities
- Quebec and Ontario Dairy Expansion:Canadian ruminant operations underutilize live yeast and direct-fed microbial additives relative to United States penetration rates, creating white space for gut health category entrants.
- Heat-Stress Formulation Gap:Specialized antioxidant and mold-inhibitor blends tailored to high-heat extrusion environments remain underdeveloped for southeastern United States poultry operations facing intensifying summer temperature extremes.
- State Ballot Initiative Tailwinds:Emerging California and Massachusetts livestock housing density restrictions redirect additive demand toward stress mitigation and immune modulation categories as production systems adapt.
Industry Challenges
- Fermentation Scale-Up Talent Scarcity:Microbial strain optimization and bioreactor engineering expertise concentrates among a narrow cohort of specialists, constraining rapid capacity expansion for live probiotic manufacturers.
- Multi-Jurisdiction Label Harmonization:Divergent Association of American Feed Control Officials state-level enforcement and Canadian bilingual labeling requirements fragment packaging and compliance workflows.
- Extrusion Thermal Stability Validation:Enzyme and probiotic efficacy claims require expensive pelleting temperature challenge studies, extending product development cycles before commercial rollout.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Feed Additives Market |
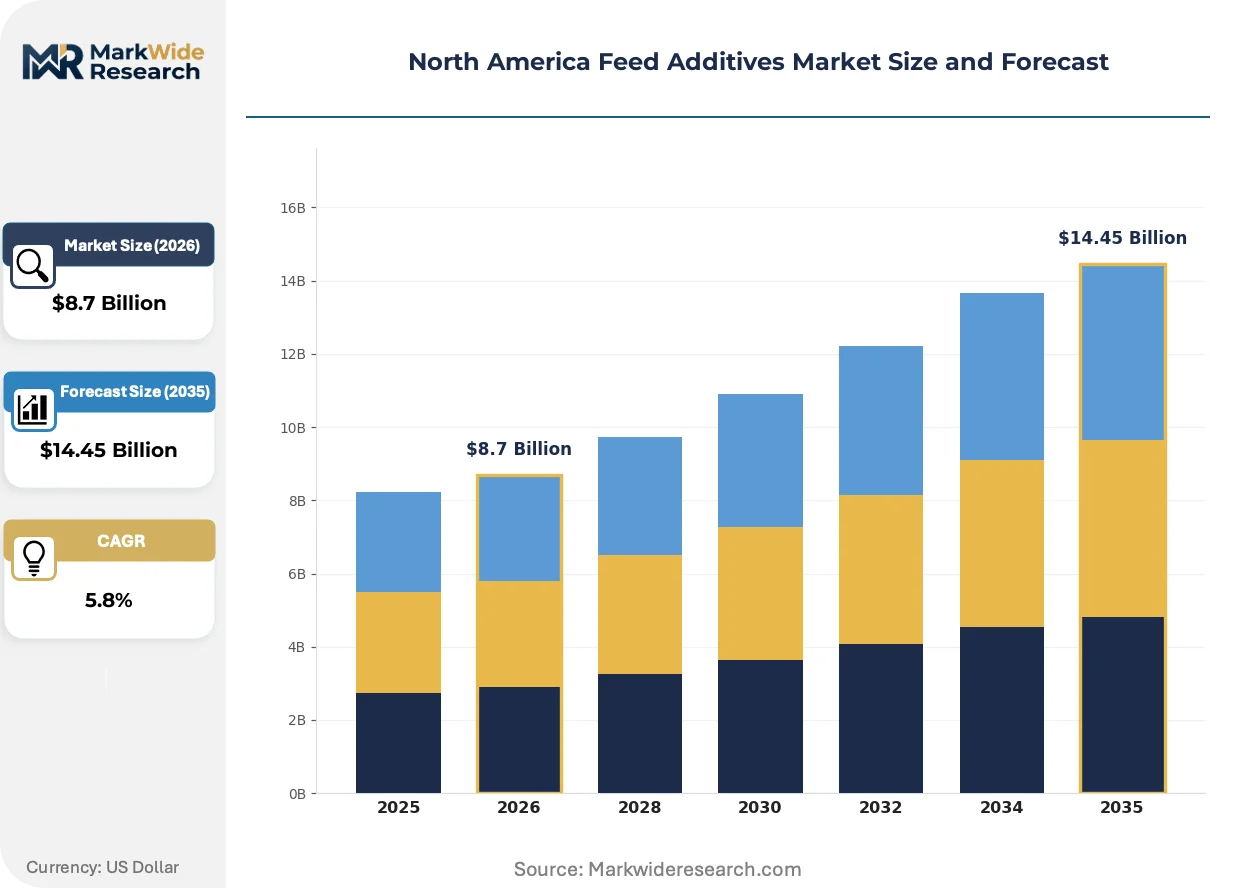
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
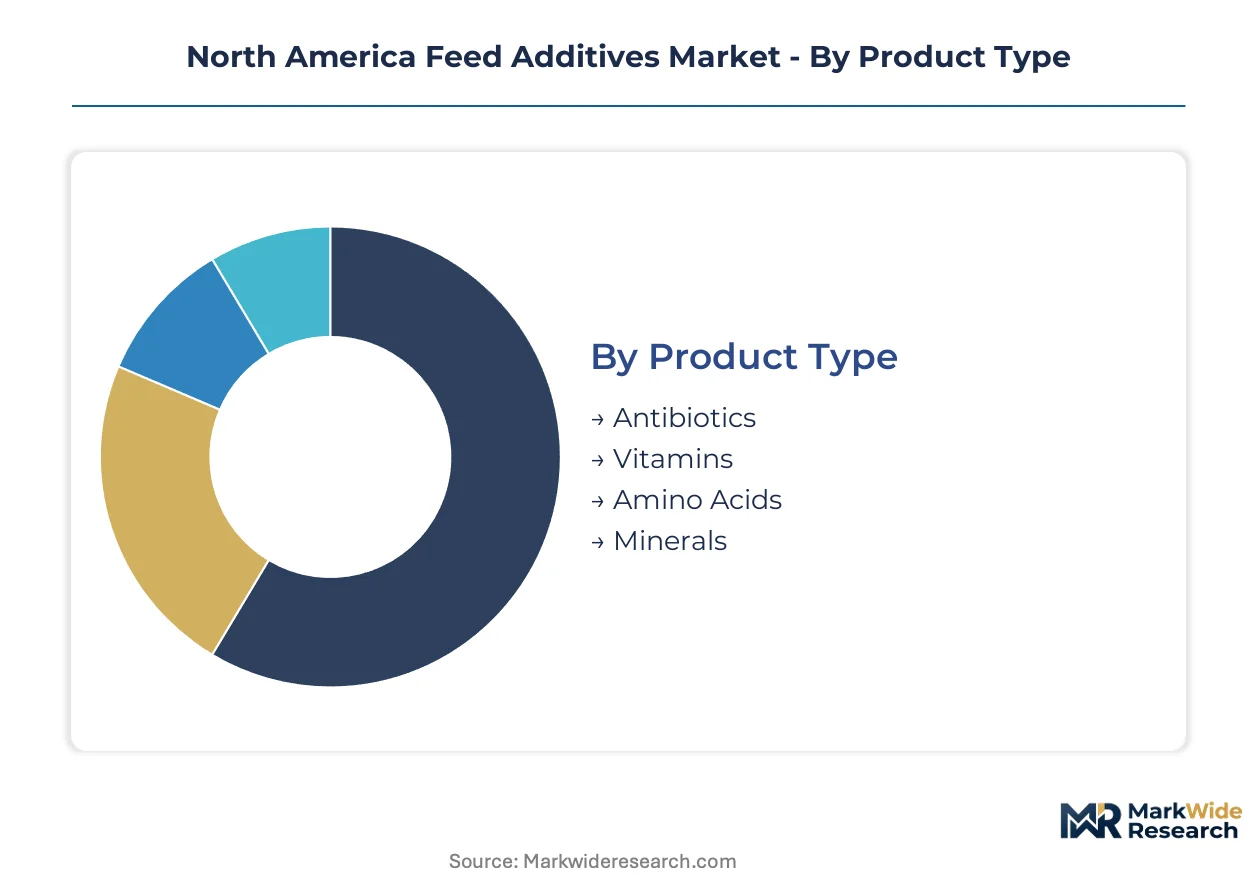
| Segmentation | Product Type: Antibiotics, Vitamins, Amino Acids, Minerals Application: Poultry, Ruminants, Swine, Aquaculture Form: Liquid, Powder, Granular, Pellet End User: Farmers, Feed Manufacturers, Livestock Producers, Companion Animal Owners |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Co., DSM-Firmenich AG, Evonik Industries AG, BASF SE, Nutreco N.V., Adisseo, Kemin Industries, Alltech, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Feed Additives Market Evolving Landscape
Precision fermentation and enzyme engineering are compressing traditional chemical synthesis pathways, while regulatory pressure on antibiotic residues accelerates botanical extract standardization across North American livestock supply chains.
Microencapsulation technology for heat-sensitive probiotics is converging with high-temperature pelleting processes that dominate United States broiler feed manufacturing. Major integrators in the southeastern states now specify thermostable Bacillus strain formulations as contract requirements. This convergence is compressing legacy unprotected freeze-dried probiotic margins and forcing reformulation investments.
The EPA's pending nutrient management rulemakings and state-level phosphorus runoff restrictions are reshaping mineral premix specifications across the Corn Belt. Swine and dairy operations face mandatory manure phosphorus reduction targets that drive phytase superdosing and novel magnesium oxide binder adoption. Layer operations in Iowa and Minnesota are responding with diet reformulation services bundled directly into additive procurement contracts.
Integrator consolidation across the Texas Panhandle and Georgia poultry corridors is compressing distributor intermediation. Direct contracting between Cargill's captive grain handling network and large-scale growers displaces traditional feed dealer channels for acidifier and enzyme purchases. This channel compression is most visible in 500,000-plus bird single-site operations where procurement teams negotiate additive blends at origination points rather than through compound feed manufacturers.
North America Feed Additives Market Segmentation
Feed additive purchasing patterns diverge sharply across North American livestock sectors. Veterinary oversight intensity, feed manufacturing scale, and regulatory compliance burdens reshape how integrators evaluate product categories.
Product Type:
Cost sensitivity and formulation complexity separate commodity buyers from premium-tier purchasers across United States and Canadian operations.
- Amino Acids:Synthetic lysine, methionine, and threonine formulations displace protein meals in least-cost rations. Corn Belt swine and poultry integrators drive volume as crude protein minimums constrain full fish meal substitution.
- Minerals:Chelated trace elements and novel magnesium oxide binders address EPA phosphorus runoff scrutiny. Iowa and Minnesota layer operations bundle diet reformulation services directly into procurement contracts.
- Vitamins:Fat-soluble and B-complex premixes stabilize under high-heat extrusion conditions.
- Antibiotics:FDA Veterinary Feed Directive constraints compress sub-therapeutic growth promoter access; ionophore coccidiostats retain market presence.
Volume sits with amino acids; growth tilts toward mineral binders.
Application:
Species-specific biology dictates additive selection criteria and margin capture potential across production systems.
- Poultry:Short grow-out cycles and intensive veterinary oversight concentrate margin pools. Texas Panhandle and Georgia broiler integrators specify thermostable Bacillus strains and verified mycotoxin binders with chain-of-custody documentation.
- Swine:Phytase superdosing accelerates as EPA nutrient management rulemakings tighten manure phosphorus limits. Corn Belt contract growers face mandatory reduction targets.
- Ruminants:Live yeast and direct-fed microbials remain underutilized in Canadian dairy relative to United States penetration.
- Aquaculture:Specialized formulations for high-density recirculating systems command technical specification premiums.
Poultry dominates current procurement spend; swine mineral reformulation climbs fastest.
Form:
Manufacturing process compatibility and storage stability differentiate procurement specifications across feed mill infrastructure.
- Powder:Standard inclusion for vitamin premixes and amino acids in mash feed operations. Dust control and segregation resistance drive formulation priorities.
- Liquid:Acidifier blends and oil-soluble vitamins integrate into post-pelleting application systems. Large-scale United States integrators favor automated dosing precision.
- Granular:Intermediate flowability for mineral premixes and certain enzyme preparations.
- Pellet:Microencapsulated probiotics and heat-sensitive enzymes require thermal stability validation through pelleting challenge studies.
Powder retains installed base dominance; liquid acidifiers gain share in automated mills.
End User:
Scale and vertical integration depth fragment purchasing authority across the value chain.
- Feed Manufacturers:Compound feed producers specify additive blends for least-cost formulation software. Cargill's captive grain handling network pre-conditions blends at origination points, displacing traditional dealer channels.
- Livestock Producers:500,000-plus bird single-site poultry operations negotiate direct contracts for acidifier and enzyme procurement, bypassing compound feed intermediation.
- Farmers:Smaller operations depend on distributor networks for premix access and technical support.
- Companion Animal Owners:Premium pet food manufacturers drive specialized antioxidant and palatant demand.
Procurement authority concentrates with livestock producers; feed manufacturers defend formulation service relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Texas Panhandle anchors North American feed additive demand concentration, where broiler and layer integrators operate at sufficient scale to negotiate direct procurement contracts for acidifier and enzyme formulations.
United States
Corn Belt swine operations and southeastern poultry corridors drive phytase enzyme and thermostable probiotic uptake. The FDA's Veterinary Feed Directive eliminates sub-therapeutic antibiotic growth promoters, redirecting formulation spend toward ionophore coccidiostats and botanical extracts. Iowa and Minnesota layer operations bundle diet reformulation services directly into mineral premix procurement contracts.
Canada
Quebec and Ontario dairy operations underutilize live yeast and direct-fed microbials relative to United States penetration rates, creating expansion white space for gut health category entrants. The Canadian Food Inspection Agency enforces residue monitoring protocols that parallel FDA timelines and shape cross-border ingredient approval synchronization. Prairie feed mill consolidation in Alberta and Saskatchewan concentrates procurement authority with compound feed manufacturers.
Mexico
Poultry integrators in the Bajío region and Nuevo León generate concentrated demand for mycotoxin binders as corn quality variability intensifies with climate stress. The national sanitary authority extends label claim substantiation timelines, delaying product launches in integrated North American supply chains. Mexico City Metro feed manufacturers serve as distribution nodes for acidifier blends moving into central Mexico swine operations.
North America Feed Additives Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and regulatory documentation capabilities. The vendor base stratifies between integrated agribusiness conglomerates with captive grain networks and specialized additive houses with fermentation or extraction expertise. Three archetypes dominate: diversified nutrition platforms with backward grain origination control, microbial fermentation specialists with strain optimization capabilities, and precision-blend formulators with extrusion thermal stability validation. Competitive moves concentrate on direct contracting with 500,000-plus bird single-site operations and pre-conditioning additive blends at grain origination points.
Within the diversified nutrition platform tier, Cargill Incorporated and Archer Daniels Midland Co. occupy positions defined by captive grain handling infrastructure and least-cost formulation software integration. BASF SE anchors the chemical synthesis and fermentation specialist segment. These three exemplify how scale-driven procurement concentration across the Texas Panhandle and Corn Belt states rewards players with upstream supply control and automated dosing system compatibility.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Co. |
| DSM-Firmenich AG |
| Evonik Industries AG |
| BASF SE |
| Nutreco N.V. |
| Adisseo |
| Kemin Industries |
| Alltech |
| Others |
Value Network & Pricing Analysis
Corn dextrose futures and soybean meal spot indices cascade through North American feed additive manufacturing, compressing margins for in-house fermentation operators while amplifying pricing power for integrated grain handlers that precondition additive blends at origination points. The interaction between raw material volatility and captive supply networks stratifies procurement economics across commodity bulk and premium traceability tiers.
Pricing Analysis
Yield-per-ton feed conversion ratios anchor value-based pricing for phytase enzymes and thermostable probiotic formulations, with integrators paying premiums for verified phosphorus extraction outcomes. Three-tier pricing structure across premium, standard, and economy levels separates chain-of-custody certified mycotoxin binders from unverified commodity alternatives. Cost compression in standard-tier amino acids intensifies as synthetic lysine capacity expands, while least-cost formulation software users in the Corn Belt exhibit highest price sensitivity and Texas Panhandle integrators accept premium positioning for documented efficacy.
Supply Chain Analysis
Direct-to-integrator channels handle demand from 500,000-plus bird single-site operations, displacing traditional feed dealer intermediation for acidifier and enzyme procurement. Fermentation capacity concentrates in the United States, Canada, and Mexico, with microbial strain optimization expertise anchoring in the Midwest. Corn dextrose and soybean meal feedstock dependencies tether production economics to grain futures volatility. Single-source vulnerability around thermostable Bacillus strain suppliers elevates supply risk for southeastern poultry operations. Distribution runs through Cargill's captive grain handling network and compound feed manufacturers defending formulation service relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation scale-up talent scarcity constrains rapid live probiotic capacity expansion, propping pricing for qualified suppliers across the analysis window. Supply constraints favor incumbents with existing bioreactor infrastructure and strain libraries.
For Market Incumbents: Anticipate regulatory acceleration of EPA nutrient management rulemakings by securing phytase superdosing formulation partnerships with Iowa and Minnesota layer operations before compliance mandates harden. Defend margin position through backward integration into captive corn dextrose supply and pre-conditioning infrastructure at grain origination points. Botanical extract standardization investments will differentiate positioning as FDA Veterinary Feed Directive enforcement tightens. For New Entrants and Emerging Players: The price-point gap between premium traceability-tier mycotoxin binders and economy-grade alternatives opens entry space for mid-tier verified products with partial chain-of-custody documentation. Quebec and Ontario dairy operations present the most penetrable geography, with live yeast and direct-fed microbial penetration trailing United States benchmarks by substantial margins. A formulation-service bundling go-to-market angle, pairing gut health additives with diet reformulation consulting, bypasses direct competition with established premix suppliers. For Investors and Strategic Acquirers: Distressed-cycle entries favor microbial fermentation specialists with validated thermostable strain libraries in the United States Midwest, where talent scarcity has stalled greenfield capacity builds. Long-term viability across a 5-10 year window rests on regulatory tailwinds for antibiotic alternatives and phosphorus compliance economics. The signal to watch is EPA finalization of manure phosphorus reduction targets, which would accelerate contract grower demand for phytase and mineral binder reformulation services.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Dextrose Supply | Captive feedstock sourcing insulates BASF and ADM from fermentation input volatility squeezing margin stability. |
| Pre-Conditioning Infrastructure at Grain Origination | Cargill's origination-point blending displaces compound feed intermediation for Texas Panhandle integrators. |
| Phytase Superdosing Formulation Partnerships | Layer operation contracts in Iowa and Minnesota bundle diet reformulation services into mineral premix procurement. |
| Thermostable Probiotic Strain Development | Microencapsulation R&D addresses pelleting temperature challenges specified by southeastern poultry integrators. |
| Chain-of-Custody Certification Investment | Verified mycotoxin binder documentation commands premium positioning from 500,000-plus bird operations. |
Research Methodology
Independent corroboration across feed mill procurement managers, veterinary nutritionists, and regulatory affairs specialists at additive manufacturers underwrites the qualitative findings in this study. Primary interviews with integrator formulation directors, compound feed plant managers, and Association of American Feed Control Officials state enforcement personnel combined with secondary validation from FDA Veterinary Feed Directive guidance documents, EPA nutrient management proposals, Canadian Food Inspection Agency residue protocols, and SEC 10-K filings from listed agribusiness conglomerates. Bottom-up volume modeling and top-down value reconciliation triangulate market sizing across the projection horizon.
Rate-of-change decomposition separates volume growth from price mix effects across amino acid, mineral, vitamin, enzyme, and phytogenic product categories. Segmentation dimensions modeled include species application, formulation complexity tier, thermal stability requirements, and procurement channel structure. CAGRs derive from historical trajectory analysis adjusted for regulatory inflection points and integrator consolidation patterns. Industry-specific forecast inputs incorporate EPA rulemaking timelines and FDA enforcement phase-in schedules without year-specific anchoring.
Inputs from primary stakeholder interviews and published regulatory guidance were available through the study window; gaps in real-time integrator procurement contract terms introduce uncertainty bands around direct contracting share estimates. Forecasts reflect assumptions regarding Veterinary Feed Directive compliance adoption curves and phosphorus reduction target implementation pacing. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Germany Feed Additives Market
Food Additives and Ingredients
Tara Gum Market
Food Additives and Ingredients
Flavor Encapsulation Market
Food Additives and Ingredients
Germany Anticaking Market
Food Additives and Ingredients
Non-GMO Citric Acid Market
Food Additives and Ingredients
Monosodium Glutamate Market
Food Additives and Ingredients
Italy Sodium Reduction Ingredients Market
Food Additives and Ingredients
South Africa Food Colorants Market
Food Additives and Ingredients
Aluminum-Free Natural Food Color Market
Food Additives and Ingredients
Clean Label Food Ingredient Market
Food Additives and Ingredients
North America Food Additives Market
Food Additives and Ingredients
Cocoglycerides Market
Food Additives and Ingredients
Bread Emulsifier Market
Food Additives and Ingredients
Ascorbyl Palmitate Market
Food Additives and Ingredients
Calcium Inosinate Market
Food Additives and Ingredients
Canada Food Enzymes Market