
 Amaranth (E123) Market | 2026-2036
Amaranth (E123) Market Size, Share, and Industry Trends Forecast 2026-2036
Amaranth (E123) Market Insights
The EU F-Gas Regulation and escalating clean-label mandates from European food retailers is restructuring procurement priorities for synthetic colorants. Chr. Hansen Holding A/S leverages its bioscience platform to develop natural alternatives that compete with traditional synthetic offerings. GNT Group anchors its position through plant-based extraction technologies that align with tightening sustainability requirements. Zhejiang Dragoi Colour Technology dominates bulk synthetic production, serving cost-sensitive manufacturers across Asia.
Amaranth (E123) is a synthetic azo dye, chemically designated as trisodium 2-hydroxy-1-(4-sulfonato-1-naphthylazo)naphthalene-3,6-disulfonate, producing a blue-red hue in aqueous solutions at pH 3-7, primarily employed to standardize color appearance in processed foods, beverages, and pharmaceutical coatings. Synthetic colorants occupy the largest volume share due to cost efficiency and batch consistency, though natural colorants represent the fastest-expanding category as certification requirements intensify. The food industry application segment commands the deepest margin pools, while pharmaceutical-grade certification demands command premium positioning across FDA Approved and Kosher Certified tiers.
REACH restrictions on azo dyes and FDA color additive petitions shape permissible applications, with EFSA evaluations driving reformulation timelines across European manufacturers. India's FSSAI and China's SAMR maintain divergent approval lists, fragmenting market access protocols for multinational suppliers. Stakeholders must monitor pending regulatory reclassifications that could abruptly restrict synthetic azo dye deployment in children's products and confectionery segments.
Market Dynamics
REACH restrictions on azo dyes are fragmenting formulation standards across European manufacturers, forcing simultaneous compliance with divergent national approval lists while Indian and Chinese producers exploit regulatory arbitrage to capture displaced volume.
Growth Catalysts
- Processed Food Standardization:Beverage manufacturers in India require batch-consistent synthetic colorants to maintain product uniformity across distributed production networks. FSSAI certification mandates accelerate certified additive procurement.
- Pharmaceutical Coating Demand:Tablet and capsule coating operations in China expand consumption of pharmaceutical-grade E123 as SAMR tightens excipient quality protocols.
- Emerging Market Industrialization:Nigeria and Egypt scale processed food manufacturing, importing certified colorants to meet domestic packaging and export compliance requirements.
Market Restraints
- Petrochemical Feedstock Volatility:Naphthalene derivative prices fluctuate with crude oil benchmarks, compressing margin predictability for azo dye synthesis operations.
- Regulatory Asymmetry:EFSA evaluations and FDA color additive petitions proceed on incompatible timelines, forcing dual-track compliance investments without harmonized standards.
- Natural Colorant Substitution:Beetroot anthocyanins and carmine alternatives displace synthetic azo dyes in premium confectionery and clean-label beverage segments.
Strategic Opportunities
- Pharmaceutical-Grade Certification:Kosher and Halal certification tiers command premium positioning in Middle Eastern and North African markets with underserved supply infrastructure.
- Microencapsulation Convergence:Spray-drying technology combined with modified starch carriers enables heat-stable E123 formulations for baked goods applications previously closed to synthetic dyes.
- Direct Distribution Channels:E-procurement platforms bypass traditional chemical distributor markups, connecting Indian manufacturers directly with African and Southeast Asian processors.
Industry Challenges
- Analytical Chemistry Talent Scarcity:Spectrophotometric assay expertise and HPLC method development capabilities remain concentrated in legacy European and Japanese laboratory networks.
- Reformulation Timeline Compression:Pending EFSA reclassifications demand 12-18 month product redevelopment cycles without guaranteed approval outcomes.
- Legacy Equipment Integration:Continuous flow reactors for azo coupling chemistry require capital deployment incompatible with depreciated batch reactor assets at mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amaranth (E123) Market |
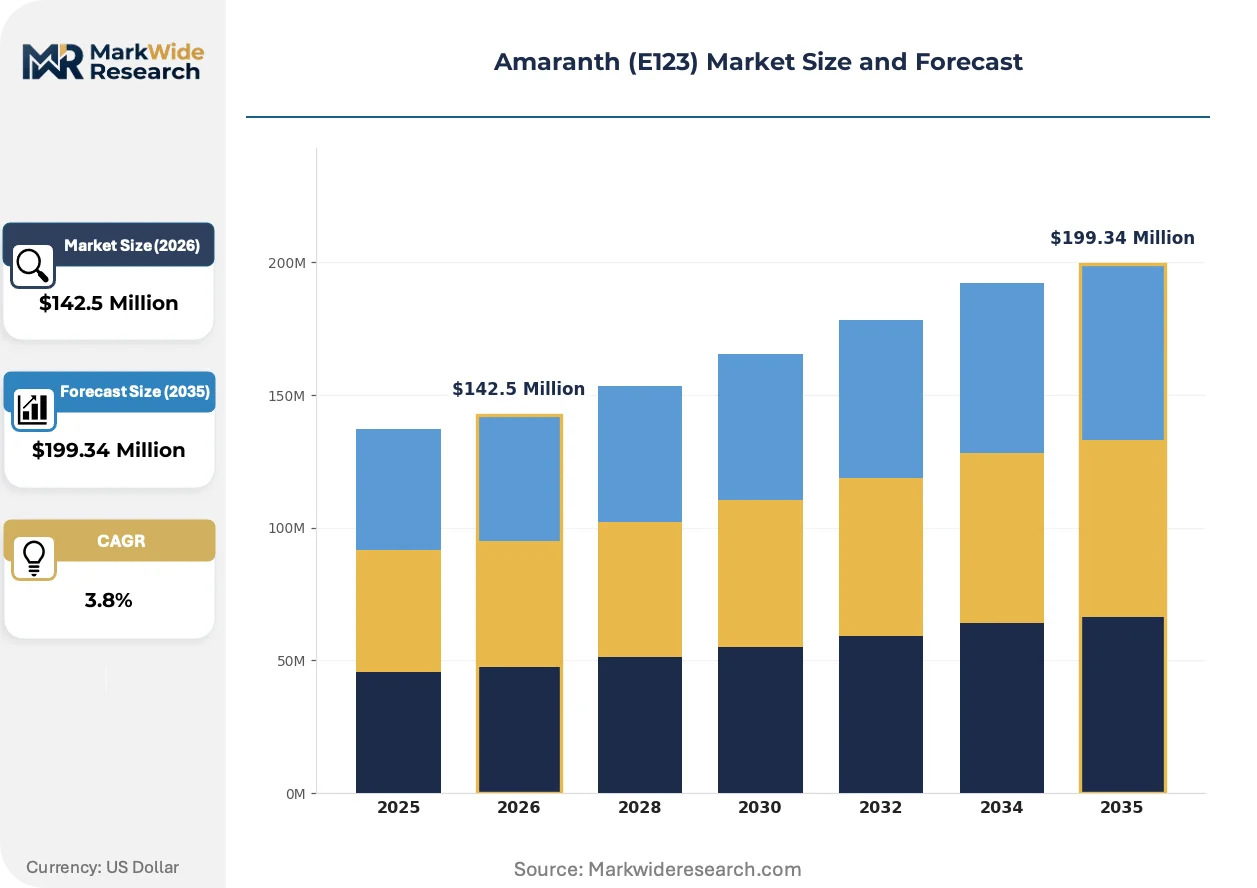
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $199.34 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Colorants, Synthetic Colorants, Liquid Colorants, Powder Colorants Application: Food Industry, Beverage Industry, Cosmetics, Pharmaceuticals End User: Manufacturers, Retailers, Distributors, Consumers Certification: FDA Approved, Organic Certified, Non-GMO Verified, Kosher Certified |
| Companies Covered | Zhejiang Dragoi Colour Technology, FMC Corporation, Sensient Cosmetic Technologies, DDW The Color House, Clariant, Vidhi Dyestuffs, Chr. Hansen Holding A/S, GNT Group, Vivify, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amaranth (E123) Market Trends and Innovations
Clean-label pressure and regulatory fragmentation are accelerating technology diversification across colorant supply chains, with automation and extraction methods displacing conventional synthesis pathways.
Continuous flow reactor technology is automating azo coupling reactions that previously required batch-wise temperature control and manual pH adjustment. Indian and Chinese bulk manufacturers adopt these systems to reduce solvent waste and improve lot-to-lot consistency. The technology is automating quality assurance overhead while compressing unit economics for commodity-grade E123 production.
EU F-Gas Regulation and escalating CSRD disclosure mandates are restructuring procurement priorities for synthetic inputs across European food manufacturing. Manufacturers now face Scope 3 emissions accounting requirements that disadvantage petrochemical-derived colorants against plant-based alternatives. German and French retailers are responding with supplier sustainability scorecards that exclude non-certified synthetic dye sources.
Buyer concentration among multinational food processors is consolidating specification power into centralized procurement functions with dedicated colorant technologists. Traditional distributor relationships fragment as direct technical partnerships with manufacturers replace transactional supply arrangements. This pattern concentrates most visibly in North American beverage and confectionery headquarters where formulation decisions cascade to global production networks.
Amaranth (E123) Market Segmentation
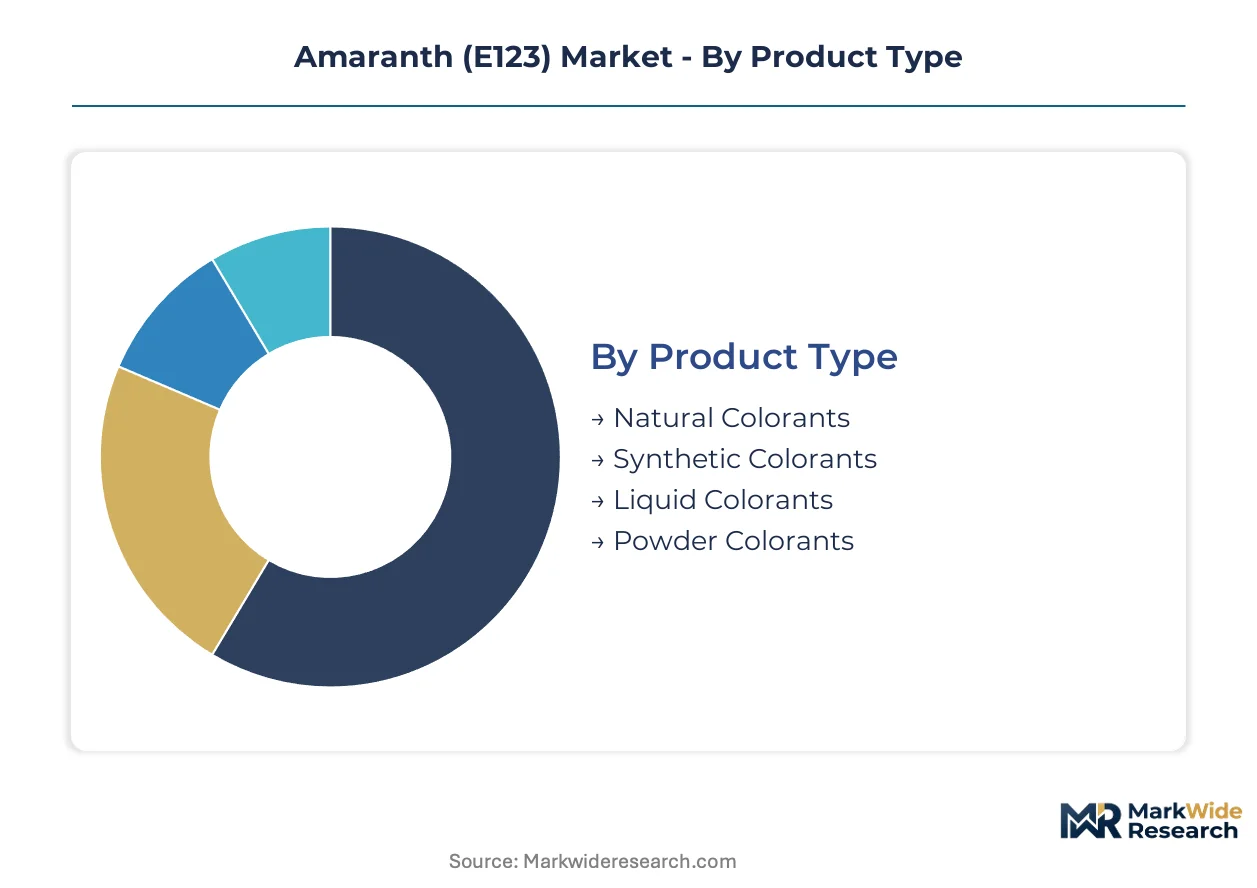
Amaranth (E123) procurement decisions hinge on regulatory certification tiers, application-specific purity requirements, and supply chain reliability across fragmented approval regimes. Buyers prioritize batch consistency and documentation packages that satisfy divergent national standards.
Product Type:
Cost efficiency and formulation stability drive manufacturer selection between synthetic and natural alternatives.
- Synthetic Colorants:Petrochemical-derived azo dyes deliver standardized hue intensity and shelf stability for mass-market processed foods. Indian beverage manufacturers favor synthetic E123 for distributed production networks requiring batch uniformity under FSSAI protocols.
- Natural Colorants:Plant-extracted alternatives command premium positioning as EU retailers enforce clean-label procurement mandates. Beetroot anthocyanins and carmine substitutes displace synthetic options in premium confectionery segments facing EFSA scrutiny.
- Liquid Colorants:Pre-dispersed solutions reduce manufacturing complexity for beverage processors.
- Powder Colorants:Concentrated dry forms optimize shipping economics for bulk pharmaceutical coating operations.
Volume sits with Synthetic Colorants; growth tilts toward Natural Colorants.
Application:
End-use regulatory exposure determines margin structure and certification investment requirements.
- Food Industry:Processed food manufacturers consume standardized E123 for uniform color appearance across packaged goods. Nigeria and Egypt scale imports of certified colorants to meet domestic packaging compliance and export requirements.
- Pharmaceuticals:Tablet and capsule coating operations demand pharmaceutical-grade E123 with full excipient documentation. SAMR tightening of quality protocols in China accelerates certified additive procurement for drug manufacturers.
- Beverage Industry:Soft drink producers require heat-stable formulations for pasteurized products.
- Cosmetics:Personal care applications face stricter dermal exposure limits in European formulations.
Revenue concentrates in Food Industry; Pharmaceuticals climb the fastest on certification premiums.
End User:
Supply chain position dictates technical support requirements and volume pricing leverage.
- Manufacturers:Direct procurement from dye producers enables custom formulation development and regulatory documentation packages. Multinational food processors centralize colorant decisions at headquarters with dedicated formulation technologists.
- Distributors:Traditional chemical distributors face margin compression as e-procurement platforms connect Indian producers directly with African and Southeast Asian processors.
- Retailers:Private-label brands demand traceability documentation for sustainability scorecards.
- Consumers:Artisanal food producers purchase small-batch certified colorants through specialty channels.
Procurement gravity centers on Manufacturers; Distributors face the steepest structural pressure.
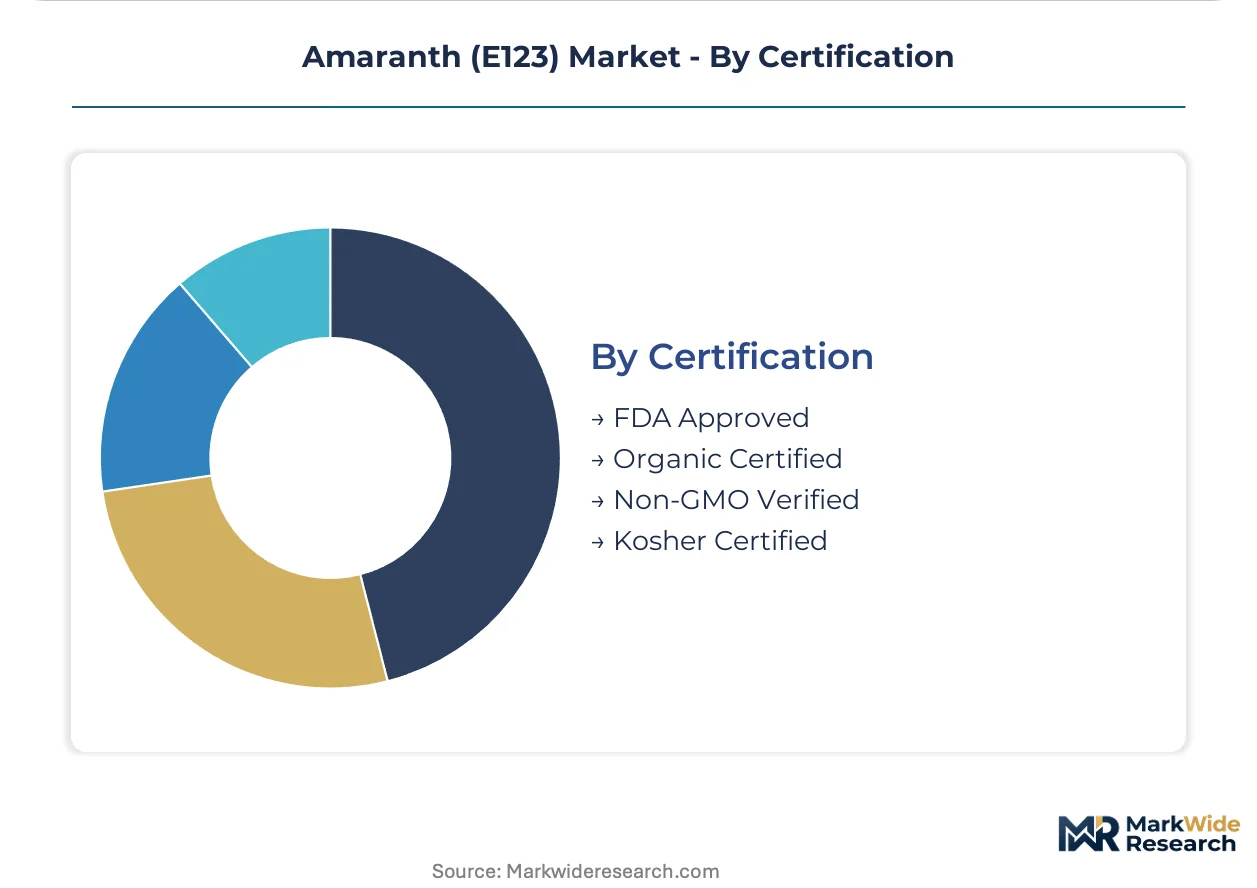
Certification:
Documentation tier separates accessible commodity supply from premium-positioned specialty grades.
- FDA Approved:Color additive petition compliance enables US market access for food and pharmaceutical applications. Dual-track investments with EFSA timelines strain multinational formulation budgets.
- Kosher Certified:Religious dietary compliance opens Middle Eastern and North African markets with underserved supply infrastructure. Certification premiums reward dedicated production line segregation.
- Organic Certified:Plant-derived alternatives qualify for clean-label positioning in European retail channels.
- Non-GMO Verified:Biotechnology-free documentation responds to retailer sustainability procurement mandates.
Accessibility clusters around FDA Approved; Kosher Certified captures the widest premium expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Chinese and Indian chemical manufacturing clusters while consumption fragments across regulatory jurisdictions with divergent approval standards. The report identifies five national markets where formulation requirements and certification protocols drive distinct procurement patterns.
China
Pharmaceutical coating operations in Jiangsu and Zhejiang provinces consume pharmaceutical-grade E123 as SAMR tightens excipient quality documentation. The national drug regulator accelerates certified additive procurement timelines for tablet manufacturers. Shanghai-based chemical distributors serve both domestic drug makers and export markets across Southeast Asia.
India
FSSAI mandates for packaged beverages and confectionery drive certified colorant procurement from Maharashtra and Gujarat production facilities. The food safety authority maintains strict batch testing protocols for synthetic azo dyes entering the domestic supply chain. Mumbai-Pune industrial corridor hosts formulation laboratories serving pan-Indian beverage distribution networks.
United States
FDA color additive petition requirements structure market access for E123 in food and pharmaceutical applications. The regulator maintains separate approval tracks for synthetic dyes versus natural alternatives, forcing dual compliance investments. New Jersey and Pennsylvania chemical processing clusters supply certified colorants to multinational food headquarters in Chicago and Minneapolis.
Germany
REACH restrictions on azo dyes and escalating CSRD disclosure mandates restructure procurement priorities for synthetic inputs. ECHA evaluations proceed on timelines incompatible with FDA processes, fragmenting formulation standards. BASF-Ludwigshafen chemical corridor manufacturers reformulate product lines to meet retailer sustainability scorecards excluding petrochemical-derived colorants.
Nigeria
Processed food manufacturing expansion in Lagos and Kano industrial zones drives import demand for certified colorants meeting ECOWAS packaging standards. The national food and drug regulator strengthens import inspection protocols for synthetic additives. Nigerian beverage bottlers source E123 through direct procurement channels from Indian manufacturers bypassing European distributor markups.
Amaranth (E123) Market Competitive Landscape
The competitive structure tilts toward bulk synthetic producers with regulatory certification depth over specialized natural extract suppliers. Tiered positioning separates pharmaceutical-grade certifiers from commodity food-grade suppliers, with mid-scale players facing margin compression from continuous flow reactor investments at scale leaders. Three archetypes dominate: petrochemical-integrated azo dye specialists, bioscience-platform natural alternatives developers, and plant-extraction technology providers. Capacity expansion and certification portfolio diversification constitute the dominant competitive moves as regulatory fragmentation intensifies.
Among Asian bulk manufacturers, Zhejiang Dragoi Colour Technology exemplifies the petrochemical-integrated archetype with concentrated synthetic production capabilities. Chr. Hansen Holding A/S and GNT Group occupy positions on the natural alternatives vector, representing divergent technology platforms responding to clean-label procurement mandates from European retailers. These three anchors illustrate the structural tension between cost-efficient synthetic supply and premium-positioned natural substitution.
| Leading Market Players |
|---|
| Zhejiang Dragoi Colour Technology |
| FMC Corporation |
| Sensient Cosmetic Technologies |
| DDW The Color House |
| Clariant |
| Vidhi Dyestuffs |
| Chr. Hansen Holding A/S |
| GNT Group |
| Vivify |
| Others |
Pricing and Supply Chain Analysis
EU F-Gas Regulation and CSRD disclosure mandates gate qualified supply access, restricting pharmaceutical-grade E123 procurement to certified producers while segmenting pricing into sustainability-verified premiums versus commodity-grade alternatives. REACH-compliant manufacturers command tiered positioning as European retailers enforce Scope 3 emissions accounting that excludes uncertified petrochemical-derived colorants.
Pricing Analysis
Certification-attached yield guarantees anchor value-based pricing for pharmaceutical-grade E123, with Kosher and Halal tiers commanding premiums over standard food-grade supply. Three-tier pricing structure across pharmaceutical-grade, food-grade certified, and commodity bulk levels reflects documentation depth and batch testing rigor. Cost compression in commodity synthetic grades is intensifying because Indian bulk producers deploy continuous flow reactors that reduce per-unit synthesis overhead. Mid-scale beverage manufacturers in Nigeria and Egypt exhibit highest price sensitivity, while multinational pharmaceutical coaters in China absorb certification premiums for SAMR compliance.
Supply Chain Analysis
Regional distribution centers in Mumbai, Shanghai, and Lagos coordinate hub-and-spoke patterns that connect Zhejiang and Gujarat production clusters with African and Southeast Asian processors. Supply concentrates in China and India for azo dye synthesis, with Germany and the United States maintaining pharmaceutical-grade formulation capabilities. Naphthalene derivatives, sulfonating agents, and sodium salt precursors constitute critical input dependencies. Single-source vulnerability runs through concentrated petrochemical feedstock channels from integrated refiners. Distribution runs through direct e-procurement platforms that displace traditional chemical distributor markups for cost-sensitive buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical-grade certification capacity constraints prop pricing premiums as SAMR and FDA timelines stretch qualified supplier rosters. Synthetic azo dye production faces tightening environmental compliance that limits expansion economics for uncertified operators.
For Market Incumbents: Anchor defensive positioning through backward integration into naphthalene derivative supply and dedicated production line segregation for Kosher certification tiers. Natural colorant substitution from beetroot anthocyanins and carmine alternatives threatens premium confectionery segments. Continuous flow reactor investments in Gujarat and Zhejiang compress unit economics for commodity-grade competitors. For New Entrants and Emerging Players: Capture white-space opportunity in pharmaceutical-grade E123 for Middle Eastern and North African markets with underserved Halal-certified supply infrastructure. Microencapsulation technology for heat-stable baked goods applications represents the most penetrable technical segment. Direct technical partnerships with Nigerian beverage bottlers bypass distributor markups and establish specification influence at formulation stage. For Investors and Strategic Acquirers: EFSA reclassification announcements for synthetic azo dyes in children's products are the leading indicator that regulatory-driven volume displacement will accelerate natural alternative penetration. Long-term viability over the next decade favors bioscience-platform developers with extraction technology portfolios over pure-play synthetic producers. Acquisition targets should display dual FDA-EFSA certification depth and captive pharmaceutical customer relationships. Pending SAMR excipient quality protocol expansions signal inflection timing for certified additive demand in Chinese drug manufacturing.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Certification Expansion | Kosher and Halal production line segregation opens Middle Eastern markets with supply gaps. |
| Continuous Flow Reactor Deployment | Automated azo coupling chemistry reduces solvent waste and improves lot-to-lot consistency for Indian bulk producers. |
| Microencapsulation Technology Investment | Spray-drying with modified starch carriers enables heat-stable formulations for baked goods applications. |
| Direct E-Procurement Platform Development | Bypassing traditional chemical distributors connects Gujarat manufacturers with African processors. |
| Natural Colorant Extraction Scale-Up | Plant-based alternatives from GNT Group and Chr. Hansen respond to EU retailer clean-label mandates. |
Research Methodology
Multi-period observation of FSSAI batch testing protocols, REACH registration timelines, and FDA color additive petition outcomes anchored the trend analysis, supplemented by interviews with plant managers at Indian and Chinese dye synthesis facilities, procurement leads at multinational beverage manufacturers, regulatory affairs directors at pharmaceutical coating operations, and distribution channel partners in African markets. Secondary validation drew from EFSA evaluation reports, SAMR excipient quality circulars, customs and trade data for naphthalene derivative flows, and SEC filings from listed chemical producers. Bottom-up capacity assessments and top-down consumption estimates were triangulated against certification database records.
Segment-weighting across synthetic versus natural colorant type, food versus pharmaceutical application grade, and FDA Approved versus Kosher Certified tiers structured the analytical framework. CAGRs were derived from regression analysis of historical procurement volumes against regulatory event timelines, with elasticity adjustments for petrochemical feedstock price volatility and substitution effects from beetroot anthocyanins. Pharmaceutical-grade purity requirements and FSSAI mandate enforcement intensity served as industry-specific forecast inputs across the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA reclassification decisions, crude oil benchmark fluctuations affecting naphthalene economics, and clean-label procurement mandate acceleration by European retailers. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Antistaling Agent Market
Food Additives and Ingredients
AKD Emulsifier Market
Food Additives and Ingredients
Russia Food Additives Market
Food Additives and Ingredients
Australia Anti Caking Market
Food Additives and Ingredients
Natural Food and Beverage Preservatives Market
Food Additives and Ingredients
Germany Food Colorants Market
Food Additives and Ingredients
Global Flaked Shortenings Market
Food Additives and Ingredients
China Anti-Caking Market
Food Additives and Ingredients
Modified Milk Ingredients Market
Food Additives and Ingredients
Japan Food Emulsifiers Market
Food Additives and Ingredients
United States Anti-Caking Market
Food Additives and Ingredients
Food and Beverage Sterilizing Agent Market
Food Additives and Ingredients
Olestra Market
Food Additives and Ingredients
PVPP Beer Stabilizer Market
Food Additives and Ingredients
Egg Emulsifier Market
Food Additives and Ingredients
Erythorbic Acid Market