
 Agar Agar Gum Market | 2026-2036
Agar Agar Gum Market Size, Share, and Industry Trends Forecast 2026-2036
Agar Agar Gum Market Analysis
Skilled seaweed cultivators in Southeast Asian coastal zones is reorganizing raw material flows for agar agar gum processors worldwide. Meron Group leverages integrated Gracilaria farming operations across Indonesian waters to secure captive supply of red algae biomass. PT Agarindo Bogatama anchors large-scale extraction capacity near Surabaya, sustaining consistent output for food-grade powder markets. Hispanagar specializes in high-gel-strength agar production from Moroccan and Spanish Atlantic seaweed stocks, differentiating on pharmaceutical-grade certification.
Agar agar gum comprises a heterogeneous polysaccharide complex extracted primarily from red algae genera Gracilaria and Gelidium, with gelation triggered at 32-43°C and melting points between 85-95°C depending on sulfate content and extraction alkali treatment. Food & Beverage end use dominates volume consumption as plant-based stabilizers displace animal-derived gelatin in confectionery and dairy analog applications. Powder format leads packaging throughput due to dosing precision in industrial batch processing, while vegan alternative positioning in European retail channels commands margin premiums over standard gelling agent sales.
EFSA purity standards for food additives and Japan's Ministry of Health, Labour and Welfare food-grade specifications shape extraction protocol investments and import gatekeeping across major consuming markets. Indonesia's BIS-equivalent national standards body and coastal province licensing regimes govern seaweed farm concessions and wet processing effluent controls. Stakeholders must monitor regulatory divergence between EU novel food pathways and Asia-Pacific traditional use exemptions as clean-label claims harden into enforceable compositional mandates.
Market Dynamics
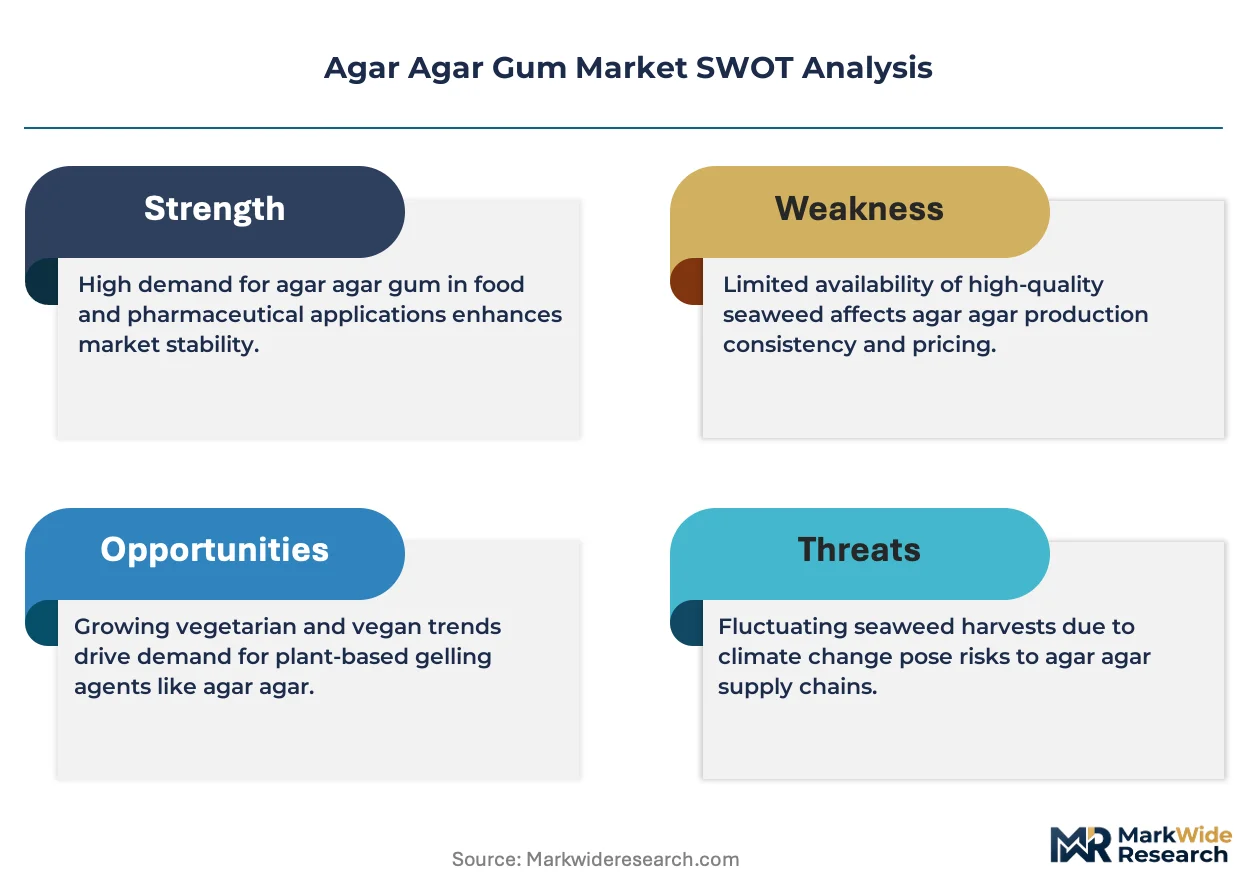
Seaweed biomass procurement is concentrating among Indonesian coastal farming cooperatives as EFSA clean-label mandates tighten purity requirements for plant-based gelatin alternatives.
Growth Catalysts
- EFSA Purity Directives:European food additive standards are compelling manufacturers to source pharmaceutical-grade agar for confectionery and dairy analog applications.
- Gracilaria Farming Cooperatives:South Sulawesi seaweed cultivators are securing long-term supply contracts with regional extractors to stabilize raw material flows.
- Alkali Extraction Protocols:Advanced alkali treatment methods are improving gel-strength consistency for high-performance food-grade powder specifications.
Market Restraints
- Red Algae Supply Concentration:Dependence on Indonesian and Moroccan seaweed stocks creates vulnerability to coastal weather disruptions and seasonal harvest variability.
- Gelidium Resource Scarcity:Premium wild-harvested Gelidium species face depletion pressures along Spanish and Portuguese Atlantic coastlines.
- Carrageenan Substitution:Lower-cost carrageenan from Kappaphycus farming operations competes for basic gelling applications in price-sensitive processed foods.
Strategic Opportunities
- Japan's Ministry of Health Standards:Pharmaceutical-grade certification pathways for agar in capsule and suppository formulations open premium margin segments.
- Cell-Cultured Meat:Scaffold material applications in cellular agriculture present novel demand for ultra-pure agar with defined pore structures.
- E-Commerce Ingredient Channels:Direct-to-manufacturer platforms are shortening procurement cycles for mid-sized European plant-based food startups.
Industry Challenges
- Phycocolloid Processing Expertise:Shortage of trained technicians for sulfate content control and gelation point calibration constrains extraction capacity expansion.
- Multi-Jurisdiction Certification:Divergent EFSA novel food pathways and Japan's traditional use exemptions create compliance complexity for exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agar Agar Gum Market |
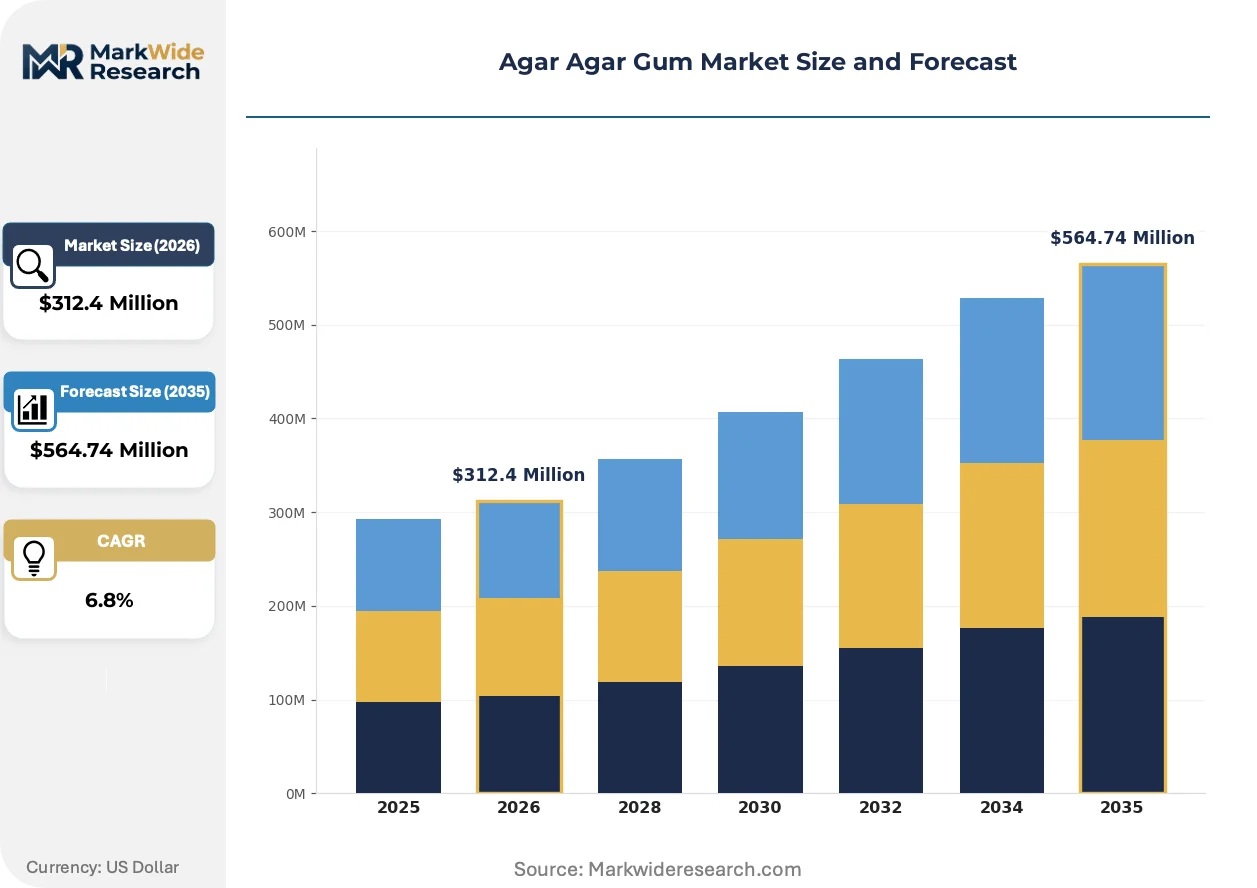
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Flakes, Sheets, Granules End Use Industry: Food & Beverage, Pharmaceuticals, Cosmetics, Nutraceuticals Application: Thickening Agent, Stabilizer, Gelling Agent, Vegan Alternative Packaging Type: Bags, Bottles, Bulk Containers, Pouches |
| Companies Covered | Meron Group, PT Agarindo Bogatama, Hispanagar, TIC Gums, Myeong Shin Agar-Agar Co., Ltd., Marine Hydrocolloids, AGARMEX, S.A. DE C.V., Industrias Roko, Orient Resources Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agar Agar Gum Market Emerging Trajectories
Extraction technology advancement and regulatory harmonization pressures are compressing traditional supply arrangements while opening certified premium channels.
Enzymatic pre-treatment methods are displacing conventional hot-water extraction for Gracilaria biomass. European plant-based dairy manufacturers are adopting these protocols to achieve cleaner flavor profiles and reduced alkali residue. This displacement is compressing margins for standard-grade agar while rewarding processors with certified low-sulfate production lines.
Japan's Ministry of Health, Labour and Welfare revised food-grade hydrocolloid specifications are mandating stricter heavy metal limits and microbial contamination thresholds. Indonesian extractors serving Japanese importers must upgrade wet processing effluent controls and laboratory testing infrastructure. Food-grade powder shipments to Japanese pharmaceutical and confectionery end-uses now require batch-level certification documentation.
Direct procurement relationships between European vegan food manufacturers and Indonesian farming cooperatives are bypassing traditional trading house intermediaries. Mid-sized plant-based confectionery brands in Germany and the Netherlands are negotiating volume commitments with South Sulawesi cultivator associations. This disintermediation is most visible in organic-certified agar segments where supply chain transparency commands retail price premiums.
Agar Agar Gum Market Segmentation
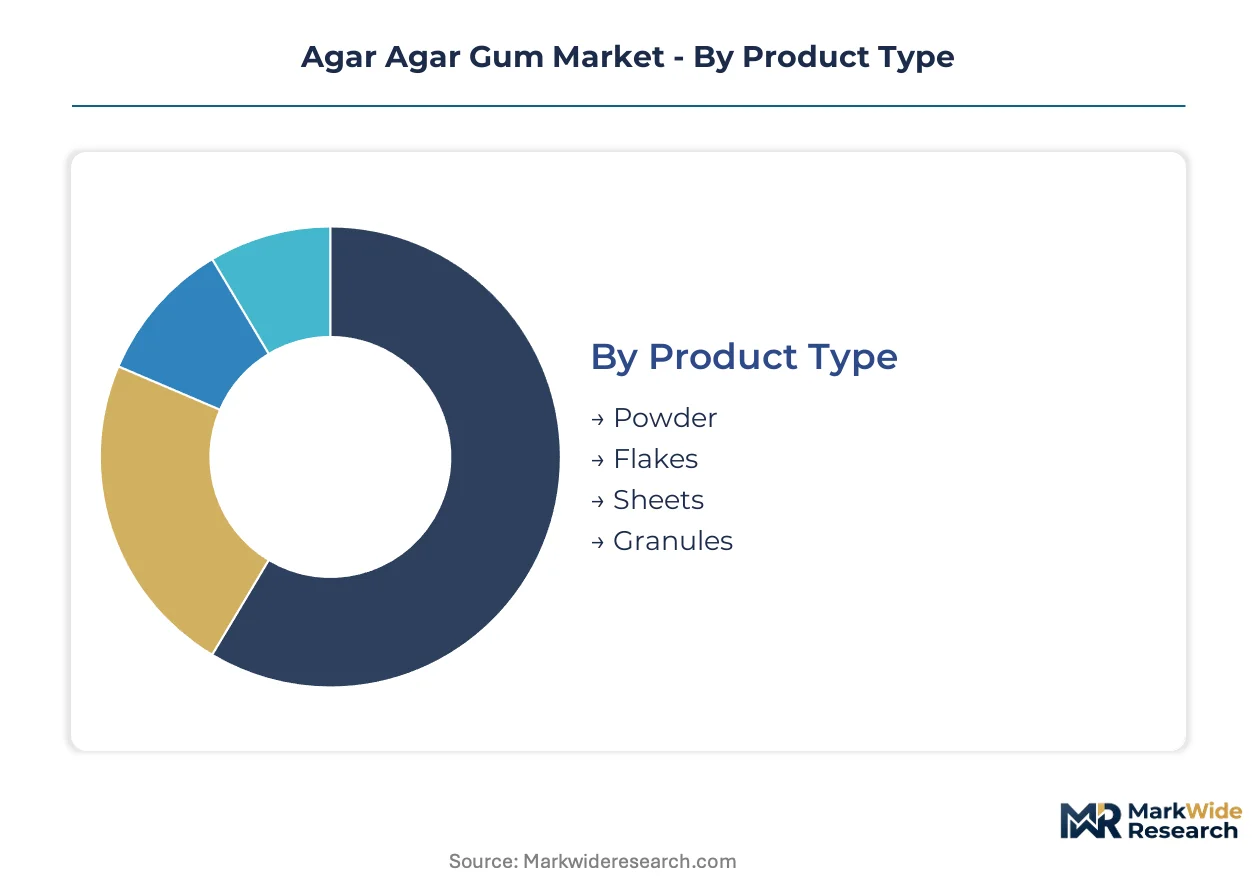
Agar agar gum's heterogeneous physical forms and functional versatility create distinct procurement channels. Each segment category aligns with specific end-use requirements, from industrial-scale food processing to precision pharmaceutical formulation.
Product Type:
Channel distribution varies sharply by physical form, with powder dominating industrial procurement and specialty formats penetrating artisanal and laboratory segments.
- Powder:Fine-ground agar with standardized mesh sizes enables precise dosing in automated batch processing systems. German and Dutch plant-based dairy manufacturers source pharmaceutical-grade powder through direct contracts with Indonesian extractors. EFSA purity mandates are compressing standard-grade margins while certified low-sulfate lines command premium positioning.
- Flakes:Irregular fragments requiring pre-hydration suit small-scale confectionery operations and educational laboratory settings. Japanese pharmaceutical capsule manufacturers specify flake format for controlled dissolution in suppository base formulations. METI certification requirements filter flake procurement through documented heavy metal testing protocols.
- Sheets:Traditional Asian dessert preparation and molecular gastronomy applications favor this format for visual portion control and consistent gel thickness.
- Granules:Intermediate particle size bridges industrial dosing precision with artisanal handling convenience in mid-scale food service operations.
By volume, Powder leads. By growth pace, Flakes is expanding most quickly through pharmaceutical certification pathways.
End Use Industry:
Cost tier stratification separates commodity food applications from certified pharmaceutical and cosmetic segments with divergent margin structures.
- Food & Beverage:Plant-based stabilizer demand concentrates in European confectionery and dairy analog manufacturing. EFSA clean-label directives are displacing animal-derived gelatin across German, French, and Dutch processing facilities. Alkali extraction protocol investments separate premium-grade suppliers from commodity competitors.
- Pharmaceuticals:Capsule, suppository, and tissue culture scaffold applications require ultra-pure agar with defined sulfate content and microbial specifications. Japan's Ministry of Health, Labour and Welfare standards create import gatekeeping that rewards Indonesian extractors with upgraded laboratory infrastructure.
- Cosmetics:Gel masks and emulsion stabilizers utilize food-grade powder diverted through cosmetic ingredient distributors with modified documentation.
- Nutraceuticals:Vegan soft-gel and gummy vitamin formulations represent emerging demand from European supplement brands seeking gelatin alternatives.
Food & Beverage anchors volume consumption. Pharmaceuticals generates the steepest margin expansion through certification premiums.
Application:
Customer type differentiation separates industrial processors seeking functional performance from retail-positioned brands emphasizing vegan credentialing.
- Thickening Agent:Viscosity modification in sauces, soups, and plant-based beverages leverages agar's pseudoplastic flow properties. Indonesian and Moroccan biomass sourcing concentration creates supply vulnerability to coastal weather disruption.
- Stabilizer:Preventing syneresis and phase separation in frozen desserts and cultured dairy alternatives requires precise gel-strength calibration. South Sulawesi farming cooperatives are securing long-term volume commitments with European plant-based food startups.
- Gelling Agent:Thermoreversible gelation at 32-43°C enables hot-fill processing and clean-label positioning in confectionery applications.
- Vegan Alternative:Retail-facing positioning commands price premiums through supply chain transparency claims and organic certification documentation.
Thickening Agent leads by installed volume base. Vegan Alternative is gaining share fastest through European retail channel expansion.
Packaging Type:
Supply concentration in Indonesian extraction clusters shapes bulk container flows, while finished goods packaging localizes near end-use markets.
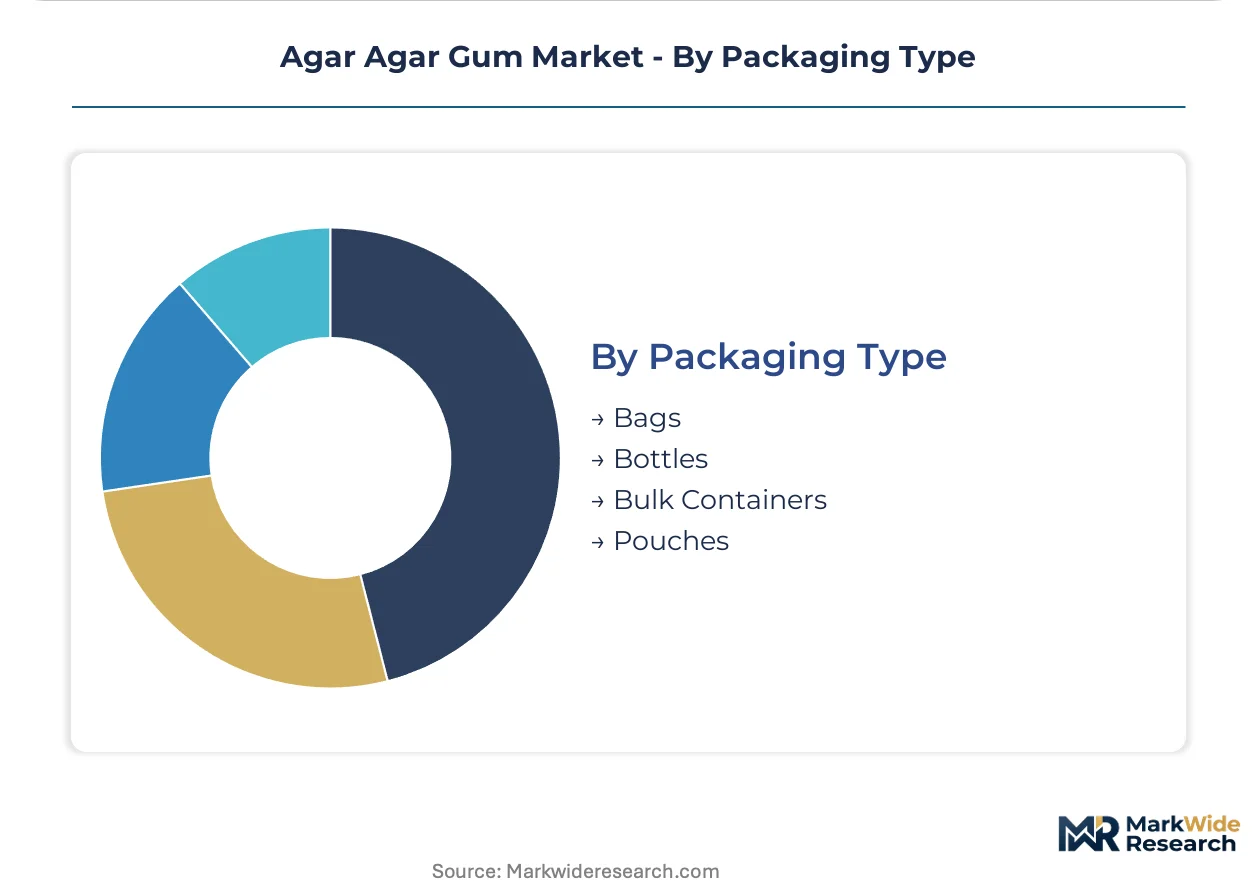
- Bulk Containers:25kg fiber drums and supersacks dominate industrial procurement from Surabaya-area extractors serving food manufacturers. PT Agarindo Bogatama anchors regional capacity for consistent food-grade powder output.
- Bags:Multi-wall paper and laminated film formats serve mid-scale food processors and ingredient distributors with intermediate volume requirements.
- Bottles:Laboratory and artisanal food service segments utilize clear PET or glass containers for visual quality assessment and moisture protection.
- Pouches:Stand-up and flat pouches penetrate direct-to-consumer retail channels and e-commerce ingredient platforms serving European vegan home cooks.
Bulk Containers dominate procurement tonnage. Pouches show the steepest expansion trajectory through disintermediated e-commerce channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between pharmaceutical-grade markets in Japan and Germany versus food-grade volume centers in Indonesia. Clean-label regulatory stringency in Western Europe compresses standard-grade margins while Asian processing clusters capture scale advantages through coastal seaweed farming integration.
Indonesia
Gracilaria farming cooperatives across South Sulawesi supply raw biomass to Surabaya-area extractors serving global food manufacturers. The national standards body enforces coastal province licensing for seaweed concessions and wet processing effluent controls. PT Agarindo Bogatama anchors regional extraction capacity, sustaining consistent food-grade powder output for export markets.
Japan
Pharmaceutical capsule and suppository formulations drive demand for ultra-pure agar with defined sulfate content specifications. The Ministry of Health, Labour and Welfare mandates stricter heavy metal limits and microbial contamination thresholds through revised food-grade hydrocolloid standards. Import gatekeeping rewards Indonesian extractors with upgraded laboratory infrastructure and batch-level certification documentation.
Germany
Plant-based confectionery and dairy analog manufacturers source pharmaceutical-grade powder through direct contracts with Indonesian extractors. EFSA clean-label directives displace animal-derived gelatin across processing facilities in North Rhine-Westphalia and Bavaria. Alkali extraction protocol investments separate premium-grade suppliers from commodity competitors in this regulatory environment.
Morocco
Atlantic coastline wild-harvested seaweed stocks support high-gel-strength agar production for European pharmaceutical certification. The national food safety authority aligns with EFSA purity benchmarks for export-oriented processing. Coastal extraction facilities face depletion pressures on premium Gelidium species availability.
Spain
Traditional agar extraction from Atlantic seaweed stocks competes with Moroccan supply for European pharmaceutical-grade certification. Regional processing clusters in Galicia maintain heritage extraction expertise while adapting to EFSA novel food pathway requirements. Wild-harvested Gelidium scarcity constrains capacity expansion along Portuguese border zones.
Agar Agar Gum Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive biomass supply separating scale players from trading-dependent competitors. The structure rewards backward integration into seaweed farming and punishes pure extraction operations exposed to raw material volatility. Three archetypes dominate: Indonesian-integrated farm-extractor combinations, European pharmaceutical-grade certifiers, and Asian trading houses with regional distribution networks. Competitive moves concentrate on long-term supply contracts with farming cooperatives and laboratory infrastructure upgrades for multi-jurisdiction certification compliance.
Within the integrated tier, Meron Group exemplifies captive supply strategy through Gracilaria farming operations across Indonesian waters. PT Agarindo Bogatama anchors large-scale extraction capacity near Surabaya, representing the scale-driven archetype serving food-grade powder markets. Hispanagar occupies a position within the pharmaceutical-grade certifier tier, differentiating on high-gel-strength production from Moroccan and Spanish Atlantic seaweed stocks.
| Leading Market Players |
|---|
| Meron Group |
| PT Agarindo Bogatama |
| Hispanagar |
| TIC Gums |
| Myeong Shin Agar-Agar Co., Ltd. |
| Marine Hydrocolloids |
| AGARMEX, S.A. DE C.V. |
| Industrias Roko |
| Orient Resources Company |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between South Sulawesi farming cooperatives and Indonesian extractors lock in biomass access while providing forward price visibility for European plant-based food manufacturers navigating EFSA purity mandates.
Pricing Analysis
Long-term offtake agreements dominate procurement between Indonesian Gracilaria cultivators and regional extractors, with pharmaceutical-grade certification and gel-strength consistency serving as the primary price differentiation drivers. Cost compression in standard-grade powder is intensifying as enzymatic pre-treatment methods displace conventional extraction, while food-grade buyers show highest price sensitivity compared to pharmaceutical capsule manufacturers who prioritize batch-level documentation over unit cost.
Supply Chain Analysis
Makassar Strait maritime corridors underpin raw material flows from South Sulawesi seaweed farms to Surabaya-area processing facilities. Supply draws from Indonesia, Morocco, and Spain for red algae biomass, with sulfate content calibration and alkali treatment chemicals representing critical input dependencies. Single-source vulnerability concentrates in Indonesian coastal farming concessions exposed to monsoon disruption. Distribution runs through bulk container shipments to European food manufacturers and pharmaceutical compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Trained phycocolloid technicians capable of sulfate content control and gelation point calibration represent the scarcest capability layer in this market, constraining extraction capacity expansion and creating acquisition premiums for integrated operations.
For Market Incumbents: Consolidate captive Gracilaria farming operations through equity stakes in South Sulawesi cooperatives to defend against carrageenan substitution in price-sensitive processed foods. Upgrade laboratory infrastructure for Japan's Ministry of Health batch-level certification to capture pharmaceutical-grade margin premiums. For New Entrants and Emerging Players: Lead with organic-certified agar segments where supply chain transparency commands retail price premiums through disintermediated e-commerce channels serving European vegan home cooks. Target mid-scale German and Dutch plant-based confectionery brands seeking direct procurement relationships with farming cooperatives. For Investors and Strategic Acquirers: Capital is best deployed toward Indonesian-integrated farm-extractor combinations with demonstrated EFSA and Japan Ministry of Health compliance infrastructure over pure extraction operations exposed to raw material volatility. Watch for regulatory divergence between EU novel food pathways and Asia-Pacific traditional use exemptions as the inflection signal requiring portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seaweed Farming | Captive Gracilaria biomass supply insulates extractors from coastal weather disruption and harvest variability. |
| Pharmaceutical-Grade Certification Investment | Japan's Ministry of Health standards reward upgraded laboratory infrastructure with premium margin access. |
| Enzymatic Extraction Technology Adoption | Pre-treatment methods achieve cleaner flavor profiles that displace conventional alkali processing in European plant-based dairy. |
| Direct-to-Manufacturer E-Commerce Platform | Shortened procurement cycles capture margin from disintermediated organic-certified agar segments. |
| Long-Term Supply Agreement with Cooperatives | Volume commitments with South Sulawesi cultivators stabilize raw material flows for food-grade powder output. |
Methodological Framework
Cross-validation between customs trade data and extraction facility capacity surveys anchors the qualitative findings. Primary interviews with seaweed farm cooperative managers, phycocolloid processing technicians, food manufacturer procurement leads, and pharmaceutical formulation scientists combined with secondary validation from EFSA additive registers, Japan Ministry of Health hydrocolloid specifications, Indonesian coastal province licensing records, and EU import tariff schedules. Bottom-up biomass cultivation estimates and top-down end-use consumption models were reconciled.
Sensitivity analysis tested forecast outputs across the projection horizon. Segmentation dimensions modeled include physical form, end-use industry, functional application, and packaging type, with regional regulatory cluster and certification tier as cross-cutting variables. CAGRs were derived from installed extraction capacity expansion trajectories and substitution elasticity estimates for gelatin displacement in European confectionery and dairy analog manufacturing.
Forecasts assume regulatory continuity in EFSA food additive pathways and Japan's Ministry of Health standards; material policy shifts would require re-modeling. Seaweed stock depletion pressures, enzymatic technology diffusion rates, and carrageenan substitution thresholds represent specific risk factors that could revise projections. Practitioners should keep alternative scenarios live as clean-label claim enforceability and pharmaceutical certification stringency evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Fat-Replacing Starch Market
Food Additives and Ingredients
Monosodium Glutamate Market
Food Additives and Ingredients
Erythorbic Acid Market
Food Additives and Ingredients
Dairy Starter Culture Market
Food Additives and Ingredients
Italy Food Emulsifier Market
Food Additives and Ingredients
Anti-Caking Market
Food Additives and Ingredients
Meat Tenderizing Agents Market
Food Additives and Ingredients
Canada Food Acidulants Market
Food Additives and Ingredients
Microencapsulation Market
Food Additives and Ingredients
Food Encapsulation Market
Food Additives and Ingredients
Clean Label Emulsifiers Market
Food Additives and Ingredients
Canada Food Emulsifiers Market
Food Additives and Ingredients
Russia Feed Additives Market
Food Additives and Ingredients
North America Food Coating Ingredients Market
Food Additives and Ingredients
Lecithin Market
Food Additives and Ingredients
Modified Milk Ingredients Market