
 Culinary Torch Market | 2026-2036
Culinary Torch Market Size, Share, and Industry Trends Forecast 2026-2036
Culinary Torch Market Analytics
China is fragmenting into multiple manufacturing clusters for culinary torch components, with Guangdong and Zhejiang provinces hosting competing supply bases. Iwatani Corporation leverages its gas appliance heritage to dominate butane torch distribution across Asian foodservice channels. Bernzomatic anchors North American propane torch sales through hardware and specialty retail partnerships. Blazer Products differentiates via precision flame control technology for professional pastry applications.
A culinary torch is a handheld fuel-burning or electrically heated device that produces a directed, high-temperature flame typically reaching 1300°C to 1500°C for caramelizing sugars, browning meringues, searing proteins, and finishing plated dishes. Butane torches sustain the largest volume share due to portability and refill convenience across commercial and home settings. Electric torches occupy a narrower but expanding niche where open-flame restrictions limit fuel-based alternatives in institutional kitchens. Sugar work and food presentation applications generate premium pricing as pastry chefs demand precise, repeatable flame adjustment.
The Consumer Product Safety Commission enforces ignition safety standards that shape child-resistant lock designs and accidental-flame prevention mechanisms in the United States. The EU F-Gas Regulation and REACH compliance restrict certain seal and valve materials, pushing manufacturers toward fluoropolymer alternatives and redesigned fuel pathways. Stakeholders must monitor evolving fire code interpretations in commercial kitchen jurisdictions and calibrate product portfolios between fuel-based performance and electric convenience as regulatory thresholds tighten.
Market Dynamics
EU F-Gas Regulation and REACH compliance are forcing manufacturers to abandon traditional seal materials and redesign fuel pathways, compressing margins while creating differentiation opportunities for fluoropolymer-ready suppliers.
Growth Catalysts
- Commercial kitchen renovation cycles:Active replacement demand in the United States, Germany, and Japan sustains butane and propane unit procurement across restaurant and catering channels.
- EU F-Gas Regulation:Material compliance mandates accelerate adoption of fluoropolymer seals and valves, rewarding early-adapting component suppliers with locked-in sourcing relationships.
- Electric torch technology:Open-flame restrictions in institutional kitchens expand addressable demand where fuel-based alternatives face operational bans.
Market Restraints
- Butane price volatility:Refined petroleum feedstock fluctuations compress torch manufacturer margins and complicate long-term contract pricing with foodservice distributors.
- Guangdong-Zhejiang supply concentration:China's competing manufacturing clusters create quality inconsistency risks and complicate supplier qualification for Western brands.
- REACH material restrictions:Phased prohibitions on certain elastomer compounds force costly engineering changes without immediate volume offsets.
Strategic Opportunities
- Japan's precision pastry segment:Sugar work and food presentation applications command premium pricing for repeatable flame control technology in high-end commercial kitchens.
- CSRD-aligned sustainability reporting:European corporate disclosure mandates create procurement preference for low-carbon-footprint electric torch alternatives.
- Direct-to-chef e-commerce:Bypassing traditional foodservice distributors reaches independent restaurants and home enthusiasts with higher-margin accessory bundles.
Industry Challenges
- Flame control calibration expertise:Precision engineering talent scarcity delays product development cycles for professional-grade temperature consistency.
- CPSC ignition safety certification:Child-resistant lock and accidental-flame prevention testing extends time-to-market for redesigned fuel pathway models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Culinary Torch Market |
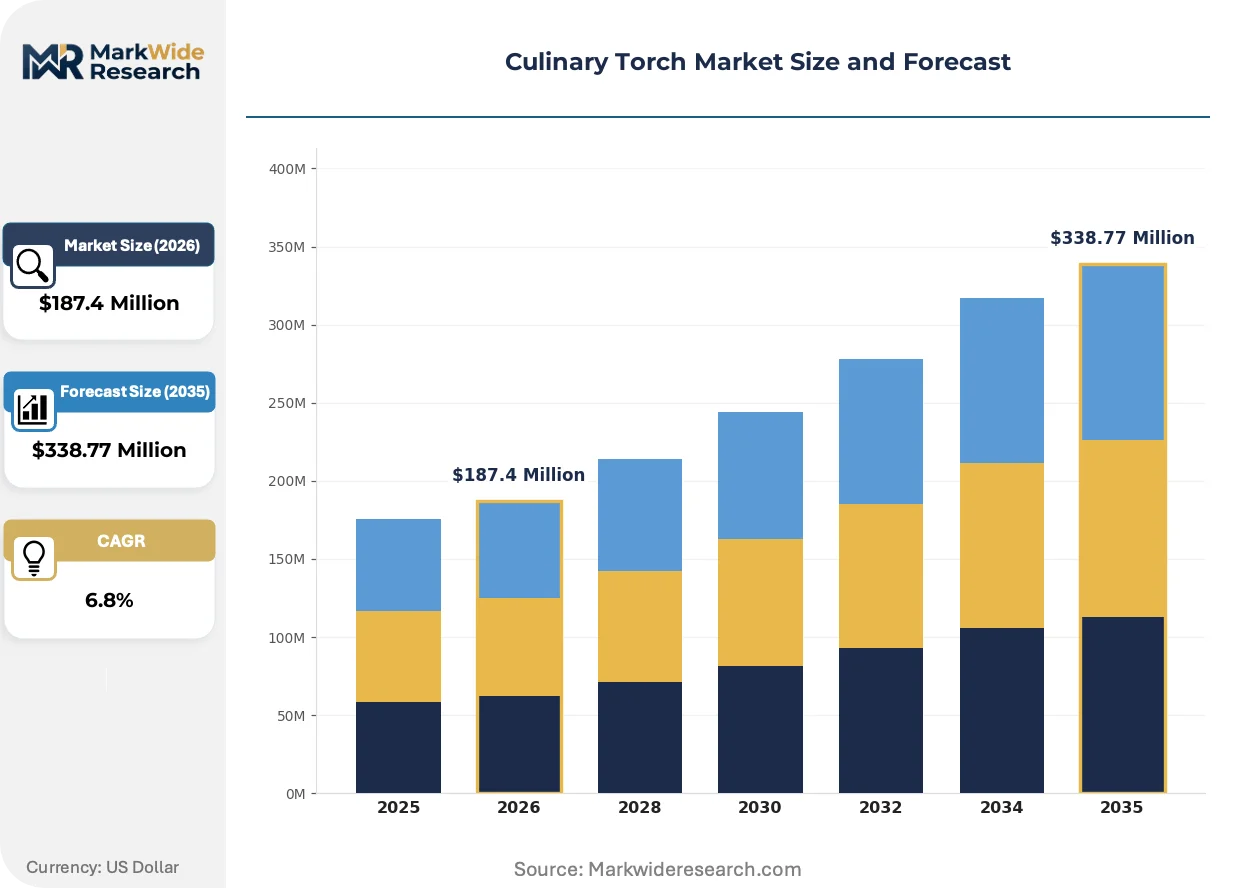
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Butane Torch, Propane Torch, Electric Torch, Specialty Torch Application: Cooking, Food Presentation, Baking, Sugar Work End User: Commercial Kitchens, Restaurants, Home Chefs, Catering Services Feature: Adjustable Flame, Safety Lock, Refillable, Ergonomic Design |
| Companies Covered | Iwatani Corporation, Blazer Products, Bernzomatic, Chefman, RSVP International, Sterno Products, Zippo Manufacturing Company, Sondiko, Jo Chef, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Culinary Torch Market Evolving Landscape
Active regulatory pressure on material composition converges with end-user demands for precision and safety, reshaping how torch manufacturers balance performance specifications against compliance burdens.
Electric heating elements with rapid-response ceramic cores is hybridizing with traditional butane architectures, enabling dual-mode units that switch between fuel and electric operation. Pastry kitchens in fire-code-restricted jurisdictions adopt these hybrids fastest. The technology is hybridizing product categories, compressing the distinction between fuel-based performance and electric convenience.
REACH authorization requirements for per- and polyfluoroalkyl substances are eliminating certain seal compounds from EU-sourced torches. Manufacturers must validate fluoropolymer alternatives through extended durability testing. Professional-grade butane models face the steepest reformulation costs, while economy electric torches gain relative compliance advantage.
Foodservice procurement teams now bundle torch purchases with broader kitchen equipment renovation contracts, consolidating vendor relationships and compressing standalone accessory margins. Specialty retailers lose volume to direct manufacturer relationships with national restaurant chains. Germany's Mittelstand catering suppliers exemplify this consolidation pattern.
Culinary Torch Market Segmentation
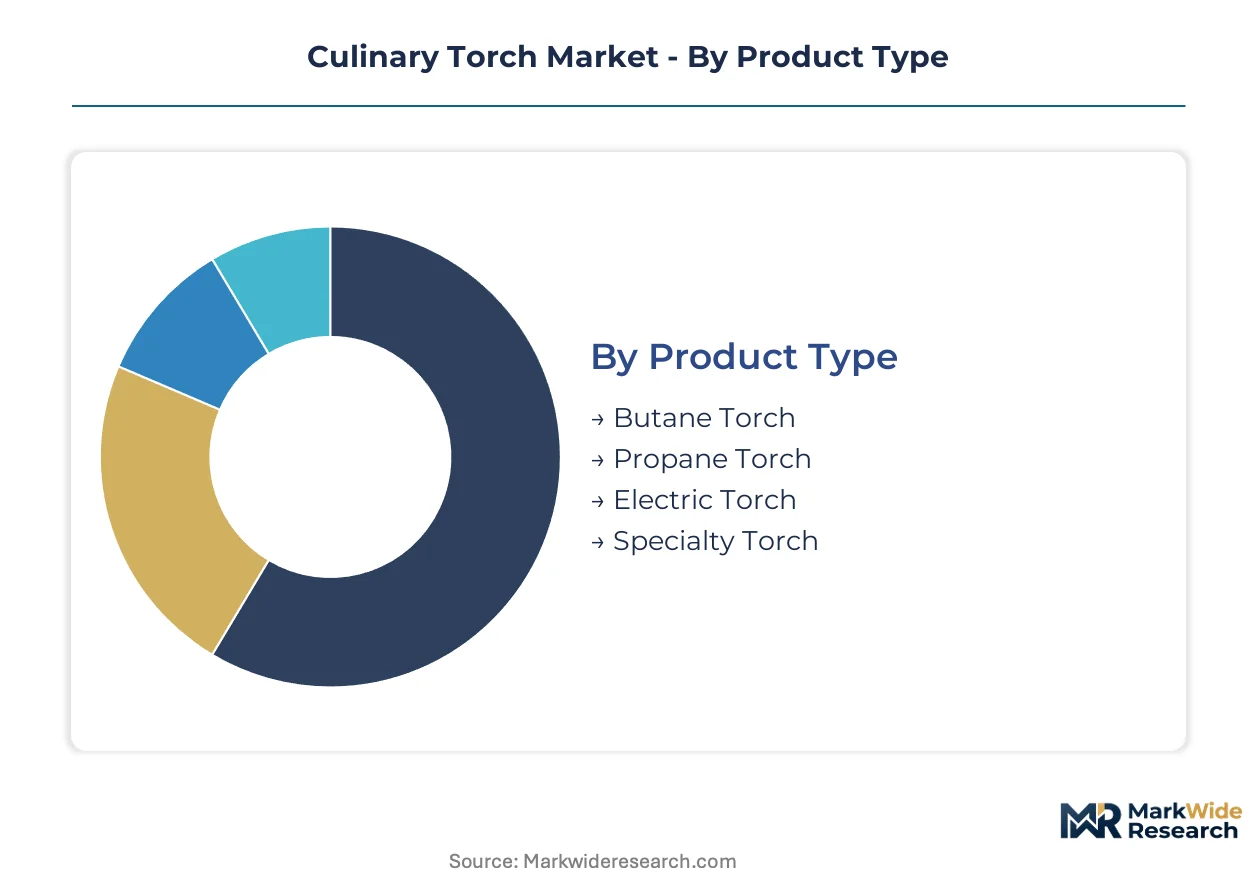
Segmentation in the culinary torch market reveals distinct procurement rhythms across product categories. Replacement cycles vary from months for high-volume commercial butane units to years for precision electric models, shaping inventory strategies for distributors and end-users alike.
Product Type:
Butane torches turn over fastest in commercial settings where daily searing operations consume fuel and wear valves, while specialty pastry units linger longest in high-end kitchens. Propane and electric alternatives occupy intermediate replacement positions depending on intensity of caramelization workloads.
- Butane Torch:Portable fuel-cell architecture dominates commercial and home settings through refill convenience and 1300°C flame output. Restaurants in the United States and Germany drive replacement demand through continuous kitchen renovation cycles and high-throughput finishing operations.
- Electric Torch:Ceramic heating cores deliver directed heat without open flame, penetrating institutional kitchens where fire codes restrict fuel-based alternatives. Schools, hospitals, and corporate cafeterias in Japan and Germany adopt these fastest where regulatory thresholds tighten operational permissions.
- Propane Torch:Higher-BTU output suits heavy-duty protein searing in catering and outdoor foodservice applications.
- Specialty Torch:Precision flame control mechanisms target sugar work and pastry finishing with repeatable temperature calibration.
Butane torch sales anchor the volume base while electric torch adoption gains share at the steepest rate as fire-code jurisdictions multiply.
Application:
Cost tier differentiation separates commodity finishing from premium presentation work, with sugar work commanding the highest per-unit equipment investment and cooking applications driving the largest aggregate spend.
- Cooking:Protein searing and surface finishing constitute the highest-volume application across restaurant and catering channels. Demand concentrates in the United States where steakhouse chains and independent operators deploy butane units for tableside and kitchen-line caramelization.
- Sugar Work:Isomalt and pulled sugar techniques require millimeter-precise flame adjustment for sculptural pastry applications. High-end commercial kitchens in Japan and France pay premium pricing for repeatable temperature control in competition and luxury hotel environments.
- Food Presentation:Plated dessert finishing and garnish browning occupy a mid-tier pricing position between commodity cooking and artisan sugar work.
- Baking:Meringue browning and crust finishing drive seasonal demand spikes in retail bakery channels.
Cooking applications generate the broadest revenue base while sugar work commands the highest margin per unit sold.
End User:
Customer type determines procurement channel and service expectations, with national restaurant chains consolidating vendor relationships and home chefs purchasing through specialty retail or direct e-commerce.
- Restaurants:Full-service and fast-casual operators represent the largest commercial segment, purchasing through foodservice distributors with negotiated equipment bundles. Chains in Germany and Japan favor multi-year supplier contracts linked to broader kitchen renovation timelines.
- Commercial Kitchens:Institutional cafeterias, hotels, and central commissaries prioritize electric and dual-mode units where open-flame restrictions apply. Procurement teams in the United States evaluate total cost of ownership including fuel logistics and safety compliance documentation.
- Catering Services:Mobile and event-based foodservice demands portable butane and propane architectures for off-premise finishing.
- Home Chefs:Enthusiast and hobbyist segments purchase through specialty cookware retailers and direct-to-consumer channels, accepting higher per-unit pricing for premium flame control features.
Restaurant procurement anchors manufacturer volume commitments while commercial kitchen electric adoption climbs fastest under tightening fire-code interpretations.
Feature:
Supply concentration in safety-critical components creates differentiation pressure, with adjustable flame mechanisms and child-resistant locks now baseline requirements rather than premium add-ons.
- Adjustable Flame:Precision valve engineering enables temperature modulation from softening to searing across 300°C to 1500°C range. Pastry chefs in Japan and France demand stepless adjustment for sugar work consistency, driving component sourcing from specialized Guangdong valve manufacturers.
- Safety Lock:Child-resistant ignition mechanisms and accidental-flame prevention satisfy CPSC enforcement in the United States and CE marking requirements for EU import. Redesigned fuel pathways incorporating these features extend product development cycles by four to six months.
- Refillable:Reusable fuel cells reduce per-use cost and align with CSRD-aligned sustainability reporting preferences in European corporate procurement.
- Ergonomic Design:Weight distribution and grip geometry reduce operator fatigue during extended pastry finishing sessions.
Adjustable flame functionality remains the primary purchase determinant while safety lock compliance expands from regulatory mandate to competitive baseline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Culinary torch consumption patterns diverge sharply between geographies. The United States favors high-throughput butane units for steakhouse chains, while Japan prioritizes millimeter-precise flame control for sugar work. Germany and France navigate stricter material compliance, and China's manufacturing clusters feed global supply despite quality fragmentation.
United States
Steakhouse chains and independent restaurants drive replacement demand through continuous kitchen renovation cycles. The Consumer Product Safety Commission enforces ignition safety standards that reshape child-resistant lock designs. Commercial kitchen equipment distributors in Chicago and Dallas consolidate procurement relationships with national restaurant groups.
Germany
Mittelstand catering suppliers and full-service restaurants anchor butane torch volume through multi-year equipment contracts. EU F-Gas Regulation and REACH compliance force seal material transitions toward fluoropolymer alternatives. Industrial valve manufacturers in Baden-Württemberg supply precision components to torch assemblers.
Japan
Luxury hotel pastry kitchens and competition environments command premium pricing for repeatable temperature calibration. METI standards and fire safety codes restrict open-flame operation in institutional settings. Nagoya-based component suppliers specialize in micro-valve engineering for sugar work applications.
China
Guangdong and Zhejiang provinces host competing manufacturing clusters for torch components and finished units. The country's national quality regulator enforces evolving product safety standards for export certification. Shenzhen valve manufacturers supply adjustable flame mechanisms to Western brands despite quality inconsistency risks.
France
High-end pastry ateliers and luxury hospitality drive demand for precision flame control in sugar work and plated dessert finishing. ECHA material restrictions eliminate certain elastomer compounds from EU-sourced equipment. Lyon and Paris commercial kitchen suppliers bundle torch purchases with broader renovation contracts.
Culinary Torch Market Competitive Landscape
Capability concentration sits with precision engineering specialists; scale advantage sits with gas appliance heritage brands. The market structures around three tiers: multinational tool manufacturers with hardware retail penetration, specialized flame-control engineering houses, and commodity fabricators serving private-label channels. Consolidation pressure runs through foodservice distributor consolidation and direct-to-chef e-commerce bypass. Competitive moves center on fluoropolymer material qualification and dual-mode fuel-electric product architecture.
Within the gas appliance heritage tier, Iwatani Corporation exemplifies distribution dominance across Asian foodservice channels. Among precision engineering specialists, Blazer Products occupies a position defined by flame control technology for professional pastry applications. At the North American hardware retail vector, Bernzomatic anchors propane torch sales through specialty retail partnerships. These three represent the archetype spread: regional distribution leverage, technical specialization premium, and mass-market scale efficiency.
| Leading Market Players |
|---|
| Iwatani Corporation |
| Blazer Products |
| Bernzomatic |
| Chefman |
| RSVP International |
| Sterno Products |
| Zippo Manufacturing Company |
| Sondiko |
| Jo Chef |
| Others |
Value Network & Pricing Analysis
Guangdong and Zhejiang valve manufacturing clusters anchor component costs for Western torch brands, concentrating margin capture with precision engineering specialists who command premium pricing for adjustable flame mechanisms. This upstream concentration forces downstream assemblers to absorb material transition costs from EU F-Gas and REACH compliance while specialty pastry segments retain pricing power through repeatable temperature calibration.
Pricing Analysis
Long-term equipment contracts with German Mittelstand catering suppliers and Japanese luxury hotel chains dominate commercial procurement, insulating premium tiers from spot-market volatility. Three-tier pricing structure across precision pastry, standard commercial, and economy home-use levels differentiates by flame control certification and ergonomic design investment. Cost compression in economy butane units intensifies because of petroleum feedstock fluctuations and Chinese supply fragmentation. Home chefs through specialty retail channels show highest price sensitivity, while competition pastry kitchens in Japan and France demonstrate lowest sensitivity due to performance requirements.
Supply Chain Analysis
EU F-Gas Regulation export controls on fluorinated seal materials limit component flows from European suppliers to Asian assemblers, reshaping sourcing patterns. Manufacturing concentrates in China, Germany, and Japan, with Baden-Württemberg industrial valve makers and Nagoya micro-engineering specialists feeding precision tiers. Raw material dependencies span butane refined petroleum, fluoropolymer seal compounds, and ceramic heating cores. Single-source vulnerability concentrates in Guangdong adjustable valve mechanisms. Distribution runs through foodservice equipment distributors and direct-to-chef e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric heating elements and dual-mode architectures threaten pure fuel-based torch incumbents as fire-code jurisdictions multiply and CSRD-aligned procurement preferences harden in European corporate kitchens.
For Market Incumbents: Insulate core butane revenue through backward integration into fluoropolymer seal production, locking in REACH-compliant component supply before 2026 material phase-outs complete. Deepen channel control by acquiring specialty foodservice distributors in Germany and Japan to defend margin position against direct-to-chef e-commerce bypass. For New Entrants and Emerging Players: Mid-market commercial kitchens in French and Japanese institutional sectors represent the most penetrable entry point, where open-flame restrictions already ban fuel alternatives but procurement teams resist incumbent premium pricing. Electric torch technology with rapid-response ceramic cores offers the strongest go-to-market angle, paired with sustainability certification bundles that satisfy emerging CSRD disclosure mandates. For Investors and Strategic Acquirers: Capital is best deployed toward precision valve engineering specialists with demonstrated fluoropolymer qualification and locked relationships with Nagoya or Baden-Württemberg component suppliers. Over the medium-term horizon, acquisition targets should demonstrate dual-mode product architecture capability or exclusive distribution through national restaurant chain equipment contracts. Watch for inflection signals in fire-code adoption rates across US state jurisdictions and German federal kitchen safety interpretations.| Strategic Initiative | Industry Significance |
|---|---|
| Fluoropolymer Seal Qualification | REACH compliance deadlines in 2026 force material transitions, rewarding early-validated suppliers with locked sourcing relationships. |
| Dual-Mode Product Architecture | Hybrid fuel-electric units penetrate institutional kitchens where METI and EU fire codes restrict open-flame operation. |
| Direct-to-Chef E-Commerce Launch | Bypassing consolidated foodservice distributors captures independent restaurant and home enthusiast segments with higher-margin accessory bundles. |
| Precision Valve Backward Integration | In-house production of adjustable flame mechanisms reduces dependency on Guangdong supply fragmentation and quality inconsistency risks. |
| CSRD-Aligned Sustainability Certification | European corporate disclosure mandates create procurement preference for low-carbon-footprint electric torch alternatives in commercial kitchen renovations. |
Research Methodology
A spread of perspectives from commercial kitchen equipment distributors, pastry chef professionals, foodservice procurement managers, and industrial valve engineers converged on the working assumptions underlying demand modeling. Primary interviews across these stakeholder categories combined with secondary validation from EU F-Gas regulatory filings, REACH authorization databases, CPSC safety standards documentation, and foodservice equipment trade customs records. Bottom-up unit economics from component cost structures triangulated against top-down market sizing from national restaurant renovation cycle data.
Demand-supply balance framing anchored the analytical approach across the projection horizon, with segmentation modeling across product architecture, application intensity, end-user procurement channel, and safety feature tier. CAGRs derived from replacement cycle velocity in commercial settings and penetration rate assumptions for electric alternatives in fire-code-restricted jurisdictions. Industry-specific inputs included butane price volatility indices and fluoropolymer material qualification timelines.
Practitioners should monitor regulatory enforcement intensity around EU F-Gas material deadlines and US state-level fire-code adoptions for early signals of substitution acceleration. Forecasts reflect documented assumptions on kitchen renovation cycle continuity and petroleum feedstock stability. Material shifts in REACH substance authorization schedules or CPSC ignition safety reinterpretations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Warewashing Professional Equipment Market
Food Service Equipment
Food Display Cabinet Market
Food Service Equipment
North America Fountain Dispenser Equipment Market
Food Service Equipment
Food Thermos Market
Food Service Equipment
Hot Food Display Cabinet Market
Food Service Equipment
Food Holding Equipment Market
Food Service Equipment
Commercial Panini Grills Market
Food Service Equipment
Gas Commercial Deep Fryers Market
Food Service Equipment
Back Bar Coolers Market
Food Service Equipment
United States Commercial Dishwasher Market
Food Service Equipment
Commercial Steamer Market
Food Service Equipment
Commercial Food Warming and Holding Equipment Market
Food Service Equipment
Food Warmer Machines Market
Food Service Equipment
Sheet Pan Racks Market
Food Service Equipment
Saudi Arabia Foodservice Disposable Packaging Market
Food Service Equipment
Commercial Ice Equipment and Supplies Market