
 China Food Preservatives Market | 2026-2036
China Food Preservatives Market Size, Share, and Industry Trends Forecast 2026-2036
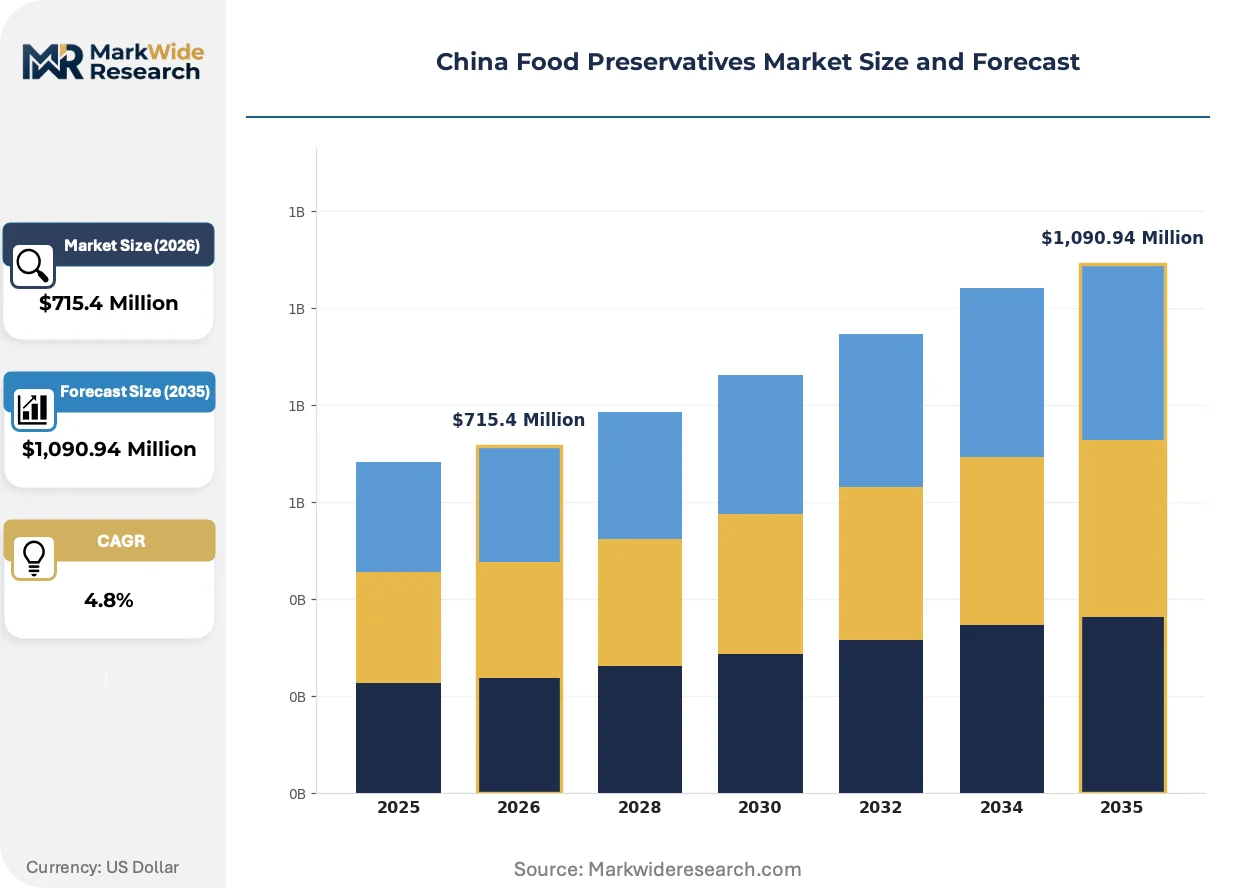
China Food Preservatives Market Outlook
Technical-grade formulation services is restructuring how preservative suppliers capture value beyond commodity sales. Cargill leverages its corn-derived ingredient pipeline to dominate sorbate supply chains across eastern China. Kerry Group anchors its position through integrated taste-and-preservation systems that reduce client formulation complexity. BASF competes on synthetic benzoate purity grades that meet stricter export-facing manufacturing standards.
Food preservatives are chemical or biological substances added to processed foods to inhibit microbial growth, oxidation, or enzymatic spoilage, typically dosed at 0.05% to 0.3% by weight depending on water activity and pH. Their primary commercial purpose is to extend distribution radius and retail shelf life for packaged goods in ambient-temperature supply chains. Sorbates lead the product-type landscape due to broad pH efficacy and clean-label migration trends among domestic dairy processors. The beverages application generates concentrated margin pools as carbonated and ready-to-drink tea segments demand high-volume, low-variation preservative contracts. Powder and granular forms command logistics advantages in China's inland food manufacturing corridors where liquid handling infrastructure remains uneven.
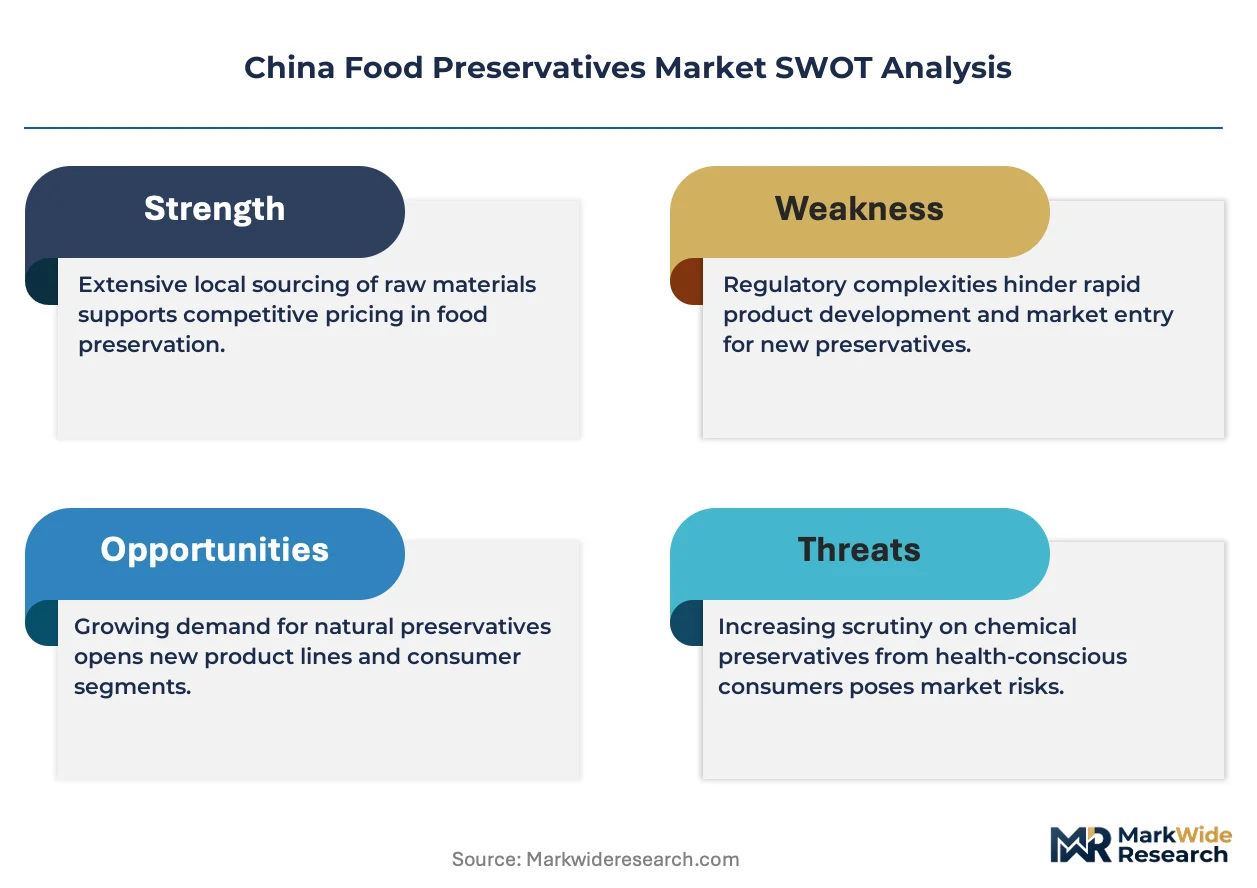
SAMR enforces GB 2760 food additive usage standards that prescribe maximum levels by food category, while NMPA-aligned safety assessments govern novel preservative approvals for functional food extensions. China's dual carbon goals are pressuring manufacturers to adopt fermentation-derived alternatives with lower process emissions profiles. Stakeholders must monitor how provincial environmental inspections reshape production costs for synthetic benzoate and propionate facilities in Shandong and Jiangsu.
Market Dynamics
SAMR's tightened GB 2760 enforcement is compressing supplier qualification timelines while coastal manufacturing clusters absorb reformulation costs faster than inland competitors. This regulatory pressure is redistributing procurement power toward integrated formulation service providers.
Growth Catalysts
- Dual carbon policy pressure:Fermentation-derived sorbates gain procurement preference as provincial environmental inspections raise synthetic production costs in Shandong and Jiangsu.
- Processed dairy shelf-life extension:Domestic dairy brands accelerate clean-label reformulation, expanding sorbate and natamycin contracts with technical-grade formulation partners.
- Shanghai-Guangzhou corridor density:Bulk preservative procurement concentrates in these coastal clusters where food processing infrastructure supports just-in-time delivery contracts.
Market Restraints
- Corn feedstock volatility:Sorbate production margins compress when corn prices spike, exposing cost structure vulnerability across fermentation-based supply chains.
- Synthetic benzoate purity bottlenecks:Export-facing manufacturers face limited qualified suppliers capable of meeting pharmaceutical-grade purity thresholds for cross-border shipments.
- Clean-label substitution pressure:High-pressure processing and modified atmosphere packaging displace chemical preservatives in premium beverage segments.
Strategic Opportunities
- Central China inland expansion:Powder and granular preservative formats bypass liquid handling infrastructure gaps in Henan and Hubei manufacturing corridors.
- NMPA novel preservative pathway:Functional food extensions create regulatory tailwind for fermentation-derived antimicrobial peptides in probiotic applications.
- Integrated taste-preservation systems:Flavor-house partnerships reduce client formulation complexity while capturing margin beyond commodity chemical sales.
Industry Challenges
- GB standard compliance timeline compression:SAMR's accelerated labeling enforcement requires rapid certificate updates that strain smaller domestic suppliers.
- Fermentation scale-up capex intensity:Cell-culture capacity expansion demands sustained capital commitment before achieving cost parity with synthetic chemistry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Food Preservatives Market |
| Market Size in 2026 | $715.4 Million |
| Market Size in 2035 | $1,090.94 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sorbates, Benzoates, Nitrates, Propionates Application: Beverages, Dairy, Bakery, Sauces Form: Liquid, Powder, Granular, Paste End User: Food Manufacturers, Retailers, Wholesalers, Restaurants |
| Companies Covered | Cargill, Kerry Group, Corbion, DSM, Jungbunzlauer, BASF, Archer Daniels Midland, Tate & Lyle, Fufeng Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Food Preservatives Market Strategic Shifts
Preservative markets are fragmenting along clean-label authenticity lines while formulation complexity migrates upstream to integrated ingredient suppliers. Technical service bundling is displacing standalone chemical procurement.
Biopreservation cultures derived from lactic acid bacteria are unifying antimicrobial function with probiotic positioning in dairy applications. Domestic yogurt processors adopt these cultures at pilot scale before full production rollout. This convergence is unifying shelf-life extension with digestive health marketing claims that command retail price premiums.
MEE provincial environmental inspections are tightening discharge permits for synthetic benzoate facilities in Jiangsu. Manufacturers face capital-intensive wastewater treatment upgrades or production curtailment decisions. Export-oriented processors accelerate supplier audits to secure uninterrupted purity-grade certification.
Buyer concentration among multinational beverage brands compresses switching cycles for preservative contracts. These procurement teams consolidate supplier panels from six vendors to two preferred partners with integrated technical service capabilities. This consolidation is most visible in Guangdong province where carbonated and ready-to-drink tea production clusters dominate volume demand.
China Food Preservatives Market Segmentation
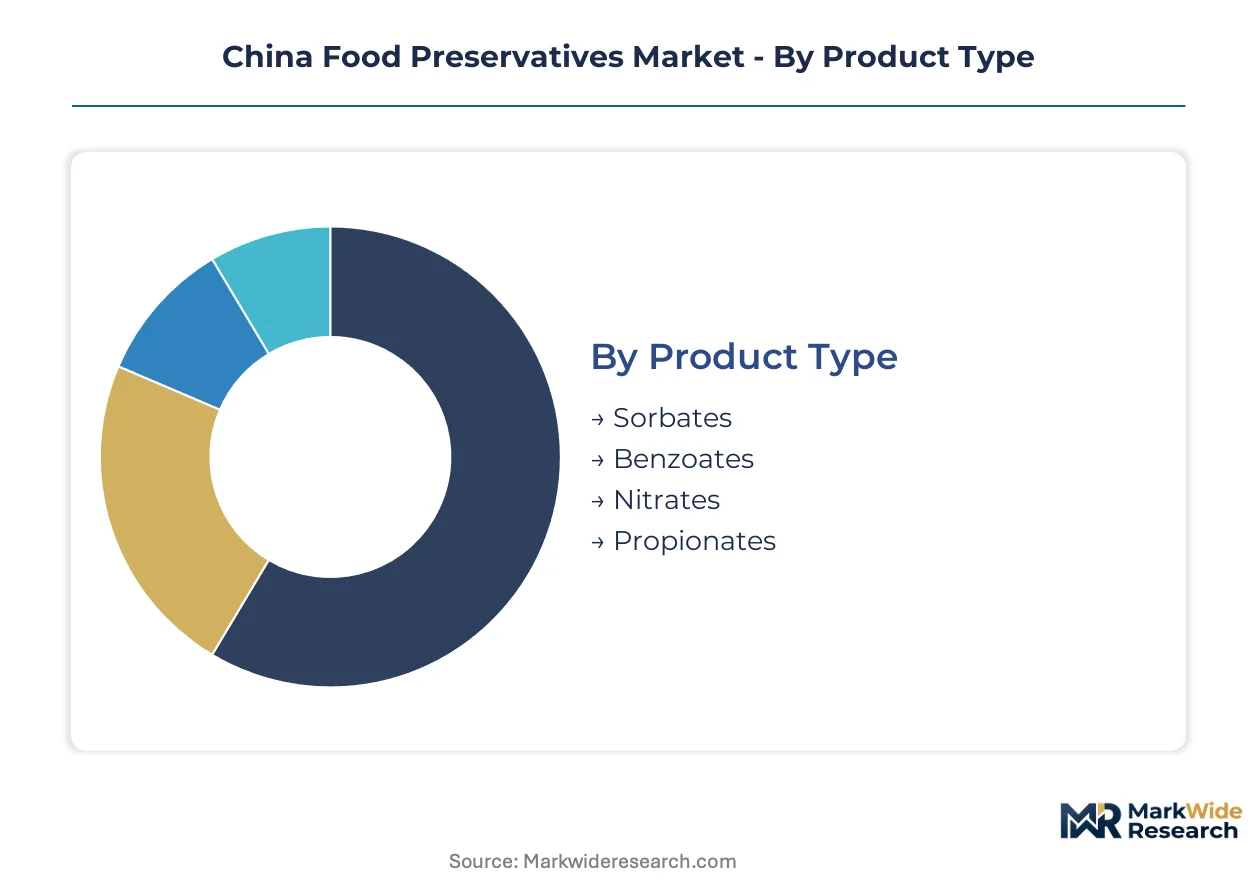
Preservative procurement in China fragments across formulation requirements, logistics constraints, and regulatory compliance tiers. Buyers select product types based on pH compatibility and clean-label positioning, while form factors respond to inland infrastructure gaps.
Product Type:
Formulation complexity drives supplier selection, with pH efficacy and fermentation-derived positioning reshaping procurement priorities.
- Sorbates:Potassium sorbate dominates due to broad antimicrobial spectrum across pH 2.5-6.5 and clean-label migration among Shanghai dairy processors. Coastal manufacturers favor sorbates for reformulation flexibility under tightening GB 2760 enforcement.
- Benzoates:Sodium benzoate offers cost-efficient preservation in acidic beverages below pH 4.5. Export-facing Guangdong bottlers demand pharmaceutical-grade purity grades that limit qualified supplier pools.
- Nitrates:Curing salts preserve color and inhibit Clostridium in processed meat applications.
- Propionates:Calcium propionate prevents mold in bakery matrices with higher water activity.
Volume sits with sorbates; growth tilts toward fermentation-derived alternatives under dual carbon policy pressure.
Application:
End-use margins concentrate where shelf-life extension commands retail price premiums and just-in-time delivery contracts.
- Beverages:Carbonated and ready-to-drink tea segments generate high-volume, low-variation procurement contracts. Guangdong production clusters absorb bulk preservative shipments through dedicated logistics corridors.
- Dairy:Domestic yogurt brands accelerate natamycin and sorbate adoption for ambient distribution expansion. Clean-label reformulation expands technical-grade formulation service contracts.
- Bakery:Extended shelf-life targets drive propionate demand in packaged bread and cake segments.
- Sauces:Fermented condiment producers balance traditional preservation with chemical additive reduction.
Beverages anchor procurement volume; dairy climbs the fastest on clean-label reformulation momentum.
Form:
Logistics infrastructure unevenness across provincial manufacturing corridors dictates format selection.
- Powder:Dry formats bypass liquid handling gaps in Henan and Hubei inland corridors. Bulk rail shipment reduces per-kilogram logistics costs for distant food processors.
- Granular:Free-flowing particles simplify dosing equipment integration in mid-scale bakeries. Dust-control properties improve workplace safety compliance under provincial labor inspections.
- Liquid:Pump-ready solutions dominate coastal facilities with integrated mixing infrastructure.
- Paste:Viscous formats serve niche applications requiring precise incorporation into emulsified matrices.
Powder commands inland volume; granular gains share fastest on safety and handling efficiency.
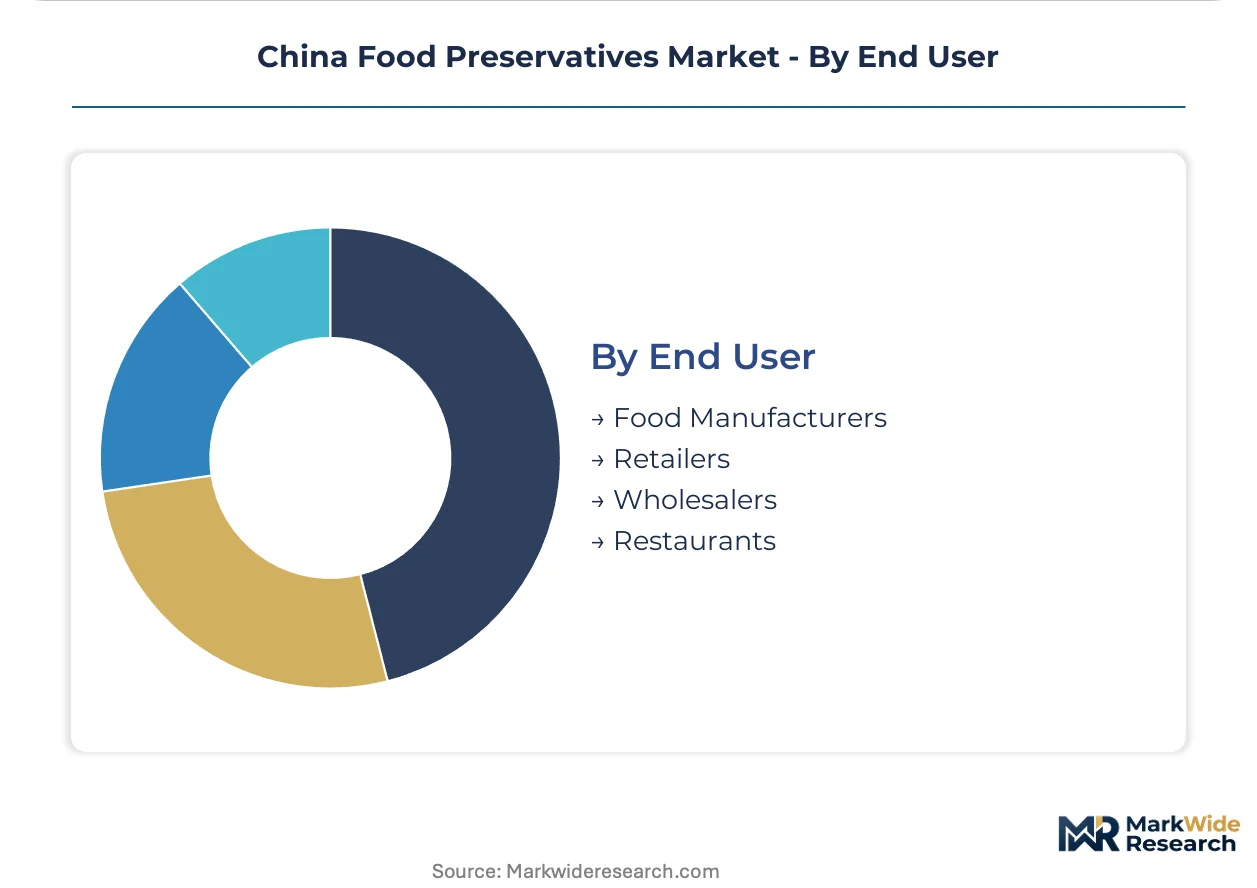
End User:
Buyer scale determines contract structure, with procurement power concentrating among integrated manufacturers.
- Food Manufacturers:Multinational beverage brands consolidate supplier panels from six vendors to two preferred partners. Technical service bundling displaces standalone chemical procurement in reformulation cycles.
- Retailers:Private-label packaged goods producers seek preservatives supporting extended distribution radius for ambient supply chains.
- Wholesalers:Regional distributors aggregate fragmented demand from small and mid-scale processors.
- Restaurants:Central kitchen operations adopt preservatives for pre-prepared ingredient stability.
Food manufacturers concentrate procurement volume; retailers expand fastest on private-label shelf-life targets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's preservative production clusters concentrate in coastal provinces while inland manufacturing corridors drive divergent format demand. Provincial environmental regulations and logistics infrastructure gaps fragment procurement patterns across sub-regional markets.
Yangtze River Delta
Shanghai anchors sorbate demand as domestic dairy processors accelerate clean-label reformulation. SAMR's GB 2760 enforcement compresses supplier qualification timelines for Jiangsu-based synthetic benzoate facilities facing MEE wastewater discharge inspections. The corridor absorbs bulk liquid preservative shipments through integrated mixing infrastructure serving carbonated beverage bottlers.
Pearl River Delta
Guangdong's ready-to-drink tea and carbonated beverage clusters generate high-volume procurement contracts with low formulation variation. Export-facing manufacturers demand pharmaceutical-grade purity thresholds that limit qualified benzoate supplier pools. Shenzhen and Guangzhou food processing density supports just-in-time delivery contracts for multinational beverage brands consolidating vendor panels.
Shandong Peninsula
Corn-derived fermentation feedstock availability positions the province as sorbate production center exposed to agricultural commodity volatility. Provincial dual carbon policy implementation raises synthetic chemistry production costs while favoring fermentation-derived alternatives. Qingdao and Jinan chemical parks face capital-intensive wastewater treatment upgrades under tightened environmental inspections.
Sichuan-Chongqing
Inland manufacturing growth in processed sauces and fermented condiments drives powder and granular preservative demand bypassing liquid handling gaps. Chongqing's central kitchen operations for restaurant chains adopt preservatives for pre-prepared ingredient stability. Rail logistics from coastal suppliers extend distribution radius for dry format bulk shipments.
Central China Corridor
Henan and Hubei food processors favor dust-controlled granular formats improving workplace safety compliance under provincial labor inspections. Mid-scale bakeries in Zhengzhou and Wuhan integrate free-flowing particles into dosing equipment without coastal-style pump infrastructure. Powder rail shipments reduce per-kilogram logistics costs for distant manufacturers.
China Food Preservatives Market Competitive Environment
Top-tier vendors anchor integrated formulation services, while commodity chemical suppliers compete on purity grades and fermentation scale. The market structures around three tiers: multinational ingredient platforms with technical service bundling, regional fermentation specialists with corn supply chain control, and synthetic chemistry pure-plays serving export-facing manufacturers. Strategic moves concentrate on backward integration into fermentation feedstock security and flavor-house partnerships capturing margin beyond standalone chemical sales.
Among multinational ingredient platforms, Cargill, Kerry Group, and BASF occupy positions exemplifying divergent competitive vectors. Cargill anchors fermentation-derived supply chain control through corn feedstock integration. Kerry Group represents integrated taste-and-preservation systems reducing client formulation complexity. BASF sits within synthetic purity-grade specialization serving export-facing manufacturers demanding pharmaceutical-grade benzoate certification.
| Leading Market Players |
|---|
| Cargill |
| Kerry Group |
| Corbion |
| DSM |
| Jungbunzlauer |
| BASF |
| Archer Daniels Midland |
| Tate & Lyle |
| Fufeng Group |
| Others |
Value Chain & Pricing Dynamics
Corn feedstock costs cascade through fermentation-based sorbate production into three distinct pricing tiers downstream. Agricultural commodity volatility in Shandong Province compresses margins for domestic suppliers while pharmaceutical-grade benzoate premiums widen the gap between export-facing and inland manufacturers.
Pricing Analysis
Margin tightening in standard-grade preservatives reflects corn price spikes and MEE environmental compliance costs. Three-tier pricing structure across pharmaceutical-grade, food-grade, and technical-grade separates export-certified benzoate from inland commodity sorbate. Cost-down pressure on economy-tier suppliers accelerates because provincial dual carbon policies raise synthetic chemistry production costs. Multinational beverage brands in Guangdong exhibit lowest price sensitivity due to just-in-time delivery requirements, while mid-scale bakeries in Central China corridors absorb highest price elasticity.
Supply Chain Analysis
Skilled fermentation technicians concentrate in Jiangsu and Shandong chemical parks where corn processing infrastructure anchors sorbate production. Supply draws from corn feedstock regions, synthetic benzoate facilities, and imported pharmaceutical-grade certification streams. Single-source vulnerability concentrates in coastal fermentation capacity exposed to environmental inspection curtailments. Distribution runs through dedicated logistics corridors serving Shanghai-Guangzhou manufacturing clusters, with rail networks extending powder formats inland.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's food preservatives sector is becoming a vertical-integration race as fermentation scale-up demands captive corn supply security. Players are pursuing backward integration into agricultural feedstock control to defend margin positions against commodity volatility.
For Market Incumbents: Anchor technical service bundling to defend against formulation complexity migration upstream. Incumbents should expand cell-culture capacity in Shandong before cost parity with synthetic chemistry erodes, while securing GB 2760 certification updates ahead of SAMR's accelerated enforcement timelines. Flavor-house partnerships capture margin pools beyond standalone chemical sales.
For New Entrants and Emerging Players: E-commerce procurement platforms for mid-scale inland bakeries represent the most penetrable white-space target. New entrants should exploit powder format logistics advantages in Henan and Hubei corridors where liquid handling infrastructure gaps persist. Direct technical service relationships with provincial dairy processors bypass multinational vendor consolidation.
For Investors and Strategic Acquirers: NMPA novel preservative approvals for functional food extensions are the leading indicator that fermentation-derived antimicrobial peptides will command valuation premiums. Acquisition targets should display captive corn supply agreements and integrated taste-preservation R&D capabilities. Watch for provincial environmental inspection intensity as the signal triggering synthetic capacity write-downs.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Feedstock | Captive agricultural supply secures sorbate margin stability against commodity spikes in Shandong. |
| Fermentation Capacity Scale-Up | Cell-culture expansion achieves cost parity with synthetic benzoate under dual carbon policy pressure. |
| Flavor-House Partnership | Integrated taste-preservation systems reduce client formulation complexity while capturing service margin. |
| Pharmaceutical-Grade Certification Investment | Export-facing purity thresholds unlock Guangdong beverage contracts with limited qualified supplier pools. |
| Powder Format Logistics Expansion | Dry preservative formats penetrate Henan-Hubei inland corridors lacking liquid handling infrastructure. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with fermentation plant managers, dairy procurement leads, beverage technical directors, and SAMR regulatory affairs specialists provided operational validation. SAMR GB standard updates, NMPA safety assessments, corn futures pricing, and provincial environmental inspection records supplied quantitative foundations. Bottom-up facility capacity estimates triangulated against top-down application demand projections.
Data-stream reconciliation across product type, application, form factor, and end-user scale dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segmented volume-demand modeling incorporating reformulation cycle timing, shelf-life extension targets, and clean-label migration rates. Fermentation scale-up capex curves and synthetic chemistry cost structures informed supply-side capacity assumptions.
The model holds under stable GB 2760 enforcement intensity and corn feedstock availability; deviation in provincial environmental inspection severity or agricultural commodity spikes would shift supplier competitiveness profiles. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Vinasse Market
Food Additives and Ingredients
Emulsified Shortenings Market
Food Additives and Ingredients
US Food Emulsifiers Market
Food Additives and Ingredients
Germany Food Colorants Market
Food Additives and Ingredients
Food and Beverage Additives Market
Food Additives and Ingredients
Global Food Anti Caking Agents Market
Food Additives and Ingredients
Food Grade Stearic Acid Market
Food Additives and Ingredients
Calcium Butyrate Market
Food Additives and Ingredients
Asia-Pacific Food Additives Market
Food Additives and Ingredients
Gardenia Food Color Market
Food Additives and Ingredients
Monosodium Glutamate Market
Food Additives and Ingredients
Canada Food Enzymes Market
Food Additives and Ingredients
Global Food Texturants Market
Food Additives and Ingredients
Clean Label Food Ingredient Market
Food Additives and Ingredients
Egypt Food Emulsifiers Market
Food Additives and Ingredients
Food Grade Dipotassium Phosphate Market