
 France Food Enzymes Market | 2026-2036
France Food Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
France Food Enzymes Market Foresight
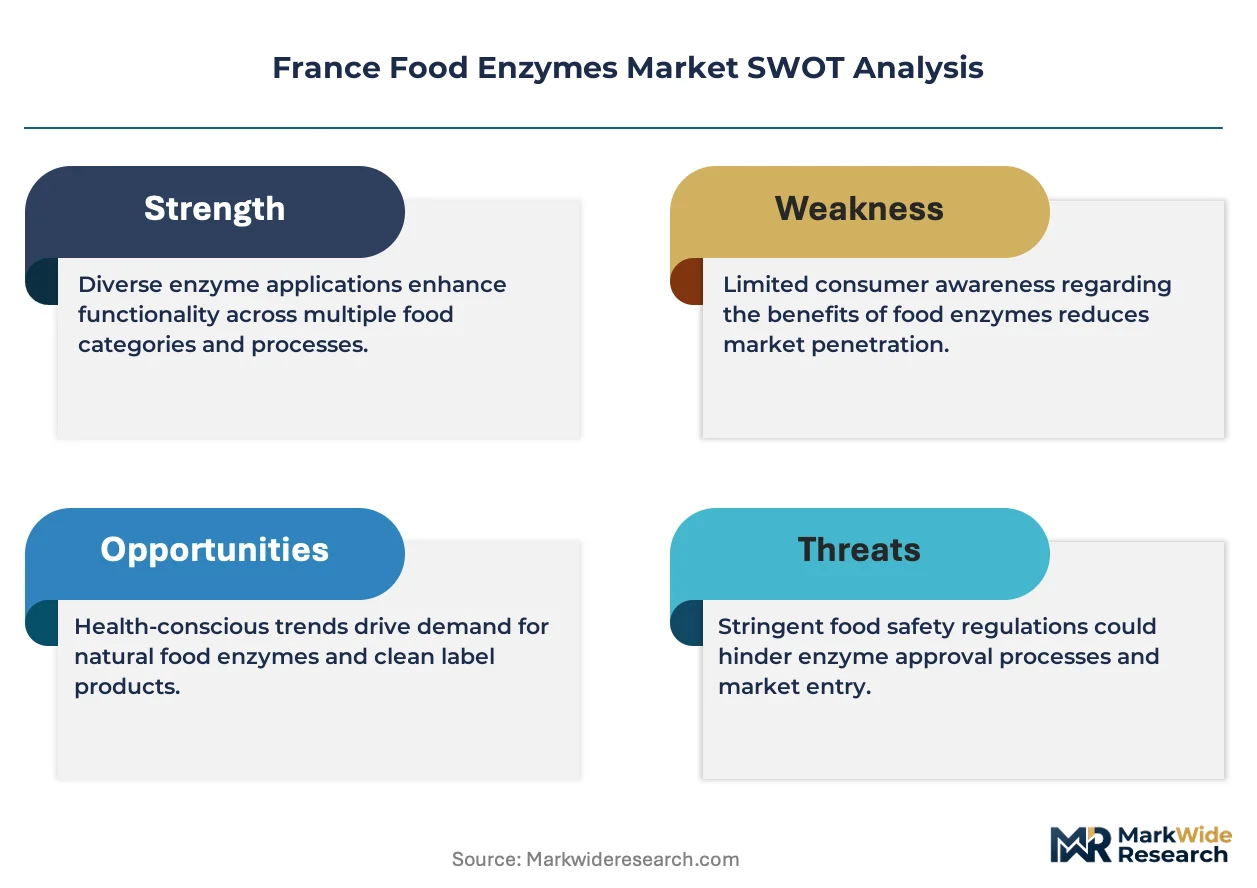
Enzyme-as-a-service formulations is broadening what French ingredient suppliers monetize beyond bulk powder sales. Novozymes A/S leverages its strain development platform to anchor premium positions in bakery enzyme portfolios. Kerry Group plc sustains formulation partnerships with mid-sized French dairies seeking clean-label protease solutions. BASF SE competes through granular enzyme forms that reduce dust exposure during industrial handling.
Food enzymes are protein-based biocatalysts, typically operating at temperatures between 30°C and 60°C and pH ranges of 4.0 to 8.0, that accelerate specific biochemical reactions in food matrices without becoming consumed in the process. Their primary commercial purpose is to modify texture, extend shelf life, or enhance flavor extraction during industrial food manufacturing. Proteases command the deepest margin pools in dairy processing applications where protein hydrolysis precision determines end-product quality. Amylases dominate volume in baking applications where starch modification controls crumb structure and staling rates. Lipase adoption is accelerating in specialty cheese production across Brittany and Normandy creameries.
ANSM and DGCCRF jointly enforce enzyme labeling and purity standards under evolving EU food additive frameworks, compelling manufacturers to document production strain genealogy and allergen cross-contamination protocols. EFSA novel food evaluations for emerging enzyme sources are lengthening approval timelines, favoring incumbents with established strain dossiers. BIS-equivalent conformity assessments for imported enzyme preparations add friction for non-EU suppliers seeking French market entry. Stakeholders must monitor how the EU Green Deal's bioprocessing targets redirect public funding toward enzymatic alternatives to chemical food processing aids.
Market Dynamics
ANSM's tightening purity thresholds for enzyme preparations are compressing supplier margins while concentrating procurement among dossier-rich incumbents who can document production strain genealogy across Île-de-France bakery clusters and Rhône-Alpes dairy processing corridors.
Growth Catalysts
- EU Green Deal bioprocessing targets:Public funding redirects toward enzymatic alternatives to chemical food processing aids, accelerating capital deployment into Brittany and Normandy creamery modernization programs.
- Clean-label protease demand:Mid-sized French dairies seek protein hydrolysis precision without synthetic additives, expanding formulation partnerships for shelf-stable specialty cheeses.
- Industrial bread line consolidation:Specialized amylase blends absorb volume as automated bakery operations across the Paris basin standardize on starch-modification systems that control crumb structure and staling rates.
Market Restraints
- EFSA novel food evaluation timelines:Lengthening approval windows for emerging enzyme sources favor established strain dossiers, freezing market entry for innovative production organisms.
- BIS-equivalent conformity friction:Non-EU suppliers face redundant safety assessments for imported enzyme preparations, raising landed costs and limiting sourcing flexibility.
- Production strain allergen protocols:Cross-contamination documentation requirements add fixed compliance costs that disproportionately burden smaller formulation houses.
Strategic Opportunities
- Enzyme-as-a-service monetization:French ingredient suppliers capture recurring revenue through performance-based formulation contracts rather than commodity powder sales.
- Granular enzyme form adoption:Dust-exposure reduction during industrial handling creates differentiation for suppliers serving high-volume baking operations with strict workplace safety mandates.
- Specialty lipase penetration:Brittany and Normandy creameries accelerate adoption for flavor-intensified aged cheeses, opening premium positioning beyond commodity dairy enzymes.
Industry Challenges
- Strain development talent scarcity:CRISPR-enabled production organism engineering requires specialized biochemists concentrated among a handful of research clusters, constraining in-house innovation capacity.
- Legacy equipment integration:Automated dosing systems for temperature-sensitive enzymes demand retrofit capital that mid-sized processors defer amid margin pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Food Enzymes Market |
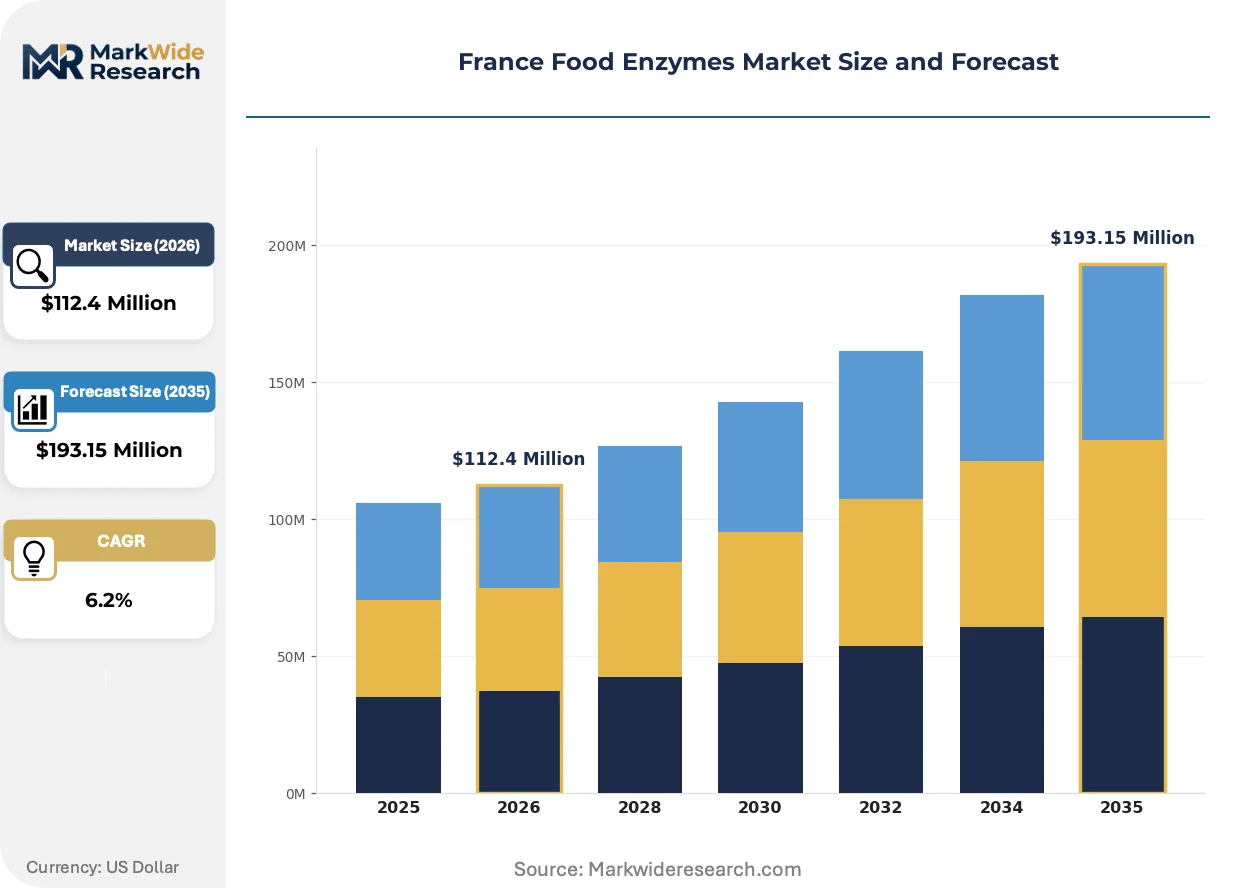
| Market Size in 2026 | $112.4 Million |
| Market Size in 2035 | $193.15 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proteases, Amylases, Lipases, Cellulases, Pectinases Application: Baking, Dairy Processing, Brewing, Meat Processing, Fruit Juice Production End User: Food & Beverage Manufacturers, Ingredient Suppliers, Food Processors, Quality Labs Form: Liquid, Powder, Granules, Tablet |
| Companies Covered | Corbion N.V., Kerry Group plc, Koninklijke DSM N.V., DuPont de Nemours Inc., Chr. Hansen Holding A/S, BASF SE, Novozymes A/S, Associated British Foods plc, International Flavors & Fragrances Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Food Enzymes Market Shifts & Advancements
Biocatalytic process intensification is compressing reaction times and energy inputs across French food manufacturing, while digital strain optimization and clean-label certification requirements reshape competitive positioning among enzyme suppliers.
CRISPR-guided strain development is unifying yield optimization with allergen reduction in production organisms. Novozymes A/S and specialized French biotech houses deploy these platforms to engineer amylase variants that operate across broader temperature windows. This capability is unifying premium pricing power with regulatory pre-approval advantages, compressing the timeline between laboratory validation and commercial bakery trials.
ANSM and DGCCRF joint enforcement of evolving EU food additive frameworks is mandating granular production strain genealogy documentation. Industrial enzyme houses must now maintain chain-of-custody records from original culture collection deposits through manufacturing scale-up. Dairy processors in the Rhône-Alpes cluster face the steepest compliance burden, responding by consolidating supplier relationships around dossier-complete incumbents.
Clean-label certification now dominates procurement scoring for French retail-facing food manufacturers. Mid-sized dairies and industrial bakeries prioritize enzyme suppliers who can deliver non-GMO, allergen-free declarations with third-party verification. This preference shift concentrates contract awards among suppliers with integrated quality systems, most visible across the Île-de-France food processing corridor where retail brand pressure transmits most directly to ingredient specifications.
France Food Enzymes Market Segmentation
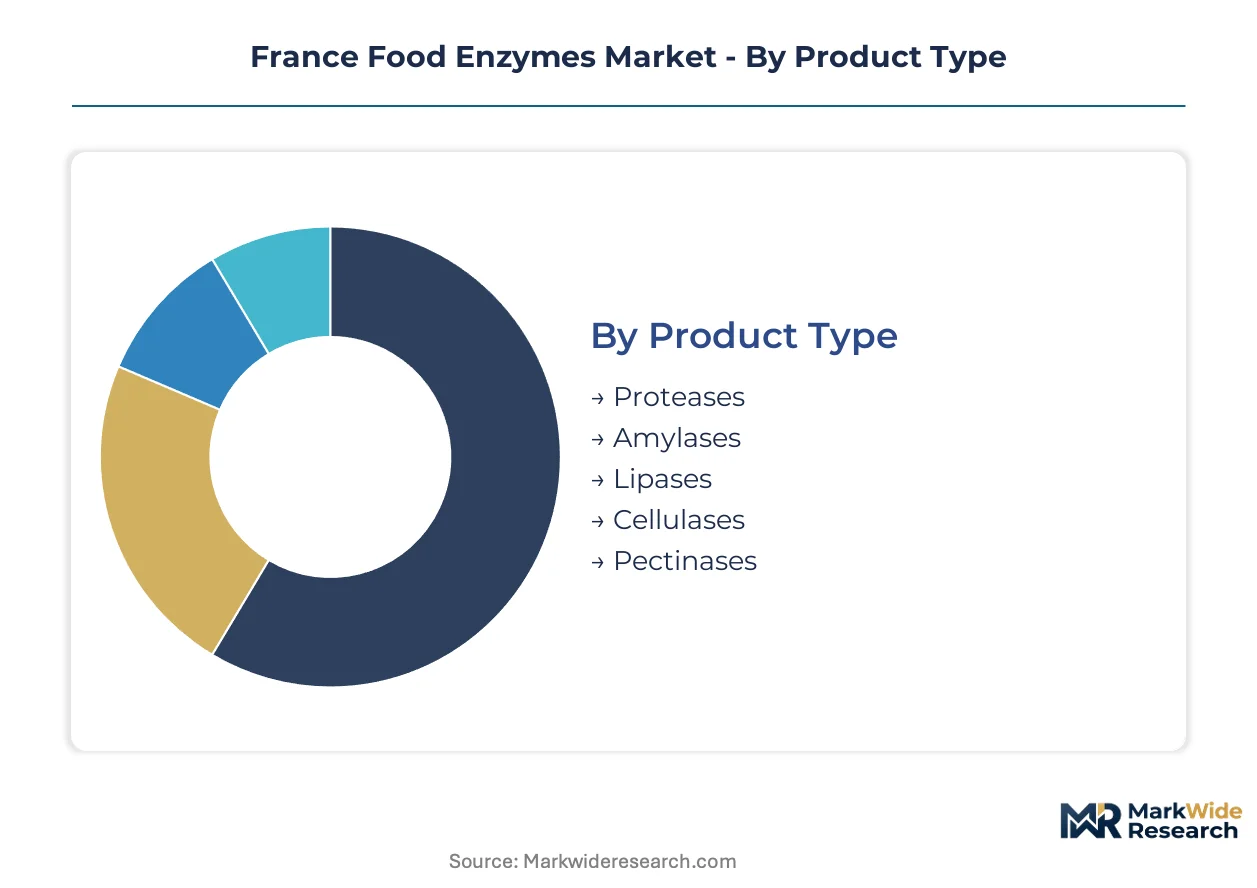
Enzyme specification tiers determine pricing power and regulatory burden across French food manufacturing. Procurement patterns diverge sharply between commodity bulk buyers and precision formulation houses serving premium retail channels.
Product Type:
Protein hydrolysis precision and starch modification breadth define competitive positioning among biocatalyst suppliers.
- Proteases:These enzymes cleave peptide bonds with substrate specificity that determines dairy protein hydrolysis efficiency. Rhône-Alpes cheese processors demand high-precision variants for aged Comté and Beaufort production, where protein breakdown kinetics control texture development and flavor intensity over 12-24 month aging cycles.
- Amylases:Alpha and beta variants modify starch gelatinization and retrogradation in bread matrices. Industrial bakery operations across the Île-de-France corridor standardize on thermostable fungal amylases that withstand dough mixing shear and oven spring temperatures while retarding staling rates in baguette and sandwich bread lines.
- Lipases:Ester bond hydrolysis generates free fatty acids for flavor accentuation in specialty cheeses.
- Cellulases:Cell wall degradation aids fruit juice extraction and clarification workflows.
- Pectinases:Pectin depolymerization improves press yields in cider and wine processing across Normandy and Champagne.
Mature deployment sits with proteases in established dairy corridors. Newer deployment is concentrated in lipase variants for artisanal creamery differentiation.
Application:
End-use process economics dictate enzyme concentration thresholds and dosing automation requirements.
- Baking:Starch modification enzymes dominate volume through automated dosing systems controlling crumb structure. Paris basin industrial bakeries absorb specialized amylase blends that reduce staling rates while maintaining label-friendly ingredient declarations.
- Dairy Processing:Protein hydrolysis precision commands premium positioning where clean-label protease solutions replace synthetic additives. Mid-sized French dairies in Brittany and Normandy prioritize formulation partnerships delivering consistent curd set times and flavor profiles.
- Brewing:Mashing efficiency enzymes reduce extraction times and improve fermentable sugar yields.
- Meat Processing:Tenderization applications utilize collagen-targeting proteases in prepared meat categories.
- Fruit Juice Production:Cell wall degrading enzymes improve press throughput and clarity in apple and grape processing.
Volume concentration favors baking applications with standardized dosing infrastructure. Margin expansion is climbing the fastest in dairy processing where precision requirements sustain premium pricing.
End User:
Procurement sophistication varies dramatically across buyer categories, with quality documentation requirements scaling with retail brand exposure.
- Food & Beverage Manufacturers:These integrated processors operate captive enzyme dosing systems with in-house quality validation. Major French retail brands demand chain-of-custody documentation from production strain deposits through finished enzyme batches, consolidating supplier relationships around dossier-complete incumbents.
- Ingredient Suppliers:Formulation houses blend enzymes into compound ingredients for downstream food processors. These intermediaries absorb ANSM purity threshold compliance costs while serving mid-sized manufacturers lacking internal biocatalysis expertise.
- Food Processors:Contract manufacturers purchase enzyme preparations through tolling arrangements.
- Quality Labs:Analytical service providers validate enzyme activity and purity for regulatory submissions.
Procurement standardization sits with food and beverage manufacturers. Emerging demand is concentrating in ingredient suppliers developing clean-label compound formulations.
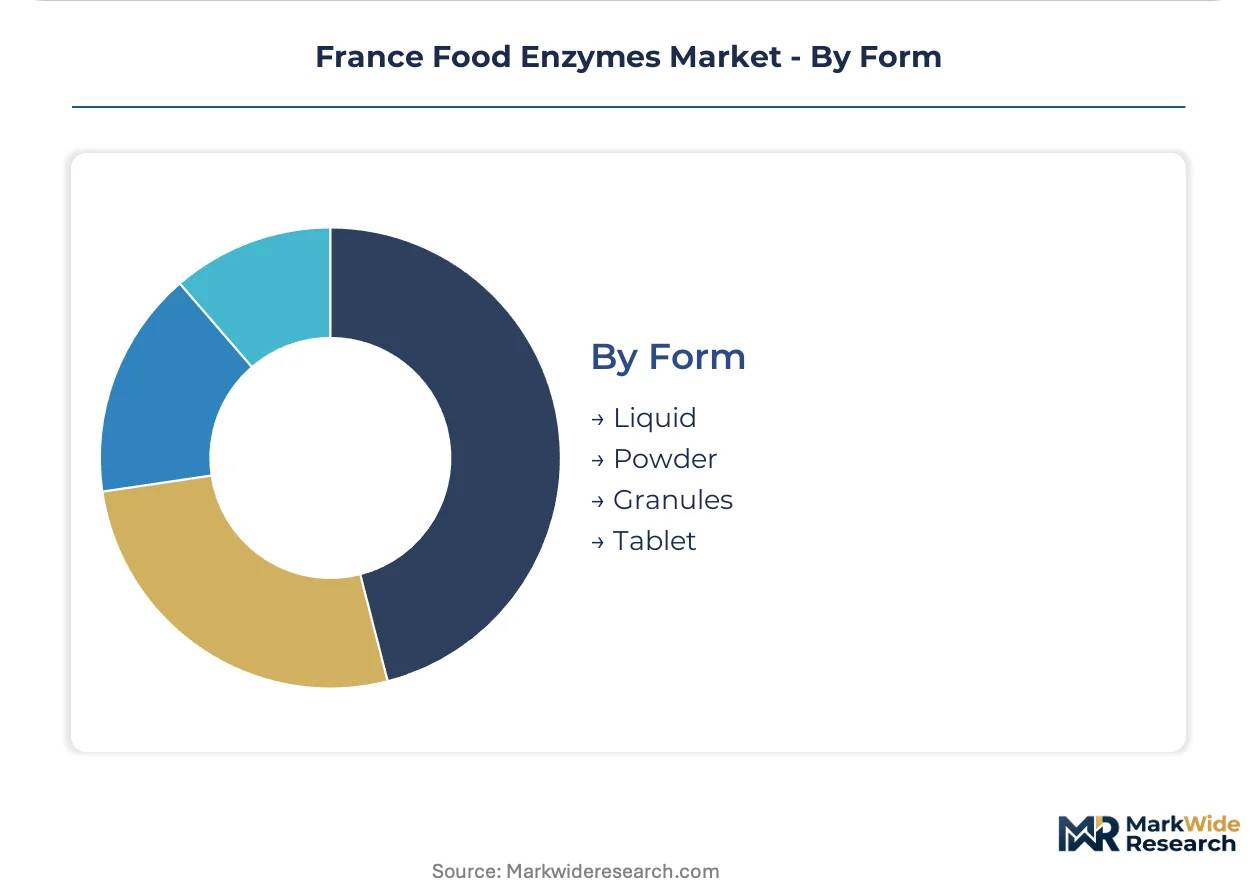
Form:
Physical presentation determines handling safety, dosing precision, and storage stability across French processing facilities.
- Liquid:Pumpable concentrates enable precise automated dosing in continuous bread and dairy lines. High-volume baking operations across the Île-de-France corridor favor liquid amylase systems integrating directly into dough mixing circuits with minimal handling exposure.
- Granules:Dust-suppressed forms reduce respiratory exposure during manual handling and bulk transfer. BASF SE and competing suppliers deploy granular protease and lipase presentations that satisfy workplace safety mandates in mid-sized creameries lacking full automation.
- Powder:Dry concentrates offer extended shelf stability for processors with intermittent enzyme demand.
- Tablet:Unit-dosed forms serve small-scale artisanal producers with batch-wise processing needs.
Industrial adoption concentrates in liquid forms with integrated dosing infrastructure. Granular penetration is expanding most quickly as workplace safety enforcement tightens across French food manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Île-de-France anchors French food enzyme demand through its dense concentration of industrial bakeries and retail brand headquarters. The Paris basin absorbs specialized amylase blends for automated bread lines while setting procurement standards that cascade to peripheral regions.
Île-de-France
Industrial bakeries across the Paris basin standardize on thermostable fungal amylase systems controlling crumb structure and staling rates. ANSM labeling requirements for enzyme preparations enforce purity documentation from production strain deposits through finished batches. Retail brand pressure concentrates in this corridor, transmitting clean-label specifications directly to ingredient procurement teams.
Auvergne-Rhône-Alpes
Rhône-Alpes dairy clusters command premium protease formulations for aged Comté and Beaufort production where protein hydrolysis precision determines texture development. EFSA novel food evaluations for emerging enzyme sources lengthen approval timelines, favoring established strain dossiers. Cheese processors in this region consolidate supplier relationships around dossier-complete incumbents capable of documenting production strain genealogy.
Brittany
Artisanal creameries accelerate lipase adoption for flavor-intensified aged cheeses, opening premium positioning beyond commodity dairy enzymes. EU Green Deal bioprocessing targets redirect public funding toward enzymatic alternatives to chemical processing aids. Modernization programs across coastal creameries absorb capital deployment for clean-label protease solutions replacing synthetic additives.
Normandy
Specialty cheese producers prioritize formulation partnerships delivering consistent curd set times and flavor profiles without synthetic inputs. DGCCRF joint enforcement with ANSM mandates granular production strain genealogy documentation across manufacturing scale-up. Mid-sized dairies in this cluster favor granular enzyme forms reducing dust exposure during manual handling.
France Food Enzymes Market Competitive Landscape
Capital-heavy producers compete with asset-light designers as multinational enzyme houses maintain captive strain development platforms while regional formulators rent access through licensing arrangements. The supplier base concentrates around dossier-rich incumbents who can navigate ANSM purity thresholds, compressing margins for smaller players lacking integrated quality systems. Two strategic archetypes dominate: integrated biocatalyst manufacturers with end-to-end strain-to-enzyme pipelines, and formulation specialists blending third-party enzymes into compound ingredients. Competitive moves center on granular form differentiation for workplace safety compliance and enzyme-as-a-service contracts capturing recurring revenue.
Among Netherlands-based biocatalyst specialists, Koninklijke DSM N.V. and Corbion N.V. occupy positions within the integrated manufacturing tier, exemplifying strain development capabilities that compress timelines between laboratory validation and commercial deployment. Novozymes A/S anchors the premium formulation segment, representing archetypal positioning through performance-based contracts rather than commodity powder sales. Kerry Group plc sits within the formulation partnership tier, serving mid-sized French dairies seeking clean-label protease solutions. These three companies illustrate how geographic origin and corporate structure correlate with strategic positioning across the French market.
| Leading Market Players |
|---|
| Corbion N.V. |
| Kerry Group plc |
| Koninklijke DSM N.V. |
| DuPont de Nemours Inc. |
| Chr. Hansen Holding A/S |
| BASF SE |
| Novozymes A/S |
| Associated British Foods plc |
| International Flavors & Fragrances Inc. |
| Others |
Supply & Pricing Matrix
EU Green Deal bioprocessing targets gate qualified supply and premium-tier pricing access by mandating enzymatic alternatives to chemical processing aids. French food manufacturers absorb compliance costs through dossier-rich incumbent relationships while mid-sized processors face margin compression from purity documentation requirements.
Pricing Analysis
Performance-based formulation contracts anchor value-based pricing where enzyme suppliers capture recurring revenue tied to yield outcomes and uptime guarantees. Three-tier pricing structure across premium, standard, and economy levels separates strain-dossier-complete incumbents from formulation houses and commodity powder traders. Cost compression in standard-tier protease supply is intensifying because ANSM purity thresholds concentrate procurement among documentation-capable suppliers. Mid-sized dairies in Brittany and Normandy exhibit highest price sensitivity due to retrofit capital constraints, while Île-de-France industrial bakeries prioritize supply security over unit cost.
Supply Chain Analysis
Culture collection deposits and production strain genealogy documentation create reverse-logistics complexity for enzyme houses maintaining chain-of-custody records through manufacturing scale-up. Supply concentrates in Denmark, the Netherlands, and Germany where integrated biocatalyst manufacturers operate captive strain development platforms. Raw material dependencies include fermentation media substrates, chromatography resins, and sterile packaging materials. Single-source vulnerability sits with specialized production organism engineering talent concentrated in CRISPR-enabled research clusters. Distribution runs through formulation partnerships and direct procurement contracts with food and beverage manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CRISPR-guided strain development is displacing legacy mutagenesis approaches, compressing timelines between laboratory validation and commercial bakery trials while raising barriers for suppliers lacking integrated biotechnology platforms.
For Market Incumbents: Deploy granular enzyme form differentiation to capture workplace safety compliance budgets across mid-sized creameries lacking full automation. Consolidate supplier relationships around dossier-complete strain genealogy documentation to defend against emerging biotech houses with faster regulatory pre-approval advantages. Channel control through enzyme-as-a-service contracts locks in recurring revenue streams.
For New Entrants and Emerging Players: Launch via specialty lipase formulations targeting artisanal creameries in Brittany and Normandy seeking flavor-intensified aged cheese differentiation. White-space concentration sits with clean-label protease solutions for mid-sized dairies replacing synthetic additives, and dust-suppressed granular forms satisfying tightening workplace safety mandates. Direct technical service partnerships bypass incumbent distribution networks.
For Investors and Strategic Acquirers: EFSA novel food approval acceleration for CRISPR-enabled production organisms is the leading indicator that strain development platform acquisitions will outperform commodity formulation houses. Long-term viability favors integrated biocatalyst manufacturers with end-to-end pipelines over asset-light blenders. Acquisition target archetype: French biotech houses with validated amylase variants and established ANSM dossiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Strain Development Platform Acquisition | CRISPR-enabled engineering capabilities compress laboratory-to-commercial timelines for thermostable enzyme variants. |
| Granular Form Manufacturing Scale-Up | Dust-exposure reduction satisfies DGCCRF workplace safety enforcement across Rhône-Alpes dairy processing corridors. |
| Enzyme-as-a-Service Contract Expansion | Performance-based recurring revenue models displace commodity powder transactions in Île-de-France baking operations. |
| Clean-Label Certification Investment | Non-GMO and allergen-free declarations secure procurement preference from retail-facing French food manufacturers. |
| Regional Formulation Partnership | Technical service proximity to Brittany and Normandy creameries enables specialty lipase customization for aged cheese production. |
Research Methodology
EFSA novel food evaluation databases, ANSM regulatory filings, and EU food additive framework directives formed the secondary backbone for enzyme approval timeline and purity threshold analysis. Primary interviews with strain development directors at integrated biocatalyst manufacturers, procurement leads at Île-de-France industrial bakeries, quality assurance managers at Rhône-Alpes cheese processors, and formulation specialists at mid-sized French dairies validated secondary findings. Customs and trade data for enzyme preparation imports supplemented bottom-up and top-down triangulation across the analysis window.
Historical trendline analysis of amylase and protease deployment patterns informed the analytical framework across product type, application, end user, and form segmentation dimensions. CAGRs were derived through regression analysis of volume absorption rates in industrial bread lines and dairy processing corridors. Industry-specific forecast inputs included EU Green Deal bioprocessing target funding allocations and ANSM labeling requirement implementation schedules.
The model assumes a particular technology adoption path; alternative pathways for CRISPR-enabled production organism engineering would alter the outlook for incumbent strain dossier advantages. Forecasts reflect assumptions about regulatory approval velocity and clean-label certification penetration. Practitioners should monitor EFSA evaluation timeline compression and DGCCRF enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Carrageenan Gum Market
Food Additives and Ingredients
Mexico Food Enzymes Market
Food Additives and Ingredients
AKD Emulsifier Market
Food Additives and Ingredients
Global Oleate Esters Market
Food Additives and Ingredients
Mediterranean Sourdough Starter Cultures Market
Food Additives and Ingredients
Asia Pacific Food Acidulants Market
Food Additives and Ingredients
India Food Acidulants Market
Food Additives and Ingredients
United States Food Enzymes Market
Food Additives and Ingredients
China Food Enzymes Market
Food Additives and Ingredients
Bakery Enzymes Market
Food Additives and Ingredients
North America Food Additives Market
Food Additives and Ingredients
North America Food Acidulants Market
Food Additives and Ingredients
United Kingdom Food Preservatives Market
Food Additives and Ingredients
Beverage Clouding Agent Market
Food Additives and Ingredients
Natural Food Color Ingredients Market
Food Additives and Ingredients
Germany Food Acidulants Market