
 UK Insect Repellent Market | 2026-2036
UK Insect Repellent Market Size, Share, and Industry Trends Forecast 2026-2036
UK Insect Repellent Market Outlook
Plant-derived active ingredient technology is fragmenting the traditional chemical-dominated formulation landscape. Reckitt Benckiser Group PLC leverages its pharmacy and supermarket shelf presence to sustain volume leadership across mainstream retail channels. SC Johnson anchors its position through concentrated R&D in DEET-free alternatives, while Spectrum Brands Holdings Inc competes aggressively in the outdoor specialty segment through targeted camper and hiker product lines.
UK insect repellent encompasses topical formulations containing active biocidal compounds such as DEET, picaridin, or plant-derived oils like citriodiol, designed to interfere with arthropod olfactory receptors and prevent bites from mosquitoes, ticks, and biting flies. These products serve commercial and consumer markets where vector-borne disease prevention and outdoor comfort drive purchasing decisions. Sprays retain dominant shelf space in supermarkets and pharmacies due to familiar application habits and lower per-unit pricing, though DEET-Free formulations are gaining fastest velocity as parental buyers and eco-conscious travelers reject synthetic actives. Online Retail channels capture disproportionate growth in subscription and bulk formats, while Natural and Herbal segments attract premium positioning despite smaller absolute volumes.
The Health and Safety Executive administers UK Biocidal Products Regulation compliance, determining which active ingredients gain market access and which formulations require re-authorization. Trading Standards services enforce product labeling accuracy and claims substantiation across England, Scotland, Wales, and Northern Ireland. Stakeholders must monitor pending HSE substance evaluations and emerging entomological risk maps to align portfolio development with both regulatory survival and shifting vector exposure patterns.
Market Dynamics
The UK Insect Repellent Market is experiencing structural pressure from the Health and Safety Executive's tightening Biocidal Products Regulation framework, which is systematically narrowing the approved active ingredient list and forcing reformulation investments across the value chain.
Growth Catalysts
- Outdoor recreation expansion:British families are extending camping and hiking participation into shoulder seasons, creating sustained demand for portable protection formats across England's national parks and southern coastal trails.
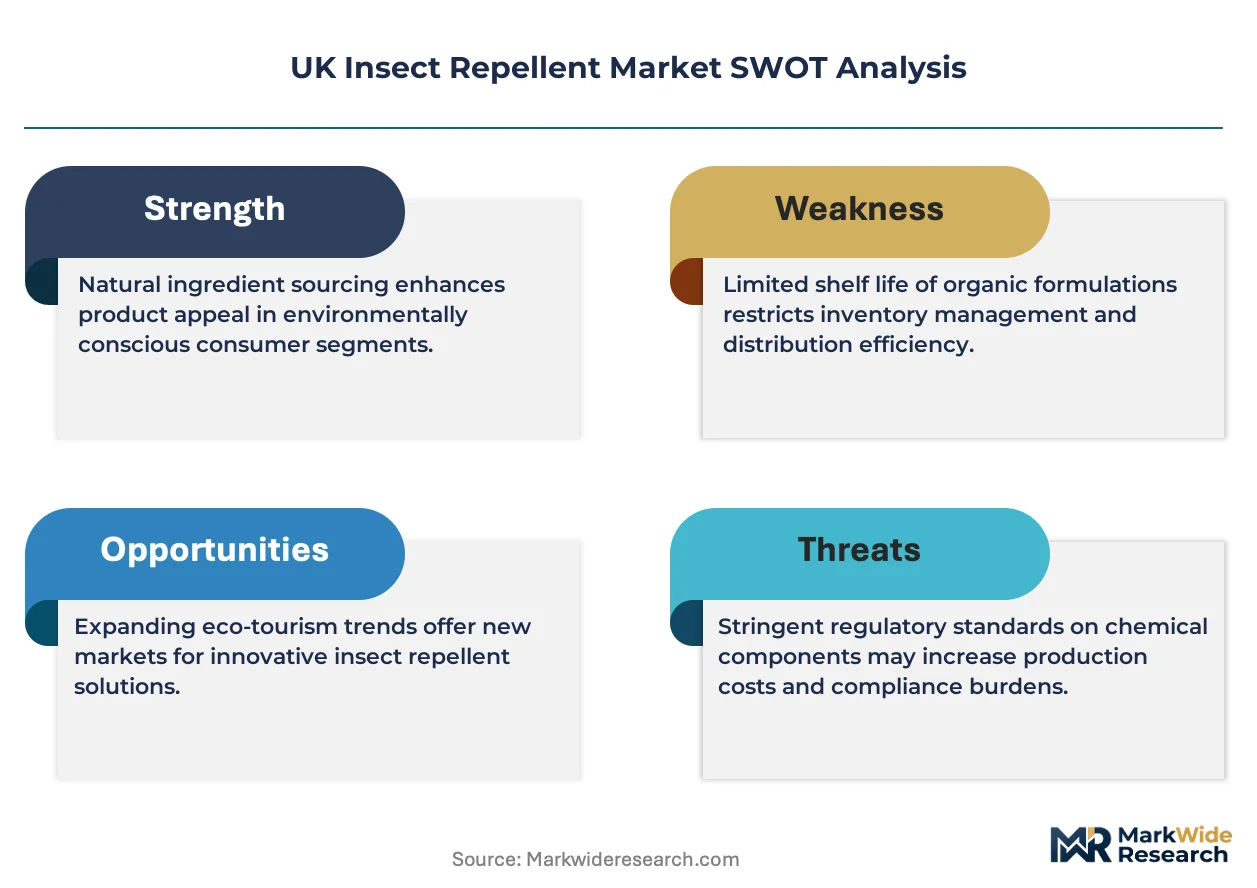
- Biocidal Products Regulation compliance deadlines:HSE-mandated re-authorization timelines are compressing product development cycles and rewarding early movers who secured dossier approvals for citriodiol and picaridin formulations.
- Vector risk mapping:Public Health England's tick and mosquito surveillance programs are identifying new high-exposure corridors in urban green spaces, driving preventive purchasing in Greater London and the South East.
Market Restraints
- Active ingredient supply concentration:Synthetic pyrethroid and DEET feedstock production clusters in China and India expose UK formulators to shipping cost volatility and customs processing delays.
- Natural extract yield variability:Citriodiol sourcing from Corymbia citriodora plantations in Australia and Brazil faces climate-driven harvest fluctuations that compress margin predictability.
- Biocidal Products Regulation authorization costs:HSE dossier preparation and efficacy testing requirements for new active substances demand six-figure investments that exclude smaller specialty entrants.
Strategic Opportunities
- Wales and Northern Ireland penetration:These regions show lower category development indices than England, presenting whitespace for targeted retail distribution and outdoor retailer partnerships.
- Subscription commerce models:Direct-to-consumer platforms are capturing recurring revenue through seasonal replenishment programs for families with consistent outdoor exposure patterns.
- Travel retail channel expansion:Airport and cross-Channel ferry terminals serving Mediterranean and tropical destinations represent high-margin impulse purchase environments for premium DEET-free formats.
Industry Challenges
- Entomological testing capacity constraints:HSE-recognized laboratories for mosquito and tick repellency testing face backlogs that extend product launch timelines by quarters.
- Label claim substantiation complexity:Trading Standards enforcement of efficacy assertions requires documented field trial data that many heritage brands lack for reformulated natural actives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Insect Repellent Market |
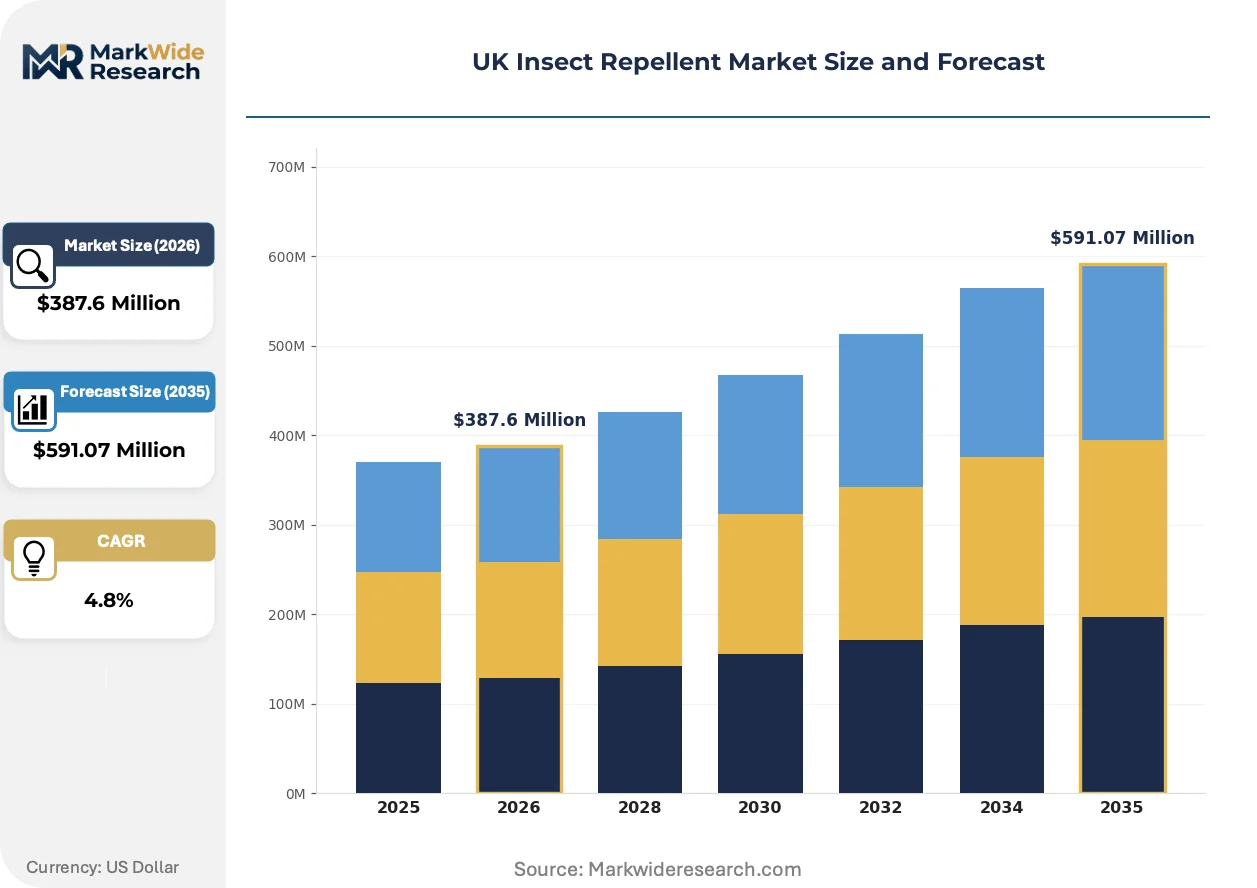
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $591.07 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sprays, Lotions, Wipes, Gels End User: Outdoorsmen, Families, Travelers, Campers Formulation: Chemical-Based, Natural, Herbal, DEET-Free Distribution Channel: Online Retail, Supermarkets, Pharmacies, Specialty Stores |
| Companies Covered | Dabur India, Henkel AG & Co KGaA, Reckitt Benckiser Group PLC, Sawyer Products, Jyothy Laboratories, SC Johnson, Spectrum Brands Holdings Inc, Coghlan's, Godrej, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Insect Repellent Market Strategic Shifts
Formulation science and distribution architecture are undergoing parallel transformation as biocidal regulation tightens and consumer preference bifurcates between clinical efficacy and natural positioning.
Encapsulated release technology is digitizing application precision in the UK Insect Repellent Market. Microsphere and polymer-matrix delivery systems extend protection duration while reducing skin absorption rates. Pediatric and sensitive-skin segments are adopting these formats fastest, compressing the historical trade-off between DEET concentration and wearability.
Health and Safety Executive substance evaluations are accelerating active ingredient substitution timelines. The pending review of icaridin concentration limits and citriodiol purity standards is forcing portfolio rationalization. Smaller formulators without regulatory affairs depth are exiting rather than absorbing compliance costs, concentrating shelf access among established players.
Parental purchasing behavior is fragmenting across channel type rather than consolidating on legacy pharmacy destinations. Amazon and specialist outdoor e-commerce platforms are capturing trial and bulk replenishment occasions that Boots and Superdrug previously dominated. This rotation is most visible in suburban England households with multiple children and seasonal travel patterns to European camping destinations.
UK Insect Repellent Market Segmentation
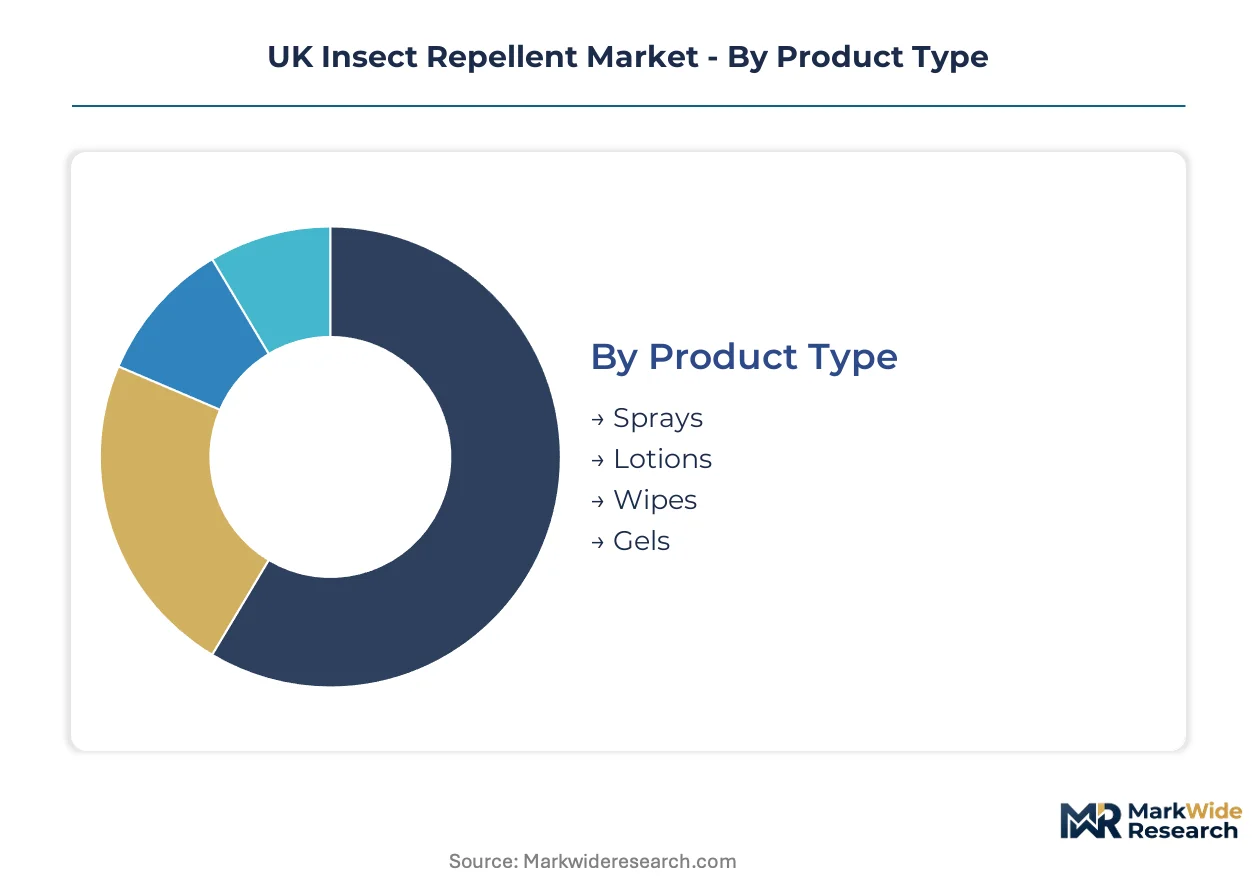
Segmentation in the UK Insect Repellent Market reveals how formulation preferences and channel behaviors fragment purchasing decisions across distinct user contexts. Understanding these divides allows manufacturers to align biocidal compliance investments with the specific efficacy expectations and application settings that drive repurchase loyalty.
Product Type:
After-sales engagement intensity varies sharply by format, with sprays demanding minimal consumer education while wipes and gels require explicit usage guidance to achieve labeled protection duration.
- Sprays:Aerosol and pump-dispersed liquid formulations dominate pharmacy and supermarket shelf space due to familiar application mechanics and rapid skin coverage. Demand concentrates in suburban England households preparing for Mediterranean holidays and domestic camping trips, where speed of application outweighs portability concerns.
- Lotions:Cream-based carriers with higher emollient content suit pediatric and sensitive-skin segments seeking controlled dosing and reduced dermal absorption. Families in Greater London and the South East favor these formats for tick-prone urban park visits, trading convenience for perceived safety margins.
- Wipes:Pre-saturated towelettes target travelers and day-hikers prioritizing packability and TSA compliance for carry-on luggage.
- Gels:Thickened formulations with extended skin adhesion serve anglers and golfers requiring sweat-resistant protection during stationary outdoor activity.
Sprays hold the largest share; momentum sits with Lotions as parental buyers reject synthetic actives for child applications.
End User:
Cost tier stratification separates commodity purchasers from premium seekers, with biocidal efficacy certification becoming the primary price discriminator.
- Outdoorsmen:Dedicated anglers, hunters, and forestry workers demand maximum protection duration against multiple vector species. These users in Scotland's Highland regions and England's Lake District tolerate higher DEET concentrations and specialized application frequencies.
- Families:Multi-person households with children drive volume through seasonal bulk purchasing and subscription replenishment. Parents in southern coastal counties prioritize DEET-Free and natural formulations for school-age children despite shorter protection windows.
- Travelers:Leisure and business passengers to tropical destinations seek compact formats meeting airline liquid restrictions and malaria prophylaxis recommendations.
- Campers:Weekend and expedition tent-based recreationists balance weight constraints with all-day protection needs across variable weather conditions.
Families command the greatest volume base; Travelers are expanding most quickly as post-pandemic long-haul bookings recover.
Formulation:
Application setting dictates active ingredient selection, with clinical environments tolerating synthetic biocides while domestic and leisure contexts favor reduced-chemistry positioning.
- Chemical-Based:Synthetic pyrethroid and high-concentration DEET formulations deliver longest-lasting protection against aggressive mosquito species. These products retain dominance among professional outdoor workers in England's agricultural and forestry sectors where HSE-authorized efficacy documentation is mandatory.
- Natural:Plant-derived actives including citronella and lemongrass oils appeal to eco-conscious consumers accepting shorter reapplication intervals. Demand clusters in Bristol, Brighton, and other urban centers with strong environmental advocacy demographics.
- Herbal:Traditional botanical preparations with limited HSE biocidal authorization occupy niche positioning through health food retail channels.
- DEET-Free:Picaridin and IR3535-based alternatives capture travelers and parents seeking synthetic-avoidance without sacrificing clinical efficacy validation.
Chemical-Based formulations retain the largest share; DEET-Free alternatives are gaining share fastest as regulatory pressure and consumer preference converge.
Distribution Channel:
Customer type fragmentation separates emergency purchasers seeking immediate availability from planners optimizing unit economics through bulk acquisition.
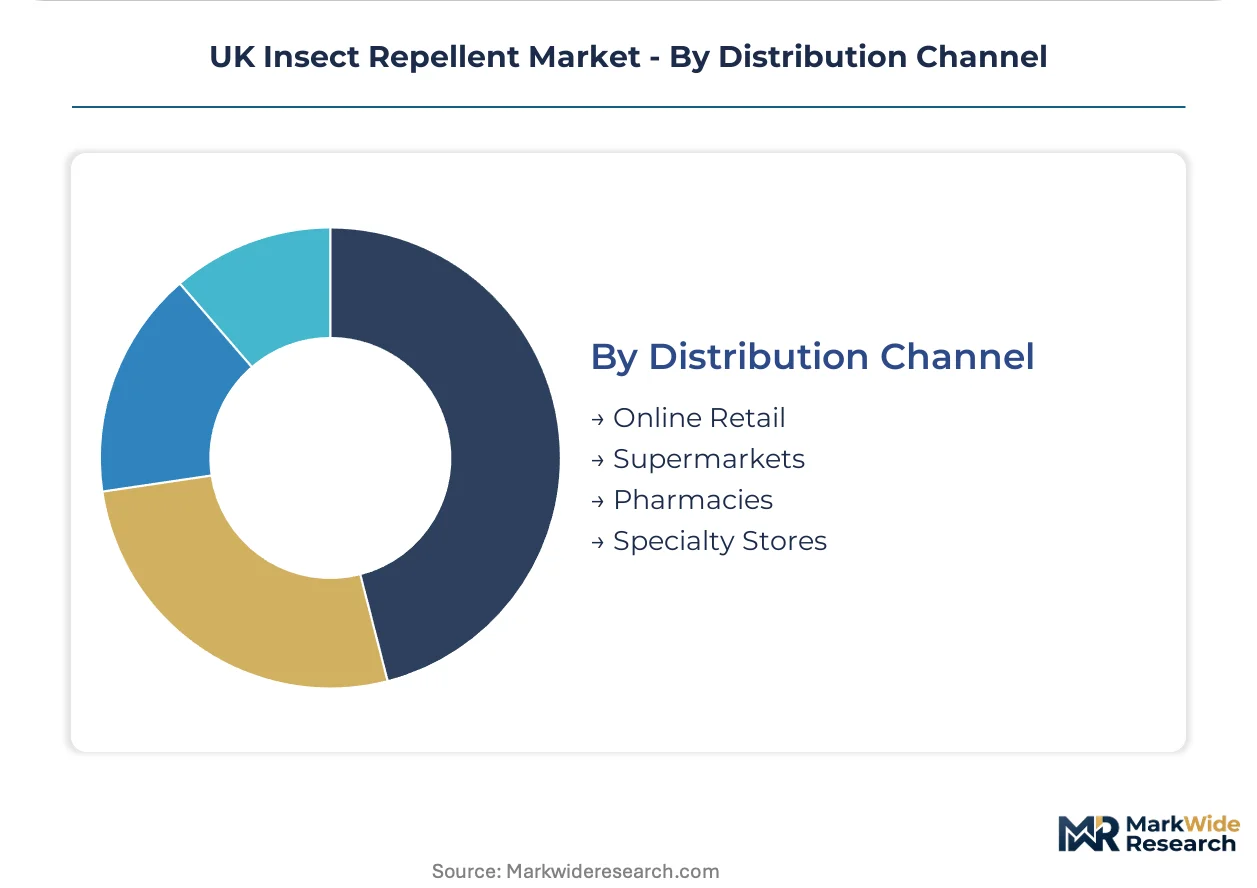
- Online Retail:Amazon and specialist outdoor e-commerce platforms capture subscription replenishment and pre-trip bulk purchasing. These channels disproportionately serve England's suburban family households with predictable seasonal travel patterns to European camping destinations.
- Supermarkets:Tesco, Sainsbury's, and Asda drive impulse and routine replenishment through prominent seasonal displays and promotional pricing. Volume concentrates in urban corridors where convenience trumps specialist advice.
- Pharmacies:Boots and Superdrug retain authority in pediatric and travel health consultations, with trained staff influencing active ingredient selection.
- Specialty Stores:Cotswold Outdoor, Go Outdoors, and independent camping retailers serve enthusiasts seeking technical product comparison and field-tested recommendations.
Supermarkets hold the largest share; Online Retail shows the steepest expansion trajectory as replenishment automation and bulk discounting lock in household loyalty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China and India supply concentrated pyrethroid and DEET feedstocks to UK formulators, while Australian citriodiol plantations serve natural-active demand. Distribution patterns concentrate manufacturing inputs in East Asia and botanical sourcing in the Southern Hemisphere before final formulation in England.
London and the South East
Urban park tick exposure and Mediterranean holiday travel drive preventive purchasing in Greater London, Surrey, and Kent. The Health and Safety Executive's Biocidal Products Regulation enforcement operates from its Bootle headquarters, directly influencing formulation approvals for products sold throughout England. Pharmacy chains and supermarket headquarters in London coordinate seasonal inventory placement for suburban family households.
England's Midlands
Manufacturing and logistics infrastructure for imported active ingredients concentrates around Birmingham and Leicester distribution hubs. Trading Standards services in the East Midlands monitor labeling compliance for products entering the UK through East Coast ports. Warehouse capacity here supports just-in-time replenishment to northern retail networks.
Scotland
Highland forestry workers and deer stalkers demand maximum-duration protection against midges and ticks in Aberdeenshire and the Cairngorms. Scottish Natural Heritage land access policies shape outdoor recreation patterns that concentrate repellent demand in summer months. Edinburgh and Glasgow retail channels serve both urban consumers and expedition outfitters bound for remote glens.
Wales
Lower category penetration relative to England creates whitespace for targeted outdoor retailer partnerships in Snowdonia and Brecon Beacons corridor. The Welsh Government's outdoor tourism promotion programs expand camping participation among English visitors crossing the border. Coastal counties face tick exposure risks comparable to southwestern England but with fewer dedicated pharmacy access points.
Northern Ireland
Cross-border trade flows with the Republic of Ireland create dual regulatory exposure to UK Biocidal Products Regulation and EU Biocidal Products Regulation frameworks. Belfast distribution serves a concentrated population base with limited outdoor specialty retail presence compared to mainland Britain. Rural counties in the west sustain agricultural worker demand for HSE-authorized professional-grade formulations.
UK Insect Repellent Market Competitive Environment
Channel-controlling players compete with product-specialist players across pharmacy, supermarket, and outdoor retail tiers. The vendor base clusters around three strategic archetypes: multinational consumer goods conglomerates with biocidal regulatory affairs depth, mid-sized outdoor specialty suppliers with enthusiast credibility, and emerging natural-formulation challengers with health-food retail access. Dominant competitive moves include portfolio diversification into DEET-Free alternatives and strategic partnerships with online subscription platforms.
Among the established multinational tier, Reckitt Benckiser Group PLC and SC Johnson occupy positions representing mainstream retail channel dominance and concentrated R&D investment respectively. Spectrum Brands Holdings Inc exemplifies the outdoor-specialist archetype through targeted product positioning. These three entities anchor the competitive structure, with Reckitt Benckiser representing pharmacy and supermarket shelf-presence strategies, SC Johnson exemplifying DEET-free formulation leadership, and Spectrum Brands occupying the camper-hiker segment specialization.
| Leading Market Players |
|---|
| Dabur India |
| Henkel AG & Co KGaA |
| Reckitt Benckiser Group PLC |
| Sawyer Products |
| Jyothy Laboratories |
| SC Johnson |
| Spectrum Brands Holdings Inc |
| Coghlan's |
| Godrej |
| Others |
Value Chain & Pricing Dynamics
Active ingredient supply concentration in China and India determines both pricing tier spreads and supply chain shape for UK formulators. HSE re-authorization timelines compress product development cycles while feedstock shipping volatility widens margin gaps between premium DEET-Free portfolios and commodity synthetic formulations.
Pricing Analysis
Technology-generation pricing gaps separate legacy DEET formulations from emerging DEET-Free alternatives and next-generation encapsulated delivery systems. Three-tier pricing structure across premium, standard, and economy levels stratifies by active ingredient certification grade and protection duration claims. Cost compression in economy-tier synthetic sprays intensifies because Chinese pyrethroid feedstock prices fluctuate with shipping lane congestion. Parental buyers in suburban England show lowest price sensitivity for pediatric lotions, while agricultural workers in East Anglia prioritize unit economics over formulation sophistication.
Supply Chain Analysis
Upstream feedstock dependencies draw from Chinese pyrethroid manufacturers, Indian DEET chemical processors, and Australian citriodiol plantations. UK formulators rest on Corymbia citriodora leaf oil, synthetic pyrethroid concentrates, and polymer-matrix encapsulation materials as critical inputs. Single-source vulnerability concentrates in Shanghai port processing delays that strand containerized active ingredients for quarters. Distribution runs through Birmingham logistics hubs serving pharmacy chains and supermarket regional distribution centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription replenishment programs represent a service-attach opportunity expanding faster than hardware unit sales. Direct-to-consumer platforms capture recurring revenue through seasonal family replenishment cycles that lock in lifetime value beyond transactional retail purchases.
For Market Incumbents: Insulate pharmacy and supermarket shelf access through exclusive citriodiol supply agreements with Australian plantation operators. Accelerate HSE dossier preparation for picaridin concentration extensions before re-authorization deadlines compress competitor response windows. Backward integration into polymer-matrix encapsulation technology preserves margin capture as formulation complexity escalates.
For New Entrants and Emerging Players: Build out Wales and Northern Ireland outdoor retailer partnerships where category development indices trail England by substantial margins. Target camping specialty stores in Snowdonia corridor with technical product education programs that established players under-resource. Pursue direct-to-consumer trial through Amazon subscription boxes before incumbents automate replenishment capture.
For Investors and Strategic Acquirers: HSE substance evaluation timelines reshaping the acquisition landscape favor targets with completed citriodiol dossier approvals over early-stage natural formulation challengers. Long-term viability centers on regulatory affairs depth rather than brand heritage as authorization costs exclude smaller entrants. Watch for HSE-recognized laboratory testing capacity expansion as inflection signal for product launch velocity recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| DEET-Free Formulation Portfolio Expansion | Captures parental buyer preference shift while satisfying HSE biocidal compliance trajectories. |
| Subscription Commerce Platform Launch | Locks in recurring revenue from suburban family households with predictable seasonal travel patterns. |
| Wales and Northern Ireland Distribution Partnership | Addresses whitespace regions with lower category penetration than England's saturated corridors. |
| Encapsulated Release Technology Investment | Extends protection duration claims while reducing dermal absorption liability for pediatric segments. |
| HSE Dossier Pre-Authorization Investment | Secures market access before re-authorization timelines compress development cycles for laggards. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with HSE regulatory affairs consultants, biocidal product formulators, pharmacy category buyers, and outdoor retailer purchasing managers; and secondary validation through Health and Safety Executive substance evaluation databases, Public Health England vector surveillance reports, UK customs import records, and supermarket seasonal promotional calendars. Bottom-up triangulation against manufacturer shipment estimates and top-down reconciliation with retail audit data anchored volume and value assessments.
Forecast inputs considered product type segmentation across sprays, lotions, wipes, and gels alongside formulation chemistry tiers and distribution channel dynamics across the analysis window. End-user behavioral patterns for families, travelers, outdoorsmen, and campers shaped adoption curve modeling. CAGRs derived from historical growth rate regression adjusted for regulatory inflection points and vector risk map expansion.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese feedstock suppliers or Australian plantation consolidators would shift outcomes. Cross-checking against NHS travel clinic prescription volumes and camping equipment retail sales is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global Vinyl Sulfone Market
Specialty Chemicals
Octocrylene Market
Specialty Chemicals
Perfluoropolyether (PFPE) Market
Specialty Chemicals
Food Grade Paraffin Market
Specialty Chemicals
Organic Sulfur Market
Specialty Chemicals
Tetrabromobisphenol a (TBBPA) Market
Specialty Chemicals
Avobenzone Market
Specialty Chemicals
Diisononyl Adipate (DINA) Market
Specialty Chemicals
Allantoin Market
Specialty Chemicals
Catharanthine Market
Specialty Chemicals
Sol-Gel Processing Market
Specialty Chemicals
Dimethyl Silicone Market
Specialty Chemicals
Global Benzoyl Peroxide Market
Specialty Chemicals
Fluoroethylene Carbonate (FEC) Market
Specialty Chemicals
Global Bio Based Esters Market
Specialty Chemicals
Polyglycolic Acid (PGA) Market