
 Non-Commercial Acrylic Paints Market | 2026-2036
Non-Commercial Acrylic Paints Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Commercial Acrylic Paints Market Analytics
Subscription-based color-mixing tutorials and artist community platforms is recalibrating how manufacturers monetize beyond the physical tube. Golden Artist Colors leverages direct-to-consumer education bundles to sustain premium pricing power. Liquitex Artist Materials anchors its position through professional-grade heavy body lines tied to certified instructor networks. Winsor & Newton competes via heritage positioning and controlled distribution through specialized art supply retailers.
Non-commercial acrylic paints comprise water-based emulsions of acrylic polymer resin with pigment loadings typically ranging from 20-45% by volume, formulated for canvas, paper, and mixed-media substrates requiring flexibility and archival stability. Heavy body formulations dominate volume sales among professional artists, while fluid acrylics represent the fastest-expanding category as pour painting and resin art techniques proliferate through social media demonstration. Tube packaging commands the highest margin pool due to perceived freshness and precise color matching, though pouch formats gain traction in educational bulk purchasing.
ASTM D4236 labeling requirements in the United States and REACH substance restrictions in Europe govern pigment safety disclosures and volatile compound limits, directly influencing R&D allocation toward cadmium-free and cobalt-alternative chemistries. Japan's JIS standards for art materials add a third compliance layer for exporters targeting East Asian premium channels. Stakeholders must monitor evolving chemical substitution mandates and digital-native competitor entry through private-label marketplace positioning.
Market Dynamics
Digital-native education platforms are fragmenting traditional distribution hierarchies for non-commercial acrylic paints, forcing manufacturers to build direct engagement infrastructure or surrender margin to marketplace intermediaries.
Growth Catalysts
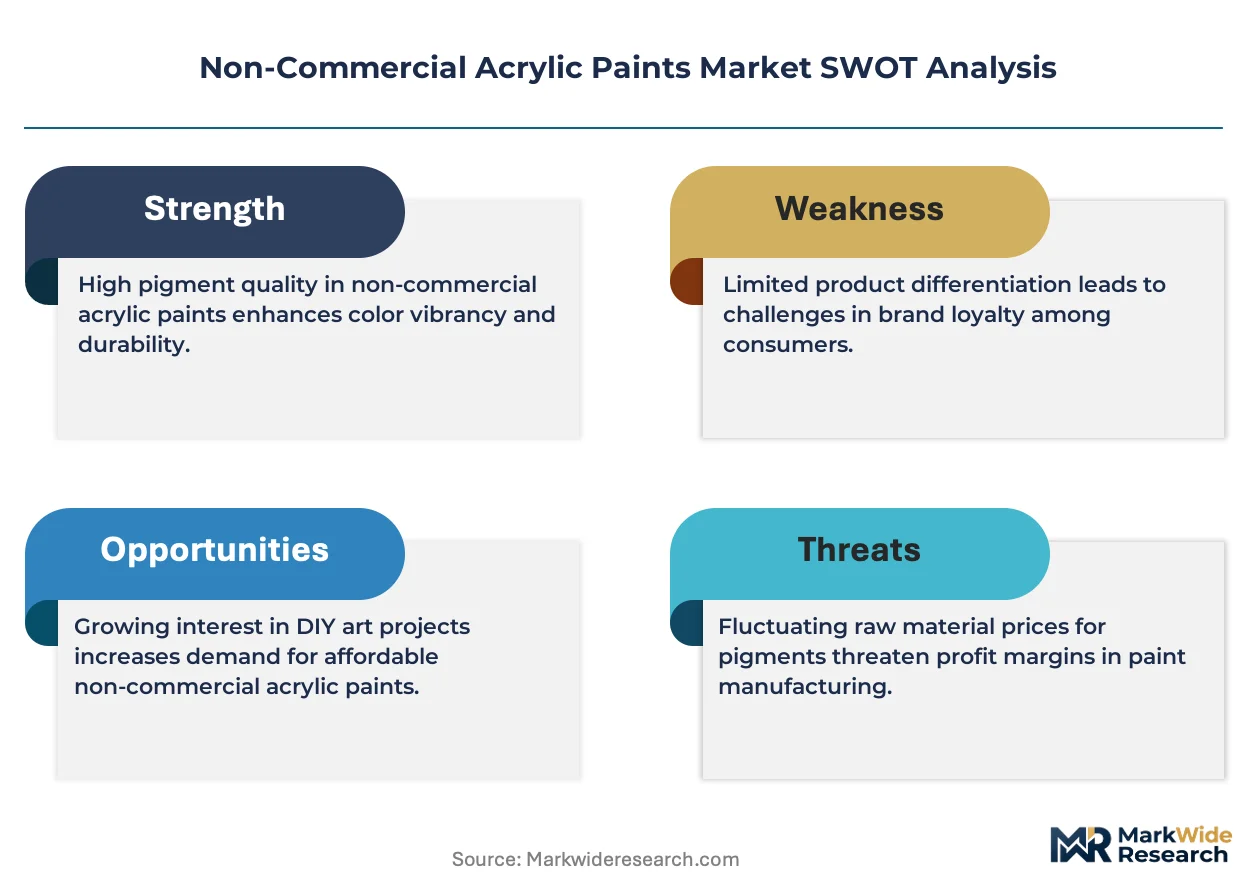
- REACH cadmium substitution mandates:ECHA restrictions on heavy metal pigments accelerate R&D investment into mineral-composite alternatives, opening premium positioning for compliant European suppliers.
- Pour painting technique proliferation:Social media demonstration channels drive fluid acrylic consumption among hobbyist segments, compressing traditional heavy body dominance in volume terms.
- Japan's JIS art material standards:Rigorous certification requirements for archival stability create import barriers that protect domestic premium manufacturers while rewarding compliant foreign exporters.
Market Restraints
- Titanium dioxide supply concentration:Chinese producers control critical white pigment feedstock, exposing formulators to input cost volatility and forced substitution to calcium carbonate extenders.
- ASTM D4236 labeling friction:US toxicity disclosure requirements impose batch-level testing costs that disproportionately burden small-batch artisan producers versus industrial scale competitors.
- Digital art software substitution:Procreate and Adobe Fresco tablet applications capture student experimentation budgets, compressing trial-size paint purchases in secondary education channels.
Strategic Opportunities
- India studio art infrastructure:BIS certification alignment and private university expansion create import-ready demand for ASTM-equivalent student-grade formulations.
- Resin art hybrid applications:Epoxy-acrylic composite techniques in furniture and jewelry making extend pigment consumption beyond traditional canvas substrates.
- EU Green Deal bio-based targets:Renewable polymer feedstock mandates incentivize acrylic resin producers to develop sugarcane-derived emulsion chemistry for sustainability-positioned brands.
Industry Challenges
- Color matching skill scarcity:Formulation chemists with dual expertise in pigment dispersion and digital colorimetry command premium compensation, constraining mid-tier producer R&D bandwidth.
- Multi-jurisdiction certification timelines:Simultaneous ASTM, REACH, and JIS compliance testing extends product launch cycles by 8-14 months, freezing capital in inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Commercial Acrylic Paints Market |
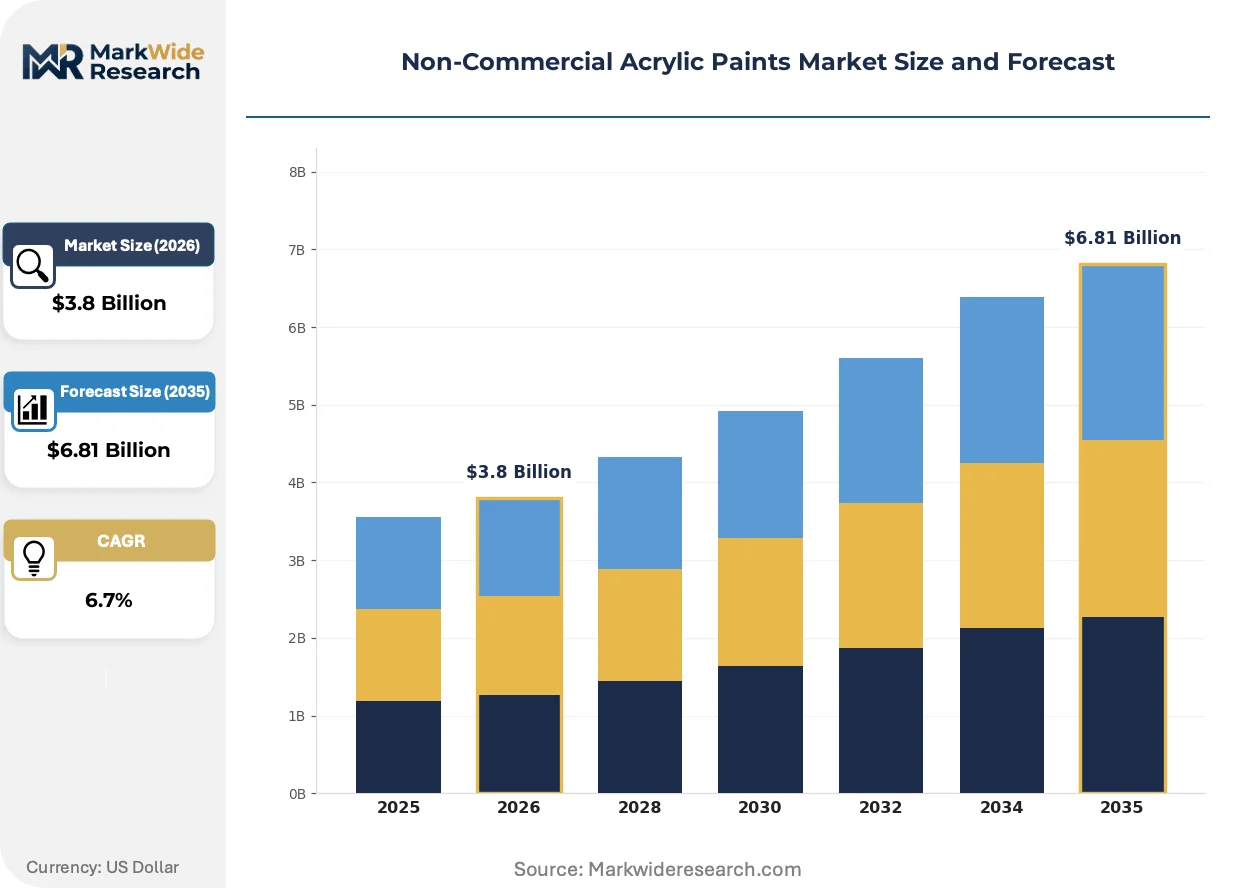
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavy Body, Fluid Acrylics, Soft Body, Acrylic Gouache End User: Artists, Educators, Students, Hobbyists Color Type: Transparent, Opaque, Metallic, Fluorescent Packaging Type: Tubes, Jars, Buckets, Pouches |
| Companies Covered | Golden Artist Colors, Liquitex Artist Materials, Winsor & Newton, Da Vinci Paint Co., Daler-Rowney, Faber-Castell, Koninklijke Royal Talens, Chroma Atelier, Pebeo SAS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Commercial Acrylic Paints Market Evolving Landscape
Formulation science and distribution architecture are undergoing parallel reinvention as manufacturers respond to regulatory chemistry mandates and direct-to-consumer channel economics.
High-performance cadmium-free pigments engineered around bismuth vanadate and pyrrole orange chemistry are expanding into professional artist segments previously resistant to substitution. Winsor & Newton and Golden Artist Colors have accelerated palette conversions, with certified instructor networks validating performance equivalence. This displacement is compressing traditional pigment supplier relationships while elevating compounders with proprietary dispersion expertise.
REACH Annex XVII restrictions on microplastic additives in leave-on products are extending to art material classifications, forcing emulsion manufacturers to eliminate polyethylene-based rheology modifiers. German and French regulators have advanced draft guidance that would reclassify certain acrylic gel mediums. Formulators are responding with associative thickener systems derived from renewable cellulosic sources, though at 15-30% raw material cost premiums.
Subscription-based color-mixing tutorial platforms are capturing recurring revenue streams that previously accrued to brick-and-mortar retailers. Golden Artist Colors and Liquitex have deployed direct-to-consumer education bundles that bundle paint shipments with video instruction, disintermediating traditional art supply distributors. This channel compression is most visible in United States and United Kingdom metropolitan markets where studio rental costs have collapsed independent retailer density.
Non-Commercial Acrylic Paints Market Segmentation
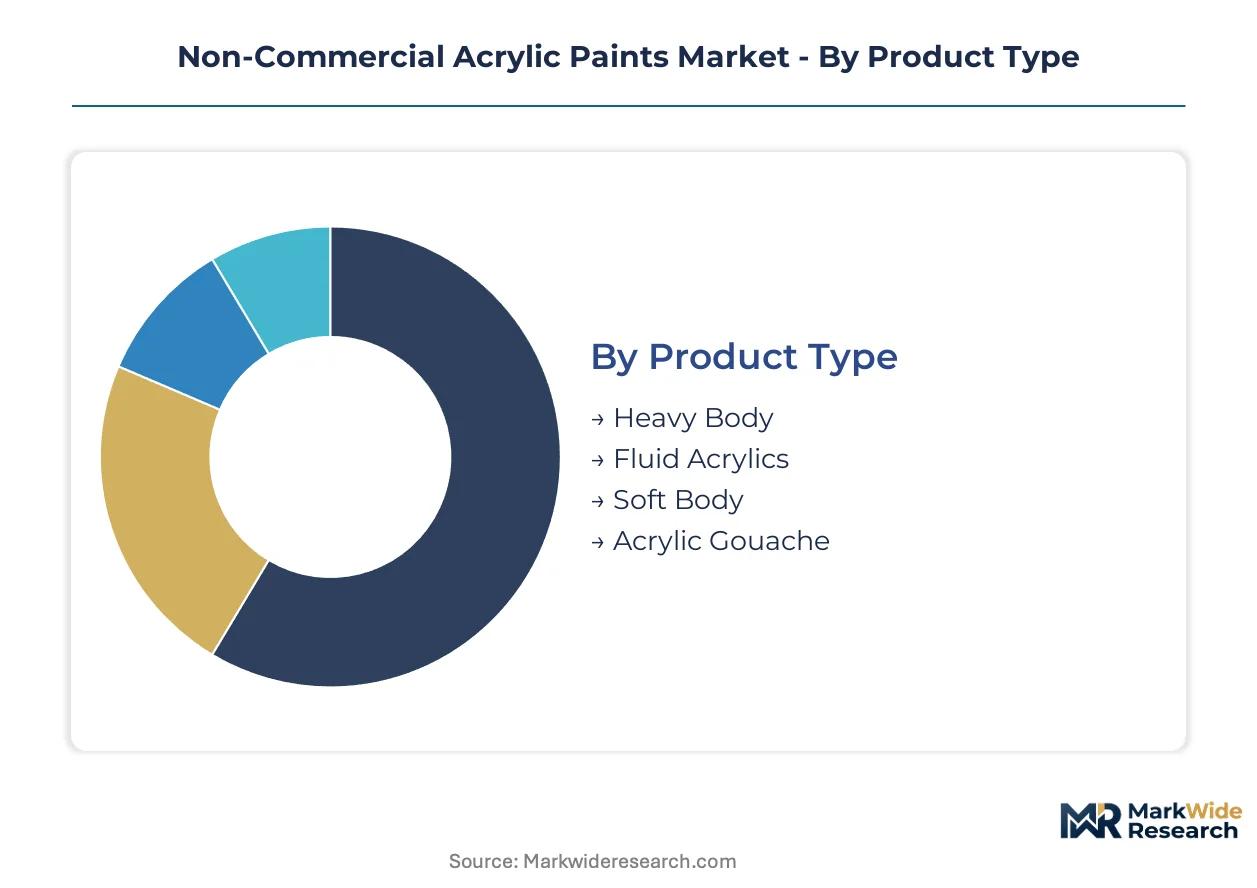
Non-commercial acrylic paints fragment across formulation viscosity, user sophistication, optical properties, and procurement scale. Each dimension carries distinct margin profiles and compliance burdens that reshape manufacturer resource allocation.
Product Type:
Application technique dictates viscosity selection, with body weight directly determining pigment loading and handling characteristics.
- Heavy Body:High-viscosity formulations carry 45-50% pigment by volume, retaining brushstroke texture on canvas. Professional artists in Germany and Japan sustain premium consumption for impasto techniques despite higher per-milliliter cost.
- Fluid Acrylics:Low-viscosity emulsions with 20-30% pigment load enable pour painting and airbrush application. Social media tutorial proliferation in the United States accelerates hobbyist adoption, compressing traditional heavy body volume dominance.
- Soft Body:Medium-viscosity formulations bridge professional control with extended workability. Preferred by educators for classroom demonstrations requiring smooth color blending.
- Acrylic Gouache:Matte-finish, opaque variants emulate traditional gouache with water-resistant film formation. Illustrators and designers in Japan favor JIS-certified archival grades for commercial reproduction work.
Volume sits with Heavy Body; growth tilts toward Fluid Acrylics.
End User:
Skill level and purchase frequency separate one-time student buyers from recurring professional accounts with certified instructor relationships.
- Artists:Professional practitioners demand ASTM D4236-labeled, lightfast-rated pigments with documented archival performance. Direct-to-consumer education bundles now capture loyalty previously held by specialized retailers.
- Educators:Institutional buyers prioritize bulk packaging and non-toxic certification for classroom safety compliance. United States public school procurement runs through cooperative purchasing agreements that favor established supply contracts.
- Students:Price-sensitive beginners purchase starter sets with limited primaries, often migrating to professional grades within 18-24 months of skill development.
- Hobbyists:Technique-driven amateurs follow social media trends, driving cyclical demand spikes for specialty formulations like metallics and pouring mediums.
Margin concentrates with Artists; expansion accelerates among Hobbyists.
Color Type:
Optical behavior determines substrate compatibility and layering technique, with transparency ratings governed by ASTM lightfastness standards.
- Transparent:Unpigmented binder allows underlying layers to remain visible, essential for glazing techniques favored by contemporary realist painters.
- Opaque:High-refractive-index pigments including titanium dioxide provide complete coverage, dominating base-layer consumption across all user segments.
- Metallic:Mica-flake and aluminum-powder suspensions create reflective surfaces for decorative and craft applications, with REACH compliance restricting certain heavy metal variants.
- Fluorescent:Optical brightener chemistry produces vivid daylight effects with poor lightfastness ratings, limiting use to temporary installations and student experimentation.
Consumption clusters around Opaque; Metallic gains fastest on resin-art crossover demand.
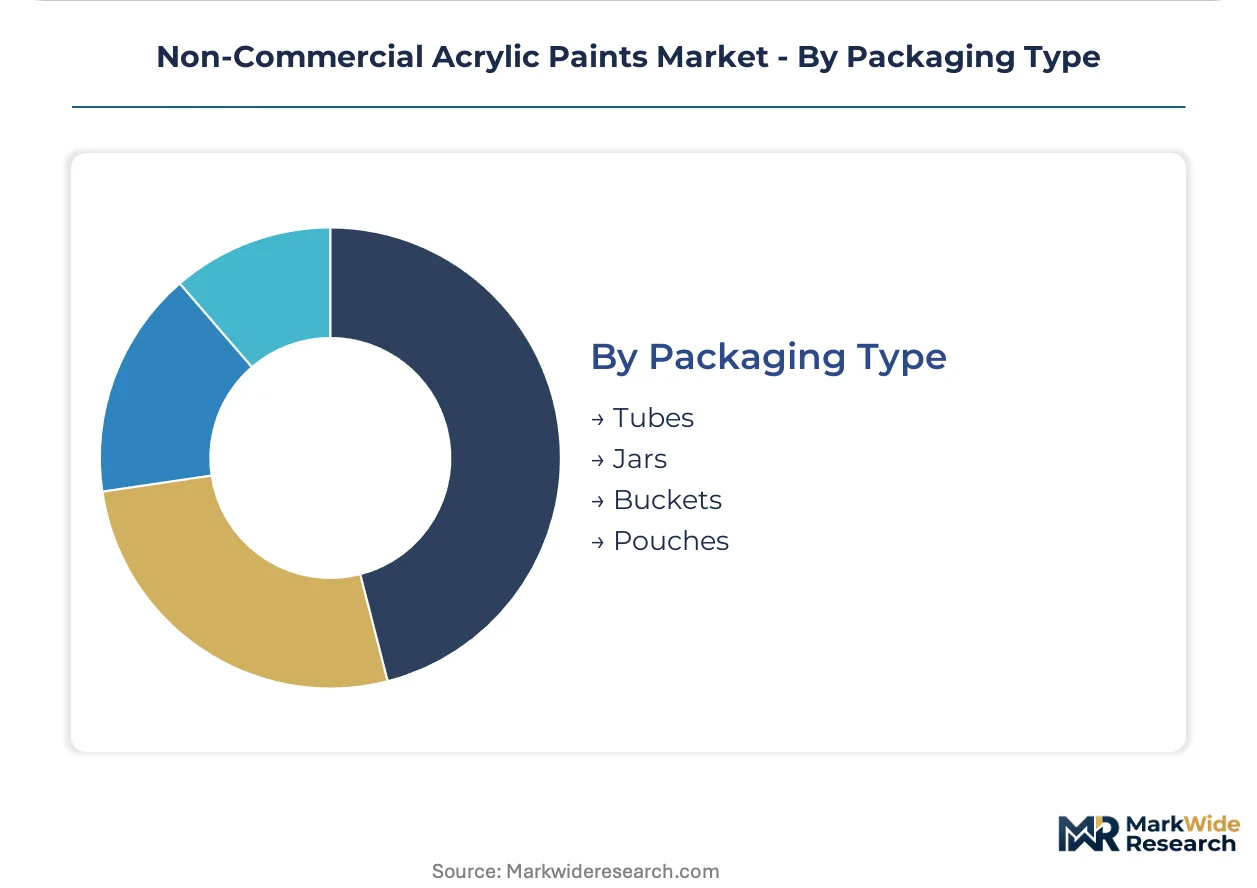
Packaging Type:
Container format signals freshness, controls unit economics, and determines retail channel placement from boutique studios to educational distributors.
- Tubes:Aluminum or laminated tubes with screw caps preserve viscosity and enable precise color matching. Command highest per-milliliter margins in professional channels due to perceived quality assurance.
- Jars:Wide-mouth containers accommodate heavy body and gel formulations requiring palette-knife access. Preferred by muralists and mixed-media practitioners for volume efficiency.
- Buckets:Industrial-scale packaging serves institutional buyers and workshop settings, with ASTM batch certification extending to largest container sizes.
- Pouches:Flexible laminate packaging reduces shipping cube and material cost, gaining traction in European educational bulk purchasing through sustainability positioning.
Margin pools in Tubes; Pouches climb fastest on logistics cost reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of acrylic polymer resins concentrates in China and Germany, while consumption clusters in markets with established studio art education and maker culture infrastructure. This geographic split creates distinct competitive dynamics for formulators and distributors.
United States
Professional artist communities in Brooklyn, Los Angeles, and Chicago sustain premium heavy body consumption through certified instructor networks. ASTM D4236 labeling requirements govern toxicity disclosure for classroom safety compliance. Golden Artist Colors anchors direct-to-consumer education bundles from its New York manufacturing base, capturing loyalty previously held by specialized retailers.
Germany
Impasto technique practitioners in Berlin and Munich drive high-viscosity formulation demand despite elevated per-milliliter costs. ECHA cadmium substitution mandates accelerate R&D investment into mineral-composite alternatives, opening premium positioning for compliant domestic suppliers. Stuttgart-area compounders develop proprietary dispersion expertise for bismuth vanadate chemistry.
Japan
Illustrators and designers in Tokyo and Osaka favor JIS-certified archival grades for commercial reproduction work. METI enforces rigorous certification requirements for lightfastness ratings that create import barriers protecting domestic premium manufacturers. Osaka-based producers supply acrylic gouache variants meeting hybrid water-resistant film specifications.
India
Private university expansion in Maharashtra and Karnataka generates import-ready demand for ASTM-equivalent student-grade formulations. BIS certification alignment proceeds slowly, favoring early movers with documented compliance pathways. Mumbai art supply distributors report accelerating pouch format adoption for educational bulk purchasing.
United Kingdom
Pour painting technique adoption in London and Manchester compresses traditional heavy body volume dominance among hobbyist segments. REACH Annex XVII restrictions on microplastic additives extend to art material classifications, forcing reformulation of gel mediums. Winsor & Newton leverages heritage positioning through controlled distribution in specialized Mayfair retailers.
Non-Commercial Acrylic Paints Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across formulation and distribution. The vendor base fragments between integrated resin compounders, pigment specialists, and education-platform bundlers. Three archetypes dominate: heritage European houses with archive positioning, North American direct-to-consumer educators, and Asia-Pacific contract manufacturers serving private-label marketplaces. Competitive moves concentrate on certified instructor network expansion and cadmium-free palette conversion.
Within the heritage tier, Winsor & Newton and Daler-Rowney exemplify archive-anchored positioning through controlled specialty retail distribution. Golden Artist Colors occupies a position as the direct-to-consumer education archetype, bundling physical product with video instruction to disintermediate traditional art supply channels. These three companies represent contrasting responses to digital-native platform fragmentation.
| Leading Market Players |
|---|
| Golden Artist Colors |
| Liquitex Artist Materials |
| Winsor & Newton |
| Da Vinci Paint Co. |
| Daler-Rowney |
| Faber-Castell |
| Koninklijke Royal Talens |
| Chroma Atelier |
| Pebeo SAS |
| Others |
Value Network & Pricing Analysis
REACH Annex XVII cadmium substitution mandates gate qualified supply for premium-tier pricing access, forcing formulators to absorb R&D premiums for compliant mineral-composite alternatives while tiering price positions around certification status. This regulatory filter concentrates margin capture among European compounders with proprietary bismuth vanadate dispersion expertise.
Pricing Analysis
Margin tightening in professional-grade heavy body lines reflects titanium dioxide feedstock volatility from Chinese producer concentration. Three-tier pricing structure across premium, standard, and economy levels separates ASTM D4236-certified archival grades from student formulations and private-label alternatives. Cost-down pressure on economy tiers accelerates because pouch format adoption reduces per-unit packaging overhead. Student buyers exhibit highest price sensitivity, while professional artists with certified instructor relationships demonstrate lowest elasticity.
Supply Chain Analysis
Direct-to-consumer education bundles now handle recurring artist demand, disintermediating traditional art supply distributors. Acrylic polymer resin production concentrates in China and Germany, with pigment dispersion compounding anchored in Stuttgart-area facilities and Osaka-based JIS-certified operations. Raw material dependencies center on titanium dioxide, bismuth vanadate alternatives, and sugarcane-derived bio-based emulsions. Single-source vulnerability in Chinese white pigment feedstock exposes formulators to forced substitution toward calcium carbonate extenders. Distribution runs through specialized art supply retailers for heritage brands and marketplace platforms for private-label entrants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into proprietary pigment dispersion capabilities is becoming the decisive upstream lever as REACH-compliant chemistry separates premium positioning from commodity substitution.
For Market Incumbents: Lock in certified instructor networks to defend loyalty against direct-to-consumer education bundlers. Secure backward integration into mineral-composite pigment compounding to offset cadmium substitution cost premiums and protect margin structure from REACH-driven reformulation cycles. For New Entrants and Emerging Players: Launch via private-label marketplace positioning targeting price-sensitive student segments with ASTM-equivalent formulations. Exploit BIS certification alignment delays in India to establish import-ready supply relationships before domestic compounders achieve compliance equivalence. For Investors and Strategic Acquirers: JIS certification expansion by foreign exporters is the leading indicator that Japan's import barrier premium is eroding, signaling consolidation opportunity. Target dispersion-technology specialists with dual expertise in pigment chemistry and digital colorimetry. Monitor ECHA draft guidance on microplastic reclassification for early signals of gel medium reformulation disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Cadmium-Free Palette Conversion | REACH compliance validates premium positioning for bismuth vanadate compounders against heritage pigment suppliers. |
| Direct-to-Consumer Education Bundling | Subscription platforms capture recurring revenue previously accruing to brick-and-mortar art supply distributors. |
| Bio-Based Emulsion Development | EU Green Deal targets incentivize sugarcane-derived polymer chemistry for sustainability-positioned brand differentiation. |
| JIS Certification Investment | METI archival standards create protected premium channels in Tokyo-Osaka illustrator markets. |
| Pouch Format Logistics Expansion | Flexible laminate packaging reduces shipping cube for European educational bulk purchasing contracts. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving formulation chemists, art supply procurement managers, certified instructor network coordinators, and regulatory compliance officers. Secondary sources included ECHA restriction proposals, ASTM D4236 labeling databases, JIS standard certification registries, and import-export documentation from German and Japanese customs authorities. Bottom-up demand modeling triangulated against top-down resin production estimates.
Data-stream reconciliation across formulation viscosity tiers, end-user sophistication levels, color optical properties, and packaging formats enabled segment-level projection construction. CAGRs derived from regression analysis of historical consumption patterns against e-learning platform enrollment trajectories and social media technique adoption curves. Industry-specific inputs incorporated cadmium substitution timelines and bio-based polymer feedstock availability curves.
REACH enforcement acceleration, titanium dioxide supply disruption, and digital art software substitution are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions around regulatory compliance timelines and pigment R&D progression. Practitioners should monitor ECHA draft guidance evolution and BIS certification alignment progress for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Silver Iodide Market
Specialty Chemicals
2-(2,2,2-Trifluoroethoxy)-1,3,2-Dioxaphospholane-2-Oxide Market
Specialty Chemicals
Perms and Relaxants Market
Specialty Chemicals
Insoluble Fibers Market
Specialty Chemicals
Keratin Products Market
Specialty Chemicals
Asia Pacific Methyl Glucose Market
Specialty Chemicals
Fabric Softener and Conditioner Market
Specialty Chemicals
Global Specialty Resins Market
Specialty Chemicals
Security Ink Market
Specialty Chemicals
Hyaluronic Acid Market
Specialty Chemicals
Organo-Modified Siloxanes Market
Specialty Chemicals
Phenoxycycloposphazene Market
Specialty Chemicals
Eitelite Market
Specialty Chemicals
Marine Hyaluronic Acid Market
Specialty Chemicals
Global Benzoyl Peroxide Market
Specialty Chemicals
Global Mannosylerythritol Lipids Market