
 Perfluoropolyether (PFPE) Market | 2026-2036
Perfluoropolyether (PFPE) Market Size, Share, and Industry Trends Forecast 2026-2036
Perfluoropolyether (PFPE) Market Analytics
The gap between aerospace-grade PFPE formulations and general industrial lubricants is realigning procurement patterns across buyer categories. Solvay SA dominates ultra-high vacuum applications through captive synthesis of low molecular weight grades. DuPont leverages backward integration into tetrafluoroethylene feedstock to sustain margin pools in North American electronics channels. Klüber Lubrication specializes in application-specific blends that command specification control at major European automotive OEMs.
Perfluoropolyether denotes a fully fluorinated polyether polymer with carbon-fluorine backbone bonds yielding thermal stability above 300°C and complete chemical inertness. Manufacturers synthesize PFPE through photo-oxidation of hexafluoropropylene or tetrafluoroethylene, then fractionate by molecular weight to match viscosity requirements across vacuum, lubrication, and coating applications. Lubricants anchor the value pool due to irreplaceable performance in semiconductor vacuum pumps and aerospace actuators where hydrocarbon alternatives fail. Electronics end use represents the fastest-expanding demand vector as advanced packaging processes multiply thermal management requirements.
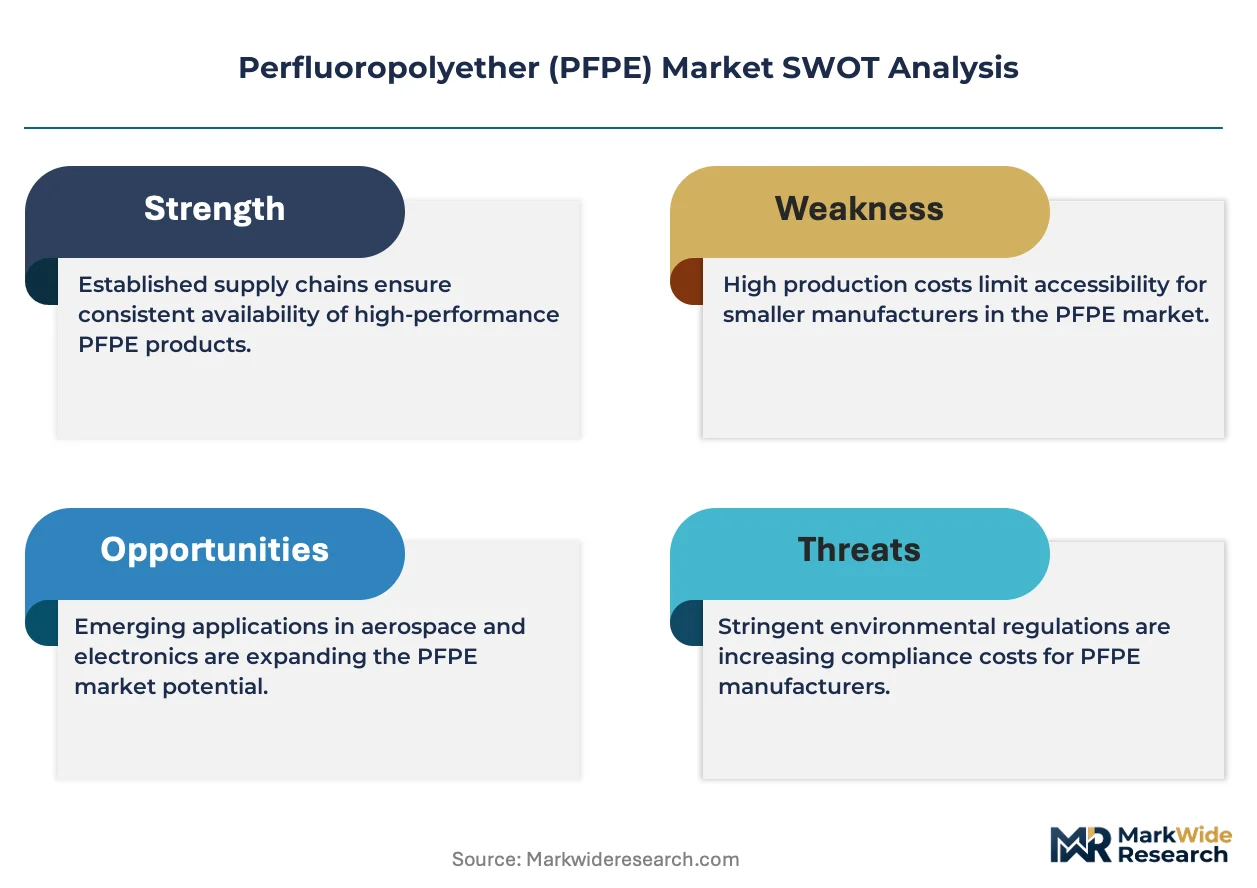
EPA oversight of per- and polyfluoroalkyl substances under TSCA Section 5 is tightening pre-manufacture notification requirements for new fluorinated chemistries, while REACH Annex XVII restrictions on persistent organic pollutants filter PFPE grades permitted in European medical devices. FDA device lubrication standards further shape healthcare segment access through biocompatibility testing protocols. Stakeholders must monitor evolving fluoropolymer regulatory thresholds to anticipate reformulation mandates before supply contract renewals.
Market Dynamics
Semiconductor fabrication node shrinkage below three nanometers is forcing equipment OEMs to specify ultra-high purity PFPE grades with molecular weight distributions tighter than legacy tolerances, compressing supplier qualification timelines and fragmenting procurement across specialty lubricant formulators.
Growth Catalysts
- REACH Annex XVII restrictions:Persistent organic pollutant limits on conventional fluorinated lubricants redirect European specification engineers toward PFPE formulations with lower environmental persistence, accelerating substitution in medical device and automotive applications.
- Advanced packaging thermal management:Heterogeneous integration and chiplet architectures multiply heat flux densities in semiconductor manufacturing, multiplying PFPE deployment in vacuum pump and thermal interface applications.
- Hsinchu Science Park concentration:Taiwan's foundry ecosystem generates concentrated demand for vacuum-grade PFPE lubricants as TSMC and UMC expand three-nanometer wafer processing capacity.
Market Restraints
- Tetrafluoroethylene feedstock volatility:Fluorinated monomer supply concentrates among Chinese and North American chemical producers, exposing formulators to input cost swings and force majeure allocation risks.
- Ultra-high vacuum grade scarcity:Low molecular weight PFPE synthesis requires photo-oxidation equipment with limited installed base, constraining supply elasticity for aerospace and semiconductor OEMs.
- Hydrocarbon lubricant performance gaps:PFPE's irreplaceability in extreme environments eliminates substitution pressure that might otherwise discipline pricing, locking buyers into concentrated supply relationships.
Strategic Opportunities
- India semiconductor manufacturing incentives:PLI scheme subsidies for domestic fab construction create virgin demand territory for vacuum pump lubricant suppliers as Micron and Tata establish assembly and test operations.
- EU F-Gas Regulation phase-down:Hydrofluorocarbon restrictions in cooling applications create regulatory tailwind for PFPE-based heat transfer fluids in data center thermal management systems.
- Solid-state battery dry room applications:Emerging lithium-metal cell manufacturing requires ultra-low humidity environments where PFPE-sealed vacuum systems displace conventional rotary pumps.
Industry Challenges
- Fluoropolymer synthesis talent scarcity:Photo-oxidation process engineering expertise concentrates among retiring chemists at legacy suppliers, constraining capacity expansion and technology transfer.
- FDA biocompatibility certification timelines:Medical device lubricant approvals require 18-24 month validation protocols that delay revenue recognition for healthcare-focused PFPE grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Perfluoropolyether (PFPE) Market |
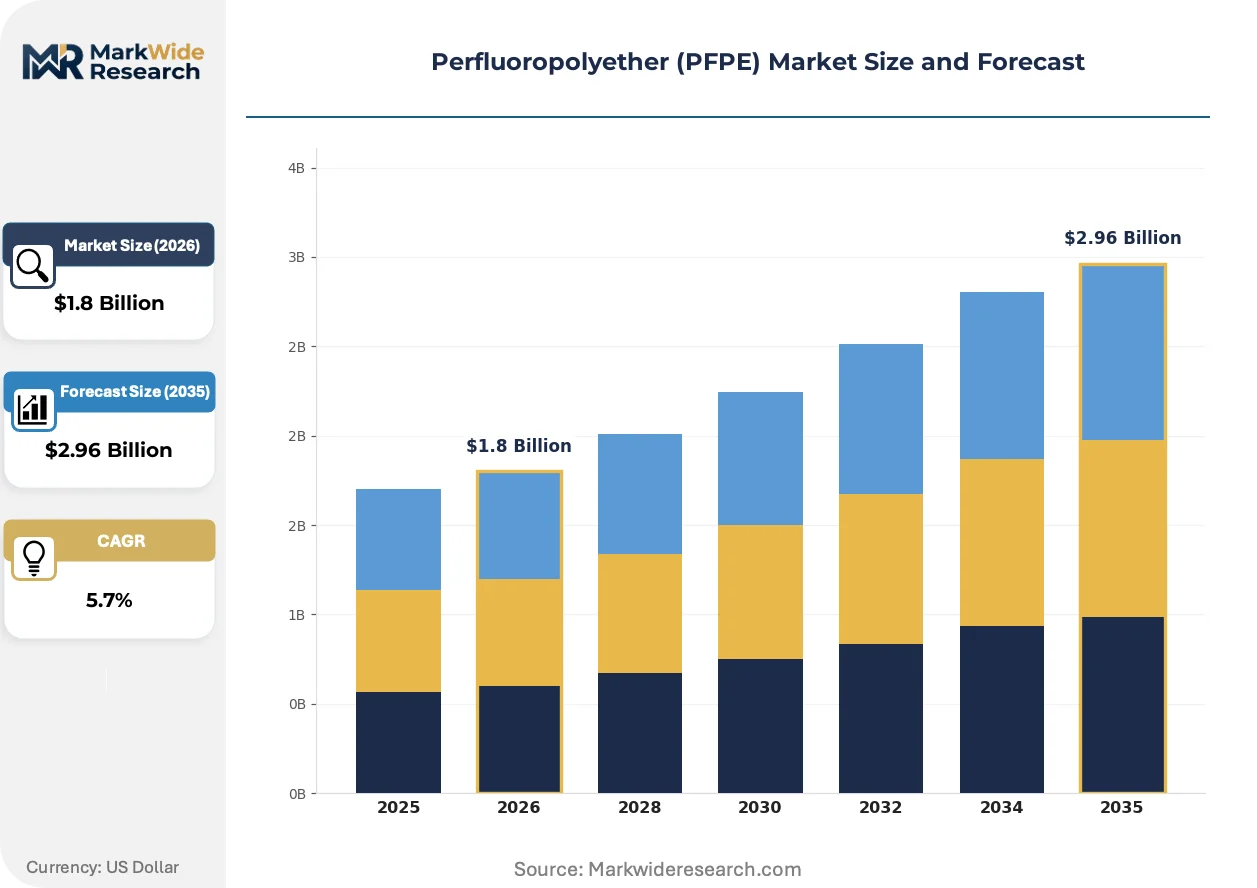
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lubricants, Coatings, Adhesives, Sealants End Use Industry: Aerospace, Automotive, Electronics, Healthcare Form: Liquid, Gel, Solid, Foam Packaging Type: Drums, Containers, Bags, Pails |
| Companies Covered | Klüber Lubrication, M&I Materials Limited, The Chemours Company, Huskey, DuPont, Solvay SA, Nye Lubricants, IKV Group, Daikin Industries Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Perfluoropolyether (PFPE) Market Evolving Landscape
PFPE market evolution centers on molecular architecture precision, regulatory chemistry redesign, and procurement specification tightening as end-users internalize total cost of equipment failure rather than unit lubricant price.
Low molecular weight PFPE fractions with polydispersity indices below 1.2 are expanding into extreme ultraviolet lithography vacuum stages where outgassing tolerances now measure parts per billion. ASML and Nikon lithography tool divisions specify these grades for 0.33 numerical aperture systems. The technology is expanding into adjacent metrology and inspection equipment as contamination budgets tighten across the semiconductor value chain.
ECHA's restriction proposal on per- and polyfluoroalkyl substances under REACH is forcing reformulation of PFPE grades with telomer alcohol impurities above trace thresholds. Medical device and food contact lubricant suppliers face 2026 compliance deadlines for impurity characterization. European OEMs are accelerating qualification of next-generation PFPE grades with certified fluorotelomer-free synthesis pathways.
Specification control is migrating from lubricant distributors to captive engineering teams at major semiconductor foundries. TSMC and Samsung Foundry now issue material qualification standards that override incumbent supplier recommendations. This pattern concentrates most visibly in Pyeongtaek and Hsinchu manufacturing clusters where equipment uptime contracts penalize unapproved lubricant substitution.
Perfluoropolyether (PFPE) Market Segmentation
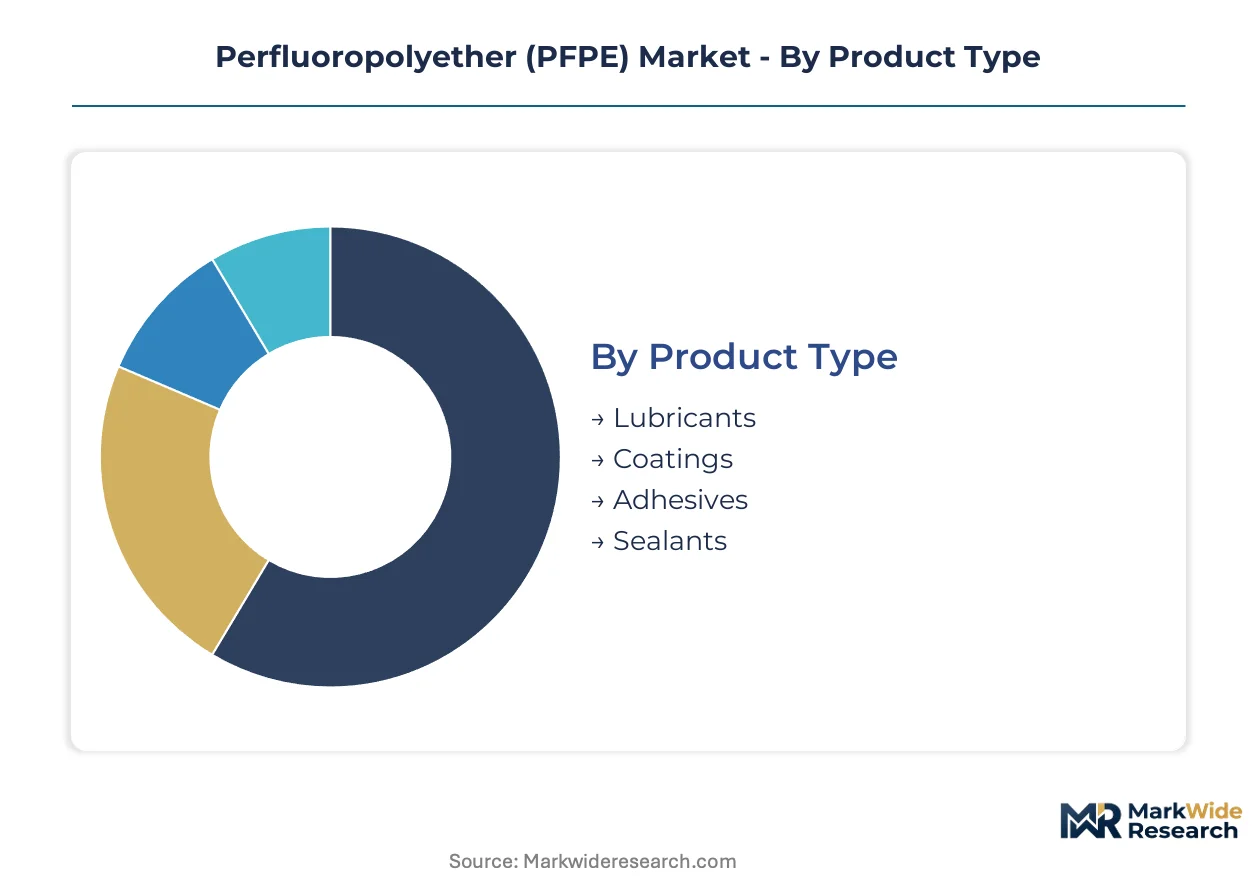
PFPE procurement decisions pivot on performance thresholds rather than cost optimization, with molecular weight distribution and purity grades determining specification control across semiconductor, aerospace, and medical device channels.
Product Type:
Application severity dictates grade selection, with vacuum pressure ratings and thermal load cycles filtering compatible formulations.
- Lubricants:Fully fluorinated polyether chains with carbon-fluorine backbone bonds deliver thermal stability above 300°C and complete chemical inertness. Vacuum pump OEMs at TSMC's Hsinchu facilities specify ultra-high purity grades with molecular weight distributions tighter than legacy tolerances for EUV lithography stages.
- Coatings:Thin-film PFPE formulations deposit through plasma-enhanced chemical vapor deposition to create hydrophobic barrier layers. Aerospace component manufacturers in Toulouse and Hamburg apply these coatings to actuator mechanisms requiring friction reduction across temperature extremes.
- Adhesives:Functionalized PFPE oligomers with terminal reactive groups bond fluoropolymer substrates where hydrocarbon adhesives fail.
- Sealants:High-viscosity PFPE greases with PTFE thickener packages maintain seal integrity in static and dynamic gasket applications.
Volume sits with lubricants; growth tilts toward coatings.
End Use Industry:
Regulatory certification requirements fragment supplier qualification timelines across buyer categories.
- Electronics:Heterogeneous integration and chiplet architectures multiply heat flux densities in semiconductor manufacturing, multiplying PFPE deployment in vacuum pump and thermal interface applications at Samsung Foundry's Pyeongtaek complex.
- Aerospace:Ultra-high vacuum grades with polydispersity indices below 1.2 serve satellite propulsion systems and aircraft actuator mechanisms where outgassing tolerances measure parts per billion.
- Automotive:Electric vehicle thermal management systems adopt PFPE heat transfer fluids as EU F-Gas Regulation phase-down restricts hydrofluorocarbon alternatives.
- Healthcare:FDA device lubrication standards shape segment access through 18-24 month biocompatibility testing protocols for medical device grades.
Electronics commands current procurement volume; healthcare presents the steepest expansion trajectory.
Form:
Physical state determines application methodology and equipment compatibility.
- Liquid:Low-viscosity PFPE fluids with narrow molecular weight fractions flow through precision dispensing systems for vacuum pump lubrication.
- Gel:Thickened PFPE formulations with inert fillers maintain position on vertical surfaces and under vibration loads.
- Solid:Polymerized PFPE resins provide structural components for seals and bearings in cryogenic environments.
- Foam:Expanded PFPE structures deliver thermal insulation with chemical resistance for specialized aerospace applications.
Liquid forms dominate unit volume; gel formulations gain share in vibration-intensive installations.
Packaging Type:
Contamination control requirements elevate packaging specifications for semiconductor-grade material.
- Drums:Stainless steel drums with nitrogen blanket systems preserve ultra-high purity PFPE during transport to foundry facilities.
- Containers:Fluoropolymer-lined vessels prevent metal ion leaching for medical device and electronics applications.
- Bags:Flexible fluorinated film packaging reduces residual waste for high-frequency dispensing operations.
- Pails:Molded fluoropolymer pails serve maintenance lubrication programs at automotive and aerospace MRO facilities.
Drums anchor semiconductor channel supply; containers expand fastest in healthcare certification programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park concentrates the most intensive PFPE procurement activity worldwide, with TSMC's three-nanometer wafer processing expansion driving vacuum-grade lubricant demand at volumes unmatched elsewhere.
United States
Advanced packaging facilities in Arizona and Texas multiply thermal management requirements for PFPE heat transfer fluids. EPA oversight of per- and polyfluoroalkyl substances under TSCA Section 5 tightens pre-manufacture notification requirements for new fluorinated chemistries. Intel's expansion in Chandler and Samsung's Taylor complex anchor concentrated demand for ultra-high purity grades.
Taiwan
TSMC and UMC expansion below three-nanometer nodes forces equipment OEMs to specify molecular weight distributions tighter than legacy tolerances. The island's national semiconductor strategy prioritizes domestic supply chain resilience for critical materials. Hsinchu Science Park generates the densest cluster of vacuum pump lubricant procurement worldwide.
South Korea
Samsung Foundry and SK Hynix deploy PFPE in EUV lithography vacuum stages and advanced packaging thermal interfaces. The Ministry of Trade, Industry and Energy's K-Semiconductor Belt initiative subsidizes domestic material sourcing. Pyeongtaek's memory and logic fabrication complex concentrates specification control within captive engineering teams.
Japan
Tokyo Electron and Nikon lithography tool divisions specify low polydispersity PFPE grades for 0.33 numerical aperture systems. METI's semiconductor revitalization policy directs investment toward domestic fluoropolymer synthesis capacity. The Kyushu and Tohoku regions host specialized vacuum equipment manufacturers driving grade qualification timelines.
Germany
Automotive OEMs in Stuttgart and Munich adopt PFPE heat transfer fluids as EU F-Gas Regulation phase-down restricts hydrofluorocarbon alternatives. ECHA's restriction proposal on per- and polyfluoroalkyl substances forces reformulation of grades with telomer alcohol impurities above trace thresholds. Bavaria's automotive engineering clusters accelerate qualification of next-generation fluorotelomer-free synthesis pathways.
Perfluoropolyether (PFPE) Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the PFPE value chain, with integrated fluoropolymer manufacturers controlling feedstock access while specialty lubricant formulators capture specification control at end-users. The market structure concentrates among three tiers: captive synthesis operations with backward integration into tetrafluoroethylene feedstock, independent formulators with application-specific blending expertise, and regional distributors serving maintenance channels. Dominant competitive moves include capacity expansion in low molecular weight photo-oxidation equipment and strategic partnerships with semiconductor equipment OEMs for qualification co-development.
Among European integrated producers, Solvay SA and Klüber Lubrication occupy distinct archetype positions—Solvay exemplifying captive synthesis dominance in ultra-high vacuum applications, Klüber representing application-specific blend specification control at major automotive OEMs. DuPont anchors the North American tier through upstream integration into fluorinated monomer supply. These three names illustrate how geographic feedstock access and end-use specialization fragment competitive positioning across the value chain.
| Leading Market Players |
|---|
| Klüber Lubrication |
| M&I Materials Limited |
| The Chemours Company |
| Huskey |
| DuPont |
| Solvay SA |
| Nye Lubricants |
| IKV Group |
| Daikin Industries Ltd |
| Others |
Value Network & Pricing Analysis
Semiconductor equipment OEMs at TSMC's Hsinchu facilities and Samsung's Pyeongtaek complex command pricing leverage through equipment uptime contracts that penalize unapproved lubricant substitution, forcing suppliers toward value-based models tied to vacuum pump performance guarantees rather than per-liter transactional rates.
Pricing Analysis
Equipment uptime guarantees anchor value-based pricing for ultra-high vacuum PFPE grades, with suppliers capturing premium returns linked to wafer throughput preservation rather than material volume. Price differentiation hinges on molecular weight distribution precision and REACH fluorotelomer-free certification tiers. Cost compression in general industrial lubricants intensifies as hydrocarbon alternatives encroach lower-specification applications. Maintenance channel buyers at automotive and aerospace MRO facilities exhibit highest price sensitivity, while semiconductor foundry engineering teams prioritize yield protection over unit cost.
Supply Chain Analysis
Refurbishment flows for photo-oxidation equipment and molecular weight fractionation systems create secondary supply channels for legacy PFPE grades serving less demanding applications. Tetrafluoroethylene feedstock concentrates in Chinese and North American chemical production, with formulators drawing from fluorinated monomer suppliers in both regions. Single-source vulnerability concentrates in low molecular weight synthesis equipment where installed photo-oxidation capacity limits supply elasticity. Distribution runs through direct technical sales teams for semiconductor-grade material and specialized industrial distributors for maintenance lubricant channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into tetrafluoroethylene feedstock and captive photo-oxidation capacity represents the decisive vertical-integration race, with players securing fluorinated monomer supply locking in margin pools unavailable to formulation-only competitors.
For Market Incumbents: Acquire photo-oxidation synthesis assets and low molecular weight fractionation capacity to defend against emerging Asian formulators with government-subsidized feedstock access. Deepen captive supply of fluorotelomer-free grades ahead of ECHA REACH compliance deadlines. Lock in multi-year offtake agreements with TSMC and Samsung Foundry engineering teams to secure specification control. For New Entrants and Emerging Players: Enter via India's PLI-subsidized semiconductor manufacturing incentives, where Micron and Tata fab construction creates virgin demand territory lacking incumbent supplier relationships. Target solid-state battery dry room applications requiring ultra-low humidity vacuum systems. Pursue joint qualification programs with domestic Indian equipment OEMs to bypass established supplier certification timelines. For Investors and Strategic Acquirers: The window for entry favors specialty lubricant formulators with FDA biocompatibility certification and fluorotelomer-free synthesis pathways already validated. Long-term viability centers on molecular architecture precision capabilities rather than commodity scale. Monitor ECHA restriction proposal enforcement timelines and EPA TSCA Section 5 pre-manufacture notification rulings as regulatory inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorinated Monomer Supply | DuPont's captive tetrafluoroethylene production sustains margin pools in North American electronics channels. |
| Capacity Expansion in Low Molecular Weight Photo-Oxidation | Solvay SA's installed base constrains competitor entry into ultra-high vacuum grades for EUV lithography. |
| REACH Fluorotelomer-Free Certification Investment | Klüber Lubrication's medical device qualification timelines create specification control at European automotive OEMs. |
| Long-Term Supply Agreement with Foundry Engineering Teams | TSMC and Samsung Foundry material qualification standards override incumbent distributor recommendations. |
| Joint Venture for India Semiconductor Manufacturing | PLI scheme subsidies for domestic fab construction generate virgin demand territory for vacuum pump lubricant suppliers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across plant managers at fluoropolymer synthesis facilities, procurement leads at semiconductor equipment OEMs, technical R&D directors at specialty lubricant formulators, and maintenance directors at aerospace MRO facilities. SEC 10-K disclosures, ECHA restriction proposal documentation, EPA TSCA Section 5 filings, and Taiwan Semiconductor Industry Association capacity reports provided validation layers. Bottom-up demand modeling triangulated against top-down fluorinated chemical production estimates.
Granularity-level modeling operated at molecular weight grade tier, end-use industry vertical, packaging contamination control specification, and regional semiconductor manufacturing cluster dimensions across the analysis window. CAGRs derived from equipment installation forecasts at advanced packaging facilities and wafer processing node migration timelines. Forecast inputs incorporated EUV lithography vacuum stage deployment rates and solid-state battery dry room construction pipelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt REACH fluorotelomer restriction acceleration or tetrafluoroethylene feedstock allocation disruptions. Forecasts reflect documented assumptions regarding semiconductor capital expenditure continuity and regulatory enforcement timelines. Practitioners should monitor ECHA restriction proposal finalization dates and EPA TSCA Section 5 ruling patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Acesulfame Potassium Market
Specialty Chemicals
Crystal Hard Wax Market
Specialty Chemicals
Polyphosphate Market
Specialty Chemicals
Arginine Market
Specialty Chemicals
Insoluble Fibers Market
Specialty Chemicals
Palm Methyl Ester Derivatives Market
Specialty Chemicals
Immunochemistry Products Market
Specialty Chemicals
Specialty Methacrylate Market
Specialty Chemicals
Methyltrimethoxysilane Market
Specialty Chemicals
Anhydroxylitol Market
Specialty Chemicals
Ytterbium Fluoride Market
Specialty Chemicals
Antioxidant 412S Market
Specialty Chemicals
Global Flame Retardants Market
Specialty Chemicals
Fe EDDHA Market
Specialty Chemicals
Global Metal Chelates Market
Specialty Chemicals
Cholesteryl Isostearate Market