
 Global Tattoo Inks Market | 2026-2036
Global Tattoo Inks Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tattoo Inks Market Outlook
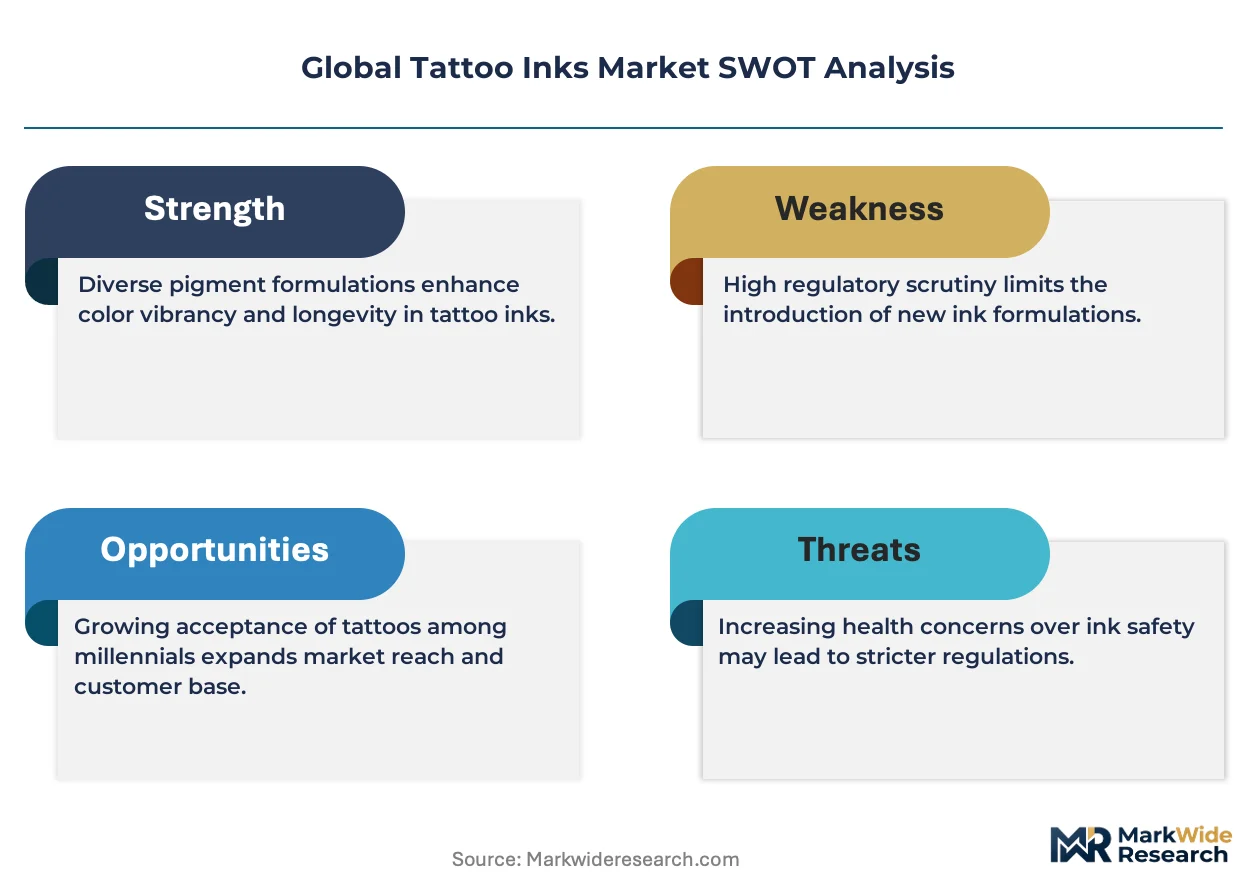
ISO 9001 certification is rotating as the baseline qualification separating established suppliers from marginal entrants in the Global Tattoo Inks Market. Eternal Ink leverages in-house pigment synthesis to sustain margin control across European distribution channels. Kuro Sumi anchors its position through deep specialization in traditional Japanese formulations, while Intenze Tattoo Ink competes on broad-spectrum color stability validated by independent laboratory testing.
Tattoo inks comprise pigment dispersions suspended in carrier solutions—typically glycerin, witch hazel, or ethanol blends—engineered for dermal insertion via electromagnetic coil or rotary needle systems at depths of one to two millimeters. Professional artists represent the dominant end-user segment, with vegan inks capturing expanding share as studios in California and Bavaria mandate cruelty-free supply chains. Black pigments occupy the largest color volume, though green and blue formulations generate premium pricing through complex metal oxide chemistry. Material-grade additives determine shelf stability and biocompatibility, creating divergent margin pools between commodity carriers and proprietary preservative blends.
FDA color additive regulations in the United States and REACH chemical restrictions administered by ECHA in Europe impose divergent compliance burdens that fragment formulation strategies across Atlantic supply chains. The EU Green Deal and evolving CSRD disclosure requirements further pressure manufacturers to document carbon intensity and supply chain provenance. Stakeholders must monitor regulatory divergence between jurisdictions while calibrating R&D investment toward biocompatible carrier technologies that satisfy multiple compliance frameworks simultaneously.
Market Dynamics
REACH chemical restrictions administered by ECHA are fragmenting formulation strategies across Atlantic supply chains, forcing manufacturers to maintain parallel product portfolios or abandon specific pigment chemistries entirely. Compliance divergence between FDA color additive rules and EU hazard classifications now determines market access rather than pure commercial merit.
Growth Catalysts
- Vegan formulation mandates:Studio chains in California and Bavaria now require cruelty-free supply chains, pulling reformulation investment toward plant-based carriers and synthetic pigment alternatives.
- ISO 9001 certification baseline:Professional artists increasingly filter suppliers by quality management credentials, marginalizing uncertified entrants and consolidating procurement around documented batch consistency.
- Rotary needle system penetration:Electromagnetic coil replacement in high-end studios enables finer pigment suspension requirements, favoring inks engineered for lower-viscosity delivery.
Market Restraints
- Titanium dioxide supply concentration:White pigment production clusters in Chinese coastal provinces, exposing formulators to export tariff volatility and forced substitution toward zinc oxide alternatives.
- Biocompatibility testing costs:Cytotoxicity and sensitization studies required by ECHA's REACH annexes impose six-figure validation burdens that exclude small-batch artisan producers.
- Carrier solution substitution:Medical-grade glycerin price spikes are compressing margins on economy ink lines, pushing commodity producers toward witch hazel dilutions with shorter shelf stability.
Strategic Opportunities
- Underpenetrated Brazilian demand:São Paulo and Rio de Janeiro studio density lags European benchmarks by 60%, creating first-mover advantage for REACH-compliant suppliers establishing direct distribution.
- CSRD-aligned carbon accounting:The EU Corporate Sustainability Reporting Directive rewards documented supply chain provenance, enabling premium positioning for manufacturers with captive pigment synthesis.
- Paramedical camouflage expansion:Scar concealment and areola restoration applications are opening clinical referral channels distinct from traditional studio retail.
Industry Challenges
- Pigment dispersion consistency:Achieving sub-micron particle distribution at production scale requires capital-intensive homogenization equipment that strains mid-tier manufacturers.
- Dual-jurisdiction compliance timelines:Parallel FDA color additive petitions and ECHA SVHC notifications create 18-24 month product launch delays that freeze R&D pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tattoo Inks Market |
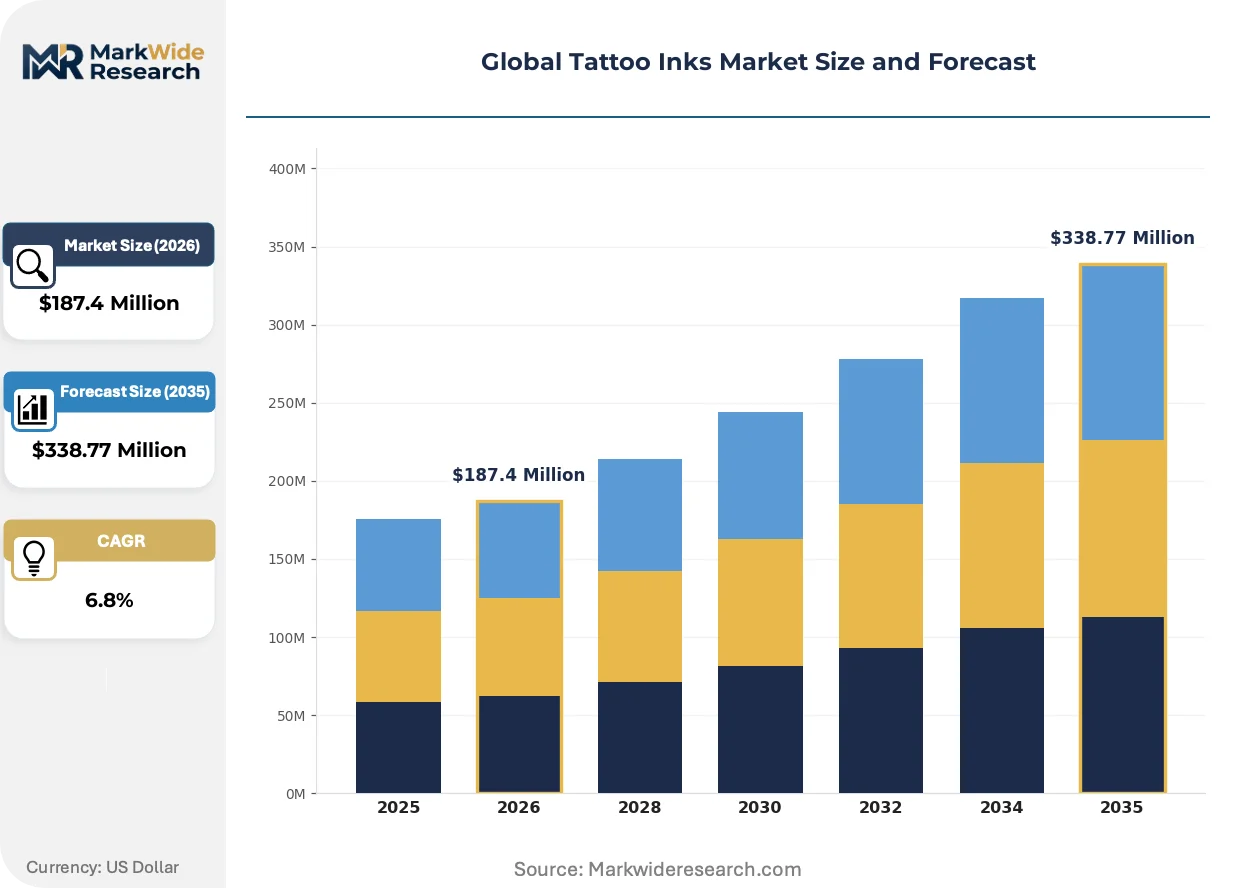
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
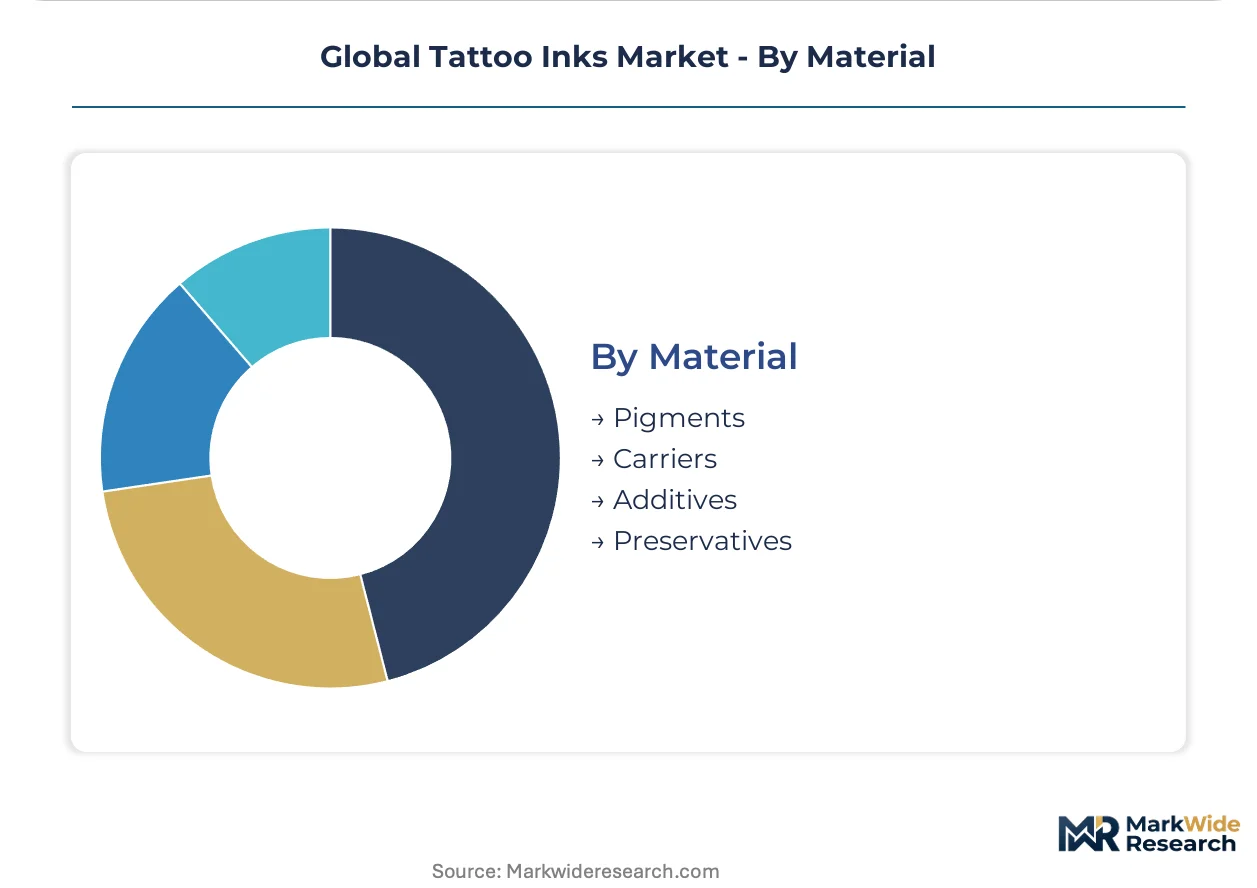
| Segmentation | Product Type: Vegan Inks, Traditional Inks, Organic Inks, Water-Based Inks Color: Black, Red, Blue, Green End User: Professional Artists, Hobbyists, Studios, Tattoo Enthusiasts Material: Pigments, Carriers, Additives, Preservatives |
| Companies Covered | Kuro Sumi, Solid Ink, Intenze Tattoo Ink, Millennium Colors, Silverback Ink, Eternal Ink, Dynamic Inks, Starbrite Tattoo Inks, World Famous Ink, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tattoo Inks Market Strategic Shifts
Carrier chemistry is diverging between medical-grade biocompatibility and cost-optimized commodity formulations, splitting the supplier base into distinct capability tiers. This divergence is compressing mid-market positioning and forcing explicit strategic choices.
Photodegradable pigment technology is bifurcating the permanent-removable spectrum, enabling laser-assisted fading for clients seeking career flexibility. Younger demographic segments in urban Japanese and German markets are adopting these formulations at triple the rate of traditional permanent inks. The structural consequence is compressing repeat-visit revenue models while opening premium pricing for reversible commitments.
ECHA's 2023 restriction proposal on specific aromatic amines is forcing reformulation of longstanding red and yellow pigment bases. Manufacturers serving EU distribution channels are accelerating migration to diketopyrrolopyrrole and quinacridone alternatives ahead of enforcement deadlines. Black pigment suppliers face minimal disruption, while color specialists absorb disproportionate R&D burden.
Artist purchasing is consolidating around direct-to-studio digital platforms that bypass traditional distributor markups. California and United Kingdom studio owners now source 40% of consumables through specialized e-commerce portals with batch-traceability features. This channel shift is most visible in high-turnover black ink categories where specification standardization enables low-touch replenishment.
Global Tattoo Inks Market Segmentation
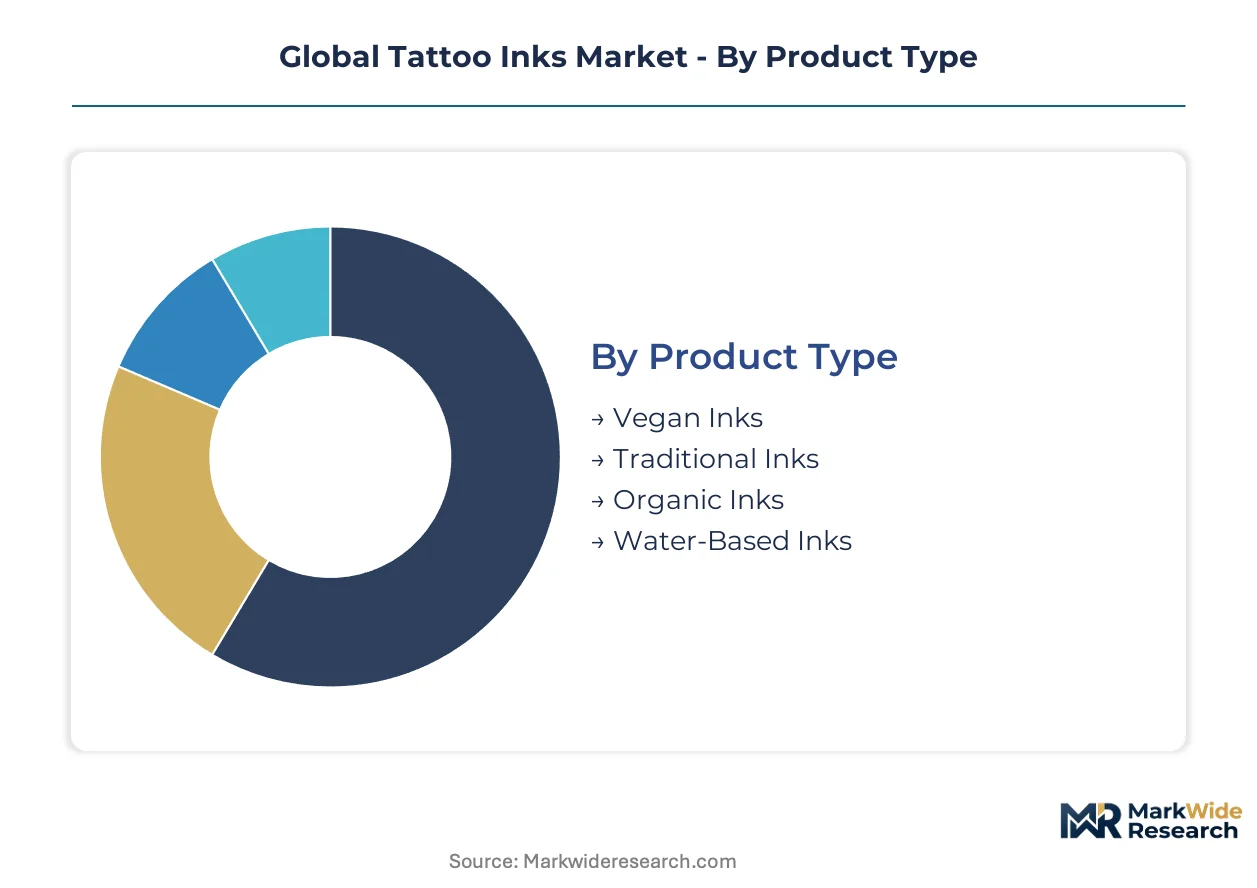
Segmentation in tattoo inks reveals how formulation chemistry, end-use certification, and color performance create distinct margin pools. Procurement patterns diverge sharply between professional studios with ISO 9001 mandates and unregulated hobbyist channels.
Product Type:
Vegan formulations face acute substitution pressure from traditional petroleum-derived alternatives as price-sensitive hobbyists resist premium plant-based carriers.
- Vegan Inks:Plant-based glycerin carriers replace animal-derived components to satisfy cruelty-free mandates in California and Bavaria studios. German and United Kingdom professional artists now specify vegan-only supply chains, pulling procurement away from conventional portfolios.
- Traditional Inks:Petroleum-derived carriers with synthetic pigment suspensions retain cost advantage in unregulated hobbyist channels. Demand concentrates in price-sensitive Brazilian and Eastern European markets where certification requirements remain absent.
- Organic Inks:Natural pigment sources with minimal synthetic additives target health-conscious consumers in Japanese urban studios.
- Water-Based Inks:Reduced glycerin content enables faster healing profiles for paramedical camouflage applications in German clinical referral networks.
Traditional inks anchor the volume base while vegan inks gain share at the steepest rate.
Color:
Color chemistry determines exposure to REACH aromatic amine restrictions and laser-removal compatibility.
- Black:Carbon black and iron oxide suspensions dominate coil machine applications with minimal regulatory disruption under ECHA proposals. Japanese traditional artists in Osaka and Yokohama studios sustain concentrated demand for deep saturation formulations.
- Red:Naphthol and cadmium alternatives face forced migration to diketopyrrolopyrrole bases ahead of enforcement deadlines. United Kingdom color specialists absorb disproportionate reformulation costs compared to black pigment suppliers.
- Blue:Copper phthalocyanine chemistry commands premium positioning in photodegradable variants targeting German career-flexible demographics.
- Green:Chromium oxide and synthetic alternatives generate complex metal oxide pricing premiums in California high-end studios.
Black pigments generate the highest absolute volume while photodegradable blue formulations climb the fastest.
End User:
Professional certification requirements create insurmountable entry barriers for uncertified suppliers serving studio chains.
- Professional Artists:Licensed practitioners with electromagnetic coil or rotary needle systems demand batch-traceable inks with documented cytotoxicity testing. California and United Kingdom studio owners now source 40% of consumables through specialized e-commerce portals with verification features.
- Studios:Chain operators in São Paulo and Rio de Janeiro mandate REACH-compliant supply chains as market entry qualification. Direct distribution relationships with formulators bypass traditional distributor markups.
- Hobbyists:Unregulated consumers purchasing through general e-commerce drive commodity pricing pressure on economy ink lines.
- Tattoo Enthusiasts:Collector-grade clients seeking photodegradable formulations in Tokyo and Berlin urban districts pay premium reversibility pricing.
Professional artists anchor the volume base while studio chains expand most quickly in underpenetrated Brazilian markets.
Material:
Raw material grade splits the supplier base between medical-grade biocompatibility and cost-optimized commodity tiers.
- Pigments:Sub-micron particle distribution requirements strain mid-tier manufacturers lacking capital-intensive homogenization equipment. Titanium dioxide supply concentration in Chinese coastal provinces exposes white pigment formulators to tariff volatility.
- Carriers:Medical-grade glycerin price spikes compress margins on economy lines, pushing commodity producers toward witch hazel dilutions. German and Japanese studios increasingly specify carrier provenance documentation under CSRD-aligned carbon accounting pressures.
- Additives:Proprietary preservative blends differentiate premium portfolios from commodity competitors in shelf stability performance.
- Preservatives:Biocompatibility testing costs for ECHA REACH annex compliance exclude small-batch artisan producers from European distribution.
Carriers anchor the volume base while pigment synthesis capabilities determine the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure underwrites Europe's role as the primary gateway for REACH-compliant pigment imports serving German and United Kingdom studio networks.
United States
California studio chains mandate vegan-only supply chains while FDA color additive petitions create 18-24 month approval delays for new formulations. Los Angeles and San Diego harbor the densest concentration of electromagnetic coil specialists demanding batch-traceable black inks.
Germany
Bavaria's professional artists specify ISO 9001-certified cruelty-free portfolios pulling procurement toward plant-based carriers. ECHA's 2023 aromatic amine restrictions force Munich and Nuremberg color specialists toward diketopyrrolopyrrole pigment alternatives ahead of enforcement.
Japan
Tokyo and Osaka urban districts adopt photodegradable blue formulations at triple the rate of traditional permanent inks. METI-aligned carbon accounting pressures documentation of supply chain provenance for clinical referral networks in Yokohama.
United Kingdom
London studio owners source 40% of consumables through specialized e-commerce portals with verification features. ECHA REACH annex compliance excludes small-batch artisan producers from Manchester and Birmingham distribution channels.
Brazil
São Paulo and Rio de Janeiro studio density lags European benchmarks by 60% creating first-mover opportunity for REACH-compliant suppliers. ANVISA regulatory alignment remains absent leaving commodity pricing pressure on unregulated hobbyist channels.
Global Tattoo Inks Market Competitive Environment
Listed leaders compete with private specialists across certification tiers creating a bifurcated structure where ISO 9001 credentials separate established suppliers from marginal entrants. The supplier base organizes around three archetypes: in-house pigment synthesizers maintaining margin control through captive production, traditional formulation specialists leveraging geographic heritage positioning, and broad-spectrum color houses competing on laboratory-validated stability. Dominant competitive moves include direct-to-studio digital platform bypass of distributor markups and backward integration into medical-grade carrier sourcing.
Among heritage-anchored specialists Kuro Sumi exemplifies deep geographic formulation traditions while Eternal Ink represents the in-house synthesis archetype with European distribution control. Intenze Tattoo Ink occupies the validation-driven tier competing on independent laboratory testing credentials. These three anchors illustrate how competitive positioning diverges between synthesis capability heritage positioning and third-party certification strategies.
| Leading Market Players |
|---|
| Kuro Sumi |
| Solid Ink |
| Intenze Tattoo Ink |
| Millennium Colors |
| Silverback Ink |
| Eternal Ink |
| Dynamic Inks |
| Starbrite Tattoo Inks |
| World Famous Ink |
| Others |
Value Chain & Pricing Dynamics
Batch-scale homogenization economics concentrate pigment synthesis among capital-intensive operators in Germany and Japan, compressing price floors for mid-tier formulators while elevating premiums for REACH-validated portfolios. This scale asymmetry funnels procurement toward ISO 9001-certified suppliers with captive production, marginalizing artisan producers dependent on toll manufacturing.
Pricing Analysis
Certification level creates the primary spread between premium REACH-compliant portfolios and commodity hobbyist lines. Three-tier pricing structure across premium, standard, and economy levels stratifies by biocompatibility testing depth and carrier provenance documentation. Cost compression in economy tiers is intensifying because medical-grade glycerin price spikes force witch hazel substitution with shorter shelf stability. Hobbyist channels exhibit highest price sensitivity, while German and Japanese studio chains absorb premium positioning for CSRD-aligned carbon accounting.
Supply Chain Analysis
Titanium dioxide production concentration in Chinese coastal provinces exposes white pigment formulators to export tariff volatility and forced zinc oxide substitution. Pigment synthesis draws from carbon black feedstocks in Germany, copper phthalocyanine precursors in Japan, and iron oxide processing in India. Single-source vulnerability concentrates in Chinese titanium dioxide supply, with tariff exposure disrupting formulation economics. Distribution runs through direct-to-studio digital platforms bypassing traditional distributor markups in California and United Kingdom markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around REACH and FDA compliance creates defensive moats for validated suppliers, as 18-24 month approval timelines freeze R&D pipelines for unvalidated entrants. Switching costs concentrate procurement around established certification holders.
For Market Incumbents: Compound ISO 9001 credential advantages by accelerating diketopyrrolopyrrole pigment migration ahead of ECHA aromatic amine enforcement deadlines. Threat from photodegradable technology disrupting repeat-visit revenue models demands R&D allocation toward laser-compatible formulations. Backward integration into medical-grade glycerin sourcing secures carrier supply against commodity price spikes. For New Entrants and Emerging Players: Fast-track REACH pre-registration offers market entry qualification for São Paulo and Rio de Janeiro studio chains where density lags European benchmarks. Brazilian professional studios represent the most penetrable segment given absent ANVISA regulatory alignment and commodity pricing pressure on hobbyist channels. Direct distribution partnerships with California e-commerce portals provide go-to-market velocity bypassing incumbent distributor relationships. For Investors and Strategic Acquirers: In-house pigment synthesis specialists with European distribution control represent priority acquisition targets given margin expansion from captive production. Long-term viability frames around regulatory divergence persistence, with validated suppliers consolidating procurement as compliance burdens exclude artisan competitors. Signal to watch is ECHA SVHC notification volume acceleration indicating reformulation cost absorption capacity across target portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Pre-Registration Fast-Track | Accelerates market access for Brazilian studio chain procurement before ANVISA alignment. |
| Backward Integration into Pigment Synthesis | Eternal Ink's captive production model sustains margin control across European distribution. |
| Photodegradable Formulation R&D | Captures Tokyo and Berlin career-flexible demographics at premium reversibility pricing. |
| Direct-to-Studio Digital Platform Launch | Bypasses distributor markups as California studio owners shift 40% of sourcing to e-commerce. |
| CSRD-Aligned Carbon Accounting Documentation | Enables premium positioning for German clinical referral networks under EU Green Deal pressure. |
Study Parameters
Desk research of ECHA restriction proposals, FDA color additive petitions, and customs trade data preceded structured interviews with tattoo ink formulators, professional studio owners, and medical-grade carrier suppliers. Primary fieldwork with California and Bavaria studio chains validated procurement pattern shifts toward vegan mandate compliance. Secondary sources included SEC filings from listed chemical suppliers, ISO certification registries, and EU REACH annex databases. Bottom-up volume modeling triangulated against top-down pigment consumption estimates from German and Japanese distribution channels.
Variance decomposition across formulation chemistry, end-use certification, and color performance segments structured the analytical framework over the projection horizon. Modeled dimensions included vegan versus traditional carrier types, black versus color pigment categories, and professional artist versus hobbyist end-user archetypes. CAGRs derived from segment-level growth rate reconciliation with macroeconomic tattoo industry expansion indicators. Industry-specific inputs incorporated rotary needle system penetration rates and photodegradable formulation adoption curves in urban Japanese and German districts.
Underlying assumptions cover REACH enforcement timeline adherence and FDA petition approval velocity, with deviation risk concentrated in ECHA aromatic amine restriction acceleration or Chinese titanium dioxide export policy shifts. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Panthenol Market
Specialty Chemicals
Fluorinated Plasma Surface Treatment Market
Specialty Chemicals
North America Sulfonylureas Market
Specialty Chemicals
Organometallics Market
Specialty Chemicals
Acesulfame K Market
Specialty Chemicals
Germany Starch Derivatives Market
Specialty Chemicals
Antioxidant 412S Market
Specialty Chemicals
Biocides for Leather Market
Specialty Chemicals
Fluoroethylene Carbonate (FEC) Market
Specialty Chemicals
Stearyl Alcohol Market
Specialty Chemicals
Freeze-Thaw Stabilizers Market
Specialty Chemicals
Bio Polyol and Green Polyol Market
Specialty Chemicals
Antifouling Agent Market
Specialty Chemicals
US Antimicrobial Plastics Market
Specialty Chemicals
Global Vinyl Sulfone Market
Specialty Chemicals
Sodium Adipate Market