
 Pyrrolidone Market | 2026-2036
Pyrrolidone Market Size, Share, and Industry Trends Forecast 2026-2036
Pyrrolidone Market Intelligence
Chemical distributor networks for specialty solvents is fragmenting as regional traders bypass traditional bulk handlers to serve battery and pharmaceutical customers directly. BASF SE leverages its integrated Ludwigshafen complex to sustain captive N-methylpyrrolidone supply for European cathode producers. Mitsubishi Chemical Corporation anchors Asia-Pacific supply through dedicated pharmaceutical-grade lines. Ashland competes in North American coatings channels with tailored N-ethylpyrrolidone formulations.
Pyrrolidones are cyclic amide solvents with a five-membered lactam ring structure, typically manufactured via Reppe synthesis from butyrolactone and ammonia or amines, valued for high polarity, low volatility, and excellent solvency across polar and nonpolar substrates. N-methylpyrrolidone dominates volume due to its entrenched role in lithium-ion battery cathode slurry preparation and semiconductor photoresist stripping, where margin pools concentrate in semiconductor-grade purification. Pharmaceutical applications represent the fastest-expanding segment as pyrrolidone carriers improve bioavailability of poorly soluble APIs in oral and injectable formulations.
EPA oversight governs N-methylpyrrolidone emissions and worker exposure limits in US manufacturing facilities, while REACH registration mandates comprehensive toxicity dossiers for European market access. ECHA's persistent classification discussions for reproductive toxicity are reshaping reformulation priorities among coatings and cleaning product suppliers. Stakeholders must monitor regulatory reclassification timelines and accelerate alternative solvent qualification before supply restrictions tighten product availability.
Market Dynamics
Battery cathode manufacturing in China is concentrating N-methylpyrrolidone demand among a handful of integrated producers, forcing solvent suppliers to co-locate purification capacity near gigafactory clusters or risk margin erosion from logistics costs.
Growth Catalysts
- Lithium-ion cathode slurry processing:N-methylpyrrolidone remains the dominant solvent for polyvinylidene fluoride binder dispersion in nickel-rich cathode formulations.
- REACH RoHS compliance premiums:European electronics manufacturers now specify semiconductor-grade purity thresholds that command price premiums over industrial grades.
- Pharmaceutical solubilization:Pyrrolidone carriers enable oral bioavailability of BCS Class II and IV APIs in oral solid dosage forms.
Market Restraints
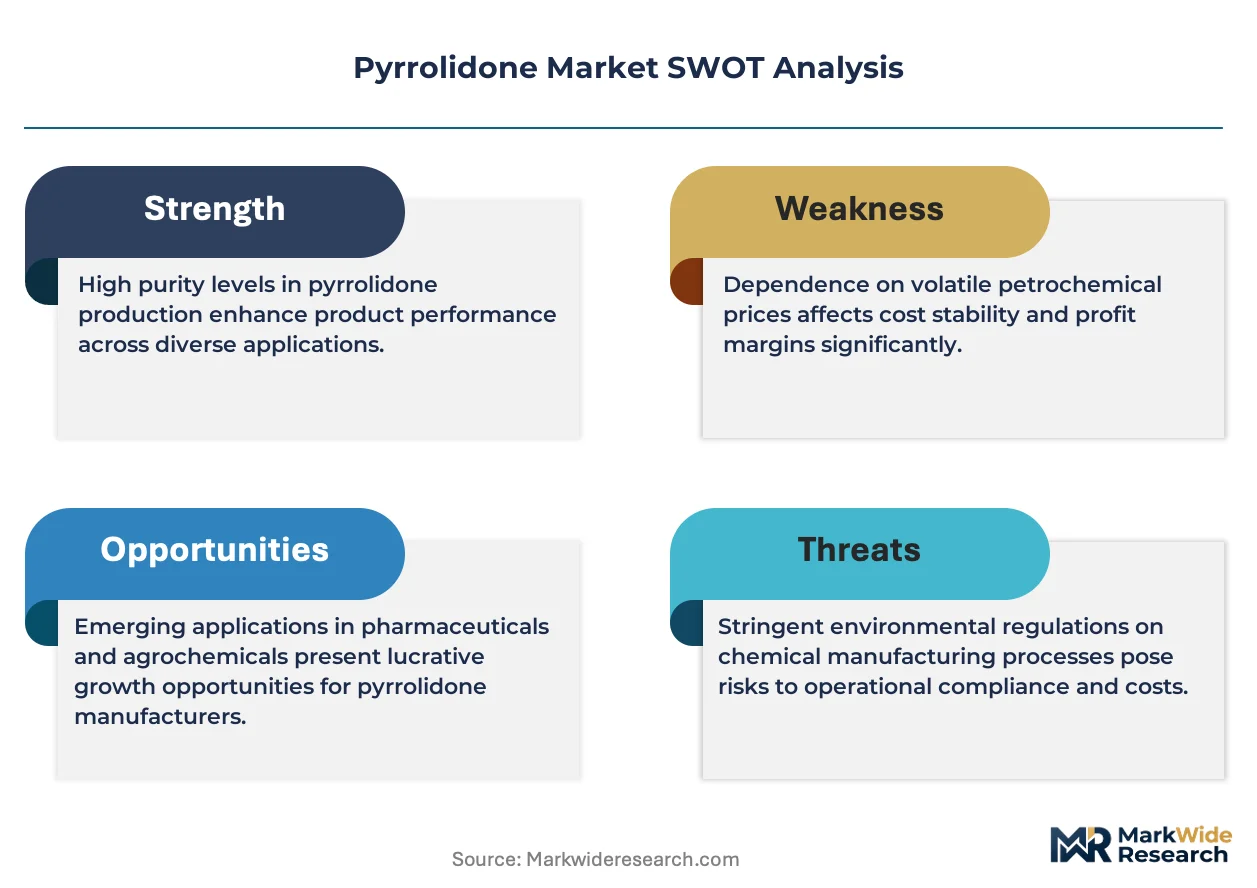
- Butyrolactone feedstock volatility:Reppe synthesis relies on acetylene or 1,4-butanediol derivatives subject to petrochemical price swings.
- China supply concentration:Over sixty percent of battery-grade N-methylpyrrolidone purification capacity sits within Jiangsu and Zhejiang provinces.
- ECHA reproductive toxicity review:Persistent classification discussions threaten downstream use in consumer coatings and industrial cleaning formulations.
Strategic Opportunities
- India battery supply chain localization:Production-linked incentive schemes for cell manufacturing create captive solvent demand as domestic cathode plants scale.
- Biopharma injectable formulations:Pyrrolidone co-solvent systems enable high-concentration antibody subcutaneous delivery formats.
- Green hydrogen electrolyzer membranes:N-vinylpyrrolidone copolymers serve as binder materials for proton exchange membrane electrode assemblies.
Industry Challenges
- Semiconductor-grade certification timelines:Achieving parts-per-billion metal ion specifications requires twelve to eighteen months of process validation with foundry customers.
- Multipurpose plant reconfiguration:Switching between pharmaceutical and electronics grades demands complete cleaning validation and analytical requalification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pyrrolidone Market |
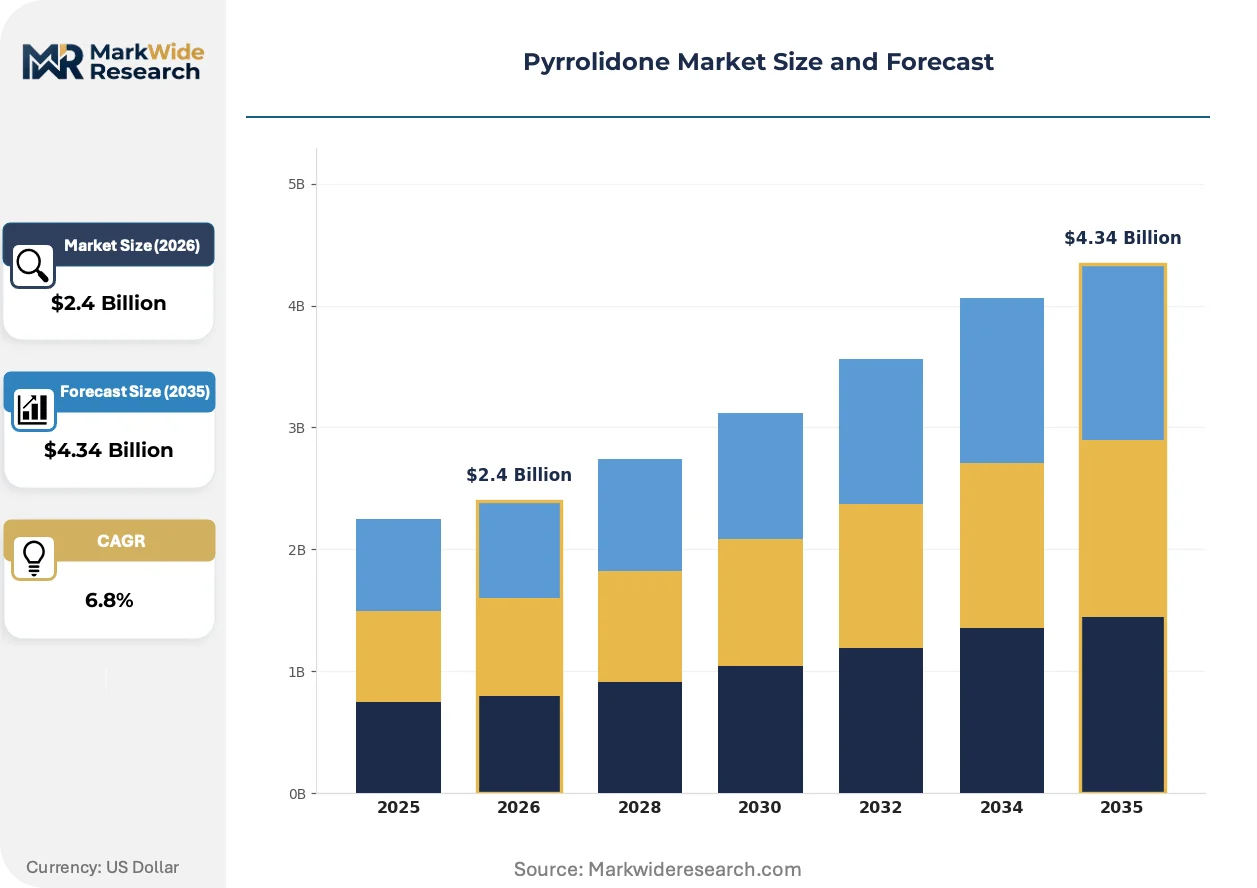
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: N-Methylpyrrolidone, N-Ethylpyrrolidone, N-Butylpyrrolidone, N-Octylpyrrolidone Application: Pharmaceuticals, Agriculture, Coatings, Cleaning Products End User: Healthcare, Chemical Industry, Personal Care, Automotive Form: Liquid, Powder, Granule, Solution |
| Companies Covered | BASF SE, Mitsubishi Chemical Corporation, Eastman Chemical Company, Ashland, LyondellBasell Industries, Johnson Matthey, Solvay, Merck KGaA, Arkema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pyrrolidone Market Strategic Shifts & Innovations
Reformulation pressures from reproductive toxicity scrutiny are accelerating solvent substitution research while battery chemistry evolution creates parallel demand for higher-purity grades.
Membrane-based purification systems are replacing traditional distillation trains for semiconductor-grade N-methylpyrrolidone production. Korean and Taiwanese foundry suppliers now specify nanofiltration-polishing hybrid processes to achieve sub-ppb sodium and potassium levels. This shift is rendering obsolete legacy multi-column distillation investments that cannot economically reach equivalent purity thresholds.
ECHA's ongoing assessment of N-methylpyrrolidone under REACH substance evaluation is forcing coatings formulators to pre-qualify alternative solvents. Industrial cleaning product manufacturers face the most immediate compliance deadlines as consumer exposure scenarios trigger stricter risk management measures. German and Dutch regulatory authorities are coordinating transitional authorization timelines that favor professional-use exemptions over retail applications.
Direct procurement relationships between cathode producers and solvent manufacturers are displacing traditional chemical distributor networks. Battery material companies in China and South Korea now negotiate multi-year tolling agreements with integrated pyrrolidone producers. This channel consolidation is most advanced in the Yangtze River Delta, where regional traders have lost significant share to captive supply arrangements.
Pyrrolidone Market Segmentation
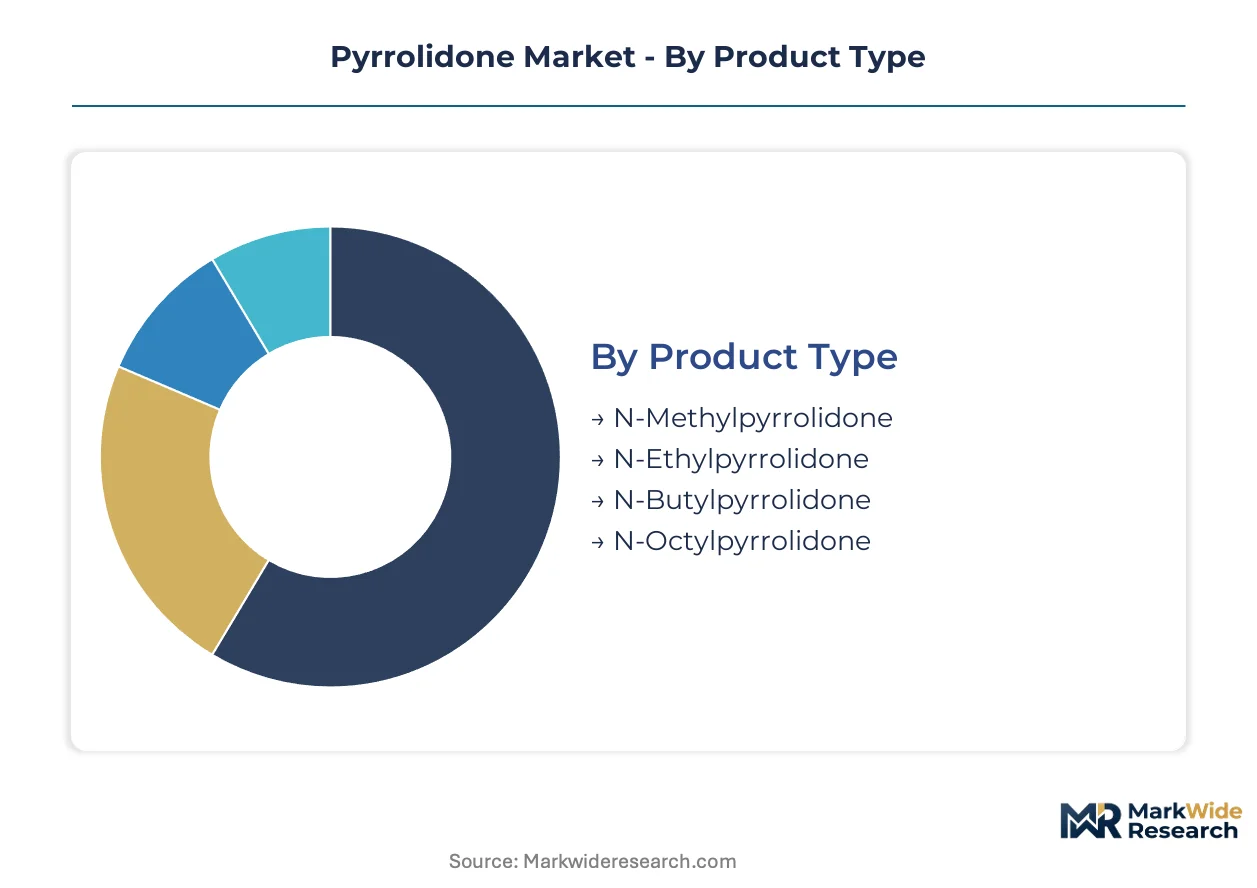
Pyrrolidone solvent selection hinges on polarity, volatility, and regulatory clearance thresholds that vary sharply across end-use specifications. Manufacturers configure product portfolios around purity grades rather than molecular variants alone.
Product Type:
Cost tier differentiation separates commodity volumes from semiconductor-grade premiums where purification intensity drives margin structure.
- N-Methylpyrrolidone:The five-membered lactam with N-methyl substitution delivers the highest polarity among commercial pyrrolidones. Battery cathode slurry processing in Jiangsu province concentrates demand, with polyvinylidene fluoride binder dispersion requiring sub-ppm metal ion specifications that command substantial price premiums over industrial grades.
- N-Ethylpyrrolidone:Slightly higher molecular weight reduces vapor pressure for coatings applications where worker exposure limits are tightening. North American industrial maintenance channels favor this variant for degreasing formulations as ECHA reproductive toxicity reviews pressure N-methylpyrrolidone substitution in consumer-facing products.
- N-Butylpyrrolidone:Extended alkyl chain improves compatibility with nonpolar substrates in agrochemical formulations.
- N-Octylpyrrolidone:Lipophilic character suits personal care emulsion systems and topical pharmaceutical carriers.
N-Methylpyrrolidone commands the established base. The steepest expansion runs through N-ethylpyrrolidone as regulatory pressure accelerates reformulation timelines.
Application:
Application segmentation tracks divergent purity requirements from pharmaceutical injectable grades to industrial maintenance solvents.
- Pharmaceuticals:Pyrrolidone carriers solubilize BCS Class II and IV active pharmaceutical ingredients in oral solid dosage forms. Injectable formulations for high-concentration antibody subcutaneous delivery are expanding most quickly as biopharma manufacturers seek alternatives to dimethyl sulfoxide co-solvent systems.
- Agriculture:Pyrrolidone solvents serve as formulation aids for systemic fungicides and herbicides requiring deep cuticular penetration.
- Coatings:Industrial protective coatings rely on N-methylpyrrolidone for epoxy and polyurethane resin thinning where film formation uniformity is critical.
- Cleaning Products:Precision electronics cleaning and metal degreasing applications face the most immediate substitution pressure from ECHA authorization timelines.
Pharmaceuticals anchors revenue concentration. Coatings faces the steepest regulatory headwinds.
End User:
Customer type segmentation reveals divergent procurement patterns between specification-driven healthcare buyers and price-sensitive industrial formulators.
- Healthcare:Pharmaceutical manufacturers and medical device sterilization operations demand comprehensive regulatory dossiers including FDA Drug Master Files and EMA Certificates of Suitability.
- Chemical Industry:Battery material producers negotiate multi-year tolling agreements directly with integrated pyrrolidone manufacturers, bypassing traditional distributor networks.
- Personal Care:Cosmetic formulators specify cosmetic-grade certifications with heavy metal and microbial limits.
- Automotive:Electric vehicle battery supply chains concentrate procurement among cathode producers scaling nickel-rich formulations.
Chemical Industry drives volume scale. Healthcare captures margin premiums.
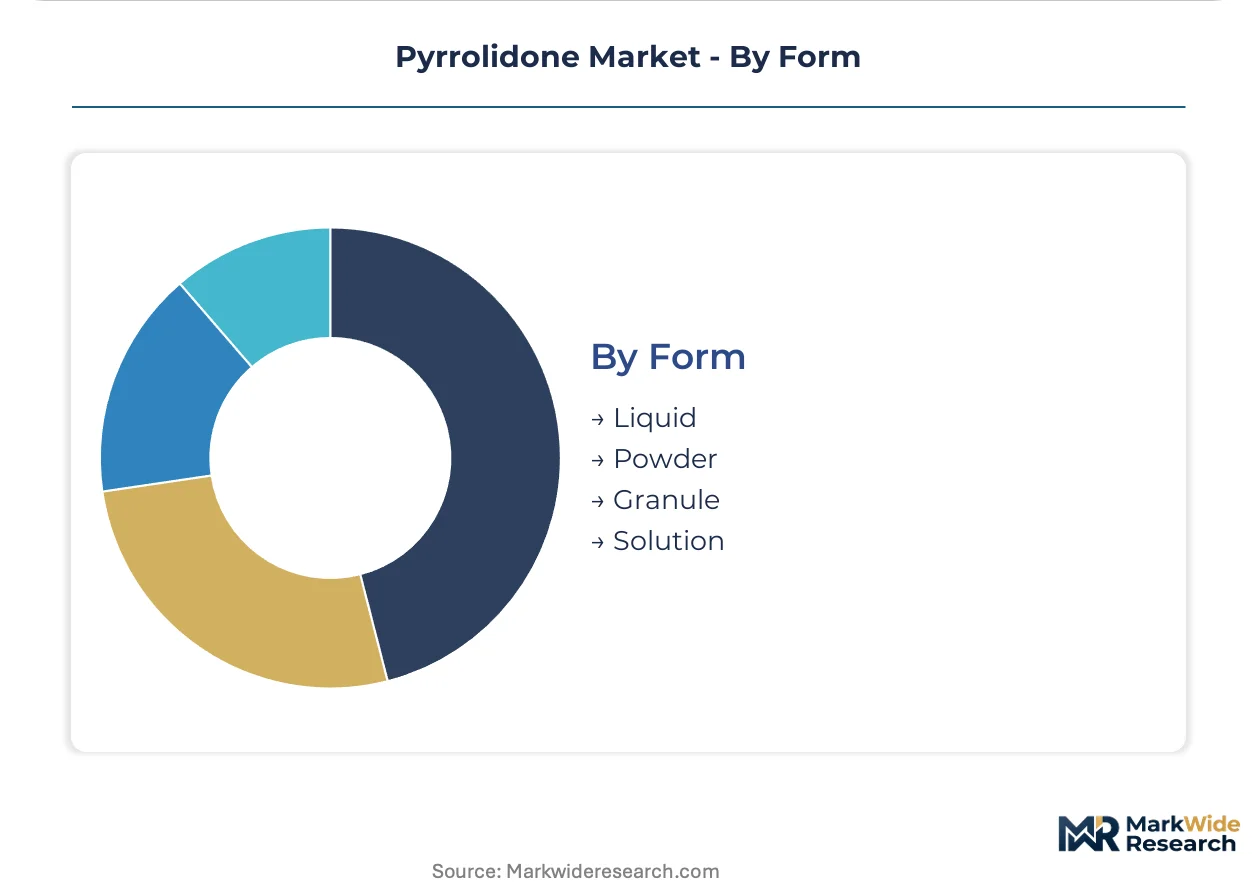
Form:
Physical state selection reflects handling logistics, dissolution kinetics, and downstream processing compatibility.
- Liquid:Bulk liquid delivery dominates battery and electronics applications where continuous processing requires pumpable feedstocks.
- Powder:Spray-dried pyrrolidone derivatives serve solid dosage form manufacturing where direct compression tableting benefits from uniform particle size distribution.
- Granule:Agglomerated forms reduce dust exposure in agricultural chemical compounding operations.
- Solution:Pre-formulated aqueous or alcoholic solutions accelerate pharmaceutical process development timelines.
Liquid form holds the volume base. Powder form is climbing fastest in solid dosage expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European semiconductor-grade premiums exceed Chinese industrial-grade pricing by substantial margins, reflecting divergent purity specifications and regulatory compliance burdens across geographies.
China
Jiangsu and Zhejiang provinces concentrate over sixty percent of global battery-grade N-methylpyrrolidone purification capacity, serving cathode slurry processing for domestic gigafactory clusters. MIIT's dual carbon goals are accelerating membrane-based purification technology adoption. Suzhou and Ningbo host integrated solvent-electrode supply chains where direct procurement agreements now displace traditional distributor networks.
Germany
BASF SE's Ludwigshafen complex anchors European captive supply for cathode producers, leveraging integrated Reppe synthesis from butyrolactone feedstock. ECHA's persistent reproductive toxicity classification discussions under REACH are forcing coatings formulators toward N-ethylpyrrolidone substitution. The Rhine-Neckar metropolitan region concentrates pharmaceutical-grade production serving EMA-certified drug manufacturers.
United States
EPA oversight of N-methylpyrrolidone emissions and worker exposure limits shapes manufacturing facility siting decisions across Texas and Louisiana petrochemical corridors. Ashland competes in North American coatings channels with tailored solvent formulations. The Gulf Coast's butyrolactone derivative supply chains feed both electronics and pharmaceutical purification operations.
South Korea
Korean foundry suppliers now specify nanofiltration-polishing hybrid processes for semiconductor-grade solvents, demanding sub-ppb sodium and potassium thresholds. MFDS pharmaceutical regulations govern pyrrolidone carrier use in injectable biopharma formulations. The Seoul Capital Area and Busan-Ulsan corridor concentrate battery material procurement negotiations with integrated Japanese and domestic solvent producers.
India
Production-linked incentive schemes for cell manufacturing are creating captive solvent demand as domestic cathode plants scale in Gujarat and Tamil Nadu. CDSCO's pharmaceutical-grade certification requirements parallel FDA Drug Master File standards for export-oriented API manufacturers. The Delhi-Mumbai Industrial Corridor is attracting tolling agreement proposals from regional pyrrolidone traders seeking to bypass traditional bulk handlers.
Pyrrolidone Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in purification and derivative chemistry. The pyrrolidone market exhibits consolidated upstream manufacturing with fragmented downstream formulation channels. Three archetypes dominate: integrated petrochemical conglomerates with captive butyrolactone supply, specialty chemical houses focused on pharmaceutical-grade certification, and regional traders serving battery cluster logistics. Competitive moves center on co-location agreements with cathode producers and membrane technology licensing for semiconductor-grade purity.
Among German-based integrated producers, BASF SE exemplifies the petrochemical platform archetype through its Ludwigshafen complex operations. Mitsubishi Chemical Corporation anchors Asia-Pacific supply positioning for pharmaceutical-grade lines. Ashland occupies a position within North American coatings-focused specialty formulation, representing the regional certification-driven tier.
| Leading Market Players |
|---|
| BASF SE |
| Mitsubishi Chemical Corporation |
| Eastman Chemical Company |
| Ashland |
| LyondellBasell Industries |
| Johnson Matthey |
| Solvay |
| Merck KGaA |
| Arkema |
| Others |
Cost & Logistics Intelligence
Jiangsu province's concentration of battery-grade purification capacity grants integrated producers substantial leverage over spot-market pricing for industrial-grade volumes. ECHA's reproductive toxicity review timelines and MIIT's dual carbon mandates are compressing margins for non-integrated traders unable to pass compliance costs downstream.
Pricing Analysis
Configured-to-order pricing for semiconductor-grade specifications commands substantial premiums over standard industrial-grade spot transactions. Three-tier pricing structure across semiconductor-grade, battery-grade, and industrial-grade levels stratifies the market, with certification intensity and metal-ion thresholds as primary differentiation drivers. Pricing pressure stems from membrane-technology capital requirements as Korean foundry suppliers tighten sub-ppb sodium and potassium specifications. Battery cathode producers exhibit lowest price sensitivity due to captive tolling arrangements, while coatings formulators face highest sensitivity amid ECHA substitution deadlines.
Supply Chain Analysis
Butyrolactone feedstock availability anchors supply security for Reppe synthesis operations across China, Germany, and the United States. Acetylene and 1,4-butanediol derivatives feed production lines, with petrochemical price volatility transmitting directly to solvent manufacturing economics. Single-source vulnerability concentrates in Jiangsu and Zhejiang provinces where over sixty percent of battery-grade purification capacity sits within flood-prone coastal zones. Distribution runs through direct procurement channels between cathode producers and integrated manufacturers, displacing traditional bulk chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as direct tolling agreements between cathode manufacturers and solvent producers lock in volume commitments ahead of regulatory reclassification deadlines. Interoperability between membrane purification technology and foundry qualification protocols is creating winner-take-most dynamics in semiconductor-grade supply.
For Market Incumbents: Pre-empt regulatory displacement by accelerating N-ethylpyrrolidone qualification for coatings applications before ECHA authorization timelines tighten. Backward integration into butyrolactone feedstock secures margin control against petrochemical volatility. BASF's Ludwigshafen complex exemplifies captive supply architecture that emerging competitors cannot readily replicate. For New Entrants and Emerging Players: Build out pharmaceutical-grade certification capabilities in India where CDSCO standards and production-linked incentive schemes create captive demand from domestic cathode scaling. Gujarat and Tamil Nadu offer the most penetrable geography given tolling agreement vacancies and limited incumbent membrane-technology presence. Target injectable biopharma formulations as the go-to-market angle where dimethyl sulfoxide substitution creates immediate formulation partnerships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated producers with multi-year tolling agreements and captive feedstock supply. Long-term viability over the projection horizon favors membrane-technology licensors over legacy distillation-asset owners. The acquisition target archetype combines semiconductor-grade certification with established foundry relationships. Watch for MFDS and FDA Drug Master File submission volumes as inflection indicators for pharmaceutical-grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Technology Licensing | Korean foundry sub-ppb specifications render legacy distillation investments obsolete. |
| Backward Integration into Butyrolactone | Ludwigshafen-style captive feedstock supply insulates margin from petrochemical volatility. |
| Pharmaceutical-Grade Certification Investment | FDA Drug Master Files and EMA Certificates of Suitability unlock biopharma injectable formulations. |
| Co-Location with Cathode Producers | Yangtze River Delta tolling agreements displace regional trader networks. |
| N-Ethylpyrrolidone Reformulation Partnerships | ECHA reproductive toxicity timelines force coatings substitution before authorization restrictions. |
Research Approach
A spread of perspectives from plant managers at integrated pyrrolidone facilities, procurement leads at battery material OEMs, technical R&D directors at pharmaceutical formulators, and distribution channel partners converged on the working assumptions. Primary interview insights combined with customs and trade data, SEC 10-K filings, ACC and Cefic industry reports, and ECHA substance evaluation dossiers. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates across grade tiers and end-use applications.
Demand-supply-balance dynamics anchored the analytical framework across the analysis window, with segmentation modeled by grade tier, end-use industry, and regional production hub. CAGRs derived from trend extrapolation of cathode slurry processing intensity, pharmaceutical solubilization adoption curves, and semiconductor-grade purity threshold evolution. Forecast inputs incorporated membrane-technology adoption rates and ECHA regulatory timeline scenarios.
Stress conditions across butyrolactone feedstock price volatility, ECHA reclassification severity, and China gigafactory capacity ramp rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory trajectory and technology substitution elasticity. Cross-checking against customs trade data and foundry capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Free-From Titanium Dioxide Market
Specialty Chemicals
North America Sugarcane Wax Market
Specialty Chemicals
South Korea Cleanroom Disposable Gloves Market
Specialty Chemicals
Petroleum Jelly Market
Specialty Chemicals
Global Release Agents Market
Specialty Chemicals
Iron Phosphate Market
Specialty Chemicals
Australia and New Zealand Aerosol Market
Specialty Chemicals
Betulinic Acid Market
Specialty Chemicals
Sodium Hyaluronate Market
Specialty Chemicals
Glucono Delta Lactone Market
Specialty Chemicals
VCI Aerosol Market
Specialty Chemicals
Bio-Based Phenol Market
Specialty Chemicals
Coconut Derived Emollients Market
Specialty Chemicals
Perms and Relaxants Market
Specialty Chemicals
Marine Hyaluronic Acid Market
Specialty Chemicals
Specialty Plasticizer Market