
 Global Ultrafast Lasers Market | 2026-2036
Global Ultrafast Lasers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ultrafast Lasers Market Foresight
Market Context
Direct OEM sales to semiconductor fabs and medical device makers is reshaping how ultrafast laser vendors capture margin, bypassing traditional photonics distributors. Coherent Corp dominates North American supply through captive crystal growth and amplifier module production. TRUMPF anchors European demand with integrated ultrafast systems for automotive micromachining. IPG Photonics Corporation leverages its fiber laser scale to push ytterbium-doped platforms into cost-sensitive industrial segments.
Technical Definition and Segment Structure
Ultrafast lasers generate pulses shorter than ten picoseconds, typically through mode-locking or Q-switching, enabling cold ablation that removes material without thermal damage to surrounding substrates. Femtosecond systems lead product type revenue due to premium pricing in corneal surgery and stent cutting, while picosecond lasers compete on throughput for OLED panel repair and PCB drilling. Ytterbium-doped fiber technology is displacing titanium sapphire in industrial settings because of superior wall-plug efficiency and reduced maintenance intervals. Semiconductor manufacturers represent the fastest-growing end user category as node shrinkage demands sub-micron precision that mechanical tools cannot achieve.
Regulatory Environment and Outlook
FDA laser product regulations in the United States, CE marking under the EU MDR, and Japan's METI industrial safety standards collectively dictate beam delivery specifications and operator training protocols. REACH compliance in Europe restricts certain optical coating chemistries, pushing suppliers toward fluorine-free alternatives. Stakeholders must monitor how the EU AI Act and emerging ISO standards for autonomous laser systems reshape product certification pathways and liability frameworks.
Market Dynamics
Semiconductor node shrinkage below 3nm is forcing fabs to abandon mechanical dicing for femtosecond ablation, rewriting procurement specifications across East Asian and North American supply chains.
Growth Catalysts
- CE Marking MDR Compliance:European medical device certification now mandates ultrafast sources for stent and catheter cutting, locking in premium laser demand from Swiss and German contract manufacturers.
- Die Singulation Precision:Wafer processing at sub-micron tolerances requires cold ablation that mechanical saws cannot achieve, pulling femtosecond systems into back-end semiconductor lines.
- OLED Panel Repair:South Korean and Chinese display fabs deploy picosecond lasers for dead-pixel correction at throughput rates mechanical probes cannot match.
Market Restraints
- Ytterbium Fiber Supply Concentration:Germany and Japan host the only qualified preform draw towers for industrial-grade doped fiber, creating single-source vulnerability for system integrators.
- REACH Optical Coating Restrictions:ECHA limitations on fluorinated deposition chemistries force reformulation of anti-reflective stacks, extending qualification cycles by 8-14 months.
- Titanium Sapphire Obsolescence Cost:Industrial users face stranded capital in legacy amplifier chains as ytterbium platforms deliver superior wall-plug efficiency and maintenance intervals.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for semiconductor packaging attract ultrafast laser vendors to establish local beam-delivery assembly, bypassing import duty exposure.
- Autonomous Beam Delivery:Convergence of machine vision and adaptive optics enables real-time kerf correction, opening unmanned micromachining cells for overnight production runs.
- Corneal Refractive Surgery:FDA-cleared femtosecond platforms for LASIK flap creation and cataract fragmentation expand addressable patient pools in outpatient surgical centers.
Industry Challenges
- Ultrafast Optics Talent Scarcity:Mode-locked oscillator alignment and dispersion compensation require PhD-level photonics expertise that vocational programs do not produce.
- ISO 11553-1 Certification Timelines:Laser safety standard compliance for industrial robot integration demands 12-18 month validation protocols that delay revenue recognition.
- Legacy CNC Integration:Mechanical machining centers require complete motion-control retrofitting to achieve the positional accuracy femtosecond ablation demands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ultrafast Lasers Market |
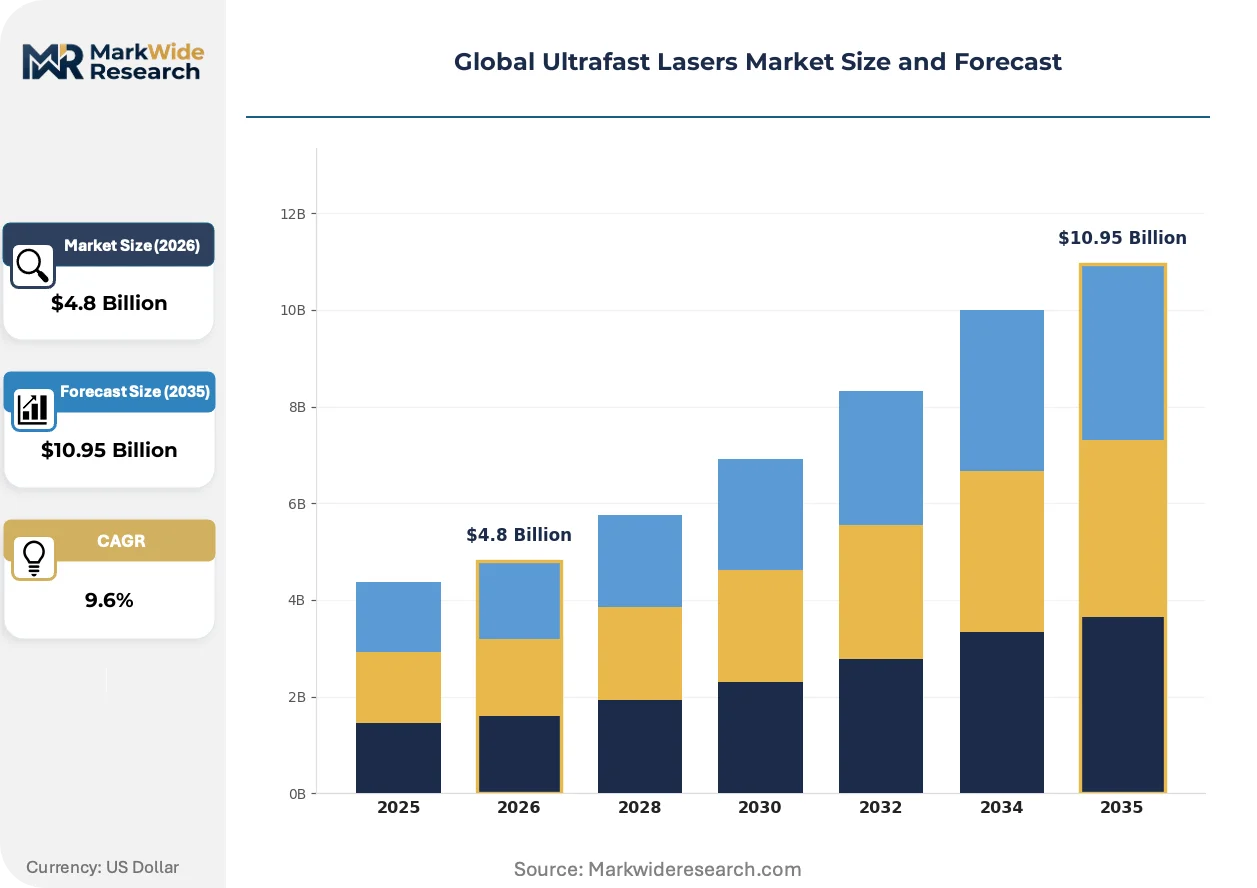
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.95 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Femtosecond Laser, Picosecond Laser, Nanosecond Laser, Mode-Locked Laser, Q-Switched Laser Technology: Titanium Sapphire, Ytterbium-Doped Fiber, Optical Parametric Amplifier, Semiconductor Saturable Absorber, Disk Laser Application: Micromachining, Spectroscopy, Medical Surgery, Telecommunications, Scientific Research End User: Research Institutes, Semiconductor Manufacturers, Medical Facilities, Defense Departments, Communication Companies |
| Companies Covered | NKT Photonics A/S, Ekspla, Coherent Corp, Amplitude Laser, Light Conversion, IPG Photonics Corporation, Newport Corporation, MKS Instruments Inc., TRUMPF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ultrafast Lasers Market Shifts & Advancements
Beam delivery architectures and regulatory frameworks are converging to compress deployment cycles while expanding addressable precision-manufacturing applications beyond traditional photonics buyers.
Adaptive optics with real-time wavefront sensing is digitizing kerf geometry control in semiconductor dicing operations. Memory fabs in Japan and South Korea deploy these systems to maintain sub-100nm edge placement accuracy as wafer thickness drops below 50 microns. This capability is digitizing quality assurance, collapsing final inspection from offline metrology to in-process verification.
REACH F-Gas Regulation amendments now restrict sulfur hexafluoride etching chemistries used in laser cavity component fabrication. German and French optical houses face reformulation mandates for plasma-deposited mirror coatings. Medical laser OEMs in Switzerland and Italy accelerate fluorine-free supplier qualification to preempt 2027 enforcement deadlines.
Direct OEM contracting is displacing photonics distributor networks for high-volume semiconductor and medical device procurement. TRUMPF and Coherent field application engineers now embed at fab and contract manufacturer sites for specification development. This pattern concentrates most visibly in Germany's precision manufacturing clusters and Arizona's semiconductor corridor.
Global Ultrafast Lasers Market Segmentation
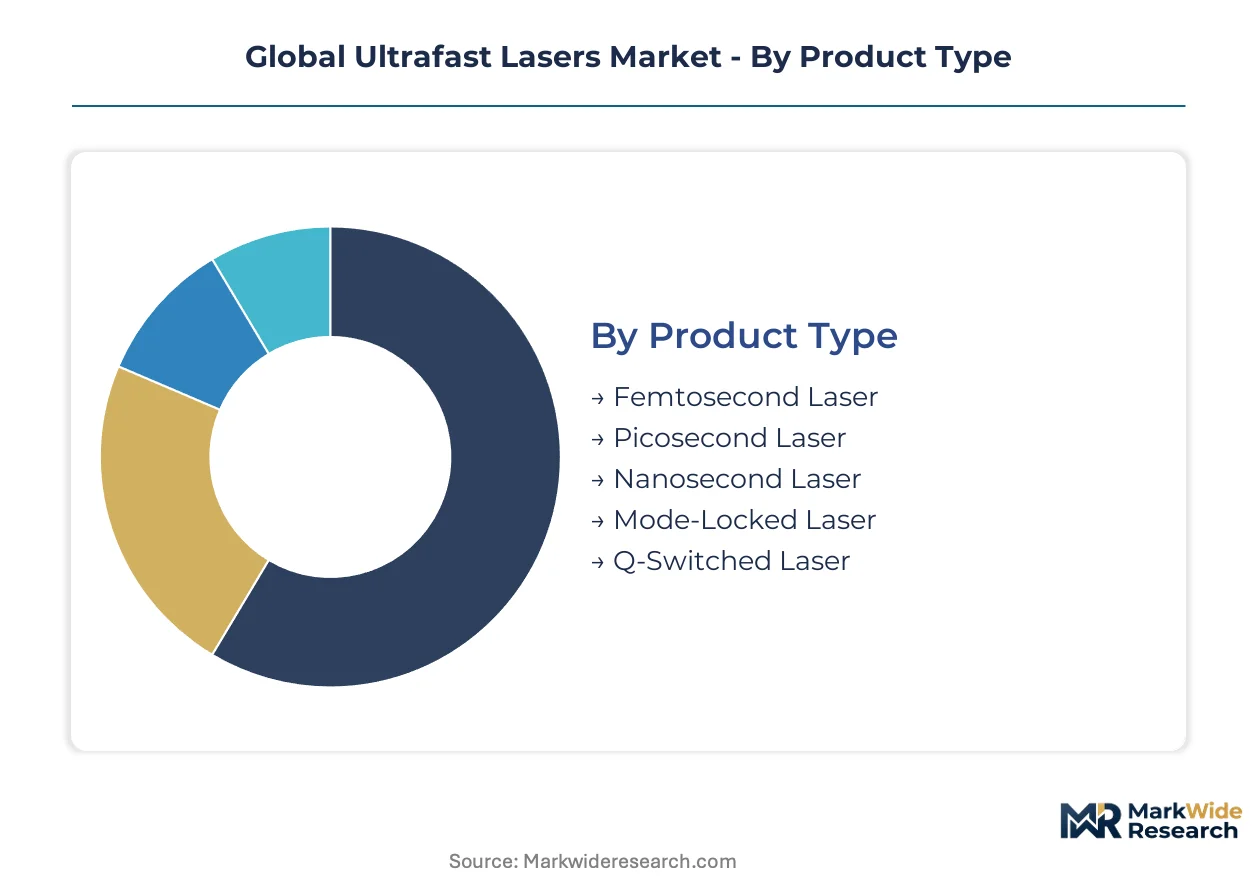
Ultrafast laser segmentation reflects a technology base in transition from laboratory instrumentation to industrial production tools. Procurement patterns diverge sharply between scientific users prioritizing pulse tunability and fabs demanding throughput stability at wafer scale.
Product Type:
Mature industrial platforms now compete with emerging formats as cold ablation requirements spread beyond research settings.
- Femtosecond Laser:Pulse durations below one picosecond enable true cold ablation with zero heat-affected zone. Semiconductor back-end lines in Germany and Japan specify femtosecond systems for die singulation below 3nm nodes where mechanical dicing fails.
- Picosecond Laser:Slightly longer pulses trade absolute precision for material removal rates. Display manufacturers in South Korea deploy picosecond sources for OLED pixel repair at throughputs mechanical probes cannot match.
- Nanosecond Laser:Thermal-mode operation suits cost-sensitive marking and engraving applications.
- Mode-Locked Laser:Oscillator architecture generating ultrafast pulse trains through cavity modulation.
- Q-Switched Laser:Pulsed operation via active or passive switching for lower-cost industrial deployment.
Femtosecond systems handle the majority of precision throughput; picosecond platforms are gaining share fastest in display and PCB applications.
Technology:
Gain medium selection determines wall-plug efficiency, maintenance burden, and capital recovery timelines across end-use categories.
- Ytterbium-Doped Fiber:Diode-pumped fiber geometry delivers superior electrical efficiency and sealed optical paths. Industrial micromachining centers in the United States and Germany favor ytterbium platforms for 24/7 production cycles.
- Titanium Sapphire:Broad tunability spanning visible and near-infrared remains essential for spectroscopy and multiphoton microscopy. Research institutes in Switzerland and Japan maintain installed bases despite higher operational costs.
- Optical Parametric Amplifier:Wavelength conversion extending into mid-infrared for specialized materials processing.
- Semiconductor Saturable Absorber:Passive mode-locking element enabling compact oscillator designs.
- Disk Laser:Thin-disk geometry combining power scaling with beam quality for high-average-power applications.
Ytterbium-doped fiber commands the dominant share of new industrial procurement; titanium sapphire retains its position in scientific instrumentation.
Application:
End-use requirements range from sub-micron dimensional tolerances to molecular-resolution detection limits.
- Micromachining:Cold ablation of metals, ceramics, and polymers without thermal damage to surrounding substrate. Swiss medical device contract manufacturers deploy ultrafast systems for stent and catheter cutting under CE marking MDR requirements.
- Medical Surgery:Femtosecond platforms for LASIK flap creation and cataract fragmentation. Outpatient surgical centers in the United States expand adoption as FDA-cleared systems proliferate.
- Spectroscopy:Time-resolved measurement of ultrafast chemical and physical processes.
- Telecommunications:Signal processing and component testing in fiber optic networks.
- Scientific Research:Fundamental physics, chemistry, and materials science investigations.
Micromachining absorbs the largest equipment volume; medical surgery is expanding most quickly as regulatory pathways mature.
End User:
Customer technical sophistication and procurement authority shape specification development and supplier engagement models.
- Semiconductor Manufacturers:Back-end wafer processing and advanced packaging operations. Fabs in Arizona and Saxony specify ultrafast systems for node shrinkage below 3nm where mechanical tools reach physical limits.
- Research Institutes:National laboratories and university facilities requiring pulse tunability and measurement flexibility. Max Planck institutes and RIKEN centers anchor demand for custom oscillator configurations.
- Medical Facilities:Hospital systems and ambulatory surgery centers performing refractive and cataract procedures.
- Defense Departments:Directed energy and sensing applications with classified performance requirements.
- Communication Companies:Network equipment manufacturers and service providers.
Semiconductor manufacturers represent the fastest-growing customer category; research institutes retain the highest per-unit specification complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Taiwan Strait submarine cable corridors and Japan-US Pacific fiber links anchor East Asian data throughput, underwriting precision manufacturing clusters that consume ultrafast laser systems for semiconductor and display fabrication.
United States
CHIPS Act subsidies for Arizona and Texas fabs pull femtosecond systems into back-end die singulation lines. FDA laser product regulations govern medical device certification for refractive surgery platforms. Greater Phoenix semiconductor corridors now host embedded field engineering teams from major laser OEMs.
Germany
Automotive micromachining in Baden-Württemberg and Saxony demands ytterbium-doped fiber systems for 24/7 production cycles. REACH compliance deadlines for fluorine-free optical coatings force reformulation of anti-reflective stacks. Munich and Stuttgart precision manufacturing clusters concentrate contract manufacturer procurement under CE marking MDR frameworks.
Japan
METI industrial safety standards dictate beam delivery specifications for memory fab operations in Hiroshima and Yokkaichi. Sub-3nm node shrinkage forces abandonment of mechanical dicing for cold ablation. Kyushu and Tohoku semiconductor corridors anchor femtosecond system deployment for wafer thinning below 50 microns.
South Korea
Display fabs in Gyeonggi Province deploy picosecond lasers for OLED pixel repair at throughputs mechanical probes cannot match. MFDS medical device regulations shape certification pathways for surgical laser platforms. Samsung and LG supply chains in Suwon and Paju concentrate procurement for dead-pixel correction systems.
Switzerland
Swissmedic certification requirements lock in premium laser demand for stent and catheter cutting from Solothurn and Jura contract manufacturers. Precision watchmaking clusters in Neuchâtel adopt femtosecond micromachining for micro-mechanical components. Basel pharmaceutical device corridors specify ultrafast sources for drug delivery system fabrication.
Global Ultrafast Lasers Market Competitive Landscape
On the supply side, the industry is consolidating around integrated system vendors with captive crystal growth and amplifier module production. Three strategic archetypes dominate: vertically integrated photonics conglomerates with fiber preform capabilities, specialized ultrafast oscillator houses serving research institutes, and industrial automation platforms adding laser modules to CNC portfolios. Competitive moves center on direct OEM contracting to bypass distributor networks and embedded field engineering at fab sites.
Among North American photonics conglomerates, Coherent Corp and IPG Photonics Corporation exemplify the integrated-system archetype with upstream control over gain medium production. TRUMPF anchors the European industrial automation tier. NKT Photonics A/S represents the specialized oscillator segment serving scientific instrumentation demand.
| Leading Market Players |
|---|
| NKT Photonics A/S |
| Ekspla |
| Coherent Corp |
| Amplitude Laser |
| Light Conversion |
| IPG Photonics Corporation |
| Newport Corporation |
| MKS Instruments Inc. |
| TRUMPF |
| Others |
Supply & Pricing Matrix
Single-source dependency on German and Japanese ytterbium-doped fiber preform draw towers compresses pricing power for system integrators while amplifying tier spreads between captive-supply conglomerates and fiber-importing assemblers. REACH F-Gas regulatory chokepoints on fluorinated optical coating chemistries extend qualification cycles and harden premium pricing for CE-marked medical device configurations.
Pricing Analysis
Volume-discount tiering structures separate femtosecond surgical platforms with FDA 510(k) clearance from industrial picosecond systems sold through distributor channels. Price differentiation hinges on CE marking MDR certification grade and bundled field engineering support. Cost compression in standard industrial tiers intensifies as IPG Photonics pushes ytterbium fiber scale economics. Semiconductor fabs in Arizona and Saxony exhibit lowest price sensitivity; contract manufacturers in emerging packaging corridors show highest.
Supply Chain Analysis
Fujikura and Furukawa Electric in Japan alongside Schott and Heraeus in Germany hold captive capacity for industrial-grade doped fiber preform production. Raw material dependencies center on high-purity silica, rare-earth ytterbium oxide, and specialized anti-reflective coating substrates. Single-source vulnerability concentrates in qualified fiber draw towers, with tariff exposure rising for beam-delivery optics sourced across Taiwan Strait corridors. Distribution runs through direct OEM contracting at fab sites, displacing traditional photonics distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ultrafast laser penetration sits at early-cycle expansion as sub-3nm semiconductor node shrinkage forces mechanical-to-laser process conversion across East Asian and North American back-end lines.
For Market Incumbents: Insulate fiber supply security through backward integration into preform draw capacity or long-term offtake agreements with Schott and Heraeus. Lock in CE marking MDR certification pathways ahead of 2027 REACH enforcement deadlines to defend premium medical device pricing against fluorine-free coating reformulators. For New Entrants and Emerging Players: Build out autonomous beam-delivery capabilities combining machine vision with adaptive optics for unmanned micromachining cells. The most penetrable white space sits in India's PLI-subsidized semiconductor packaging corridors, where local beam-delivery assembly bypasses import duty exposure and embedded field engineering commands premium positioning. For Investors and Strategic Acquirers: EU AI Act implementation reshapes the acquisition landscape for autonomous laser system vendors by introducing new product liability frameworks and certification complexity. Long-term viability favors targets with captive crystal growth and amplifier module production. The signal to watch is FDA 510(k) clearance velocity for femtosecond surgical platforms as outpatient center penetration accelerates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Preform Production | Captive ytterbium-doped fiber supply insulates against German-Japanese draw tower concentration risk. |
| CE Marking MDR Certification Acceleration | Fluorine-free coating qualification ahead of REACH deadlines locks premium medical device pricing tiers. |
| Autonomous Beam Delivery Development | Machine vision convergence enables unmanned micromachining cells for overnight semiconductor production runs. |
| India PLI Corridor Establishment | Local assembly bypasses import duty exposure in government-subsidized semiconductor packaging zones. |
| Direct OEM Field Engineering Embedment | On-site specification development at Arizona and Saxony fab sites displaces distributor channel margin. |
Research Methodology
A standing panel of laser systems engineers, semiconductor fab procurement directors, medical device regulatory affairs leads, and photonics distributor principals provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) filings, ECHA REACH substance restriction updates, METI industrial safety standard revisions, and SEC filings from listed photonics conglomerates. Bottom-up equipment shipment tracking triangulated against top-down fab capex disclosure analysis.
Scenario-bracketing framed demand projections across the analysis window, modeling pulse duration tier, gain medium technology, end-use application, and geographic regulatory cluster segmentation. CAGRs derived from equipment replacement cycle analysis and node shrinkage-driven process conversion timelines. Forecast inputs incorporated ytterbium fiber supply elasticity and CE marking MDR certification pipeline velocity.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese fiber laser platforms or accelerated EU AI Act enforcement would shift outcomes. Quarterly review of FDA 510(k) clearance backlogs and ECHA fluorine-free coating qualification timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
NB-IoT Module Market
Emerging and Next Generation Technologies
Nanodiamond Market
Emerging and Next Generation Technologies
3D Electronics Market
Emerging and Next Generation Technologies
Nanoparticle Technology Market
Emerging and Next Generation Technologies
Asia Pacific Wigig Market
Emerging and Next Generation Technologies
Global WI SUN Technology Market
Emerging and Next Generation Technologies
Transparent Solar Cells Market
Emerging and Next Generation Technologies
Global Terahertz Components and Systems Market
Emerging and Next Generation Technologies
Global 3D TSV and 2.5D Market
Emerging and Next Generation Technologies
Terahertz Radiation Devices Market
Emerging and Next Generation Technologies
Global Broad Ion Beam Technology Market
Emerging and Next Generation Technologies
Triboelectric Nano-Generator Market
Emerging and Next Generation Technologies
Internet of Nano Things Market
Emerging and Next Generation Technologies
Printed Electronics Market
Emerging and Next Generation Technologies
Ultra-Thin Solar Cells Market
Emerging and Next Generation Technologies
Stretchable Electronics Market