
 AI PC Market | 2026-2036
AI PC Market Size, Share, and Industry Trends Forecast 2026-2036
AI PC Market Insights
The capital-intensity divergence between integrated chip-design houses and assembly-only OEMs is collapsing as NPU fabrication costs force consolidation. Intel sustains massive foundry investments to anchor x86 AI acceleration in enterprise laptops. Qualcomm dominates ARM-based Windows AI PCs through its Snapdragon X Elite platform. Lenovo navigates global channel complexity by controlling manufacturing scale across multiple continents.
An AI PC integrates a neural processing unit alongside traditional CPU and GPU architectures, enabling local execution of machine learning inference workloads without cloud dependency. The architecture typically requires at least 40 TOPS of NPU compute capacity to qualify under emerging industry benchmarks, with on-device large language model inference serving as the primary commercial purpose. Laptop AI PC configurations currently lead volume shipments as mobile professionals demand offline generative AI capabilities. Workstation AI PC units command the highest margin pools due to specialized deep learning training requirements among scientific researchers and financial analysts. Desktop AI PC adoption remains concentrated in creative agencies running computer vision pipelines for content production.
The EU AI Act imposes risk-classification requirements on AI systems deployed through commercial hardware, directly affecting how OEMs certify on-device inference capabilities. The U.S. Department of Commerce export controls on advanced AI accelerators shape which NPU architectures can ship to specific markets, while the FCC governs wireless connectivity standards for AI-enabled edge devices. Stakeholders must track whether regulatory fragmentation around on-device model training versus inference triggers divergent product certification paths across jurisdictions.
Market Dynamics
Enterprise procurement of on-device inference workstations is compressing traditional cloud-dependent AI workflows into localized compute architectures, forcing hardware vendors to certify NPU performance against emerging TOPS benchmarks while navigating fragmented cross-border semiconductor controls.
Growth Catalysts
- EU AI Act risk-classification mandates:Hardware OEMs must certify on-device inference capabilities against standardized benchmarks, creating replacement cycles for enterprise fleets lacking compliant NPUs.
- Financial services edge-compute requirements:Quantitative trading desks and risk-modeling teams demand workstation-class AI PCs running proprietary algorithms without cloud data exposure.
- TSMC 3nm NPU fabrication scale-up:Foundry capacity allocation to neural processing units is reducing unit costs for qualifying 40+ TOPS architectures.
Market Restraints
- Advanced packaging substrate shortage:CoWoS and EMIB capacity constraints at Taiwanese and Korean suppliers are throttling NPU die stacking volumes.
- U.S. Department of Commerce export controls:Licensing requirements for AI accelerators above specified performance thresholds are fragmenting product SKUs across markets.
- On-device LLM thermal ceilings:Laptop form factors face sustained workload throttling that degrades inference consistency versus desktop alternatives.
Strategic Opportunities
- German industrial automation clusters:Automotive and precision manufacturing engineering centers are piloting AI PCs for real-time computer vision quality control.
- India PLI scheme for IT hardware:Domestic assembly incentives are attracting OEMs to establish NPU-integrated laptop production for South Asian enterprise demand.
- Federated learning at the edge:Convergence of differential privacy frameworks with on-device training capabilities is opening healthcare and defense applications previously restricted to air-gapped systems.
Industry Challenges
- NPU software stack fragmentation:Developers must optimize inference engines across Intel OpenVINO, Qualcomm QNN, and AMD Ryzen AI toolchains simultaneously.
- Cross-jurisdiction certification timelines:FCC wireless approval, EU CE marking, and BIS safety testing create staggered product launch windows that fragment inventory planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI PC Market |
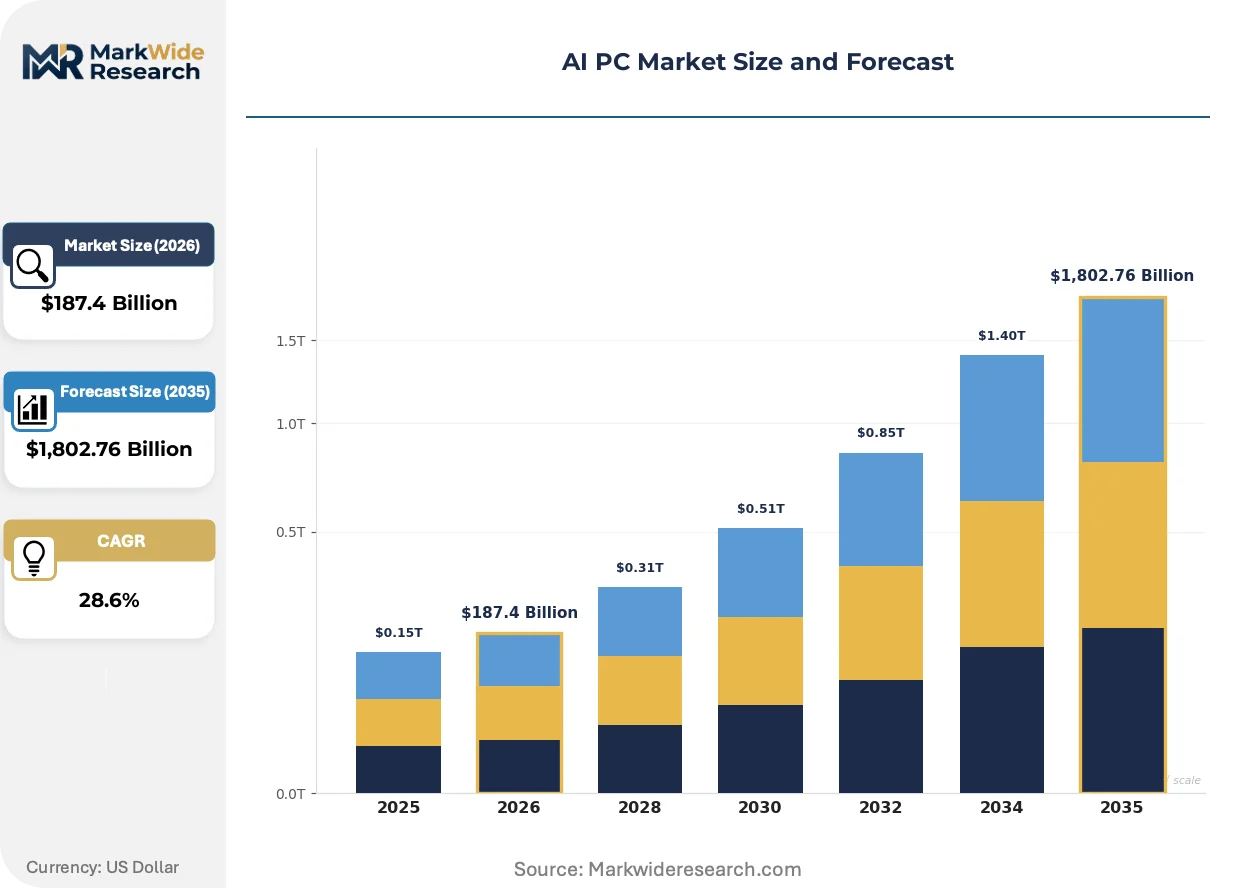
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $1,802.76 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop AI PC, Laptop AI PC, Workstation AI PC, Mini AI PC Technology: Machine Learning, Natural Language Processing, Computer Vision, Deep Learning, Reinforcement Learning Application: Data Analysis, Content Creation, Scientific Research, Virtual Assistance, Cybersecurity End User: IT Professionals, Academic Researchers, Creative Agencies, Financial Analysts |
| Companies Covered | Apple, Lenovo, Dell Technologies, HP, ASUSTeK Computer, Acer, Microsoft, Intel, Qualcomm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI PC Market Trends and Innovations
Heterogeneous compute architectures are fragmenting monolithic AI processing into distributed workloads across CPU, GPU, and NPU silicon, with software orchestration layers determining which inference tasks execute on which die.
Chiplet-based NPU design is decomposing traditional monolithic neural accelerators into modular compute tiles interconnected through standardized die-to-die interfaces. Enterprise workstation vendors are adopting these disaggregated architectures to customize TOPS-per-watt configurations for scientific computing and financial modeling workloads. This decomposition is compressing time-to-market for specialized inference silicon while forcing legacy integrated GPU suppliers to license interconnect IP or cede the workstation segment.
The EU AI Act's risk-tier classification system is mandating conformity assessment procedures for AI PCs deployed in high-risk application contexts including biometric inference and credit scoring. Hardware OEMs must maintain technical documentation and quality management systems traceable to notified body certification. Laptop manufacturers targeting European enterprise procurement are prioritizing NPU architectures with deterministic execution timing to satisfy explainability requirements under the Act's transparency obligations.
Enterprise IT departments are consolidating vendor relationships around full-stack AI PC suppliers capable of delivering pre-configured inference environments with model optimization services. Systems integrators and value-added resellers are losing attach rates as direct OEM enterprise contracts bundle hardware with MLOps tooling and fine-tuning support. This concentration is most visible in United States healthcare and financial services verticals where procurement teams prioritize single-source accountability for on-device AI deployment failures.
AI PC Market Segmentation
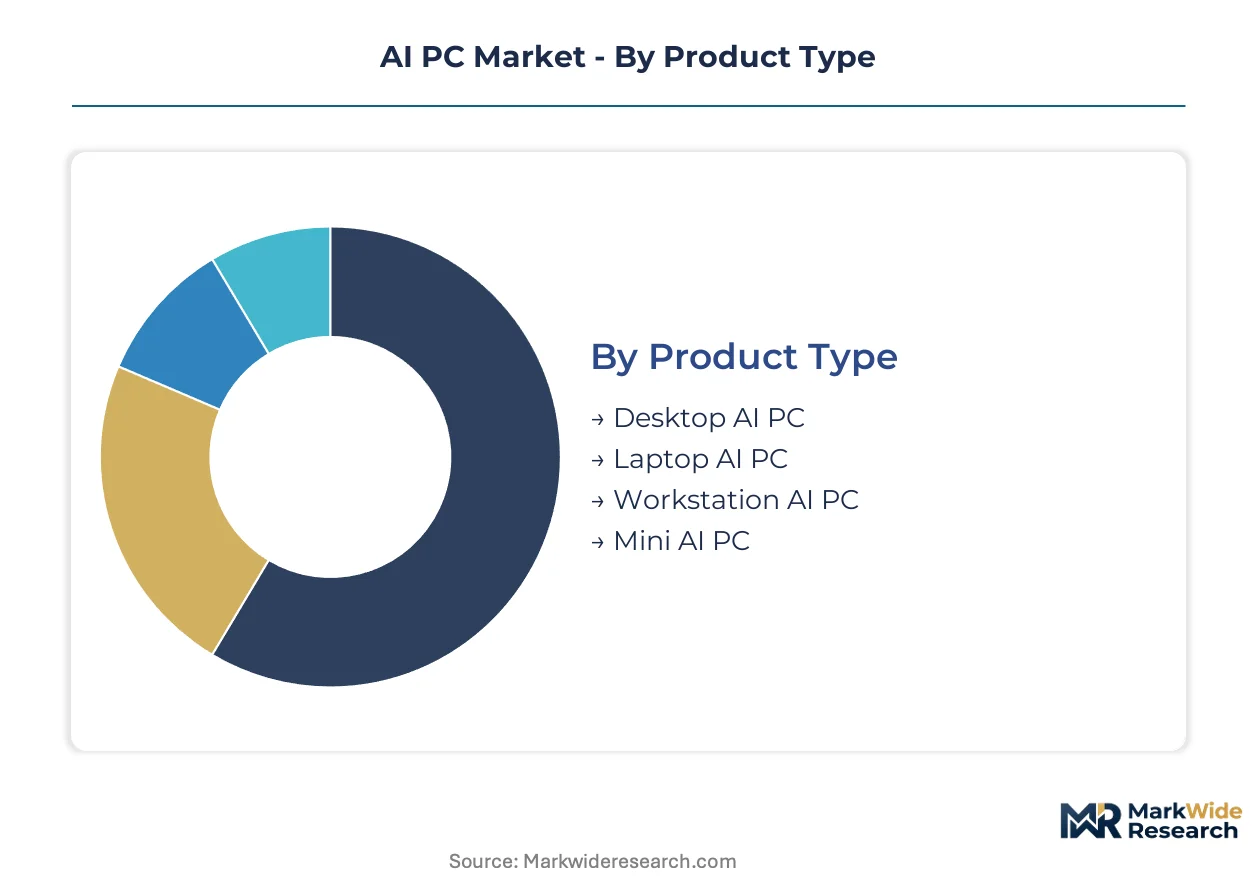
AI PC segmentation reveals how NPU compute requirements fracture across mobility constraints and thermal envelopes. Channel strategy diverges sharply between volume laptop SKUs and margin-rich workstation configurations.
Product Type:
Direct enterprise procurement concentrates in workstation and desktop segments, while laptop AI PCs flow through retail and value-added reseller channels with heavy OEM bundling of MLOps tooling.
- Laptop AI PC:Mobile form factors integrate 40+ TOPS NPUs under strict thermal ceilings, enabling offline generative AI for traveling professionals. Demand concentrates among United States consulting firms and German automotive engineering teams requiring field-deployable inference without cloud connectivity.
- Workstation AI PC:Rack-mounted and tower configurations deploy dual-NPU architectures exceeding 100 TOPS for training fine-tuned models on proprietary datasets. Financial services quantitative desks in New York and London absorb premium units to eliminate data residency risks in algorithmic trading workflows.
- Desktop AI PC:Creative agencies in Los Angeles and Tokyo run computer vision pipelines for content production with expandable GPU-NPU hybrid configurations.
- Mini AI PC:Compact edge deployments serve industrial automation quality control stations in Stuttgart and Shenzhen manufacturing clusters.
Laptop AI PC dominates installed base. Workstation AI PC is where expansion concentrates.
Technology:
Software stack maturity varies dramatically across inference paradigms, with toolchains from Intel, Qualcomm, and AMD forcing developers into parallel optimization tracks that segment hardware procurement.
- Natural Language Processing:On-device large language model inference demands deterministic latency guarantees for enterprise virtual assistant deployments. Healthcare systems in Massachusetts and insurance underwriters in Connecticut prioritize this capability for HIPAA-compliant document analysis.
- Computer Vision:Real-time image classification and object detection pipelines leverage NPU tensor cores for manufacturing defect detection. German automotive suppliers in Bavaria and South Korean electronics assemblers drive qualification requirements for sub-50ms inference latency.
- Machine Learning:Traditional statistical inference workloads execute across CPU-NPU heterogeneous scheduling in financial risk modeling applications.
- Deep Learning:Multi-layer neural network training at the edge requires workstation-class thermal headroom and advanced packaging substrates.
- Reinforcement Learning:Autonomous system training loops remain experimental in robotics prototyping labs with limited commercial volume.
Computer Vision anchors current revenue. Natural Language Processing is climbing the fastest as generative AI workloads migrate on-device.
Application:
Workload-specific NPU utilization patterns determine whether customers prioritize TOPS-per-watt efficiency or raw compute scaling, creating distinct margin pools across vertical software certifications.
- Content Creation:Video production studios and generative art platforms exploit NPU-accelerated diffusion models for real-time rendering. Post-production houses in Los Angeles and game developers in Montreal specify hardware against Adobe and Autodesk certification matrices.
- Scientific Research:Molecular dynamics simulation and climate modeling workloads demand FP16 precision at scale. National laboratories in California and Max Planck Institute centers in Munich procure workstation fleets through dedicated research computing grants.
- Data Analysis:Tabular inference and predictive analytics spread across enterprise business intelligence teams with moderate NPU requirements.
- Virtual Assistance:Enterprise productivity copilots drive laptop refresh cycles as IT departments mandate local processing for meeting transcription.
- Cybersecurity:Behavioral threat detection on endpoints remains nascent, with SOAR platform vendors still certifying NPU-accelerated anomaly detection.
Data Analysis represents broadest deployment. Content Creation is gaining share fastest as creative software vendors ship NPU-optimized inference engines.
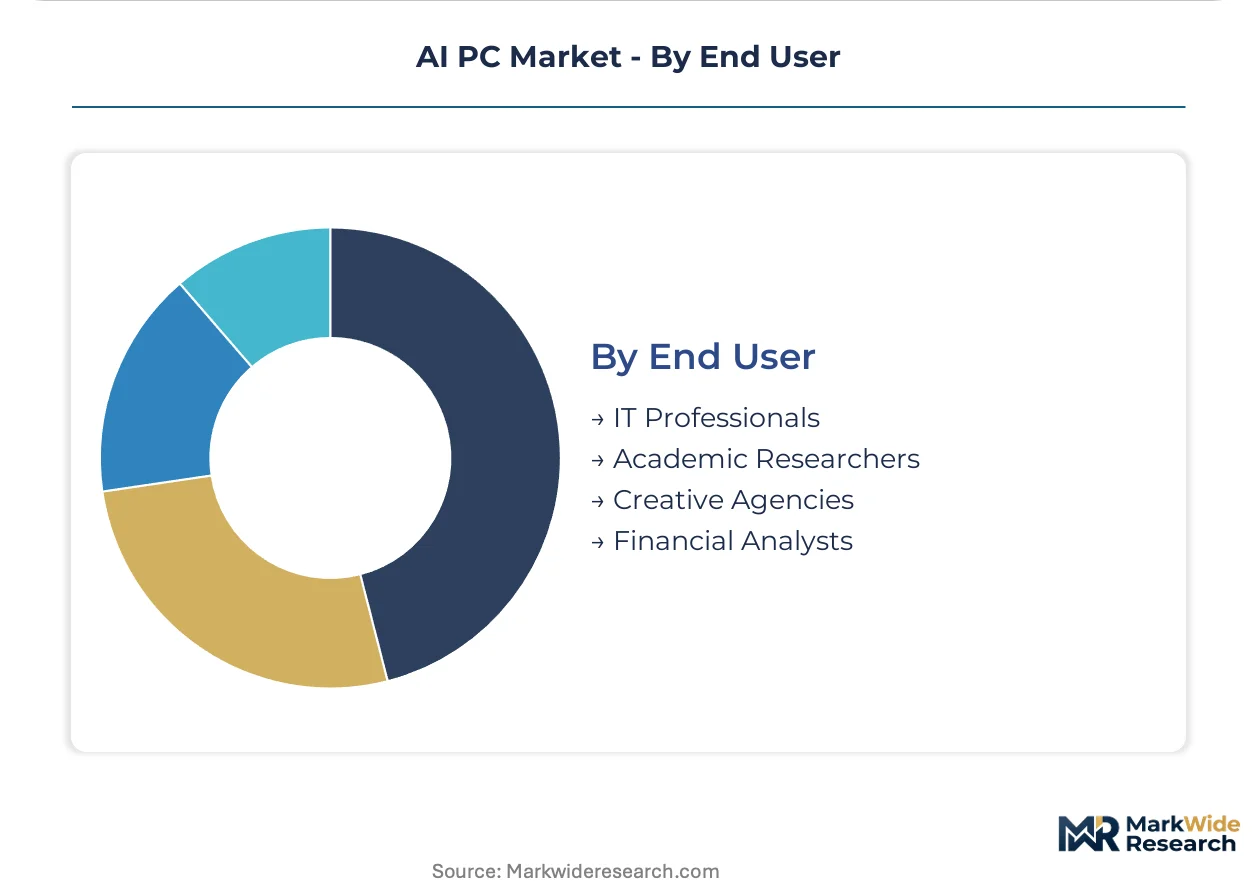
End User:
Procurement authority and technical specification control diverge between centralized IT departments and researcher-driven purchasing, fragmenting sales motion complexity.
- IT Professionals:Enterprise fleet managers standardize on Microsoft Copilot+ PC specifications with 40 TOPS minimums, negotiating volume discounts through direct OEM relationships. United States healthcare systems and German Mittelstand manufacturers centralize purchasing decisions here.
- Financial Analysts:Quantitative researchers and risk modelers specify workstation configurations with deterministic execution timing for regulatory audit trails. Hedge funds in Connecticut and investment banks in London drive premium pricing for air-gapped inference environments.
- Academic Researchers:Grant-funded principal investigators balance capital constraints against compute requirements through institutional purchasing consortia.
- Creative Agencies:Boutique production shops and in-house brand studios prioritize software ecosystem compatibility over raw NPU specifications.
IT Professionals control volume procurement. Financial Analysts is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German industrial procurement while volume absorption centers on Chinese enterprise refresh cycles, creating a structural asymmetry that shapes regional deployment timelines and certification priorities across the AI PC supply base.
United States
Healthcare systems in Massachusetts and financial services firms in Connecticut drive workstation-class procurement for HIPAA-compliant and air-gapped inference environments. The FCC governs wireless connectivity standards for AI-enabled edge devices while the Department of Commerce export controls fragment product SKUs across performance thresholds. Quantitative trading desks in New York absorb premium units to eliminate data residency risks in algorithmic workflows.
China
Domestic cloud hyperscalers and state-backed research institutes are expanding on-device inference procurement despite advanced packaging substrate constraints. MIIT oversees NPU performance benchmarking and semiconductor self-sufficiency targets under national dual carbon goals. Manufacturing clusters in Shenzhen and Beijing-Tianjin-Hebei are piloting mini AI PC deployments for industrial automation quality control stations.
Germany
Automotive suppliers in Bavaria and precision engineering Mittelstand manufacturers dominate European enterprise fleet procurement with strict TOPS-per-watt specifications. The EU AI Act imposes risk-classification requirements on biometric inference and credit scoring workloads, forcing deterministic execution timing certifications. Stuttgart industrial automation clusters are deploying real-time computer vision pipelines for manufacturing defect detection.
India
Domestic IT services firms and banking sector procurement teams are accelerating laptop refresh cycles under local data sovereignty mandates. The PLI scheme for IT hardware attracts OEMs to establish NPU-integrated assembly for South Asian enterprise demand. Karnataka and Tamil Nadu manufacturing corridors are consolidating production scale for regional distribution into Southeast Asian markets.
Japan
Corporate IT departments and research computing consortia prioritize thermal-efficient laptop configurations for mobile professional workflows. METI coordinates semiconductor supply chain resilience initiatives and edge AI standardization frameworks. Tokyo and Osaka metropolitan enterprise clusters are standardizing on Microsoft Copilot+ PC specifications with 40 TOPS minimums.
AI PC Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated chip-design houses commanding premium positioning through NPU architecture control while assembly-scale OEMs compete on procurement efficiency and channel reach. The vendor base consolidates around three strategic archetypes: silicon suppliers with captive foundry relationships, full-stack systems integrators bundling hardware with MLOps tooling, and volume manufacturers leveraging multi-continent assembly scale. Dominant competitive moves center on strategic partnerships between chip architects and software ecosystems, alongside geographic expansion of NPU-integrated production capacity.
Within the silicon supplier tier, Intel and Qualcomm exemplify divergent architectural bets on x86 and ARM-based AI acceleration respectively, each anchoring distinct enterprise procurement coalitions through software toolchain investments. Lenovo occupies a position bridging assembly-scale efficiency with direct enterprise contract consolidation, particularly in healthcare and financial services verticals where single-source accountability commands premium positioning. These three entities represent the core competitive tension shaping procurement authority concentration and margin pool distribution across the AI PC value chain.
| Leading Market Players |
|---|
| Apple |
| Lenovo |
| Dell Technologies |
| HP |
| ASUSTeK Computer |
| Acer |
| Microsoft |
| Intel |
| Qualcomm |
| Others |
Pricing and Supply Chain Analysis
EU AI Act risk-classification mandates gate both NPU qualification thresholds and price differentiation between compliant and non-compliant hardware tiers, compressing margins for OEMs lacking certified 40+ TOPS architectures while rewarding early certification investments with enterprise procurement premiums.
Pricing Analysis
Configured-to-order workstation pricing commands substantial premiums over standard laptop SKUs, with financial services buyers in New York and London absorbing 3-4x multiples for air-gapped inference environments. Pricing stratifies across premium, standard, and economy tiers based on NPU TOPS certification level and deterministic execution timing guarantees. Cost compression in standard laptop tiers is intensifying because TSMC 3nm foundry allocation favors high-margin workstation die. IT Professionals demonstrate highest price sensitivity through centralized fleet negotiations, while Financial Analysts show lowest sensitivity due to regulatory audit trail requirements.
Supply Chain Analysis
Inventory strategy bifurcates between just-in-time laptop assembly in India and strategic CoWoS substrate stockpiling for workstation NPU production. Supply concentrates in Taiwan for TSMC foundry services, South Korea for advanced packaging substrates, and China for final assembly integration. Raw material dependencies span silicon wafers, high-bandwidth memory stacks, and organic substrate laminates. Single-source vulnerability at Taiwanese CoWoS suppliers threatens workstation NPU volumes. Distribution runs through direct OEM enterprise contracts consolidating hardware with MLOps tooling bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of deterministic NPU execution timing expertise constrains how quickly OEMs can certify against EU AI Act transparency obligations, privileging incumbents with established notified body relationships over assembly-scale competitors.
For Market Incumbents: Compound software toolchain investments to lock enterprise procurement around Intel OpenVINO and Qualcomm QNN ecosystems, defending against ARM-based entrants. Deepen captive foundry relationships through TSMC capacity reservations, prioritizing 3nm NPU die allocation for workstation margins. Channel control through direct healthcare and financial services contracts remains the critical lever for margin defense. For New Entrants and Emerging Players: Federated learning integration services represent an under-served layer where incumbents bundle hardware without differential privacy tooling. Healthcare systems in Massachusetts and defense contractors present the most penetrable verticals for on-device training capabilities. A go-to-market angle anchored to MLOps workflow migration services bypasses hardware certification barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across chiplet-based NPU design, favoring acquisition targets with licensed die-to-die interconnect IP over monolithic architecture legacy players. Long-term viability rests on software ecosystem anchoring rather than transient TOPS specifications. The signal to watch is EU notified body certification queue lengths as a leading indicator of competitive positioning durability.| Strategic Initiative | Industry Significance |
|---|---|
| NPU Software Stack Certification | Intel OpenVINO and Qualcomm QNN toolchain investments lock enterprise procurement against ARM entrants. |
| Foundry Capacity Reservation | TSMC 3nm allocation commitments secure die supply for workstation-class 100+ TOPS architectures. |
| Direct Enterprise Contract Consolidation | Healthcare systems in Massachusetts prioritize single-source accountability for HIPAA-compliant deployments. |
| Chiplet Architecture Licensing | Modular NPU compute tiles accelerate time-to-market for specialized inference silicon configurations. |
| EU Notified Body Pre-Certification | Deterministic execution timing documentation satisfies transparency obligations under AI Act risk tiers. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with semiconductor procurement directors, enterprise IT fleet managers, and foundry planning officers; and secondary validation through SEC semiconductor capex filings, TSMC investor disclosures, EU AI Act technical documentation, and customs trade data for NPU-integrated laptop shipments. Bottom-up triangulation against top-down TAM estimates anchored volume projections.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, NPU TOPS tier, application workload, and regional regulatory cluster. CAGRs derived from fitted growth curves against historical PC refresh cycle patterns and enterprise AI adoption S-curves. Forecast inputs incorporated foundry capacity allocation schedules and EU AI Act implementation timelines.
Underlying assumptions cover sustained TSMC 3nm yield improvements and stable export control thresholds, with deviation risk concentrated in advanced packaging substrate supply disruptions and cross-jurisdiction certification timeline divergence. Revision becomes warranted when CoWoS capacity constraints trigger sustained workstation NPU allocation rationing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Global Electronic Design Automation (EDA) Market
Emerging and Next Generation Technologies
Molecular Electronics Market
Emerging and Next Generation Technologies
Swarm Intelligence Market
Emerging and Next Generation Technologies
Swarm Computing Market
Emerging and Next Generation Technologies
Metamaterial Medium Market
Emerging and Next Generation Technologies
Inp Lasers Market
Emerging and Next Generation Technologies
Spintronics Market
Emerging and Next Generation Technologies
Flexible Electronics Market
Emerging and Next Generation Technologies
Haptic Technology Market
Emerging and Next Generation Technologies
Global Metamaterial Market
Emerging and Next Generation Technologies
Lab on Chips Market
Emerging and Next Generation Technologies
Programmable Semiconductor Technologies Market
Emerging and Next Generation Technologies
Global Plasma Pulse Technology Market
Emerging and Next Generation Technologies
Metal Additive Manufacturing Systems Market
Emerging and Next Generation Technologies
Triboelectric Nano-Generator Market
Emerging and Next Generation Technologies
Global WI SUN Technology Market