
 Terahertz Radiation Devices Market | 2026-2036
Terahertz Radiation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Terahertz Radiation Devices Market Analytics
Photonic integration with silicon platforms is rewriting terahertz device architectures, collapsing size and cost curves for commercial deployment. HÜBNER GmbH & Co. KG leverages its precision photonics heritage to dominate terahertz source modules for industrial imaging. Menlo Systems anchors European supply chains through stabilized femtosecond laser systems that feed terahertz emitters. Toptica Photonics AG specializes in tunable diode laser technology that extends wavelength coverage for spectroscopy applications.
Terahertz radiation devices generate and detect electromagnetic waves in the 0.1–10 THz range, bridging microwave and infrared spectra for non-destructive testing and material characterization. Solid-state and photonic technologies lead product development, with photonic architectures capturing premium margins due to their superior signal-to-noise ratios in security screening. CMOS-based terahertz sensors represent the fastest-growing segment as foundries adapt semiconductor processes for cost-sensitive automotive and telecommunications end users. Imaging and spectroscopy applications currently absorb the majority of device output, though communications is emerging as a structural growth vector.
FDA clearance pathways shape healthcare adoption timelines for terahertz diagnostic systems, while FCC spectrum allocations determine commercial viability for terahertz communications hardware. The EU AI Act and CE marking framework impose algorithmic transparency requirements on automated terahertz screening systems deployed in European transport hubs. Stakeholders must monitor regulatory convergence between medical device and telecommunications classifications, as overlapping jurisdiction creates compliance complexity for multi-use terahertz platforms.
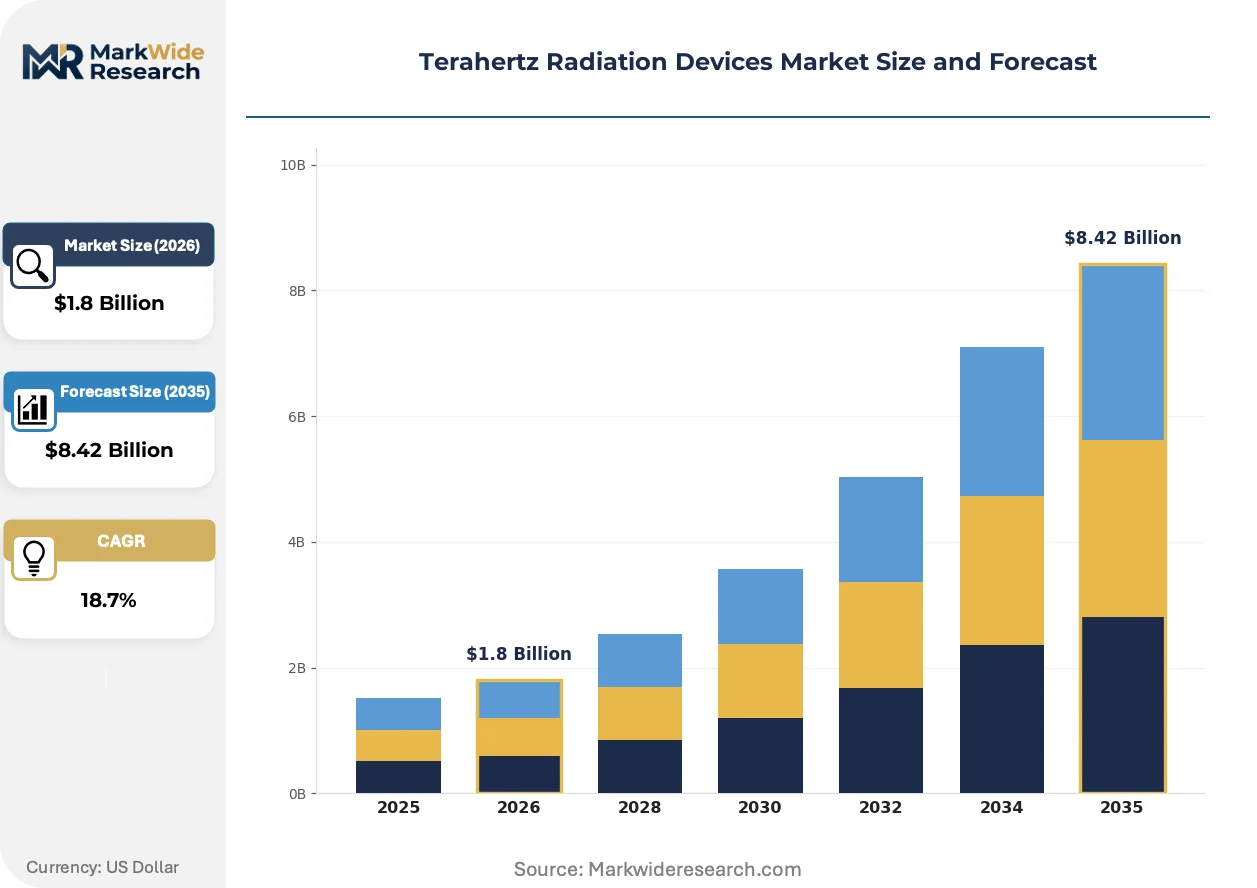
Market Dynamics
Photonic integration with silicon platforms is compressing device footprints and collapsing cost curves, enabling terahertz systems to migrate from laboratory benches to factory floors and clinical settings at accelerating velocity.
Growth Catalysts
- EU AI Act compliance mandates:Automated screening deployments in European transport hubs now require certified algorithmic transparency, pulling device makers toward photonic architectures that satisfy CE marking and auditability requirements simultaneously.
- Semiconductor fab expansion:Taiwan and South Korea fabs are adding dedicated terahertz inspection lines for wafer-level defect detection, creating captive demand for high-throughput source modules and sensor arrays.
- CMOS process adaptation:Foundries are modifying existing semiconductor flows to fabricate terahertz sensors, opening cost-sensitive automotive and telecommunications verticals previously closed to exotic III-V technologies.
Market Restraints
- Indium phosphide supply concentration:High-performance photomixer chips depend on InP substrates sourced from a concentrated supplier base, exposing device makers to input volatility and geopolitical disruption risk.
- FCC spectrum allocation uncertainty:Terahertz communications hardware faces commercial viability constraints until the regulator clarifies licensing frameworks for 100 GHz and above bands.
- Liquid nitrogen cooling dependency:Cryogenic requirements for certain detector technologies impose operational complexity and facility infrastructure costs that limit deployment flexibility.
Strategic Opportunities
- India pharmaceutical inspection:CDSCO quality enforcement is tightening on solid dosage form manufacturing, creating entry points for terahertz moisture-content analyzers in Mumbai and Hyderabad production clusters.
- 6G R&D acceleration:METI funding in Japan and NSF programs in the United States are converging on terahertz wireless backhaul, positioning device makers for standards-body engagement before commercialization windows open.
- Digital distribution platforms:Specialized photonics marketplaces are emerging as direct channels for component sales, reducing reliance on legacy distributor markups for standard emitter and detector modules.
Industry Challenges
- Femtosecond laser alignment expertise:The specialized optomechanical skill required for stabilized laser-terahertz coupling is scarce, constraining production scaling and service network expansion.
- FDA 510(k) pathway navigation:Diagnostic system developers face extended certification timelines as the regulator develops precedents for electromagnetic safety in clinical terahertz exposure protocols.
- Legacy NDT system integration:Industrial customers require seamless data handoff between terahertz imagers and existing ultrasonic or X-ray inspection databases, complicating deployment architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Terahertz Radiation Devices Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Terahertz Emitters, Terahertz Detectors, Terahertz Sources, Terahertz Sensors Application: Imaging, Spectroscopy, Security Screening, Communications End User: Healthcare, Automotive, Aerospace, Telecommunications Technology: Solid-State, Photonic, CMOS, Quantum Cascade |
| Companies Covered | HÜBNER GmbH & Co. KG, Menlo Systems, Advantest Corporation, QMC Instruments Ltd., Thorlabs Inc., TeraView Limited, Toptica Photonics AG, TeraSense Group, Luna Innovations, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Terahertz Radiation Devices Market Evolving Landscape
Convergence between photonic and electronic terahertz generation is dissolving traditional technology boundaries, while regulatory frameworks crystallize around safety and algorithmic accountability.
Silicon-germanium photodiode arrays are hybridizing electronic and photonic signal generation within single chip stacks. Automotive radar suppliers in Germany are piloting these devices for sub-millimeter resolution imaging at 300 GHz. The approach is hybridizing cost structures previously separated between III-V component premiums and silicon CMOS economies.
REACH restrictions on hazardous substances are tightening material specifications for terahertz optical substrates and coatings. Manufacturers reformulating epoxy adhesives and anti-reflection layers face reformulation cycles affecting delivery schedules. Medical device segments in the European Union are responding fastest, with several participants accelerating substitution timelines to maintain CE marking continuity.
Specification-driven purchasing is consolidating buyer influence around certified performance metrics rather than brand reputation or historical relationships. Systems integrators in security screening now require documented noise-equivalent power and spectral stability before contract award. This pattern is most pronounced in German precision optics clusters, where procurement teams impose standardized test protocols adapted from semiconductor metrology practices.
Terahertz Radiation Devices Market Segmentation
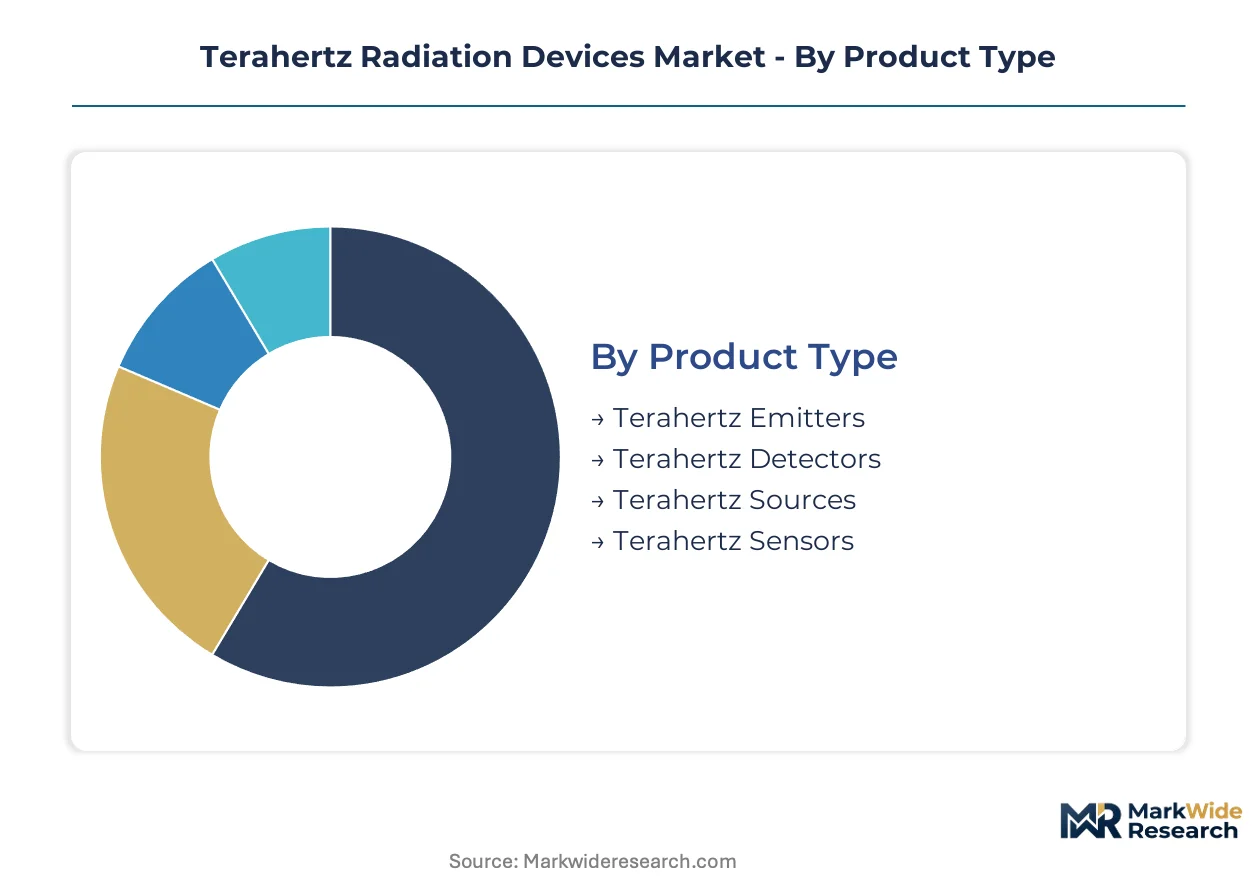
Terahertz device architectures fragment across generation mechanisms, deployment contexts, and performance thresholds. Segmentation clarity enables buyers to match cooling requirements, spectral resolution, and integration complexity against specific use cases.
Product Type:
The use-case spectrum spans laboratory-grade precision instruments to embedded automotive sensors, with thermal management and packaging density driving selection criteria.
- Terahertz Emitters:Photoconductive antennas and quantum cascade lasers generate coherent radiation for time-domain spectroscopy. Demand concentrates in German precision optics clusters where Jena-based system integrators specify femtosecond-pumped emitter modules for pharmaceutical quality control.
- Terahertz Detectors:Electro-optic crystals and bolometric sensors capture weak terahertz signals with cryogenic or room-temperature operation. South Korean semiconductor fabs are qualifying detector arrays for inline wafer inspection, pulled by yield improvement mandates in advanced node manufacturing.
- Terahertz Sources:Multiplier chains and backward wave oscillators deliver continuous-wave output for communications prototyping.
- Terahertz Sensors:Packaged emitter-detector pairs with integrated optics reduce assembly burden for industrial integrators.
Established volume favors Terahertz Emitters; emerging adoption favors Terahertz Sensors.
Application:
Cost tier separation distinguishes premium analytical instrumentation from volume security hardware, with communications equipment occupying an intermediate position pending spectrum allocation clarity.
- Imaging:Pulsed and continuous-wave systems reconstruct sub-millimeter resolution for non-destructive testing of composite aerospace structures. German automotive suppliers in Munich are piloting 300 GHz imagers for paint thickness verification, driven by surface quality specifications in electric vehicle manufacturing.
- Spectroscopy:Time-domain and frequency-domain instruments identify molecular fingerprints for pharmaceutical polymorphism detection. CDSCO enforcement on solid dosage form quality in India is expanding moisture-content analyzer deployments across Mumbai and Hyderabad production facilities.
- Security Screening:Portal and handheld systems detect concealed anomalies under clothing or within packaging.
- Communications:Wireless backhaul prototypes operate at 100 GHz and above for 6G research programs.
Margin concentration sits with Spectroscopy; volume scaling potential sits with Security Screening.
End User:
Customer type fragmentation separates regulated medical device procurement from automotive cost-down pressures and telecommunications standards-body timelines.
- Healthcare:Diagnostic imaging and tissue spectroscopy systems require FDA 510(k) clearance for electromagnetic exposure protocols. Extended certification timelines in the United States are constraining commercial rollout velocity for dermatological and dental applications.
- Telecommunications:Base station backhaul and fronthaul equipment demands FCC spectrum allocation certainty above 100 GHz. METI-funded research in Japan and NSF programs in the United States are converging on terahertz wireless before commercialization windows open.
- Automotive:Radar and in-cabin sensing applications prioritize CMOS compatibility for cost targets.
- Aerospace:Composite inspection and satellite cross-link applications tolerate III-V component premiums for performance.
Procurement maturity favors Healthcare; technology transition velocity favors Telecommunications.
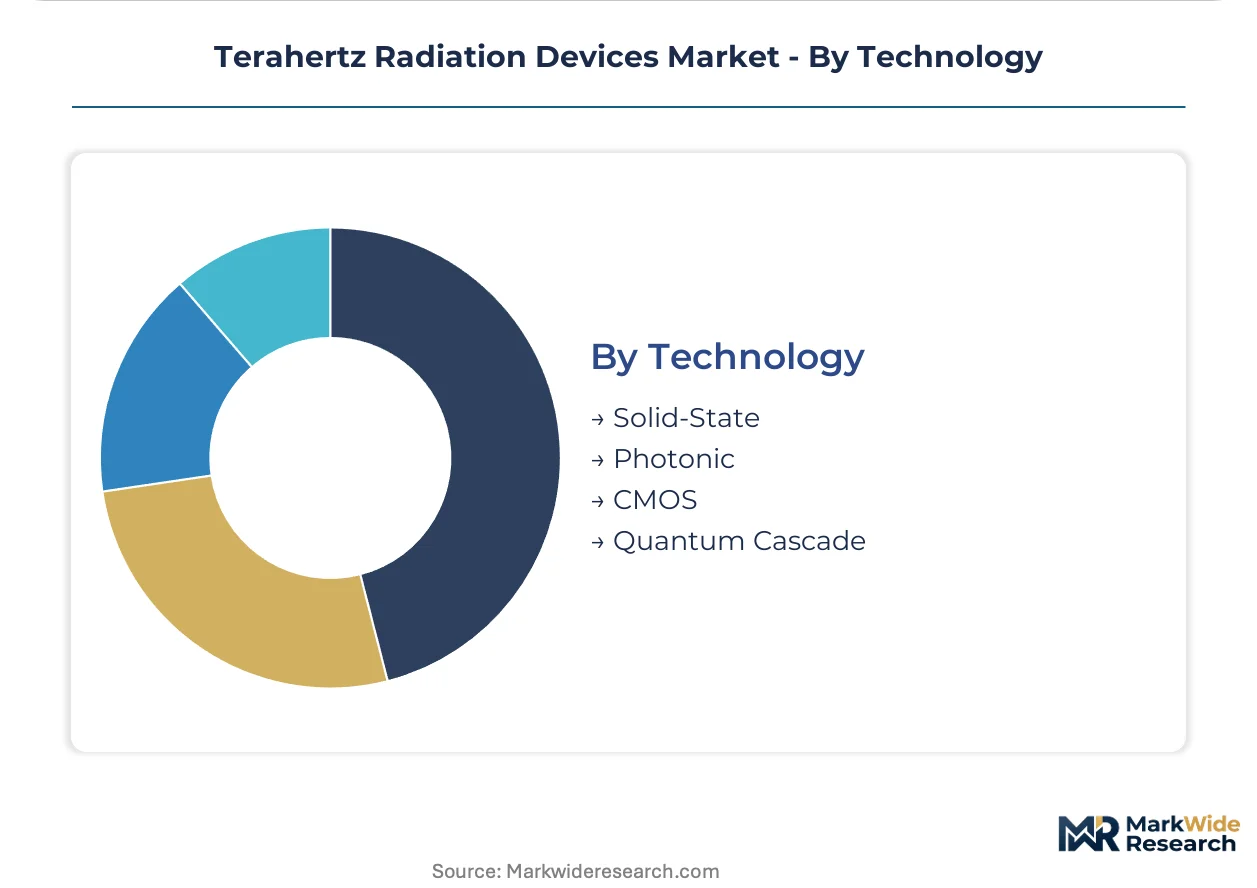
Technology:
Supply concentration determines availability risk, with indium phosphide substrate sourcing constraining photonic architectures and silicon foundry access enabling CMOS scaling.
- Photonic:Femtosecond laser-driven systems achieve superior signal-to-noise ratios for laboratory and security screening applications. EU AI Act compliance mandates for algorithmic transparency in European transport hubs are pulling device makers toward photonic architectures that satisfy CE marking requirements.
- CMOS:Silicon-based terahertz circuits leverage existing foundry infrastructure for cost-sensitive automotive and telecommunications verticals. Taiwan and South Korea fabs are adapting process flows to fabricate terahertz sensors, opening markets previously closed to exotic III-V technologies.
- Solid-State:Electronic multiplier chains and Schottky diode systems serve established test and measurement applications.
- Quantum Cascade:Semiconductor lasers deliver milliwatt-level continuous-wave output for spectroscopy and imaging.
Performance ceiling favors Photonic; manufacturing scalability favors CMOS.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense contractors and pharmaceutical manufacturers anchor terahertz device procurement across concentrated industrial clusters. Taiwan and South Korea fabs generate captive demand for inline inspection systems. German precision optics clusters drive specification standards for European deployment.
United States
FDA clearance pathways for diagnostic imaging and FCC spectrum allocation uncertainty above 100 GHz shape commercial timelines. NSF research programs fund 6G terahertz wireless backhaul development. Boston and Austin host defense contractors integrating terahertz sensors into aerospace non-destructive testing workflows.
Germany
Automotive suppliers in Munich pilot 300 GHz imagers for electric vehicle paint thickness verification. EU AI Act compliance mandates pull device makers toward photonic architectures satisfying CE marking and algorithmic transparency requirements. Jena-based system integrators specify femtosecond-pumped emitter modules for pharmaceutical quality control.
Japan
METI funding accelerates terahertz wireless research for beyond-5G communications infrastructure. PMDA regulatory frameworks influence electromagnetic exposure protocols for clinical diagnostic systems. Nagoya automotive clusters evaluate CMOS-compatible terahertz radar for sub-millimeter resolution imaging.
Taiwan
Semiconductor fabs expand dedicated terahertz inspection lines for advanced node wafer-level defect detection. The concentrated indium phosphide supply base exposes device makers to input volatility. Hsinchu Science Park anchors captive demand for high-throughput source modules and sensor arrays.
India
CDSCO quality enforcement tightens on solid dosage form manufacturing in Mumbai and Hyderabad production clusters. BIS standards development lags equipment deployment, creating certification gaps for imported systems. Domestic pharmaceutical inspection creates entry points for moisture-content analyzers.
Terahertz Radiation Devices Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base separates between precision photonics heritage firms and semiconductor-adjacent scale manufacturers. Three archetypes dominate: femtosecond laser system suppliers, photonic component module vendors, and CMOS process adaptation specialists. Competitive moves concentrate on strategic partnerships with foundries and geographic expansion through distributor network consolidation.
Within the precision photonics tier, HÜBNER GmbH & Co. KG and Menlo Systems exemplify German engineering heritage in stabilized laser systems. Toptica Photonics AG occupies a position among tunable diode laser specialists extending wavelength coverage. These three entities anchor European supply chains through differentiated photonic architectures rather than scale manufacturing.
| Leading Market Players |
|---|
| HÜBNER GmbH & Co. KG |
| Menlo Systems |
| Advantest Corporation |
| QMC Instruments Ltd. |
| Thorlabs Inc. |
| TeraView Limited |
| Toptica Photonics AG |
| TeraSense Group |
| Luna Innovations |
| Others |
Value Network & Pricing Analysis
Indium phosphide substrate sourcing from concentrated suppliers in Japan and the United States anchors margin pools in photonic emitter modules, where device makers capture premiums downstream. Pricing power concentrates with femtosecond laser system integrators who bundle stabilized sources with application-specific optics.
Pricing Analysis
Cost-plus contracts with indium phosphide substrate indexation dominate procurement for photonic architectures, transferring input volatility to downstream device pricing. Three-tier pricing structure across laboratory-grade, industrial-integrated, and automotive-CMOS levels separates certification-burdened medical tiers from cost-sensitive volume segments. Pricing pressure stems from foundry-adapted CMOS sensors eroding III-V component premiums in automotive radar. Automotive OEMs exhibit highest price sensitivity; pharmaceutical quality control labs demonstrate lowest.
Supply Chain Analysis
Supplier-financing facilities extended by German precision optics houses stabilize working capital for Jena-based system integrators sourcing femtosecond-pumped modules. Manufacturing concentrates in Germany, Taiwan, and South Korea, with Taiwan fabs drawing from Japanese indium phosphide and German laser optics. Supply chain risk centers on single-source vulnerability for InP substrates. Distribution runs through specialized photonics marketplaces and legacy distributor networks serving industrial integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across application requirements creates niche specialization opportunities as CMOS adaptation separates automotive cost tiers from photonic performance tiers.
For Market Incumbents: Harden femtosecond laser alignment expertise through captive training programs before scarcity constrains service network expansion. Deepen backward integration into stabilized laser cavity manufacturing to defend margins against CMOS sensor commoditization in security screening. For New Entrants and Emerging Players: India's pharmaceutical inspection clusters in Mumbai and Hyderabad offer underpenetrated entry points as CDSCO enforcement tightens moisture-content analyzer requirements. Target CDSCO compliance bundling with local service partnerships as the go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed photonics component specialists holding CE-marked architectures but lacking foundry partnerships for CMOS scaling. Long-term viability favors platforms spanning both photonic performance tiers and silicon economies. Watch FCC spectrum allocation clarity above 100 GHz as the inflection signal for communications hardware valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Photonic-CMOS Hybrid Development | Silicon-germanium integration captures automotive radar volumes while preserving laboratory margins. |
| EU AI Act Certification Investment | CE-marked algorithmic transparency opens European transport hub deployments against uncertified competitors. |
| Foundry Process Adaptation Partnership | Taiwan and South Korea fab access enables cost-sensitive automotive and telecommunications sensor scaling. |
| Specialized Photonics Marketplace Launch | Direct component channels reduce distributor markups for standard emitter and detector modules. |
| Indium Phosphide Supply Diversification | Alternative substrate sourcing mitigates geopolitical disruption risk for photomixer chip production. |
Research Methodology
A spread of perspectives from femtosecond laser system engineers, semiconductor fab process integration leads, pharmaceutical quality control managers, and security screening procurement officers converged on the working assumptions. Primary interview insights combined with secondary validation from FDA 510(k) filings, FCC spectrum allocation dockets, METI research program disclosures, and EU AI Act implementation guidance. Bottom-up unit economics for emitter and detector modules triangulated against top-down addressable market sizing across application verticals.
Demand-supply balance modeling anchored projections across the analysis window, with segmentation across product type, application, end user, and technology dimensions. CAGRs derived from fitted growth curves incorporating foundry capacity expansion timelines, regulatory clearance velocity, and standards-body convergence patterns. Industry-specific inputs included semiconductor fab terahertz inspection line deployment schedules and pharmaceutical regulatory enforcement intensity indices.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by CMOS-adapted foundries or accelerated FCC spectrum releases would shift outcomes. Macroeconomic contraction in automotive and telecommunications capex, regulatory divergence between FDA and PMDA exposure protocols, or breakthrough electronic terahertz generation efficiency would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Mexico Cleanroom Technology Market
Emerging and Next Generation Technologies
Asia Pacific Quantum Computing Market
Emerging and Next Generation Technologies
Ultra-Thin Solar Cells Market
Emerging and Next Generation Technologies
Laser Technology Market
Emerging and Next Generation Technologies
Metal Additive Manufacturing Systems Market
Emerging and Next Generation Technologies
Global Flexible and Printed Electronics Market
Emerging and Next Generation Technologies
Global Terahertz Components and Systems Market
Emerging and Next Generation Technologies
Swarm Intelligence Market
Emerging and Next Generation Technologies
Global Digital Twin Technology Market
Emerging and Next Generation Technologies
North America Wigig Market
Emerging and Next Generation Technologies
Haptic Technology Market
Emerging and Next Generation Technologies
North America Cleanroom Technology Market
Emerging and Next Generation Technologies
NB-IoT Module Market
Emerging and Next Generation Technologies
Hyperscale Computing Market
Emerging and Next Generation Technologies
Internet of Nano Things Market
Emerging and Next Generation Technologies
Triboelectric Nano-Generator Market